
 Baby Shoes Market | 2026-2036
Baby Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Shoes Market Outlook
Online specialty retail is realigning how parents discover and purchase baby footwear, shifting volume away from traditional department stores toward direct-to-consumer platforms. Nike leverages its sportswear heritage to dominate athletic-inspired infant lines, while Stride Rite anchors its position through podiatric partnerships and width-specific sizing. Adidas competes via sustainable material narratives and lifestyle crossover appeal in the toddler segment.
Baby shoes are soft-soled or flexible footwear engineered for children from birth through approximately four years, constructed with breathable uppers, non-slip outsoles, and anatomically shaped interiors that accommodate undeveloped foot arches and rapid growth. Leather and canvas materials command premium positioning due to natural breathability and biodegradability credentials, while synthetic alternatives capture volume through cost accessibility and color versatility. The toddler age bracket generates the largest revenue pool as walking milestones trigger repeat purchase cycles, and unisex styling is displacing traditional gendered assortments in urban markets.
Consumer Product Safety Commission guidelines in the United States, REACH chemical restrictions enforced by ECHA across Europe, and GB standards administered by SAMR in China collectively govern phthalate limits, small-part choking hazards, and labeling transparency. These frameworks elevate compliance costs for synthetic material suppliers while creating market access barriers for uncertified imports. Stakeholders must monitor evolving chemical restriction schedules and regional enforcement intensity to anticipate sourcing disruptions and certification renewal demands.
Market Dynamics
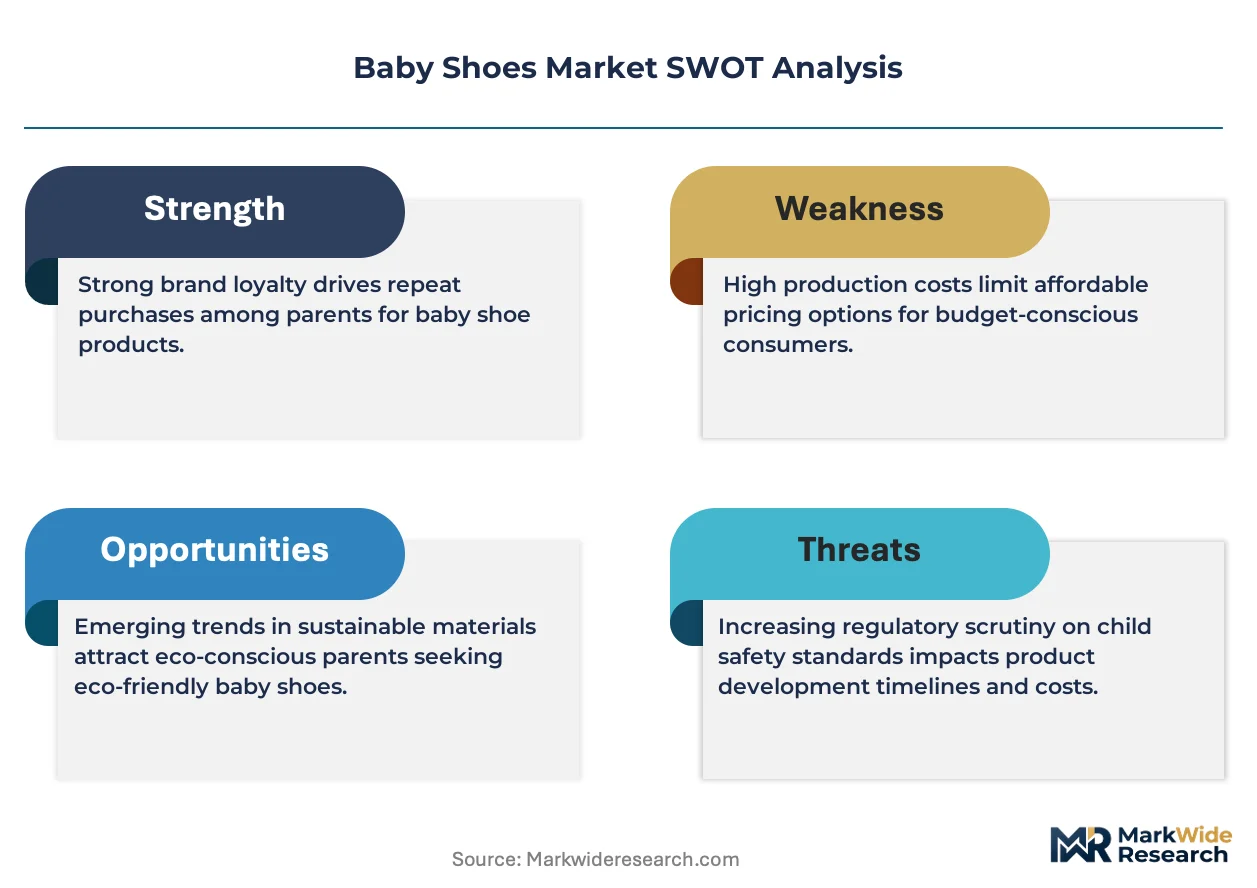
Millennial parental purchasing patterns are compressing traditional retail cycles as safety certification and podiatric endorsement become non-negotiable filters in the baby shoes category. REACH chemical standards and parallel frameworks in North America and Asia are forcing material recertification across synthetic supply chains.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement is accelerating substitution of phthalate-laden synthetics with bio-based alternatives, opening premium positioning for compliant suppliers.
- Toddler walking milestones:Repeat purchase cycles triggered by rapid foot growth in children aged 12-36 months sustain inventory velocity through predictable size progression.
- Direct-to-consumer platforms:Specialty e-commerce channels are capturing volume from department store footwear sections by offering fit-guarantee programs and subscription sizing.
Market Restraints
- Leather input volatility:Tannery capacity concentration in Italy and Brazil exposes margin structures to hide price fluctuations and seasonal availability constraints.
- GB standards administration:China's SAMR certification timelines for imported children's footwear create 4-6 month market access delays for non-domestic manufacturers.
- Technical sizing fragmentation:Absence of unified infant foot measurement protocols forces redundant SKU proliferation across width, length, and volume dimensions.
Strategic Opportunities
- India's organized retail expansion:Metro city mall penetration and e-commerce logistics improvements are unlocking access to 25 million annual births with limited domestic premium footwear options.
- Biodegradable sole compounds:Convergence of plant-based polymers and compostability certification is enabling circular economy claims in the premium segment.
- Subscription sizing models:Automated replacement scheduling tied to pediatric growth tracking apps is reducing customer acquisition costs for direct brands.
Industry Challenges
- Podiatric certification scarcity:Limited pool of accredited pediatric foot specialists creates bottlenecks in design endorsement and marketing claim substantiation.
- Multi-jurisdiction labeling:Simultaneous compliance with US CPSC choking hazard warnings, EU REACH substance declarations, and China GB age-grading requirements strains packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Shoes Market |
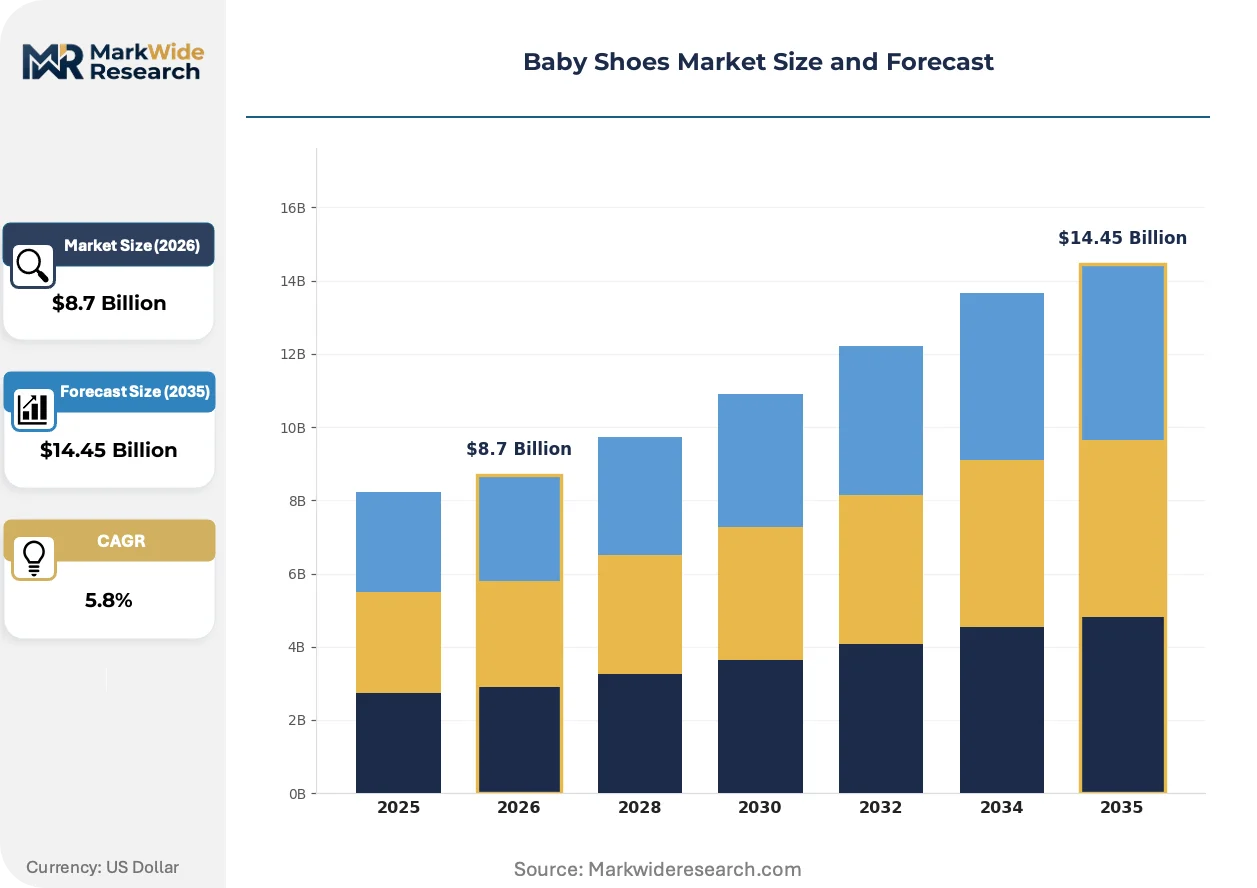
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Casual, Formal, Sports, Pre-Walker Material: Leather, Canvas, Synthetic, Rubber Age Group: Newborn, Infant, Toddler, Preschool Gender: Boys, Girls, Unisex, Others |
| Companies Covered | Nike, Adidas, New Balance, Puma, SKECHERS USA, Stride Rite, Crocs, See Kai Run, Goodbaby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Shoes Market Strategic Shifts
Material science advances and regulatory tightening are converging to reshape how baby footwear is engineered, certified, and sold. Three distinct vectors are compressing legacy production models while opening new competitive terrain.
3D-knitted uppers constructed from single-piece recycled polyester yarns are unifying breathability, stretch recovery, and waste reduction in one manufacturing step. Athletic-inspired infant lines at Nike and Adidas are adopting these structures fastest, collapsing the traditional cut-and-sew assembly timeline from weeks to days while eliminating material scrap rates that previously reached 15 percent in leather patterning.
REACH chemical restrictions enforced by ECHA are mandating systematic phthalate substitution across all synthetic components entering European retail channels. The industrial consequence is a forced supplier migration toward bio-based TPU and natural rubber outsoles, with toddler segment SKUs facing the steepest reformulation costs due to higher surface-area-to-weight ratios that amplify chemical exposure risk assessments.
Parents are consolidating purchase authority through specialty e-commerce platforms that aggregate podiatric reviews, fit-prediction algorithms, and seamless return logistics. This channel concentration is displacing department store children's sections in the United States and Germany, where urban consumers now expect same-week sizing exchanges and video gait-analysis support as standard service elements.
Baby Shoes Market Segmentation
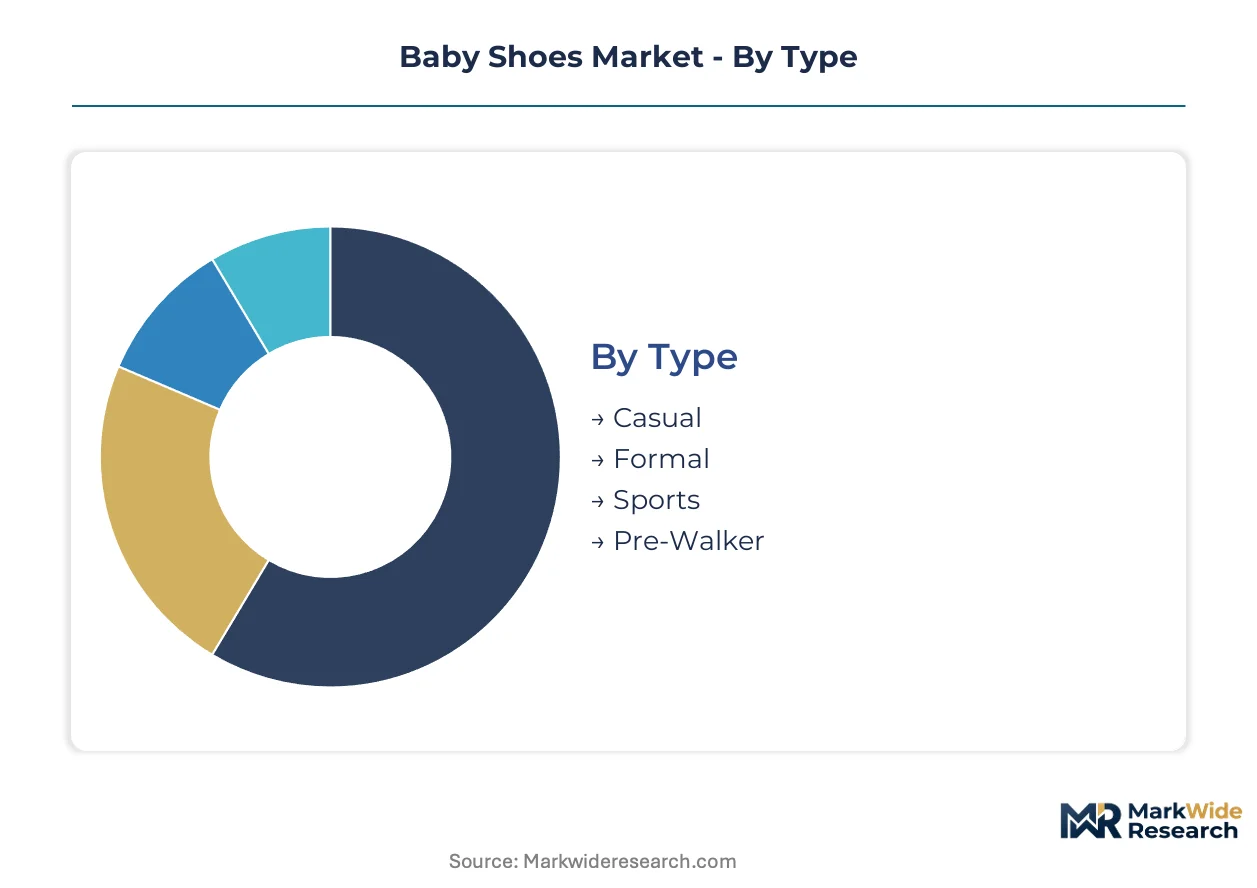
Segmentation in baby footwear determines material sourcing strategies, certification pathways, and channel placement. Each dimension—type, material, age, and gender—creates distinct margin profiles and regulatory exposure that shape supplier priorities.
Type:
Standardization dominates casual and formal lines, while sports and pre-walker categories demand specialized engineering and podiatric validation.
- Sports:Athletic-inspired designs integrate 3D-knitted uppers and biomechanical flex grooves for early mobility support. Nike and Adidas concentrate development resources here, targeting millennial parents in the United States and Germany who prioritize performance heritage brands for toddler gym programs.
- Pre-Walker:Ultra-flexible soles with zero-drop profiles accommodate undeveloped foot arches during crawling-to-standing transitions. Stride Rite anchors this segment through width-specific sizing partnerships with pediatric podiatrists, capturing repeat purchases as parents navigate sizing uncertainty.
- Casual:Everyday wearables balance durability with cost accessibility across canvas and synthetic constructions.
- Formal:Special-occasion leather constructions command event-driven purchase cycles with limited repeat velocity.
Leading the category by volume: Casual. Growing fastest: Sports.
Material:
Cost tier stratification separates premium natural inputs from volume synthetic alternatives, with compliance costs reshaping supplier economics.
- Leather:Full-grain and nappa constructions from Italian and Brazilian tanneries deliver natural breathability and biodegradability credentials. REACH phthalate restrictions are elevating vegetable-tanned alternatives in European markets, though hide price volatility compresses margins during supply shortages.
- Synthetic:PU and TPU compounds dominate mass-market production through color versatility and cost accessibility. ECHA enforcement is forcing systematic migration toward bio-based TPU formulations, with toddler SKUs facing disproportionate reformulation costs due to higher surface-area-to-weight exposure ratios.
- Canvas:Cotton-based uppers offer washable convenience and seasonal pattern flexibility for casual lines.
- Rubber:Natural and synthetic outsole compounds provide non-slip traction across wet indoor surfaces.
Driving premium positioning: Leather. Expanding most quickly: Synthetic alternatives with bio-based certification.
Age Group:
Volume concentration and purchase frequency vary sharply across developmental milestones, with walking initiation triggering the steepest repeat cycles.
- Toddler:Children aged 12-36 months generate the largest revenue pool as independent walking drives size progression every 8-12 weeks. Parents in China and the United States consolidate purchases through subscription sizing models that automate replacement scheduling.
- Infant:Pre-walking babies aged 6-12 months require soft-soled flexibility with minimal structural interference. Podiatric endorsement scarcity creates marketing claim bottlenecks for brands seeking differentiation in this bracket.
- Newborn:Gift-driven purchases concentrate around birth events with limited functional requirements.
- Preschool:Children aged 3-4 years transition toward miniaturized adult styling with durability demands for outdoor play.
Steepest expansion trajectory: Toddler. Emerging margin pressure: Preschool as durability expectations rise.
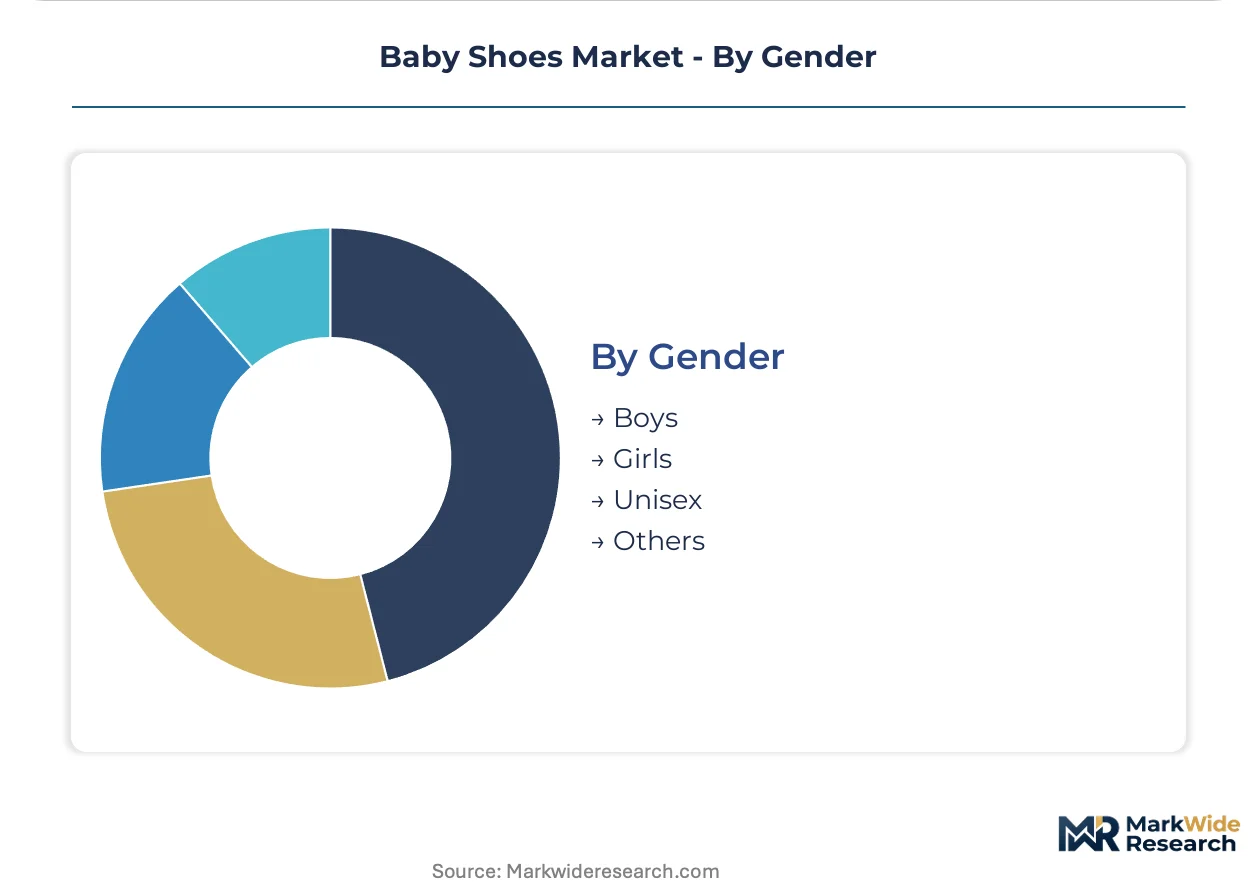
Gender:
Customer type evolution is displacing traditional gendered assortments in urban markets, with unisex styling capturing premium positioning.
- Unisex:Neutral color palettes and interchangeable designs reduce inventory risk for direct-to-consumer platforms. Urban parents in Germany and the United States increasingly reject pink-blue binary assortments, compressing SKU proliferation for specialty retailers.
- Girls:Traditional feminine styling with decorative elements maintains volume in department store channels and gift purchases.
- Boys:Athletic and outdoor-oriented constructions concentrate in sports-specialist retail.
- Others:Gender-neutral marketing claims without explicit unisex labeling serve niche positioning.
Gaining share fastest: Unisex. Defending volume position: Gendered lines in mass retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Guangdong and bonded warehousing clusters around Rotterdam accelerate inventory staging for brands targeting millennial parents. These logistics hubs compress lead times for podiatric-certified footwear while navigating divergent chemical compliance regimes.
United States
Millennial parents in metropolitan markets drive subscription sizing adoption for toddler footwear. Consumer Product Safety Commission guidelines mandate choking hazard warnings and phthalate limits that elevate packaging compliance costs. Los Angeles and New York City anchor direct-to-consumer fulfillment networks with same-week exchange logistics.
China
SAMR-administered GB standards impose certification timelines that delay market access for imported children's footwear. Yangtze River Delta manufacturing clusters concentrate synthetic material production for domestic brands. Shanghai and Hangzhou e-commerce platforms automate replacement scheduling tied to pediatric growth tracking.
Germany
ECHA REACH enforcement accelerates vegetable-tanned leather substitution in premium infant lines. Berlin and Munich specialty retailers displace department store volume through podiatric review aggregation. Bavaria-based tanneries supply biodegradable sole compounds to compliant brands.
India
Metro city mall expansion in Maharashtra and Karnataka unlocks access to annual birth cohorts with limited domestic premium options. BIS certification requirements for children's products create compliance bottlenecks for imported synthetic materials. Mumbai and Bengaluru logistics improvements support specialty e-commerce penetration.
Brazil
Tannery capacity concentration in São Paulo and Rio Grande do Sul exposes margin structures to hide price volatility. ANVISA pediatric product regulations align with Mercosur chemical restriction frameworks. São Paulo retail corridors concentrate formal occasion-driven purchase cycles for leather constructions.
Baby Shoes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with athletic heritage names capturing premium positioning and volume producers serving mass-market synthetic lines. The structure tiers around certification depth, material sourcing control, and direct-to-consumer channel ownership. Three archetypes dominate: podiatric-endorsed specialists, sportswear heritage crossovers, and private-label volume fabricators. Capacity expansion and strategic partnerships with pediatric foot clinics constitute the primary competitive moves.
Within the sportswear crossover tier, Nike and Adidas exemplify athletic heritage migration into infant lines through biomechanical design narratives. Stride Rite occupies a specialist position through width-specific sizing partnerships with pediatric podiatrists. These three names anchor the competitive map without exhausting its fabricator depth.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| New Balance |
| Puma |
| SKECHERS USA |
| Stride Rite |
| Crocs |
| See Kai Run |
| Goodbaby |
| Others |
Value Chain & Pricing Dynamics
Hide price volatility in Italian and Brazilian tanneries cascades through premium leather tiers, compressing margins for vegetable-tanned constructions while synthetic alternatives capture volume through cost stability. REACH compliance costs in European markets amplify this divergence, as bio-based TPU reformulation expenses concentrate in toddler SKUs with higher surface-area-to-weight ratios.
Pricing Analysis
Lead-time premiums reward rapid-turn suppliers serving direct-to-consumer platforms with fit-guarantee programs, while spot inventory in department store channels clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with podiatric-endorsed designs commanding sustained premiums and mass-market synthetics facing price erosion from Asian manufacturing scale. Parents in subscription sizing models exhibit lowest price sensitivity, whereas gift purchasers in formal occasion segments prioritize cost accessibility over performance claims.
Supply Chain Analysis
Domestic-content thresholds in India's BIS certification framework are redirecting synthetic material sourcing toward Maharashtra-based compounders, reducing reliance on imported TPU feedstocks. Manufacturing gravity centers on China, Vietnam, and Indonesia for cut-and-sew assembly, while Italian and Brazilian tanneries supply premium leather inputs. Raw material dependencies rest on natural rubber from Southeast Asian plantations, petroleum-derived TPU from South Korean petrochemical complexes, and full-grain hides from European and South American processors. Single-source vulnerability in tannery capacity exposes margin structures to hide price spikes. Distribution runs through bonded warehousing clusters around Rotterdam and Guangdong free-trade zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical standards function as a cost-of-compliance moat, elevating barrier-to-entry for uncertified imports while rewarding incumbent investment in bio-based material substitution.
For Market Incumbents: To counter subscription sizing disruption from direct-to-consumer specialists, deepen podiatric certification partnerships with pediatric foot clinics and anchor width-specific sizing as a retention mechanism. Capture backward integration into vegetable-tanned leather supply through tannery offtake agreements in Italy and Brazil. For New Entrants and Emerging Players: Begin with biodegradable sole compound development targeting Germany's premium segment, where compostability certification commands measurable price premiums. India's metro city mall expansion offers the most penetrable white-space, with limited domestic premium options and improving e-commerce logistics supporting direct entry. For Investors and Strategic Acquirers: SAMR certification timeline compression in China is the leading indicator that compliant import channels will consolidate around established players with regulatory affairs infrastructure. Acquisition targets should display dual REACH-GB certification capability and captive tannery relationships. Watch for ECHA enforcement intensity spikes as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Podiatric Certification Partnership | Stride Rite's width-specific sizing alliances demonstrate endorsement scarcity as a competitive moat. |
| Bio-based Material Transition | Adidas's sustainable TPU narratives capture REACH-compliant positioning in European toddler segments. |
| Direct-to-Consumer Platform Launch | Nike's athletic heritage migration leverages fit-prediction algorithms to displace department store volume. |
| Subscription Sizing Model | Automated replacement scheduling tied to pediatric growth tracking reduces customer acquisition costs. |
| India Organized Retail Expansion | Maharashtra and Karnataka mall penetration unlocks access to birth cohorts with limited premium domestic options. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with brand managers at athletic heritage crossover companies, category buyers at specialty e-commerce platforms, supply planners at tannery operations, and pediatric podiatrists serving endorsement partnerships. ECHA substance restriction schedules, SAMR GB standard updates, and CPSC guideline revisions provided regulatory trajectory inputs. Bottom-up SKU-level volume estimates triangulated against top-down category spend data from retail audit sources.
Data-stream reconciliation across the projection horizon integrated toddler age bracket repeat purchase velocity, leather input price cycles, and compliance cost escalations. Segmentation dimensions spanned type, material, age group, and gender, with channel dynamics and regional regulatory clusters as cross-cutting variables. CAGRs derived from fitted growth curves applied to certified versus non-certified supplier cohorts, with podiatric endorsement penetration and bio-based material adoption rates as key forecast inputs.
Underlying measurement precision varies by segment; toddler and sports categories carry tighter precision than newborn gift-driven purchases due to higher purchase frequency and channel data availability. Forecasts reflect documented assumptions around regulatory enforcement intensity and birth rate stability. Supply disruption from tannery capacity constraints or certification timeline extensions in China could revise trajectory estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
LAMEA Baby Care Products Market
Baby Products
Smart Pacifier Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Feeding Pillow Market
Baby Products
India Baby Care Products Market
Baby Products
Mexico Baby Care Products Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Baby Care Products Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Travel Pillow Market
Baby Products
Baby Bottle Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Products Detergents Market
Baby Products
Baby Gift Basket Market