
 Global Baby Product Market | 2026-2036
Global Baby Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Product Market Analysis
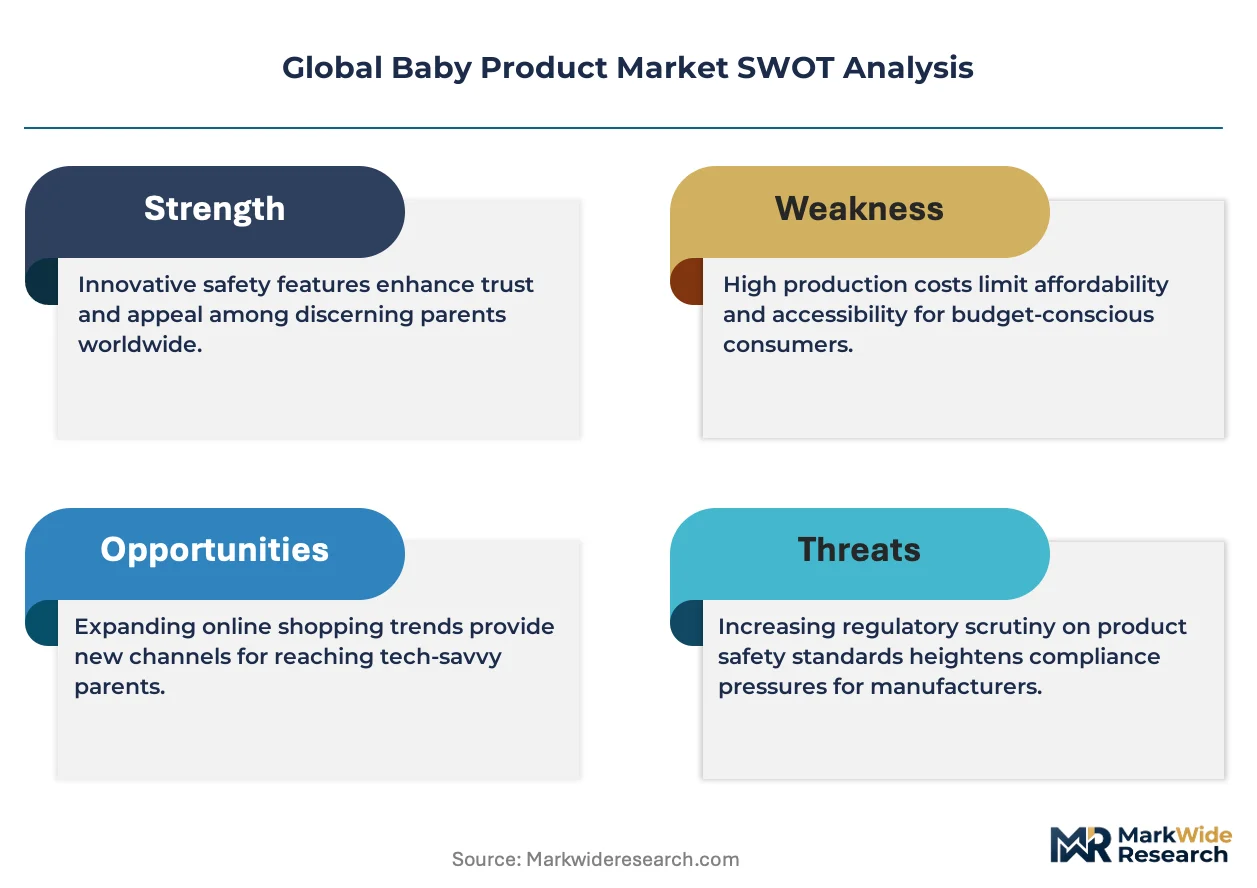
Subscription bundling of diapers, wipes, and skincare is repositioning how parents evaluate total cost of ownership versus single-item purchases. Procter & Gamble Co. leverages its Gillette Club infrastructure to anchor recurring revenue streams in developed markets. Kimberly-Clark Corporation competes through geographic dominance in Latin American diaper markets. The Honest Company Inc. differentiates via material transparency and direct-to-consumer channel control.
Baby products encompass consumables, durables, and apparel engineered for infant safety, hygiene, and developmental stimulation, typically manufactured to specifications including pH-neutral formulations, choke-resistant dimensions, and flame-retardant textile standards. Diapers represent the largest value pool due to high purchase frequency and premiumization toward chlorine-free and plant-based absorbent cores. Online Retail captures the fastest growth trajectory as pharmacy and supermarket channels cede share to platform-based subscription models and social commerce live-streaming events in Asian markets.
FDA cosmetic and food-contact regulations, EU REACH chemical restrictions, and China's GB national standards collectively elevate compliance costs while filtering out subscale manufacturers. EMA pediatric medicine guidelines and Japan's METI product safety frameworks further fragment certification requirements for multinational portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional SKU customization or unified global platforms deliver superior returns.
Market Dynamics
Subscription bundling is compressing purchase cycles and locking parents into recurring revenue relationships that reshape manufacturer margin structures away from transactional retail.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH restrictions on phthalates and formaldehyde releasers force reformulation toward plant-based absorbents and natural preservatives, opening premium pricing tiers.
- Live-stream commerce penetration:Chinese platforms integrate real-time product demonstrations with instant checkout, collapsing traditional retail markups and accelerating trial rates among first-time parents.
- Plant-based absorbent cores:Superabsorbent polymers derived from corn starch and bamboo fiber reduce petrochemical dependence while meeting chlorine-free certification standards demanded by Millennial buyers.
Market Restraints
- Pulp and SAP input volatility:Fluctuating softwood pulp prices and acrylate monomer costs squeeze diaper margin structures, particularly for mid-tier private-label manufacturers lacking long-term supply contracts.
- China GB standard fragmentation:Provincial enforcement variations in GB 15979 hygiene standards and GB 28007 safety requirements create compliance complexity that filters out subscale importers.
- Reusable diaper substitution:All-in-two and pocket cloth systems with biodegradable liners capture environmentally motivated parents, eroding disposables volume in Nordic and German urban markets.
Strategic Opportunities
- India tier-two city expansion:Rising disposable incomes in Pune, Ahmedabad, and Kochi outpace organized retail penetration, creating direct-to-consumer subscription whitespace before modern trade consolidation.
- Biometric monitoring integration:Sensor-embedded diapers tracking hydration, sleep patterns, and early illness markers converge wearable technology with infant hygiene, opening data-service revenue streams.
- Japan METI carbon-labeling incentives:Product-level carbon footprint disclosures under the Green Transformation program reward domestic manufacturers with procurement preferences in hospital and daycare institutional channels.
Industry Challenges
- Cross-jurisdictional certification timelines:Simultaneous FDA cosmetic registration, EU CPNP notification, and China NMPA filing for skincare lines extend product launch windows by 18-24 months.
- Legacy ERP integration with subscription platforms:Established manufacturers struggle to reconcile batch-oriented manufacturing systems with real-time inventory allocation for personalized bundle configurations.
- Specialized pediatric toxicology talent scarcity:Formulation chemists with expertise in immature skin barrier penetration and developmental neurotoxicity command premium compensation that concentrates in contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Product Market |
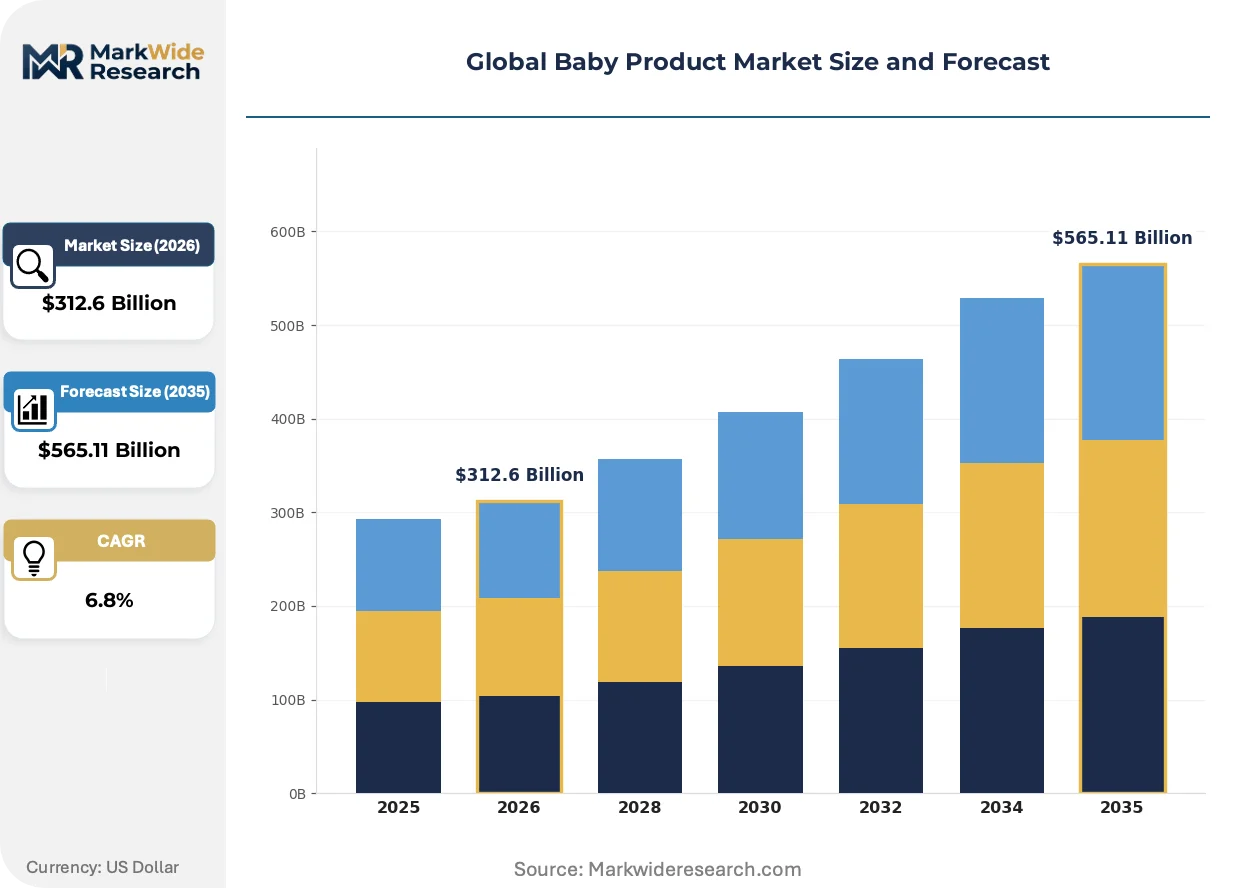
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Baby Food, Clothing, Toys Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End User: Parents, Caregivers, Maternity Hospitals, Childcare Centers Material: Organic Cotton, Polyester, Biodegradable Plastics, Silicone |
| Companies Covered | Procter & Gamble Co., Johnson & Johnson, Kimberly-Clark Corporation, Nestlé S.A., Unilever, Abbott Laboratories, Danone S.A., The Honest Company Inc., Goodbaby International Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Product Market Emerging Trajectories
Biodegradable materials, connected health monitoring, and platform-based commerce are restructuring how parents discover, purchase, and use infant care products across developed and emerging markets.
Bamboo-derived viscose and Tencel lyocell fibers are overtaking conventional cotton and synthetic blends in premium diaper and apparel segments. Millennial parents in Germany, South Korea, and California prioritize closed-loop manufacturing certifications and soil-to-soil biodegradability claims. This fiber transition is compressing commodity cotton demand while forcing textile suppliers to retool spinning and dyeing equipment for lower-temperature processing.
REACH Annex XVII restrictions on fragrance allergens and endocrine-disrupting chemicals are tightening formulation standards for baby wipes and skincare. Manufacturers must reformulate preservative systems and submit updated safety dossiers to ECHA, elevating compliance costs that disproportionately burden small and mid-tier brands. The EU regulatory pressure is propagating to Middle Eastern markets where distributors now demand REACH-equivalent documentation for import clearance.
Parents increasingly assemble personalized subscription boxes combining diapers, wipes, and developmental toys rather than purchasing categories separately. This bundle economics is displacing pharmacy and supermarket impulse purchases with algorithm-curated replenishment cycles. The behavioral shift is most visible in US coastal metro areas and Chinese tier-one cities where platform loyalty programs lock in 12-month commitments through steep introductory discounts.
Global Baby Product Market Segmentation
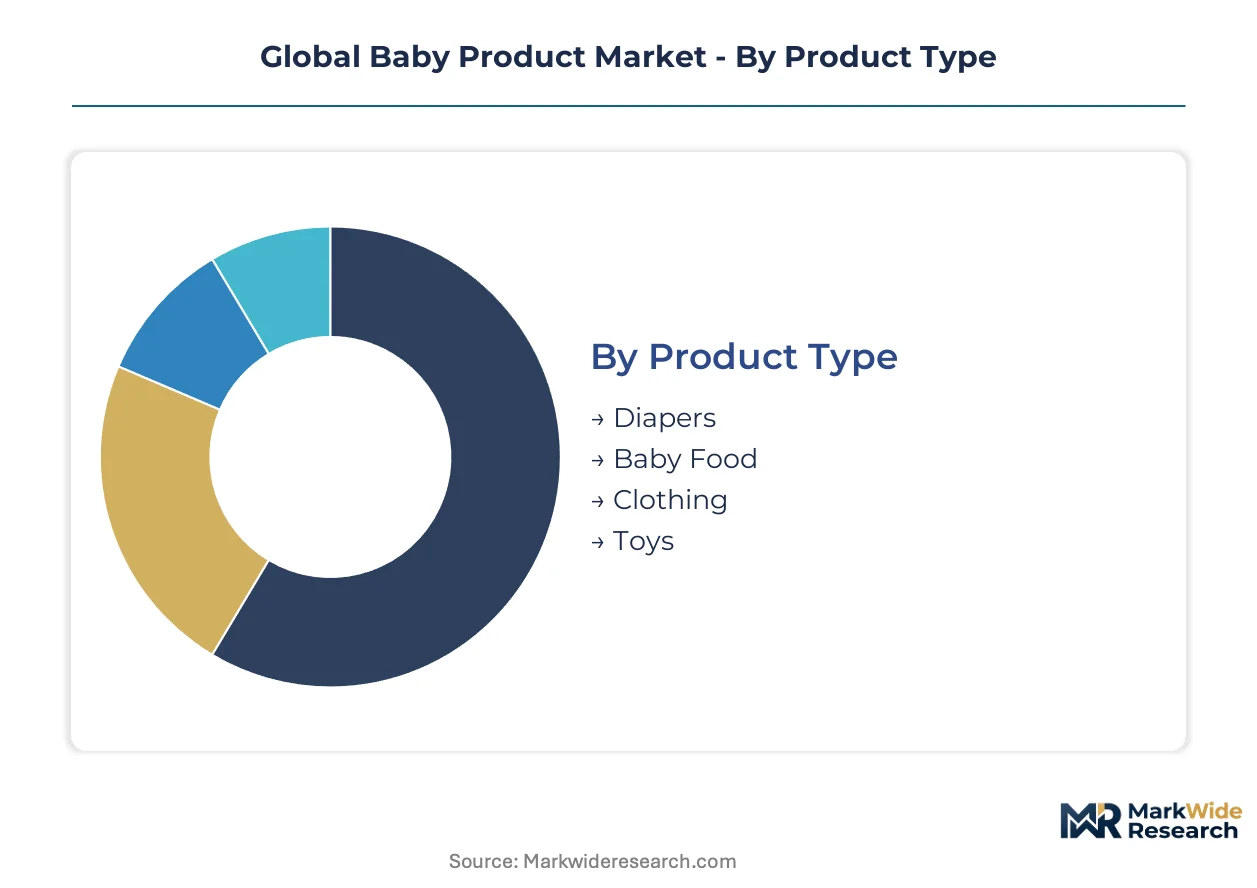
Segmentation in the baby product market reveals how purchase frequency, safety certification tiers, and channel loyalty stratify value capture across infant care categories. Manufacturers align R&D pipelines and SKU architectures to these divides, optimizing for either volume throughput or premium positioning.
Product Type:
Upgrade cycles vary dramatically across infant care categories, with consumables commanding repeat purchase relationships and durables extending replacement intervals across multiple developmental stages.
- Diapers:Superabsorbent polymer cores with plant-based absorbent layers dominate premium tier formulations. Demand concentrates in Chinese tier-one cities and US coastal metros where Millennial parents prioritize chlorine-free certification and subscription replenishment models.
- Baby Food:Organic puree pouches and hydrolyzed protein formulas address allergen-sensitive infants. EU Green Deal chemical standards and China's GB 10765 infant formula regulations reshape ingredient sourcing and labeling requirements across export markets.
- Clothing:Flame-retardant sleepwear and GOTS-certified organic cotton bodysuits address safety and skin sensitivity concerns.
- Toys:Phthalate-free plastics and FSC-certified wooden developmental tools align with REACH Annex XVII restrictions and parental toxin avoidance preferences.
Volume placements concentrate in Diapers; the faster expansion belongs to Baby Food as organic and clean-label formulations displace conventional shelf-stable options.
Distribution Channel:
Channel economics diverge sharply between inventory-light subscription platforms and fixed-cost brick-and-mortar networks, reshaping margin allocation and customer acquisition spend.
- Online Retail:Platform-based subscription bundling and Chinese live-stream commerce collapse traditional retail markups while algorithmic replenishment locks in 12-month parent commitments. This segment is expanding most quickly as pharmacy and supermarket channels cede share to personalized bundle configurations.
- Supermarkets:Impulse-driven end-cap placement and private-label tiering capture price-sensitive bulk purchasers in suburban and exurban geographies.
- Specialty Stores:Curated assortments with certified organic and Montessori-aligned educational products serve affluent urban parents seeking expert guidance.
- Pharmacies:Pharmacist-endorced skincare and clinical-grade diaper rash treatments leverage trust transfer in European and Japanese markets.
Transaction density peaks in Supermarkets; the steepest growth trajectory resides in Online Retail as platform loyalty programs consolidate purchase behavior.
End User:
Procurement authority and volume scale separate institutional buyers from individual consumers, fragmenting pricing structures and compliance documentation requirements.
- Parents:Direct purchasers evaluating total cost of ownership across subscription bundles versus single-item trials, with Millennial and Gen Z cohorts driving organic and sustainable formulation preferences.
- Caregivers:Grandparents and non-parental guardians prioritizing familiarity and pharmacy-channel trust over novel brand exploration.
- Maternity Hospitals:Bulk procurement of single-use diapers and sterile skincare kits with Joint Commission or equivalent accreditation requirements in the United States, Japan, and Germany.
- Childcare Centers:Volume purchasers subject to state-level or municipal safety inspections and allergen documentation mandates in licensed facility frameworks.
Purchase frequency concentrates in Parents; institutional volume expansion is accelerating fastest in Childcare Centers as dual-income household penetration rises across Asian and European metros.
Material:
Raw material sourcing and processing certifications increasingly determine market access eligibility, with regulatory divergence between jurisdictions forcing regional SKU customization.
- Organic Cotton:GOTS-certified fiber with closed-loop water recycling and soil-to-soil biodegradability claims. EU Ecolabel and Japan's METI carbon-labeling incentives reward domestic manufacturers with procurement preferences in institutional channels.
- Biodegradable Plastics:PLA and PHA alternatives to petroleum-based polymers in diaper backsheet films and food packaging. China's dual carbon goals and EU Green Deal chemical phase-outs accelerate substitution timelines.
- Polyester:Recycled PET and moisture-wicking synthetic blends in budget-tier apparel and wipe substrates.
- Silicone:Medical-grade platinum-cured formulations for bottle nipples and teething products meeting FDA food-contact and EU MDR safety standards.
Supply scale concentrates in Polyester; premium share gains are climbing fastest in Organic Cotton as closed-loop manufacturing certifications become table stakes for Millennial buyer conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures absorbent core materials and diaper substrates for export while the United States and Western Europe absorb premium finished goods. Production clusters concentrate in coastal provinces with chemical feedstock access, whereas consumption tilts toward markets with subscription-commerce maturity and elevated safety certification requirements.
United States
Millennial parents in coastal metros drive subscription-bundle adoption for diapers and organic skincare. FDA cosmetic registration and food-contact regulations extend product launch timelines for imported formulations. Austin and Denver host direct-to-consumer brand headquarters leveraging algorithmic replenishment to lock in 12-month parent commitments.
China
Tier-one city parents purchase through live-stream commerce platforms that collapse traditional retail markups. GB 15979 hygiene standards and GB 28007 safety requirements fragment provincial enforcement and filter subscale importers. Yangtze River Delta manufacturing clusters supply superabsorbent polymer cores to Southeast Asian assembly plants.
Germany
Nordic and urban parents substitute reusable cloth diaper systems with biodegradable liners for environmentally motivated purchase decisions. REACH Annex XVII restrictions on fragrance allergens and phthalates force preservative reformulation and elevate compliance documentation burdens. Bavaria hosts textile suppliers retooling dyeing equipment for lower-temperature bamboo-fiber processing.
India
Rising disposable incomes in Pune, Ahmedabad, and Kochi outpace organized retail penetration, creating direct-to-consumer subscription whitespace. FSSAI infant formula regulations and BIS certification requirements reshape ingredient sourcing for domestic and export markets. Maharashtra industrial corridors attract diaper manufacturers seeking proximity to petrochemical feedstock suppliers.
Japan
METI carbon-labeling incentives reward domestic manufacturers with procurement preferences in hospital and daycare institutional channels. PMDA pediatric medicine guidelines and product safety frameworks fragment certification requirements for multinational skincare portfolios. Kanto region consumers prioritize pharmacist-endorsed clinical-grade diaper rash treatments through pharmacy-channel trust transfer.
Global Baby Product Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around multinational consumer goods conglomerates with diaper and nutrition portfolios, mid-tier regional manufacturers with private-label supply contracts, and direct-to-consumer specialists with material-transparency positioning. Strategic moves center on subscription-platform infrastructure deployment and geographic expansion into Indian tier-two cities before modern trade consolidation.
Within the conglomerate tier, Procter & Gamble Co. and Kimberly-Clark Corporation occupy positions anchored by recurring revenue infrastructure and Latin American geographic dominance respectively. The Honest Company Inc. exemplifies the direct-to-consumer archetype with channel control and formulation transparency positioning. Nestlé S.A. and Danone S.A. represent nutrition-focused multinationals navigating divergent regulatory requirements across FDA, EFSA, and China NMPA jurisdictions.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Nestlé S.A. |
| Unilever |
| Abbott Laboratories |
| Danone S.A. |
| The Honest Company Inc. |
| Goodbaby International Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Millennial parents concentrated in Chinese tier-one cities and US coastal metros anchor subscription-bundle purchasing, locking manufacturers into recurring-revenue pricing models that trade upfront margin for lifetime value capture.
Pricing Analysis
Margin tightening in mid-tier private-label tiers reflects pulp and superabsorbent polymer input volatility squeezing manufacturers lacking long-term supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates chlorine-free certified subscription bundles from pharmacy-channel single-unit sales and supermarket bulk private-label packs. Cost-down pressure on standard-tier SKUs accelerates because acrylate monomer and softwood pulp spot markets feed directly into diaper margin structures. Price sensitivity concentrates in suburban supermarket shoppers; pharmacy-channel and subscription buyers exhibit lower elasticity due to trust transfer and convenience lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta superabsorbent polymer core manufacturers supplying Southeast Asian assembly plants. Raw material dependencies center on Chinese petrochemical feedstocks for acrylate monomers, Indonesian and Brazilian pulp for absorbent layers, and German textile equipment for bamboo-fiber processing. Supply chain risk manifests as tariff exposure on US-bound finished goods and REACH-equivalent documentation demands from Middle Eastern distributors. Distribution runs through platform-based subscription infrastructure in developed markets and fragmented traditional trade in Indian tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric toxicology chemist scarcity and REACH reformulation timelines constrain new product velocity, propping premium pricing for compliant incumbents while filtering subscale entrants.
For Market Incumbents: Hedge against reusable diaper substitution in Nordic and German urban markets by accelerating biodegradable liner R&D and securing GOTS-certified cotton supply contracts. Backward integration into superabsorbent polymer production in Maharashtra industrial corridors reduces exposure to Chinese petrochemical volatility. Channel control through direct-to-consumer subscription infrastructure defends margin position against platform disintermediation. For New Entrants and Emerging Players: Enter via tier-two Indian cities—Pune, Ahmedabad, Kochi—where disposable income growth outpaces organized retail penetration and subscription whitespace persists before modern trade consolidation. Live-stream commerce platforms in Chinese tier-one cities offer the most penetrable go-to-market angle for plant-based formulation trials. Algorithm-curated bundle economics displaces single-category impulse purchases, favoring entrants with platform-native capabilities over legacy retail relationships. For Investors and Strategic Acquirers: The window for entry favors direct-to-consumer specialists with material-transparency positioning and captive subscription infrastructure. Long-term viability hinges on regulatory compliance scalability across FDA cosmetic registration, EU CPNP notification, and China NMPA filing timelines. Watch provincial enforcement variations in China's GB 15979 hygiene standards as an inflection signal for import filtration intensity and domestic manufacturer procurement preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Infrastructure Deployment | Algorithmic replenishment locks 12-month parent commitments through steep introductory discounts in US coastal metros. |
| Plant-Based Absorbent Core Transition | Corn starch and bamboo fiber cores meet chlorine-free certification demanded by Millennial buyers in Germany and South Korea. |
| REACH-Equivalent Documentation Investment | ECHA safety dossiers open Middle Eastern import clearance where distributors now mandate EU-aligned compliance. |
| Biometric Monitoring Integration | Sensor-embedded diapers tracking hydration and sleep patterns converge wearable technology with infant hygiene in Japanese hospital channels. |
| Tier-Two India Geographic Expansion | Direct-to-consumer subscription whitespace in Pune and Kochi precedes modern trade consolidation and price competition. |
Methodological Framework
Independent corroboration across brand managers at multinational diaper manufacturers, category buyers at pharmacy chains, supply planners at textile suppliers, and regulatory affairs leads at skincare formulators underwrites the qualitative findings. Primary interviews with channel sales heads and subscription platform operators combined with secondary validation from FDA cosmetic registration databases, EU ECHA REACH filings, China customs records, and Nielsen retail audit data establish demand-side ground truth. Bottom-up SKU-level volume builds and top-down macroeconomic consumption trends triangulate to segment-level estimates.
Rate-of-change decomposition across the projection horizon segments volume and value by product type (diapers, baby food, clothing, toys), distribution channel (online retail, supermarkets, specialty stores, pharmacies), end user (parents, caregivers, maternity hospitals, childcare centers), and material (organic cotton, biodegradable plastics, polyester, silicone). CAGRs derive from modeled adoption curves for subscription bundling, live-stream commerce penetration, and plant-based formulation substitution. Forecast inputs incorporate REACH Annex XVII chemical restriction timelines and India FSSAI infant formula regulatory evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden pulp or acrylate monomer price spikes, abrupt China GB standard enforcement shifts, or accelerated reusable diaper adoption in EU urban markets. Forecasts reflect documented assumptions regarding birth-rate trajectories, dual-income household penetration, and platform commerce maturity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Sleeping Bag Market
Baby Products
North America Baby Bottle Market
Baby Products
Breastfeeding Accessories Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Diaper Bag Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Cloth Diapers Market
Baby Products
India Baby Care Products Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Mexico Baby Care Products Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Stroller Market
Baby Products
Baby Care Products Market
Baby Products
Baby Shoes Market
Baby Products
Asia-Pacific Baby Care Products Market