
 United Kingdom E-Commerce Market | 2026-2036
United Kingdom E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom E-Commerce Market Analytics
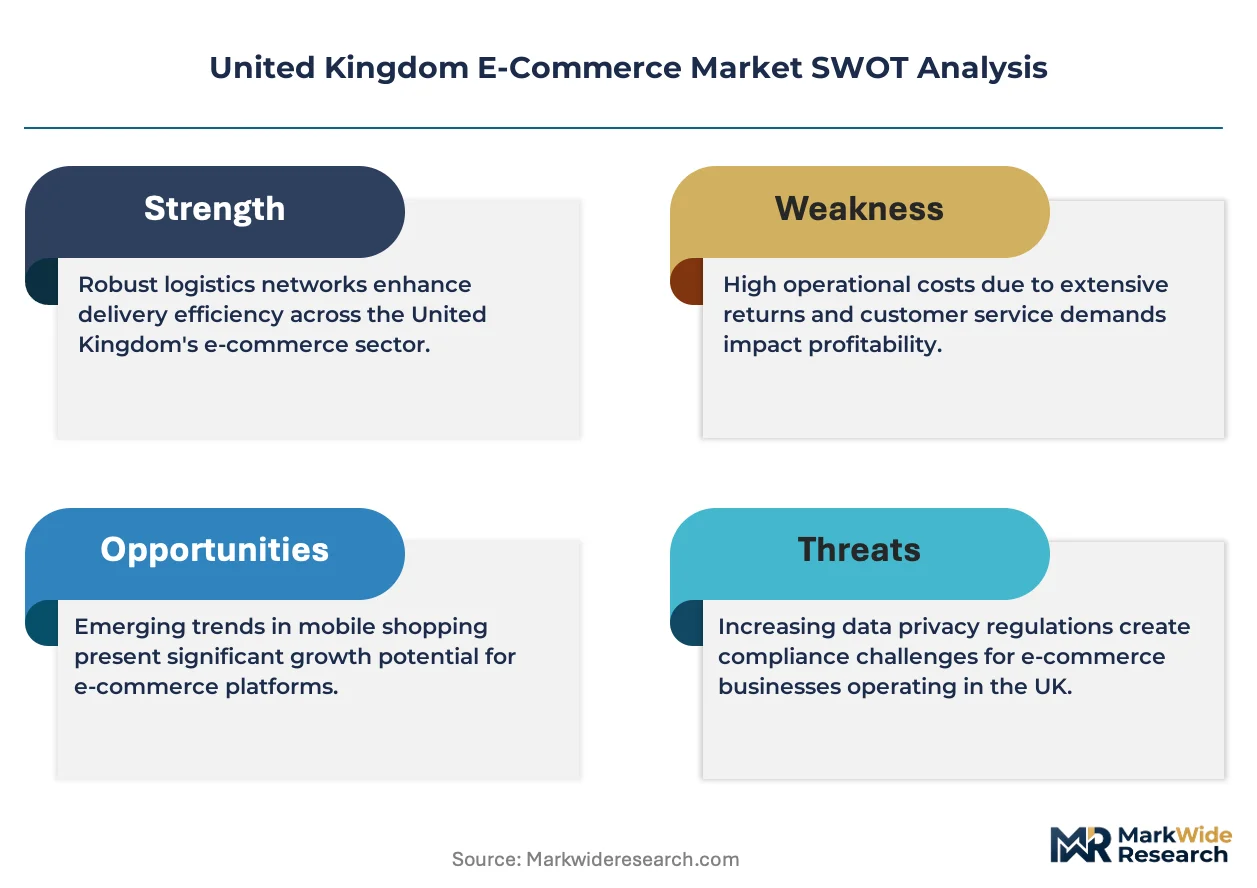
Direct-to-consumer fulfillment infrastructure is reshaping how British retailers allocate capital between owned warehouses and third-party logistics. Amazon.co.uk leverages its captive delivery network to compress lead times across grocery and general merchandise. Tesco anchors its online growth through click-and-collect integration with its store estate. Ocado specializes in automated warehouse robotics, differentiating its platform from conventional picker-based operations.
United Kingdom E-Commerce denotes the digital exchange of goods and services where transactions complete through web-based storefronts or mobile applications, with settlement occurring via encrypted payment gateways integrated into merchant platforms. Fashion and electronics command the largest share of transaction volume, though home and garden categories are expanding fastest as merchants improve bulky-item logistics. Marketplace platforms continue to aggregate consumer traffic, but buy now pay later adoption is shifting payment economics toward deferred-settlement models that alter merchant cash flow dynamics.
The UK Competition and Markets Authority scrutinizes platform pricing algorithms, while the Financial Conduct Authority governs buy now pay later providers under evolving consumer credit rules. GDPR and the UK Online Safety Bill together impose data governance and content moderation obligations that raise compliance costs for cross-border sellers. Stakeholders must weigh regulatory compliance investments against the margin compression from fulfillment speed expectations that now define customer retention.
Market Dynamics
Same-day fulfillment expectations are compressing inventory positioning decisions across British retail networks, forcing capital reallocation from marketing spend toward automated sortation and micro-fulfillment nodes in suburban corridors.
Growth Catalysts
- GDPR-compliant data infrastructure:Merchants investing in consent-management platforms capture higher lifetime value through personalized retention flows. The UK's data protection framework rewards first-party data strategies.
- Suburban grocery fulfillment:Automated picking systems and dark store networks bring fresh categories within two-hour delivery windows for households outside London's core.
- Open banking integration:Account-to-account payment rails reduce interchange costs for merchants while accelerating settlement velocity versus card networks.
Market Restraints
- Last-mile labor cost escalation:Driver availability constraints in the South East push fulfillment wages upward, eroding margin on low-basket-value orders.
- Warehousing land scarcity:Industrial zoned plots within the M25 corridor command premium lease rates, limiting network expansion for mid-scale operators.
- UK Online Safety Bill compliance burden:Content moderation obligations and age-verification requirements impose fixed operational costs disproportionate to smaller marketplace sellers.
Strategic Opportunities
- Northern England logistics penetration:Manchester and Leeds corridors offer lower fulfillment costs and underindexed e-commerce adoption relative to purchasing power.
- Buy-now-pay-later regulatory clarity:FCA consumer credit rules, once stabilized, will legitimize deferred payment products for mass-market merchant integration.
- AI-powered demand forecasting:Machine learning convergence with inventory management systems enables dynamic safety-stock reduction across seasonal categories.
Industry Challenges
- Warehouse automation engineering talent:Robotics integration and maintenance skill shortages delay deployment timelines for automated picking facilities.
- Returns processing infrastructure:Fashion and electronics categories generate reverse-logistics volume that outstrips dedicated inspection and refurbishment capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom E-Commerce Market |
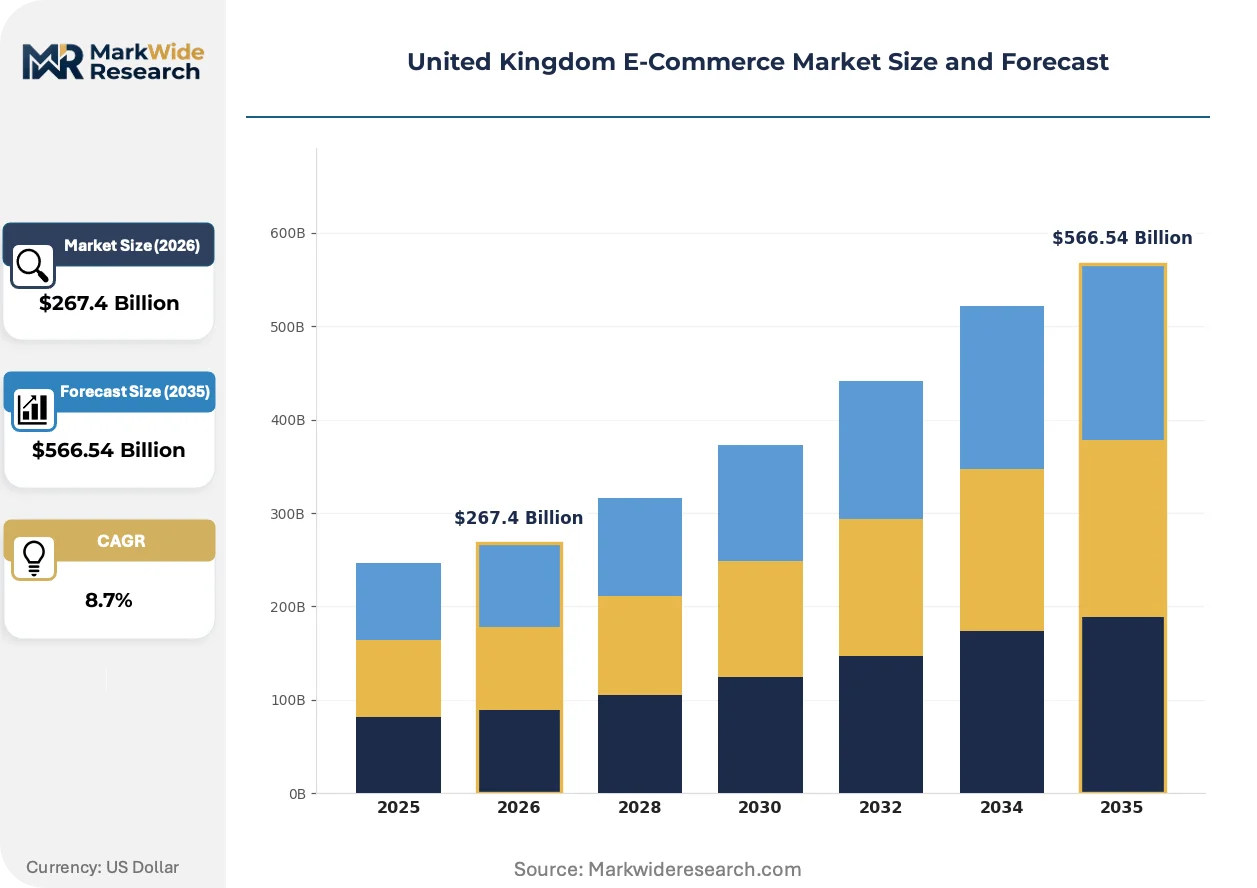
| Market Size in 2026 | $267.4 Billion |
| Market Size in 2035 | $566.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home & Garden, Health & Beauty Customer Type: Individuals, Small Businesses, Enterprises, Government Sales Channel: Direct-to-Consumer, Marketplace Platforms, Subscription Services, Social Media Payment Method: Credit Card, Debit Card, PayPal, Buy Now Pay Later |
| Companies Covered | Amazon.co.uk, eBay, Tesco, Sainsbury's, Asda, Argos, Ocado, Next, Currys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom E-Commerce Market Evolving Landscape
Algorithmic inventory positioning and embedded finance products are restructuring how British merchants acquire customers and manage working capital, compressing the traditional separation between transaction completion and fulfillment execution.
Automated warehouse robotics is migrating from centralized regional hubs toward smaller urban micro-fulfillment centers. Grocery specialists and quick-commerce operators deploy compact picking systems in repurposed retail units. This technology is migrating from capital-intensive greenfield builds toward retrofit configurations that reduce deployment timelines from years to months.
The UK Online Safety Bill imposes duty-of-care obligations on platforms regarding illegal content and age-appropriate design. Marketplace operators must invest in automated content classification and human moderation layers. Fashion and electronics marketplaces face particular scrutiny given counterfeit and unsafe product risks in third-party seller catalogs.
Subscription-based replenishment models are displacing discretionary basket-building in household consumables. British shoppers lock into automated delivery schedules for pet food, personal care, and cleaning products. This pattern concentrates most visibly in Greater London and the South East, where delivery density supports economically viable subscription economics.
United Kingdom E-Commerce Market Segmentation
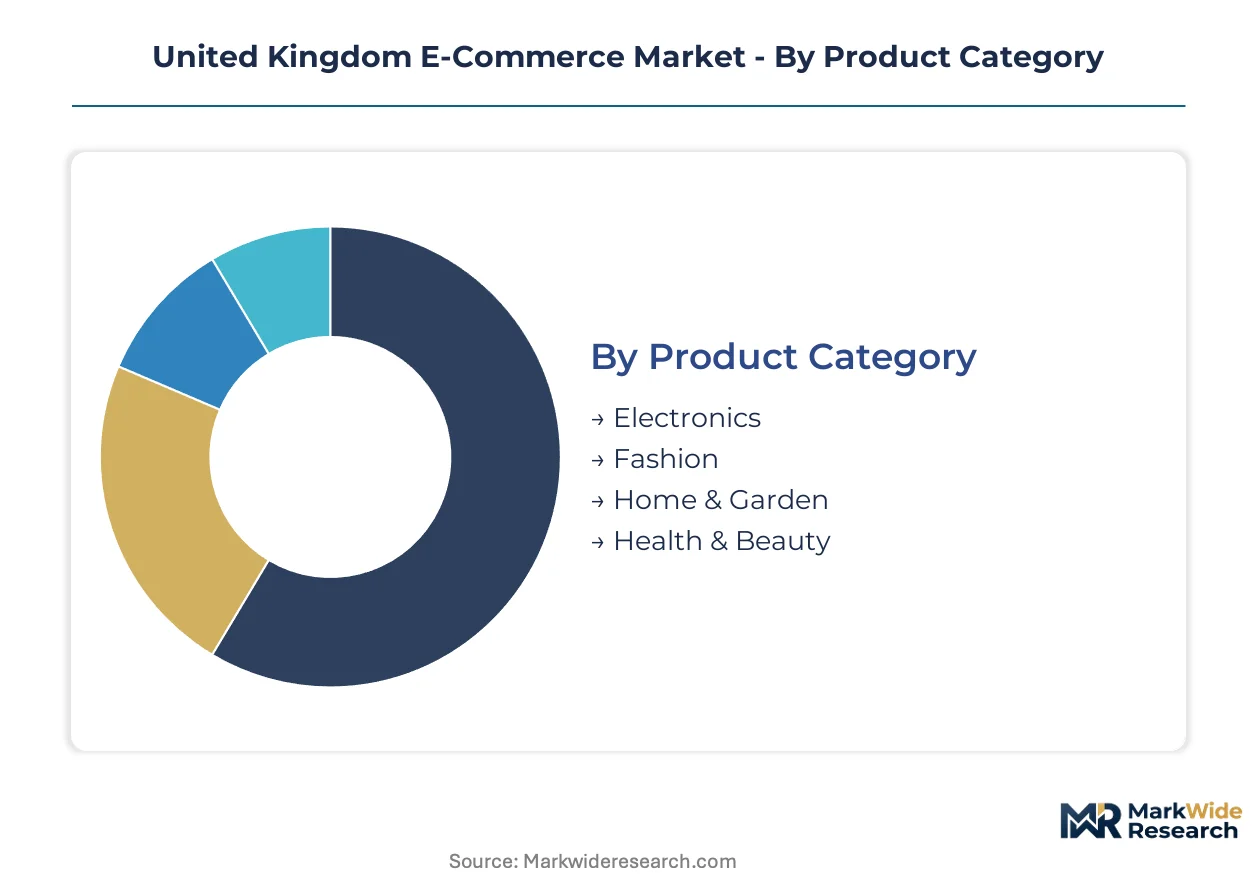
Segmentation in United Kingdom E-Commerce reveals how purchasing behavior fragments across product types, customer scale, and transaction mechanics. Understanding these divisions illuminates where fulfillment investments and regulatory compliance burdens concentrate most intensely.
Product Category:
Electronics and fashion dominate basket composition, while home and garden categories exploit improved bulky-item logistics to expand addressable demand.
- Electronics:High-consideration purchases involving smartphones, laptops, and consumer appliances with extended warranty attachments. Demand clusters in Greater London and the South East where disposable income supports premium device refresh cycles and same-day delivery expectations compress merchant margins.
- Fashion:Apparel and footwear transactions characterized by high return rates and seasonal inventory velocity. Returns processing infrastructure in the Midlands struggles to match the volume generated by online fitting-room behavior, creating working capital strain for mid-scale retailers.
- Home & Garden:Furniture, DIY supplies, and outdoor equipment requiring specialized last-mile handling. Two-person delivery teams and assembly services differentiate fulfillment quality in suburban corridors outside Manchester and Leeds.
- Health & Beauty:Personal care products and cosmetics with subscription replenishment potential. Regulatory scrutiny from the UK's product safety frameworks elevates compliance costs for cross-border sellers in this category.
The dominant share belongs to Electronics, while Home & Garden is closing the gap fastest as logistics capabilities mature for oversized parcel handling.
Customer Type:
Transaction scale determines payment method acceptance, fulfillment service tier, and account management overhead across the merchant base.
- Individuals:Consumer purchasers driving volume through mobile-optimized checkout flows and buy now pay later adoption. GDPR-compliant consent management becomes essential for personalized retention marketing at this scale.
- Small Businesses:B2B procurement of office supplies, equipment, and professional services with negotiated payment terms. Open banking integration reduces interchange costs and accelerates settlement velocity versus traditional card networks.
- Enterprises:Large-scale purchasing with dedicated account management, volume pricing, and customized fulfillment SLAs. Procurement platforms integrate directly with merchant ERP systems for automated reordering.
- Government:Public sector procurement through framework agreements with stringent transparency and audit requirements. The UK Online Safety Bill imposes additional duty-of-care obligations on platforms serving this segment.
Individuals command absolute transaction volume, though Enterprises generate the highest revenue per order and lowest return rates.
Sales Channel:
Channel selection shapes customer acquisition economics, inventory ownership, and brand control intensity for British merchants.
- Direct-to-Consumer:Owned storefronts and mobile applications capturing first-party data and full margin. Amazon.co.uk's captive delivery network forces independents to match compressed lead times or concede suburban grocery and general merchandise demand.
- Marketplace Platforms:Aggregated traffic environments with commission structures and fulfillment service options. The UK Competition and Markets Authority scrutinizes pricing algorithms and seller treatment practices in these environments.
- Subscription Services:Automated replenishment models for consumables with predictable demand forecasting. Pet food and personal care lock-ins concentrate in Greater London delivery density corridors.
- Social Media:Discovery-driven purchasing through integrated checkout and influencer attribution. Age-verification requirements under the UK Online Safety Bill complicate platform operations in this channel.
Marketplace Platforms aggregate the widest consumer reach, while Subscription Services demonstrate the stickiest retention economics and lowest customer acquisition cost.
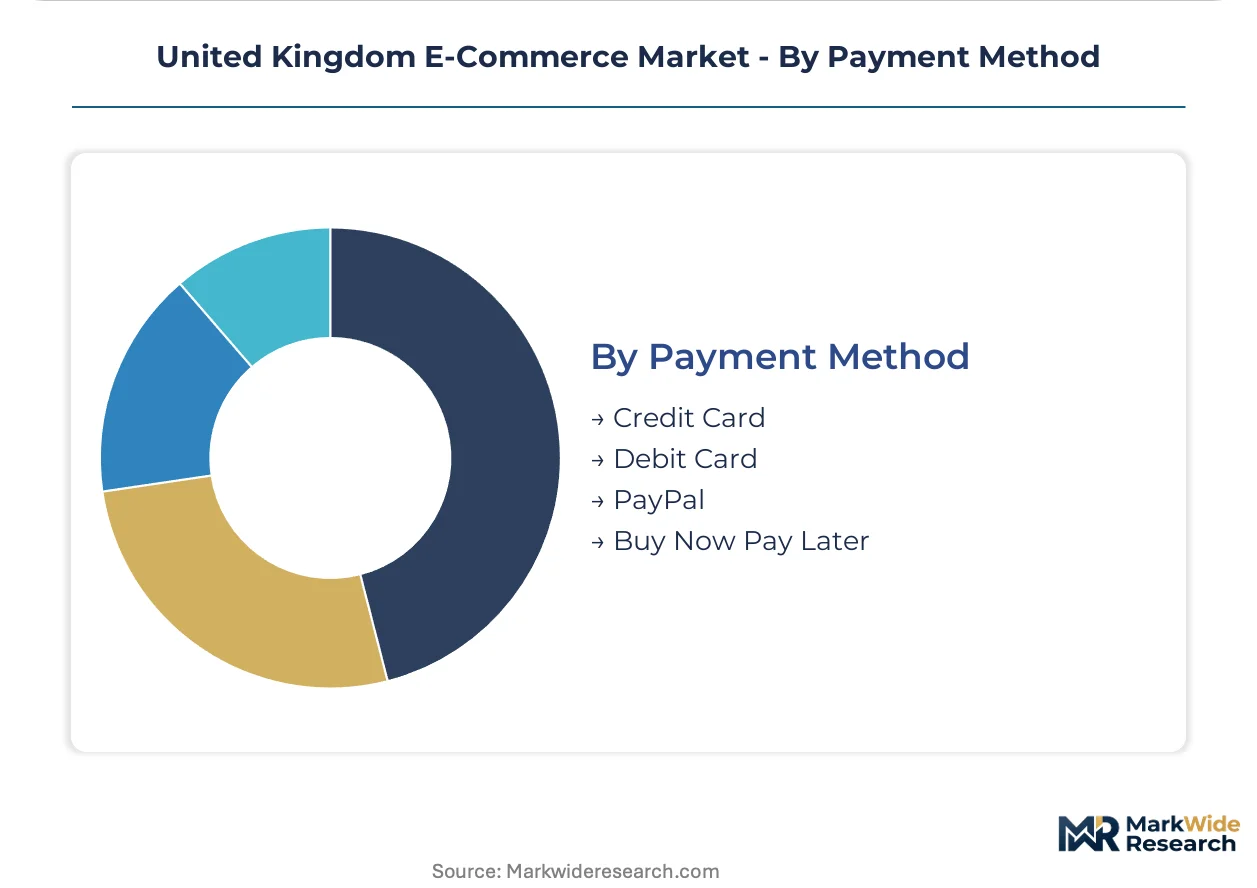
Payment Method:
Settlement mechanics influence merchant cash flow timing, fraud exposure, and regulatory compliance scope under evolving consumer credit frameworks.
- Credit Card:Dominant online payment rail with chargeback protection and reward program integration. Interchange fees erode margin on low-basket-value orders, particularly in grocery categories.
- Debit Card:Immediate settlement without credit risk exposure for merchants. Open banking account-to-account rails threaten displacement of debit volume as merchants seek cost reduction.
- PayPal:Wallet-based checkout with stored credentials and buyer protection programs. Trust signals reduce cart abandonment for first-time merchant relationships.
- Buy Now Pay Later:Deferred settlement products shifting payment economics toward installment models. The Financial Conduct Authority's evolving consumer credit rules will legitimize or constrain mass-market merchant integration pending regulatory clarity.
Credit Card and Debit Card together settle the majority of transaction value, though Buy Now Pay Later is expanding most quickly among younger demographics and fashion purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Financial Conduct Authority governs payment innovation and consumer credit frameworks across England, Scotland, Wales and Northern Ireland. Regional fulfillment economics diverge sharply between the M25 corridor and peripheral zones.
Greater London and South East
Disposable income concentration drives premium electronics demand and same-day delivery expectations. The UK Online Safety Bill imposes duty-of-care obligations on platforms serving this dense consumer base. Automated micro-fulfillment centers in Croydon and Slough compress grocery lead times below two hours.
Midlands
Central warehouse positioning minimizes national distribution lead times for bulky home and garden categories. GDPR-compliant data infrastructure investments cluster around Birmingham's logistics tech corridor. Returns processing facilities in Leicester struggle with fashion category reverse-logistics volume from London-directed orders.
North England
Manchester and Leeds corridors offer underindexed e-commerce adoption relative to household purchasing power. Open banking integration reduces merchant interchange costs as regional fintech adoption accelerates. Dark store networks in Liverpool and Newcastle expand fresh grocery reach beyond traditional supermarket catchments.
Scotland
Edinburgh and Glasgow sustain concentrated demand for subscription replenishment models in health and beauty categories. The UK's data protection framework rewards first-party data strategies among Scottish direct-to-consumer brands. Aberdeen's energy sector workforce generates above-average electronics refresh cycles.
Wales
South Wales corridors connect to Bristol fulfillment networks with lower last-mile labor costs than the South East. Warehouse automation engineering talent shortages delay robotic picking deployment in Cardiff. Cross-border logistics integration with England dominates merchant network design decisions.
United Kingdom E-Commerce Market Competitive Landscape
Marketplace aggregators and integrated grocery retailers split the market between traffic ownership and fulfillment control. Three archetypes dominate: pure-play digital marketplaces, omnichannel supermarket operators, and specialized logistics-technology platforms. Consolidation pressure intensifies as Amazon.co.uk's captive delivery network forces margin compression on independent merchants. Strategic moves concentrate on automated warehouse robotics deployment and click-and-collect estate integration.
Among marketplace aggregators, Amazon.co.uk and eBay occupy positions defined by traffic scale and third-party seller dependency. Tesco and Sainsbury's exemplify the omnichannel archetype, leveraging store estates for fulfillment integration. Ocado sits within the logistics-technology tier, differentiating through automated warehouse robotics rather than conventional picker-based operations. These three archetypes represent the competitive structure governing capital allocation between owned infrastructure and third-party service reliance.
| Leading Market Players |
|---|
| Amazon.co.uk |
| eBay |
| Tesco |
| Sainsbury's |
| Asda |
| Argos |
| Ocado |
| Next |
| Currys |
| Others |
Value Network & Pricing Analysis
Chinese warehouse robotics manufacturers and Dutch automated picking system suppliers anchor capital equipment pricing for British fulfillment operators, concentrating margin capture upstream while UK retailers absorb downstream pressure from same-day delivery expectations.
Pricing Analysis
Greater London commands 15-20% fulfillment premiums over Northern England corridors due to last-mile labor scarcity and M25 warehouse rent escalation. Three-tier pricing structure across premium, standard, and economy levels stratifies around delivery speed guarantees and returns flexibility. Cost compression in economy tiers is intensifying because Amazon.co.uk's captive network forces margin matching on independents. Small businesses exhibit highest price sensitivity, while enterprise procurement with customized SLAs shows lowest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-finance arrangements for warehouse automation vendors serving British retailers. Equipment sourcing draws from China, Germany, and the Netherlands for robotics hardware, conveyor systems, and control software. Dependencies on lithium-ion battery cells, precision sensors, and aluminum extrusion frames create vulnerability. Single-source vulnerability concentrates in proprietary software licenses for automated picking algorithms. Distribution runs through regional system integrators with direct manufacturer relationships for Tier 1 grocery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK E-Commerce market sits within a post-pandemic cyclical recovery as suburban household penetration normalizes and fulfillment infrastructure investment cycles mature.
For Market Incumbents: Entrench automated warehouse robotics deployment ahead of labor cost inflection in the South East. Ocado's technology licensing model threatens to commoditize proprietary fulfillment advantages; defend through backward integration into micro-fulfillment real estate in Manchester and Leeds corridors. Channel control via click-and-collect estate integration remains the critical defensive lever against pure-play marketplace erosion. For New Entrants and Emerging Players: Build out subscription replenishment infrastructure in health and beauty categories where Scottish and Welsh markets show underindexed penetration relative to disposable income metrics. Northern England logistics corridors offer the most penetrable geography given lower fulfillment cost bases and lagging e-commerce adoption. A direct-to-consumer launch with GDPR-compliant first-party data architecture enables retention economics that marketplace dependence cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated grocery fulfillment as robotics deployment timelines compress from years to months. Long-term viability favors platforms with owned logistics technology rather than third-party service reliance. Acquisition targets should display integrated software-warehouse capabilities or dense suburban real estate positions. The signal to watch is FCA regulatory clarity on buy-now-pay-later consumer credit rules, which will determine deferred payment product legitimacy and merchant integration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Robotics Deployment | Ocado's licensing model accelerates technology diffusion beyond capital-intensive greenfield builds. |
| Micro-Fulfillment Real Estate Acquisition | Suburban dark stores in Croydon and Slough compress grocery lead times below two-hour thresholds. |
| GDPR-Compliant First-Party Data Infrastructure | Consent-management platforms enable personalized retention flows that third-party cookies cannot replicate. |
| Open Banking Payment Integration | Account-to-account rails reduce interchange costs and accelerate settlement velocity versus card networks. |
| Subscription Replenishment Model Expansion | Automated delivery schedules for consumables lock in retention economics in Greater London density corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with grocery fulfillment directors, warehouse automation engineers, logistics procurement managers, and regulatory compliance officers at marketplace platforms. Secondary validation drew from UK Competition and Markets Authority filings, Financial Conduct Authority consumer credit consultations, Companies House registry data, and industrial real estate lease transaction records. Bottom-up merchant revenue estimates and top-down macro consumption indicators were triangulated to anchor market sizing.
Calibration against historical fulfillment infrastructure deployment rates and payment method adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, customer type, sales channel, and payment method, with additional granularity on delivery speed tier and returns policy structure. CAGRs were derived from logistic diffusion curves fitted to suburban grocery penetration patterns and automated warehouse robotics installation trajectories. Forecast inputs incorporated South East labor cost indices and M25 industrial land availability constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by quick-commerce specialists or regulatory acceleration on buy-now-pay-later rules would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Direct-To-Consumer Test Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Kuwait E-Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Ambient Commerce Enablement Infrastructure Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market