
 Turkey E-Commerce Market | 2026-2036
Turkey E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey E-Commerce Market Outlook
Asset-light marketplace models and third-party logistics leasing are fragmenting capital requirements across Turkey's e-commerce landscape. Trendyol leverages its captive delivery network to control fulfillment costs in dense urban zones. Hepsiburada anchors its position through backward integration into warehousing and last-mile infrastructure. Amazon Turkey competes by extending its global supplier relationships to Turkish merchants seeking cross-border reach.
Turkey e-commerce denotes digital retail transactions conducted through web-based platforms and mobile applications, encompassing product discovery, payment processing, and order fulfillment via integrated logistics networks. The sector operates on real-time inventory synchronization, secure payment gateways, and algorithmic recommendation engines that match consumer preferences with available stock. Electronics and apparel dominate transaction volumes, with electronics sustaining higher average order values and apparel generating more frequent purchase cycles. B2C channels capture the majority of consumer spending, while D2C models are gaining traction as domestic brands bypass intermediary platforms to retain margin pools and customer data.
Turkey's Banking Regulation and Supervision Agency (BDDK) oversees digital payment licensing, while the Personal Data Protection Authority (KVKK) mandates consent frameworks for consumer information handling. KVKK compliance costs are pushing smaller merchants toward platform-enclosed ecosystems where data governance is managed centrally. BDDK e-wallet regulations are accelerating bank-fintech partnerships that expand credit-accessible checkout options. Stakeholders must monitor how evolving data localization requirements and payment infrastructure rules reshape platform economics and merchant onboarding barriers.
Market Dynamics
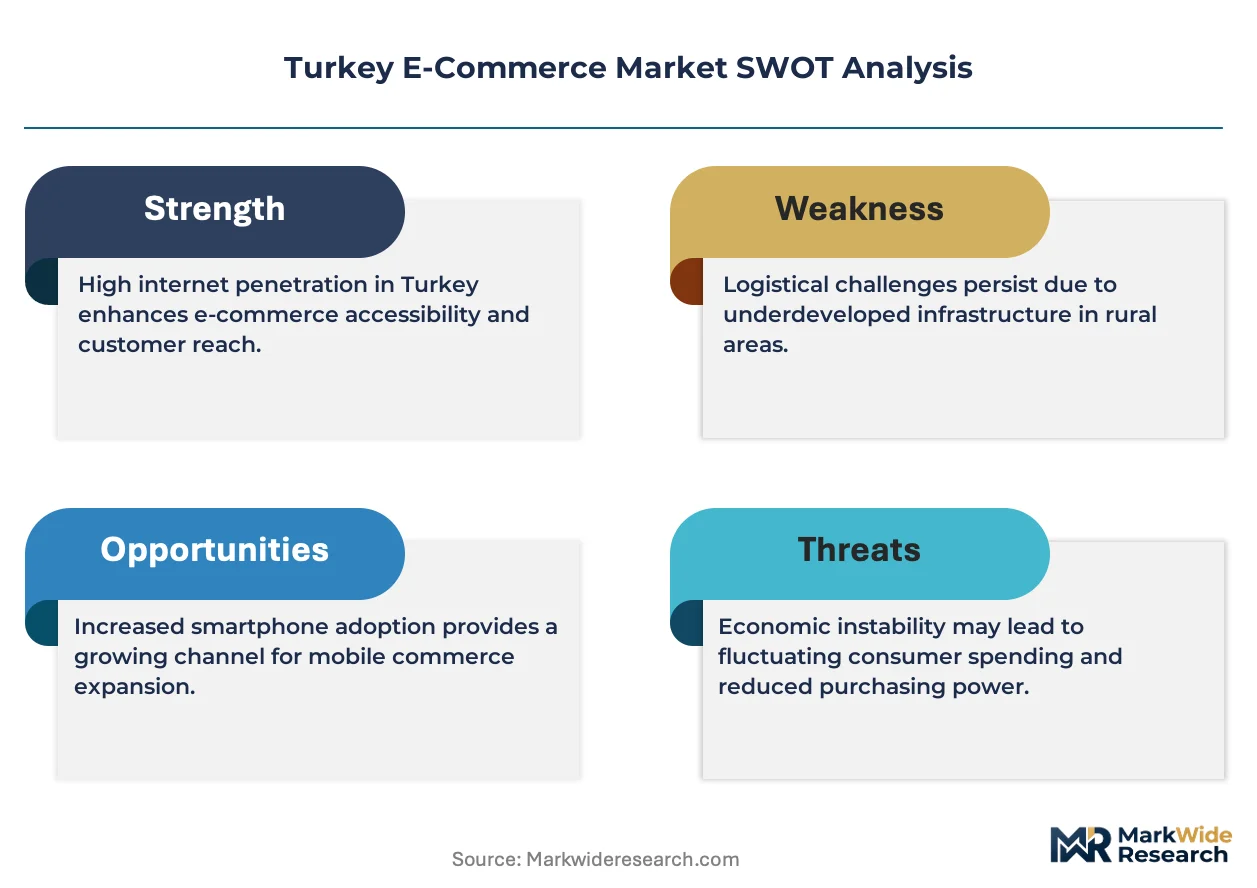
KVKK consent frameworks and BDDK digital wallet licensing are restructuring platform economics, pushing merchant consolidation toward enclosed ecosystems where compliance costs concentrate.
Growth Catalysts
- Smartphone penetration corridors:Istanbul, Ankara, and Izmir generate concentrated demand density where logistics networks achieve route optimization at scale.
- BDDK fintech partnerships:Bank-fintech collaborations expand credit-accessible checkout options, reducing cart abandonment in high-ticket electronics categories.
- Gen Z purchase frequency:Urban millennials and younger cohorts drive apparel transaction velocity through mobile-first discovery and social commerce integration.
Market Restraints
- KVKK compliance cost structure:Data governance mandates impose fixed operational burdens that disproportionately burden small merchants with limited legal resources.
- Last-mile logistics concentration:Dense urban zones capture infrastructure investment while Anatolian hinterlands suffer delivery cost penalties and extended fulfillment windows.
- Cash-on-delivery persistence:Traditional payment methods retain significant share in peripheral regions, limiting working capital efficiency for platform operators.
Strategic Opportunities
- Anatolian city penetration:Secondary urban centers beyond the three primary corridors present underdeveloped logistics density ripe for third-party fulfillment partnerships.
- D2C brand migration:Domestic apparel and electronics manufacturers bypass intermediary platforms to capture margin pools and first-party customer data.
- Cross-border merchant enablement:Global supplier relationship extensions allow Turkish sellers access to international fulfillment networks and expanded addressable markets.
Industry Challenges
- Data localization infrastructure:Evolving KVKK server requirements force platform re-architecture and cloud provider switching costs.
- Algorithmic inventory synchronization:Real-time stock matching across fragmented merchant bases demands specialized technical talent scarce in domestic labor markets.
- Payment gateway fragmentation:Multiple e-wallet standards and bank API inconsistencies complicate checkout integration and increase engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey E-Commerce Market |
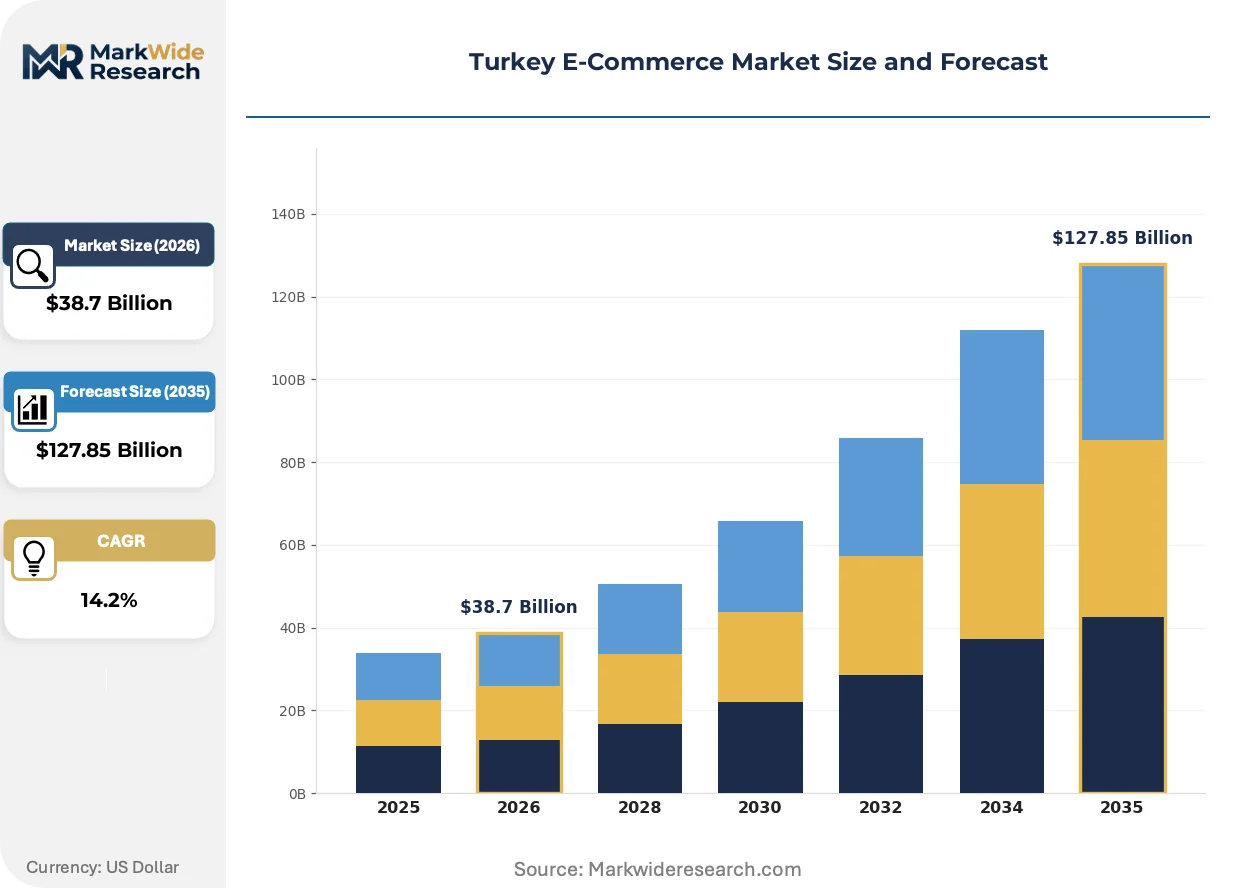
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Appliances, Cosmetics Customer Type: B2C, C2C, B2B, D2C Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Delivery Mode: Standard Shipping, Express Delivery, Click & Collect, Same-Day Delivery |
| Companies Covered | Trendyol, Hepsiburada, Amazon Turkey, n11, Sahibinden, Teknosa, PTTAVM, Getir, Yemeksepeti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey E-Commerce Market Strategic Shifts
Algorithmic recommendation engines and captive delivery networks are compressing fulfillment timelines while regulatory data frameworks reshape platform architecture requirements.
AI-powered demand forecasting is rendering obsolete manual inventory planning across Trendyol's captive logistics network. Urban fulfillment centers deploy machine learning models that predict neighborhood-level consumption patterns with 48-hour precision. Traditional warehouse stocking methodologies are rendering obsolete as automated replenishment triggers replace buyer intuition.
KVKK consent management mandates require explicit opt-in frameworks for every data processing instance. Platforms must now maintain auditable consent chains from discovery through post-purchase marketing. Apparel merchants with complex retargeting operations face the steepest reconfiguration costs as they rebuild attribution models around permission-based data flows.
Social commerce discovery is displacing traditional search-based product finding among Istanbul's younger demographics. Influencer-curated storefronts and live-stream purchasing events capture attention that previously flowed through category browsing. Electronics and fast fashion verticals show the strongest channel rotation toward content-integrated checkout experiences.
Turkey E-Commerce Market Segmentation
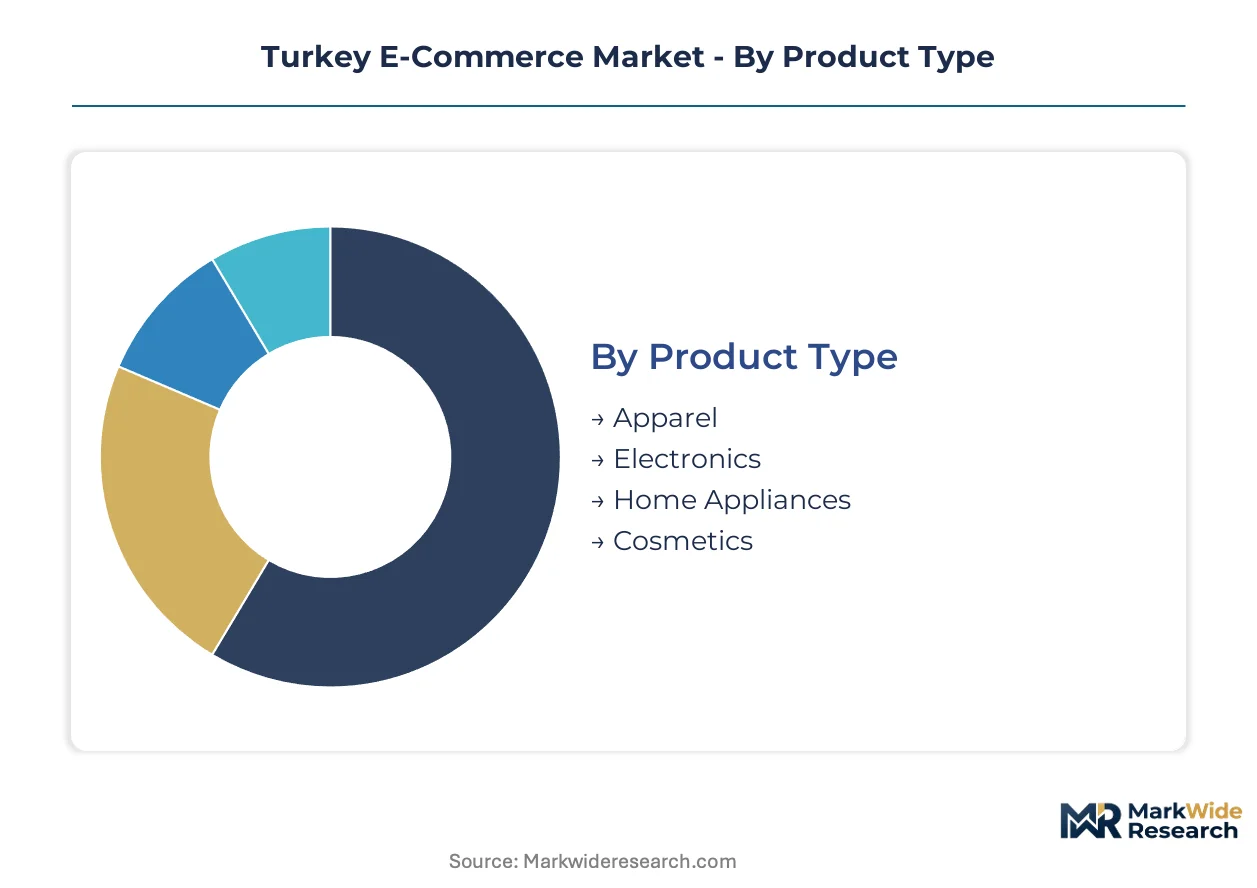
Turkey's e-commerce segmentation reveals how transaction mechanics, fulfillment preferences, and purchasing relationships fragment into distinct operational models. Each dimension carries specific infrastructure requirements and margin implications for platform operators and merchants.
Product Type:
Cost tier differentiation separates high-velocity, low-margin categories from capital-intensive segments requiring specialized handling and warranty infrastructure.
- Apparel:Fast fashion and seasonal collections drive repeat purchase frequency through mobile-first discovery. Istanbul's urban millennials sustain the highest transaction velocity, though return rates compress net margins for marketplace operators managing reverse logistics.
- Electronics:Smartphones, laptops, and accessories command elevated average order values with extended decision cycles. Ankara's professional workforce concentrates demand for business-grade equipment, while KVKK compliance adds documentation burden to warranty and repair data handling.
- Home Appliances:Refrigerators, washing machines, and climate systems require white-glove delivery and installation coordination. Izmir's new residential developments generate concentrated demand for full-suite kitchen and laundry purchases.
- Cosmetics:Skincare and color cosmetics leverage influencer-driven discovery with subscription replenishment models. Regulatory scrutiny from Turkey's Ministry of Agriculture and Forestry shapes import documentation for international brands.
Electronics holds installed capacity. Cosmetics is rotating up the share rankings.
Customer Type:
Channel architecture determines who controls customer data, pricing power, and fulfillment quality across Turkey's digital retail landscape.
- B2C:Established marketplaces aggregate merchant inventory under centralized discovery and payment infrastructure. Trendyol and Hepsiburada dominate transaction volume through captive logistics networks and algorithmic personalization engines.
- C2C:Peer-to-peer resale platforms enable individual sellers to liquidate pre-owned goods. Trust mechanisms and escrow services address fraud concerns that limit category expansion beyond collectibles and electronics.
- B2B:Wholesale procurement platforms serve Istanbul's manufacturing and retail sectors with volume-tiered pricing and trade credit facilities. BDDK-regulated payment terms complicate working capital structures for cross-border supplier relationships.
- D2C:Domestic apparel and electronics manufacturers bypass intermediary platforms to capture first-party customer data and margin pools. KVKK consent frameworks enable direct retargeting without platform-mediated attribution.
B2C maintains transaction dominance. D2C is climbing the fastest as brands seek data sovereignty.
Payment Method:
Settlement infrastructure maturity shapes checkout conversion rates and merchant cash flow predictability across Turkey's fragmented banking landscape.
- Credit Card:Installment plans spanning 3-12 months sustain high-ticket electronics purchases. BDDK oversight of interest rate disclosures adds compliance overhead to promotional financing campaigns.
- Debit Card:Immediate settlement reduces chargeback risk for merchants while limiting consumer purchasing power. Anatolian hinterlands show higher debit preference due to limited credit access.
- E-Wallet:Papara, Paycell, and bank-integrated digital wallets accelerate checkout completion on mobile devices. BDDK licensing requirements concentrate provider base toward established fintech-bank partnerships.
- Bank Transfer:Manual remittance persists for B2B transactions and cash-preferred demographics. Settlement delays create working capital friction for smaller merchants.
Credit Card holds transaction value concentration. E-Wallet is gaining share fastest through mobile-first user acquisition.
Delivery Mode:
Fulfillment speed tiers segment customers by urgency tolerance and urban density, with infrastructure investment concentrating where route optimization achieves scale.
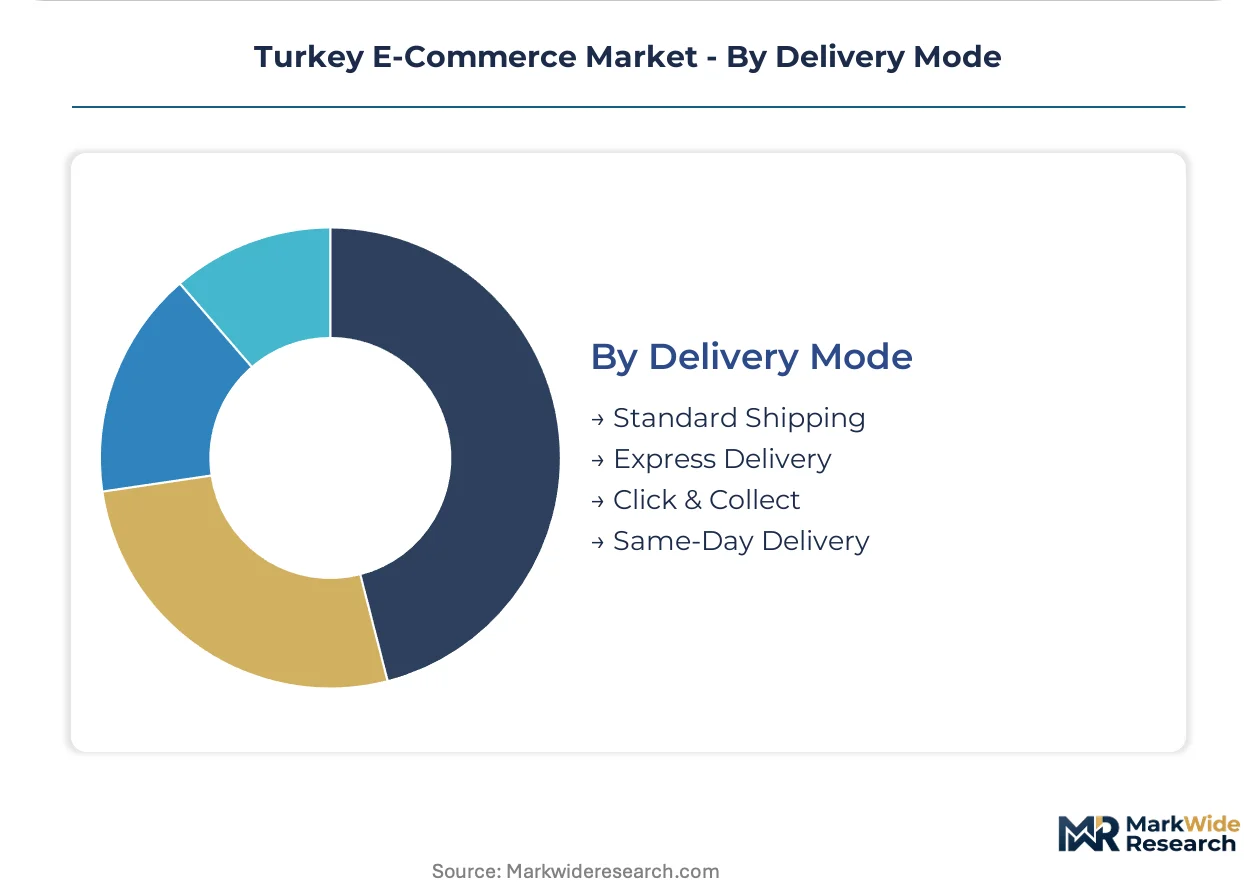
- Standard Shipping:2-5 day delivery windows minimize per-order logistics cost through batch consolidation. Anatolian secondary cities rely almost exclusively on this tier due to infrastructure gaps.
- Express Delivery:24-48 hour commitment commands premium pricing for time-sensitive purchases. Istanbul's dense districts enable profitable express operations through Trendyol's captive fleet.
- Click & Collect:Locker networks and partner retail locations reduce last-mile failure rates. Students and working professionals in Izmir favor pickup flexibility over home delivery scheduling.
- Same-Day Delivery:Ultra-rapid fulfillment requires micro-fulfillment centers within 15 kilometers of demand clusters. Electronics and urgent apparel replacements sustain this tier's economics in Ankara's core districts.
Standard Shipping maintains volume leadership. Same-Day Delivery is expanding most quickly through urban micro-fulfillment investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennials and Gen Z consumers concentrate in Turkey's three primary metropolitan corridors, where smartphone penetration and logistics density create self-reinforcing e-commerce adoption loops. Istanbul, Ankara, and Izmir generate the majority of transaction volume, while secondary Anatolian cities present underdeveloped infrastructure with latent demand potential. Provincial hinterlands remain constrained by cash-on-delivery persistence and extended fulfillment windows.
Marmara Region
Istanbul anchors national e-commerce volume through its captive logistics networks and micro-fulfillment center density. The Personal Data Protection Authority enforces KVKK consent frameworks that reshape platform data architecture requirements. The city's European and Anatolian sides host competing fulfillment hubs where Trendyol and Hepsiburada operate dedicated last-mile fleets.
Central Anatolia
Ankara's professional workforce sustains elevated demand for business-grade electronics and subscription replenishment services. The Banking Regulation and Supervision Agency oversees digital wallet licensing that accelerates bank-fintech partnerships across the capital. The Çankaya and Yenimahalle districts concentrate same-day delivery investment for urgent apparel and device replacement purchases.
Aegean Region
Izmir's new residential developments generate concentrated demand for white-glove home appliance delivery and installation coordination. Municipal zoning regulations influence fulfillment center placement along the İzmir-Ankara highway corridor. Bornova and Karşıyaka districts serve as logistics nodes connecting the port city's import infrastructure to Anatolian distribution networks.
Mediterranean Region
Antalya's tourism economy creates seasonal demand spikes for electronics and fast fashion among transient populations and hospitality sector procurement. Provincial commercial codes govern B2B wholesale platform operations serving the region's manufacturing base. The Kepez and Muratpaşa districts host emerging locker networks and click-and-collect infrastructure.
Black Sea Region
Samsun and Trabzon present logistics cost penalties due to mountainous terrain and limited express delivery infrastructure. Central bank payment system regulations extend digital wallet access to regional banking partnerships. These secondary urban centers rely predominantly on standard shipping tiers with 2-5 day fulfillment windows.
Turkey E-Commerce Market Competitive Environment
Channel-controlling players compete with product-specialist players across Turkey's fragmented e-commerce structure. Marketplace operators with captive logistics networks command pricing power in dense urban zones, while electronics and apparel specialists defend margin pools through category expertise. Three archetypes dominate: integrated marketplace-logistics hybrids, category-focused vertical platforms, and cross-border enablers extending international reach. Consolidation pressures concentrate around M&A activity targeting fulfillment infrastructure and strategic partnerships bridging bank-fintech payment integration.
Within the integrated marketplace tier, Trendyol and Hepsiburada exemplify divergent fulfillment strategies—one leveraging asset-light third-party logistics leasing, the other anchoring position through backward integration into warehousing infrastructure. Amazon Turkey occupies a position as cross-border enabler, extending global supplier relationships to domestic merchants seeking international market access.
| Leading Market Players |
|---|
| Trendyol |
| Hepsiburada |
| Amazon Turkey |
| n11 |
| Sahibinden |
| Teknosa |
| PTTAVM |
| Getir |
| Yemeksepeti |
| Others |
Value Chain & Pricing Dynamics
Istanbul's fulfillment center density compresses logistics costs for same-day delivery tiers, translating into pricing power for operators controlling captive last-mile fleets. Merchants outside the Marmara corridor absorb delivery surcharges that widen the landed cost gap between urban and peripheral demand zones.
Pricing Analysis
Delivery speed tier creates the primary spread between standard and express checkout options. Three-tier pricing structure across same-day, express, and standard shipping levels captures urgency-based willingness to pay. Cost compression in standard shipping is intensifying because third-party logistics providers compete on batch consolidation efficiency. Small merchants in Anatolian hinterlands exhibit highest price sensitivity due to limited order volume leverage, while Istanbul-based electronics retailers show lowest sensitivity when warranty bundling justifies premium tiers.
Supply Chain Analysis
Export-control regimes on semiconductor components limit flows from Taiwan, South Korea, and USA into Turkish electronics assembly. Smartphone chipsets, lithium-ion cells, and display panels draw from concentrated East Asian manufacturing bases. Single-source vulnerability in advanced processor supply creates inventory risk during geopolitical friction periods. Distribution runs through Istanbul's bonded warehouses before Anatolian redistribution via trucking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's e-commerce sector sits in a cyclical recovery phase as post-inflationary consumer confidence rebuilds through BDDK-enabled credit expansion. Installment financing penetration serves as the cyclical driver normalizing high-ticket electronics purchasing patterns.
For Market Incumbents: Insulate margin pools by deepening captive logistics control over Ankara and Izmir micro-fulfillment networks. Consolidate merchant onboarding through centralized KVKK compliance tooling that raises barriers for platform-hopping sellers. Threat from Amazon Turkey's cross-border supplier relationships demands counterinvestment in domestic brand D2C enablement services. For New Entrants and Emerging Players: Establish a beachhead in Anatolian secondary cities where standard shipping economics remain underoptimized. Target B2B wholesale procurement platforms serving manufacturing clusters around Konya and Gaziantep with trade credit facilities. Go-to-market angle: third-party fulfillment partnerships that aggregate fragmented merchant demand into route-dense delivery schedules. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors logistics-tech hybrids with AI-powered demand forecasting capabilities over pure marketplace plays. Five-to-ten year viability hinges on data localization infrastructure ownership as KVKK server requirements tighten. Acquisition target archetype: regional locker network operators with municipal zoning permits. Signal to watch: BDDK digital wallet licensing velocity as predictor of checkout conversion improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Trendyol's urban warehouse density locks in same-day delivery economics against Hepsiburada's centralized model. |
| KVKK Compliance Platform Development | Centralized consent management tools reduce merchant churn from data governance complexity costs. |
| Bank-Fintech Payment Integration | BDDK-licensed e-wallet partnerships expand credit-accessible checkout options for electronics categories. |
| Anatolian Logistics Partnership | Third-party fulfillment alliances penetrate secondary cities where captive fleet economics fail. |
| D2C Brand Enablement Services | Domestic apparel manufacturers bypass marketplace fees while retaining first-party customer data assets. |
Study Parameters
Initial hypotheses were tested against primary input from e-commerce platform executives, logistics operations directors, merchant category managers, and BDDK regulatory affairs leads and refined through secondary validation. Primary fieldwork encompassed structured interviews across Istanbul, Ankara, and Izmir with fulfillment center operators and payment gateway engineers. Secondary sources included KVKK enforcement bulletins, BDDK fintech licensing registers, Turkish Statistical Institute retail trade data, and customs import records for electronics components. Bottom-up merchant volume estimates were triangulated against top-down consumer spending surveys.
Demand-supply balance modeling across the projection horizon incorporated smartphone penetration trajectories, logistics infrastructure investment pipelines, and regulatory compliance cost curves. Segmentation dimensions spanned product category velocity tiers, customer type channel architecture, payment method settlement infrastructure, and delivery mode speed commitments. CAGRs were derived from trend extrapolation adjusted for smartphone adoption saturation effects and urban logistics density thresholds. Industry-specific inputs included KVKK consent framework implementation timelines and BDDK digital wallet licensing velocity.
Stress conditions across inflation volatility, lira exchange rate fluctuation, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smartphone penetration ceilings and logistics route optimization limits. Material shifts in BDDK payment infrastructure rules or KVKK data localization mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
E-Commerce Household Appliances Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market