
 Saudi Arabia Cloud Services Market | 2026-2036
Saudi Arabia Cloud Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cloud Services Market Analytics
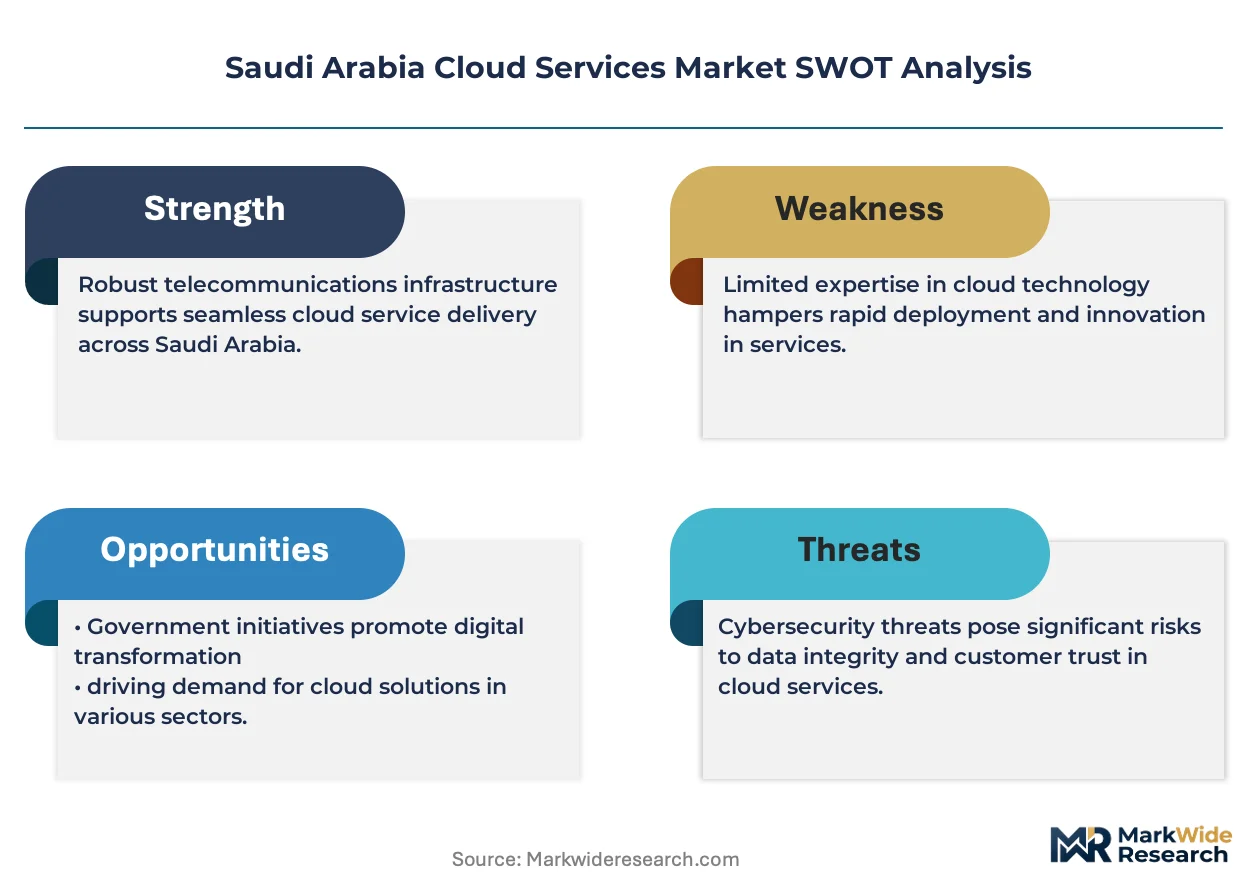
The capital-intensity divergence between hyperscale infrastructure and regional hosting providers is rotating competitive dynamics across the Kingdom. Amazon Web Services leverages its early Riyadh Region launch to anchor enterprise workload migration. STC Cloud sustains domestic advantage through sovereign data center ownership and government channel control.
Saudi Arabia cloud services encompass on-demand delivery of computing resources including virtualized servers, container orchestration, and API-managed storage over IP networks with latency specifications typically below 50ms for enterprise tiers, primarily enabling digital transformation without captive infrastructure ownership. Public Cloud deployments dominate volume economics while Hybrid Cloud configurations capture premium margins from regulated verticals requiring workload partitioning. SaaS delivery models lead adoption velocity among mid-market buyers, whereas IaaS retains the deepest spend concentration from national oil and gas digitization programs.
SAMA's cloud computing guidelines for financial institutions and SDAIA's ECC-1:2019 cybersecurity controls shape vendor qualification and data sovereignty requirements for all market participants. NITC certification mandates further constrain foreign provider market access unless operational partnerships with licensed local entities are established. Stakeholders must monitor evolving local content thresholds and sovereign AI infrastructure commitments that will determine which deployment architectures retain long-term commercial viability.
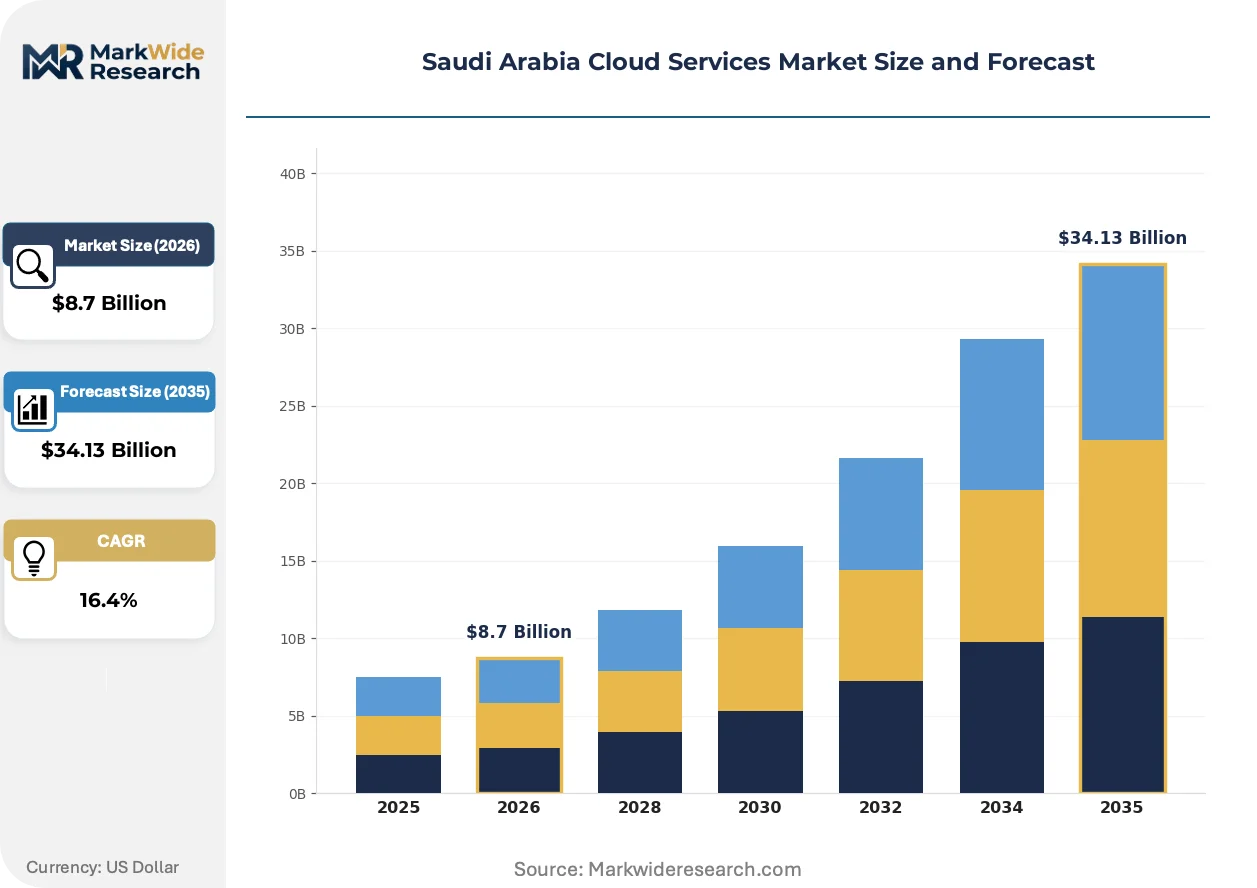
Market Dynamics
SDAIA's binding ECC-1:2019 cybersecurity framework and SAMA's financial sector cloud guidelines are structurally bifurcating vendor qualification tiers, forcing operational partnerships between foreign hyperscalers and licensed domestic entities for market access.
Growth Catalysts
- SDAIA Data Residency Mandates:Binding local storage requirements for government and critical infrastructure workloads are expanding addressable market for sovereign-certified domestic providers.
- Aramco Digitization Programs:National oil and gas infrastructure modernization is generating concentrated IaaS demand for high-performance computing and predictive maintenance workloads.
- Riyadh Enterprise Corridor Concentration:Centralized headquarters economy of banking, telecom, and petrochemical conglomerates creates efficient customer acquisition density for cloud vendors.
Market Restraints
- Capital Intensity Divergence:Hyperscale infrastructure economics require billion-dollar data center commitments that regional hosting providers cannot replicate, consolidating supply-side power.
- NITC Certification Barriers:Foreign cloud operators lacking operational partnerships with licensed Saudi entities face explicit market exclusion from regulated verticals.
- Specialized Talent Scarcity:Shortage of certified cloud architects and cybersecurity specialists with ECC-1:2019 compliance expertise constrains service delivery scaling.
Strategic Opportunities
- Jeddah Fintech Cluster Expansion:Underpenetrated Islamic finance technology stack presents white space for API-native banking infrastructure and regulatory technology deployment.
- NEOM Cognitive City Buildout:Greenfield smart city construction enables cloud-native architecture deployment without legacy system integration burden.
- Sovereign AI Infrastructure Commitments:Government-backed artificial intelligence data center investments create co-location and specialized compute service opportunities.
Industry Challenges
- ECC-1:2019 Compliance Timelines:Extended certification cycles for multi-tenant environments delay revenue recognition and increase pre-operational burn rates.
- Hybrid Integration Complexity:Partitioned workload architectures across on-premise, private cloud, and public cloud environments multiply operational overhead for financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cloud Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: SMEs, Large Enterprises, Government, Education Application: Data Backup, Disaster Recovery, Software Development, Web Hosting |
| Companies Covered | Oracle, Alibaba Cloud, Amazon Web Services, Zain Cloud, Huawei Cloud, Microsoft Azure, STC Cloud, Sahara Net, Google Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cloud Services Market Evolving Landscape
Container orchestration and serverless architectures are compressing traditional virtualization economics while sovereign data requirements and edge computing demands reshape deployment topology decisions across the Kingdom.
Kubernetes-native container orchestration is supplanting virtual machine-based workload management in enterprise migration pipelines. Saudi banking consortiums are adopting this architecture for microservices-based core banking renovation. The shift is compressing infrastructure provisioning cycles from weeks to minutes while elevating DevOps capability requirements.
SAMA's cloud computing guidelines for financial institutions are mandating workload classification and encryption standards that exceed baseline international practice. Banks must now maintain audit trails for data access across all cloud deployment models. The regulation is accelerating demand for Saudi-hosted private cloud configurations with dedicated security operations centers.
Consumption-based billing models are displacing committed-use contracts among mid-market manufacturing and logistics buyers. Channel partners in Dammam's industrial zone are unbundling managed services from infrastructure fees to capture price-sensitive segments. This pattern is most pronounced in supply chain digitization projects where workload predictability remains low.
Saudi Arabia Cloud Services Market Segmentation
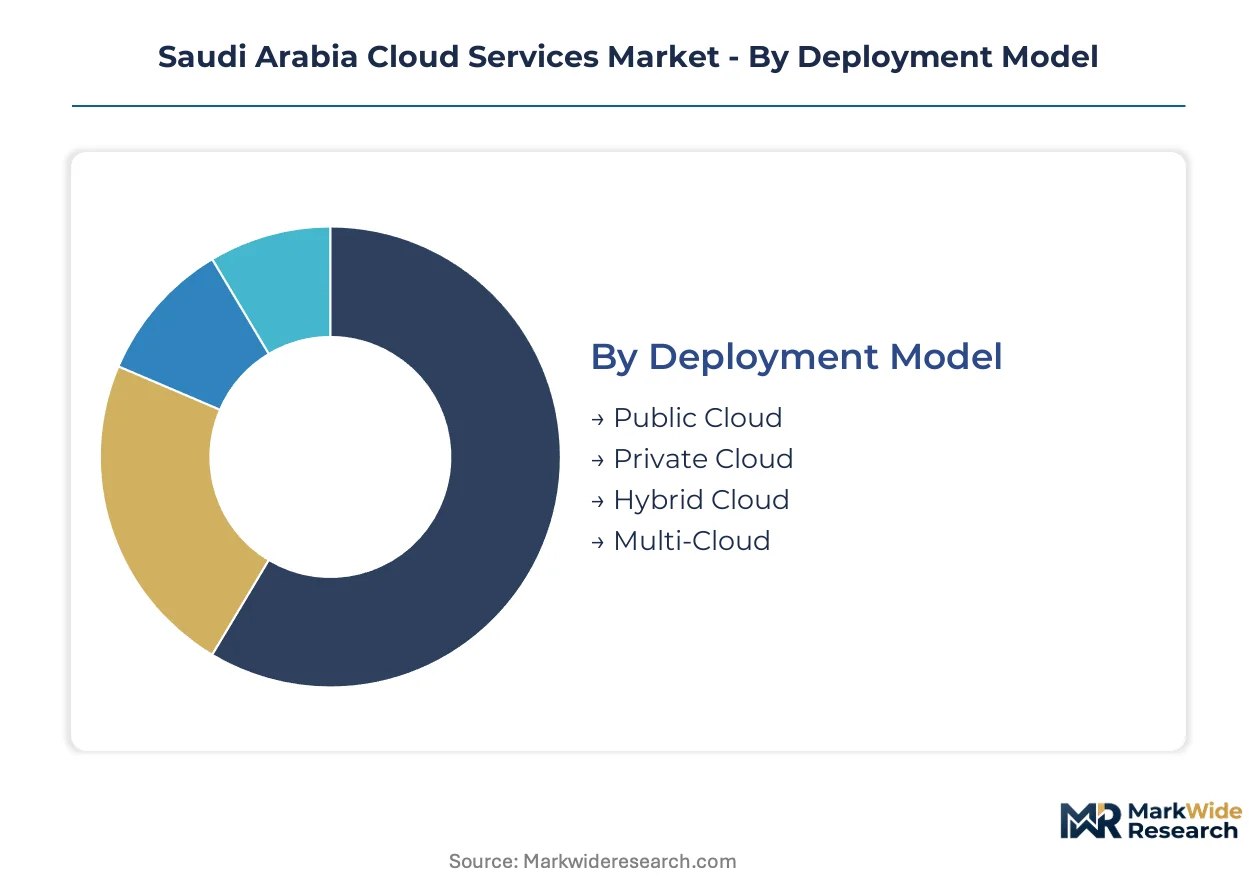
Segmentation reveals how SDAIA compliance requirements and SAMA financial guidelines reshape procurement patterns across deployment architectures. Channel strategies diverge sharply between sovereign-certified domestic routes and hyperscale partnership pathways.
Deployment Model:
Public Cloud flows through direct hyperscale channels, while Private and Hybrid configurations route through systems integrators with ECC-1:2019 certification.
- Public Cloud:Shared infrastructure delivers virtualized compute and storage via IP networks with sub-50ms latency SLAs. Riyadh's banking headquarters cluster drives concentrated demand for elastic capacity during month-end reporting cycles.
- Private Cloud:Dedicated single-tenant environments with hardware isolation meet SDAIA data residency mandates. Aramco's predictive maintenance workloads anchor premium spending in this segment despite higher unit economics.
- Hybrid Cloud:Partitioned architectures spanning on-premise and hosted infrastructure.
- Multi-Cloud:Workload distribution across two or more provider environments to mitigate vendor lock-in.
By volume, Public Cloud leads. By growth pace, Hybrid Cloud is gaining share fastest as financial institutions navigate SAMA's workload classification requirements.
Service Type:
Margin structures concentrate in infrastructure layers for oil and gas digitization, while application layers capture mid-market velocity through consumption billing.
- IaaS:Raw compute, storage, and networking resources provisioned via API. National oil and gas infrastructure modernization programs generate the deepest spend concentration in this segment.
- SaaS:Application software delivered over IP networks without local installation. Jeddah's fintech cluster is expanding addressable market for API-native banking infrastructure delivered through this model.
- PaaS:Development and deployment environments with managed middleware and runtime.
- DaaS:Desktop virtualization and workspace streaming services.
By revenue concentration, IaaS dominates. By adoption velocity, SaaS is climbing the fastest among manufacturing and logistics buyers in Dammam's industrial zone.
End User:
Customer scale determines contract structure, with Large Enterprises negotiating committed-use agreements and SMEs driving consumption-based model expansion.
- Large Enterprises:Banking, telecom, and petrochemical conglomerates with centralized Riyadh headquarters. These buyers anchor IaaS demand and require dedicated security operations centers with 24/7 Arabic-language support.
- Government:Ministries and agencies subject to binding SDAIA data residency mandates. This segment generates non-negotiable demand for sovereign-certified domestic providers with NITC licensing.
- SMEs:Mid-market manufacturing and logistics operators.
- Education:Universities and technical training institutes.
By absolute spend, Large Enterprises lead. By expansion trajectory, Government is ahead due to ECC-1:2019 compliance deadlines accelerating procurement timelines.
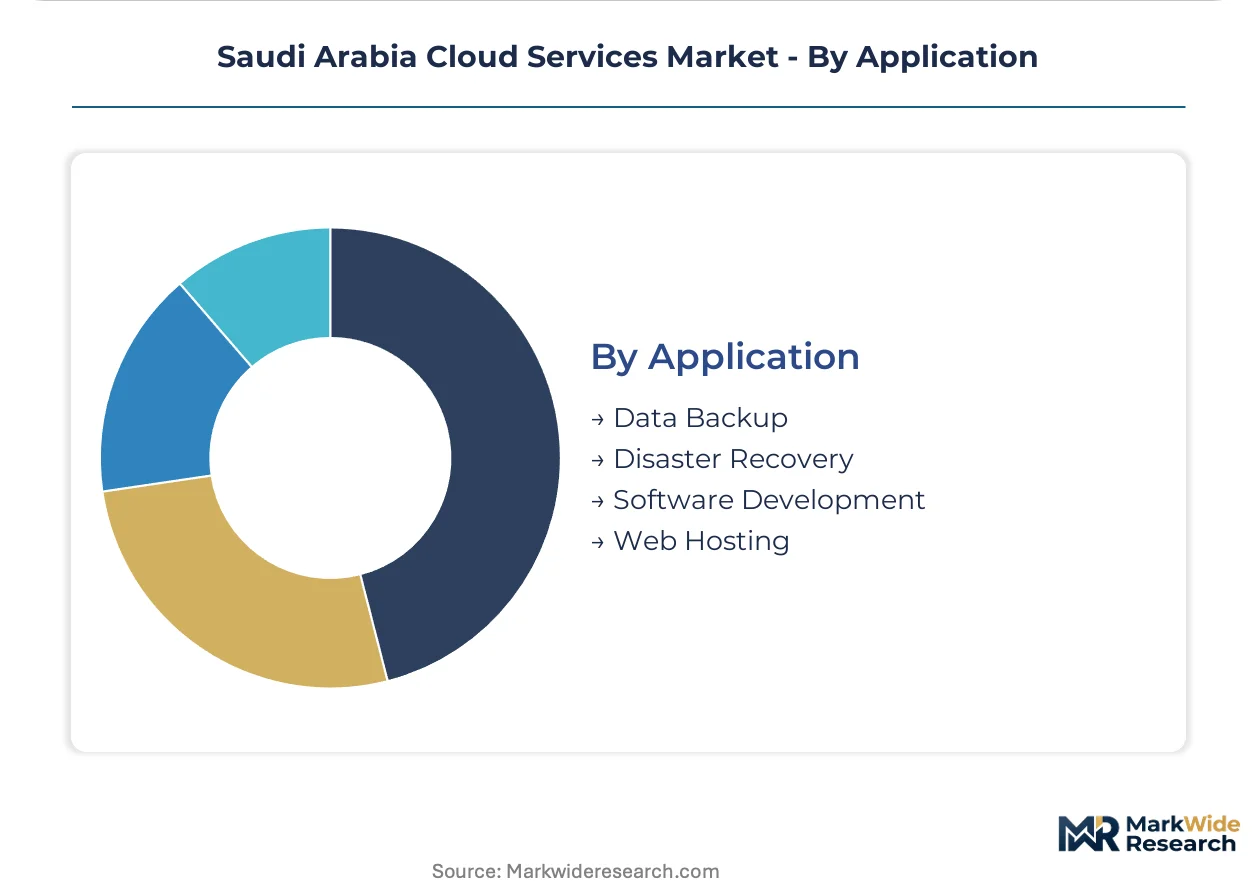
Application:
Workload criticality shapes deployment topology, with core banking systems demanding private infrastructure and development environments tolerating public elasticity.
- Software Development:Container orchestration and CI/CD pipeline hosting with Kubernetes-native architectures. Saudi banking consortiums are renovating core systems through microservices migration, compressing provisioning cycles from weeks to minutes.
- Disaster Recovery:Geographically distributed failover infrastructure with sub-hour recovery objectives. SAMA's audit trail requirements for data access are mandating Saudi-hosted secondary sites with dedicated encryption key management.
- Data Backup:Immutable object storage for compliance and operational recovery.
- Web Hosting:Content delivery and application serving infrastructure.
By deployment frequency, Data Backup leads. By strategic priority, Disaster Recovery is expanding most quickly as financial institutions confront SAMA's enhanced encryption standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Riyadh's enterprise corridor while Jeddah's fintech cluster commands premium rates for compliant infrastructure. Eastern Province industrial zones anchor volume economics through Aramco-linked digitization programs. Regulatory divergence across Saudi sub-regions is accelerating vendor specialization.
Riyadh
Banking headquarters and petrochemical conglomerates drive concentrated demand for sovereign-certified private cloud. SDAIA's ECC-1:2019 mandates require dedicated security operations centers with Arabic-language support. The King Abdullah Financial District hosts multi-tenant facilities serving SAMA-regulated institutions.
Jeddah
Islamic finance technology stacks and API-native banking infrastructure expand addressable market for compliant SaaS. SAMA's cloud computing guidelines enforce workload classification standards exceeding international baselines. The Jeddah Economic City corridor attracts fintechs requiring sub-50ms latency SLAs.
Eastern Province
Aramco's predictive maintenance and high-performance computing workloads anchor IaaS spending. NITC certification requirements constrain foreign provider access without licensed local partnerships. Dammam's industrial zone channels consumption-based billing models for supply chain digitization.
NEOM Northwest
Greenfield smart city construction enables cloud-native architecture without legacy integration burden. Sovereign AI infrastructure commitments create specialized compute and co-location opportunities. The cognitive city buildout demands edge computing nodes with localized data processing.
Western Region
Makkah and Madinah logistics corridors generate disaster recovery demand for geographically distributed failover. SDAIA data residency rules mandate Saudi-hosted secondary sites with dedicated encryption key management. The region's religious tourism economy drives seasonal capacity elasticity requirements.
Saudi Arabia Cloud Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Saudi cloud market. Hyperscale operators anchor public cloud volume through billion-dollar infrastructure commitments while domestic providers capture sovereign-certified segments via NITC licensing control. Three archetypes dominate: hyperscale platforms with early-mover regional presence, telecom-affiliated hosts with government channel access, and specialized integrators with ECC-1:2019 compliance expertise. Competitive moves concentrate on operational partnerships with licensed local entities and dedicated security operations center investments.
Among hyperscale operators, Amazon Web Services and Microsoft Azure occupy positions as early Riyadh Region anchors for enterprise workload migration. STC Cloud exemplifies the telecom-affiliated archetype through sovereign data center ownership and domestic channel control. Oracle represents the enterprise software-integrated path with database workload specialization.
| Leading Market Players |
|---|
| Oracle |
| Alibaba Cloud |
| Amazon Web Services |
| Zain Cloud |
| Huawei Cloud |
| Microsoft Azure |
| STC Cloud |
| Sahara Net |
| Google Cloud |
| Others |
Value Network & Pricing Analysis
Billion-dollar hyperscale data center commitments in Riyadh and Jeddah create unit cost floors that regional hosting providers cannot match, compressing margins for uncertified operators while elevating price premiums for sovereign-compliant infrastructure. This capital asymmetry concentrates supply-side power among early-mover platforms with NITC licensing, forcing domestic competitors into partnership arrangements that reshape procurement economics across regulated verticals.
Pricing Analysis
The customization-premium spread between configured-to-order private cloud deployments and standard public cloud tiers runs wide in Saudi Arabia, with ECC-1:2019 certification and dedicated security operations centers commanding substantial markups over baseline IaaS rates. Pricing stratifies across premium sovereign-certified, standard compliant, and economy non-regulated tiers, with differentiation driven by data residency guarantees and Arabic-language support availability. Cost compression in the standard tier is intensifying because hyperscale operators are absorbing fixed infrastructure costs to capture government channel access. Mid-market manufacturing buyers in Dammam's industrial zone exhibit the highest price sensitivity, while Riyadh banking conglomerates show the lowest due to SAMA-mandated compliance requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites the majority of server hardware and networking equipment inbound to Saudi data centers, creating a persistent logistics chokepoint for infrastructure expansion timelines. Supply concentrates in China, Taiwan, and the United States for compute silicon, storage arrays, and optical networking gear. Raw material dependencies span rare earth elements for magnetic storage, high-purity silicon for semiconductors, and copper for power distribution. Single-source vulnerability from concentrated semiconductor fabrication in East Asia poses structural supply chain risk. Distribution runs through Dubai-based regional distributors and direct manufacturer relationships with Riyadh-based systems integrators holding NITC certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SDAIA's binding data residency mandates and SAMA's financial sector cloud guidelines are accelerating a high-growth disruption that will restructure vendor qualification tiers and procurement patterns across the Kingdom's enterprise technology stack.
For Market Incumbents: Shield sovereign-certified market position by deepening operational partnerships with licensed domestic entities before NITC certification barriers harden further. Prioritize dedicated security operations center investments with 24/7 Arabic-language support to defend against hyperscale entrants targeting Riyadh banking headquarters. Channel control through STC Cloud's government relationships represents the critical defensive lever against AWS and Azure's early-mover regional presence. For New Entrants and Emerging Players: Lead with API-native banking infrastructure targeting Jeddah's underpenetrated Islamic finance technology stack, where SAMA's workload classification requirements have outpaced incumbent solution development. The fintech cluster presents the most penetrable geography due to specialized compliance demands that hyperscale platforms address poorly. A go-to-market angle anchored in regulatory technology deployment with embedded ECC-1:2019 audit trail capabilities will differentiate against generalized cloud offerings. For Investors and Strategic Acquirers: Specialist systems integrators with proven ECC-1:2019 compliance expertise and existing NITC licensing represent the highest-probability acquisition target archetype for long-term viability across a five-to-ten-year window. These entities command scarcity premiums due to extended certification cycles that constrain service delivery scaling. The signal to watch is SDAIA's evolving local content thresholds, which will determine which deployment architectures retain commercial viability as sovereign AI infrastructure commitments mature.| Strategic Initiative | Industry Significance |
|---|---|
| Operational Partnership Formation | Foreign hyperscalers gain NITC market access through licensed Saudi entity alliances. |
| Dedicated Security Operations Center Buildout | Arabic-language 24/7 support meets SAMA audit requirements for financial institutions. |
| API-Native Banking Platform Launch | Microservices architecture addresses Jeddah fintech cluster compliance demands. |
| Sovereign AI Infrastructure Co-Location | NEOM cognitive city buildout creates specialized compute service opportunities. |
| Consumption-Based Billing Model Expansion | Dammam industrial zone supply chain digitization captures price-sensitive segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud procurement officers at Riyadh banking headquarters, platform engineers at hyperscale regional operations, channel partners in Jeddah's fintech corridor, and ECC-1:2019 compliance specialists at domestic systems integrators. Secondary validation drew from SDAIA regulatory filings, SAMA circulars on cloud computing guidelines, NITC certification databases, hyperscaler capital expenditure disclosures, and Aramco digitization program announcements. Bottom-up service provider revenue estimates were triangulated against top-down enterprise IT spending surveys to anchor segmentation integrity.
Across the analysis window, the forecast framework modeled deployment architecture adoption curves, service type margin evolution, and end-user procurement pattern shifts. Segmentation dimensions included public-private-hybrid-multi-cloud deployment models, IaaS-PaaS-SaaS service tiers, and large enterprise-government-SME customer scale. CAGRs were derived from fitted growth curves calibrated to named infrastructure investment announcements and regulatory compliance deadline acceleration effects. Key inputs comprised SDAIA data residency mandate expansion timelines and SAMA workload classification enforcement intensity.
Forecasts assume regulatory continuity in SDAIA's ECC-1:2019 framework and SAMA's financial sector guidelines; material policy shifts would require re-modeling. Specific risk factors include NITC certification requirement relaxation that would erode domestic provider premiums, or hyperscale operator direct licensing that would compress partnership economics. Revision becomes warranted when sovereign AI infrastructure commitment scale crosses thresholds that fundamentally alter co-location demand calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Private Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Indonesia Cloud Market