
 Cruise Travel Market | 2026-2036
Cruise Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Cruise Travel Market Insights
Onboard ancillary revenue is narrowing as a share of total yield per passenger, pressuring operators to rebalance ticket pricing against casino, beverage, and excursion spend. Carnival Corporation & plc leverages its multi-brand architecture to segment price points across Carnival, Princess, and Holland America Line. Royal Caribbean Group anchors its competitive stance through private-destination infrastructure at Perfect Day at CocoCay and Labadee. Norwegian Cruise Line Holdings differentiates via its freestyle cruising concept, reducing structured dining to capture independent travelers.
Cruise travel denotes commercial passenger voyages aboard vessels purpose-built for leisure itineraries, typically ranging from 2,000 to 6,000 passenger capacities with draft limitations dictating port accessibility and terminal infrastructure requirements. The primary commercial purpose centers on packaged vacation experiences combining transportation, accommodation, entertainment, and destination access into a single-transaction purchase. Luxury and premium cruise lines command disproportionate margin pools relative to their berth count, while mass-market operators compete on scale economics and itinerary breadth. Adventure cruising represents the fastest-growing duration-destination hybrid, with expedition vessels penetrating polar and remote archipelago routes previously inaccessible to conventional hull designs.
The International Maritime Organization enforces MARPOL Annex VI sulfur caps and upcoming carbon intensity indicators that reshape newbuild specifications and retrofit schedules across flagged fleets. The EU Green Deal and associated Fit for 55 package extend emissions trading scheme coverage to maritime transport, directly affecting European-ported itineraries and vessel deployment calculus. Port-state regulators in the US, Italy, and the Bahamas impose wastewater discharge and air-quality standards that determine terminal access and berthing priority. Stakeholders must monitor IMO's 2025 revised greenhouse gas strategy and corresponding fuel-certification frameworks to align capital commitments with compliance pathways.
Market Dynamics
The International Maritime Organization's MARPOL Annex VI sulfur caps and impending carbon intensity indicators are forcing fleet-wide propulsion retrofits and newbuild specification changes across all flagged fleets, fundamentally restructuring capital deployment timelines and fuel procurement strategies for operators.
Growth Catalysts
- Multigenerational family demand:Extended-family booking patterns are expanding average party sizes and cabin category upsells, particularly for Caribbean and Mediterranean itineraries during school holiday windows.
- EU Green Deal maritime extensions:The Fit for 55 package's emissions trading scheme coverage creates compliance-driven investment in shore power connectivity and LNG bunkering infrastructure at European ports.
- Expedition vessel hull innovations:Ice-class strengthened designs and shallow-draft propulsion systems are opening polar routes and remote archipelago access previously unreachable by conventional cruise ships.
Market Restraints
- Marine fuel price volatility:Low-sulfur fuel oil and LNG bunker cost swings compress operating margins and complicate hedging strategies for mass-market operators.
- Asian shipyard concentration:Newbuild capacity concentrates in South Korean and Chinese yards, creating delivery slot scarcity and pricing power asymmetry during order surges.
- Port infrastructure draft limitations:Terminal depth constraints and air-draft bridge clearances restrict vessel deployment to a finite set of upgraded facilities, limiting itinerary innovation.
Strategic Opportunities
- Underpenetrated Indian outbound market:Rising disposable income and simplified visa regimes for cruise passengers present first-mover advantages for operators establishing home-porting in Mumbai and Chennai.
- Shore power regulatory tailwinds:California's CARB regulations and EU port mandates for cold-ironing infrastructure create competitive differentiation for vessels with onboard electrical compatibility.
- Artificial intelligence and dynamic pricing convergence:Real-time yield management systems integrating booking pace, competitor pricing, and excursion inventory are optimizing revenue per available berth day.
Industry Challenges
- Marine engineering talent scarcity:Specialized expertise in dual-fuel engine maintenance and exhaust scrubber system operation is outpacing training program output, extending drydock durations.
- Retrofit capex intensity:Ballast water treatment system installations, scrubber additions, and shore power readiness modifications demand simultaneous capital outlays across aging fleet segments.
- IMO certification timeline compression:The 2025 revised greenhouse gas strategy and corresponding fuel-certification frameworks are accelerating compliance deadlines faster than supply chain adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruise Travel Market |
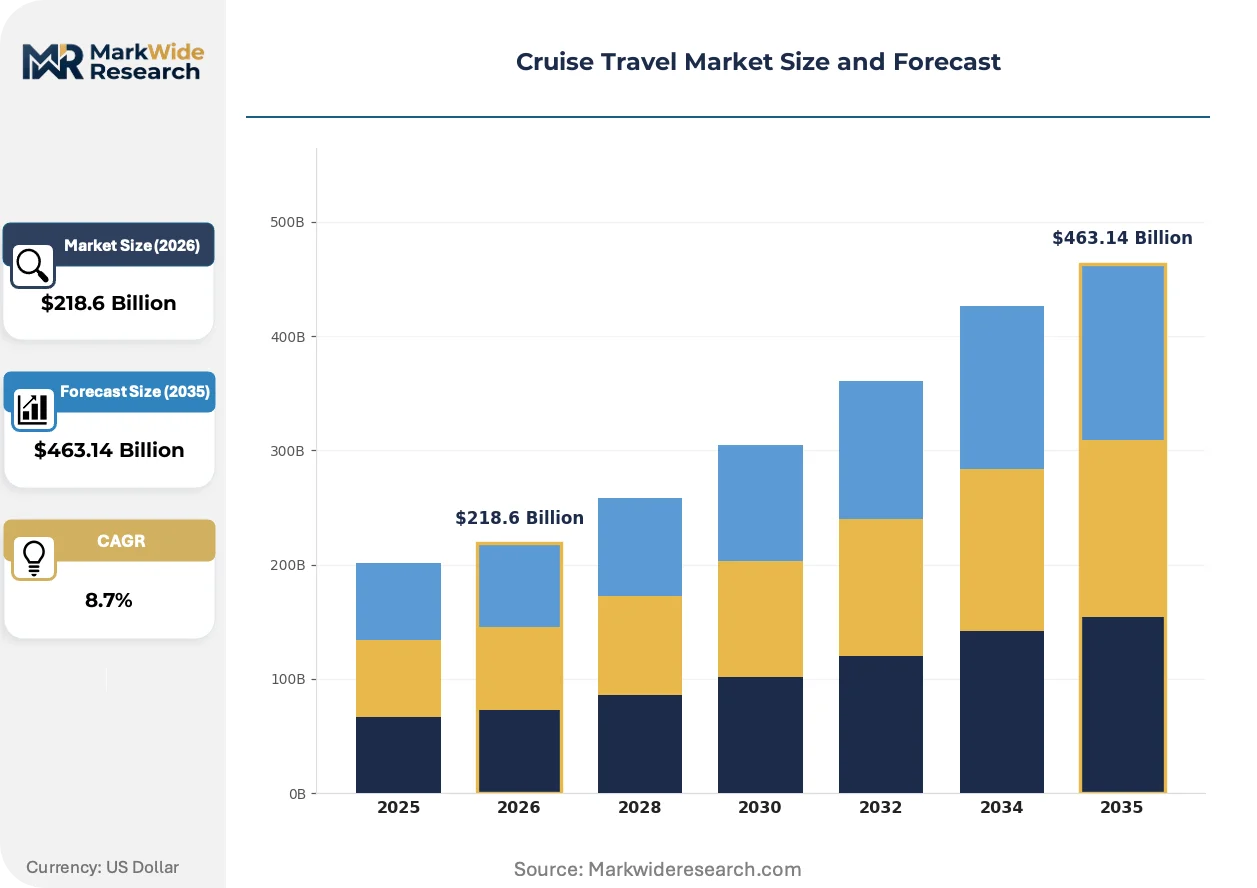
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $463.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cruise Line: Mass Market, Luxury, Premium, Adventure Duration: Short-term, Long-term, Weekend, Extended Onboard Experience: Family-Friendly, Wellness, Entertainment, Culinary Destination Type: Caribbean, Mediterranean, Alaskan, Asia-Pacific |
| Companies Covered | Carnival Corporation & plc, Royal Caribbean Group, Norwegian Cruise Line Holdings, MSC Cruises, Disney Cruise Line, Viking Cruises, TUI Group, Genting Hong Kong, Silversea Cruises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruise Travel Market Trends and Innovations
Fuel transition pathways and digital guest experience platforms are compressing traditional operational models while regulatory pressure accelerates capital redeployment toward sustainability infrastructure.
Liquefied natural gas propulsion systems are collapsing the historical tradeoff between emissions compliance and operating economics for newbuild vessels. Mid-size and premium operators are adopting LNG-dual-fuel configurations at accelerated procurement cadences. This technology is collapsing the cost premium previously associated with sub-0.10% sulfur compliance, repositioning fuel choice as a strategic variable rather than a regulatory burden.
The EU Green Deal's extension of emissions trading to maritime transport is restructuring deployment calculus for European-ported itineraries. Operators are optimizing port rotations to minimize carbon allowance exposure and berthing fees. Mediterranean and Baltic routes are most affected, with lines adjusting season lengths and home-port selections to manage compliance cost accumulation.
Guest preference for independent shore excursion booking is fragmenting traditional packaged vacation economics. Online travel agencies and direct-to-consumer experience platforms are capturing margin previously retained by cruise operators. This pattern is most visible in Caribbean deployments, where private-destination infrastructure investments now serve partly as defensive moats against third-party excursion disintermediation.
Cruise Travel Market Segmentation
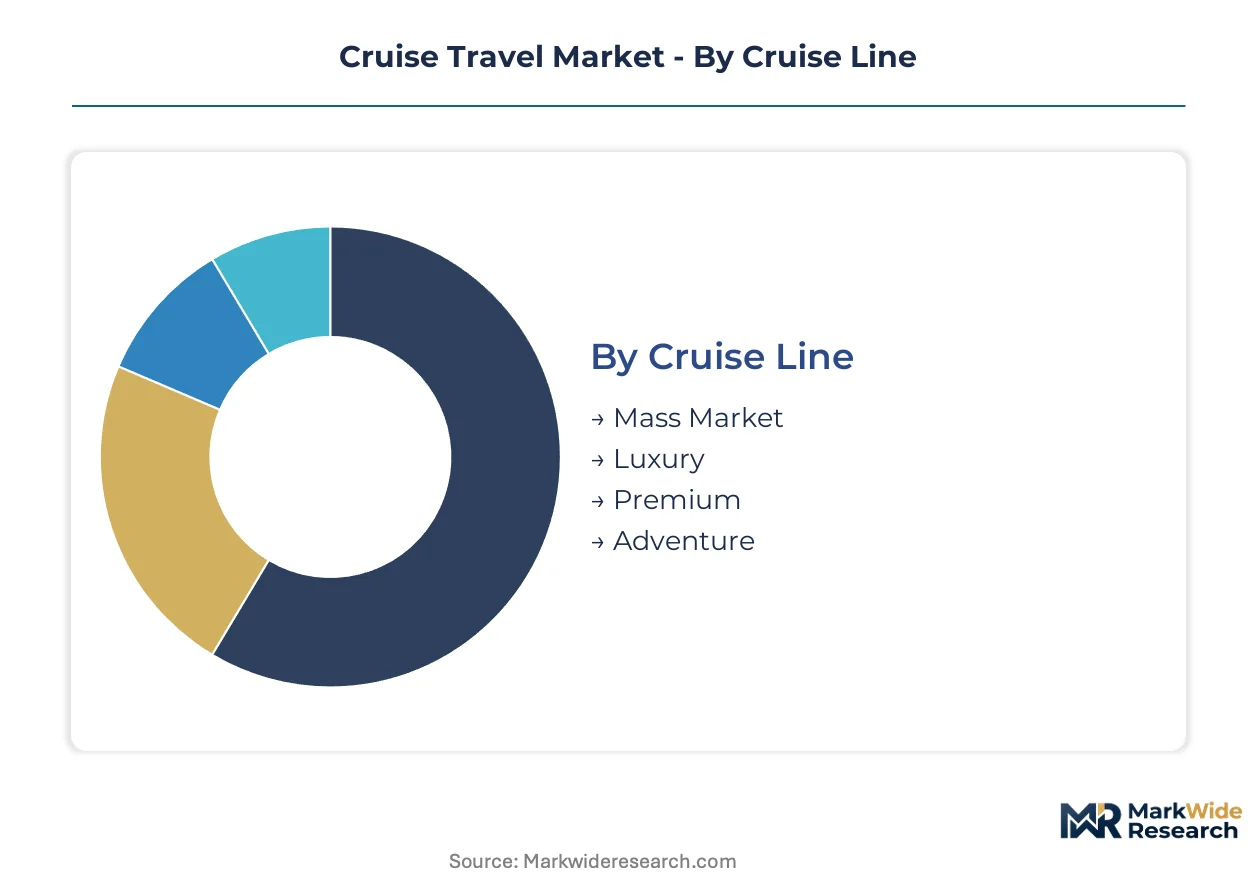
Cruise operators segment passenger offerings to align vessel deployment with distinct willingness-to-pay profiles and itinerary preferences. Each segmentation dimension reveals divergent margin structures, capital intensity requirements, and regulatory exposure across the fleet.
Cruise Line:
Price positioning spans from volume-driven mass deployment to ultra-luxury expedition vessels with ice-class hull ratings.
- Mass Market:Vessels carrying 3,000 to 6,000 passengers dominate deployed capacity. Carnival Corporation and Royal Caribbean Group compete on scale economics, with Caribbean itineraries absorbing the largest share of berth nights and onboard casino revenue subsidizing ticket yields.
- Luxury:Smaller ships below 1,000 passengers command disproportionate margin pools through all-inclusive pricing and extended Mediterranean voyages. Seabourn and Silversea target repeat cruisers with personalized service ratios exceeding one crew member per guest.
- Premium:Mid-size vessels balance upgraded accommodations with accessible pricing. Holland America Line and Princess Cruises emphasize destination immersion over onboard spectacle, capturing affluent retirees and empty-nest couples.
- Adventure:Expedition ships with ice-strengthened hulls and shallow-draft propulsion penetrate polar routes. Lindblad Expeditions and Ponant lead Antarctic and Arctic penetration where port infrastructure constraints exclude conventional cruise ships.
The dominant share belongs to Mass Market, while Adventure is closing the gap fastest.
Duration:
Booking windows and revenue recognition patterns vary sharply across voyage lengths, from casino-dependent weekend sailings to extended world cruises with 12-month advance deposits.
- Short-term:Three- to five-day itineraries concentrate in Bahamas and Baja California corridors. Carnival Cruise Line and Royal Caribbean deploy older tonnage here, maximizing asset utilization through rapid turnaround schedules at Miami and Port Canaveral.
- Long-term:Voyages exceeding 14 nights generate higher per-diems and excursion attachment rates. Cunard and Viking Ocean Cruises dominate transoceanic and world cruise segments where passenger loyalty programs drive rebooking rates above 60 percent.
- Weekend:Two-night sailings serve drive-to markets from Los Angeles, New York, and Singapore. These itineraries prioritize onboard spend over ticket yield, with beverage package penetration exceeding 80 percent.
- Extended:Segments between 21 and 45 nights attract retired passengers with flexible calendars. Repositioning cruises between seasonal deployment regions offer discounted fares that fill otherwise empty berths during transits.
Short-term sailings capture the volume lead, though Extended voyages show the steepest expansion trajectory among repeat cruisers.
Onboard Experience:
Amenity mix determines capital allocation between entertainment infrastructure, spa square footage, and dining venue diversity.
- Family-Friendly:Water parks, kids clubs, and character partnerships drive Disney Cruise Line and Royal Caribbean's Oasis-class deployment. Multigenerational bookings expand average party sizes and cabin category upsells during school holiday windows.
- Wellness:Dedicated spa decks, fitness programming, and healthy dining options attract premium pricing. Celebrity Cruises and MSC Cruises have expanded thermal suite capacity and partnered with recognized fitness brands to differentiate sea days.
- Entertainment:Broadway-caliber productions, casinos, and nightlife venues dominate mass-market ship design. Norwegian Cruise Line's freestyle concept reduces structured dining to maximize theater and nightclub throughput.
- Culinary:Chef partnerships, cooking demonstrations, and specialty restaurants command cover charges and beverage upsells. Oceania Cruises and Regent Seven Seas built brand identity around gastronomic programming with included fine dining.
Family-Friendly anchors deployment capacity, while Wellness programming gains share fastest among premium repositioning.
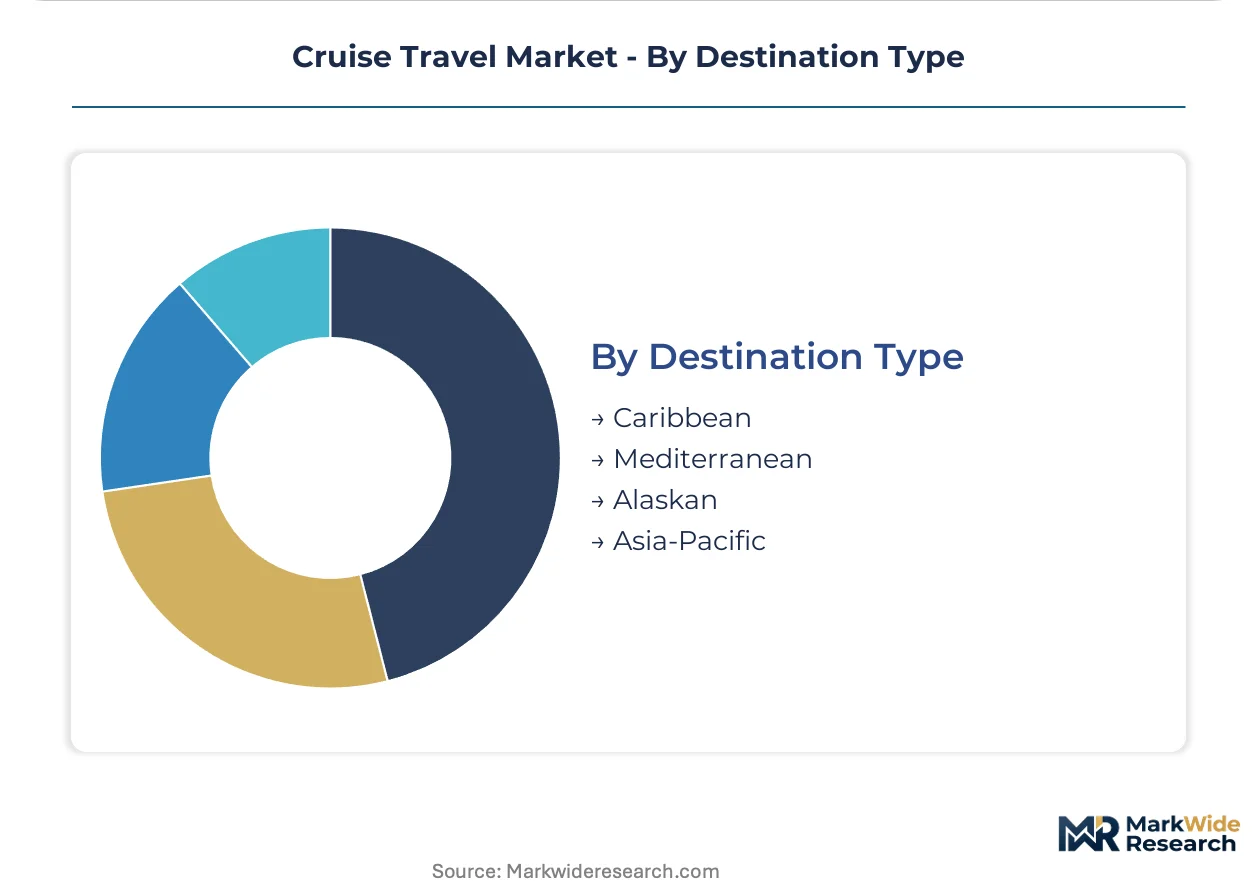
Destination Type:
Geographic concentration shapes fuel procurement, port fee structures, and seasonal staffing models across the fleet.
- Caribbean:Eastern, Western, and Southern itineraries absorb the largest deployed capacity globally. Private-destination infrastructure at Perfect Day at CocoCay and Labadee defends margin against third-party excursion disintermediation.
- Mediterranean:Seasonal deployment from Barcelona, Rome, and Athens faces EU Green Deal emissions trading exposure. Operators optimize port rotations to minimize carbon allowance accumulation and cold-ironing compliance costs.
- Alaskan:Summer-only itineraries require Jones Act-compliant hulls and generate premium pricing through scenic cruising demand. Princess Cruises and Holland America Line maintain century-long infrastructure investments in rail and lodge extensions.
- Asia-Pacific:Underpenetrated sourcing from India and Southeast Asia presents first-mover opportunities. Home-porting trials in Mumbai and Chennai target rising disposable income with simplified visa regimes for cruise passengers.
Caribbean deployment retains the dominant position, though Asia-Pacific sourcing is expanding most quickly as outbound markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across source markets, with North American passengers exhibiting lower price sensitivity on ticket premiums while Asian outbound travelers prioritize value-per-day metrics in booking decisions.
United States
Florida and California home-porting clusters drive the largest passenger embarkation volumes globally, with Miami, Port Canaveral, and Fort Lauderdale processing multi-brand fleet deployments year-round. The Environmental Protection Agency enforces Clean Water Act vessel discharge standards that determine terminal access priority at US ports. Alaska's seasonal cruise corridor generates premium pricing through Jones Act-compliant hull requirements and scenic cruising demand concentrated in the Inside Passage.
China
Shanghai and Tianjin cruise terminals anchor Asia-Pacific capacity deployment, though outbound passenger recovery lags pre-pandemic trajectory due to visa processing friction and air connectivity gaps. The Ministry of Ecology and Environment implements domestic emission control areas mirroring IMO sulfur caps with stricter coastal zone enforcement. Hainan Island's duty-free retail infrastructure supports home-porting experimentation targeting Southeast Asian itinerary expansion.
Germany
Hamburg and Kiel serve as Northern Europe's primary embarkation points, with German passengers showing highest per-capita spending on shore excursions and beverage packages. The EU Green Deal's Fit for 55 package extends emissions trading scheme coverage to maritime transport, directly affecting Baltic and Norwegian fjord itineraries. Meyer Werft in Papenburg and Meyer Turku in Finland concentrate newbuild construction for premium and expedition vessel segments.
Italy
Civitavecchia, Venice, and Genoa rotate as Mediterranean home-ports with seasonal deployment optimization to minimize EU carbon allowance accumulation. Port-state regulators impose wastewater discharge standards that determine berthing priority alongside cold-ironing infrastructure requirements. The Adriatic cruise corridor connecting Venice to Greek Isles commands premium pricing through destination density and cultural excursion attachment.
United Kingdom
Southampton anchors transatlantic and Northern European deployment, with British passengers over-indexing on extended voyage bookings exceeding fourteen nights. Maritime and Coastguard Agency enforcement of SOLAS conventions and passenger ship safety certificates shapes fleet certification timelines. Scotland's Edinburgh and Greenock terminals support summer expedition vessel positioning for Arctic and Norwegian coastal routes.
Cruise Travel Market Competitive Landscape
Scale-driven mass-market operators and experience-differentiated premium lines split the market into distinct competitive spheres with limited direct overlap. Consolidation around three major holding companies dominates deployed capacity, while specialized expedition and luxury segments retain fragmentation through niche positioning. Strategic archetypes include fleet-scale volume players, destination-infrastructure owners, and experience-concept innovators. Competitive moves center on private-destination capital deployment and multi-brand portfolio architecture to segment price points without fleet commingling.
Among publicly traded holding companies, Carnival Corporation & plc, Royal Caribbean Group, and Norwegian Cruise Line Holdings occupy positions exemplifying scale-driven and experience-differentiated archetypes respectively. MSC Cruises represents the privately held European challenger with shipyard-backed newbuild financing advantages. Disney Cruise Line anchors the family-entertainment integration model through intellectual property licensing and character-driven onboard programming. Viking Cruises exemplifies the adult-focused, destination-immersion positioning that captures affluent retiree and empty-nest demographics with extended itinerary specialization.
| Leading Market Players |
|---|
| Carnival Corporation & plc |
| Royal Caribbean Group |
| Norwegian Cruise Line Holdings |
| MSC Cruises |
| Disney Cruise Line |
| Viking Cruises |
| TUI Group |
| Genting Hong Kong |
| Silversea Cruises |
| Others |
Pricing and Supply Chain Analysis
Marine fuel price volatility determines both ticket tier spreads and fleet deployment economics, compressing operating margins for mass-market operators while forcing premium lines to absorb bunker cost swings through bundled pricing. This cost pressure cascades into newbuild procurement schedules and retrofit prioritization across flagged fleets.
Pricing Analysis
Onboard casino, beverage, and excursion revenue drives lifetime passenger value beyond base ticket yields. Three-tier pricing structure across premium, standard, and economy levels segments willingness-to-pay through cabin category, dining inclusion, and shore excursion bundling. Price differentiation hinges on brand tier and itinerary exclusivity, with luxury lines commanding spreads through personalized service ratios. Pricing pressure stems from third-party excursion platform disintermediation capturing margin previously retained by operators. Mass-market passengers exhibit highest price sensitivity on ticket premiums, while luxury cruisers show lowest sensitivity on ancillary upsells.
Supply Chain Analysis
Asian shipyard concentration at South Korean and Chinese builders holds dominant newbuild capacity, creating delivery slot scarcity during order surges. Supply draws from specialized marine engineering talent pools in Germany, Finland, and Italy for dual-fuel propulsion and ice-class hull design. Raw material dependencies include marine-grade steel, LNG bunkering infrastructure, and exhaust scrubber systems. Single-source vulnerability concentrates in emission control technology suppliers facing IMO certification timeline compression. Distribution runs through flagged registries and classification societies that validate compliance for port-state access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across expedition and adventure segments where multigenerational family demand creates niche deployment windows underserved by mass-market scale economics.
For Market Incumbents: Build private-destination infrastructure moats at Perfect Day at CocoCay and Labadee to defend excursion margin against third-party platform disintermediation. Invest in shore power readiness and LNG bunkering compatibility to secure berthing priority under EU Green Deal and California CARB regulations. Expand multi-brand architecture to segment price points without fleet commingling, capturing both value-conscious families and affluent empty-nest cruisers through distinct vessel deployment. For New Entrants and Emerging Players: Mid-size premium repositioning between mass volume and ultra-luxury represents the most penetrable entry point, particularly for wellness-focused itineraries with thermal suite and fitness programming differentiation. Underpenetrated Indian outbound markets with rising disposable income and simplified visa regimes offer first-mover home-porting advantages in Mumbai and Chennai. Target expedition vessel segments with ice-strengthened hulls for polar route access where port infrastructure constraints exclude conventional cruise ship competition. Pursue direct-to-consumer booking platforms to bypass traditional travel agency commission structures. For Investors and Strategic Acquirers: IMO's 2025 revised greenhouse gas strategy reshapes the acquisition landscape toward dual-fuel propulsion readiness and shore power electrical compatibility. Long-term viability across the analysis window favors operators with demonstrated compliance pathway execution and private-destination capital deployment. Acquisition target archetype: mid-size premium lines with established repeat cruiser loyalty above 60 percent and European-ported itinerary exposure manageable through carbon allowance optimization. Monitor IMO fuel-certification framework implementation pace as inflection indicator for retrofit capex intensity and fleet valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Private Destination Infrastructure Expansion | Perfect Day at CocoCay and Labadee defend margin against third-party excursion disintermediation in Caribbean deployment. |
| LNG Dual-Fuel Propulsion Retrofit | Collapses historical tradeoff between IMO MARPOL Annex VI compliance and operating economics for newbuild vessels. |
| Shore Power Cold-Ironing Readiness | California CARB and EU port mandates create competitive differentiation through onboard electrical compatibility investment. |
| Artificial Intelligence Yield Management | Real-time systems integrating booking pace and competitor pricing optimize revenue per available berth day. |
| Expedition Vessel Ice-Class Hull Procurement | Ice-strengthened designs open polar routes and remote archipelago access previously unreachable by conventional cruise ships. |
Research Methodology
A standing panel of fleet operations directors, port authority planners, marine engineering procurement leads, and cruise line revenue management executives provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from IMO regulatory filings, EU ETS maritime extension documentation, port-state discharge standard records, and cruise operator SEC disclosures. Bottom-up berth deployment modeling and top-down market size triangulation anchored value estimates.
Scenario-bracketing around fuel transition pathways and regulatory compliance timelines bounded high-low estimates across the projection horizon. Segmentation dimensions modeled include cruise line tier, voyage duration, onboard experience positioning, and destination geography, with additional granularity on emissions trading exposure for European-ported itineraries. CAGRs derived from historical deployment patterns, newbuild delivery schedules, and passenger sourcing market maturity curves. Forecast inputs incorporated shore power infrastructure buildout pace and LNG bunkering terminal availability.
Macroeconomic conditions sit as an overlay; deviation in discretionary travel spending, marine fuel price indices, or currency exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding IMO regulatory implementation timing and fleet retrofit capex absorption capacity. Quarterly review of newbuild orderbook concentration, port infrastructure investment announcements, and emissions trading allowance pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
River Cruises Market