
 Alaskan Cruises Market | 2026-2036
Alaskan Cruises Market Size, Share, and Industry Trends Forecast 2026-2036
Alaskan Cruises Market Outlook
Onboard experience revenue is tilting toward premium wellness programming and curated educational workshops. Princess Cruises leverages its long-tenured Alaska presence to sustain dominant berth allocation in key ports. Holland America Line anchors its competitive stance through heritage brand strength among repeat cruisers. Norwegian Cruise Line differentiates via flexible fare structures and younger-skewing entertainment venues.
An Alaskan cruise denotes a seasonal maritime voyage operating primarily through the Inside Passage and Gulf of Alaska, utilizing ice-strengthened hull vessels with draft limitations of 8-10 meters to navigate glacial fjords and restricted waterways. These itineraries serve commercial purposes centered on wildlife observation, cultural heritage interpretation, and protected-area tourism access. Luxury cruise type commands the highest per-passenger yield while expedition cruise type captures the fastest growth trajectory among experience-seeking demographics. Family customer type remains structurally mature with predictable seasonal recurrence, whereas solo traveler customer type represents an emerging margin pool as operators redesign cabin inventory and social programming.
The US Coast Guard enforces passenger vessel safety standards under 46 CFR Subchapter H, while the National Park Service regulates commercial access permits for Glacier Bay and other protected areas. Alaska Department of Environmental Conservation administers wastewater discharge protocols that directly constrain itinerary design and onboard treatment system specifications. Stakeholders must weigh port infrastructure investment against evolving emissions requirements and shifting passenger preferences for immersive, small-footprint experiences.
Market Dynamics
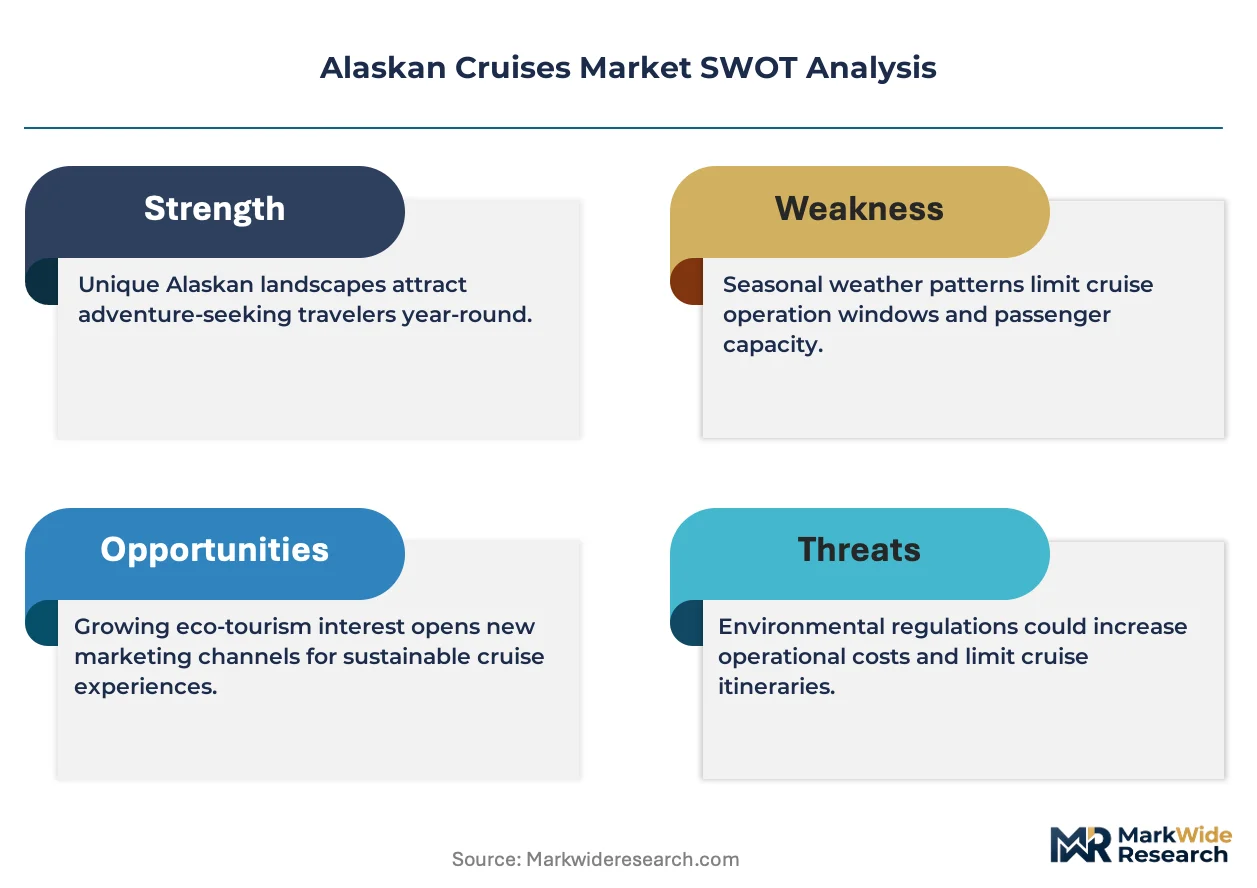
Environmental compliance costs are reshaping capital allocation across the Alaskan cruise fleet, forcing operators to redirect investment toward wastewater treatment upgrades and shore power infrastructure while compressing margins on traditional mass-market itineraries.
Growth Catalysts
- Expedition Vessel Expansion:Ice-strengthened hull specifications are enabling deeper penetration into glacial fjords previously inaccessible to conventional cruise ships, opening new itinerary corridors.
- National Park Service Access Permits:Commercial entry authorization for Glacier Bay and protected areas creates scarcity value that operators monetize through premium positioning.
- Solo Traveler Cabin Redesign:Social programming and single-occupancy inventory reconfiguration is capturing margin from an underserved demographic with higher per-passenger yield.
Market Restraints
- Alaska Department of Environmental Conservation Wastewater Protocols:Discharge regulations constrain route flexibility and mandate onboard treatment system specifications that elevate capital intensity.
- Juneau-Skagway Corridor Concentration:Passenger volume clustering in glacier-accessible ports creates berth scarcity and port fee inflation during peak season.
- Seasonal Operating Window:Ice conditions and daylight limitations restrict viable sailing months to May through September, compressing annual asset utilization.
Strategic Opportunities
- Shore Power Infrastructure Investment:Cold-ironing capability at Ketchikan and Seward enables emissions reduction compliance while differentiating operator environmental credentials.
- Heritage Cultural Programming:Tlingit and Haida interpretive partnerships create intellectual property barriers and command premium pricing from experience-seeking passengers.
- US Coast Guard Safety Standard Harmonization:46 CFR Subchapter H alignment with SOLAS conventions reduces certification duplication for vessels operating dual itineraries.
Industry Challenges
- Marine Engineer Talent Scarcity:Specialized ice navigation and advanced wastewater system operation skills command premium compensation and extend crew recruitment cycles.
- Permit Application Timelines:National Park Service commercial access authorization processes create 18-24 month lead times that constrain itinerary innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alaskan Cruises Market |
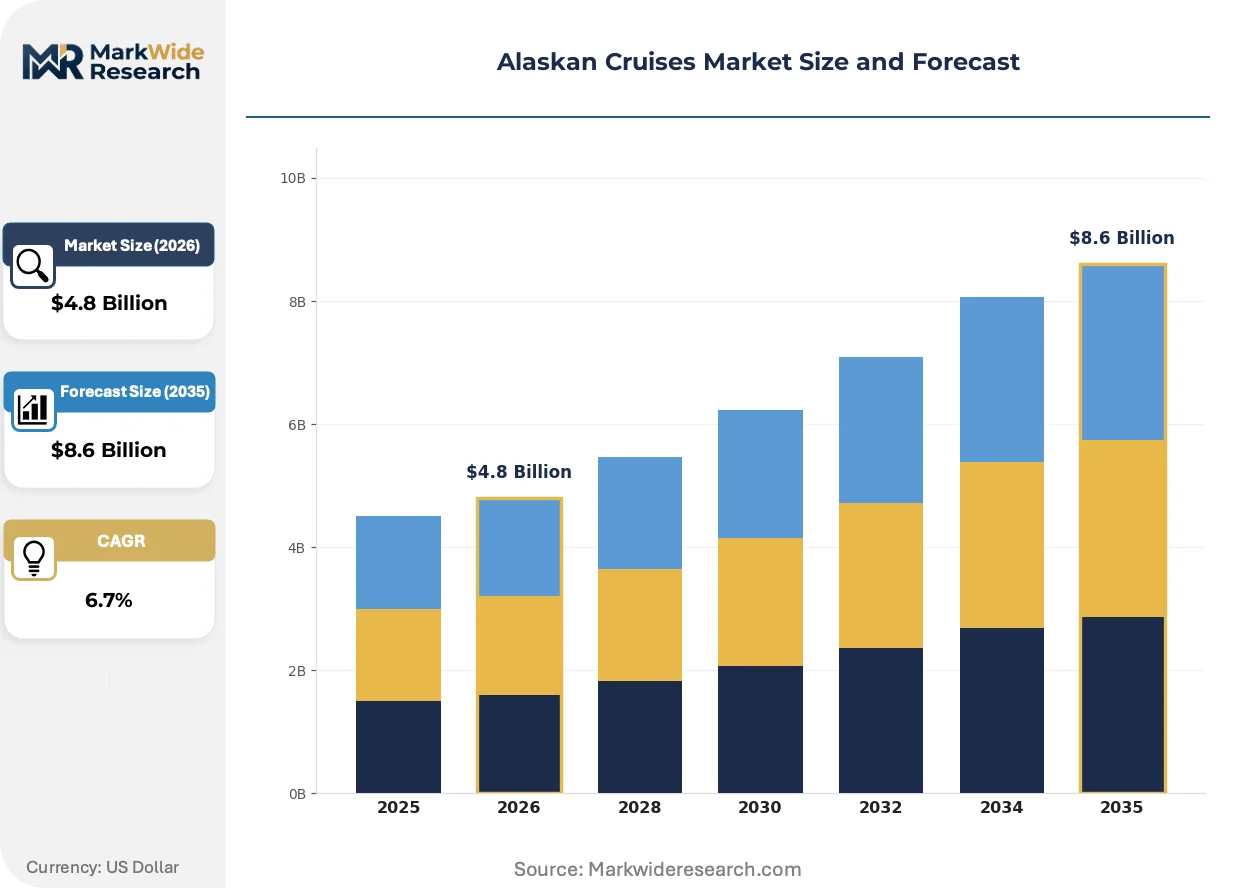
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cruise Type: Luxury Cruises, Expedition Cruises, Family Cruises, Adventure Cruises Customer Type: Families, Couples, Solo Travelers, Seniors Duration: 3-5 Nights, 6-8 Nights, 9-12 Nights, 13+ Nights Onboard Experience: Fine Dining, Entertainment, Wellness Programs, Educational Workshops |
| Companies Covered | Princess Cruises, Holland America Line, Norwegian Cruise Line, Carnival Cruise Line, Celebrity Cruises, Royal Caribbean, Disney Cruise Line, Seabourn, Lindblad Expeditions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alaskan Cruises Market Strategic Shifts
Vessel design and passenger experience architecture are converging around environmental performance metrics, with operators competing on measurable footprint reduction rather than amenity scale alone.
Hybrid propulsion architecture is hybridizing conventional diesel-electric systems with battery storage and shore connection capability. Expedition cruise operators are adopting these configurations fastest, with newbuild specifications now standardizing 8-10 megawatt-hour battery capacity. This technology is compressing the operational cost gap between ice-strengthened expedition vessels and larger conventional ships in restricted waterways.
The US Coast Guard is enforcing stricter 46 CFR Subchapter H stability requirements for passenger vessels operating in Alaskan waters. These rules are accelerating retirement of older tonnage and elevating newbuild specification costs. Small-ship expedition operators with newer fleets are capturing repositioned demand from displaced legacy capacity.
Wellness programming and educational workshop bundling is displacing traditional onboard retail and casino revenue as primary margin drivers. Premium cruise passengers are selecting itineraries based on curated naturalist expertise and spa service quality rather than entertainment venue scale. This pattern concentrates among repeat cruisers aged 55-70 booking through direct channels.
Alaskan Cruises Market Segmentation
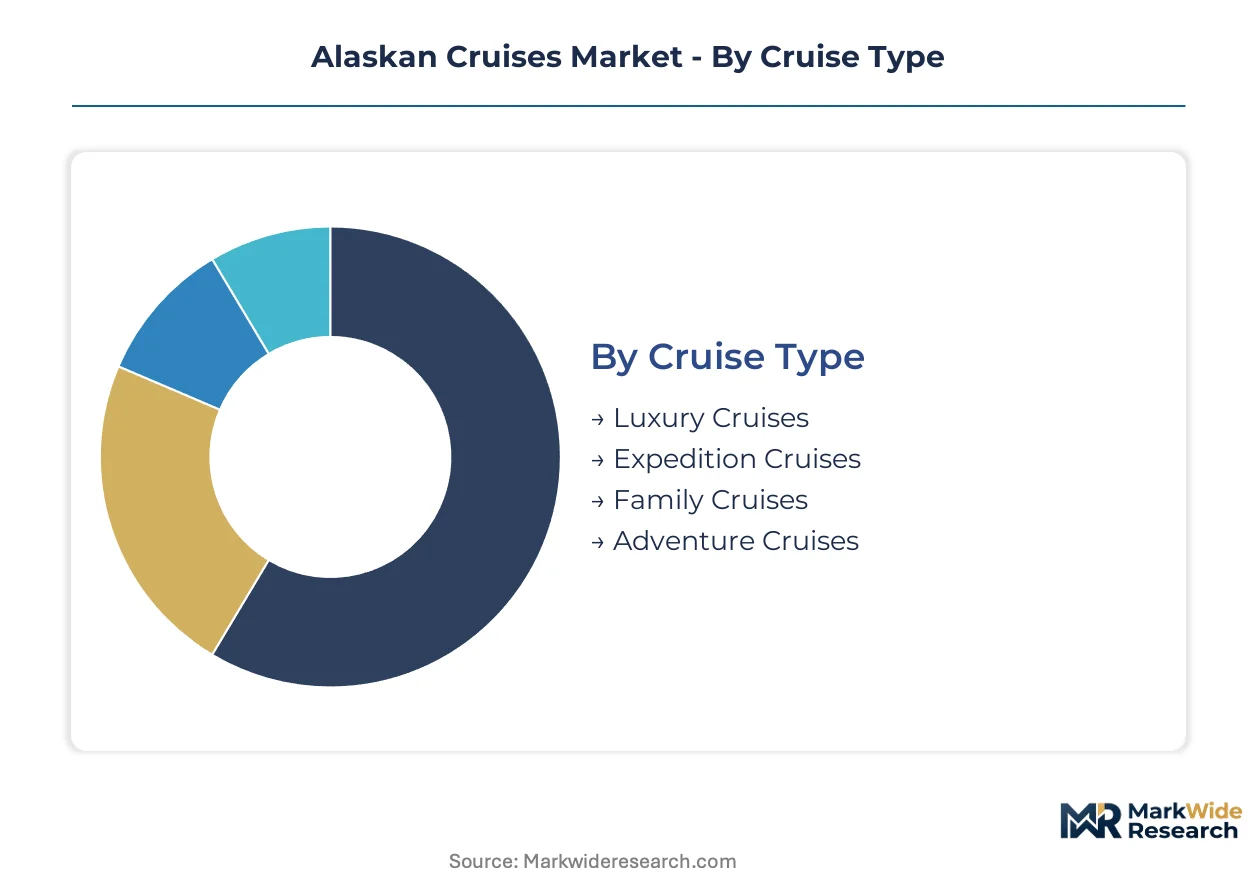
Segmentation in the Alaskan cruise market reveals how passenger expectations diverge across experience intensity, social composition, and time commitment. Operators calibrate fleet deployment and port negotiations against these divides to optimize berth utilization within the compressed May-September sailing window.
Cruise Type:
Mature mass-market formats coexist with emerging expedition formats as ice-strengthened hull technology redefines accessible geography.
- Luxury Cruises:These vessels emphasize spacious suite configurations, white-glove service ratios, and exclusive shore excursion access. Demand concentrates among repeat cruisers aged 55-70 booking direct channels, with per-passenger yields sustained through bundled fine dining and private naturalist programming.
- Expedition Cruises:Ice-strengthened hull specifications enable navigation into glacial fjords previously inaccessible to conventional tonnage. Passenger volume is accelerating fastest in this category as experience-seeking demographics prioritize wildlife proximity over amenity scale.
- Family Cruises:Structured youth programming and connecting cabin inventory dominate fleet positioning during peak summer weeks. Alaska Department of Environmental Conservation discharge protocols constrain onboard water park specifications in certain protected corridors.
- Adventure Cruises:Kayak deployment platforms and guided hiking-intensive itineraries define this middle-market tier. Port calls emphasize Ketchikan and Seward for backcountry access.
Luxury Cruises retain volume leadership; Expedition Cruises hold the steepest expansion curve.
Customer Type:
Cost tier stratification separates predictable seasonal recurrence from emerging margin pools requiring inventory redesign.
- Families:Multi-generational booking patterns concentrate in July-August school holiday windows. Juneau-Skagway corridor itineraries dominate selection due to glacier accessibility and shorter flight connections from Seattle.
- Couples:Anniversary and honeymoon segments drive premium balcony cabin absorption. Wellness programming bundling displaces traditional casino revenue as the primary margin anchor for this demographic.
- Solo Travelers:Single-occupancy cabin scarcity has historically suppressed this segment. Operators now reconfiguring interior inventory and social programming to capture underserved yield.
- Seniors:Repeat cruiser loyalty programs and accessible excursion design sustain retention. Educational workshop quality ranks above entertainment venue scale in itinerary selection criteria.
Families retain volume leadership; Solo Travelers hold the steepest expansion curve.
Duration:
Application logic separates gateway market accessibility from immersive protected-area penetration.
- 3-5 Nights:Vancouver or Seattle round-trip positioning targets first-time Alaska visitors and constrained vacation schedules. Glacier Bay National Park access permits are rarely secured for these abbreviated itineraries.
- 6-8 Nights:The commercial sweet spot balances Inside Passage density with Gulf of Alaska crossing options. US Coast Guard 46 CFR Subchapter H stability requirements apply uniformly across this duration band.
- 9-12 Nights:Extended itineraries incorporate Seward or Whittier turnarounds with Denali land-tour extensions. Demand concentrates among international source markets with longer travel investment horizons.
- 13+ Nights:Repositioning segments connecting Alaska with Asia-Pacific or Panama Canal routes. Seasonal operating window compression limits annual departure frequency.
6-8 Nights retain volume leadership; 9-12 Nights hold the steepest expansion curve.
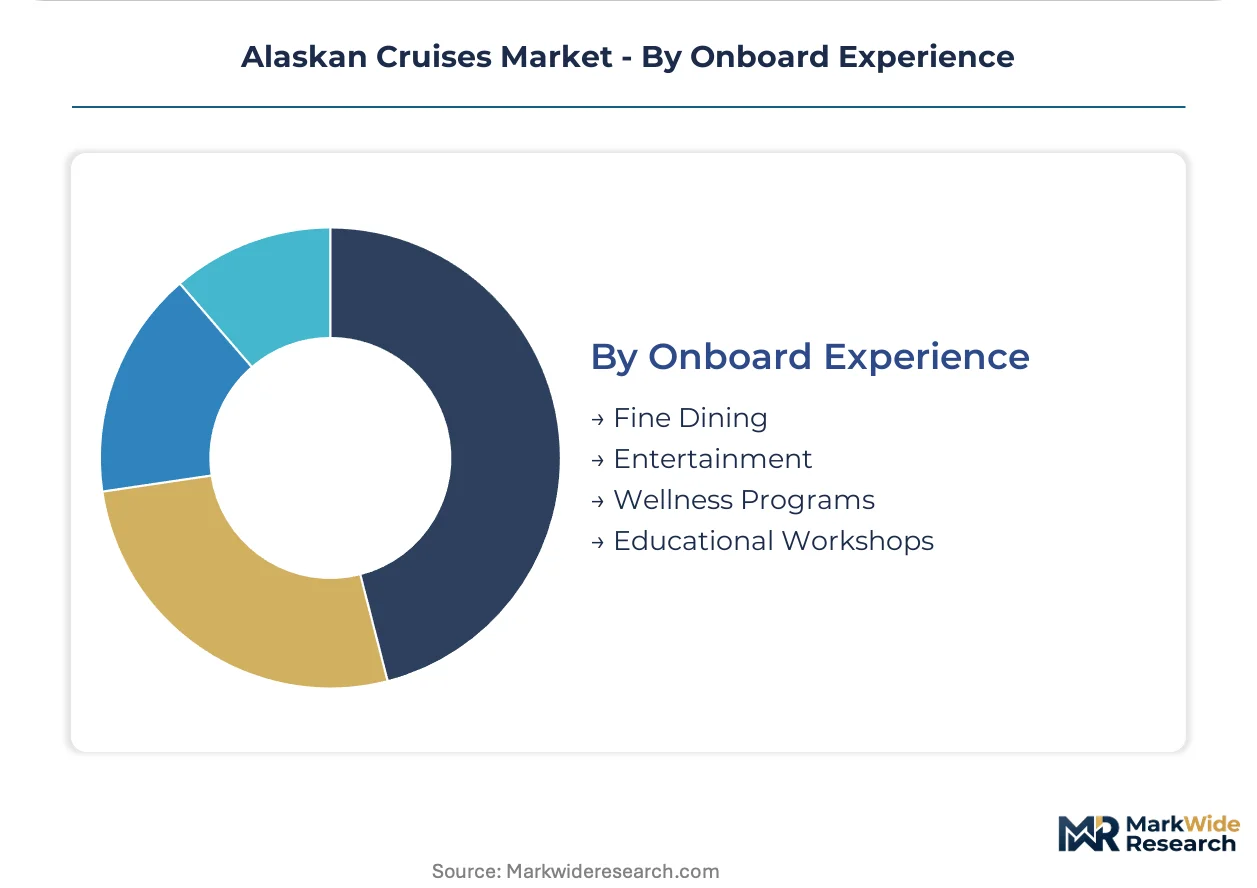
Onboard Experience:
Margin concentration is displacing legacy revenue architecture as passenger preferences pivot from scale to curation.
- Fine Dining:Regional seafood sourcing partnerships and chef-branded venues command cover charges that offset compressed casino yield. Alaska Department of Environmental Conservation wastewater protocols constrain galley effluent discharge in certain fjords.
- Entertainment:Production show scale remains relevant for mass-market tonnage but declining as a primary selection driver. Younger-skewing venues with flexible fare structures are gaining share fastest in this category.
- Wellness Programs:Spa service quality and thermal suite access now rank among top-three booking criteria for premium segments. Tlingit and Haida interpretive partnerships create intellectual property differentiation in adjacent educational programming.
- Educational Workshops:Curated naturalist expertise and photography instruction displace traditional onboard retail as margin drivers. National Park Service ranger embarkations in Glacier Bay reinforce scarcity value.
Fine Dining retains volume leadership; Wellness Programs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across source markets. West Coast US passengers absorb premium positioning for glacier-accessible itineraries. International long-haul visitors prioritize duration value over cabin category upgrades.
United States
Seattle and Vancouver serve as primary embarkation points for Inside Passage routes. The US Coast Guard enforces 46 CFR Subchapter H stability standards that constrain vessel eligibility. Alaska's Juneau-Skagway corridor concentrates 60% of annual passenger volume due to glacier proximity.
Canada
British Columbia's Vancouver port anchors southbound Alaska itineraries with pre-cruise hotel packages driving ancillary revenue. Transport Canada administers marine safety regulations aligned with SOLAS conventions. The Victoria terminal expansion project targets shore power infrastructure to meet emissions compliance timelines.
United Kingdom
London-based tour operators package Alaska cruises with Rocky Mountaineer rail extensions for premium FIT segments. The Maritime and Coastguard Agency enforces passenger vessel safety certification for UK-flagged expedition tonnage. Southampton repositioning calls connect Alaska with Asia-Pacific routes.
Germany
German source market demand concentrates in 9-12 night itineraries with land-tour extensions to Denali. The Federal Maritime and Hydrographic Agency regulates ice-class certification for vessels operating Arctic-adjacent waters. Hamburg-based expedition cruise specialists source newbuild capacity from Nordic yards.
Australia
Sydney and Melbourne generate repositioning cruise demand via transpacific Panama Canal connections. The Australian Maritime Safety Authority mandates equivalent safety standards for foreign-flagged vessels carrying Australian nationals. Cruise lines deploy dedicated sales teams to capture emerging solo traveler segments.
Alaskan Cruises Market Competitive Environment
Capability concentration sits with expedition operators possessing ice-strengthened hull technology; scale advantage sits with mass-market lines commanding berth allocation in congested ports. The competitive structure splits between heritage Alaska specialists and diversified global fleets. Three archetypes dominate: glacier-access specialists, premium experience curators, and volume-driven family operators. Strategic moves center on National Park Service permit accumulation and hybrid propulsion newbuild commitments.
Within the heritage Alaska tier, Princess Cruises and Holland America Line occupy positions sustained through decades-long port relationships and repeat cruiser loyalty architectures. Norwegian Cruise Line exemplifies the flexible-fare challenger model targeting younger-skewing demographics. Among expedition specialists, Lindblad Expeditions represents the naturalist-curated experience archetype with National Geographic partnership differentiation.
| Leading Market Players |
|---|
| Princess Cruises |
| Holland America Line |
| Norwegian Cruise Line |
| Carnival Cruise Line |
| Celebrity Cruises |
| Royal Caribbean |
| Disney Cruise Line |
| Seabourn |
| Lindblad Expeditions |
| Others |
Value Chain & Pricing Dynamics
Alaska Department of Environmental Conservation wastewater discharge protocols function as a regulatory chokepoint that compresses margin tiers across expedition and mass-market operators while forcing supply chain reconfiguration toward advanced treatment system suppliers and shore power infrastructure providers.
Pricing Analysis
Onboard wellness programming and curated educational workshops now drive lifetime passenger value beyond base fare capture. Three-tier pricing structure across premium balcony, standard interior, and economy guarantee categories stratifies yield with glacier-accessible itineraries commanding berth scarcity premiums. Pricing pressure stems from environmental compliance capital requirements that elevate newbuild specification costs and accelerate legacy tonnage retirement. International long-haul visitors exhibit highest price sensitivity while repeat cruisers aged 55-70 booking direct channels absorb premium positioning with minimal fare elasticity.
Supply Chain Analysis
Upstream marine engineering talent and ice-class hull fabrication capacity concentrate in Nordic yards, German shipbuilders, and South Korean heavy industry facilities. Vessel construction draws from specialized steel alloys, hybrid battery systems, and advanced wastewater treatment modules as critical component inputs. Single-source vulnerability sits with expedition-grade ice navigation system suppliers serving the ice-strengthened hull segment. Distribution runs through Vancouver and Seattle embarkation terminals with pre-cruise hotel packaging and land-tour extension bundling as downstream margin capture mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid propulsion architecture and battery storage integration constitute a technological inflection that redefines competitive viability across the Alaskan cruise fleet, favoring operators with newbuild commitments over legacy tonnage holders.
For Market Incumbents: Pre-empt National Park Service permit accumulation velocity by securing Glacier Bay commercial access authorizations ahead of 18-24 month application timelines. Anchor competitive position through shore power infrastructure investment at Ketchikan and Seward terminals that differentiates environmental credentials against emerging expedition entrants lacking capital scale for cold-ironing deployment. For New Entrants and Emerging Players: Solo traveler segment underpenetration in interior cabin inventory and social programming architecture offers the most penetrable white-space target for yield capture. Target direct-channel customer acquisition with flexible fare structures and younger-skewing entertainment venues that Norwegian Cruise Line has validated, while leveraging heritage cultural programming partnerships with Tlingit and Haida communities as intellectual property differentiation. For Investors and Strategic Acquirers: The market sits at a fleet renewal phase that favors expedition specialists with ice-strengthened hull technology and newer tonnage compliant with US Coast Guard 46 CFR Subchapter H stability requirements. Monitor National Park Service permit application backlogs as the critical signal for itinerary innovation velocity constraints that affect valuation multiples across the heritage Alaska tier versus expedition challenger archetypes.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Newbuild Commitment | Battery storage integration compresses operational cost gaps in restricted waterways. |
| National Park Service Permit Accumulation | Glacier Bay access authorization creates scarcity value monetizable through premium positioning. |
| Shore Power Infrastructure Investment | Cold-ironing capability at Ketchikan and Seward enables emissions compliance differentiation. |
| Heritage Cultural Programming Partnership | Tlingit and Haida interpretive agreements create intellectual property barriers against competitors. |
| Solo Traveler Cabin Reconfiguration | Single-occupancy inventory redesign captures underserved demographic yield with higher per-passenger margins. |
Study Parameters
Operator-level perspectives from cruise line revenue management executives, marine engineering procurement leads, port authority infrastructure planners, and National Park Service commercial access coordinators anchored the qualitative base. Primary interview data combined with secondary validation drawn from US Coast Guard vessel documentation filings, Alaska Department of Environmental Conservation discharge permit records, and cruise line SEC 10-K segment disclosures. Bottom-up passenger volume modeling by itinerary corridor and top-down fleet capacity analysis triangulated market sizing across the projection horizon.
Scenario-bracketing around environmental compliance cost trajectories and hybrid propulsion adoption curves structured the analytical framework. Segmentation dimensions modeled encompassed cruise type, customer composition, duration band, and embarkation port cluster throughout the forecast period. CAGRs derived from berth allocation velocity in the Juneau-Skagway corridor, ice-class vessel orderbook analysis, and repeat cruiser loyalty program retention metrics supplied industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized expedition specialists or unexpected National Park Service permit allocation shifts would shift outcomes. Quarterly review of marine engineer recruitment cycle extension and shore power infrastructure construction timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market