
 Cruise Tourism Market | 2026-2036
Cruise Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Cruise Tourism Market Analysis
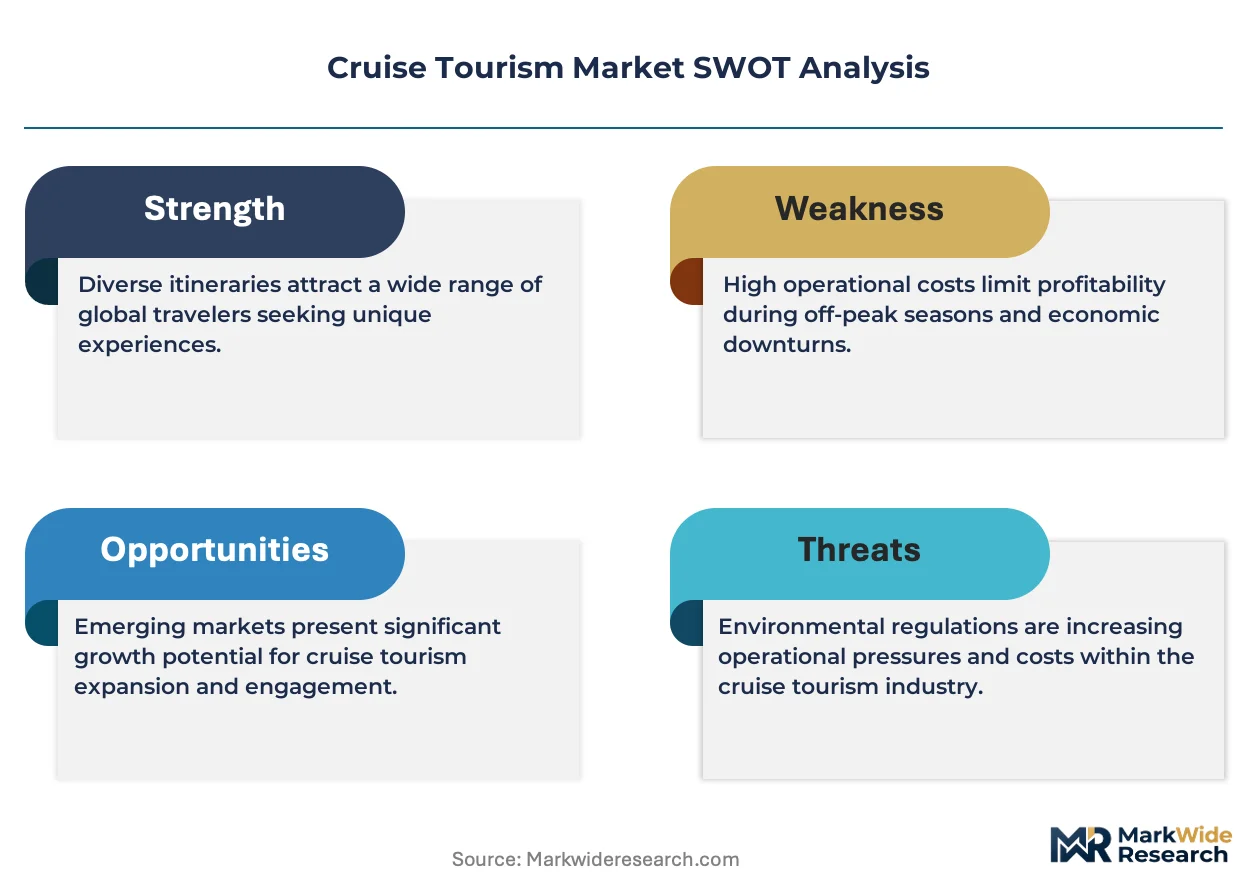
IMO 2023 emission regulations is decoupling legacy fleet economics from newbuild viability, forcing operators to reevaluate capital deployment timelines. Carnival Corporation navigates this transition through scale advantages in dual-fuel vessel procurement. Royal Caribbean Cruise Lines anchors its position through proprietary private destination infrastructure that insulates yield from port congestion. Norwegian Cruise Line Holdings differentiates via flexible class architecture that segments guest experience without duplicating hull designs.
Cruise tourism constitutes a packaged hospitality service delivered via self-contained maritime vessels, combining transportation, accommodation, and entertainment across sequential port calls with passenger capacities ranging from under 200 on expedition vessels to over 6,000 on mega ships. The service generates revenue through ticket sales, onboard spending, and shore excursion commissions with yield management systems optimizing cabin inventory across booking windows. Luxury ships command premium pricing through space ratios and inclusive fare structures that concentrate margin pools among ultra-high-net-worth travelers. Expedition ships represent the fastest-growing category as polar route permits and specialist vessel scarcity create capacity constraints. Mega ships sustain volume economics through amortized entertainment infrastructure and diversified dining venues that extend dwell-time spending.
The US Coast Guard enforces passenger vessel safety standards under SOLAS conventions while the EU MRV monitors carbon reporting for European-ported itineraries, tightening operational transparency requirements. The EPA regulates wastewater discharge in Alaskan waters, directly shaping itinerary design and treatment system investments for operators serving that corridor. Stakeholders must weigh regulatory compliance capex against itinerary yield potential as emission control area expansion redefines viable routing economics.
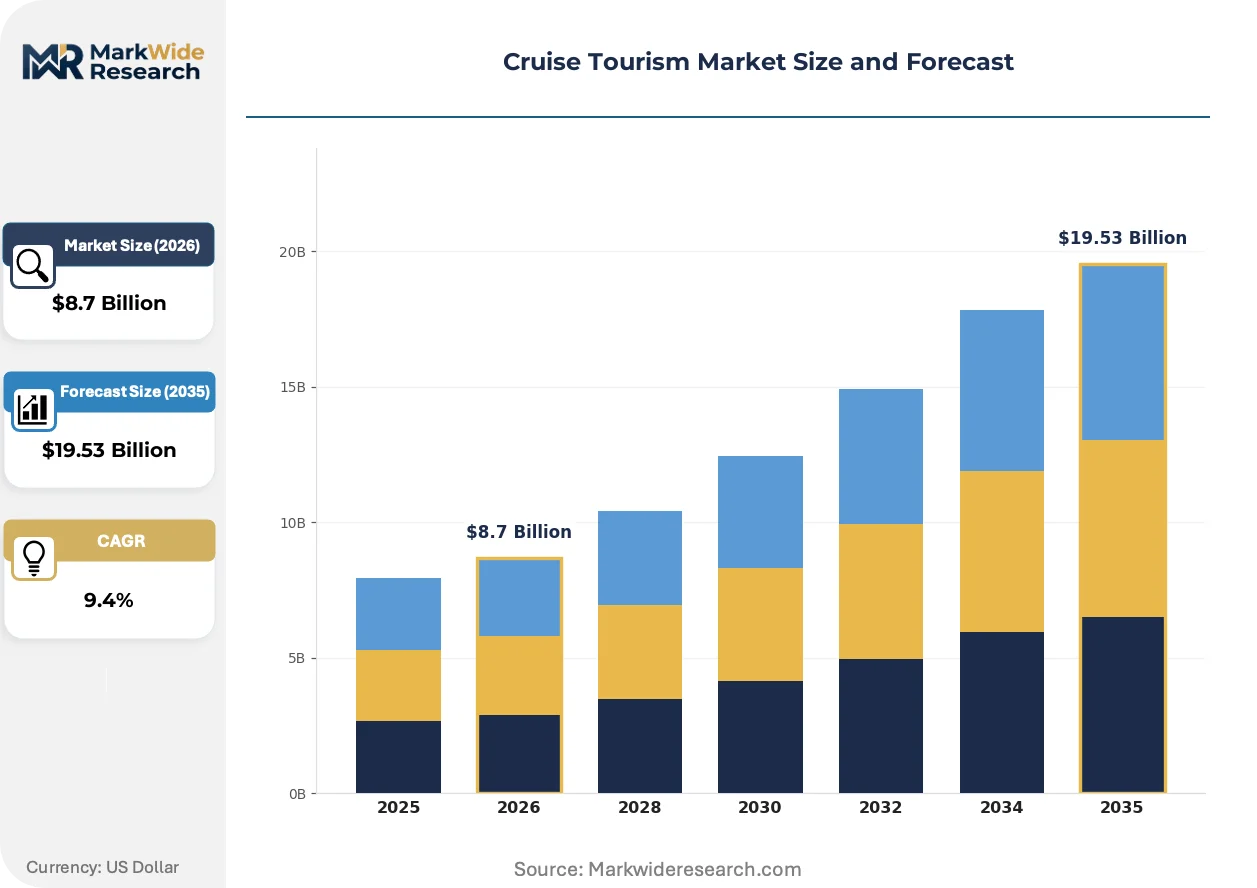
Market Dynamics
The International Maritime Organization's 2023 emission standards are forcing a capital-intensive fleet transition, decoupling legacy vessel economics from newbuild viability and compressing operator deployment timelines across all passenger segments.
Growth Catalysts
- Expedition Vessel Scarcity:Polar route permit constraints and specialist hull shortages create capacity bottlenecks that sustain premium pricing power among affluent adventure travelers targeting Antarctic and Arctic corridors.
- Shore Power Mandates:The EU Alternative Fuels Infrastructure Regulation mandates port electrification infrastructure, enabling LNG-electric hybrid vessels to eliminate auxiliary engine emissions during port calls in Barcelona, Southampton, and Rotterdam.
- Private Destination Infrastructure:Proprietary island developments insulate yield from congested municipal port schedules while capturing 100% of shore excursion spend through captive hospitality ecosystems.
Market Restraints
- Dual-Fuel Engine Cost Premium:LNG-compatible propulsion systems add 15-20% to newbuild capital outlays, straining balance sheets for mid-tier operators without Carnival Corporation's procurement scale.
- European Shipyard Concentration:Meyer Werft, Fincantieri, and Chantiers de l'Atlantique control 90% of large cruise vessel construction, creating orderbook bottlenecks and limited pricing leverage for buyers.
- Alaska Wastewater Regulations:EPA discharge standards in Alaskan waters require advanced treatment system retrofits that constrain itinerary design and eliminate marginal port calls for non-compliant vessels.
Strategic Opportunities
- Japan Expedition Expansion:METI tourism infrastructure investments in Hokkaido and Okinawa create new embarkation points for polar-class vessels targeting the Asia-Pacific affluent demographic.
- Modular Cabin Architecture:Flexible stateroom configurations enable rapid reconfiguration between premium and standard inventory without dry-dock intervention, optimizing yield across booking windows.
- EU Green Deal Taxonomy Alignment:Sustainable finance classification for low-emission maritime transport unlocks preferential debt pricing for LNG and methanol-ready newbuild programs.
Industry Challenges
- Marine Engineer Talent Pipeline:Specialized training for dual-fuel propulsion and exhaust scrubber systems outpaces maritime academy output, creating crew certification backlogs.
- Legacy Fleet Stranding Risk:Non-compliant vessels face accelerated depreciation and exclusion from emission control areas, forcing premature retirement decisions before book value recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruise Tourism Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cruise Lines, Shore Excursions, Onboard Entertainment, Travel Packages Customer Type: Families, Couples, Solo Travelers, Seniors Duration: Short Cruises, Week-long Cruises, Extended Cruises, Themed Cruises Ship Type: Luxury Ships, Expedition Ships, River Cruise Vessels, Mega Ships |
| Companies Covered | Norwegian Cruise Line Holdings, Regent Seven Seas Cruises, Carnival Corporation, Celebrity Cruises, Viking Cruises, Royal Caribbean Cruise Lines, Disney Cruise Line, AmaWaterways, MSC Cruises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruise Tourism Market Emerging Trajectories
Propulsion technology and regulatory compliance systems are converging to redefine vessel economics, with operators racing to deploy lower-carbon fleets before carbon pricing mechanisms activate across major embarkation markets.
Battery-hybrid propulsion systems are consolidating auxiliary power architecture aboard mid-size vessels, with Silversea and Seabourn retrofitting expedition ships to eliminate diesel generator runtime in sensitive marine environments. The technology enables zero-emission maneuvering in Norwegian fjords and Galápagos protected waters. This shift is consolidating competitive advantage around operators with capital reserves to absorb retrofit cycles while smaller competitors face asset stranding.
The EU Monitoring, Reporting and Verification regulation tightens carbon disclosure requirements for European-ported itineraries, mandating granular fuel consumption transparency from 2024. Operators must install certified flow meters and submit verified emissions data to flag states. Luxury and premium segments face the steepest compliance cost escalation as their older, smaller vessels lack the hull space for treatment system retrofits without passenger capacity sacrifice.
Affluent travelers are fragmenting booking channels away from traditional travel agencies toward direct operator platforms and specialist expedition advisors. Seabourn and Ponant report 40% of polar bookings now originate through direct digital channels or niche adventure travel networks. This disintermediation concentrates in English-speaking markets and Germany, where regulatory transparency around carbon footprint disclosure influences platform selection criteria.
Cruise Tourism Market Segmentation
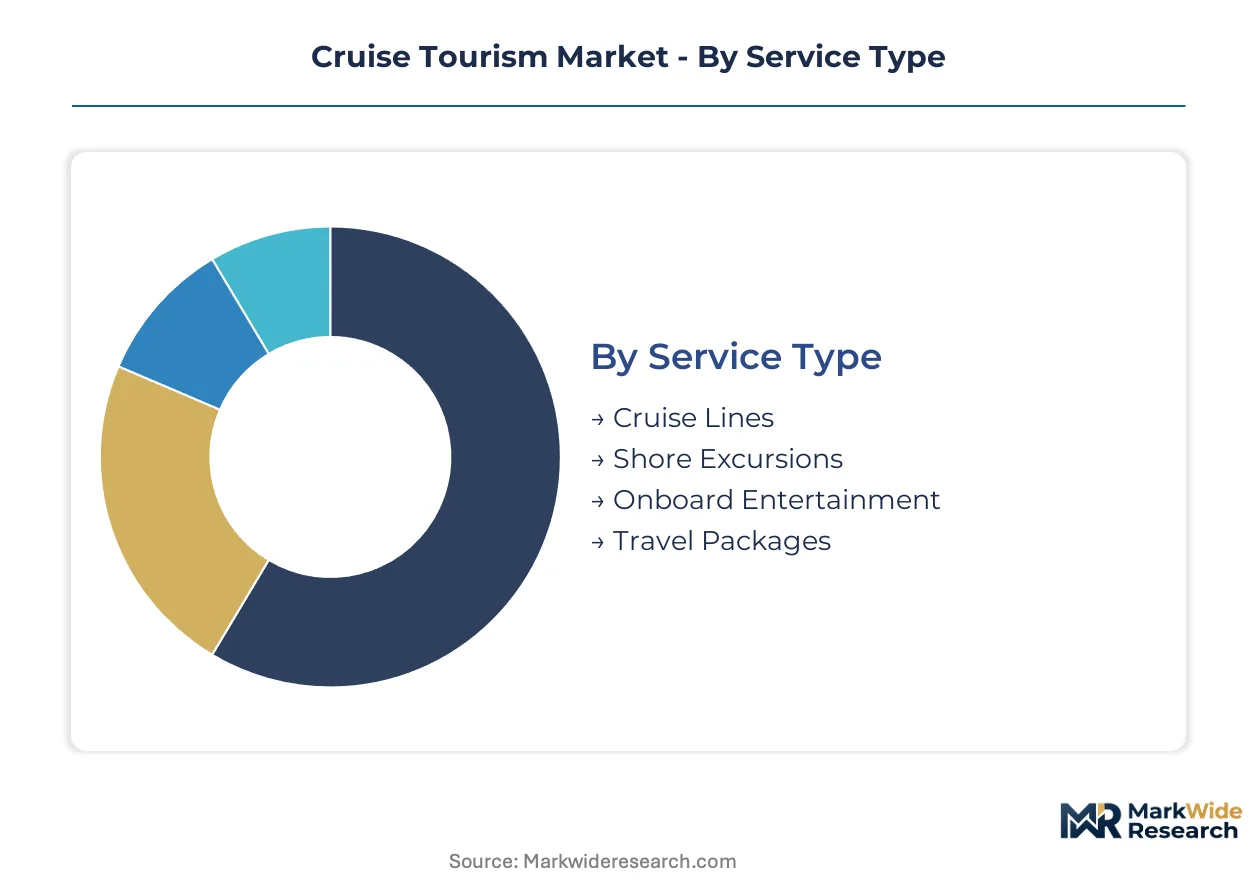
Cruise tourism segmentation reveals divergent capital requirements and yield profiles across vessel categories and service models. Operators deploy distinct infrastructure strategies for expedition hulls versus mega-ship entertainment complexes. Customer and duration segments determine booking window dynamics and onboard spending velocity.
Service Type:
Cruise Lines command the highest upfront capital commitment, requiring hull acquisition, crew certification, and port access agreements before revenue generation begins.
- Cruise Lines:Vessel ownership and charter operations form the capital backbone of the industry, with dual-fuel propulsion systems adding substantial newbuild premiums. Demand concentrates among affluent adventure travelers seeking Antarctic and Arctic corridors, where polar route permit scarcity sustains premium pricing power.
- Shore Excursions:Commission-based port activities generate ancillary revenue through third-party operator partnerships or proprietary destination infrastructure. Caribbean and Mediterranean itineraries remain the primary demand concentration zones, with private island developments capturing full excursion spend.
- Onboard Entertainment:Amortized theater, casino, and specialty dining infrastructure extends passenger dwell-time spending across sequential sea days.
- Travel Packages:Bundled air-sea offerings integrate pre- and post-cruise accommodation to extend revenue capture beyond vessel operations.
Most installed capacity flows through Cruise Lines. Expansion is steepest in Shore Excursions as proprietary destination infrastructure multiplies yield per passenger.
Customer Type:
Yield optimization varies sharply across demographic segments, with family units driving volume and seniors concentrating margin through inclusive fare tolerance.
- Families:Multi-generational bookings prioritize cabin connectivity and youth programming that extends sailing frequency. Demand clusters in Caribbean embarkation ports during school holiday windows, where shorter duration itineraries accommodate scheduling constraints.
- Couples:Premium stateroom categories and specialty dining packages generate per-passenger spending multiples above family averages. Mediterranean itineraries attract this segment through cultural shore excursion depth.
- Solo Travelers:Single-occupancy cabin inventory and dedicated social programming address historically underserved capacity.
- Seniors:Extended booking windows and inclusive fare structures concentrate ultra-high-net-worth travelers in luxury and expedition segments.
Family bookings dominate passenger volume. Couples deliver the highest per-cabin yield expansion trajectory.
Duration:
Itinerary length determines vessel utilization cycles and the economic viability of distant embarkation points.
- Short Cruises:Three-to-five-day rotations maximize annual passenger throughput on high-capacity hulls. Caribbean routes from Florida and Mediterranean circuits from Barcelona sustain this segment through frequent repeat visitation.
- Week-long Cruises:Standard seven-day itineraries balance sea days with port density across established corridors. Alaska and Norwegian fjord routes concentrate demand here.
- Extended Cruises:Multi-week and world voyage products target retired demographics with time flexibility and accumulated loyalty status.
- Themed Cruises:Nautical heritage, culinary, and music programming commands premium pricing through differentiated experience design.
Week-long deployments carry the largest installed base. Themed products are climbing the fastest through experience differentiation.
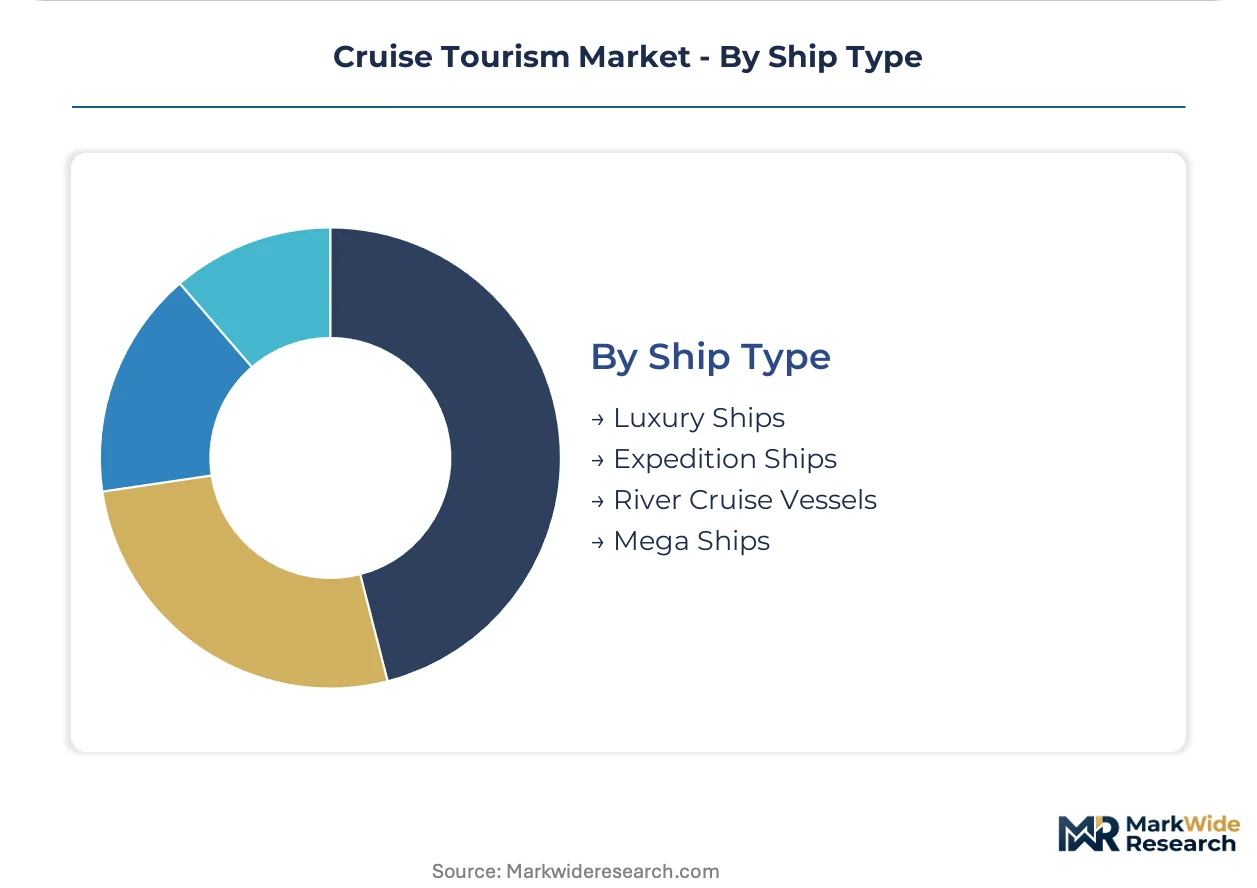
Ship Type:
Hull architecture dictates route access, crew specialization requirements, and the competitive intensity of yield management.
- Luxury Ships:Space ratios above 50 gross tons per passenger and inclusive fare structures concentrate margin pools among ultra-high-net-worth travelers. Demand anchors in English-speaking markets and Germany, where regulatory transparency around carbon footprint influences platform selection.
- Expedition Ships:Polar-class hulls with ice-strengthened construction and specialist crew certification access constrained permit zones. Antarctic and Arctic corridors face capacity bottlenecks from shipyard scarcity and environmental quota limitations.
- River Cruise Vessels:Shallow-draft hulls navigate inland waterways with port-proximity advantages that eliminate sea-day positioning costs.
- Mega Ships:Passenger capacities exceeding 6,000 enable amortized entertainment infrastructure and diversified dining venues that extend dwell-time spending.
Mega Ships deploy the greatest installed capacity. Expedition hulls are gaining share fastest through affluent adventure traveler targeting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine engineers and hospitality crews concentrate in coastal clusters with deep maritime heritage. These talent pools anchor operational headquarters and embarkation infrastructure across distinct national markets.
United States
Florida and Alaska generate the highest passenger embarkation volumes through Miami and Seattle port infrastructure. The EPA regulates wastewater discharge in Alaskan waters, forcing advanced treatment system investments. PortMiami and Port Everglades sustain the world's densest cruise terminal clustering with dedicated shore power installations.
Italy
Luxury shipbuilding heritage and Mediterranean itinerary demand concentrate operational resources in Genoa and Venice. The EU MRV monitors carbon reporting for European-ported itineraries, tightening fuel consumption transparency. Fincantieri shipyards in Monfalcone and Marghera anchor newbuild construction for premium operators.
Germany
River cruise expertise and affluent expedition traveler demand cluster in Hamburg and along Rhine embarkation points. The EU Alternative Fuels Infrastructure Regulation mandates port electrification infrastructure. Meyer Werft in Papenburg maintains specialized cruise vessel construction capacity with LNG-ready hull designs.
China
Shanghai and Tianjin port expansions target outbound cruise tourism growth from middle-class coastal populations. The country's national maritime regulator enforces SOLAS convention compliance for international itineraries. Yangtze River Delta shipyards develop domestic cruise construction capabilities alongside foreign joint ventures.
Australia
Sydney and Brisbane serve as primary embarkation points for South Pacific and expedition itineraries targeting Antarctic corridors. The country's national environmental regulator enforces strict biosecurity and ballast water standards. Expedition vessel operators concentrate crew training facilities in Hobart for polar-class certification.
Cruise Tourism Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across vessel categories and itinerary types. The market structure consolidates around three dominant operators controlling mega-ship capacity, while expedition and river segments fragment among niche specialists. Strategic archetypes include scale-driven volume players, luxury-inclusive operators, and polar-class expedition specialists. Competitive moves center on proprietary destination infrastructure acquisition and dual-fuel fleet renewal programs.
Among diversified cruise conglomerates, Carnival Corporation and Royal Caribbean Cruise Lines occupy positions defined by scale advantages in procurement and port access. Norwegian Cruise Line Holdings exemplifies the flexible-class architecture approach within the premium tier. Viking Cruises anchors the river and expedition specialist archetype through integrated destination control. These three entities represent distinct capital deployment strategies: volume amortization, yield insulation through private infrastructure, and segment-focused experience design.
| Leading Market Players |
|---|
| Norwegian Cruise Line Holdings |
| Regent Seven Seas Cruises |
| Carnival Corporation |
| Celebrity Cruises |
| Viking Cruises |
| Royal Caribbean Cruise Lines |
| Disney Cruise Line |
| AmaWaterways |
| MSC Cruises |
| Others |
Supply Flow & Price Mechanics
LNG-electric hybrid propulsion retrofits simultaneously inflate newbuild capital requirements and consolidate procurement leverage among operators with scale-advantaged shipyard relationships. This technological transition concentrates pricing power with Meyer Werft, Fincantieri, and Chantiers de l'Atlantique while forcing mid-tier buyers into unfavorable contract terms.
Pricing Analysis
Ticket pricing splits between bundled inclusive fares and unbundled base-plus-ancillary models across luxury and premium segments. Three-tier pricing structure across premium, standard, and economy levels differentiates by cabin space ratio and shore excursion inclusion. Cost compression in mid-tier expedition vessels is intensifying because polar-class hull scarcity limits buyer negotiating leverage. Family segments demonstrate highest price sensitivity through booking window timing, while ultra-high-net-worth travelers in luxury categories show minimal fare elasticity.
Supply Chain Analysis
Dual-sourcing requirements for dual-fuel propulsion systems and exhaust scrubber assemblies are mandated by major operators to mitigate European shipyard concentration risk. Newbuild construction draws from Italy, Germany, and France, with specialized steel plate and marine engine components anchored in South Korea and Japan. Single-source vulnerability around ice-class hull certification creates bottlenecks for expedition fleet expansion. Distribution runs through direct operator platforms and specialist expedition advisors, with traditional travel agencies losing share in English-speaking markets and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier yield insulation as private destination infrastructure captures full excursion spend and LNG-ready newbuilds command regulatory-compliant premiums.
For Market Incumbents: Anchor competitive position through proprietary port infrastructure acquisition that eliminates municipal congestion exposure. Accelerate dual-fuel fleet renewal before emission control area expansion strands legacy assets. Defend against expedition specialist encroachment by securing polar route permits early. For New Entrants and Emerging Players: Capture white-space in Japan expedition expansion as METI infrastructure investments create new Hokkaido and Okinawa embarkation points. Target Asia-Pacific affluent demographic through polar-class vessel deployment with Mandarin-speaking crew certification. Pursue direct digital channel development to disintermediate traditional travel agency relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier operators facing legacy fleet stranding risk without Carnival Corporation's procurement scale. Long-term viability favors operators with LNG-ready orderbooks and private destination portfolios. Watch for carbon pricing mechanism activation across major embarkation markets as inflection indicator for regulatory-compliant fleet premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Renewal | LNG propulsion systems satisfy IMO emission standards while enabling shore power compatibility in EU ports. |
| Private Destination Infrastructure | Proprietary island developments capture full excursion spend and insulate yield from municipal port congestion. |
| Polar Route Permit Acquisition | Antarctic and Arctic environmental quotas create capacity constraints that sustain premium pricing power. |
| Direct Digital Channel Expansion | Seabourn and Ponant report 40% of polar bookings now originate through operator platforms and specialist networks. |
| Modular Cabin Architecture Investment | Flexible stateroom configurations enable rapid premium-standard reconfiguration without dry-dock intervention. |
Methodological Framework
Direct dialogue with cruise line fleet planning executives, port authority infrastructure directors, maritime regulatory compliance officers, and expedition travel specialist advisors grounded qualitative findings. Secondary validation drew from IMO emission regulation filings, EU MRV carbon disclosure databases, EPA Alaskan wastewater discharge records, and shipyard orderbook disclosures. Bottom-up vessel deployment modeling and top-down tourism expenditure patterns were triangulated to anchor market sizing.
Bottom-up analysis tracked individual hull configurations, passenger capacities, and itinerary yield assumptions across the projection horizon. Segmentation dimensions modeled include service type, customer demographic, duration category, and ship architecture tier. CAGRs were derived from weighted average of deployment schedules and pricing trajectory assumptions. Forecast inputs incorporated polar route permit availability constraints and shore power infrastructure rollout timelines.
Regulatory enforcement delays, shipyard construction bottlenecks, and carbon pricing mechanism activation timing are the dominant revision risks to modeled outcomes. Deviation in IMO emission standard implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market