
 Global Cruise Market | 2026-2036
Global Cruise Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cruise Market Analysis
Liquefied natural gas is shifting from niche adoption to mainstream propulsion economics across newbuild programs. Carnival Corporation leverages its fleet renewal scale to anchor LNG infrastructure commitments in multiple homeports. Royal Caribbean Group sustains dual-fuel investment intensity across its Oasis and Icon class vessels. Norwegian Cruise Line Holdings differentiates through selective scrubber retrofits and battery-hybrid pilots on select hulls.
A cruise vessel constitutes a self-contained maritime hospitality platform, typically exceeding 70,000 gross tons for ocean-going units, integrating propulsion, lodging, food service, and entertainment systems for sustained multi-day voyages. Its commercial purpose centers on packaged vacation experiences combining transportation, accommodation, and destination access in a single tariff structure. Contemporary vessels dominate deployed capacity and passenger volume, while expedition categories command premium pricing through specialized ice-class hulls and limited guest counts. Luxury segments concentrate margin pools through higher per-diems and lower passenger-to-crew ratios. River categories occupy a distinct operational niche with shallower draft requirements and port-proximity economics.
The International Maritime Organization enforces MARPOL Annex VI emission standards that constrain sulfur oxide and nitrogen oxide outputs, directly shaping engine technology selection and scrubber installation decisions. The EU Green Deal and associated Fit for 55 framework extend carbon intensity benchmarks to vessels calling at European ports, tightening compliance windows for older tonnage. The US Coast Guard and CDC maintain overlapping safety and sanitation protocols that govern market access for Caribbean-focused itineraries. Stakeholders must monitor LNG bunkering network maturity and alternative fuel certification pathways to align fleet planning with tightening operational constraints.
Market Dynamics
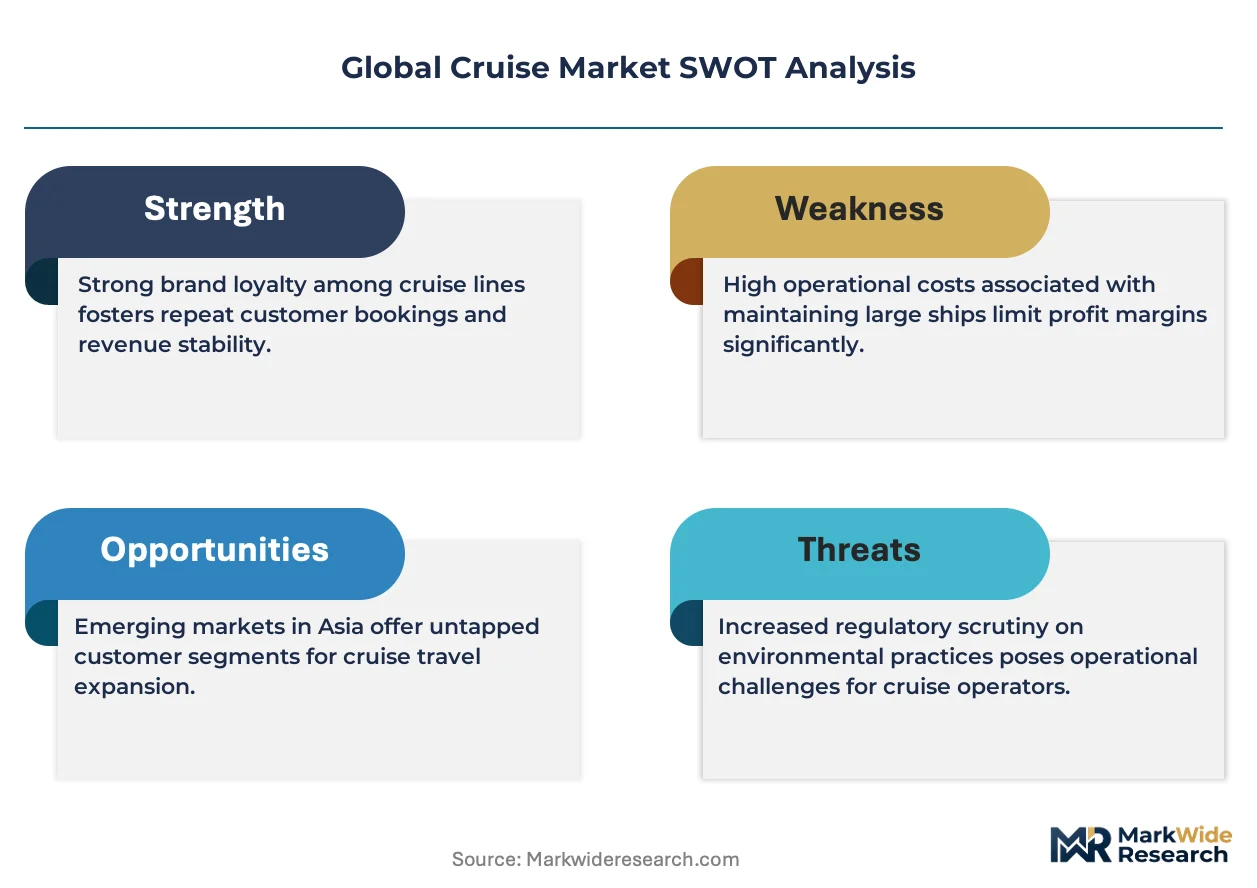
The EU Green Deal and IMO MARPOL Annex VI emission standards are forcing a fleet-wide propulsion transition, compressing capital deployment timelines and reshaping competitive positioning around fuel infrastructure access rather than hull economics alone.
Growth Catalysts
- Multi-generational family travel:Extended-family booking patterns are expanding average cabin occupancy and onboard spending per voyage, particularly across Mediterranean and Caribbean itineraries.
- LNG bunkering infrastructure:Port authorities in Spain, Italy, and the Netherlands are anchoring supply commitments that de-risk newbuild propulsion decisions for fleet operators.
- Expedition category premiumization:Ice-class hull specifications and limited passenger counts command pricing multiples that justify specialized vessel construction.
Market Restraints
- Steel and marine equipment cost volatility:Newbuild program economics face input price uncertainty from concentrated Asian shipyard supply chains.
- Scrubber retrofit payback compression:Low-sulfur fuel price spreads have narrowed, extending return timelines for exhaust cleaning installations on existing tonnage.
- Port congestion at marquee destinations:Infrastructure limits in Dubrovnik, Santorini, and Barcelona constrain daily passenger volumes and itinerary flexibility.
Strategic Opportunities
- India outbound market development:Mumbai and Chennai homeporting potential remains underdeveloped relative to per-capita income growth curves.
- Battery-hybrid shore power integration:Converging shore-side electricity infrastructure and onboard storage systems enable zero-emission port operations.
- EU Fit for 55 carbon intensity benchmarks:Compliance windows create first-mover advantages for operators with younger, more efficient fleets calling at European ports.
Industry Challenges
- Marine engineering talent scarcity:Specialized propulsion system expertise—particularly dual-fuel engine and cryogenic fuel handling—outpaces training pipeline output.
- Classification society certification timelines:Novel alternative fuel approvals from Lloyd's Register and DNV extend newbuild delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cruise Market |
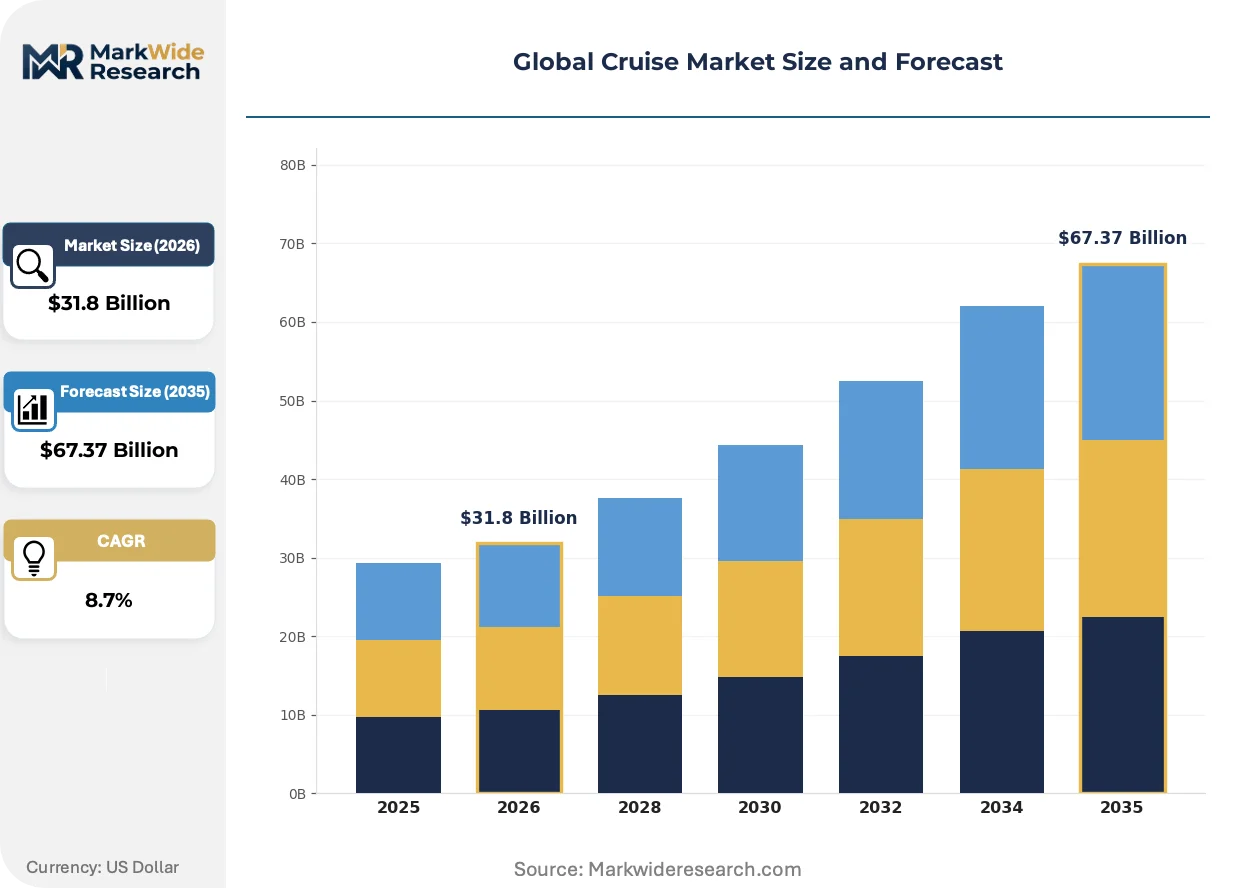
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $67.37 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Luxury, Contemporary, River, Expedition Customer Type: Families, Couples, Solo Travelers, Seniors Itinerary Type: Transatlantic, Mediterranean, Caribbean, Alaskan Service Type: All-Inclusive, Basic, Premium, Excursion-Based |
| Companies Covered | Carnival Corporation, Royal Caribbean Group, Norwegian Cruise Line Holdings, MSC Cruises, Princess Cruises, Celebrity Cruises, Disney Cruise Line, Viking Cruises, Virgin Voyages, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cruise Market Emerging Trajectories
Liquefied natural gas propulsion systems are actively reshaping fleet renewal economics, with infrastructure lock-in effects creating durable competitive moats for early movers in key homeport clusters.
Dual-fuel LNG marine engines are overtaking conventional diesel-electric configurations as the default specification for ocean-going newbuilds. Major fleet operators now specify LNG-ready propulsion for vessels exceeding 100,000 gross tons, compressing the residual value of legacy tonnage unable to access emerging bunkering networks. This technology shift is enabling longer compliance horizons against tightening NOx and SOx emission limits while constraining route flexibility to ports with confirmed fuel availability.
The EU Fit for 55 framework extends carbon intensity benchmarks to all vessels calling at European ports from 2025. Shipowners face escalating compliance costs for older tonnage, accelerating demolition decisions and favoring operators with newer fleets. Mediterranean and Northern European itineraries bear the highest regulatory exposure, prompting itinerary rebalancing toward non-EU ports where feasible.
Charter and incentive-based booking models are displacing traditional fixed-itinerary sales in the expedition and luxury segments. Affluent travelers increasingly demand customizable port sequences and extended destination immersion, compressing standard seven-day cycle preferences. This pattern is most visible in Alaska and Antarctica markets, where flexible scheduling commands pricing premiums over rigid departure calendars.
Global Cruise Market Segmentation
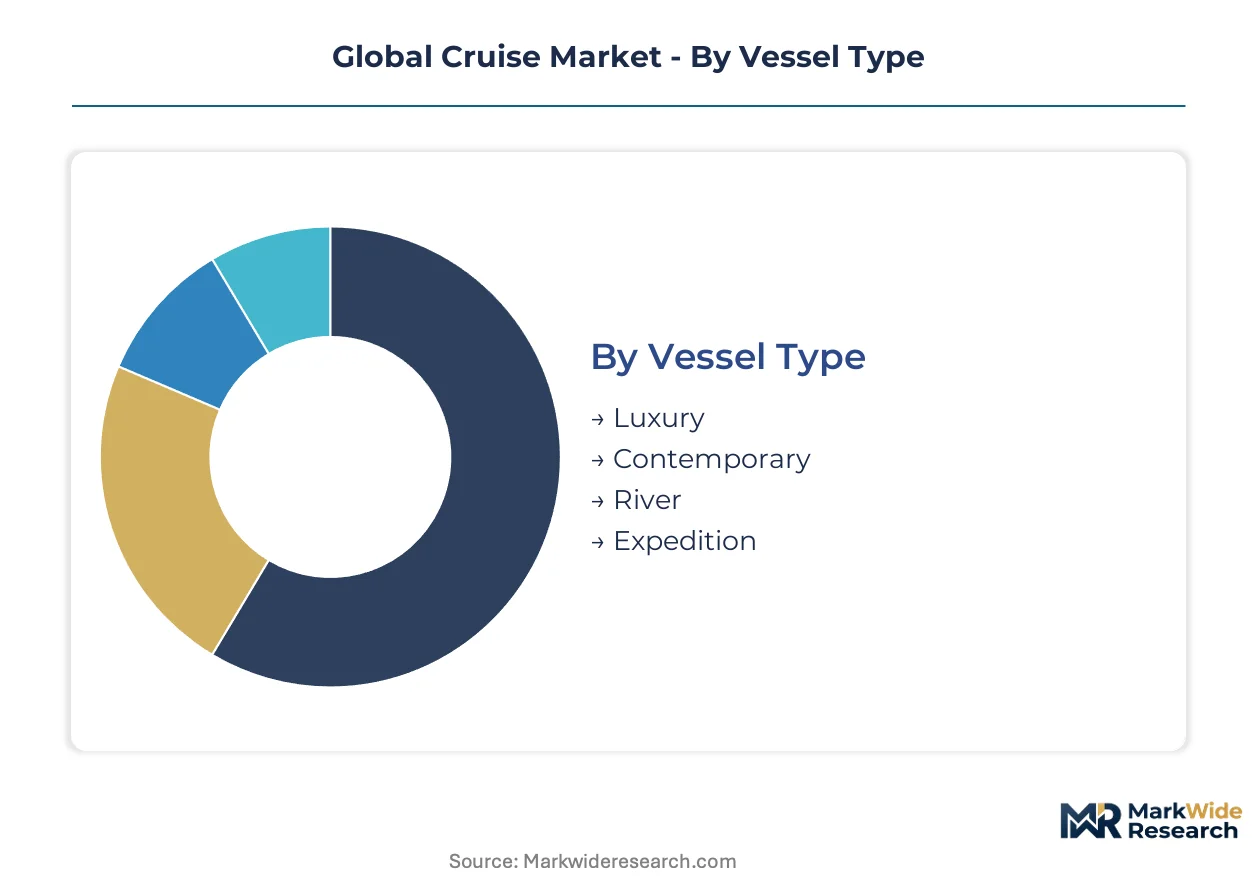
Cruise market segmentation reveals how vessel economics, customer demographics, and itinerary design interlock to determine revenue architecture. Operators calibrate capacity deployment across these dimensions to optimize load factors and per-passenger yields.
Vessel Type:
Standalone vessel categories operate as distinct profit pools with minimal cross-segment substitution, while embedded propulsion and hospitality systems create technology lock-in effects that segment operators by infrastructure access.
- Contemporary:These vessels exceed 100,000 gross tons with standardized cabin configurations and mass-market entertainment programming. Demand concentrates in Caribbean and Mediterranean homeports where port infrastructure supports high passenger throughput. Carnival Corporation and Royal Caribbean Group anchor fleet renewal programs here, leveraging scale economies in LNG propulsion procurement.
- Luxury:Smaller hulls under 50,000 gross tons emphasize space ratios and personalized service delivery. Seabourn and Silversea capture demand from ultra-high-net-worth travelers in Northern European and Asia-Pacific itineraries, where per-diems justify elevated crew-to-guest ratios and premium F&B sourcing.
- River:Shallow-draft vessels navigate inland waterways with port-proximity economics. Viking River Cruises dominates European Rhine and Danube deployments, while AmaWaterways expands Southeast Asian Mekong operations.
- Expedition:Ice-class specifications enable polar navigation with strict passenger limits. Lindblad Expeditions and Ponant command pricing multiples in Antarctica and Arctic markets where regulatory caps constrain supply expansion.
Volume placements concentrate in Contemporary; the faster expansion belongs to Expedition.
Customer Type:
Booking patterns segment by cabin occupancy economics and onboard spending profiles, with multi-generational clusters driving higher per-voyage revenue than solo or couple configurations.
- Families:Extended-family bookings average 2.8 cabins per reservation with concentrated demand for connecting staterooms and youth programming. Disney Cruise Line and Royal Caribbean capture this segment through branded entertainment IP and adventure facilities, particularly on Caribbean and Bahamas itineraries departing from Florida ports.
- Couples:Adult-focused travelers prioritize dining variety and spa services over children's amenities. Norwegian Cruise Line's "Freestyle Cruising" and Celebrity Cruises' "Modern Luxury" positioning target this demographic with flexible dining and premium cabin categories.
- Solo Travelers:Purpose-built single cabins and reduced single supplements address historically penalized demand. Norwegian's studio cabin complexes and dedicated solo lounges in Breakaway-class vessels have normalized this segment.
- Seniors:Extended voyage durations and enrichment programming align with retirement-schedule flexibility. Holland America Line and Oceania Cruises concentrate deployment in world cruise and grand voyage itineraries with multi-week port immersion.
Family bookings anchor revenue concentration; solo traveler infrastructure investment is climbing the fastest.
Itinerary Type:
Route selection determines regulatory exposure, fuel bunkering requirements, and destination access fees that segment operators by compliance capability and port relationship depth.
- Caribbean:Seven-day Eastern and Western circuits dominate deployed capacity with established private island infrastructure. Royal Caribbean's Perfect Day at CocoCay and Disney's Castaway Cay demonstrate vertical integration into destination experiences that capture excursion revenue.
- Mediterranean:Seasonal deployment from Barcelona, Civitavecchia, and Piraeus faces EU Fit for 55 carbon intensity benchmarks from 2025. Operators with LNG-capable fleets gain compliance advantages in Italian, Spanish, and Greek ports where bunkering infrastructure is maturing.
- Alaskan:Seasonal demand concentrates June through August with strict passenger caps at Glacier Bay and Hubbard Glacier. Holland America and Princess Cruises leverage long-term park service permits that constrain competitive entry.
- Transatlantic:Repositioning voyages bridge seasonal deployment between Caribbean winter and Mediterranean summer markets. Cunard maintains scheduled liner service on this route with Queen Mary 2, while other operators treat these as discounted repositioning inventory.
Caribbean itineraries absorb peak capacity; Mediterranean regulatory pressure is accelerating fleet renewal decisions most sharply.
Service Type:
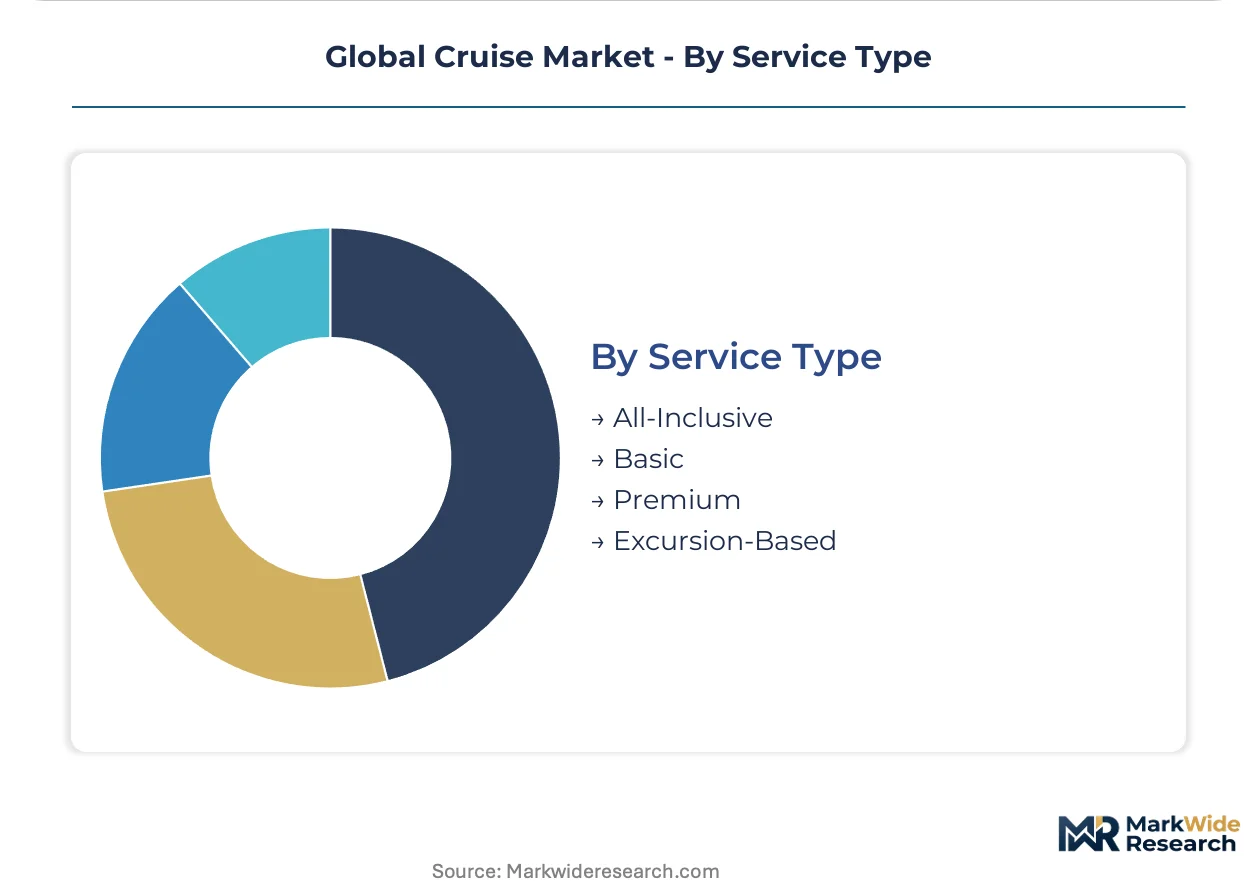
Tariff architecture segments by revenue recognition timing and onboard spending capture, with all-inclusive models front-loading revenue while excursion-based structures retain flexibility.
- All-Inclusive:Bundled pricing covers beverages, gratuities, and specialty dining, reducing passenger decision friction and stabilizing revenue predictability. Regent Seven Seas and Seabourn operate pure all-inclusive models; mainstream lines offer "plus" packages as upgrades.
- Premium:Tiered service levels separate cabin grades, dining venues, and shore excursion access without full bundling. Celebrity Cruises' "The Retreat" and Norwegian's "Haven" create ship-within-ship premium enclaves.
- Basic:Unbundled pricing minimizes entry fares while maximizing ancillary capture through onboard sales. Carnival Corporation's core brands deploy this model with intensive casino, photo, and spa revenue optimization.
- Excursion-Based:Expedition and adventure itineraries treat destination access as the primary value driver. Lindblad's National Geographic partnership and Hurtigruten's science-focused voyages embed expert-led excursions in base pricing.
Basic service structures dominate passenger volume; all-inclusive packaging is gaining share fastest in luxury and expedition categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger sourcing concentrates in the United States, Germany, and the United Kingdom, with homeport infrastructure in Florida, Barcelona, and Southampton anchoring deployment decisions. Regulatory pressure from the EU Green Deal and IMO MARPOL Annex VI is accelerating fleet renewal timelines across European itineraries. Emerging source markets in India and Southeast Asia remain underdeveloped relative to income growth trajectories.
United States
Florida homeports in Miami, Port Canaveral, and Fort Lauderdale absorb the highest passenger volumes globally, driven by Caribbean itinerary demand and private island infrastructure investments. The US Coast Guard and CDC maintain overlapping safety and sanitation protocols governing market access. PortMiami's LNG bunkering terminal expansion supports Carnival Corporation's fleet renewal commitments in the region.
Germany
North Sea and Baltic itineraries from Hamburg and Kiel serve concentrated demand for Northern European voyages among German-speaking travelers. The EU Fit for 55 framework extends carbon intensity benchmarks to vessels calling at German ports from 2025, tightening compliance windows. Meyer Werft in Papenburg anchors specialized cruise vessel construction with dual-fuel LNG propulsion specifications.
United Kingdom
Southampton remains the dominant Northern European homeport for transatlantic and Mediterranean deployments, with secondary capacity in Dover and Liverpool. Maritime and Coastguard Agency enforcement of IMO emission standards shapes operator technology decisions. Harland and Wolff in Belfast supports expedition vessel construction for polar itinerary operators.
Spain
Barcelona and Valencia anchor Western Mediterranean deployment with concentrated demand from European and North American source markets. Spanish port authorities are anchoring LNG supply commitments that de-risk newbuild propulsion decisions for fleet operators. The Port of Barcelona's infrastructure limits constrain daily passenger volumes and itinerary flexibility during peak season.
Italy
Civitavecchia, Genoa, and Venice serve as primary embarkation points for Eastern and Western Mediterranean circuits. Italian regulators enforce EU Green Deal emission benchmarks alongside national coastal protection protocols affecting itinerary design. Fincantieri in Monfalcone and Marghera dominates ocean-going and expedition vessel construction for global operators.
Global Cruise Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators controlling end-to-end vacation packaging while regional players concentrate on itinerary-specific deployment. The vendor base organizes around three strategic archetypes: scale-driven mass-market operators commanding fleet renewal economics, premium specialists capturing higher per-diems through space ratios, and expedition pioneers leveraging ice-class hull scarcity. Competitive moves center on LNG infrastructure lock-in through homeport commitments and selective M&A to acquire expedition permits and polar access rights.
Within the scale-driven tier, Carnival Corporation and Royal Caribbean Group exemplify operators leveraging fleet renewal intensity to anchor LNG bunkering commitments across multiple homeport clusters. Norwegian Cruise Line Holdings occupies a position between mass-market scale and premium positioning through its "Freestyle Cruising" differentiation. MSC Cruises represents the European-based challenger archetype with aggressive capacity expansion in Mediterranean and Caribbean deployment.
| Leading Market Players |
|---|
| Carnival Corporation |
| Royal Caribbean Group |
| Norwegian Cruise Line Holdings |
| MSC Cruises |
| Princess Cruises |
| Celebrity Cruises |
| Disney Cruise Line |
| Viking Cruises |
| Virgin Voyages |
| Others |
Supply Flow & Price Mechanics
Marine engineering talent scarcity in South Korean and German shipyard clusters compresses labor-cost differentials into pricing-tier spreads across newbuild programs, with specialized dual-fuel expertise commanding premiums that propagate through contemporary, luxury, and expedition vessel quotations.
Pricing Analysis
Volume-mass-market contemporary vessels trade at compressed per-berth economics against margin-rich expedition units commanding multiples through ice-class scarcity and limited passenger caps. Three-tier pricing structure across premium, standard, and economy levels segments by space ratios, crew-to-guest ratios, and itinerary exclusivity. Pricing pressure stems from steel and marine equipment cost volatility originating in concentrated Asian supply chains. Family-booking segments demonstrate highest price sensitivity through volume-driven fare negotiations, while ultra-high-net-worth expedition travelers exhibit minimal elasticity.
Supply Chain Analysis
Workforce-availability constraints in Italian, German, and Finnish shipyard geographies tether newbuild delivery schedules to specialized propulsion-system installation capacity. Hull steel, LNG cryogenic fuel systems, and ice-classification certifications draw from concentrated European and Asian supplier bases. Single-source vulnerability permeates dual-fuel engine manufacturing where MAN Energy Solutions and Wärtsilä anchor global output. Distribution runs through direct yard-operator contracting with minimal intermediary channel presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cruise Market functions as a cost-of-compliance story where EU Fit for 55 carbon intensity benchmarks erect durable barrier-to-entry moats favoring operators with younger, LNG-capable fleets and verified shore-power integration.
For Market Incumbents: Deepen LNG infrastructure lock-in through exclusive homeport bunkering commitments in Barcelona, Miami, and Civitavecchia that constrain competitor fuel access. Accelerate demolition timelines for pre-2010 tonnage unable to meet escalating EU Green Deal emission thresholds. Vertical integration into private island destination experiences captures excursion revenue pools and differentiates against emerging entrants lacking comparable port assets. For New Entrants and Emerging Players: The mid-market pricing gap between premium luxury and mass-market contemporary tiers presents white-space opportunity for differentiated positioning. Target underdeveloped India outbound source markets where Mumbai and Chennai homeporting infrastructure lags per-capita income growth curves. Pursue battery-hybrid expedition vessel construction to bypass established players' LNG infrastructure moats while capturing EU port compliance advantages. For Investors and Strategic Acquirers: The window for entry favors operators with confirmed polar expedition permits and ice-class hull construction expertise. Long-term viability centers on fleet age profiles and regulatory compliance horizons rather than scale economies alone. Watch LNG bunkering network maturity in Mediterranean and Caribbean clusters as inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| LNG Propulsion Retrofit Program | Extends compliance horizons against IMO MARPOL Annex VI emission standards tightening through 2030. |
| Expedition Vessel Construction | Captures pricing multiples in Antarctica and Arctic markets where regulatory caps constrain supply expansion. |
| Private Island Infrastructure Investment | Enables vertical integration into destination experiences capturing excursion revenue from Caribbean itineraries. |
| Shore Power Integration Partnership | Secures zero-emission port operations compliance with EU Fit for 55 carbon intensity benchmarks. |
| Multi-Generational Cabin Configuration | Optimizes yield per voyage through connecting stateroom layouts targeting extended-family booking patterns. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while structured interviews with fleet operations directors, shipyard procurement managers, port authority infrastructure planners, and marine classification society surveyors validated demand-side assumptions. CLIA passenger volume statistics, IMO MARPOL compliance databases, Lloyd's Register vessel records, and EU ETS maritime emissions registries supplied quantitative foundations. Bottom-up newbuild order analysis triangulated against top-down fleet capacity deployment tracking.
Granularity-level modeling distinguished vessel type, itinerary region, customer segment, and service tier dimensions across the projection horizon. Contemporary, luxury, expedition, and river categories were modeled separately with distinct propulsion-technology compliance cost structures. CAGRs derived from hull delivery schedules, demolition forecasts, and regulatory phase-in timelines. LNG bunkering infrastructure buildout curves and EU carbon intensity benchmark trajectories informed fleet renewal pace assumptions.
Inputs from port authority infrastructure planners and shipyard order books were available through the study window; gaps in long-term alternative fuel certification timelines from classification societies introduce uncertainty bands around newbuild delivery schedules. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fuel price spread evolution. Material deviation in EU Green Deal implementation pace or LNG infrastructure commitment withdrawals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Fishing Tourism Market