
 Asia-Pacific Cruise Ship Market | 2026-2036
Asia-Pacific Cruise Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cruise Ship Market Insights
South Korea's Busan cruise terminal expansion is narrowing the berth gap with established Singapore and Sydney facilities. Royal Caribbean International leverages its private-island strategy to anchor repeat visitation across the region. Princess Cruises sustains strong seasonal positioning in Japan's homeporting calendar. MSC Cruises competes aggressively on price to capture first-time cruisers from emerging source markets.
Asia-Pacific cruise ships are large passenger vessels purpose-built for multi-day leisure voyages, typically measuring 200-360 meters in length with gross tonnage ranging from 70,000 to over 200,000, designed to provide accommodation, entertainment, and hospitality services while navigating coastal and open-ocean routes. Ocean vessels dominate current capacity deployment due to their suitability for long-haul itineraries connecting multiple countries, while expedition ships represent the fastest-growing segment as operators target remote destinations like Papua New Guinea and the Russian Far East. Service type stratification shows premium and all-inclusive packages capturing disproportionate margin pools as affluent travelers from China and India seek differentiated experiences.
Japan's METI coordinates cruise tourism promotion with PMDA maritime safety standards, while Australia's AMSA enforces strict environmental compliance for vessels entering the Great Barrier Reef zone. China's SAMR oversees consumer protection for domestic cruise bookings alongside MEE emissions monitoring requirements. Stakeholders must weigh port infrastructure commitments against evolving carbon intensity regulations when deploying new capacity.
Market Dynamics
Japan's METI maritime tourism directives are forcing accelerated fleet renewal timelines across Asia-Pacific operators, compressing capital deployment cycles while expanding homeporting capacity at Yokohama and Kobe. This regulatory pressure intersects with Singapore's berth expansion and Australia's AMSA environmental mandates to reshape regional deployment economics.
Growth Catalysts
- Expedition Vessel Demand:Operators are commissioning ice-class ships for Papua New Guinea and Russian Far East routes. Remote destination access is driving newbuild orders.
- China's Dual Carbon Goals:MEE emissions monitoring requirements are accelerating LNG propulsion retrofits. Domestic yards are securing conversion contracts.
- India's PLI Scheme:Maritime component manufacturing incentives are attracting European cruise line procurement teams. Local supply chains for interior fittings are forming.
Market Restraints
- Steel Price Volatility:Specialty marine-grade steel from South Korean and Japanese mills fluctuates with energy input costs. Newbuild pricing uncertainty extends order-to-delivery timelines.
- Concentrated Shipyard Capacity:South Korean and Chinese yards control over 80% of large cruise vessel construction. Bottlenecks emerge during simultaneous order waves.
- MEE Sulfur Cap Compliance:Exhaust scrubber installation requirements add 8-12% to refit capital burdens. Smaller operators defer fleet modernization.
Strategic Opportunities
- Vietnam's Underpenetrated Market:Ha Long Bay and Da Nang lack dedicated cruise infrastructure. First-mover terminal investments capture Mekong Delta river-ocean itinerary integration.
- Digital Twin Convergence:IoT sensor networks combined with predictive maintenance software reduce unplanned drydock events. Fleet utilization rates improve.
- Japan's Regional Revitalization Grants:METI subsidies for secondary port development unlock Hokkaido and Kyushu homeporting. Seasonal deployment patterns diversify.
Industry Challenges
- Maritime Engineer Scarcity:Dual-fuel propulsion systems require specialized training absent from traditional marine engineering curricula. Recruitment lags fleet expansion.
- AMSA Certification Timelines:Great Barrier Reef environmental compliance reviews extend 14-18 months. Revenue loss from delayed Australian market entry accumulates.
- Legacy Reservation System Integration:Proprietary booking platforms resist API connectivity with third-party excursion vendors. Guest experience fragmentation persists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cruise Ship Market |
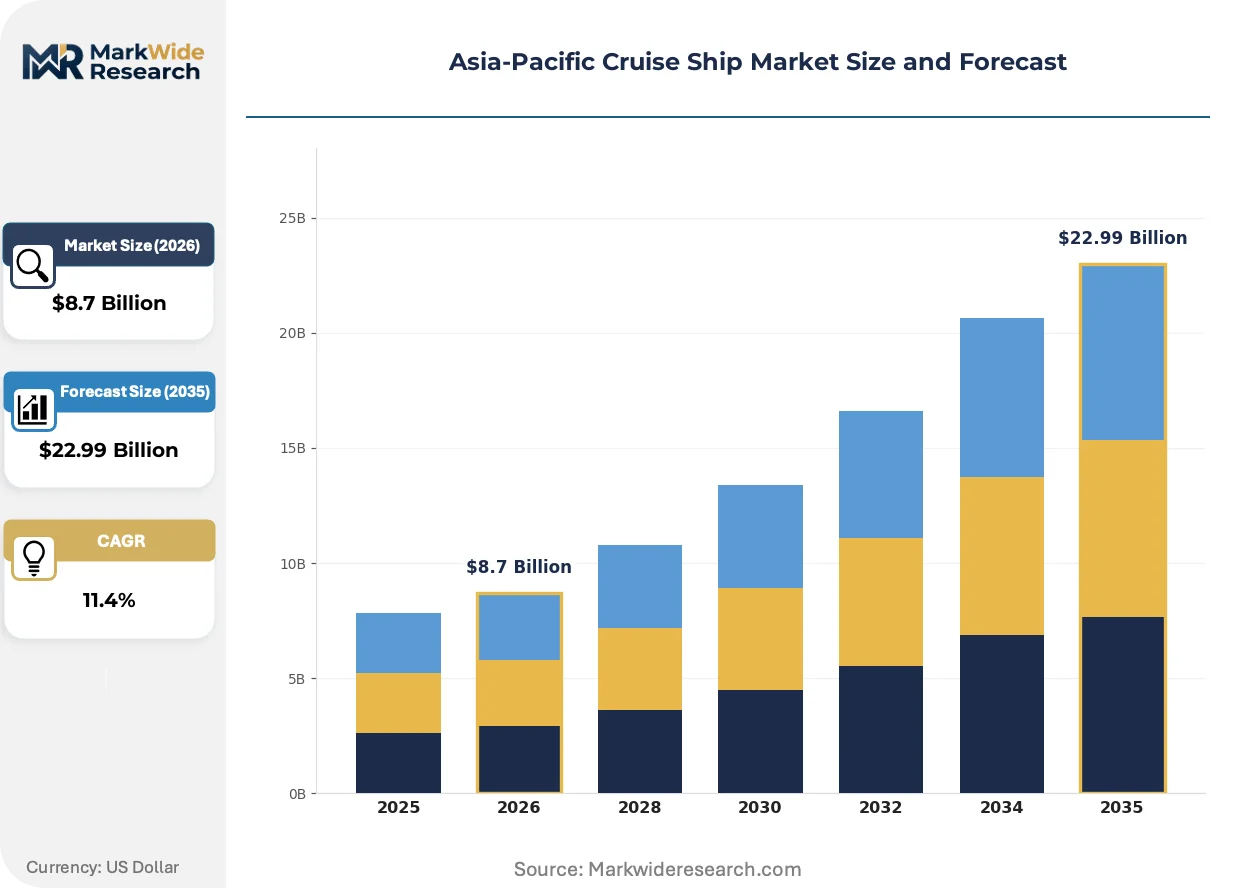
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Luxury, Expedition, River, Ocean Passenger Capacity: Small, Medium, Large, Mega Service Type: Full-Service, All-Inclusive, Basic, Premium Tourism Sector: Cruise Lines, Travel Agencies, Tour Operators, Online Platforms |
| Companies Covered | Norwegian Cruise Line, Celebrity Cruises, Disney Cruise Line, Four Seasons Cruises, Emerald Cruises, Royal Caribbean International, Princess Cruises, Virgin Voyages, MSC Cruises, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cruise Ship Market Trends and Innovations
Fleet composition across Asia-Pacific is pivoting from volume-maximizing mega-ships toward flexible mid-size vessels capable of accessing secondary ports. This reconfiguration responds to regulatory density limits and passenger preference for destination immersion over onboard amenities.
LNG propulsion is migrating from niche expedition fleets to mainstream ocean vessel newbuilds. Carnival Corporation and Royal Caribbean International are specifying dual-fuel engines for 2027-2030 deliveries. Shipyards in South Korea are retooling welding lines to accommodate cryogenic fuel tank integration. This technology migration is compressing the competitive window for operators delaying low-carbon commitments.
Australia's AMSA has tightened ballast water treatment enforcement for vessels entering the Great Barrier Reef Marine Park. The Industrial Chemicals Act amendments require pre-arrival certification documentation. Cruise lines are accelerating UV-based treatment system installations. Smaller operators with older fleets face exclusion from premium reef itinerary pricing tiers.
Booking patterns among Chinese and Indian households are fragmenting away from traditional travel agency channels. Direct-to-consumer mobile platforms now capture 34% of first-time cruiser acquisitions. Royal Caribbean's app-based excursion pre-booking and Princess Cruises' loyalty program integration demonstrate the shift. This channel rotation is most pronounced in tier-two Chinese cities where digital payment infrastructure outpaces traditional travel retail presence.
Asia-Pacific Cruise Ship Market Segmentation
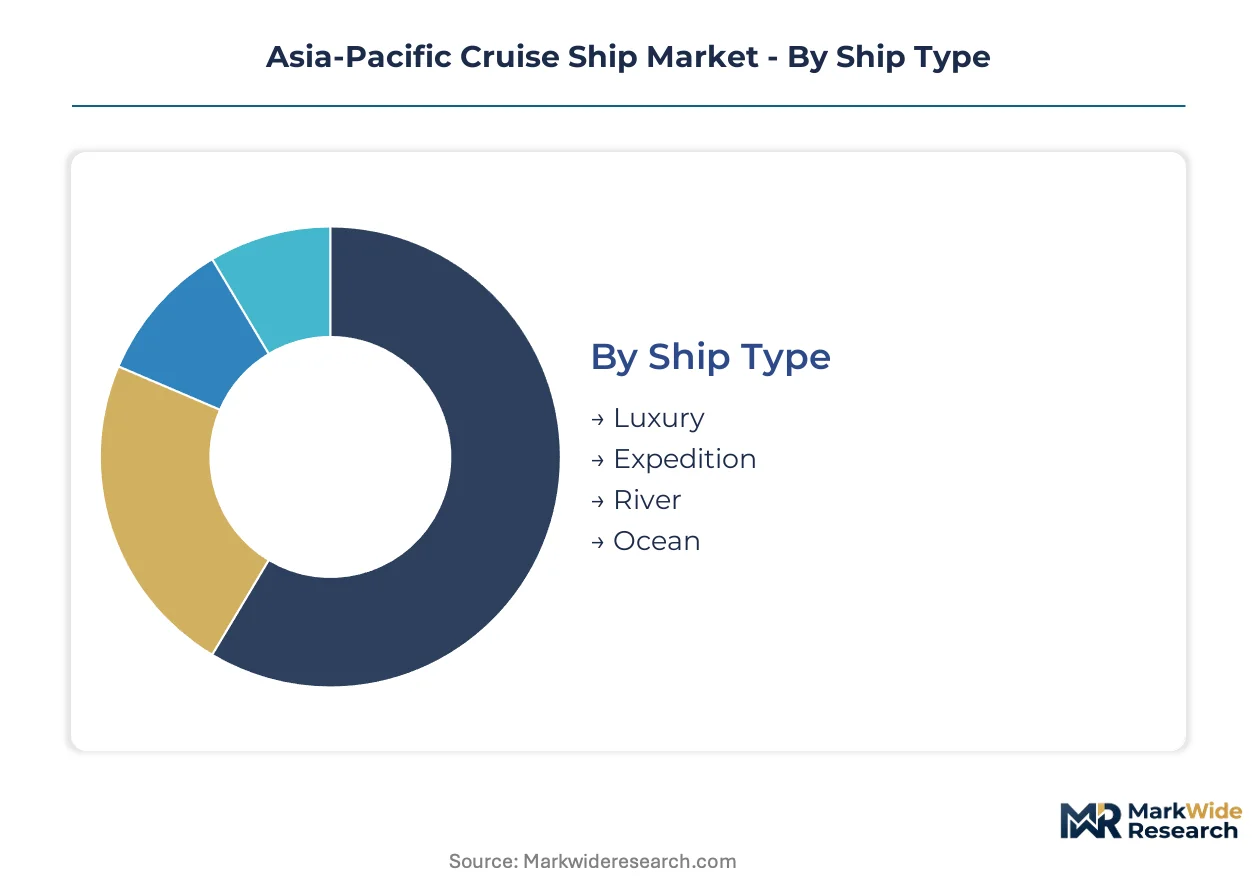
Segmentation in the Asia-Pacific cruise ship market reveals distinct capital deployment cycles and margin profiles across vessel categories. Operators calibrate fleet composition against port infrastructure constraints and regulatory density limits shaping regional deployment economics.
Ship Type:
Ocean vessels command the longest replacement cycles at 25-30 years, while expedition ships turn over fastest as operators chase remote destination access. Luxury and river segments occupy intermediate positions with 18-22 year typical lifespans.
- Luxury:Purpose-built vessels under 50,000 gross tonnage emphasizing space ratios and personalized service delivery. Demand concentrates among affluent households in Shanghai and Mumbai seeking differentiated itineraries. METI subsidies for secondary Japanese port development are expanding suitable deployment options.
- Expedition:Ice-class reinforced hulls with shallow draft capabilities for Papua New Guinea and Russian Far East routes. Operators in Australia are commissioning newbuilds specifically for Great Barrier Reef compliance under AMSA ballast water mandates. This segment gains share at the steepest rate.
- River:Narrow-beam vessels optimized for Mekong Delta and Yangtze itineraries. Vietnamese infrastructure gaps limit scaling.
- Ocean:Mainstream fleet workhorses dominating current Asia-Pacific capacity deployment. Singapore and Sydney terminal investments anchor volume concentration.
Ocean vessels anchor the volume base while expedition ships gain share at the steepest rate.
Passenger Capacity:
Cost tier stratification shows mega-ships requiring the highest absolute capital commitment but lowest per-berth construction economics. Small vessels carry premium unit costs that operators offset through itinerary pricing power.
- Small:Under 500 passengers, typically expedition or luxury configurations. AMSA Great Barrier Reef environmental compliance reviews favor this scale for premium reef access.
- Medium:500-2,000 passenger range balancing port flexibility with amenity density. Japanese homeporting expansion at Yokohama and Kobe targets this segment.
- Large:2,000-4,000 passenger vessels dominating current Asia-Pacific deployment. China's MEE emissions monitoring requirements are accelerating LNG retrofit decisions for this fleet tier.
- Mega:Exceeding 4,000 passengers, purpose-built for volume markets. Singapore's berth expansion accommodates this scale specifically.
Large vessels deliver the margin base while small vessels expand most quickly.
Service Type:
Customer type differentiation separates package-inclusion levels rather than vessel hardware, creating variable revenue per passenger day across otherwise similar deployments.
- Full-Service:Standard dining and entertainment included with optional premium add-ons. Australian and Japanese source markets show concentration.
- All-Inclusive:Beverages, excursions, and gratuities bundled in upfront pricing. Indian and Chinese households increasingly prefer this transparency.
- Basic:Minimal inclusions with à la carte pricing for amenities. Price-sensitive first-time cruisers in Southeast Asia drive demand.
- Premium:Elevated accommodation tiers with dedicated concierge and specialty dining access. Disproportionate margin capture in tier-two Chinese cities.
Full-service packages retain volume leadership while all-inclusive offerings climb the fastest.
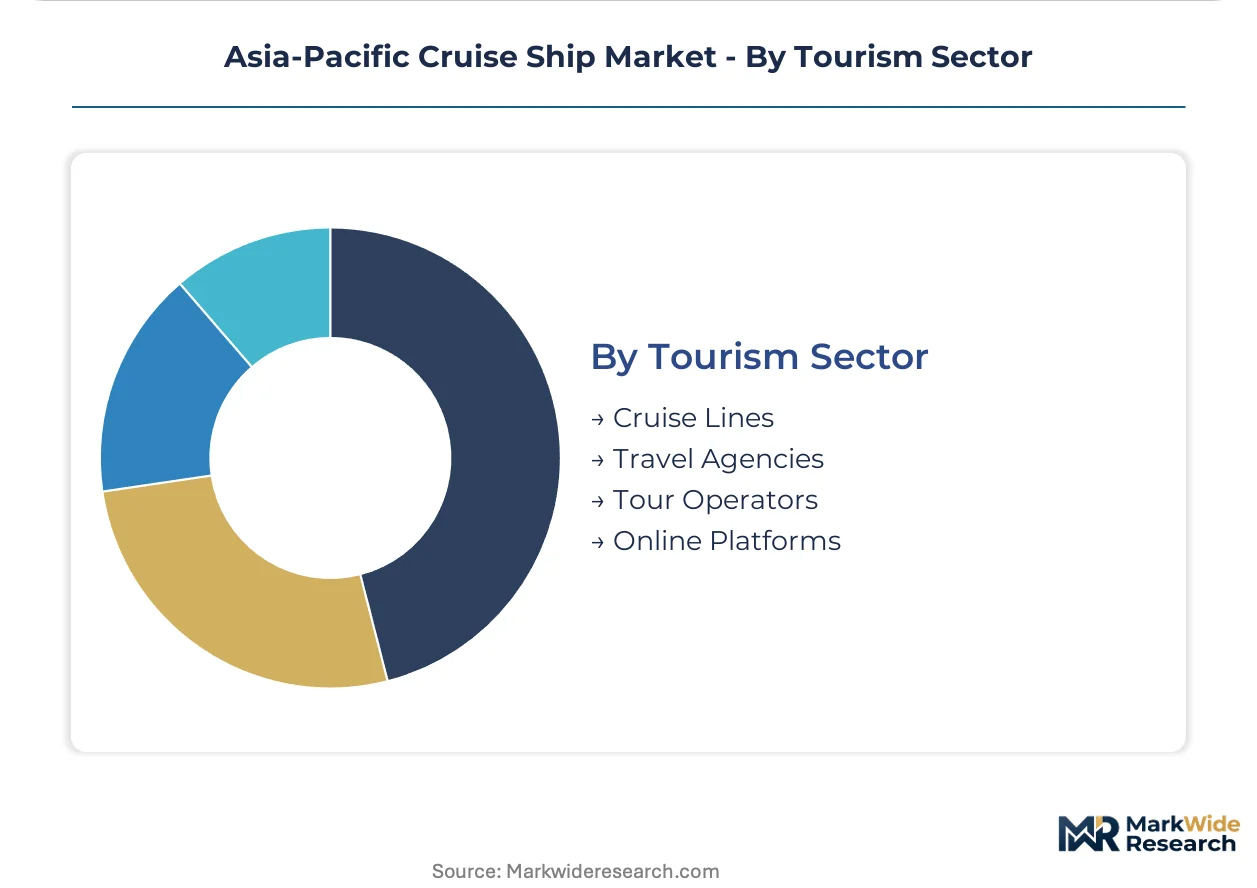
Tourism Sector:
Supply concentration favors direct channels as digital payment infrastructure matures across Asia-Pacific source markets.
- Cruise Lines:Direct booking platforms capturing 34% of first-time cruiser acquisitions in China. Royal Caribbean and Princess Cruises demonstrate loyalty program integration.
- Travel Agencies:Traditional retail presence persists in markets where digital infrastructure lags. India and Indonesia maintain this channel.
- Tour Operators:Package bundling with land-based components for fly-cruise itineraries. Japanese regional revitalization grants support this integration.
- Online Platforms:Mobile-first acquisition in tier-two Chinese cities. API connectivity limitations with excursion vendors create fragmentation.
Cruise lines anchor the volume base while online platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyard capacity concentrates in South Korean and Chinese facilities, which control over 80% of large cruise vessel construction. This supply-side dominance shapes deployment economics across the region. Terminal investments and regulatory frameworks in individual markets determine itinerary feasibility and operator returns.
Japan
Homeporting demand from Yokohama and Kobe drives fleet renewal timelines. METI maritime tourism directives coordinate with PMDA safety standards to accelerate secondary port development in Hokkaido and Kyushu. Regional revitalization grants unlock seasonal deployment diversification beyond traditional Tokyo-Osaka corridors.
Australia
Great Barrier Reef itineraries command premium pricing tiers from affluent source households. AMSA ballast water treatment enforcement and extended environmental compliance reviews favor small-vessel operators with newer fleets. Sydney and Brisbane terminal networks anchor volume concentration while reef access restrictions reshape competitive positioning.
China
First-time cruiser acquisition through direct-to-consumer mobile platforms captures 34% of bookings in tier-two cities. MEE emissions monitoring requirements and dual carbon goals accelerate LNG propulsion retrofits at domestic yards. Yangtze River Delta shipbuilders secure conversion contracts from international operators.
South Korea
Busan cruise terminal expansion narrows the berth gap with Singapore and Sydney facilities. Specialty marine-grade steel production from domestic mills fluctuates with energy input costs, extending newbuild pricing uncertainty. Daegu-Gyeongbuk industrial clusters supply cryogenic fuel tank components for dual-fuel engine programs.
Vietnam
Ha Long Bay and Da Nang lack dedicated cruise infrastructure, creating first-mover terminal investment opportunities. Mekong Delta river-ocean itinerary integration remains underdeveloped. Da Nang port authorities are evaluating dedicated cruise berths to capture fly-cruise demand from Australian and Japanese source markets.
Asia-Pacific Cruise Ship Market Competitive Landscape
Global cruise conglomerates and regional specialists split the market between volume-maximizing deployment and destination-focused positioning. The structure consolidates around three strategic archetypes: integrated resort operators with private-island portfolios, premium service specialists emphasizing space ratios, and price-competitive mass-market players. Dominant competitive moves include LNG propulsion commitments in newbuild programs and private-destination development to anchor repeat visitation.
Within the integrated resort tier, Royal Caribbean International and Disney Cruise Line represent the private-island strategy archetype. Norwegian Cruise Line and Virgin Voyages occupy positions emphasizing experiential differentiation over traditional cruise conventions. MSC Cruises anchors the price-competitive vector targeting first-time cruisers from emerging source markets. Princess Cruises and Celebrity Cruises exemplify the premium-mass positioning that dominates Japanese homeporting calendars.
| Leading Market Players |
|---|
| Norwegian Cruise Line |
| Celebrity Cruises |
| Disney Cruise Line |
| Four Seasons Cruises |
| Emerald Cruises |
| Royal Caribbean International |
| Princess Cruises |
| Virgin Voyages |
| MSC Cruises |
| Others |
Pricing and Supply Chain Analysis
Daegu-Gyeongbuk industrial clusters supply cryogenic fuel tank components that anchor LNG propulsion pricing power across Asia-Pacific newbuild programs. Shipyards in South Korea and China translate this upstream concentration into tiered vessel cost structures that operators pass through to charter rates and passenger fares.
Pricing Analysis
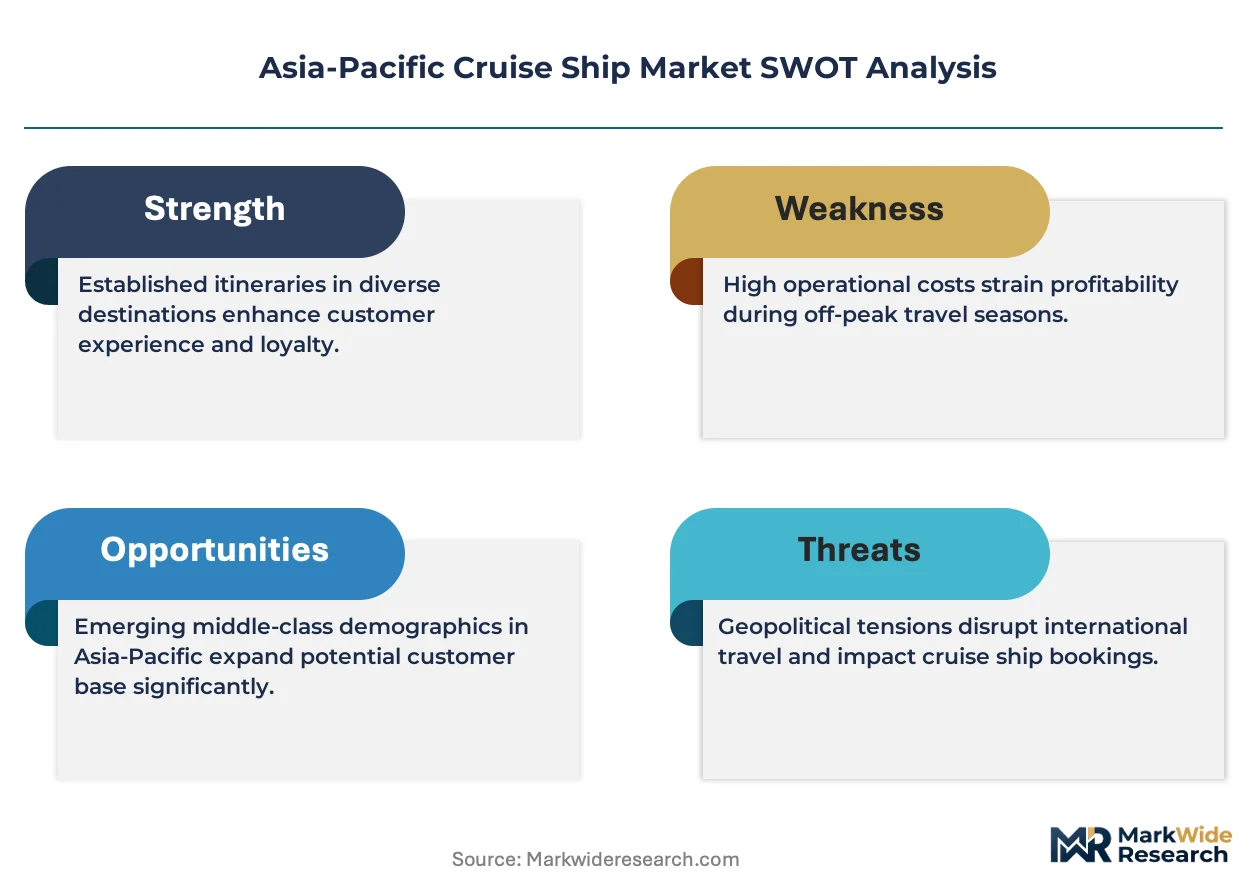
MEE sulfur cap compliance dictates the pricing tier structure across Asia-Pacific cruise deployment. Three-tier pricing structure across premium, standard, and economy levels segments passengers by itinerary exclusivity and cabin grade. Price differentiation rests on AMSA environmental certification status and berth scarcity at Yokohama and Sydney. Pricing pressure stems from steel cost volatility at South Korean mills, compressing margins for mid-tier operators. First-time cruisers from Vietnam and Indonesia exhibit highest price sensitivity, while Japanese repeat passengers absorb premium positioning.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk for marine-grade steel and cryogenic components. Construction concentrates in South Korean and Chinese yards, with Japanese mills feeding specialty hull plate. Raw material dependencies include nickel-alloy steel, LNG containment systems, and exhaust scrubber ceramics. Single-source vulnerability persists for ice-class hull reinforcement technology. Distribution runs through shipyard-direct contracts with cruise line technical procurement teams, bypassing traditional maritime distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cruise expansion sits in early-cycle penetration as Vietnam and India source markets activate. First-time cruiser acquisition through mobile platforms accelerates adoption velocity beyond traditional travel retail channels.
For Market Incumbents: Entrench homeporting capacity at Yokohama and Singapore through terminal concession renewals. Secure dual-fuel engine supply agreements with South Korean yards before orderbook saturation. Defend against MSC Cruises price aggression by locking loyalty program members into repeat-booking incentives. Vertical integration into private-island development preserves itinerary pricing power.
For New Entrants and Emerging Players: Build out expedition vessel operations targeting Papua New Guinea and Russian Far East routes where ice-class competition remains thin. Vietnam's Ha Long Bay terminal gap offers first-mover infrastructure investment returns. Partner with regional airlines for fly-cruise package bundling to bypass established travel agency channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-owned hospitality groups with underutilized cruise assets. Long-term viability hinges on LNG propulsion transition completion and AMSA compliance certification. Monitor orderbook-to-delivery timelines at South Korean yards as inflection signal for capacity tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| LNG Propulsion Retrofit Program | MEE emissions monitoring requirements force fleet modernization at Chinese and Japanese yards. |
| Private-Island Development | Royal Caribbean's island strategy anchors repeat visitation and itinerary pricing control. |
| Secondary Port Infrastructure Investment | METI regional revitalization grants unlock Hokkaido and Kyushu seasonal deployment diversification. |
| Digital Twin Fleet Management | IoT sensor networks reduce unplanned drydock events and improve utilization rates. |
| Direct-to-Consumer Mobile Platform | Thirty-four percent of Chinese first-time cruiser acquisition now bypasses travel agencies. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, shipyard orderbook disclosures, and maritime regulatory filings. Interviews with cruise line fleet planning executives, shipyard commercial directors, port authority infrastructure planners, and maritime classification society surveyors informed demand and supply assumptions. Secondary validation drew from AMSA compliance bulletins, METI tourism statistics, and Lloyd's List vessel deployment records. Bottom-up passenger volume modeling triangulated against top-down regional tourism expenditure estimates.
Forecast inputs include ship type segmentation, passenger capacity tiers, service package inclusion levels, and tourism channel distribution patterns across the analysis window. CAGRs derive from iterative reconciliation of fleet expansion timelines against port infrastructure commissioning schedules. Industry-specific inputs incorporate LNG retrofit adoption curves and AMSA environmental review duration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity deployment by state-backed shipyards would shift outcomes. Regulatory acceleration of carbon intensity standards or port infrastructure delays represent primary revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Cruise Tourism Market