
 Asia-Pacific Cruise Tourism Market | 2026-2036
Asia-Pacific Cruise Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cruise Tourism Market Insights
Onboard experience packages is shifting from add-on amenities to core revenue architecture across Asia-Pacific itineraries. Royal Caribbean International leverages its private island destinations to sustain premium pricing power in Southeast Asian waters. Norwegian Cruise Line anchors its competitive stance through flexible dining and entertainment modules tailored to multi-generational Asian travelers. Princess Cruises dominates seasonal deployment patterns with dedicated Australia-based vessels operating year-round South Pacific circuits.
Asia-Pacific cruise tourism encompasses maritime leisure voyages operating from ports across East Asia, Southeast Asia, and Oceania, typically employing vessels between 2,000 and 5,000 passenger capacities with integrated hospitality, entertainment, and shore-excursion logistics. The primary commercial purpose centers on extracting multi-day consumer expenditure through bundled accommodation, dining, and destination experiences while optimizing vessel utilization across repositioning routes. Luxury cruises command disproportionate margin pools due to higher per-passenger spending and lower crew-to-guest ratios, while family cruises drive volume concentration during school holiday periods across Australian and North Asian source markets. Adventure cruises represent the fastest-expanding category, capitalizing on expedition-ready vessels accessing remote Papua New Guinea and Indonesian archipelago destinations.
Singapore's Maritime and Port Authority coordinates regional cruise terminal standards alongside Australia's biosecurity protocols administered by the Department of Agriculture, Fisheries and Forestry, both frameworks directly shaping itinerary feasibility and passenger processing capacity. Japan's transport ministry oversees port readiness certifications that determine which vessels qualify for homeporting status at Yokohama and Kobe. Stakeholders must monitor evolving environmental compliance timelines for liquefied natural gas propulsion mandates affecting fleet deployment economics across regional waters.
Market Dynamics
Japan's streamlined visa protocols for cruise passengers and Singapore's terminal capacity expansions are compressing embarkation friction across Southeast Asian itineraries, accelerating regional deployment schedules.
Growth Catalysts
- Port Infrastructure Modernization:Singapore's Maritime and Port Authority terminal upgrades and Japan's transport ministry port readiness certifications are expanding homeporting capacity at Yokohama, Kobe, and Singapore.
- Visa Liberalization Frameworks:Japan's multi-entry cruise passenger visa waivers and Australia's streamlined electronic travel authority processing are reducing booking friction for Chinese and Indian source markets.
- Liquefied Natural Gas Propulsion Mandates:Environmental compliance timelines for LNG-ready fleet deployment are rewriting vessel economics and attracting sustainability-focused affluent travelers across Australian and Southeast Asian routes.
Market Restraints
- Bunker Fuel Price Volatility:Marine gasoil and low-sulfur fuel oil cost fluctuations compress operating margins on repositioning routes between seasonal deployment zones.
- Biosecurity Protocol Stringency:Australia's Department of Agriculture, Fisheries and Forestry inspection regimes create itinerary uncertainty and passenger processing delays at Sydney and Brisbane terminals.
- Expedition Vessel Supply Concentration:Limited shipyard capacity for ice-class and shallow-draft hull construction concentrates adventure cruise supply among Scandinavian and Italian builders.
Strategic Opportunities
- Papua New Guinea Archipelago Access:Underdeveloped shore excursion infrastructure and uncharted diving sites offer first-mover positioning for expedition operators deploying zodiac-equipped vessels.
- Intergenerational Itinerary Design:Flexible dining modules and multi-cabin family suite configurations address unmet demand from multi-generational Indian and Chinese traveler segments.
- Private Island Destination Control:Exclusive lease arrangements for uninhabited Indonesian and Philippine island clusters enable premium pricing power through controlled guest experiences.
Industry Challenges
- Specialized Expedition Crew Scarcity:Certified naturalist guides and ice navigation officers command premium wages, constraining fleet expansion timelines for polar and remote archipelago routes.
- Terminal Slot Coordination Complexity:Synchronized berth scheduling across Singapore, Sydney, and Shanghai requires multi-year advance commitments that limit operational flexibility during demand shocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cruise Tourism Market |
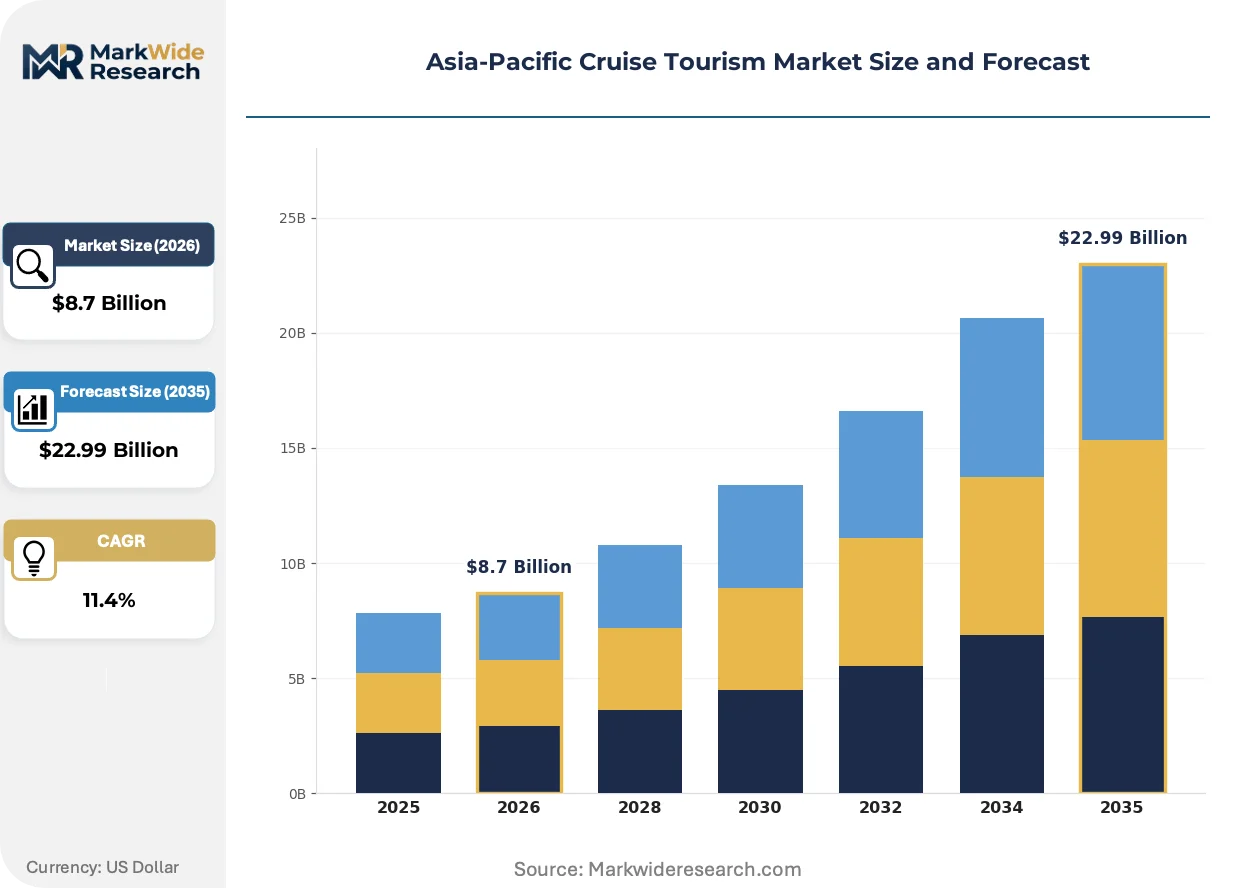
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Cruises, Adventure Cruises, Family Cruises, Eco-Tourism Cruises Customer Type: Solo Travelers, Couples, Families, Corporate Groups Destination: Caribbean, Mediterranean, Southeast Asia, South Pacific Duration: Short Cruises, Week-Long Cruises, Extended Cruises, Day Cruises |
| Companies Covered | Princess Cruises, Cunard Line, Celebrity Cruises, Seabourn Cruise Line, Royal Caribbean International, Norwegian Cruise Line, Holland America Line, Oceania Cruises, Regent Seven Seas Cruises, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cruise Tourism Market Trends and Innovations
Digital embarkation systems and AI-driven itinerary personalization are compressing passenger processing times while expanding shore excursion customization across Asia-Pacific source markets.
Liquefied natural gas propulsion systems are rewriting fuel economics and emissions profiles for newbuild vessels operating Australian coastal and Southeast Asian island-hopping routes. Japanese and Australian operators are retrofitting existing fleets with dual-fuel capabilities to meet port authority environmental compliance deadlines. This technology is compressing the operational cost gap between conventional marine diesel and alternative fuel architectures.
Singapore's Maritime and Port Authority coordinated terminal standards and Japan's transport ministry environmental certification requirements are mandating shore power connectivity and wastewater treatment upgrades. These frameworks increase capital expenditure burdens for smaller operators while creating competitive moats for fleet-scale players with dedicated sustainability compliance teams. Australian and Japanese homeporting routes face the most stringent implementation timelines.
Chinese and Indian travelers are unbundling traditional package components, selecting à la carte dining, spa, and excursion modules through mobile booking platforms rather than pre-cruise bundled purchases. This pattern compresses operator revenue predictability while expanding direct-to-consumer ancillary sales channels. Southeast Asian itineraries departing Singapore exhibit the most pronounced shift toward modular consumption patterns.
Asia-Pacific Cruise Tourism Market Segmentation
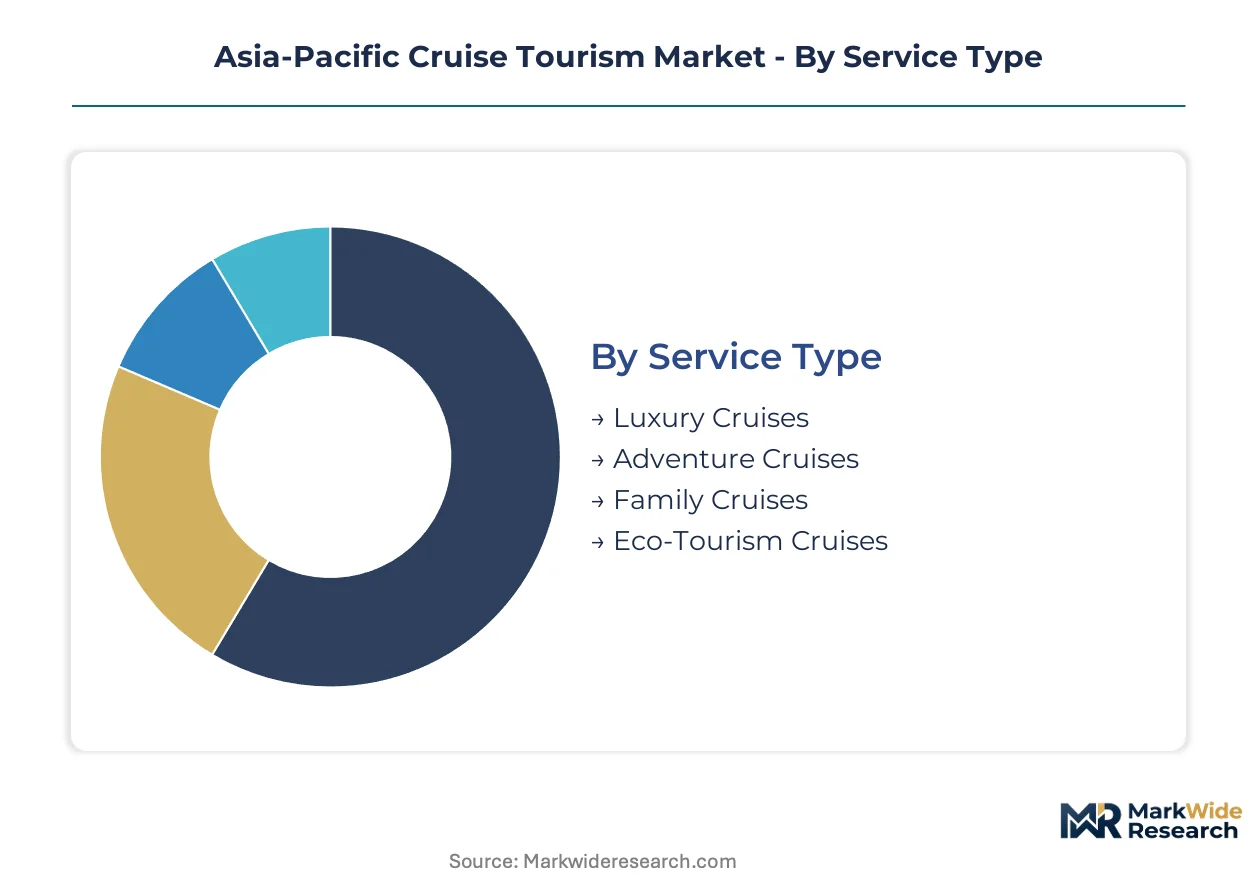
Asia-Pacific cruise operators architect revenue streams through precise segment targeting, matching vessel configurations and itinerary designs to distinct passenger expenditure profiles. Each segmentation dimension carries specific certification burdens and port authority compliance requirements that shape deployment economics.
Service Type:
Japan's transport ministry port readiness certifications and Singapore's Maritime and Port Authority terminal standards impose differentiated compliance loads across service tiers, with luxury and expedition vessels facing the most stringent environmental and safety mandates.
- Luxury Cruises:These vessels emphasize spacious suite configurations, elevated crew-to-guest ratios, and exclusive shore excursion access. Demand concentrates among affluent travelers departing Singapore and Sydney, where Australia's biosecurity protocols administered by the Department of Agriculture, Fisheries and Forestry add processing complexity for high-value itineraries.
- Adventure Cruises:Expedition-ready hulls with ice-class ratings and zodiac deployment capabilities characterize this segment. Papua New Guinea and Indonesian archipelago routes attract experienced travelers seeking uncharted diving sites, though limited shipyard capacity for specialized construction constrains fleet expansion.
- Family Cruises:Multi-generational cabin configurations and flexible dining modules dominate vessel design. School holiday periods across Australian and North Asian source markets drive volume concentration.
- Eco-Tourism Cruises:LNG-ready propulsion systems and shore power connectivity define operational specifications. Sustainability-focused affluent travelers across Australian coastal routes respond to environmental compliance positioning.
Leading the category by volume: Family Cruises. Growing fastest: Adventure Cruises.
Customer Type:
Booking platform preferences and modular purchasing behaviors vary sharply across customer types, with Chinese and Indian travelers increasingly unbundling traditional packages through mobile channels.
- Solo Travelers:Single-occupancy cabin demand and structured social programming characterize this segment. Southeast Asian itineraries departing Singapore exhibit pronounced solo booking growth through direct digital channels.
- Couples:Premium dining and spa module selection dominates expenditure patterns. Australia's electronic travel authority streamlined processing supports couple bookings from Indian source markets.
- Families:Multi-cabin suite configurations and intergenerational itinerary design address unmet demand. Japanese port infrastructure investments at Yokohama and Kobe accommodate family embarkation volume.
- Corporate Groups:Dedicated meeting facilities and team-building shore excursions drive charter demand. Singapore's terminal capacity expansions support corporate event logistics.
Volume concentration: Families. Steepest expansion trajectory: Solo Travelers.
Destination:
Biosecurity stringency and visa liberalization frameworks create divergent accessibility profiles across destination clusters, directly shaping operator deployment decisions.
- Southeast Asia:Singapore anchors regional embarkation with streamlined terminal standards. Japan's multi-entry cruise passenger visa waivers reduce booking friction for Chinese source markets.
- South Pacific:Dedicated Australia-based vessels operate year-round circuits. Princess Cruises dominates seasonal deployment patterns through homeporting infrastructure.
- Caribbean:Repositioning routes connect Asia-Pacific vessels to seasonal deployment zones. Bunker fuel price volatility compresses operating margins on these long-haul itineraries.
- Mediterranean:Cross-regional itineraries require multi-jurisdictional compliance coordination. Terminal slot coordination complexity limits operational flexibility for extended deployments.
Primary revenue concentration: Southeast Asia. Gaining share fastest: South Pacific.
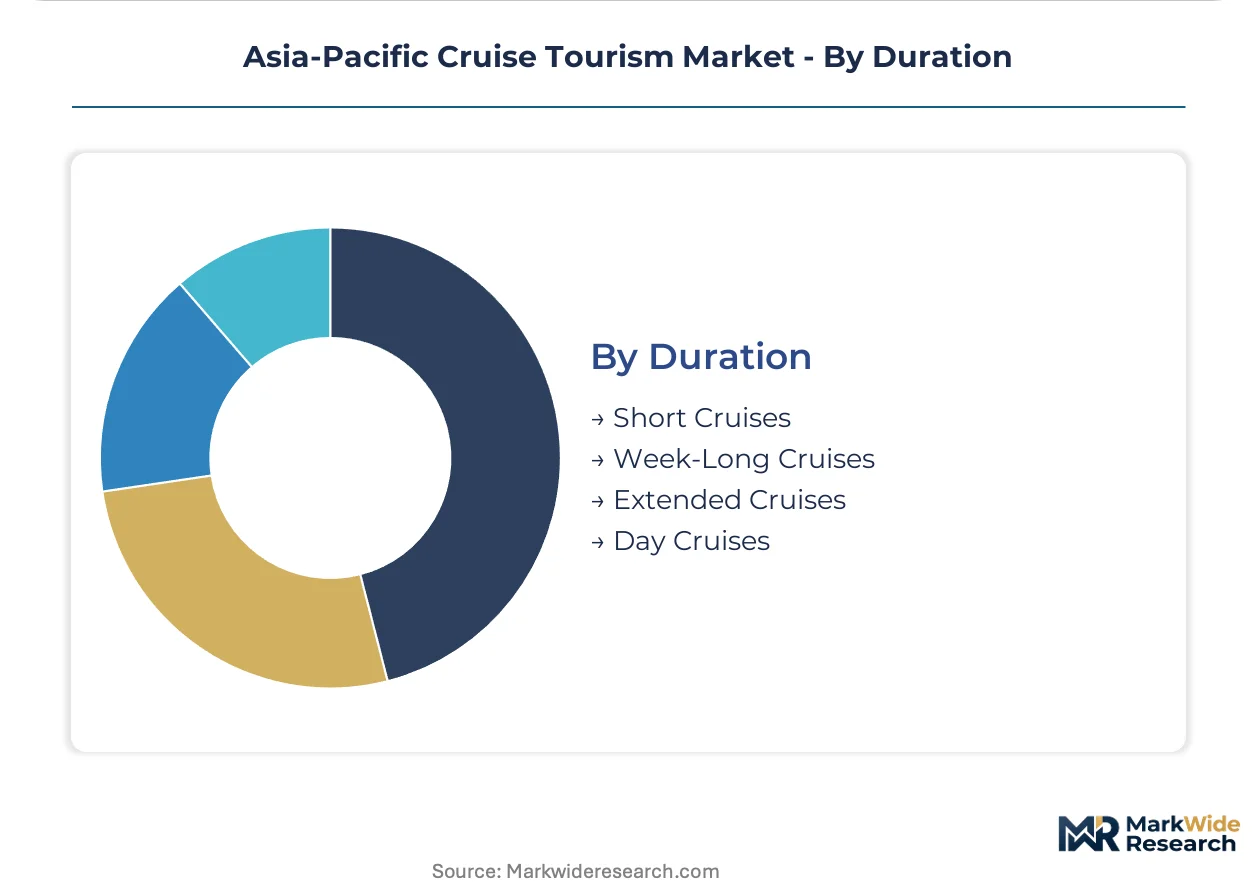
Duration:
Vessel utilization optimization and passenger processing capacity constraints create distinct economic profiles across duration tiers, with short cruises maximizing terminal throughput.
- Short Cruises:Two-to-four-night itineraries maximize berth turnover at Singapore and Sydney. Digital embarkation systems compress passenger processing times for high-frequency departures.
- Week-Long Cruises:Standard seven-night deployments balance revenue per passenger against vessel utilization. School holiday periods across Australian markets drive peak demand.
- Extended Cruises:Multi-week itineraries accessing remote Papua New Guinea and Indonesian archipelago destinations command premium pricing. Specialized expedition crew scarcity constrains fleet expansion.
- Day Cruises:Coastal circuits from Japanese and Australian ports serve domestic tourism demand. Shore power connectivity mandates affect port economics for frequent short calls.
Dominant volume tier: Week-Long Cruises. Climbing the fastest: Extended Cruises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and Australia concentrate cruise infrastructure investment, while Singapore and China drive passenger volume. Regional capacity expansion outpaces source market maturation in several corridors.
Japan
Japan's transport ministry port readiness certifications unlock homeporting capacity at Yokohama and Kobe. Streamlined multi-entry visa waivers for cruise passengers reduce booking friction from Chinese source markets. Tokyo Bay terminals handle premium vessel deployments with dedicated shore power connectivity.
Australia
Australia's Department of Agriculture, Fisheries and Forestry biosecurity protocols shape itinerary feasibility for Sydney and Brisbane terminals. School holiday periods concentrate family cruise demand across New South Wales and Victoria. Princess Cruises anchors year-round South Pacific circuits through dedicated Australia-based vessels.
Singapore
Singapore's Maritime and Port Authority coordinates regional terminal standards and berth capacity expansions. The city-state processes embarkation volume from Chinese and Indian source markets with streamlined electronic systems. Marina Bay Cruise Centre Singapore handles multi-vessel simultaneous turnaround operations.
China
Shanghai anchors mainland China's cruise embarkation infrastructure with dedicated terminal facilities at Wusongkou. China's coastal tourism development policies support domestic cruise circuit expansion. The Yangtze River Delta cluster concentrates passenger processing capacity for regional itineraries.
South Korea
Busan port authorities coordinate terminal slot allocation for Northeast Asian repositioning routes. South Korea's coastal tourism promotion programs support short cruise circuit development. The Busan-Ulsan maritime cluster handles vessel provisioning and maintenance calls.
Asia-Pacific Cruise Tourism Market Competitive Landscape
Top-tier vendors anchor premium and expedition segments, while mid-scale operators concentrate volume-driven family itineraries. The competitive structure stratifies across three archetypes: global fleet-scale players with multi-brand portfolios, regional specialists deploying seasonally adapted vessels, and expedition-focused operators with ice-class capabilities. Dominant competitive moves include private island destination control and LNG-ready fleet retrofit programs.
Among North American-based fleet operators, Royal Caribbean International, Norwegian Cruise Line, and Princess Cruises occupy positions across distinct competitive vectors. Royal Caribbean International exemplifies the private island destination strategy through controlled guest experiences in Southeast Asian waters. Norwegian Cruise Line represents flexible dining and entertainment modularization tailored to multi-generational Asian travelers. Princess Cruises anchors seasonal deployment dominance through Australia-based year-round operations.
| Leading Market Players |
|---|
| Princess Cruises |
| Cunard Line |
| Celebrity Cruises |
| Seabourn Cruise Line |
| Royal Caribbean International |
| Norwegian Cruise Line |
| Holland America Line |
| Oceania Cruises |
| Regent Seven Seas Cruises |
| Others |
Pricing and Supply Chain Analysis
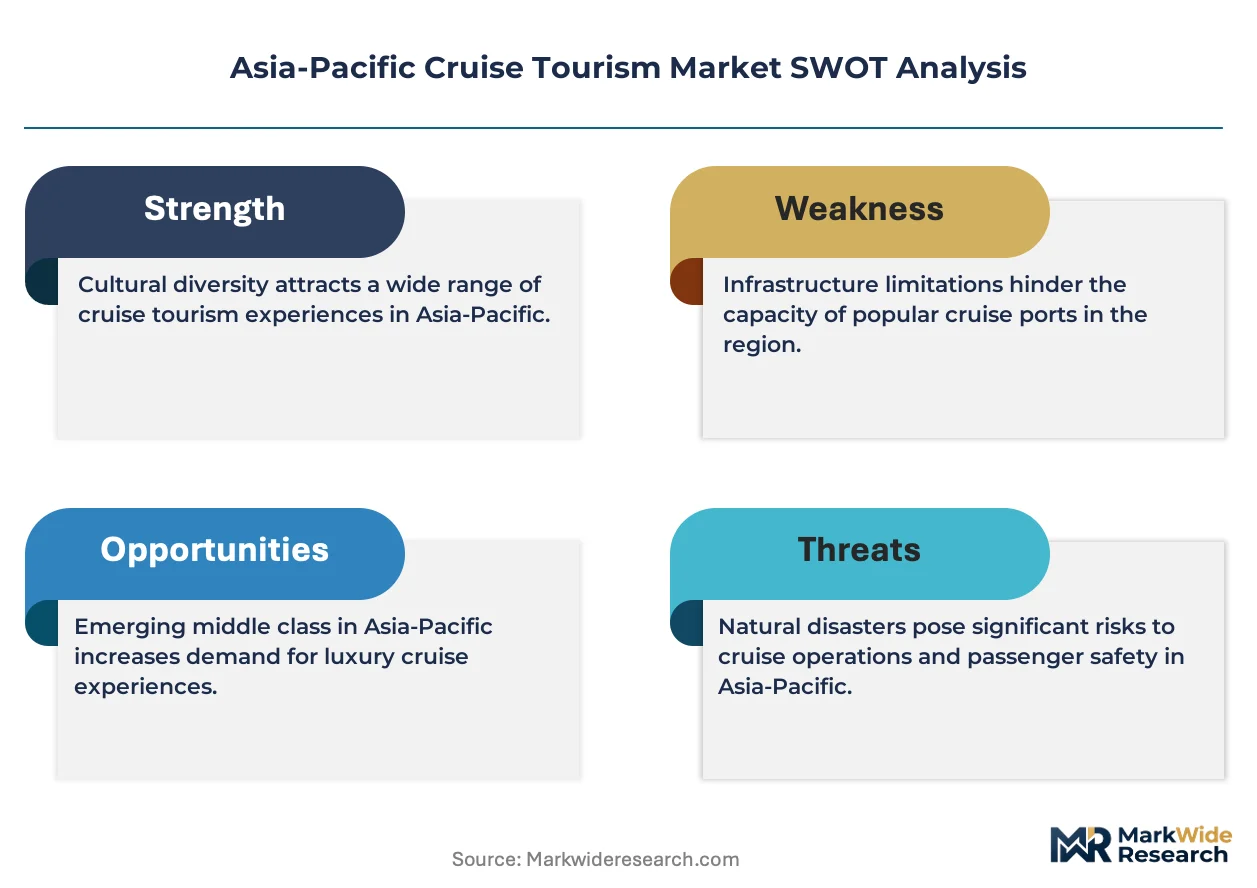
Marine gasoil and low-sulfur fuel oil price indices cascade through Asia-Pacific cruise economics, compressing operating margins on repositioning routes and forcing three-tier pricing stratification across premium, standard, and economy cabin tiers. Bunker fuel volatility feeds directly into itinerary pricing, with Singapore's Maritime and Port Authority environmental surcharges and Japan's LNG-ready port fees layering additional cost architecture onto fare structures.
Pricing Analysis
Margin tightening in economy-class cabins reflects bunker fuel volatility and biosecurity processing surcharges at Australian terminals. Three-tier pricing structure across premium, standard, and economy levels separates all-inclusive luxury packages from modular à la carte offerings, with certification grade for shore power compliance and volume scale for charter bookings driving differentiation. Pricing pressure stems from repositioning route economics between seasonal deployment zones. Chinese and Indian source markets exhibit highest price sensitivity through mobile platform comparison, while Australian family segments show lowest sensitivity during school holiday peaks.
Supply Chain Analysis
Vessel refurbishment cycles and engine retrofit flows concentrate at shipyards in Italy, Germany, and Finland, creating reverse-logistics chokepoints for LNG-ready fleet transitions. Newbuild hull construction draws from South Korean and Japanese yards, while specialty zodiac equipment and expedition gear sources from Norway and France. Single-source vulnerability concentrates in ice-class hull plating from Scandinavian mills. Distribution runs through Singapore's Maritime and Port Authority-coordinated terminal networks, with provisioning chains anchored in Australian and Japanese homeporting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cruise capacity expansion trails demand acceleration, with expedition vessel shipyard bottlenecks and certified naturalist crew scarcity propping premium pricing power across Papua New Guinea and Indonesian archipelago routes.
For Market Incumbents: Acquire expedition-ready vessel slots at Italian and Scandinavian shipyards before competitor commitments lock capacity through 2030. Secure exclusive lease arrangements for uninhabited Indonesian island clusters to defend margin position against Norwegian Cruise Line's flexible dining modularization and Royal Caribbean International's private island control. Invest in dual-fuel retrofit capabilities at Singapore and Yokohama maintenance facilities to meet Japan's transport ministry environmental deadlines. For New Entrants and Emerging Players: Enter via intergenerational itinerary design for Indian and Chinese family segments, where multi-cabin suite demand outstrips Princess Cruises' Australia-based vessel allocation. Target Papua New Guinea archipelago routes with zodiac-equipped shallow-draft hulls, exploiting underdeveloped shore excursion infrastructure and uncharted diving site access. Pursue direct-to-consumer mobile booking platform partnerships with Chinese fintech channels to bypass incumbent travel agency networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale expedition operators with ice-class certifications and established naturalist crew pipelines in Australian and Southeast Asian waters. Long-term viability centers on LNG-ready fleet positioning and private island destination control through 5-10 year lease structures. Watch Japan's transport ministry port readiness certification timelines as inflection indicator for homeporting capacity expansion at Yokohama and Kobe.| Strategic Initiative | Industry Significance |
|---|---|
| Expedition Vessel Acquisition | Ice-class hull construction at Italian shipyards secures Papua New Guinea route access before competitor fleet deployment. |
| LNG Retrofit Program | Dual-fuel engine upgrades at Singapore yards meet Japan's transport ministry environmental compliance deadlines. |
| Private Island Lease Arrangement | Exclusive Indonesian archipelago access enables premium pricing through controlled guest experience architecture. |
| Naturalist Crew Pipeline Development | Certified guide training partnerships with Australian marine institutes address specialized expedition crew scarcity. |
| Digital Embarkation Platform Deployment | AI-driven passenger processing at Marina Bay Cruise Centre Singapore compresses turnaround times for high-frequency departures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with Cruise Lines International Association passenger statistics, Japan's transport ministry port readiness certifications, and Australia's Department of Agriculture biosecurity processing reports forming the backbone. Primary interviews with cruise line fleet deployment directors, terminal operations managers at Singapore's Maritime and Port Authority, shore excursion procurement leads, and LNG retrofit engineering consultants validated expenditure pattern assumptions. Bottom-up passenger volume modeling and top-down revenue triangulation across Singapore, Sydney, and Shanghai embarkation clusters reconciled segmentation splits.
Data-stream reconciliation matched vessel deployment schedules against berth capacity expansions at Yokohama, Kobe, and Marina Bay Cruise Centre Singapore across the projection horizon. Segmentation dimensions modeled included service tier, customer type, destination cluster, and duration tier, with expedition versus mainstream vessel economics and family versus solo traveler expenditure profiles as industry-specific forecast inputs. CAGRs derived from iterative convergence of source market growth curves and port infrastructure investment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under bunker fuel price spikes, Australia's biosecurity protocol stringency escalations, or Japan's visa waiver policy reversals. Forecasts reflect assumptions on shipyard delivery schedules and crew certification pipeline throughput. Material deviation in LNG propulsion mandate timelines or terminal slot coordination failures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Cruise Tourism Market