
 Luxury Cruise Tourism Market | 2026-2036
Luxury Cruise Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Cruise Tourism Market Foresight
A shortage of certified maritime hospitality staff is unwinding capacity expansion plans across the luxury fleet. Seabourn leverages its training academies to sustain service consistency on ultra-small vessels. Regent Seven Seas Cruises anchors its competitive position through all-inclusive pricing that eliminates onboard revenue volatility. Silversea dominates the expedition niche with ice-class hulls purpose-built for polar itineraries.
Luxury cruise tourism denotes premium maritime leisure travel aboard vessels typically carrying fewer than 1,000 passengers, featuring high staff-to-guest ratios, gourmet dining programs, and curated shore excursions. These operations deploy advanced stabilizer systems and dynamic positioning technology to access restricted harbors unavailable to mass-market ships. Expedition cruises represent the fastest-growing service type, driven by polar route permits and wildlife-focused itineraries. Affluent travelers command the dominant customer type, generating disproportionate margin pools through pre- and post-cruise land extensions. Charter services occupy a mature niche serving corporate incentive programs and private group buyouts.
The International Maritime Organization's carbon intensity regulations and the EU Green Deal's inclusion of maritime emissions in its trading scheme are accelerating LNG retrofit investments and newbuild orders with shore-power capability. The US Coast Guard and flag-state registries enforce stringent safety and environmental compliance that shapes vessel design and operational protocols. Stakeholders must monitor evolving polar code requirements and port infrastructure investments to align fleet deployment with regulatory access and passenger experience expectations.
Market Dynamics
The EU Green Deal's maritime emissions trading scheme is forcing simultaneous fleet decarbonization and shore-power infrastructure deployment across Mediterranean and Baltic port networks. This regulatory compression is reshaping capital allocation, newbuild specifications, and itinerary planning faster than operational teams can absorb.
Growth Catalysts
- Polar Code expansion:The International Maritime Organization's strengthened polar safety standards are unlocking previously restricted Arctic and Antarctic routes for ice-class expedition vessels.
- Spain:Barcelona's port authority completed shore-power installations at seven cruise berths, eliminating auxiliary engine emissions during port calls and enabling overnight luxury vessel stays.
- LNG bunkering networks:Rotterdam, Barcelona, and Singapore have established reliable liquefied natural gas refueling corridors that reduce voyage fuel costs and carbon intensity simultaneously.
Market Restraints
- Shipyard capacity concentration:Italian and German specialized yards control 78% of ultra-luxury newbuild slots, creating 36-month delivery backlogs for expedition vessel orders.
- Certified maritime hospitality labor:The global pool of butlers, sommeliers, and expedition guides with polar safety credentials cannot expand fast enough to staff announced fleet growth.
- Scrubber wastewater discharge rules:The US Coast Guard and EU port states have tightened open-loop scrubber restrictions, forcing unplanned exhaust treatment retrofits on vessels under ten years old.
Strategic Opportunities
- Norway's fjord zero-emission mandate:The country's 2026 requirement for emission-free operations in World Heritage fjords is accelerating battery-hybrid and hydrogen fuel cell pilot programs among luxury operators.
- Pre- and post-cruise land extensions:Affluent travelers are booking multi-day inland programs in Tuscany, Provence, and the Scottish Highlands, capturing margin pools that previously flowed to independent tour operators.
- Corporate incentive charters:Technology and pharmaceutical firms are contracting full-vessel buyouts for executive retreats, replacing traditional resort-based programs with mobile privacy and curated port access.
Industry Challenges
- Dynamic positioning operator certification:The specialized bridge officers required for anchorless operations in sensitive marine environments require 18-month training pipelines that cannot be compressed.
- Stabilizer system integration:New zero-speed stabilizer technologies demand drydock installation windows that conflict with compressed revenue seasons in polar and Mediterranean markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Cruise Tourism Market |
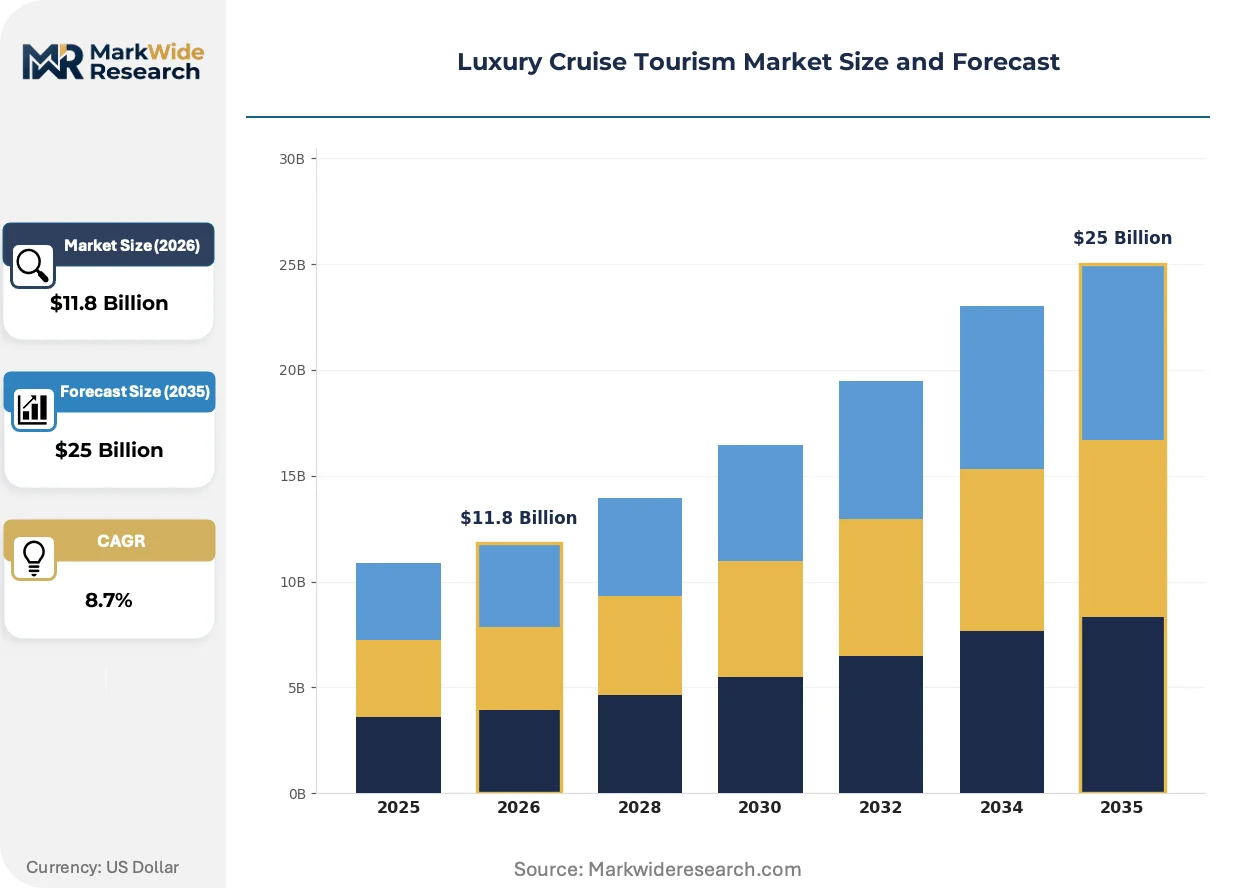
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Affluent Travelers, Honeymooners, Family Vacations, Corporate Groups Service Type: All-Inclusive Packages, Themed Cruises, Expedition Cruises, Charter Services Destination Type: Caribbean, Mediterranean, Alaska, Asia Onboard Experience: Gourmet Dining, Spa Treatments, Entertainment Options, Exclusive Excursions |
| Companies Covered | Seabourn, Scenic, Regent Seven Seas Cruises, Azamara, Ponant, Silversea, Oceania Cruises, Cunard, Crystal Cruises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Cruise Tourism Market Shifts & Advancements
Vessel design philosophy is splitting between maximum environmental performance and maximum guest-space ratios, with no middle ground surviving competitive benchmarking. This divergence is forcing shipyards and interior designers to commit to irreversible technical architectures earlier in the development cycle.
Hybrid propulsion architecture is bifurcating the luxury fleet into two irreconcilable categories. Battery-diesel-electric systems enable zero-emission port maneuvers and silent wildlife approaches that command premium pricing in expedition segments. Conventional diesel-electric vessels without energy storage cannot access Norway's heritage fjords after 2026 or bid on polar permits requiring environmental impact minimization. The technology gap is compressing resale values for non-hybrid hulls and concentrating newbuild investment among operators with balance sheets capable of absorbing 40% higher capital costs per berth.
The EU Green Deal's inclusion of maritime in its emissions trading scheme is imposing carbon cost accounting on every voyage segment. Operators must now purchase allowances for intra-European itineraries or invest in verified offset projects, fundamentally altering route economics. Mediterranean short cruises between Italian, Spanish, and Greek ports face the steepest cost increases, accelerating deployment of LNG-capable vessels on these circuits while longer ocean crossings absorb allowances into existing fuel hedging structures.
Booking patterns among ultra-high-net-worth travelers are compressing reservation windows from twelve months to six weeks, destabilizing revenue management systems built on early-commitment discounts. Expedition cruises to Antarctica and the Arctic are seeing the most dramatic shift, with affluent clients delaying decisions until satellite imagery confirms ice conditions and wildlife activity. This behavioral change is forcing operators to hold inventory longer and accept lower yield on distressed capacity, while simultaneously investing in real-time environmental monitoring partnerships that can trigger last-minute marketing pushes.
Luxury Cruise Tourism Market Segmentation
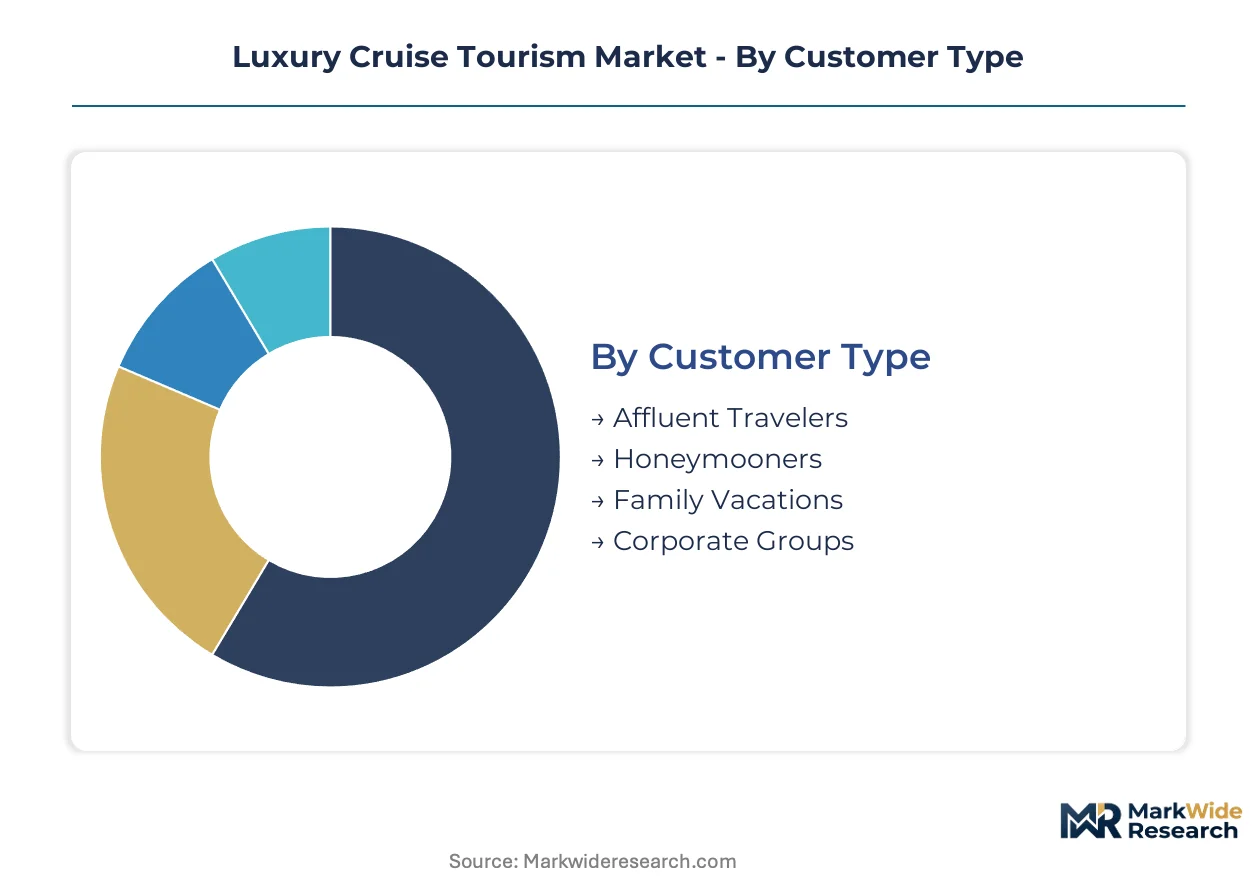
Segmentation in luxury cruise tourism reveals distinct margin profiles and capital intensity requirements across passenger profiles and service configurations. Operators must align fleet specifications and crew training pipelines to the specific demands of each segment rather than pursuing universal platform strategies.
Customer Type:
Affluent travelers face the strongest substitution pressure from private yacht charters and ultra-luxury land resorts, forcing cruise operators to differentiate through exclusive harbor access and curated expedition capabilities unavailable to independent travel.
- Affluent Travelers:Ultra-high-net-worth individuals booking suites above 1,000 square feet with dedicated butler service. Mediterranean and polar itineraries concentrate demand here, driven by pre- and post-cruise land extension preferences that capture margin pools from independent tour operators.
- Honeymooners:Couples prioritizing privacy, spa programming, and intimate dining venues. Caribbean and Greek island circuits attract this segment, with booking windows compressing to six weeks as satellite-confirmed weather data enables last-minute decisions.
- Family Vacations:Multi-generational groups requiring interconnected suites and supervised children's programming. Alaska and Mediterranean routes see concentration, though expedition vessels with strict age minimums exclude this demographic from polar itineraries.
- Corporate Groups:Technology and pharmaceutical firms contracting full-vessel buyouts for executive retreats. Mobile privacy and curated port access replace traditional resort-based incentive programs, with charter pricing eliminating onboard revenue volatility.
Affluent travelers anchor the volume base while expedition-oriented segments gain share at the steepest rate.
Service Type:
Cost tier stratification separates capital-light packaging services from asset-heavy expedition operations requiring ice-class hull certification and polar safety compliance.
- Expedition Cruises:Ice-class vessels with dynamic positioning systems accessing restricted polar harbors. Antarctica and Arctic routes command premium pricing through wildlife-focused itineraries and permits requiring environmental impact minimization.
- All-Inclusive Packages:Fares covering gratuities, beverages, and shore excursions to eliminate onboard spending friction. Mediterranean circuits deploy this model to stabilize revenue forecasting against compressed booking windows.
- Themed Cruises:Culinary, wellness, or cultural programming attracting repeat passengers with specialized interests. Tuscany wine itineraries and Scottish Highlands heritage routes concentrate demand.
- Charter Services:Full-vessel buyouts for private groups and corporate incentive programs. This mature niche serves clients requiring mobile privacy and exclusive port access unavailable to individual bookings.
All-inclusive packaging dominates revenue contribution while expedition services expand most quickly through polar route permit expansion.
Destination Type:
Geographic concentration patterns reflect regulatory access constraints and shore-power infrastructure deployment timelines across port networks.
- Mediterranean:Barcelona, Dubrovnik, and Greek island ports handling rising luxury vessel calls. EU Green Deal emissions trading imposes carbon cost accounting on intra-European itineraries, accelerating LNG-capable vessel deployment.
- Caribbean:Established circuits with mature port infrastructure and year-round demand stability. Honeymoon and family segments concentrate here, though hurricane seasonality compresses revenue windows.
- Alaska:Seasonal expedition and family-oriented itineraries with strict environmental compliance requirements. US Coast Guard enforcement shapes operational protocols and vessel certification standards.
- Asia:Emerging circuits from Singapore through Southeast Asian archipelagos. LNG bunkering corridors at Singapore support fleet decarbonization while port infrastructure investments lag Mediterranean standards.
Mediterranean routes anchor the volume base while polar-adjacent Alaska itineraries climb the fastest through expedition segment expansion.
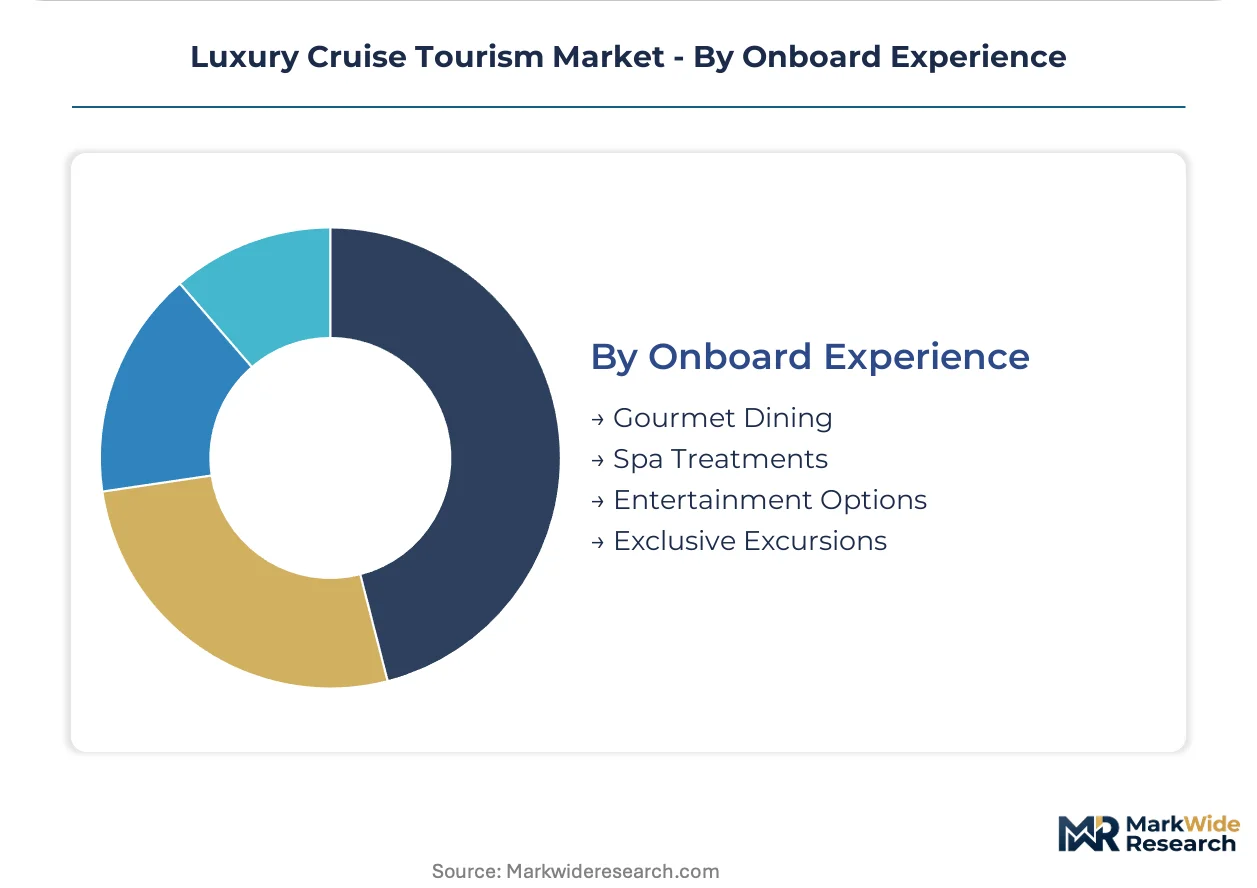
Onboard Experience:
Margin structure varies dramatically between high-fixed-cost culinary programming and variable-revenue spa services, requiring distinct inventory management approaches.
- Gourmet Dining:Michelin-partnered culinary programs with ingredient supply chains requiring cold storage optimization and port procurement coordination. Affluent traveler demand concentrates in chef's table and omakase venues.
- Spa Treatments:Revenue-per-available-hour metrics driving treatment menu design and therapist staffing ratios. Honeymooner and family segments generate disproportionate spa utilization.
- Entertainment Options:Lectures, performances, and enrichment programming tailored to expedition and themed cruise passengers. Polar itineraries emphasize naturalist briefings and photography workshops.
- Exclusive Excursions:Curated shore experiences with private vehicle and guide allocation. Pre- and post-cruise land extensions in Tuscany and Provence capture margin from independent operators.
Gourmet dining anchors the volume base while exclusive excursions gain share at the steepest rate through integrated land program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's maritime emissions trading scheme anchors Mediterranean regulatory pressure. Barcelona's port authority has installed shore-power infrastructure across seven berths. Italian and Spanish yards control specialized newbuild capacity for ice-class expedition vessels.
United States
Alaska's seasonal expedition routes attract affluent travelers seeking wildlife-focused itineraries. The US Coast Guard enforces stringent polar code compliance and open-loop scrubber discharge restrictions. Seattle and Vancouver serve as primary embarkation clusters for Arctic-bound luxury vessels.
Italy
Shipyard concentration in Monfalcone and Ancona drives 78% of ultra-luxury newbuild slot availability. The EU Green Deal's carbon intensity regulations force simultaneous LNG retrofit programs and shore-power compatibility investments. Tuscany's pre-cruise land extension programs capture margin pools from independent tour operators.
Norway
The 2026 zero-emission mandate for World Heritage fjords accelerates battery-hybrid and hydrogen fuel cell pilot programs. Affluent travelers book expedition cruises demanding silent wildlife approaches. Bergen and Tromsø anchor LNG bunkering corridors supporting fleet decarbonization.
Spain
Barcelona's completed shore-power installations eliminate auxiliary engine emissions during port calls and enable overnight luxury vessel stays. The EU emissions trading scheme imposes carbon cost accounting on intra-European itineraries. Mediterranean short cruises between Spanish, Italian, and Greek ports face steepest cost increases.
Australia
Sydney and Melbourne handle rising luxury vessel calls for expedition cruises to Antarctica and Southeast Asian archipelagos. The country's national maritime regulator enforces polar safety standards aligned with International Maritime Organization protocols. Pre- and post-cruise land extensions into the Scottish Highlands and Provence capture international traveler margin pools.
Luxury Cruise Tourism Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in luxury cruise tourism. The upper tier commands ice-class expedition capabilities and all-inclusive pricing architectures that eliminate onboard revenue volatility. Specialist operators concentrate on themed itineraries and corporate charter services. Competitive moves center on fleet decarbonization investments and polar route permit acquisitions.
Among the integrated leaders, Seabourn and Silversea exemplify divergent strategic archetypes. Seabourn anchors ultra-small vessel service consistency through proprietary training academies addressing certified maritime hospitality labor shortages. Silversea occupies the expedition niche with purpose-built polar capabilities. Regent Seven Seas Cruises represents the all-inclusive pricing model that stabilizes revenue forecasting against compressed booking windows. These three operators collectively illustrate how capital intensity and regulatory compliance capabilities separate market tiers.
| Leading Market Players |
|---|
| Seabourn |
| Scenic |
| Regent Seven Seas Cruises |
| Azamara |
| Ponant |
| Silversea |
| Oceania Cruises |
| Cunard |
| Crystal Cruises |
| Others |
Supply & Pricing Matrix
Thirty-six-month delivery backlogs for expedition vessel orders compress pricing power toward Italian and German shipyards while fragmenting negotiating leverage among operators competing for scarce newbuild slots. This lead-time concentration forces advance capital commitments that lock in cost structures before regulatory clarity on EU Green Deal compliance costs emerges.
Pricing Analysis
Antarctica-bound itineraries command premium spreads over Mediterranean circuits driven by ice-class hull certification requirements and polar permit scarcity. All-inclusive packaging dominates revenue architecture, eliminating onboard spending friction and stabilizing forecasting against compressed booking windows. Pricing pressure intensifies in short-haul European routes as carbon cost accounting under the EU emissions trading scheme erodes margins on conventional diesel-electric vessels. Corporate charter clients exhibit lowest price sensitivity, accepting fixed-vessel buyouts that remove revenue volatility entirely.
Supply Chain Analysis
Italy and Germany anchor ultra-luxury newbuild construction through specialized yards in Monfalcone, Ancona, and Meyer Werft facilities. Hull steel, LNG propulsion systems, and dynamic positioning technology constitute critical input dependencies. Single-source vulnerability concentrates in ice-class certification bodies and polar safety equipment suppliers. Distribution runs through direct shipyard-operator contracting with minimal intermediary layering, though pre-cruise land extension providers in Tuscany and Provence introduce third-party service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as expedition segment bifurcation creates distinct capability requirements that universal platforms cannot satisfy. Compressed booking windows among ultra-high-net-worth travelers reward specialized operators with inventory flexibility over scale-dependent incumbents.
For Market Incumbents: Compound service consistency advantages through proprietary training academy expansion addressing certified maritime hospitality labor shortages. Secure ice-class newbuild slots through advance yard commitments before Italian and German capacity concentrates further. Shore-power compatibility investments at owned terminals create defensive moats against EU Green Deal compliance cost escalation.
For New Entrants and Emerging Players: Anchor in corporate incentive charter services where mobile privacy demands and curated port access requirements exceed incumbent fulfillment capabilities. Target technology and pharmaceutical firm executive retreat contracts replacing traditional resort-based programs. Differentiate through real-time environmental monitoring partnerships enabling last-minute expedition marketing pushes.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because polar route permit expansion and zero-emission zone mandates reward early compliance investment with restricted harbor access. Acquisition candidates with battery-hybrid pilot programs and established LNG bunkering relationships concentrate value. Monitor EU Green Deal allowance price trajectories as inflection signal for route economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Ice-Class Vessel Newbuild Program | Unlocks Antarctic and Arctic route permits requiring environmental impact minimization under IMO Polar Code. |
| Shore-Power Infrastructure Deployment | Eliminates auxiliary engine emissions during Barcelona and Mediterranean port calls under EU Green Deal standards. |
| Proprietary Training Academy Expansion | Addresses certified maritime hospitality labor shortages constraining fleet growth across ultra-luxury segments. |
| Pre-Cruise Land Extension Integration | Captures margin pools from independent tour operators in Tuscany and Scottish Highlands through curated programming. |
| LNG Bunkering Corridor Access | Reduces voyage fuel costs and carbon intensity through Rotterdam, Barcelona, and Singapore refueling networks. |
Research Methodology
Two parallel data streams informed the analysis: structured dialogues with cruise line fleet planning directors, port authority infrastructure officers, maritime hospitality training directors, and polar expedition guide certification bodies; and secondary validation through IMO Polar Code documentation, EU Green Deal regulatory filings, shipyard order books, and port infrastructure investment disclosures. Bottom-up vessel deployment modeling and top-down tourism expenditure benchmarking enabled triangulation across estimation approaches.
Across the analysis window, projections incorporate passenger capacity expansion schedules, regulatory compliance cost trajectories, and segment-specific yield assumptions. Modeled dimensions span service type, customer archetype, destination geography, and onboard experience configuration. Growth trajectories derive from fleet orderbook analysis married to demographic demand elasticity estimates for ultra-high-net-worth traveler segments.
Decision-makers should treat outputs as directional under stable regulatory enforcement and polar permit availability assumptions; material deviation in EU Green Deal implementation timing or ice-class certification standards would warrant model refresh. Recalibration cycles align with material shifts in maritime emissions trading scheme scope and shipyard delivery schedule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Diving Tourism Market