
 Diving Tourism Market | 2026-2036
Diving Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Diving Tourism Market Outlook
Certification-as-a-service is recalibrating what diving tourism operators sell, transforming one-time training into recurring membership and continuing education revenue streams. PADI leverages its instructor network across thousands of affiliated dive centers to sustain global reach without direct asset ownership. ZuBlu differentiates through curated eco-conscious destination matching, while Bluewater Travel anchors its position in specialized liveaboard and photographic expedition segments.
Diving tourism encompasses organized recreational and professional underwater activities where participants use self-contained or surface-supplied breathing apparatus to access submerged environments, typically requiring water depths from shallow coral gardens to technical wreck penetrations exceeding 40 meters. The industry's commercial purpose centers on experience monetization through training progression, equipment utilization, and site access fees. Reef diving occupies the largest volume share among dive type segments, though wreck diving commands premium pricing due to specialized certification requirements and limited site availability. Liveaboard operators within the service provider category capture disproportionate margin pools through multi-day itinerary bundling that reduces customer acquisition costs per dive.
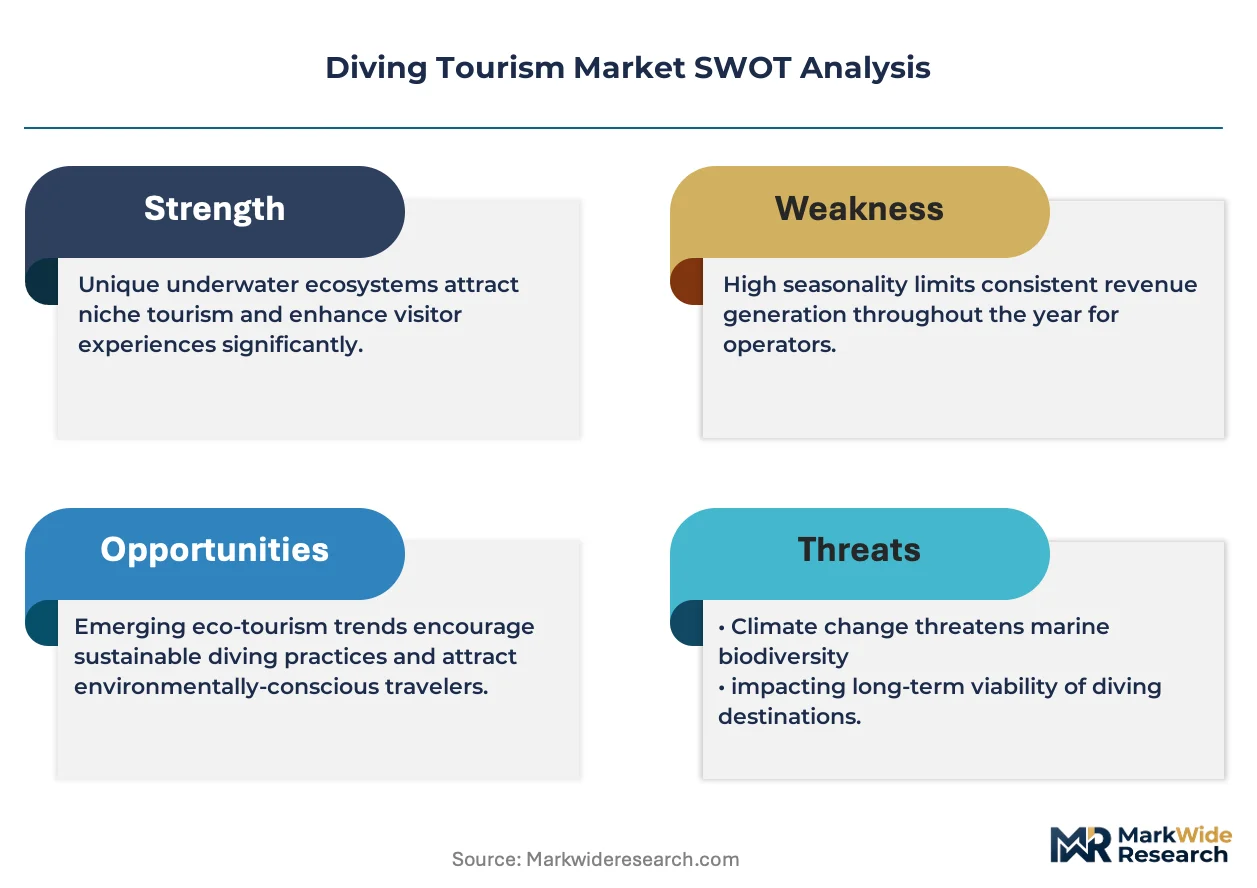
The International Maritime Organization's guidelines on vessel emissions affect liveaboard fleet operations, while Indonesia's Ministry of Marine Affairs and Fisheries regulates dive site permits and carrying capacities in protected areas. The EU Marine Strategy Framework Directive imposes environmental monitoring obligations on Mediterranean coastal operators, directly influencing site accessibility and seasonal closures. Stakeholders must monitor how climate-driven coral bleaching events reshape destination viability and certification curriculum requirements.
Market Dynamics
Liveaboard fleet operators now dominate premium itinerary bundling, compressing customer acquisition costs per dive while consolidating margin pools across multi-day expedition segments. This vessel-based service model is reshaping competitive positioning between land-based dive centers and mobile operators.
Growth Catalysts
- Marine conservation certification frameworks:PADI and SSI continuing education programs convert beginner divers into recurring membership revenue. Certification progression creates predictable upgrade pathways from open water through technical specialties.
- Indonesia's marine protected area expansion:The Ministry of Marine Affairs and Fisheries has established carrying capacity limits in Raja Ampat and Komodo National Park, channeling demand toward permitted operators with established sustainability protocols.
- Underwater photography equipment miniaturization:Compact camera housings and integrated strobe systems lower the skill barrier for content creation, expanding the addressable market beyond technical divers to social media-motivated travelers.
Market Restraints
- Liveaboard construction cost inflation:Steel hull prices and marine diesel engine supply constraints limit fleet expansion velocity for mid-size operators.
- Dive site permit scarcity:Indonesia's protected area licensing creates artificial supply caps that concentrate operational rights among incumbent permit holders.
- Coral reef degradation exposure:Climate-driven bleaching events in the Great Barrier Reef and Caribbean reduce destination viability without geographic diversification.
Strategic Opportunities
- Philippines archipelago development:Tubbataha Reef and Anilao macro diving sites remain underdeveloped relative to Indonesian counterparts, offering first-mover positioning for liveaboard operators.
- EU Green Deal vessel retrofit incentives:Mediterranean operators can access transition financing for hybrid propulsion systems, reducing fuel cost exposure and meeting EMAS environmental management standards.
- Virtual reality pre-certification modules:PADI's eLearning convergence with immersive simulation technology reduces pool time requirements and expands addressable geography for landlocked training centers.
Industry Challenges
- Master instructor pipeline constraints:Certification agency training ratios limit instructor production velocity, creating talent scarcity for expanding dive center networks.
- Rebreather technical certification complexity:Extended training timelines and equipment capital requirements restrict wreck and cave diving segment growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diving Tourism Market |
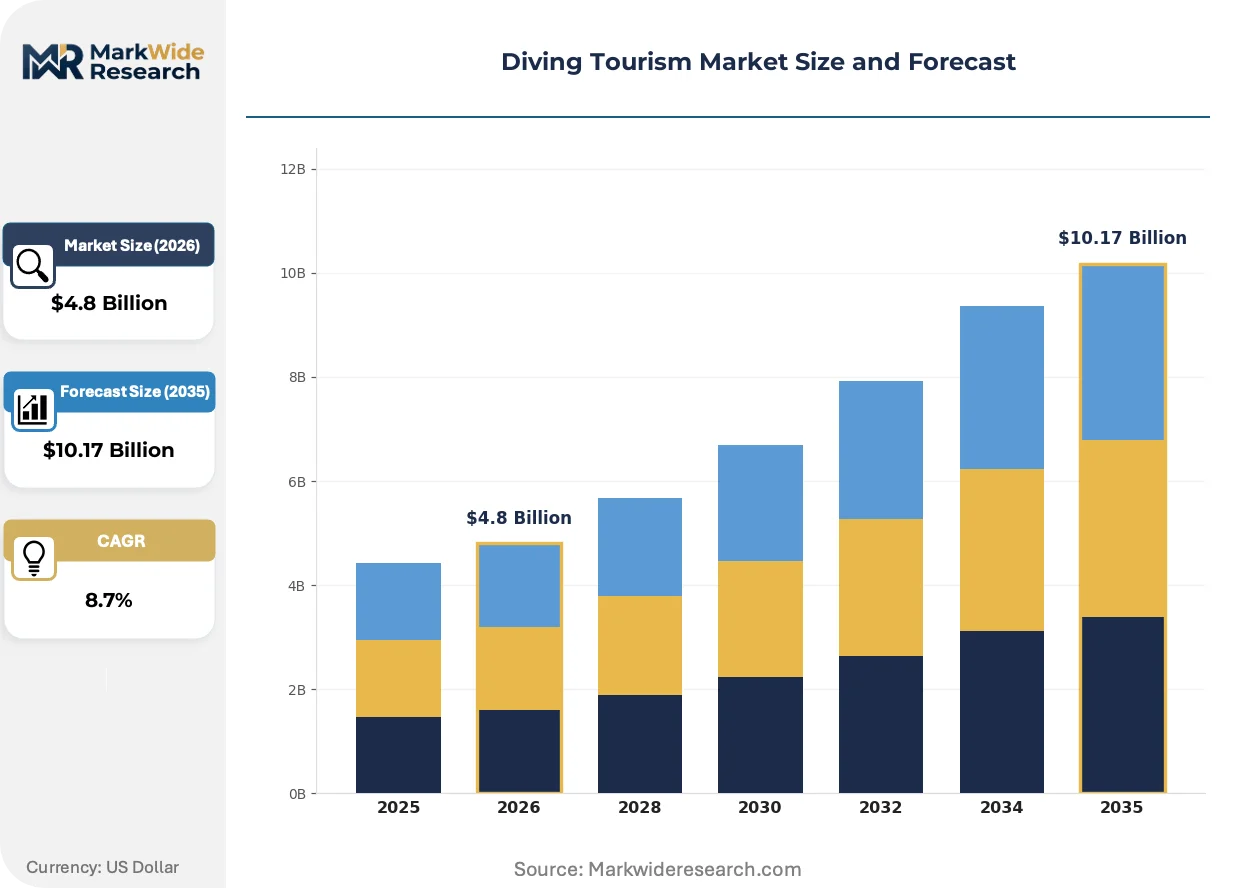
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Experience Level: Beginner, Intermediate, Advanced, Professional Dive Type: Reef Diving, Wreck Diving, Cave Diving, Drift Diving, Night Diving Service Provider: Diving Schools, Tour Operators, Equipment Rental Services, Liveaboard Operators, Adventure Clubs Customer Age Group: Youth, Adults, Seniors, Families, Couples |
| Companies Covered | PADI (Professional Association of Diving Instructors), SSI (Scuba Schools International), The Natural Travel Collection Ltd, Bluewater Travel, Scuba Travel, ZuBlu, Fly & Sea Dive Adventures, Ultimate Diving, Entrada Travel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diving Tourism Market Strategic Shifts
Diving tourism operators are restructuring service delivery around certification continuity and vessel-based mobility, displacing the traditional land-resort model. Technology integration and regulatory pressure are accelerating this operational pivot.
Rebreather technology is modularizing technical diving access by separating oxygen sensing, scrubber canister, and buoyancy control into interoperable subsystems. Advanced recreational divers are adopting semi-closed circuit units at accelerating rates in cave and wreck penetration environments. This architecture is modularizing what previously required manufacturer-specific training pathways, compressing certification transfer costs between equipment brands.
The EU Marine Strategy Framework Directive imposes environmental monitoring obligations on Mediterranean coastal operators, mandating dive site impact assessments and seasonal closure protocols. French and Italian operators face direct compliance costs for underwater noise and waste management documentation. Liveaboard itineraries are restructuring around these windows, with Corsica and Sardinia operators consolidating high-season density to offset restricted months.
Certification-driven destination selection is displacing price-based booking patterns among intermediate divers. Dive travelers now prioritize PADI 5-Star IDC center status and ecological accreditation over base package rates, particularly in the German and British outbound segments. This preference shift concentrates booking volume toward vertically integrated operators with captive training infrastructure, visible across Red Sea and Thailand liveaboard routes.
Diving Tourism Market Segmentation
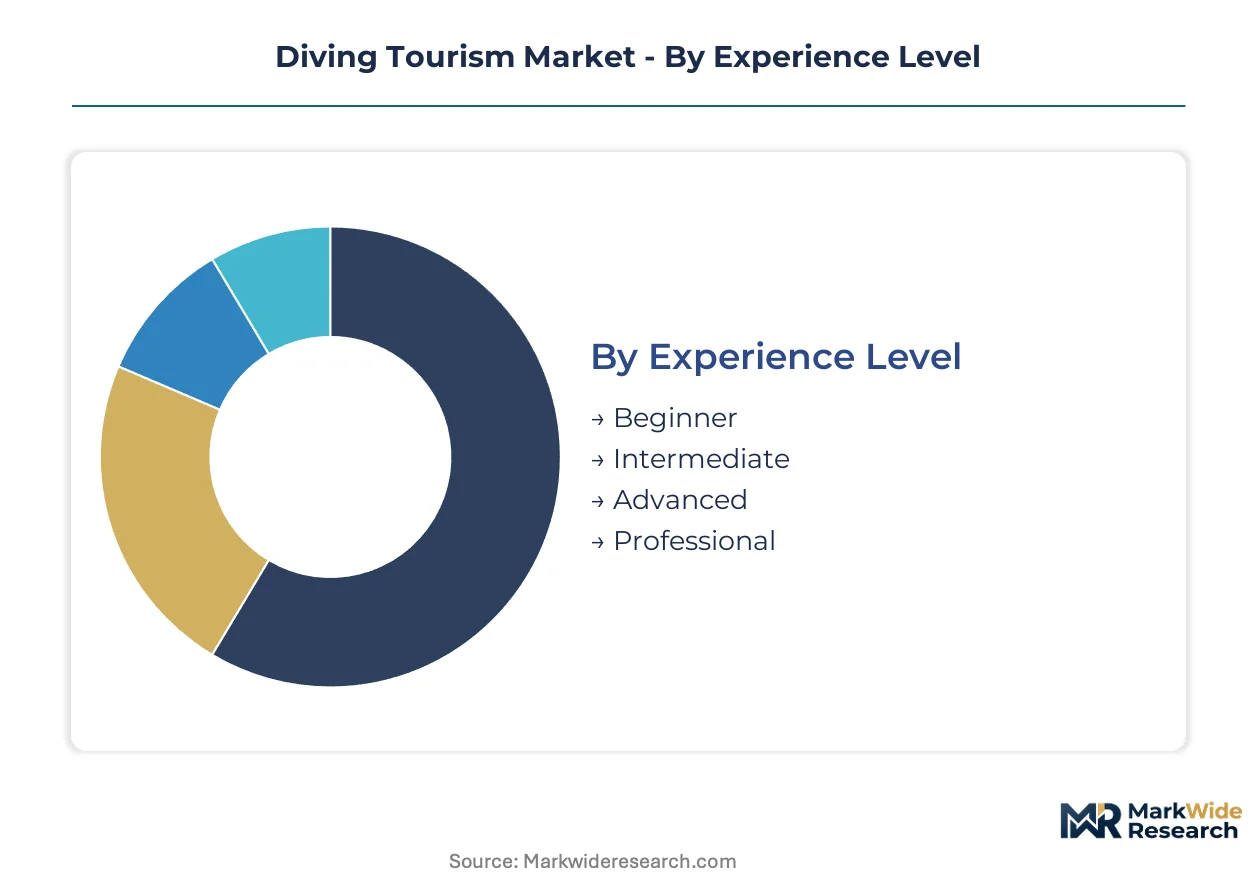
Diving tourism operators calibrate service delivery, pricing architecture, and marketing spend against distinct participant profiles. Segmentation by experience level, dive type, service model, and demographic cohort determines inventory allocation, instructor staffing ratios, and destination positioning strategies.
Experience Level:
Certification progression creates predictable equipment replacement cycles and continuing education revenue streams that anchor operator business models.
- Beginner:Open Water certification candidates require confined water training and shallow reef supervision. Demand concentrates in Thailand's Koh Tao and Australia's Great Barrier Reef gateway cities where PADI-affiliated centers bundle accommodation with training packages.
- Intermediate:Advanced Open Water and specialty certification holders seek drift diving and deep site access. Indonesia's Komodo National Park attracts this cohort with current-swept channels and multi-day liveaboard itineraries that monetize accumulated skills.
- Advanced:Technical diving preparation including nitrox and decompression procedures. Egypt's Red Sea wreck corridor from Sha'ab Abu Nuhas to the Thistlegorm draws divers pursuing penetration certifications.
- Professional:Divemaster and instructor candidates generating extended-stay revenue. Philippines' Puerto Galera and Utila in Honduras host month-long training residencies with dormitory-style accommodation economics.
Beginner sits at the top of the volume ranking, with Professional climbing the fastest as career-change demographics expand post-pandemic.
Dive Type:
Site accessibility and safety infrastructure requirements stratify pricing power and operational complexity across underwater environments.
- Reef Diving:Coral garden and wall diving accessible from shore or day boats. Operators in Indonesia's Raja Ampat and Malaysia's Sipadan leverage permit scarcity to bundle reef access with premium accommodation tiers.
- Wreck Diving:Submerged vessel penetration requiring specialized training and redundant gas supply protocols. Truk Lagoon in Micronesia and Scapa Flow in Scotland command itinerary premiums due to historical significance and depth profiles that filter participant volume.
- Cave Diving:Cenote systems in Mexico's Yucatán Peninsula and Florida's aquifer networks demand rebreather or side-mount configuration. Limited certified instructors constrain market expansion despite high per-dive revenue.
- Drift Diving:Current-assisted propulsion across reef walls and channels. Palau's Blue Corner and the Maldives' atoll passes attract photographers seeking pelagic encounters with minimal fin effort.
- Night Diving:Nocturnal reef exploration with specialized lighting equipment. Manta ray night feeds in Kona, Hawaii and bioluminescence tours in Puerto Rico generate ancillary revenue for land-based operators.
Reef Diving holds the largest participant base, though Wreck Diving achieves the steepest expansion trajectory as technical certification pathways mature.
Service Provider:
Capital intensity and customer acquisition economics separate asset-light training models from vessel-heavy expedition operations.
- Diving Schools:Certification-focused centers with pool facilities and confined water access. Thailand's Phuket and Spain's Costa Brava concentrate independent operators competing on course completion speed.
- Tour Operators:Day-trip bundlers aggregating transportation, equipment, and site access. Croatia's Adriatic coast and Greece's Cyclades islands feature seasonal operators optimizing around cruise ship arrival schedules.
- Equipment Rental Services:Regulator, BCD, and wetsuit leasing for travelers avoiding baggage fees. Airport-adjacent depots in Cairns and Cancun capture fly-in traffic with online reservation integration.
- Liveaboard Operators:Multi-day vessel-based itineraries with onboard accommodation and meals. Fleet operators in Indonesia and Egypt consolidate margin pools through direct booking channels that disintermediate resort intermediaries.
- Adventure Clubs:Membership-based organizations coordinating group travel and training progression. British Sub-Aqua Club and Scuba Schools International affiliate networks provide customer acquisition infrastructure for independent instructors.
Liveaboard Operators capture the highest revenue per customer, with Diving Schools expanding most quickly through eLearning convergence and landlocked market penetration.
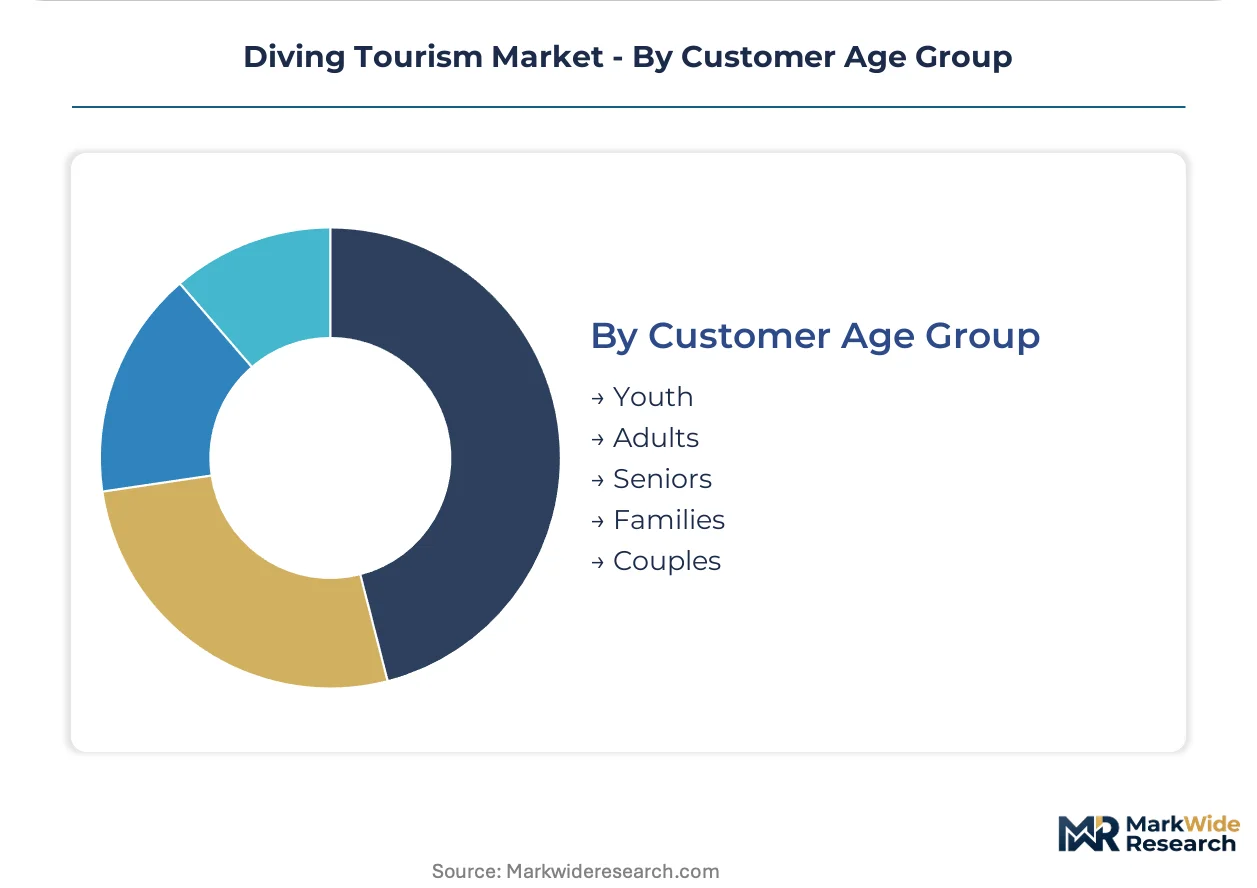
Customer Age Group:
Life stage determines risk tolerance, discretionary spending capacity, and companion travel dynamics that shape package design.
- Youth:Gap-year and university break travelers prioritizing cost minimization. Southeast Asia's hostel-integrated dive centers in Vietnam's Nha Trang and the Philippines' Boracay optimize for dormitory accommodation and social programming.
- Adults:Career-established professionals with concentrated vacation time and elevated equipment purchase intent. Liveaboard operators in the Galápagos and Socorro Islands target this segment with photographic expedition specialization.
- Seniors:Post-retirement travelers with extended availability and preference for moderate physical intensity. Caribbean operators in Bonaire and Curaçao emphasize shore diving accessibility and medical evacuation insurance inclusion.
- Families:Multi-generational groups requiring childcare infrastructure and shallow-site supervision. Egypt's Sharm El-Sheikh and Mexico's Cozumel blend junior certification programs with resort amenity packages.
- Couples:Romantic travel positioning with private guide allocation and intimate vessel configurations. Maldives overwater bungalow integrations and Fiji's private island liveaboards command premium positioning.
Adults generate the highest absolute revenue contribution, with Families gaining share fastest as junior certification curricula expand and school holiday timing aligns with regional dive seasons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands premium liveaboard density in Raja Ampat while Egypt anchors value-priced Red Sea access, revealing how geography and permit scarcity stratify regional positioning.
Indonesia
Raja Ampat and Komodo National Park drive liveaboard fleet concentration. The Ministry of Marine Affairs and Fisheries enforces carrying capacity limits and dive site permits that channel demand toward established operators. Sorong and Labuan Bajo function as embarkation clusters where domestic and international liveaboard operators consolidate multi-day itineraries.
Egypt
Red Sea wreck diving from Sha'ab Abu Nuhas to the Thistlegorm attracts technical certification candidates. The Egyptian Environmental Affairs Agency regulates marine protected area access and vessel emissions in the Ras Mohammed National Park zone. Hurghada and Sharm El-Sheikh host dense dive center networks competing on course completion speed and package bundling.
Thailand
Koh Tao maintains the highest per-capita open water certification throughput globally. The Department of Marine and Coastal Resources monitors coral reef health and seasonal closure protocols around the Similan Islands. Phuket and Krabi concentrate independent dive schools optimizing for backpacker accommodation economics and hostel-integrated training.
Philippines
Tubbataha Reef and Anilao macro sites remain underdeveloped relative to Indonesian counterparts. The Department of Environment and Natural Resources manages protected area entry permits and liveaboard licensing in the Sulu Sea. Puerto Galera on Mindoro Island anchors month-long professional training residencies for divemaster and instructor candidates.
United States
Florida's aquifer networks and Kona's manta ray night feeds serve distinct cave and pelagic specialty segments. The National Oceanic and Atmospheric Administration oversees marine sanctuary regulations affecting Florida Keys and Hawaiian Island dive operations. Key Largo and Kona concentrate technical training infrastructure for rebreather and deep wreck penetration certifications.
Diving Tourism Market Competitive Environment
Top-tier vendors anchor certification standardization and instructor network scale, while mid-tier operators compete on destination curation and photographic expedition specialization. The vendor base stratifies across certification agencies with global reach, liveaboard fleet operators with vessel assets, and digital booking platforms with curated matching algorithms. Three archetypes dominate: certification agencies monetizing continuing education pathways, liveaboard operators capturing multi-day itinerary margins, and aggregator platforms reducing search friction for specialized experiences. Competitive moves center on instructor network expansion and direct booking channel development that disintermediates traditional travel intermediaries.
Within the certification agency tier, PADI and SSI exemplify divergent approaches to global instructor network deployment and continuing education curriculum design. Among curated destination platforms, ZuBlu occupies a position emphasizing eco-conscious matching algorithms, while Bluewater Travel anchors specialized liveaboard and photographic expedition segments. These three entities represent the dominant competitive archetypes: standardization-driven scale, sustainability-positioned curation, and niche specialization with premium pricing authority.
| Leading Market Players |
|---|
| PADI (Professional Association of Diving Instructors) |
| SSI (Scuba Schools International) |
| The Natural Travel Collection Ltd |
| Bluewater Travel |
| Scuba Travel |
| ZuBlu |
| Fly & Sea Dive Adventures |
| Ultimate Diving |
| Entrada Travel Group |
| Others |
Value Chain & Pricing Dynamics
EU Marine Strategy Framework Directive compliance requirements gate both qualified supply and premium-tier pricing access, as Mediterranean operators must absorb environmental monitoring costs that filter marginal players from certified liveaboard tiers. Permit scarcity in Indonesia's Raja Ampat and Komodo National Park creates artificial supply caps that concentrate operational rights among incumbent holders, compressing price competition at the top tier while fragmenting land-based day-trip economics.
Pricing Analysis
Capacity additions in the Philippines are reshaping price floors for mid-tier liveaboard itineraries, forcing Indonesian operators to differentiate through extended-route specialization. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and vessel amenity density, with PADI 5-Star IDC status commanding measurable booking premiums. Pricing pressure stems from steel hull inflation and marine diesel supply constraints that limit fleet expansion velocity. Backpacker-oriented diving schools in Thailand exhibit highest price sensitivity, while photographic expedition specialists in the Galápagos demonstrate lowest elasticity due to itinerary uniqueness.
Supply Chain Analysis
Direct-to-consumer booking channels handle premium liveaboard demand, disintermediating traditional travel intermediaries and capturing margin pools previously allocated to resort networks. Geographic supply concentrates in Indonesia, Egypt, and Thailand, with vessel construction drawing from Chinese shipyards and European marine diesel suppliers. Raw material dependencies center on steel hull plating, scrubber canister media, and compact camera housing polymers. Single-source vulnerability runs through Indonesian permit licensing authorities that control site access allocation. Distribution runs through fleet operator direct platforms and curated destination matching algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diving tourism has matured into a late-cycle quality story where certification continuity and ecological accreditation now outweigh base package rates in booking decisions. Demand has shifted decisively toward premium specifications as intermediate divers prioritize PADI 5-Star IDC center status and liveaboard sustainability protocols.
For Market Incumbents: Anchor defensive positioning through captive instructor network expansion and direct booking channel development that locks in recurring certification revenue. Consolidate operational rights in permit-constrained geographies like Raja Ampat before Philippine archipelago development accelerates. Vertical integration into vessel ownership reduces third-party charter exposure as steel hull inflation intensifies. For New Entrants and Emerging Players: Launch via equipment rental services adjacent to airport hubs in underpenetrated liveaboard markets, capturing fly-in traffic before incumbent fleet operators establish presence. Target the Philippines' Tubbataha Reef and Anilao macro segments where permit infrastructure remains underdeveloped relative to Indonesian counterparts. Differentiate through rebreather technical certification specialization that incumbent land-based centers cannot easily replicate. For Investors and Strategic Acquirers: Roll-up economics work for mid-size liveaboard fleet operators because permit scarcity creates moated cash flow streams with limited new entrant threat. Five-to-ten year viability hinges on geographic diversification away from climate-vulnerable reef systems. Monitor coral bleaching event frequency as the critical inflection indicator for destination viability reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Liveaboard Fleet Expansion | Multi-day itinerary bundling compresses customer acquisition costs per dive in Indonesia's protected areas. |
| Certification Curriculum Integration | PADI and SSI continuing education pathways convert beginners into predictable recurring membership revenue. |
| Direct Booking Channel Development | Operator-owned reservation platforms disintermediate resort intermediaries and capture full margin pools. |
| Eco-Accreditation Investment | EU Marine Strategy Framework Directive compliance opens premium Mediterranean positioning and Green Deal financing. |
| Geographic Diversification | Philippine archipelago development reduces climate-driven reef degradation exposure concentrated in Caribbean markets. |
Study Parameters
Coverage spans Southeast Asia, the Middle East, Europe, and North America, with primary inputs from each region combining liveaboard fleet operators, certification agency curriculum directors, marine protected area regulators, and underwater photography equipment manufacturers. Secondary validation draws from Indonesia's Ministry of Marine Affairs and Fisheries permit disclosures, EU Marine Strategy Framework Directive implementation reports, PADI and SSI certification throughput statistics, and liveaboard operator booking platform data. Bottom-up vessel capacity modeling triangulates against top-down destination arrival estimates.
Rate-of-change decomposition separates volume effects from value mix shifts across the projection horizon, with CAGRs derived from segmented growth trajectory analysis. Segmentation dimensions include experience level progression, dive type specialization, service provider category, and customer age cohort. Forecast inputs incorporate climate-driven coral bleaching probability distributions and marine diesel engine supply constraint scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated reef degradation or permit regime liberalization scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market