
 Cruise Ship Market | 2026-2036
Cruise Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Cruise Ship Market Analysis
Affluent experience-seeking travelers are redrawing demand patterns away from traditional mass-market cruising toward premium expedition and luxury voyages. Royal Caribbean International leverages its scale advantage across mega-ship construction and private destination development. MSC Cruises anchors its growth in European homeporting and year-round Mediterranean deployment. Norwegian Cruise Line differentiates through freestyle dining concepts and flexible itinerary architecture.
A cruise ship constitutes a purpose-built passenger vessel exceeding 100 gross tons, designed for multi-day voyages with integrated hotel, entertainment, and hospitality systems operating on fixed or variable itineraries. These vessels employ diesel-electric or liquefied natural gas propulsion architectures to achieve the sustained speeds and hotel loads required for commercial viability. Luxury and expedition cruise categories command the widest margin pools as passenger yield per berth day far exceeds mass-market equivalents, while mega cruise vessels dominate absolute capacity deployment and capital intensity. River cruise operations occupy a structurally distinct niche with shallower draft requirements and port-restricted dimensions that limit competitive entry.
The International Maritime Organization enforces carbon intensity indicator benchmarks that constrain fleet operations without compliant propulsion retrofits, while the EU MRV framework and impending FuelEU Maritime standards in Europe impose additional emissions accounting burdens on vessels calling at European ports. The US Coast Guard and CDC maintain parallel health and safety inspection protocols that shape operational readiness and itinerary planning for North American deployments. Stakeholders must monitor regulatory compliance cost trajectories against yield recovery timelines as the industry navigates its decarbonization investment cycle.
Market Dynamics
The International Maritime Organization's carbon intensity indicator regulations are forcing a fleet-wide propulsion transition, compelling operators to retire older tonnage or invest in dual-fuel LNG architectures and battery-hybrid systems to maintain route access.
Growth Catalysts
- LNG Propulsion Mandates:The IMO's revised carbon intensity benchmarks are accelerating dual-fuel engine retrofits across existing fleets, creating sustained demand for shipyard capacity and marine engineering services.
- Expedition Segment Expansion:Polar-class vessel construction is concentrating in specialized European yards as affluent travelers seek Antarctic and Arctic itineraries requiring ice-strengthened hulls.
- Port Infrastructure Investment:Caribbean basin governments are expanding berthing capacity and shore power connectivity to accommodate larger vessel classes and reduce idle emissions.
Market Restraints
- Steel Price Volatility:Hull construction costs fluctuate with global steel plate markets, compressing shipyard margins on fixed-price newbuild contracts.
- Engine Supplier Concentration:Marine dual-fuel engine manufacturing concentrates among two European-German engineering groups, creating procurement bottlenecks for LNG-ready propulsion systems.
- Regulatory Timeline Compression:The EU FuelEU Maritime standard's 2025 implementation window leaves insufficient lead time for full fleet compliance without operational restrictions.
Strategic Opportunities
- Battery-Hybrid Convergence:Integration of solid-state battery banks with conventional diesel-electric plants enables zero-emission port maneuvering and hotel load management.
- Indian Ocean Deployment:Underpenetrated markets in the Seychelles, Maldives, and Sri Lanka offer white-space itinerary development for mid-size luxury operators.
- Shore Power Infrastructure:EU port electrification mandates under the Alternative Fuels Infrastructure Regulation create contracting opportunities for marine electrical integration specialists.
Industry Challenges
- Marine Engineering Talent Scarcity:Specialized technicians for dual-fuel engine maintenance and high-voltage electrical systems remain in critically short supply across shipyard and operator workforces.
- Classification Society Bottlenecks:Lloyd's Register and DNV approval queues for novel propulsion configurations are extending newbuild delivery schedules by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruise Ship Market |
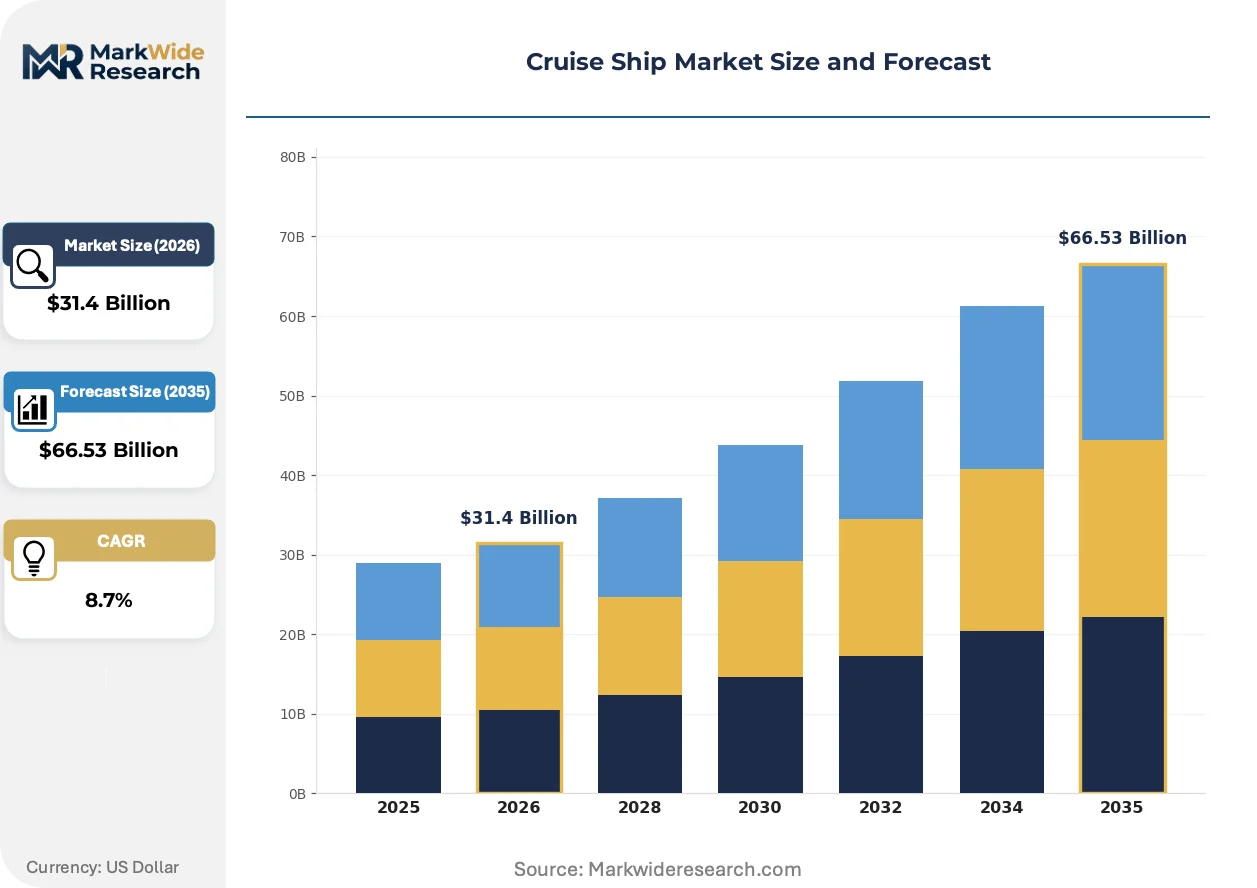
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $66.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Luxury Cruise, River Cruise, Expedition Cruise, Mega Cruise Onboard Service: Dining Options, Entertainment, Spa Services, Health and Wellness Passenger Segment: Families, Couples, Solo Travelers, Seniors Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Others |
| Companies Covered | Disney Cruise Line, Princess Cruises, Royal Caribbean International, Regent Seven Seas Cruises, Celebrity Cruises, MSC Cruises, Carnival Cruise Line, P&O Cruises, Norwegian Cruise Line, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruise Ship Market Emerging Trajectories
Propulsion technology diversification and regulatory compliance architecture are actively fragmenting competitive positioning across vessel size classes and deployment geographies.
Liquefied natural gas bunkering infrastructure is fragmenting across European and East Asian port networks. Mediterranean and Baltic Sea operators are adopting LNG as a bridging fuel ahead of zero-carbon alternatives. This technology diffusion is enabling smaller operators to achieve compliance parity with capital-intensive mega-ship fleets.
REACH and the EU Green Deal's maritime extensions are mandating lifecycle emissions disclosure for vessels calling at European ports. Shipowners must now document well-to-wake carbon intensity across fuel supply chains. Expedition and luxury segments face disproportionate compliance burdens due to lower passenger volumes per berth-day.
Charter and fractional ownership models are displacing traditional direct-booking patterns among ultra-high-net-worth travelers. Yacht brokers and luxury travel advisors are capturing itinerary design authority from cruise line reservation systems. This channel shift concentrates most visibly in Mediterranean summer deployments and Caribbean winter seasons.
Cruise Ship Market Segmentation
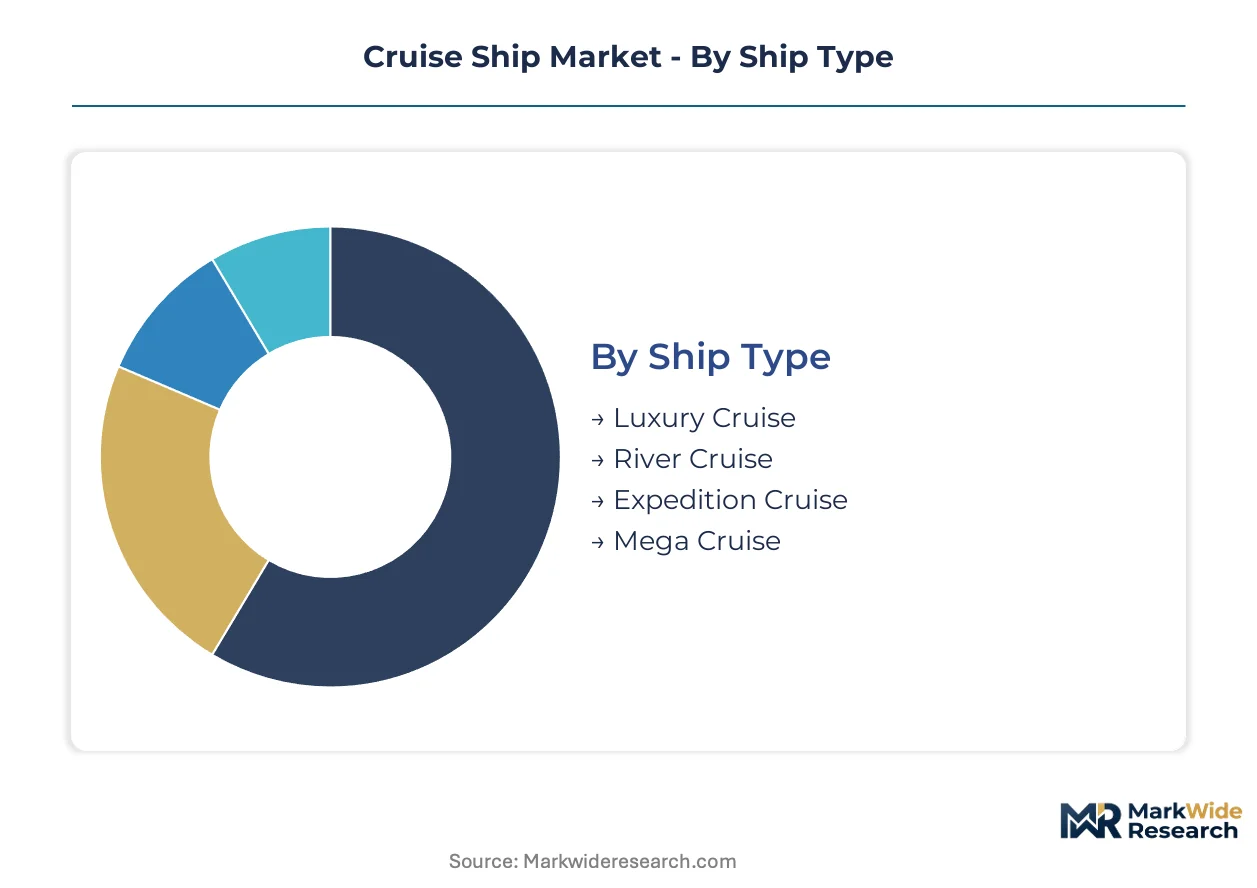
Cruise ship segmentation reveals how vessel architecture, service configuration, and passenger targeting collectively determine yield structures and capital deployment priorities across the industry. Understanding these divisions exposes where margin pools concentrate and where competitive entry faces structural barriers.
Ship Type:
Geographic deployment patterns diverge sharply across vessel categories, with some segments anchored in specific basins while others operate as globally mobile assets.
- Mega Cruise:These vessels exceed 200,000 gross tons and accommodate 5,000+ passengers across multi-deck hotel complexes with integrated entertainment districts. Demand concentrates in Caribbean and Mediterranean homeporting clusters where port infrastructure investments have expanded berthing capacity specifically for this class. IMO carbon intensity regulations are forcing dual-fuel LNG retrofits that favor newer tonnage with space for auxiliary fuel systems.
- Luxury Cruise:Smaller vessels typically under 50,000 gross tons emphasize suite accommodations, fine dining, and personalized service ratios. Passenger yield per berth-day far exceeds mass-market equivalents, with itineraries concentrated in Mediterranean summer and Caribbean winter seasons. Charter and fractional ownership models are displacing traditional direct-booking patterns among ultra-high-net-worth travelers.
- Expedition Cruise:Polar-class vessels with ice-strengthened hulls serve Antarctic and Arctic itineraries requiring specialized construction at European yards.
- River Cruise:Shallow-draft vessels operate on inland waterways with port-restricted dimensions that limit competitive entry and concentrate manufacturing among specialized builders.
Mega Cruise holds the largest share; momentum sits with Expedition Cruise as affluent travelers seek remote destination access.
Onboard Service:
Service architecture determines operating cost structures and drives differentiation in passenger acquisition economics across competitive tiers.
- Dining Options:Freestyle and flexible dining concepts reduce fixed meal-time infrastructure while accommodating diverse passenger preferences. Norwegian Cruise Line pioneered this architecture, forcing competitive response across mid-market operators. Specialty restaurant upcharges represent a critical ancillary revenue stream that improves net yield per passenger.
- Entertainment:Broadway-caliber productions, aqua-theater spectaculars, and destination-exclusive experiences anchor passenger value propositions on larger vessels. Royal Caribbean International leverages scale advantage across mega-ship construction and private destination development to amortize entertainment infrastructure costs across higher passenger volumes.
- Spa Services:Thermal suites, treatment rooms, and wellness programming generate high-margin ancillary spending concentrated in sea-day itineraries.
- Health and Wellness:Fitness centers, medical facilities, and wellness coaching respond to aging demographic profiles in core passenger bases.
Entertainment commands the largest infrastructure investment; Dining Options are climbing the fastest as flexible concepts expand across fleet retrofits.
Passenger Segment:
Demographic targeting shapes itinerary design, marketing channel selection, and shore excursion packaging across deployment regions.
- Families:Multi-generational cruising demands interconnected cabin configurations, supervised youth programming, and age-appropriate shore excursions. MSC Cruises anchors growth in European homeporting with year-round Mediterranean deployment that captures school holiday scheduling. Private island destinations with dedicated children's facilities concentrate competitive investment.
- Couples:Romantic getaway positioning emphasizes adult-only deck spaces, specialty dining, and destination wedding programming. Caribbean basin deployment dominates winter demand with port infrastructure investments expanding berthing capacity for premium vessels.
- Solo Travelers:Single-occupancy cabin inventory and dedicated social programming address historically punitive pricing for individual passengers.
- Seniors:Accessibility infrastructure, medical facilities, and relaxed pacing accommodate aging population segments in established markets.
Families hold the largest share; momentum sits with Solo Travelers as dedicated cabin inventory expands across newbuild specifications.
Booking Channel:
Channel economics determine customer acquisition costs and influence pricing transparency across passenger segments.
- Direct Booking:Cruise line reservation systems capture full margin but require substantial marketing investment to overcome travel advisor influence. Loyalty program enrollment and past-passenger incentives anchor retention economics. Digital platform investment concentrates on mobile-first interfaces that reduce friction in itinerary customization.
- Online Travel Agencies:Aggregator platforms deliver volume with compressed margins and reduced brand control over passenger experience positioning. Price comparison transparency intensifies competitive pressure on base fare structures.
- Travel Agents:Traditional advisors retain itinerary design authority for complex multi-leg bookings and luxury segment penetration.
- Others:Charter operators, incentive travel planners, and corporate event specialists occupy niche volume channels with distinct contracting terms.
Travel Agents hold the largest share in luxury and expedition categories; Online Travel Agencies are gaining share fastest in mass-market segments through mobile platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent experience-seeking travelers concentrate in coastal gateway cities with established cruise infrastructure, driving port investment and itinerary design across multiple national markets. The report examines five countries where deployment patterns, regulatory frameworks, and passenger demographics collectively shape competitive positioning.
United States
Florida's PortMiami and Port Canaveral anchor the world's largest cruise passenger throughput, with Miami-Dade infrastructure investments expanding terminal capacity for mega-vessel classes. The US Coast Guard and CDC maintain parallel inspection protocols that shape operational readiness for Caribbean deployments. Galveston and Seattle homeporting clusters are gaining share as Gulf Coast and Alaska itineraries diversify beyond traditional Florida concentration.
Germany
Hamburg and Bremerhaven serve as Europe's primary cruise construction and homeporting hub, with Meyer Werft and Meyer Turku yards specializing in LNG-ready newbuilds. The EU MRV framework and impending FuelEU Maritime standards impose emissions accounting burdens on vessels calling at German ports. Kiel and Warnemünde are expanding shore power connectivity under Alternative Fuels Infrastructure Regulation mandates.
China
Shanghai's Wusongkou International Cruise Terminal anchors Asia-Pacific deployment growth, with Tianjin and Guangzhou developing secondary homeporting capacity for domestic passenger demand. MIIT and SAMR oversight shapes safety certification requirements for vessels operating in Chinese waters. The Yangtze River Delta cruise manufacturing cluster is emerging through joint ventures with European shipbuilders.
Italy
Civitavecchia, Venice, and Genoa concentrate Mediterranean summer deployment, with port infrastructure investments targeting year-round operational capability. REACH and EU Green Deal maritime extensions mandate lifecycle emissions disclosure for vessels at Italian ports. Fincantieri's Monfalcone and Marghera yards specialize in luxury and expedition vessel construction for global operators.
Australia
Sydney's Circular Quay and White Bay terminals anchor South Pacific itineraries, with Brisbane and Melbourne expanding seasonal homeporting for domestic and international passengers. The country's national maritime regulator enforces safety standards aligned with IMO conventions for vessels operating in Australian waters. Cairns and Fremantle serve as expedition cruise gateways for Great Barrier Reef and Kimberley region deployments.
Cruise Ship Market Vendor Landscape
Player mix skews toward integrated cruise operators with captive shipyard relationships and destination development capabilities. The vendor base concentrates among three European-German engineering groups for propulsion systems and a handful of specialized yards for hull construction. Strategic archetypes include scale-driven mega-ship operators, premium expedition specialists, and river cruise niche players. Competitive moves center on dual-fuel LNG fleet retrofits and private island destination acquisitions that lock in itinerary differentiation.
Among US-based integrated operators, Royal Caribbean International, Carnival Cruise Line, and Norwegian Cruise Line exemplify the scale-driven archetype through mega-ship deployment and private destination portfolios. Disney Cruise Line occupies a position within the family-focused premium tier, leveraging entertainment IP integration that commands yield premiums over standard mass-market positioning. MSC Cruises represents the European homeporting specialist model, with year-round Mediterranean deployment and aggressive fleet expansion through captive shipyard relationships.
| Leading Market Players |
|---|
| Disney Cruise Line |
| Princess Cruises |
| Royal Caribbean International |
| Regent Seven Seas Cruises |
| Celebrity Cruises |
| MSC Cruises |
| Carnival Cruise Line |
| P&O Cruises |
| Norwegian Cruise Line |
| Others |
Supply Flow & Price Mechanics
Take-or-pay shipyard contracts with steel price indexation lock in hull construction slots while transferring commodity volatility risk to operators. This contracting architecture concentrates pricing power among European yards with Meyer Werft and Fincantieri commanding premium slot premiums for LNG-ready newbuilds.
Pricing Analysis
Cost-plus contracts indexed to steel plate benchmarks dominate newbuild negotiations, with fuel system certification tier and berth-day yield potential driving price spreads between mass-market and luxury specifications. Three-tier pricing structure across premium, standard, and economy levels separates polar-class expedition vessels from mid-market deployments from older tonnage facing regulatory obsolescence. Cost compression in legacy diesel-electric retrofits is intensifying because IMO carbon intensity deadlines compress yard availability. Mass-market operators exhibit highest price sensitivity due to thin yield margins, while ultra-luxury charter clients demonstrate inelastic demand.
Supply Chain Analysis
Just-in-time marine engine procurement preferences clash with strategic fuel system stockpiling as dual-fuel LNG component lead times extend. Manufacturing concentrates in Germany, Italy, and Finland for hull construction, with South Korean yards competing on mega-ship scale. Supply chains draw from specialized steel plate mills, marine engine foundries, and cryogenic fuel tank fabricators. Single-source vulnerability concentrates in Wärtsilä and MAN Energy Solutions for dual-fuel propulsion systems. Distribution runs through shipyard direct contracting with operator fleet planning departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across IMO, EU, and national maritime authorities creates specialist niches for compliance-focused engineering services and polar-class construction. Affluent millennial and Gen Z travelers are redrawing demand profiles toward expedition and experiential voyages.
For Market Incumbents: Secure captive shipyard relationships through multi-vessel order commitments that lock in construction slots through the decarbonization investment cycle. Acquire specialized expedition operators to capture yield premiums as polar-class demand accelerates. Battery-hybrid technology integration represents the critical R&D lever for port compliance.
For New Entrants and Emerging Players: Differentiate on shore power integration and zero-emission port maneuvering capabilities that exceed incumbent retrofit constraints. Target Indian Ocean deployment white space in Seychelles and Maldives itineraries where infrastructure investments lag demand. Charter and fractional ownership models offer the most penetrable go-to-market angle for ultra-high-net-worth client acquisition.
For Investors and Strategic Acquirers: Specialized marine engineering firms with dual-fuel certification capabilities offer acquisition exposure to the propulsion retrofit cycle. Long-term viability hinges on regulatory compliance cost recovery through yield expansion rather than volume growth. Watch for FuelEU Maritime enforcement intensity as the inflection signal for stranded asset risk in non-compliant tonnage.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel LNG Retrofit Program | IMO carbon intensity compliance secures route access for existing fleet tonnage. |
| Polar-Class Vessel Construction | Ice-strengthened hulls unlock Antarctic and Arctic itineraries for affluent travelers. |
| Private Destination Development | Controlled island experiences differentiate itineraries from commodity port calls. |
| Shore Power Infrastructure Investment | EU Alternative Fuels Infrastructure Regulation mandates create contracting opportunities. |
| Battery-Hybrid System Integration | Solid-state battery banks enable zero-emission maneuvering in regulated ports. |
Methodological Framework
Operator-level perspectives from fleet managers, shipyard commercial directors, marine engineering procurement leads, and port authority infrastructure planners anchored the qualitative base. Primary interviews combined with secondary validation from Lloyd's Register classification filings, DNV approval records, IMO regulatory submissions, and EU MRV emissions databases. Bottom-up vessel deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against steel price volatility scenarios and regulatory timeline compression risks. Segmentation dimensions modeled include ship type, onboard service configuration, passenger demographic targeting, and booking channel economics. CAGRs derived from berth-day yield trajectories, fleet expansion schedules, and regional deployment capacity constraints. Propulsion technology adoption curves and port infrastructure investment pipelines served as industry-specific forecast inputs.
Material uncertainties — steel commodity spikes, yard capacity bottlenecks, and regulatory enforcement variability — sit outside the modeled envelope. Forecasts reflect assumptions on dual-fuel engine delivery schedules and polar-class certification timelines. Revision becomes warranted when FuelEU Maritime compliance cost trajectories cross yield recovery thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Fishing Tourism Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Diving Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market