
 Fishing Tourism Market | 2026-2036
Fishing Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Tourism Market Foresight
Online booking aggregators and specialized travel agencies is reshaping how fishing tourism packages reach end consumers. Frontiers Travel leverages its direct relationships with remote lodge operators to control premium inventory access. Yellow Dog Flyfishing anchors its competitive position through destination expertise in saltwater flats and freshwater rivers. Orvis Travel differentiates by integrating retail equipment sales with guided expedition packages, creating repeat purchase pathways.
Fishing tourism encompasses guided recreational angling expeditions, equipment provision, and lodging arrangements where the primary activity centers on catching fish in natural or managed aquatic environments, typically requiring specialized vessels, tackle, and local ecological knowledge. The activity generates direct revenue through service fees while supporting secondary spending in rural coastal and riparian economies where alternative employment options remain limited. Saltwater and deep sea segments command premium pricing due to fuel costs, vessel requirements, and seasonal weather windows that constrain supply. Fly fishing attracts the highest per-trip spending among customer types, while family groups represent the volume base with shorter duration bookings and lower equipment intensity.
EPA clean water standards and NOAA fisheries management protocols in the United States restrict access seasons and catch limits, directly constraining operator capacity and elevating permit values. The EU Green Deal's marine strategy framework requires member states to assess tourism impacts on coastal habitats, pushing operators toward conservation program integration as a market access condition. Stakeholders must monitor evolving catch-and-release mandates and carbon disclosure requirements that will determine which destinations retain operating licenses.
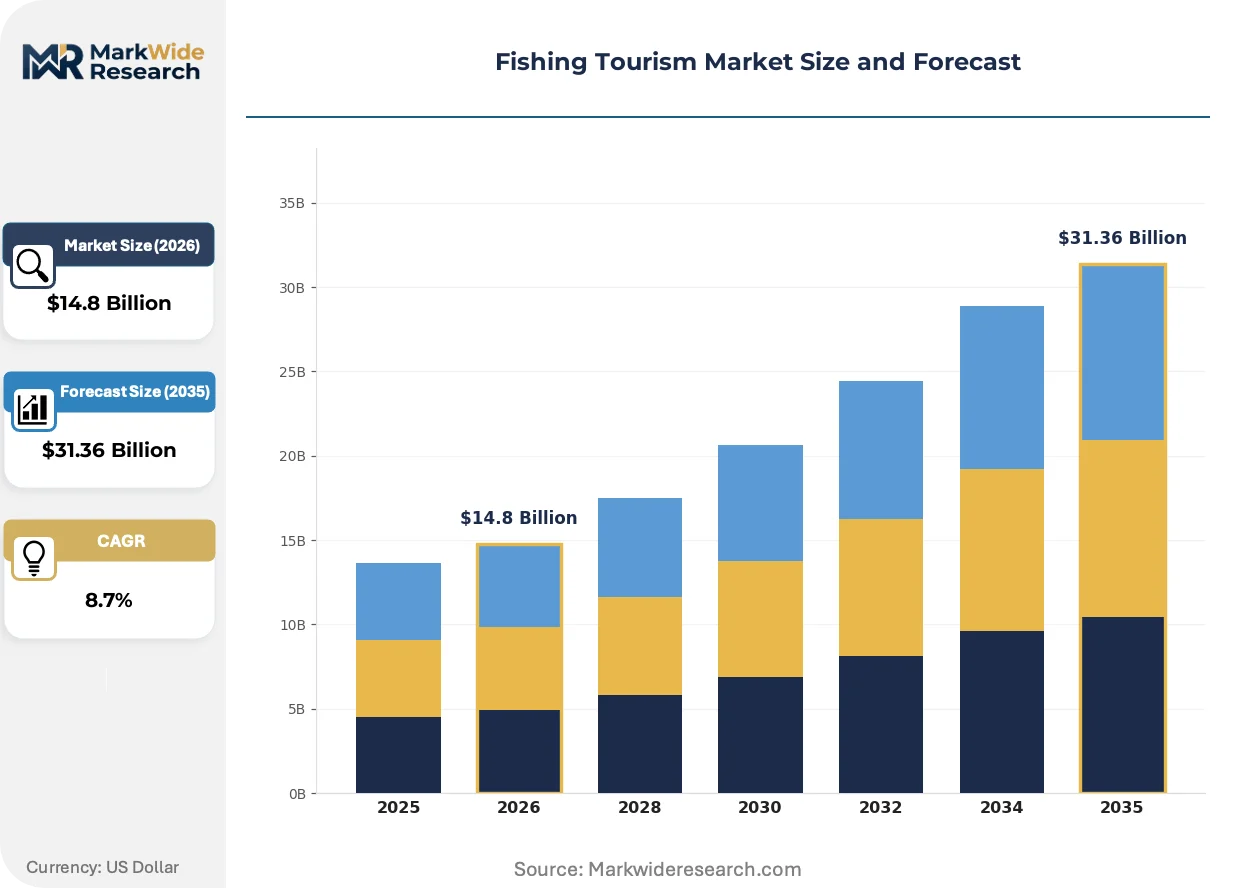
Market Dynamics
The EU Green Deal's marine strategy framework is forcing coastal operators to integrate conservation programming as a prerequisite for license retention, compressing margins while creating barriers to unqualified entrants.
Growth Catalysts
- EU Green Deal marine directives:Conservation-linked certification programs now unlock premium pricing tiers from sustainability-focused international anglers seeking ethical destination credentials.
- Recreational angler digitalization:Online booking aggregators are consolidating fragmented lodge inventory, reducing search friction for remote saltwater expedition planning.
- Norway's fjord clustering:Concentrated catch-and-release infrastructure investments in Vestland and Møre og Romsdal counties attract high-yield international visitor flows.
Market Restraints
- Marine diesel cost volatility:Deep-sea charter operations face margin compression from fuel price swings that operators cannot fully pass through to fixed-package bookings.
- Permit supply rigidity:NOAA fisheries management protocols cap seasonal access windows in US federal waters, constraining fleet utilization rates regardless of demand surges.
- Weather window concentration:North Atlantic storm patterns compress viable operating seasons, forcing capital-heavy vessel investments to earn returns across narrow temporal bands.
Strategic Opportunities
- Carbon disclosure mandates:Early adoption of vessel emission tracking positions operators for preferential licensing under tightening EU Green Deal enforcement trajectories.
- Family segment expansion:Shorter-duration, lower-equipment-intensity packages targeting multi-generational groups remain underdeveloped relative to premium fly-fishing specialization.
- Retail-equipment bundling:Tackle and apparel integration with expedition booking creates repeat purchase pathways and reduces customer acquisition costs.
Industry Challenges
- Guide certification bottlenecks:Local ecological knowledge requirements and safety credentialing timelines constrain qualified labor supply during peak seasonal demand windows.
- Legacy booking system integration:Remote lodge operators face technical friction migrating reservation management from phone-based systems to aggregator platform APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Tourism Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Freshwater, Saltwater, Fly Fishing, Ice Fishing, Deep Sea, Shore Customer Type: Recreational Anglers, Charter Operators, Eco Tourists, Adventure Seekers, Family Groups, Retirees Service Offering: Guided Tours, Equipment Rental, Lodging Packages, Educational Workshops, Conservation Programs Application: Leisure, Competitive Tournaments, Wildlife Photography, Cultural Experiences, Corporate Retreats |
| Companies Covered | Frontiers Travel, Hatch Adventure Travel, Orvis Travel, Got Fishing, Adventure Life, Yellow Dog Flyfishing, AndBeyond, International Expeditions, FishingBooker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Tourism Market Shifts & Advancements
Digital platforms and conservation-linked certification are restructuring how fishing tourism inventory reaches buyers and how destinations qualify for operating authority.
Real-time sonar mapping and species identification apps are rendering obsolete traditional guide-dependent location scouting for saltwater expeditions. Tech-enabled recreational anglers now self-direct vessel positioning, compressing the value capture historically concentrated with local knowledge holders. Charter operators in the Bahamas and Florida Keys respond by layering hospitality and equipment services atop diminished navigational premiums.
The EU Green Deal's marine strategy framework directive requires member states to assess tourism impacts on coastal habitats, pushing operators toward mandatory conservation program integration. This regulatory architecture elevates compliance costs for small-scale independents while advantaging capitalized networks capable of absorbing monitoring and reporting overhead. Norwegian fjord operators lead adaptation, embedding marine biology education modules into premium package structures.
International visitors now pre-book specialized expeditions through aggregator platforms rather than direct lodge relationships, fragmenting operator control over pricing and customer data. Frontiers Travel and Yellow Dog Flyfishing capture this flow by controlling premium inventory access through exclusive lodge contracts. This channel shift concentrates marketing spend and technical capability requirements, marginalizing operators lacking platform integration resources.
Fishing Tourism Market Segmentation
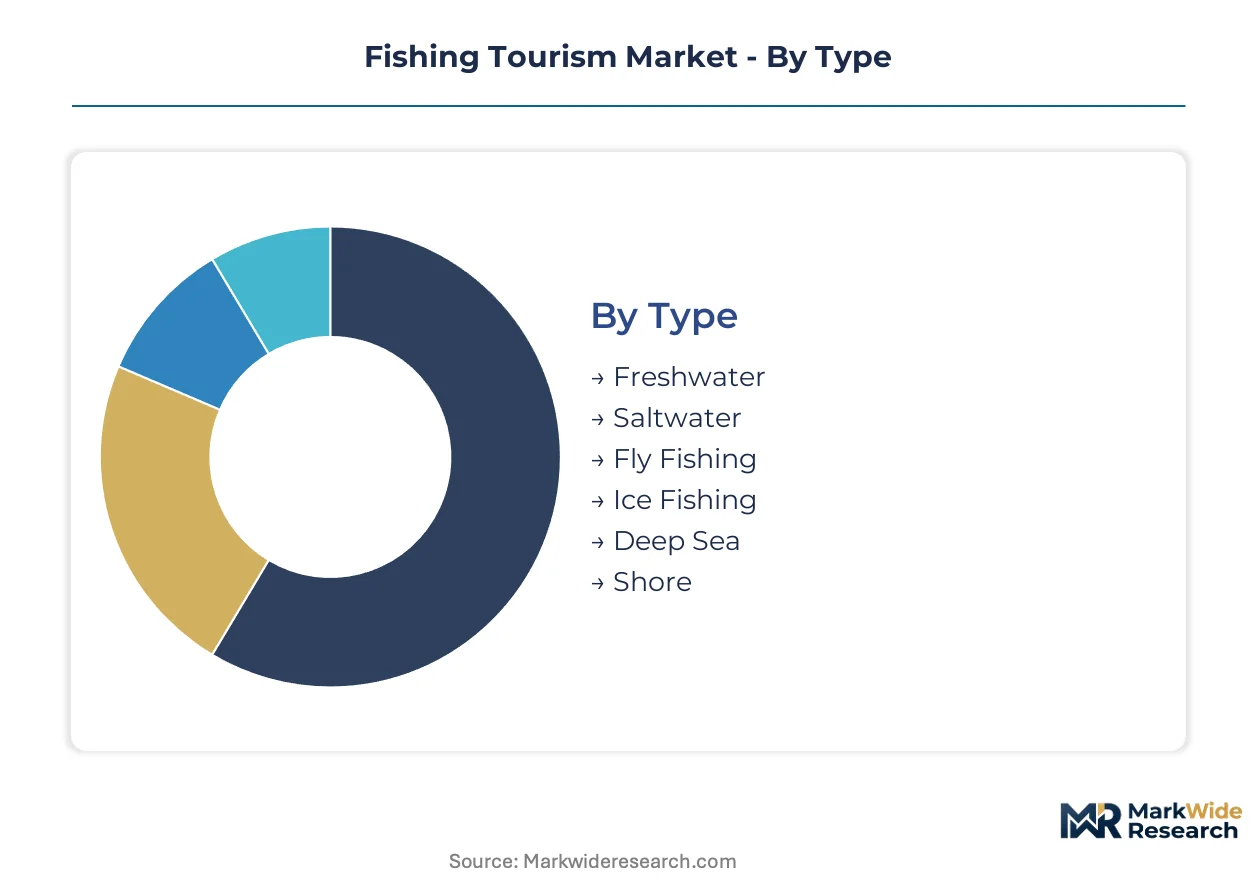
Segmentation in fishing tourism reveals how trip duration, equipment intensity, and conservation requirements fragment demand across distinct price tiers and operational models. Operators must match vessel configuration, guide specialization, and lodging infrastructure to specific angler profiles rather than deploying uniform service packages.
Type:
Cost tier differentiation across aquatic environments determines capital requirements, fuel exposure, and seasonal revenue windows for operators.
- Saltwater:Offshore expeditions require twin-engine vessels, radar systems, and coast guard-certified crews. Norwegian fjord operators in Vestland county attract premium-paying international visitors through catch-and-release protocols that satisfy EU Green Deal marine directives.
- Fly Fishing:Specialized casting instruction and river access permits generate the highest per-trip spending across all customer types. Demand concentrates in Scotland's Tweed system and Montana's Madison River where private water leases create scarcity value.
- Freshwater:Lake and river angling accessible from shore or small craft dominates volume through lower barriers to entry.
- Deep Sea:Extended offshore trips to continental shelf drop-offs require heavy tackle and fish-finding sonar.
- Ice Fishing:Seasonal hardwater activity dependent on sustained sub-freezing temperatures and ice safety certification.
- Shore:Beach and pier access with minimal equipment requirements serves price-sensitive day-trip segments.
Saltwater commands the established base. The steepest expansion runs through Fly Fishing.
Customer Type:
Application focus varies sharply between solitary pursuit, group entertainment, and conservation-linked experience seekers.
- Recreational Anglers:Individual and small-group enthusiasts booking through online platforms now drive the fastest-expanding demand channel. Digital aggregators reduce search friction for remote saltwater expedition planning.
- Family Groups:Multi-generational parties seek shorter-duration packages with lower equipment intensity and shore-based safety. This segment remains underdeveloped relative to premium fly-fishing specialization.
- Charter Operators:Commercial buyers purchasing block bookings for resale to end customers.
- Eco Tourists:Conservation-program participants prioritizing habitat education over catch volume.
- Adventure Seekers:Experience-maximizing travelers combining angling with remote access challenges.
- Retirees:Extended-stay visitors with flexible timing and high repeat-booking propensity.
Recreational Anglers command the established base. The steepest expansion runs through Family Groups.
Service Offering:
Margin structure shifts dramatically between high-touch guided labor and scalable equipment rental operations.
- Guided Tours:Professional angler instruction and location scouting capture value from local ecological knowledge. EPA and NOAA protocols in US federal waters restrict guide capacity through seasonal access windows and catch limits.
- Lodging Packages:Integrated accommodation and expedition booking creates multi-day revenue capture. Remote lodge operators face technical friction migrating from phone-based reservation systems to aggregator platform APIs.
- Equipment Rental:Tackle and vessel provision without labor attachment.
- Educational Workshops:Casting clinics and species identification training.
- Conservation Programs:Mandatory EU Green Deal compliance activities now unlocking premium pricing tiers from sustainability-focused international visitors.
Guided Tours command the established base. Conservation Programs are climbing the fastest as regulatory requirements harden.
Application:
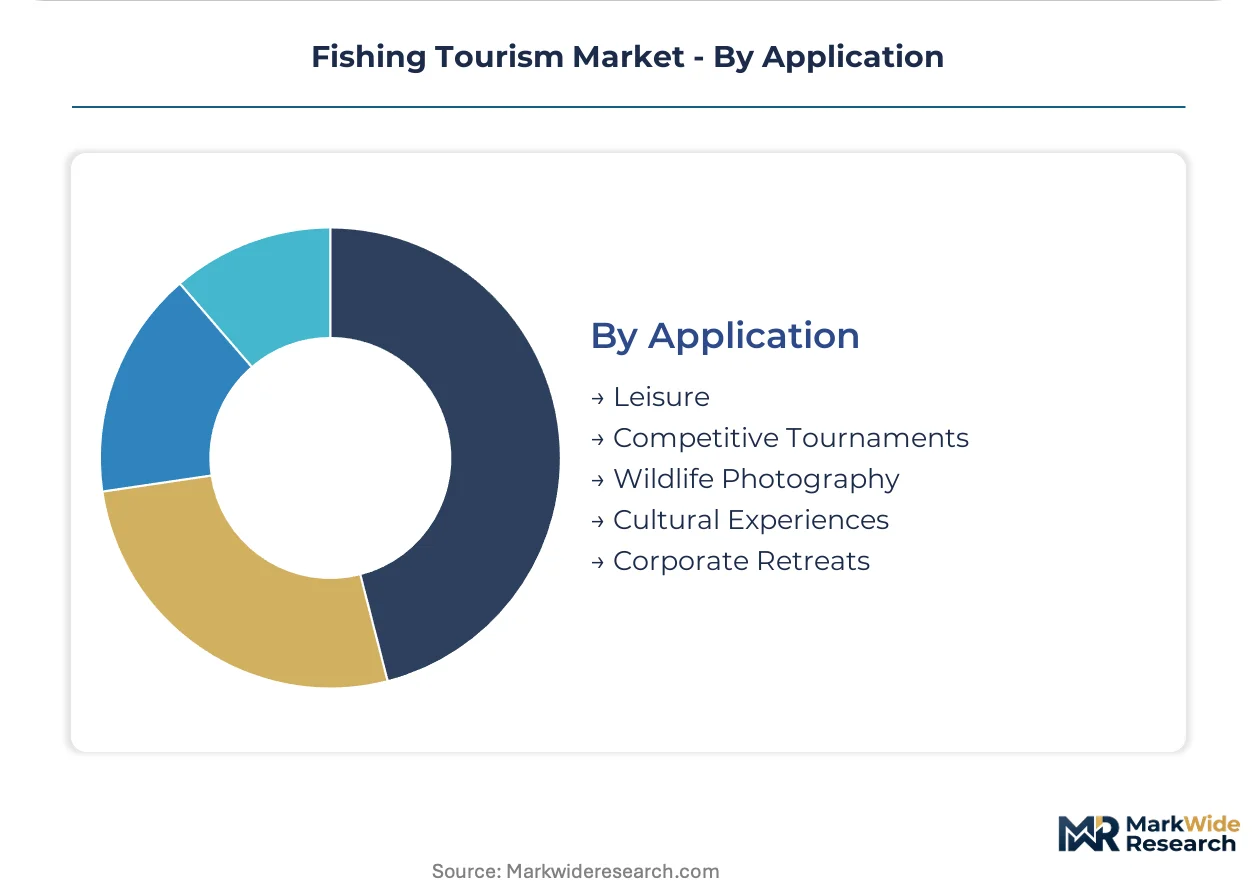
Volume concentration and pricing power diverge between leisure relaxation and competitive or corporate use cases.
- Leisure:Relaxation-focused angling without competitive structure generates the foundational revenue base across all operator types.
- Competitive Tournaments:Organized events with entry fees, prize structures, and sponsor exposure requirements. Demand clusters around Florida Keys and Bahamas destinations where consistent catch rates justify travel investment.
- Wildlife Photography:Capture-focused expeditions prioritizing visual documentation over harvest.
- Cultural Experiences:Indigenous and traditional fishing practice integration.
- Corporate Retreats:Team-building packages combining angling with hospitality programming.
Leisure commands the established base. Competitive Tournaments are expanding most quickly through sponsor-funded destination marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal marine strategy directives are redirecting capital toward conservation-linked destinations that satisfy tightening environmental compliance requirements. Norway's catch-and-release infrastructure investments and the United States' federal fisheries management protocols exemplify how regulatory frameworks now determine market access conditions.
Norway
Vestland and Møre og Romsdal counties attract premium-paying international visitors through concentrated saltwater expedition infrastructure. The Norwegian Environment Agency enforces strict catch-and-release protocols under EU marine strategy alignment. Bergen-based operators now embed marine biology education modules into premium package structures.
United States
Florida Keys and Bahamas-adjacent waters cluster competitive tournament activity with sponsor-funded destination marketing. EPA clean water standards and NOAA fisheries management protocols restrict seasonal access windows and catch limits. Miami charter fleets face margin compression from fuel price volatility that operators cannot fully pass through to fixed-package bookings.
United Kingdom
Scotland's Tweed system commands scarcity value through private water leases for specialized fly fishing expeditions. The Environment Agency regulates river access permits and seasonal fishing rights. Highlands operators integrate conservation programming to satisfy emerging carbon disclosure requirements.
Bahamas
Saltwater flats attract the highest per-trip spending among customer types with consistent catch rates justifying travel investment. The Bahamas National Trust coordinates marine protected area management affecting charter access zones. Nassau-based operators respond to tech-enabled anglers by layering hospitality services atop diminished navigational premiums.
Canada
British Columbia's Pacific coastline and interior lake systems support multi-generational family group packages with shorter duration bookings. Fisheries and Oceans Canada administers recreational licensing and habitat protection mandates. Vancouver Island lodges face technical friction migrating phone-based reservation systems to aggregator platform APIs.
Fishing Tourism Market Competitive Landscape
On the supply side, the industry is consolidating around digital platforms that control premium inventory access through exclusive lodge contracts. Specialized travel agencies and online booking aggregators now capture customer flows that previously ran through direct operator relationships. Three archetypes dominate: destination expertise specialists, equipment-retail integrators, and platform-based aggregators. Competitive moves concentrate on exclusive inventory contracting and technical capability investments that marginalize operators lacking platform integration resources.
Within the destination expertise tier, Frontiers Travel and Yellow Dog Flyfishing occupy positions defined by remote saltwater and freshwater river specialization. Orvis Travel represents the equipment-retail integrator archetype, exemplifying how tackle and apparel bundling with expedition booking creates repeat purchase pathways. These three entities anchor the competitive structure through distinct value capture mechanisms rather than overlapping service replication.
| Leading Market Players |
|---|
| Frontiers Travel |
| Hatch Adventure Travel |
| Orvis Travel |
| Got Fishing |
| Adventure Life |
| Yellow Dog Flyfishing |
| AndBeyond |
| International Expeditions |
| FishingBooker |
| Others |
Supply & Pricing Matrix
Marine diesel cost volatility determines both pricing tier spreads and supply chain shape across fishing tourism operations, compressing margins for deep-sea charter fleets while forcing vessel procurement toward fuel-efficient twin-engine configurations in premium segments.
Pricing Analysis
Certification level under EU Green Deal marine directives creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with conservation-linked credentials commanding substantial premiums from sustainability-focused international anglers. Pricing pressure stems from fuel price swings that operators cannot fully pass through to fixed-package bookings. Family groups exhibit highest price sensitivity, while fly fishing specialists show least sensitivity due to scarcity value of private water leases.
Supply Chain Analysis
Upstream feedstock for vessel construction and specialized tackle draws from Norway, the United States, and Japan for marine-grade aluminum hulls, carbon fiber rods, and electronic fish-finding systems. Raw material dependencies center on marine diesel, radar electronics, and coast guard-certified safety equipment. Single-source vulnerability concentrates in Norwegian fjord regions where catch-and-release infrastructure investments cluster. Distribution runs through online booking aggregators that consolidate fragmented lodge inventory and control customer data flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
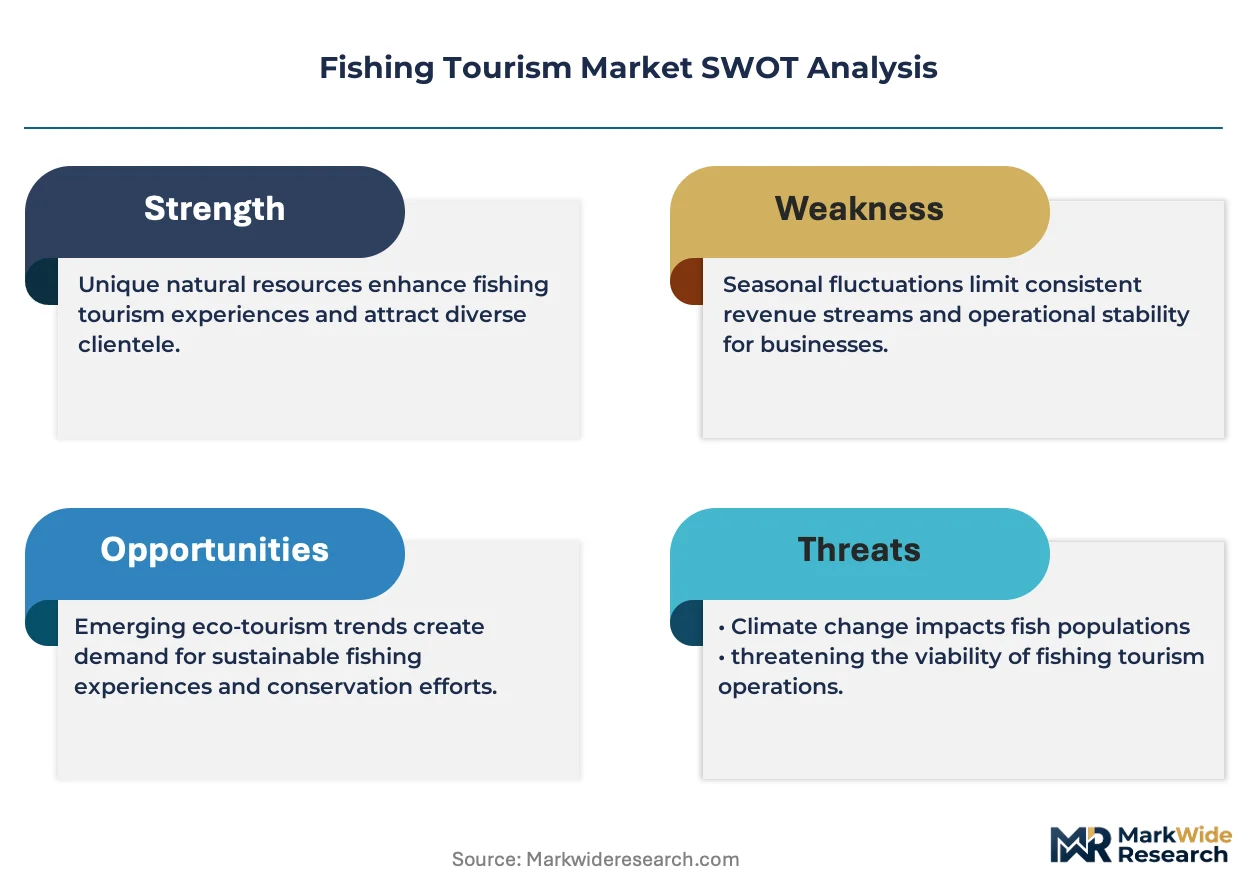
Fragmentation across customer types creates white-space opportunities, as digital platform penetration remains uneven and conservation-linked certification opens premium niches for differentiated operators.
For Market Incumbents: Insulate premium positioning through exclusive lodge contracts that lock inventory access against aggregator platform expansion. Secure backward integration into vessel fleets to control fuel cost exposure and maintain margin structure against marine diesel volatility. Prioritize EU Green Deal compliance investments ahead of enforcement trajectories to capture sustainability-premium pricing tiers.
For New Entrants and Emerging Players: Canada's British Columbia family segment offers underpenetrated white-space with shorter-duration, lower-equipment-intensity packages targeting multi-generational groups. Norway's fjord infrastructure investments demonstrate how conservation programming unlocks premium positioning. Target direct-to-angler digital marketing bypassing incumbent aggregator control to build owned customer relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-based aggregators with technical integration capabilities over fragmented independent operators. Long-term viability over the next decade hinges on carbon disclosure compliance and aggregator platform API integration. Watch for regulatory acceleration in EU marine strategy enforcement as the signal indicating valuation inflection for certified versus non-certified operator networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Conservation Certification Investment | EU Green Deal compliance unlocks premium pricing tiers from sustainability-focused international visitors. |
| Aggregator Platform Integration | API connectivity reduces customer acquisition costs and captures digital-native recreational angler flows. |
| Equipment-Retail Bundling | Orvis Travel demonstrates how tackle integration creates repeat purchase pathways and reduces churn. |
| Family Segment Package Development | Shorter-duration offerings target underdeveloped multi-generational demand with lower capital intensity. |
| Vessel Emission Tracking Adoption | Early carbon disclosure positions operators for preferential licensing under tightening EU enforcement. |
Research Methodology
The analysis maps saltwater expedition infrastructure, fly fishing specialization, and family-oriented freshwater operations, each validated through charter fleet operators, lodge proprietors, online booking platform executives, and marine conservation officers. Primary interviews combined with secondary validation from NOAA fisheries protocols, EU marine strategy directives, Norwegian Environment Agency catch-and-release regulations, and lodge reservation system data. Bottom-up vessel capacity and booking volume estimates triangulated against top-down tourism expenditure flows.
Assumptions held regulatory enforcement timelines and fuel price volatility bands within observed ranges while varying digital platform penetration rates and conservation certification adoption curves across the projection horizon. Segmentation dimensions modeled include aquatic environment type, customer archetype, service offering intensity, and regional regulatory cluster. CAGRs derived from regression analysis of historical booking volume against vessel capacity constraints and seasonal access windows. Industry-specific inputs incorporated EPA seasonal restrictions and EU Green Deal marine directive implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by FishingBooker or Frontiers Travel would shift competitive dynamics and pricing power distribution. Material shifts in EU marine strategy enforcement acceleration or North Atlantic storm pattern severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cruise and Marine Tourism
Cruise Ship Market
Cruise and Marine Tourism
Cruise Tourism Market
Cruise and Marine Tourism
Luxury Cruise Tourism Market
Cruise and Marine Tourism
Global Cruise Market
Cruise and Marine Tourism
Asia-Pacific Cruise Ship Market
Cruise and Marine Tourism
Saudi Arabia Diving Tourism Market
Cruise and Marine Tourism
Alaskan Cruises Market
Cruise and Marine Tourism
River Cruises Market
Cruise and Marine Tourism
Coastal and Maritime Tourism Market
Cruise and Marine Tourism
US Hotels, Resorts, and Cruise Lines Market
Cruise and Marine Tourism
Asia-Pacific Cruise Tourism Market
Cruise and Marine Tourism
Cruise Travel Market
Cruise and Marine Tourism
Diving Tourism Market