
 Cross-Border E-Commerce Logistics Market | 2026-2036
Cross-Border E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Border E-Commerce Logistics Market Analysis
Cross-border parcel networks is fragmenting as e-commerce volumes overwhelm traditional postal monopolies. DHL leverages its European hub architecture to sustain premium express lanes into Asia-Pacific. FedEx anchors North American outbound capacity with integrated customs brokerage. Aramex competes on price-sensitive Middle East-Africa corridors where legacy carriers carry heavier cost structures.
Cross-border e-commerce logistics encompasses the end-to-end movement of consumer goods across national jurisdictions, combining multimodal transport with customs clearance, last-mile delivery, and returns management through track-and-trace systems operating at SKU-level granularity. Its commercial purpose centers on collapsing delivery times for international online purchases while maintaining cost structures that preserve merchant margins. Air freight commands premium pricing for time-definite shipments but faces margin compression from ocean freight's encroachment into less urgent e-commerce lanes. Express delivery services capture the highest per-unit margins though standard delivery volumes dominate absolute shipment counts. Warehousing functions increasingly concentrate near destination markets as merchants pre-position inventory to circumvent customs delays.
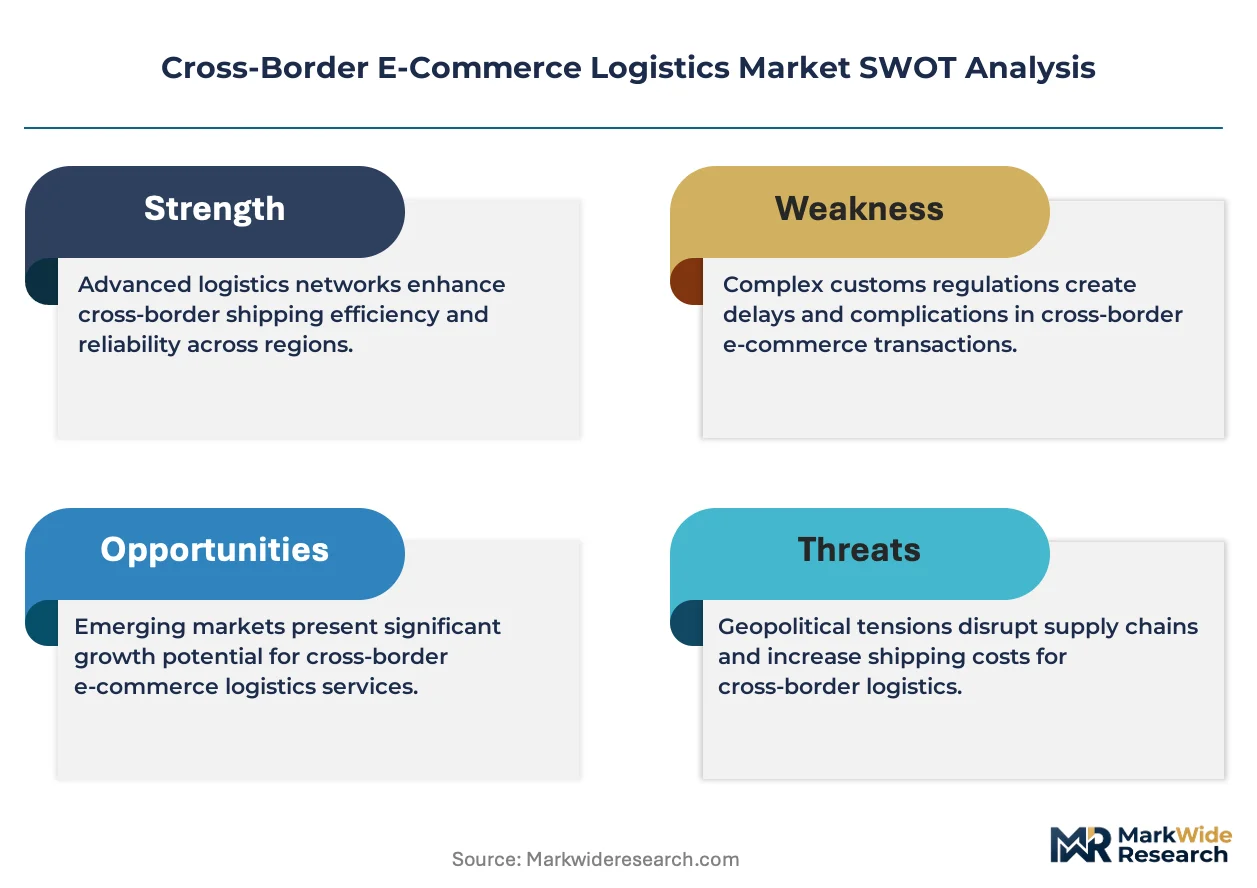
WTO trade facilitation agreements shape baseline customs procedures while the EU's ICS2 system mandates advance cargo data submission before goods depart origin countries. China's SAMR enforces consumer protection rules on cross-border platform sales including product labeling and recall liability. Stakeholders must monitor how divergent de minimis thresholds across jurisdictions reshape routing decisions and compliance cost allocation.
Market Dynamics
Customs pre-arrival data mandates are restructuring network economics by forcing origin-side compliance investments that favor integrated operators over fragmented postal handoffs. The EU's ICS2 system exemplifies this shift, compressing clearance timelines while raising fixed-cost barriers for cross-border parcel flows.
Growth Catalysts
- ICS2 Pre-Declaration Mandate:The EU's advance cargo data requirement accelerates carrier consolidation as smaller forwarders lack IT infrastructure for automated filing.
- Fashion E-Commerce Concentration:Southeast Asian apparel merchants drive express lane expansion from Shenzhen and Guangzhou manufacturing clusters into European last-mile networks.
- SKU-Level Track-and-Trace:Granular visibility systems enable pre-positioned inventory strategies that compress delivery windows for time-sensitive consumer goods.
Market Restraints
- Air Freight Input Cost Volatility:Jet fuel price swings compress margins on premium express lanes where fuel surcharges lag spot market movements.
- Origin-Side Supply Concentration:China's export manufacturing clusters around Pearl River Delta cities create single-point vulnerability for outbound capacity.
- De Minimis Divergence:Inconsistent duty-free thresholds across jurisdictions force complex routing arbitrage that fragments network efficiency.
Strategic Opportunities
- Middle East-Africa Corridors:Price-sensitive lanes between Dubai and Lagos remain underpenetrated by integrated carriers with heavy European cost bases.
- Returns Management Infrastructure:Reverse logistics capabilities near destination markets capture merchant spend currently lost to postal monopolies.
- Ocean-Air Multimodal Convergence:Hybrid routing for non-urgent e-commerce compresses unit costs while preserving delivery predictability.
Industry Challenges
- Customs Brokerage Talent Scarcity:Specialized compliance expertise for ICS2 filing and HS code classification outpaces training pipeline capacity.
- Legacy Warehouse Management Integration:Pre-positioned inventory strategies require API connectivity with merchant ERP systems that mid-market retailers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Border E-Commerce Logistics Market |
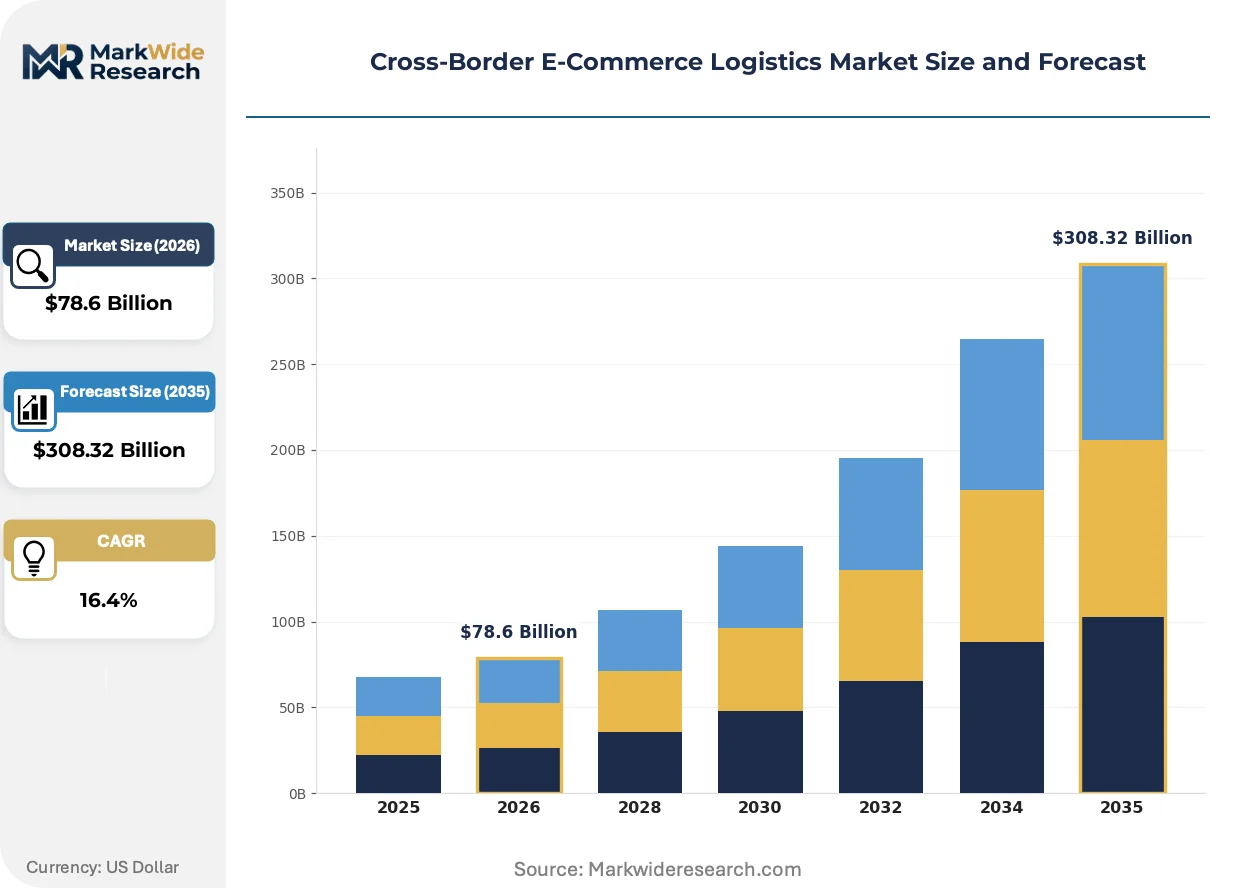
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $308.32 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Shipping Method: Air Freight, Ocean Freight, Rail Freight, Ground Transportation Service Type: Express Delivery, Standard Delivery, Warehousing, Customs Clearance Package Type: Parcel, Pallet, Container, Document End User: Retailers, Wholesalers, Manufacturers, Entrepreneurs |
| Companies Covered | Spring Global Delivery Solutions, UPS, DHL, Kuehne + Nagel, Flexport, Aramex, FedEx, DB Schenker, Asendia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Border E-Commerce Logistics Market Emerging Trajectories
Automation of customs documentation and real-time cargo visibility are compressing the traditional trade-off between delivery speed and landed cost. Three developments are restructuring competitive positioning in cross-border fulfillment.
Blockchain-enabled cargo documentation is collapsing clearance delays at destination ports by creating immutable chain-of-custody records accessible to customs authorities before physical arrival. Large apparel retailers with high shipment frequency are piloting these systems across Asia-Europe lanes. The structural consequence is collapsing the documentation advantage previously held by integrated express carriers with proprietary customs brokerage networks.
REACH chemical compliance requirements for consumer goods entering the European Economic Area are forcing origin-side testing investments that reshape supplier qualification. Manufacturers in Guangdong province now embed compliance documentation into production workflows rather than treating it as pre-shipment add-on. Electronics and cosmetics categories face the steepest documentation burden, driving consolidation toward vertically integrated exporters with captive testing laboratories.
Merchant procurement of logistics services is fragmenting across channel-specific requirements as marketplace platforms impose divergent fulfillment standards. Amazon's FBA cross-border program competes directly with merchant-direct routing for inventory ownership and customer data. This tension is most visible among Shenzhen-based electronics sellers balancing platform dependency against margin preservation through independent logistics procurement.
Cross-Border E-Commerce Logistics Market Segmentation
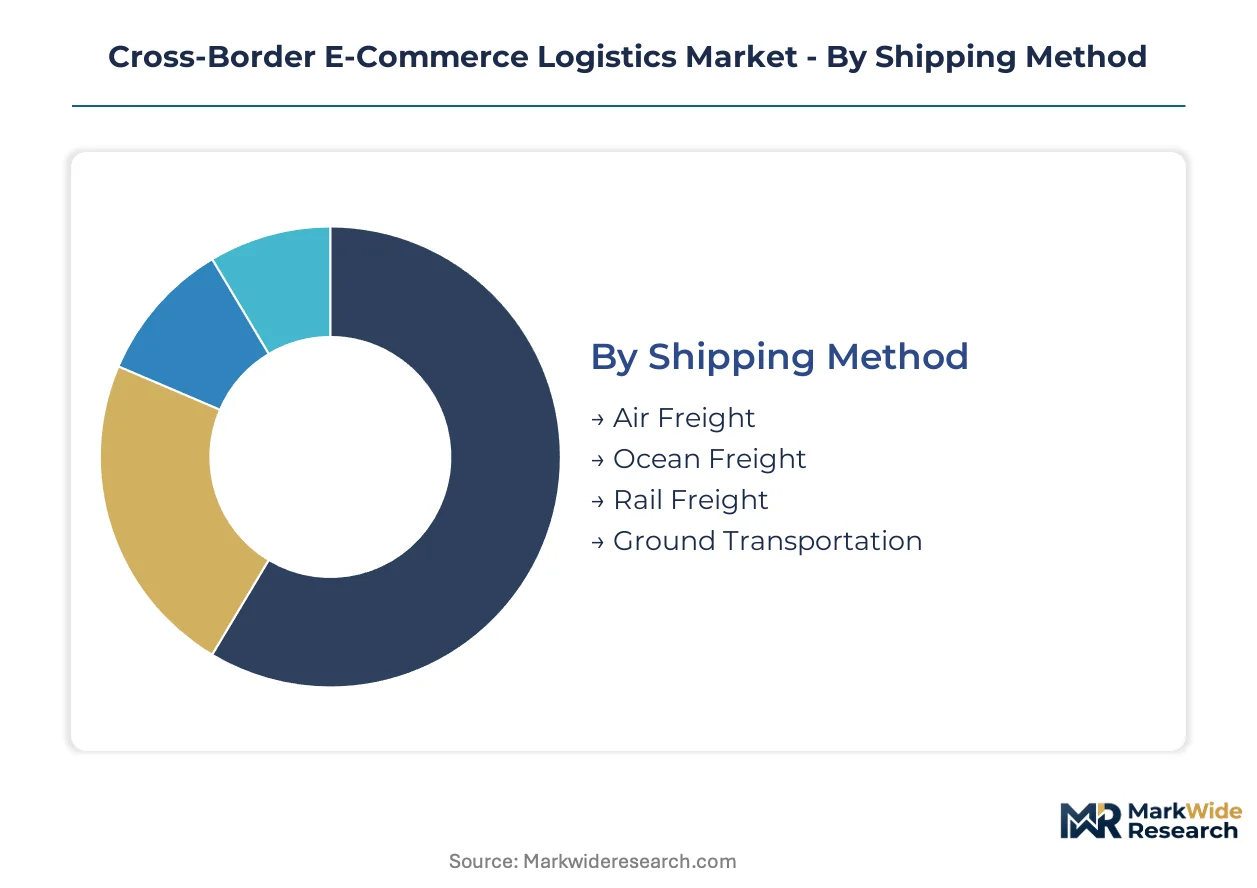
Cross-border e-commerce logistics segments diverge sharply in after-sales intensity. Returns processing, warranty fulfillment, and customer service touchpoints vary by shipping method and service tier, directly shaping margin structures and technology investments across operator portfolios.
Shipping Method:
After-sales service intensity escalates with delivery speed commitments, creating tiered liability exposure across modal choices.
- Air Freight:Temperature-controlled and time-definite cargo movements dominate high-value electronics and perishable goods. Pharmaceutical exporters from Switzerland and fashion retailers in Italy concentrate demand here, driven by shelf-life compression and inventory carrying cost minimization. Express carriers absorb full liability for delivery failures, embedding premium pricing.
- Ocean Freight:Consolidated container loads and less-than-container options service non-urgent e-commerce with extended transit windows. Furniture merchants from Vietnam and bulk apparel shippers in Bangladesh favor this mode, constrained by port congestion variability and customs examination delays at destination.
- Rail Freight:Block train services along China-Europe corridors balance speed and cost for mid-value consumer goods. Electronics assemblers in Chengdu leverage this lane to bypass air freight surcharges.
- Ground Transportation:Cross-border trucking and courier networks handle intra-regional flows with flexible routing. Mexican manufacturers serving US e-commerce platforms depend on bonded trucking for just-in-time replenishment.
By volume, ocean freight leads. By growth pace, rail freight between China and Europe is expanding most quickly.
Service Type:
Margin capture stratifies across service tiers, with value-added functions commanding disproportionate returns relative to commoditized transport.
- Express Delivery:Time-guaranteed door-to-door movements with proactive exception management and dedicated customer service channels. Luxury cosmetics brands in France and premium electronics sellers in South Korea require this tier, constrained by fuel surcharge volatility and last-mile density requirements in suburban zones.
- Standard Delivery:Deferred transit with consolidated handling and extended delivery windows. Mid-market apparel merchants in Turkey and homeware exporters in Poland optimize cost here, accepting 7-14 day transit trade-offs.
- Warehousing:Bonded storage, pick-and-pack, and inventory positioning near consumption markets. Pre-positioned stock strategies near Rotterdam and Dubai reduce customs clearance exposure for seasonal demand spikes.
- Customs Clearance:Documentation preparation, duty calculation, and regulatory compliance brokerage. Specialized providers with ICS2 filing capabilities capture premium fees as EU pre-arrival mandates tighten.
Standard delivery moves the most units. Express delivery claims the steepest expansion trajectory as consumer tolerance for delay shrinks.
Package Type:
Physical handling requirements and damage liability scale with shipment dimensions, reshaping infrastructure investments.
- Parcel:Individual consumer shipments under 30 kilograms with barcode-level tracking. Direct-to-consumer electronics from Shenzhen and cosmetics from Seoul flow through automated sortation hubs.
- Pallet:Unitized loads for business-to-business replenishment with forklift handling requirements. Industrial component distributors in Germany utilize this format for consolidated cross-border stocking.
- Container:Full and partial container loads for high-volume shippers with dedicated space commitments. Furniture aggregators in Vietnam secure ocean capacity through annual service contracts.
- Document:Time-critical paper shipments with minimal customs complexity. Legal and financial services firms in Singapore and London maintain dedicated courier relationships for original instrument delivery.
Parcel volume dominates shipment counts. Container movements gain share fastest as merchants scale direct import models.
End User:
Procurement sophistication and logistics technology adoption vary sharply across buyer categories, fragmenting service requirements.
- Retailers:Omnichannel merchants with inventory synchronization needs across online and physical channels. Department store chains in Japan and marketplace sellers in Brazil invest in integrated visibility platforms.
- Wholesalers:Volume aggregators with consolidated purchasing power and standardized routing preferences. Industrial supply distributors in the Netherlands negotiate annual rate agreements across multiple origin markets.
- Manufacturers:Vertical integrators controlling upstream production and downstream distribution. Electronics OEMs in Taiwan manage component inbound and finished goods outbound through captive logistics operations.
- Entrepreneurs:Small-scale cross-border sellers with sporadic shipment patterns and limited compliance expertise. Individual merchants on global marketplace platforms depend on freight forwarder bundling services for customs navigation.
Retailers generate the highest absolute logistics spend. Entrepreneur segment growth is climbing the fastest as platform barriers to cross-border selling fall.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement of consumer protection rules on cross-border platform sales anchors China's regulatory framework for international e-commerce logistics. Divergent de minimis thresholds across jurisdictions force complex routing arbitrage that fragments network efficiency while reshaping carrier investment priorities.
China
Shenzhen and Guangzhou manufacturing clusters generate concentrated export volumes for fashion and electronics categories. SAMR mandates product labeling and recall liability for cross-border platform sales, tightening compliance requirements for origin-side merchants. Pearl River Delta logistics hubs are expanding bonded warehousing capacity to support pre-positioned inventory strategies for European and North American demand spikes.
Germany
Industrial component distributors and automotive parts suppliers drive demand for consolidated cross-border replenishment. REACH chemical compliance requirements for consumer goods entering the European Economic Area force origin-side testing investments that reshape supplier qualification. Rotterdam-adjacent warehousing complexes serve as pre-positioning nodes for seasonal inventory surges into German last-mile networks.
United States
Mexican manufacturers serving US e-commerce platforms depend on bonded trucking for just-in-time replenishment across the southern border. FDA and CBP maintain strict documentation requirements for consumer goods imports, favoring integrated operators with captive customs brokerage capabilities. Los Angeles and Long Beach port complexes face congestion variability that pushes time-sensitive shippers toward air freight alternatives.
United Arab Emirates
Dubai anchors price-sensitive Middle East-Africa corridors where legacy carriers carry heavier cost structures than regional specialists. MOHAP and Dubai Customs enforce pharmaceutical and consumer goods import standards that require specialized compliance expertise. Jebel Ali free zone warehousing is capturing merchant spend for returns management infrastructure currently lost to postal monopolies.
Netherlands
Rotterdam and Amsterdam distribution hubs concentrate European inbound e-commerce flows requiring customs clearance and last-mile injection. ICS2 pre-arrival declaration mandates accelerate carrier consolidation as smaller forwarders lack IT infrastructure for automated filing. Eindhoven-adjacent logistics parks are expanding SKU-level track-and-trace capabilities for pre-positioned inventory strategies.
Cross-Border E-Commerce Logistics Market Vendor Landscape
Integrated express networks and digital freight forwarders split the market along service-tier lines. DHL, FedEx, and UPS anchor premium express lanes with proprietary customs brokerage, while Flexport and similar platforms capture price-sensitive volume through algorithmic rate discovery. Three archetypes dominate: legacy integrators with hub-and-spoke infrastructure, asset-light digital forwarders with API-first customer interfaces, and regional specialists with corridor-specific density. Competitive moves concentrate on customs technology licensing and last-mile partnership networks.
Among integrated carriers, DHL, FedEx, and UPS exemplify the hub-architecture archetype with European and North American infrastructure dominance. Flexport represents the digital-forwarder tier with technology-native customer acquisition. Aramex anchors the regional-specialist position on Middle East-Africa corridors where cost structures favor lighter asset bases. DB Schenker and Kuehne + Nagel occupy hybrid positions combining forwarding scale with customs brokerage depth.
| Leading Market Players |
|---|
| Spring Global Delivery Solutions |
| UPS |
| DHL |
| Kuehne + Nagel |
| Flexport |
| Aramex |
| FedEx |
| DB Schenker |
| Asendia |
| Others |
Supply Flow & Price Mechanics
Shenzhen's export manufacturing clusters generate concentrated outbound capacity that compresses pricing power for fragmented forwarders while amplifying margin capture for integrated carriers with captive customs brokerage networks. Pearl River Delta logistics hubs feed pricing stratification across express, standard, and deferred delivery tiers as merchants arbitrage between speed commitments and landed cost preservation.
Pricing Analysis
Asia-Europe price spreads of three-to-fivefold separate premium express lanes from ocean-deferred alternatives, with air freight surcharges amplifying volatility during jet fuel spikes. Three-tier pricing structure across premium express, standard deferred, and economy postal handoffs segments buyer archetypes by inventory carrying cost tolerance. Cost compression in standard delivery tiers intensifies because merchant procurement teams consolidate volume through freight forwarder bidding platforms. Small-scale marketplace sellers exhibit highest price sensitivity, while luxury cosmetics brands absorb premium express rates without volume elasticity.
Supply Chain Analysis
Upstream feedstock of bonded warehouse capacity, customs brokerage licenses, and last-mile injection points concentrates in China, Netherlands, and United Arab Emirates. Jet fuel, container slot allocations, and sorting automation equipment anchor variable cost structures across modal choices. Single-source vulnerability runs through Pearl River Delta export clusters where ICS2 pre-declaration mandates favor operators with automated filing infrastructure. Distribution feeds from origin-side manufacturing through bonded transit hubs into destination-market last-mile partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ICS2 compliance investments create irreversible scale advantages for integrated operators with proprietary customs technology.
For Market Incumbents: Insulate core express lanes by embedding SKU-level track-and-trace capabilities into merchant ERP systems, raising switching costs for platform-dependent sellers. Acquire specialized ICS2 filing talent pools before customs brokerage scarcity accelerates wage inflation. Digital freight forwarders threaten margin compression through algorithmic rate discovery; defend by licensing customs automation technology to mid-market forwarders as a revenue layer. For New Entrants and Emerging Players: Establish a beachhead in returns management infrastructure near Dubai and Lagos where postal monopolies currently capture merchant reverse logistics spend. Target Middle East-Africa corridors with asset-light operating models that undercut European carrier cost structures. Deploy API-first customer interfaces targeting Shenzhen-based electronics sellers balancing platform dependency against independent logistics procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent de minimis thresholds across jurisdictions perpetuate routing complexity that favors specialized compliance operators. Acquisition targets should display captive customs brokerage depth with ICS2 filing capabilities. Watch for ICS2 enforcement tightening as the inflection signal indicating accelerated carrier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Technology Licensing | Monetizes ICS2 compliance infrastructure through SaaS fees from mid-market forwarders lacking automation. |
| Returns Infrastructure Buildout | Captures merchant reverse logistics spend currently lost to postal monopolies in Dubai and Lagos corridors. |
| Ocean-Air Multimodal Integration | Compresses unit costs for non-urgent e-commerce while preserving delivery predictability through hybrid routing. |
| ERP System API Connectivity | Raises switching costs for platform-dependent sellers by embedding inventory visibility into merchant workflows. |
| Specialized Compliance Talent Acquisition | Preempts customs brokerage scarcity before ICS2 mandates accelerate specialized expertise demand. |
Methodological Framework
A standing panel of customs brokerage directors, cross-border platform logistics managers, and bonded warehouse operators provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through WTO trade facilitation documentation, EU ICS2 regulatory filings, and customs authority enforcement notices. Bottom-up shipment volume modeling triangulated against top-down carrier capacity disclosures to anchor market size estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning shipping method, service tier, package type, and end-user procurement sophistication. CAGRs derived from curve-fitting historical volume trajectories against announced capacity expansions at Rotterdam, Jebel Ali, and Pearl River Delta hubs. Jet fuel price elasticity and ICS2 compliance cost pass-through rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, cross-border tariff regimes, or air freight fuel surcharges would shift the trajectory. Forecasts reflect documented assumptions about customs pre-arrival mandate adoption timelines and merchant inventory pre-positioning behavior. Cross-checking against carrier quarterly capacity disclosures and customs authority enforcement priority statements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
Pharma E-Commerce Market