
 US Customer Relationship Management Market | 2026-2036
US Customer Relationship Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Customer Relationship Management Market Intelligence
Enterprise-grade AI orchestration is redrawing competitive boundaries in the US CRM landscape. Salesforce.com, Inc. leverages its native Einstein AI layer to anchor premium positioning across sales automation and service clouds. Microsoft Corporation extends its CRM reach through deep Azure integration and Teams-native workflows that dominate enterprise productivity stacks. Oracle Corporation competes on database-to-application continuity, sustaining appeal among manufacturing and financial services buyers with complex data sovereignty requirements.
Customer relationship management software comprises integrated applications for tracking interactions, managing pipelines, and automating engagement workflows across sales, marketing, and service functions, typically deployed via multi-tenant cloud architectures with API extensibility for enterprise system interoperability. Cloud-based deployment leads structural growth as vendors retire on-premise maintenance streams and buyers prioritize subscription elasticity over capital-intensive infrastructure ownership. Among end-user verticals, financial services and healthcare represent the most contested margin pools, with compliance-ready configurations commanding pricing premiums over standard retail implementations. Small and medium enterprises constitute the fastest-expanding size tier, though large enterprises still absorb the majority of solution-specific revenue through multi-module contracts spanning sales automation, marketing automation, and analytics.
The Federal Trade Commission scrutinizes data brokerage and consent mechanisms embedded in CRM platforms, while state-level frameworks such as the California Consumer Privacy Act and emerging legislation in Virginia and Colorado impose granular requirements on cross-border data flows and deletion protocols. The Securities and Exchange Commission further shapes demand among publicly traded CRM buyers through disclosure rules governing customer data incident reporting. Stakeholders must monitor the divergence between federal preemption debates and patchwork state enforcement to anticipate compliance cost trajectories and platform architecture roadmaps.
Market Dynamics
Enterprise AI orchestration is compressing sales cycles and forcing vendors to rebuild core architectures around predictive inference engines rather than static workflow automation.
Growth Catalysts
- CCPA Compliance Mandates:California's data governance framework pressures financial services and healthcare buyers to replace legacy systems with privacy-embedded CRM stacks, accelerating replacement cycles.
- Predictive Analytics Convergence:Machine learning pipelines for churn prediction and lead scoring are becoming table stakes in Texas and New York B2B sales environments.
- Healthcare Vertical Expansion:Patient engagement regulations and value-based care models drive hospital systems toward integrated CRM-service cloud deployments.
Market Restraints
- Data Residency Fragmentation:Divergent state-level privacy laws create architectural complexity for multi-state enterprises, inflating implementation costs.
- Cloud Infrastructure Concentration:Reliance on hyperscale compute providers limits vendor negotiating leverage and creates single-point vulnerabilities.
- Legacy System Entrenchment:Decades of on-premise customization in manufacturing and government segments slows cloud migration timelines.
Strategic Opportunities
- Mid-Market White Space:SMB segments in Florida and Georgia show CRM penetration gaps of 40-plus points versus large enterprises, offering expansion runway.
- FTC Consent Architecture:Proactive data brokerage compliance tools position vendors for premium pricing as regulatory scrutiny intensifies.
- Voice-CRM Integration:Natural language interfaces for sales call transcription and sentiment analysis open new workflow automation categories.
Industry Challenges
- AI/ML Talent Scarcity:Shortage of engineers capable of deploying production-grade predictive models delays customer go-live dates.
- Multi-Cloud Integration Complexity:Enterprises running hybrid Azure-AWS-GCP environments demand seamless CRM interoperability that strains vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Customer Relationship Management Market |
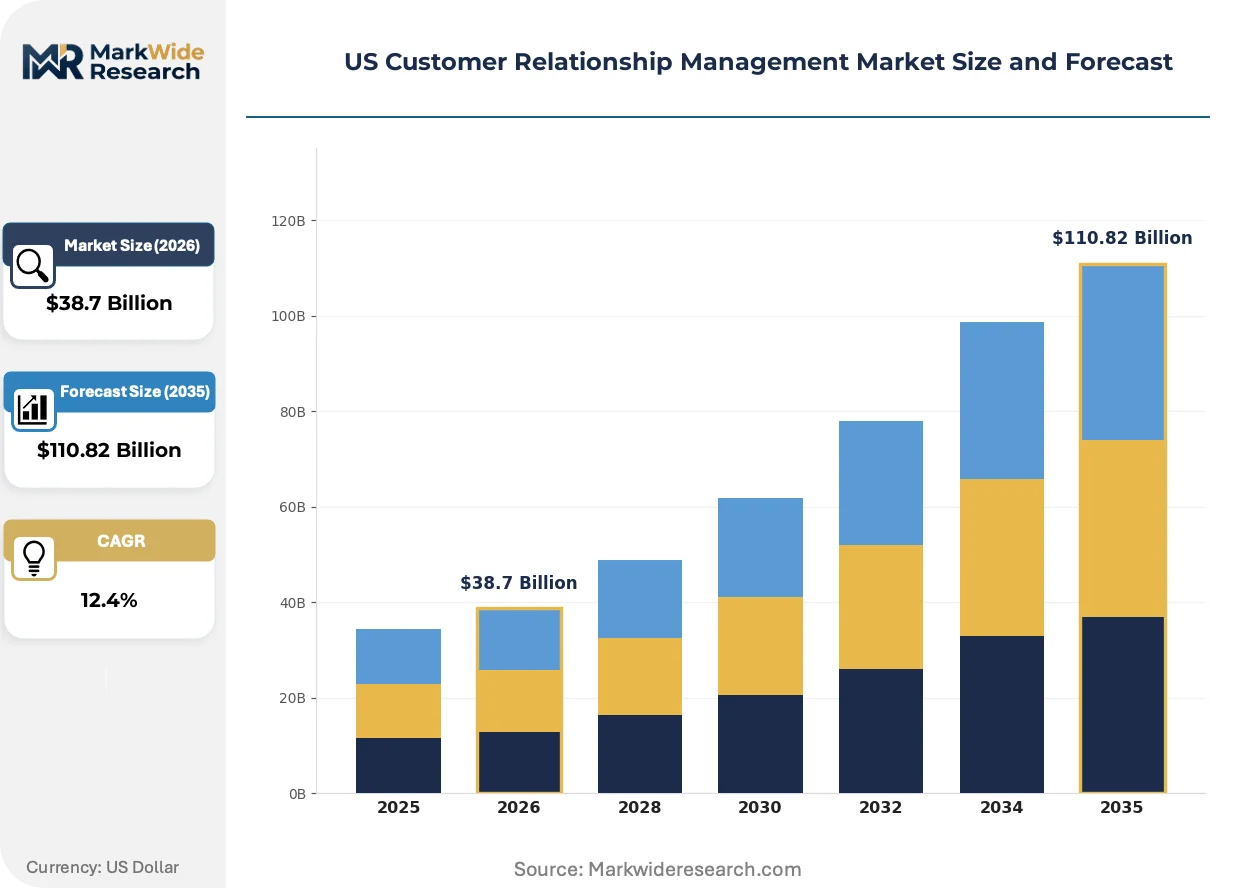
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $110.82 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Services End User: Retail, Healthcare, Financial Services, Manufacturing Solution: Sales Automation, Marketing Automation, Customer Service, Analytics Size: Small Businesses, Medium Enterprises, Large Enterprises, Startups |
| Companies Covered | Salesforce.com, Inc., Microsoft Corporation, Oracle Corporation, SAP SE, Adobe Systems Inc., HubSpot Inc., Zoho Corp., IBM, Genesys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Customer Relationship Management Market Strategic Shifts & Innovations
Agentic AI systems are rewriting automation boundaries across sales and service functions, compressing the gap between insight generation and autonomous execution.
Generative AI for sales content creation is supplanting template-based email and proposal tools. Mid-market SaaS buyers in Illinois and Ohio are deploying these systems within six-month procurement windows. The shift is collapsing content production cycles from days to minutes and redrawing competitive differentiation around inference speed.
SEC disclosure rules governing customer data incident reporting are tightening accountability structures for publicly traded CRM buyers. Financial services firms now embed real-time breach notification workflows into platform specifications. The requirement is accelerating demand for audit-ready logging architectures in New York and Connecticut.
Subscription elasticity preferences are displacing perpetual license retention among state government buyers. Procurement officers in Virginia and Colorado now prioritize usage-based pricing with annual true-up provisions. The pattern is most visible in education and municipal healthcare verticals where budget volatility demands cost predictability.
US Customer Relationship Management Market Segmentation
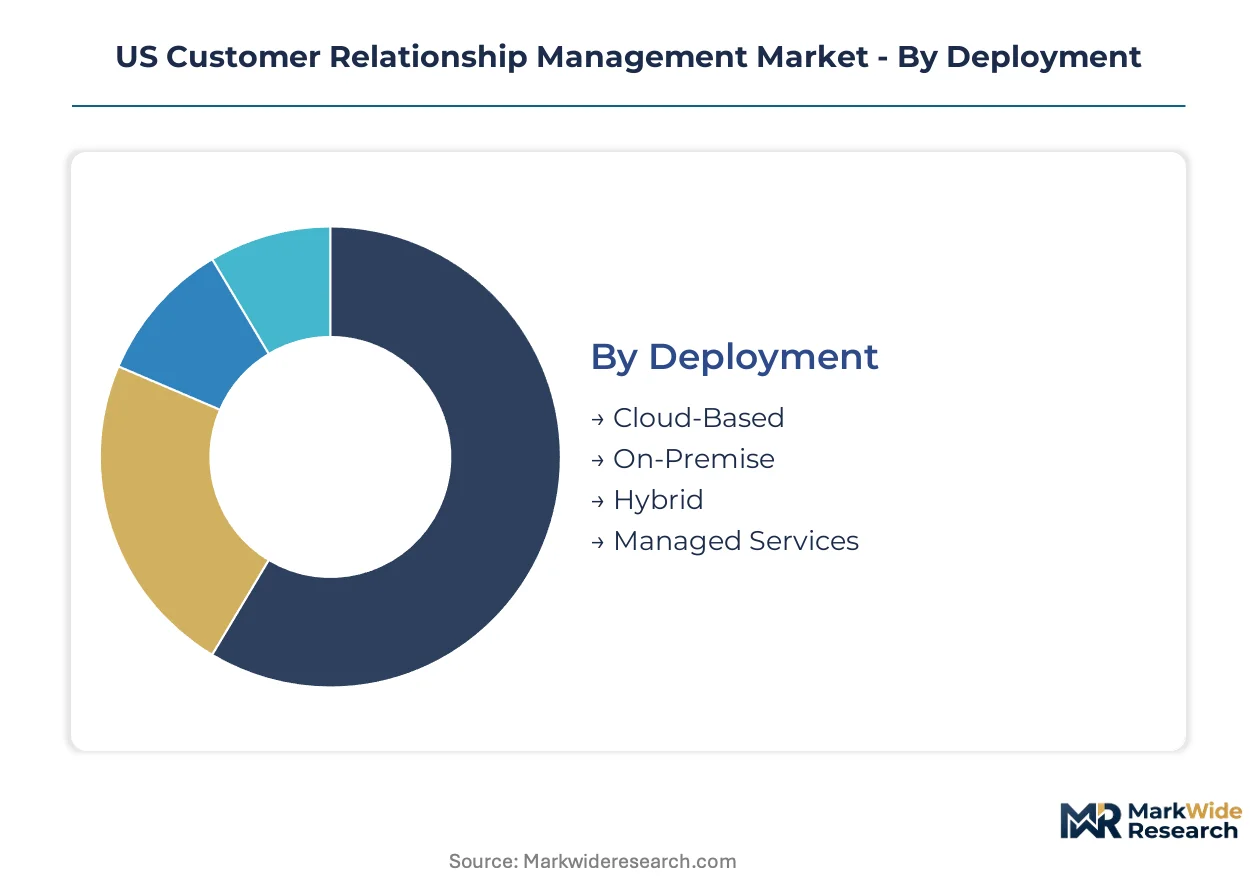
CRM segmentation in the US market reveals distinct margin architectures across deployment models, vertical applications, and enterprise tiers. Vendors optimize pricing and feature depth by matching platform complexity to buyer sophistication and regulatory exposure.
Deployment:
Cloud-based configurations command premium pricing in Texas and New York financial services hubs where elasticity and rapid scaling offset compliance overhead.
- Cloud-Based:Multi-tenant SaaS architectures with API extensibility dominate new procurement. Financial services firms in Manhattan and Dallas prioritize subscription elasticity over capital expenditure, accepting higher per-seat costs for zero infrastructure ownership.
- On-Premise:Legacy installations with dedicated hardware persist in defense contracting and classified government environments. Manufacturing plants in Michigan and Ohio retain these stacks for air-gapped operational technology integration despite rising maintenance burdens.
- Hybrid:Split architectures synchronize sensitive customer records on-premise with marketing automation in public cloud. Healthcare systems in California deploy this model to isolate HIPAA-protected data while leveraging cloud analytics.
- Managed Services:Third-party operated deployments with vendor-assigned infrastructure teams. State government buyers in Virginia and Colorado favor this option where internal IT capacity constraints limit self-management.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are gaining share fastest as regulated verticals seek architectural compromise.
End User:
Vertical specialization determines pricing power, with compliance-heavy sectors absorbing 40-60% premiums over standard retail implementations.
- Financial Services:Banks, insurers, and wealth managers require SEC-audit-ready logging and real-time breach notification workflows. New York and Connecticut buyers specify these features in procurement, accepting elevated per-seat costs for regulatory insulation.
- Healthcare:Hospital systems and payers integrate CRM with electronic health records for patient engagement. Value-based care mandates in California and Massachusetts drive demand for predictive readmission risk scoring embedded in service clouds.
- Retail:Omnichannel engagement platforms unify e-commerce and physical store interactions. Midwest retail chains prioritize inventory-aware recommendation engines over deep compliance tooling.
- Manufacturing:Complex B2B sales cycles with long lead times require configure-price-quote automation. Industrial equipment sellers in Illinois and Ohio emphasize partner portal functionality and distributor incentive management.
Financial Services captures the dominant revenue share, though Healthcare is expanding most quickly as patient engagement regulations tighten.
Solution:
Module bundling patterns reveal buyer maturity, with multi-module contracts generating 3-4x revenue per customer versus single-function deployments.
- Sales Automation:Pipeline management, forecasting, and mobile field access form the core CRM entry point. Texas energy sector buyers demand predictive lead scoring integrated with commodity price volatility feeds.
- Marketing Automation:Campaign orchestration, journey mapping, and attribution modeling. Illinois and Ohio mid-market SaaS firms deploy generative AI content tools within compressed six-month procurement windows.
- Customer Service:Case management, knowledge bases, and omnichannel support routing. Healthcare providers in Florida prioritize voice-CRM integration for call transcription and sentiment analysis.
- Analytics:Predictive churn modeling, customer lifetime value calculation, and executive dashboards. Large enterprises in Georgia specify real-time inference pipelines as table stakes for renewal negotiations.
Sales Automation retains the dominant installed base, while Analytics modules are climbing the fastest as AI orchestration becomes competitive necessity.
Size:
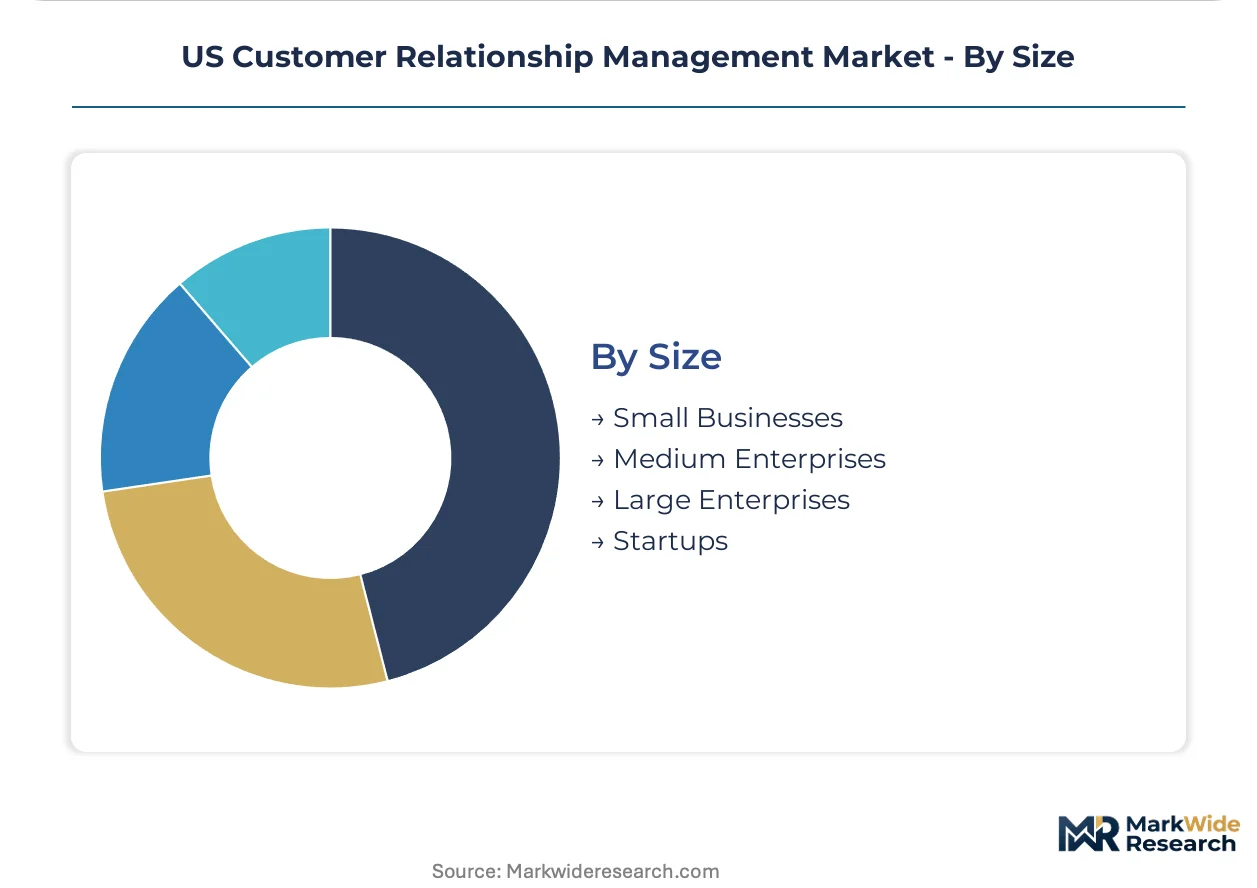
Enterprise scale dictates contract structure, with large buyers extracting volume discounts that compress vendor margins despite absolute dollar growth.
- Large Enterprises:Multi-divisional deployments spanning sales, marketing, and service clouds with custom integration requirements. Fortune 500 headquarters in New York and California negotiate three-year enterprise agreements with annual true-up provisions.
- Medium Enterprises:Single-platform standardization with limited customization and rapid implementation timelines. Regional healthcare networks in North Carolina and Arizona represent the fastest-expanding addressable pool.
- Small Businesses:Out-of-box configurations with template workflows and minimal IT support. Florida and Georgia show penetration gaps exceeding 40 points versus large enterprises, offering expansion runway.
- Startups:Freemium-to-paid conversion models with usage-based scaling. Venture-backed technology firms in Austin and Boston prioritize rapid deployment over deep feature depth.
Large Enterprises absorb the majority of solution-specific revenue, though Medium Enterprises are closing the gap fastest as vendor sales motions downmarket mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CRM market operates as a net exporter of software services, with domestic vendors licensing platforms internationally while importing specialized AI infrastructure components. Trade flows concentrate through California and Washington technology corridors, creating regional specialization in cloud delivery versus hardware acceleration.
California
Silicon Valley hyperscalers anchor enterprise AI development, with San Francisco and San Jose hosting concentrated engineering talent pools. The California Consumer Privacy Act mandates granular data deletion protocols that reshape platform architecture roadmaps. Healthcare systems in Los Angeles deploy hybrid cloud configurations to isolate HIPAA-protected patient records while leveraging cloud analytics capabilities.
Texas
Dallas and Houston energy sector buyers demand predictive lead scoring integrated with commodity price volatility feeds, compressing sales automation procurement cycles. State procurement frameworks emphasize usage-based pricing with annual true-up provisions for municipal healthcare and education verticals. Austin venture-backed technology firms prioritize rapid CRM deployment over deep feature customization, driving freemium-to-paid conversion models.
New York
Manhattan financial services firms specify SEC-audit-ready logging and real-time breach notification workflows in enterprise procurement, accepting elevated per-seat costs for regulatory insulation. The New York Department of Financial Services cybersecurity regulations extend to third-party CRM vendor oversight. Fortune 500 headquarters negotiate three-year enterprise agreements spanning sales, marketing, and service clouds with custom integration requirements.
Illinois
Chicago manufacturing plants retain on-premise stacks for air-gapped operational technology integration despite rising maintenance burdens. Industrial equipment sellers emphasize partner portal functionality and distributor incentive management for complex B2B sales cycles. Mid-market SaaS buyers in the broader Midwest deploy generative AI content tools within compressed six-month procurement windows.
Florida
Miami healthcare providers prioritize voice-CRM integration for call transcription and sentiment analysis, opening new workflow automation categories. State government buyers favor managed service deployments where internal IT capacity constraints limit self-management. SMB penetration gaps exceeding 40 points versus large enterprises offer vendors expansion runway through template workflow configurations.
US Customer Relationship Management Market Key Industry Players
Listed leaders compete with private specialists across cloud infrastructure depth and vertical compliance specialization. The vendor base stratifies into three tiers: hyperscale platform providers with native AI layers, enterprise application incumbents leveraging database-to-application continuity, and agile cloud-native challengers targeting mid-market white space. Dominant competitive moves include strategic partnerships with hyperscale compute providers and portfolio diversification into adjacent marketing automation and analytics modules.
Within the hyperscale platform tier, Salesforce.com, Inc., Microsoft Corporation, and Oracle Corporation exemplify divergent architectural bets. Salesforce.com, Inc. anchors premium positioning through native Einstein AI integration across sales and service clouds. Microsoft Corporation extends CRM reach through deep Azure integration and Teams-native workflows that dominate enterprise productivity stacks. Oracle Corporation sustains appeal among manufacturing and financial services buyers with complex data sovereignty requirements through database-to-application continuity.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Adobe Systems Inc. |
| HubSpot Inc. |
| Zoho Corp. |
| IBM |
| Genesys |
| Others |
Cost & Logistics Intelligence
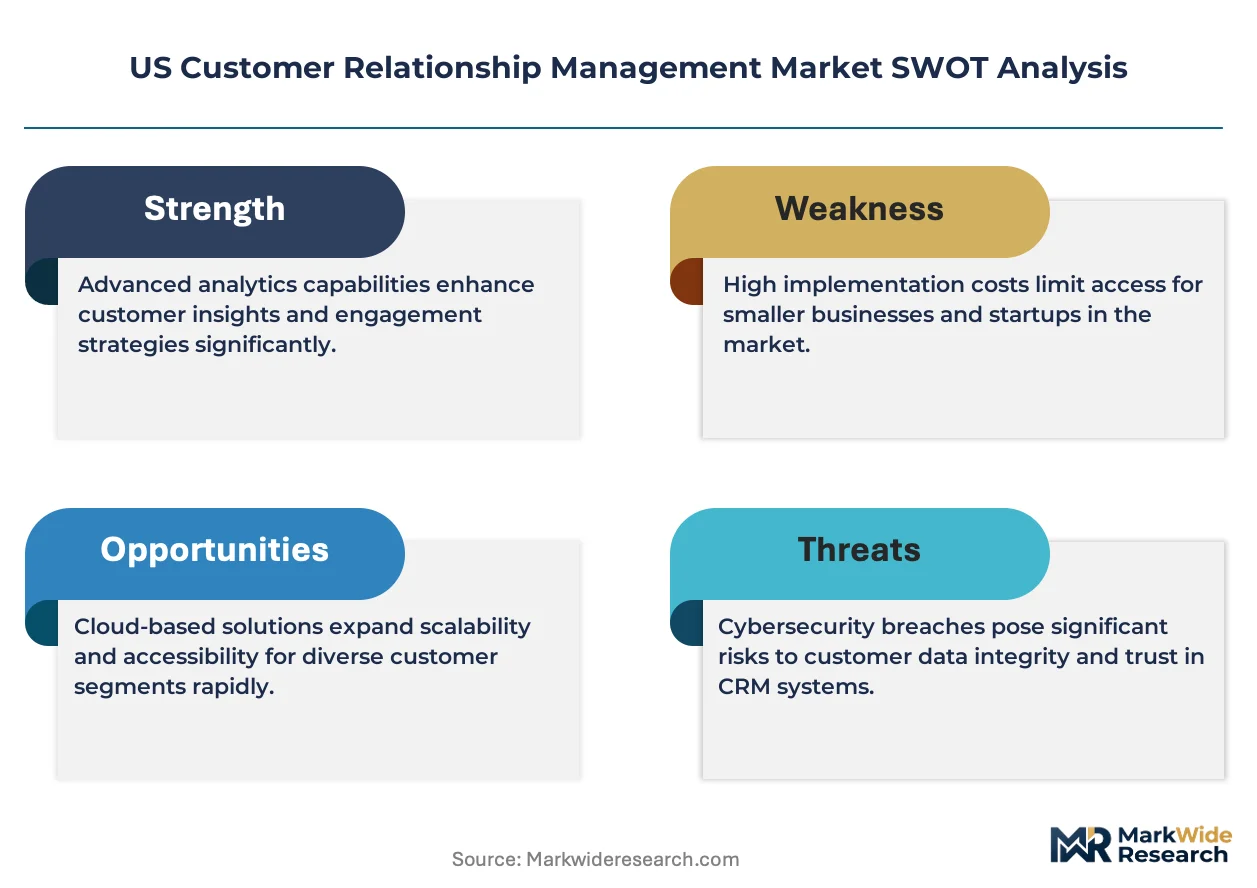
Sixty-to-ninety-day implementation cycles for enterprise CRM deployments concentrate pricing power with hyperscale platform vendors while compressing margins for systems integrators managing multi-cloud configurations. Texas energy sector buyers and Manhattan financial services firms absorb premium per-seat costs for compliance-embedded architectures, whereas Florida and Georgia SMB segments face 40-plus point penetration gaps that force template-based economy positioning.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing across sales automation and service cloud modules, with three-tier pricing structure across premium, standard, and economy levels separating Fortune 500 multi-divisional contracts from mid-market SaaS configurations. Price differentiation rests on HIPAA certification grade and SEC-audit-ready logging depth, with healthcare and financial services verticals absorbing 40-60% premiums over standard retail implementations. Cost compression in the mid-market tier is intensifying because generative AI content tools collapse procurement windows to six months. State government buyers in Virginia and Colorado exhibit highest price sensitivity through usage-based pricing demands, while New York headquarters show lowest sensitivity given regulatory insulation requirements.
Supply Chain Analysis
Azure, AWS, and GCP hyperscaler concentration in Washington and California underwrites infrastructure cost structures for multi-tenant SaaS architectures. Taiwan semiconductor fabrication, South Korean memory module production, and domestic data center construction in Nevada and Oregon feed hardware dependencies. Single-source vulnerability in GPU acceleration for Einstein AI and comparable inference engines creates procurement bottlenecks. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for SMB conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US CRM market sits in early-cycle recovery as Federal Trade Commission consent order activity accelerates replacement demand among data-brokerage-dependent financial services incumbents.
For Market Incumbents: Fortify compliance architecture moats through embedded CCPA deletion protocol automation and real-time SEC breach notification workflows. Acquire voice-CRM transcription specialists to block natural language interface commoditization. Prioritize Azure-GCP interoperability engineering to reduce multi-cloud integration friction for hybrid enterprise buyers. For New Entrants and Emerging Players: Lead with generative AI sales content tools targeting Illinois and Ohio mid-market SaaS firms where six-month procurement windows reward rapid deployment. Exploit Florida and Georgia SMB white space through template workflow configurations priced below Salesforce Einstein tiers. Pursue channel partnerships with managed service providers serving Virginia and Colorado state government buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy on-premise vendors in Michigan and Ohio manufacturing corridors where cloud migration delays create distressed asset opportunities. Five-to-ten year viability hinges on AI orchestration depth rather than workflow automation breadth. Monitor FTC consent decree volume as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Agentic AI Platform Integration | Autonomous execution capabilities compress sales cycles for Texas energy sector buyers. |
| CCPA Compliance Architecture Certification | California healthcare systems prioritize HIPAA-isolated hybrid cloud configurations. |
| Voice-CRM Transcription Acquisition | Florida hospital systems demand sentiment analysis for patient engagement workflows. |
| Mid-Market Template Standardization | Georgia SMB penetration gaps exceed 40 points versus large enterprise adoption. |
| Hyperscaler Partnership Deepening | Azure-native Teams workflows dominate New York Fortune 500 productivity stacks. |
Research Approach
Cross-validation between CTO interviews at Texas energy firms and SEC 10-K disclosure analysis anchors the qualitative findings. Primary fieldwork encompassed CRM procurement officers, platform integration specialists, healthcare IT directors, and state government technology chiefs across California, Texas, New York, and Illinois. Secondary sources included hyperscaler capex disclosures, FTC consent order databases, and Gartner enterprise software spending surveys. Bottom-up deployment estimates and top-down vertical spending allocations underwent iterative reconciliation.
Sensitivity analysis across deployment model, organization size, vertical compliance exposure, and regional adoption pattern shaped the analytical framework. Modeled segmentation spanned cloud-based, on-premise, hybrid, and managed service configurations crossed with financial services, healthcare, retail, and manufacturing end users. CAGRs derived from trend extrapolation of subscription elasticity preferences and AI module attach rates. Forecast inputs incorporated CCPA enforcement trajectory and SEC disclosure rule tightening timelines.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler infrastructure investment or FTC enforcement acceleration would require recalibration. Forecasts reflect documented assumptions regarding generative AI adoption curves and state-level privacy law divergence. Practitioners should keep alternative scenarios live as Federal Trade Commission consent mechanisms and state attorney general enforcement priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market