
 Construction Toys Market | 2026-2036
Construction Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Toys Market Intelligence
The substitution of traditional petroleum-based plastics with recycled and bio-derived polymers is recalibrating production costs and brand perception. This shift addresses consumer and regulatory pressure for sustainability. The LEGO Group leverages its significant R&D investment to develop these alternative materials. Meanwhile, Mattel, through its Mega Bloks brand, competes on both licensed intellectual property and material innovation to capture market share.
Construction toys are systems of standardized, interlocking pieces that enable the creation of various models and structures. These toys are defined by their modularity and compatibility, allowing for open-ended, creative play. While traditional plastic building blocks remain a foundational product type, magnetic tiles represent the fastest-growing category, commanding higher price points. The market also segments by age group, with products for preschoolers focusing on larger, simpler components for safety and ease of use.
Product safety and material composition are governed by stringent international standards. Regulations like the EU's Toy Safety Directive and the US Consumer Product Safety Improvement Act (CPSIA) mandate specific testing for chemicals and physical hazards. These frameworks heavily influence material sourcing and manufacturing processes for all market participants. Navigating the dual demands for educational value and sustainable materials will define competitive success for manufacturers.
Market Dynamics
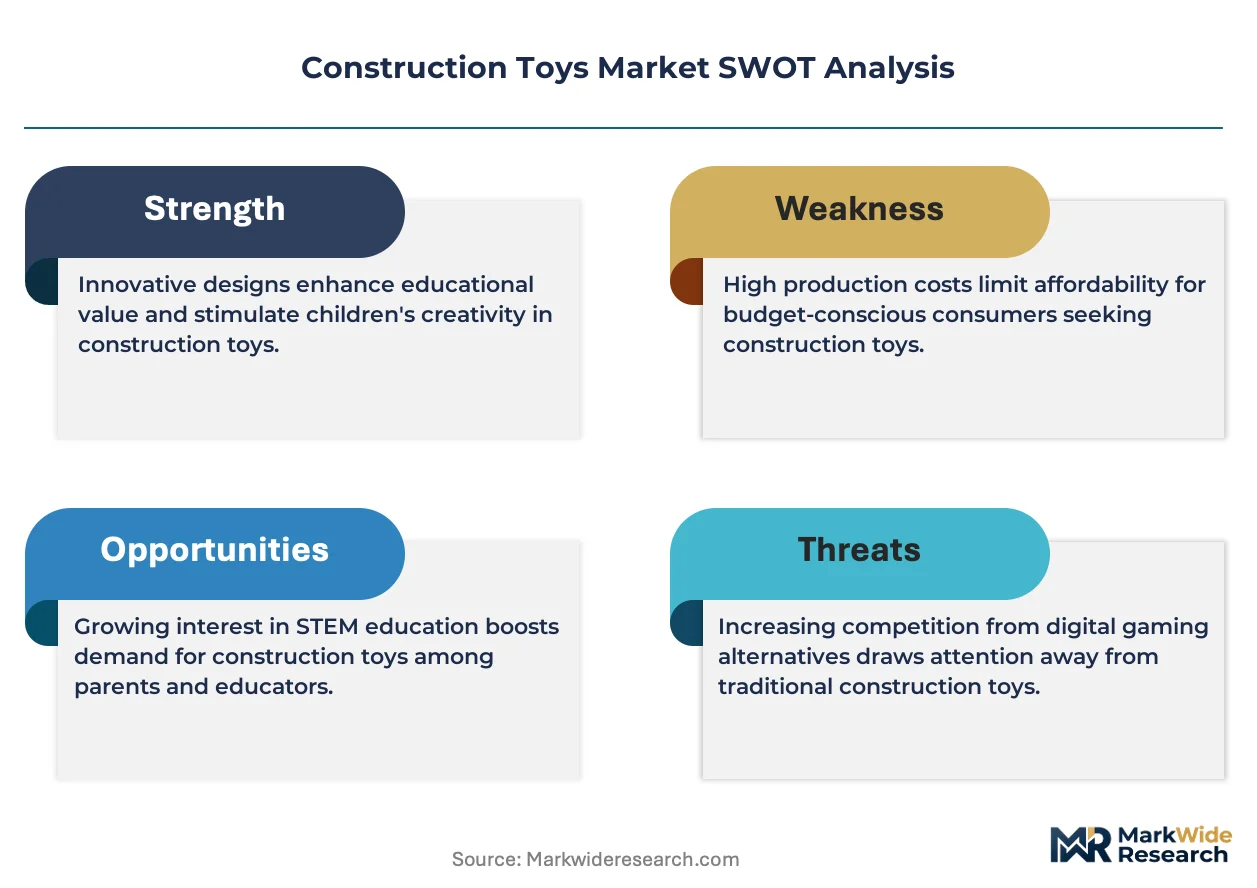
The market's structure is defined by the dual pressure for sustainable material science and rising demand for toys with demonstrable STEM educational value. This dynamic dictates R&D priorities and supply chain sourcing for all manufacturers globally.
Growth Catalysts
- STEM Integration:Government initiatives promoting STEM education in primary schools are creating institutional demand for construction toys as learning aids, particularly in developed economies.
- Rising Disposable Income:In markets like China and India, increasing household incomes and a cultural emphasis on early childhood development are expanding the consumer base for premium construction toys.
- Magnetic Tile Innovation:The expansion of the magnetic tile category, which supports complex 3D building, is attracting new consumers and enabling higher price points compared to traditional blocks.
Market Restraints
- Volatile Polymer Costs:Fluctuation in the price of petroleum, the primary feedstock for traditional ABS plastics, creates cost instability and margin pressure for manufacturers not diversified into alternative materials.
- Stringent Safety Standards:Compliance with multifaceted regulations like the EU's Toy Safety Directive and the US CPSIA adds significant testing costs and lengthens time-to-market, creating barriers for smaller entrants.
- Digital Entertainment Competition:The proliferation of tablets and mobile gaming presents a significant substitution threat, competing directly for children's leisure time and parental spending on play activities.
Strategic Opportunities
- Geriatric and Therapeutic Use:An emerging opportunity exists in using construction toys for cognitive therapy and fine motor skill maintenance in elderly populations and rehabilitation centers, a largely untapped market.
- Augmented Reality Integration:Combining physical building sets with AR applications that animate creations or provide interactive instructions offers a new dimension of play and a path to premium product differentiation.
- Latin American Market Entry:Markets such as Brazil and Mexico show significant underpenetration for premium and educational construction toys, representing a key expansion frontier beyond North America and Europe.
Industry Challenges
- Counterfeit Product Proliferation:The high brand value and simple form factor of popular construction toys make them a prime target for counterfeit manufacturing, eroding brand trust and sales in online marketplaces.
- Sustainable Material Scaling:The transition to bio-polymers and recycled plastics at industrial scale presents technical and supply chain challenges, including ensuring color consistency and clutch power across billions of pieces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Toys Market |
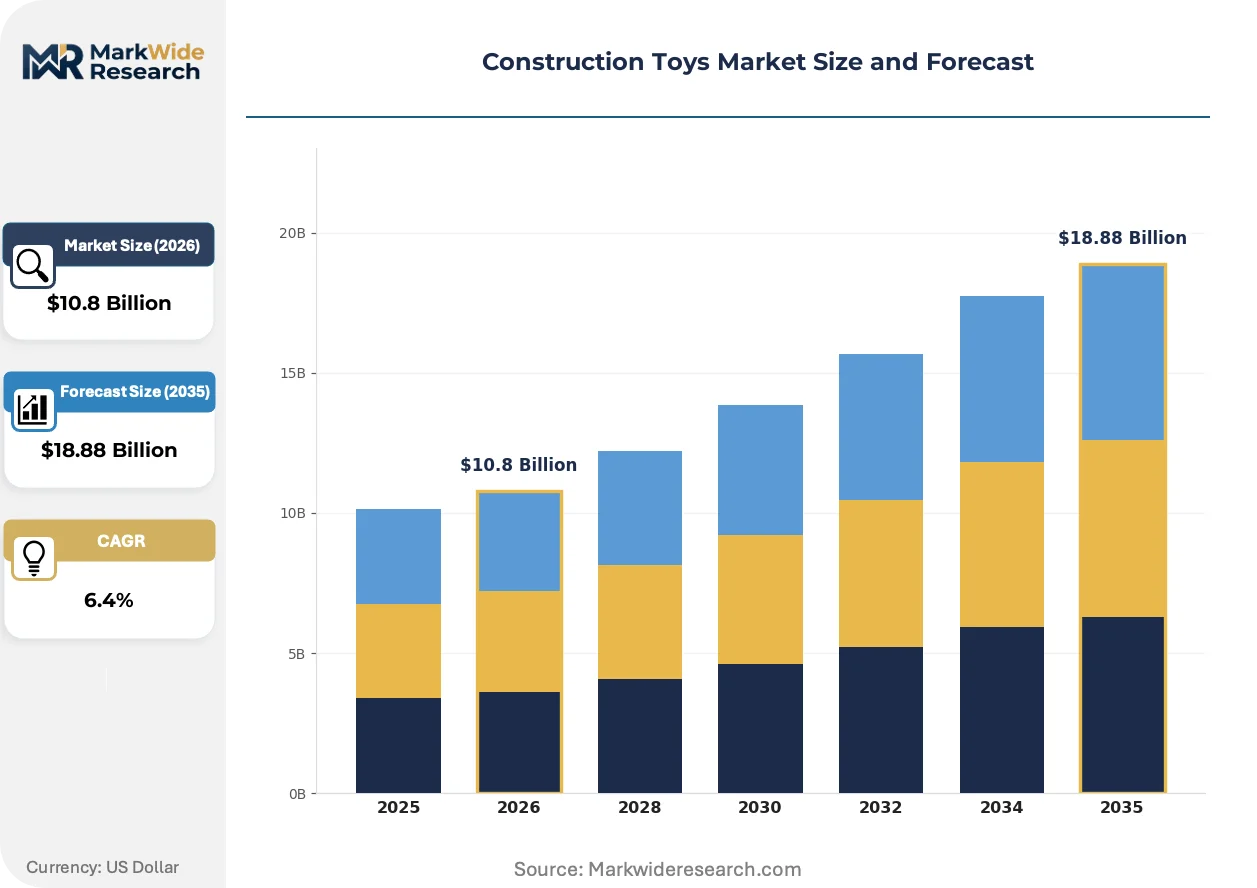
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Blocks, Model Kits, Magnetic Tiles, Construction Sets Age Group: Toddlers, Preschoolers, School Age, Teens Material: Plastic, Wood, Metal, Foam Theme: Space, Vehicles, Architecture, Animals |
| Companies Covered | Magformers, Playmobil, LEGO Group, Spin Master, Mega Bloks, Mattel, Magna-Tiles, BanBao, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Toys Market Strategic Shifts & Innovations
The integration of digital experiences with physical play and the industry-wide pivot towards sustainable materials are fundamentally altering product design. These forces create new product categories while redefining consumer expectations for value and environmental responsibility.
Smart bricks, containing embedded sensors, microcontrollers, or LEDs, introduce interactivity and programmability to traditional building systems. Educational institutions and adult hobbyist segments are early adopters, seeking more complex and responsive building experiences. This technology is converging with app-based coding platforms, transforming static models into simple robotic devices and creating a new 'phy-gital' play pattern.
European Union's Circular Economy Action Plan and related "right to repair" initiatives are influencing toy design beyond immediate safety concerns. These policies pressure manufacturers to design for durability, disassembly, and material recyclability, moving away from single-use or mixed-material components. The preschool segment is most affected, as parents favor brands demonstrating long-term product lifecycles and using easily recycled mono-materials.
A direct-to-consumer (DTC) shift is accelerating, with manufacturers using their own e-commerce platforms to cultivate brand communities and launch exclusive sets. This model bypasses traditional toy retailers, giving brands direct control over pricing, marketing, and customer data collection. The trend is most visible in the adult and collector segments of North America and Europe, where limited edition releases and loyalty programs drive significant DTC sales volume.
Construction Toys Market Segmentation
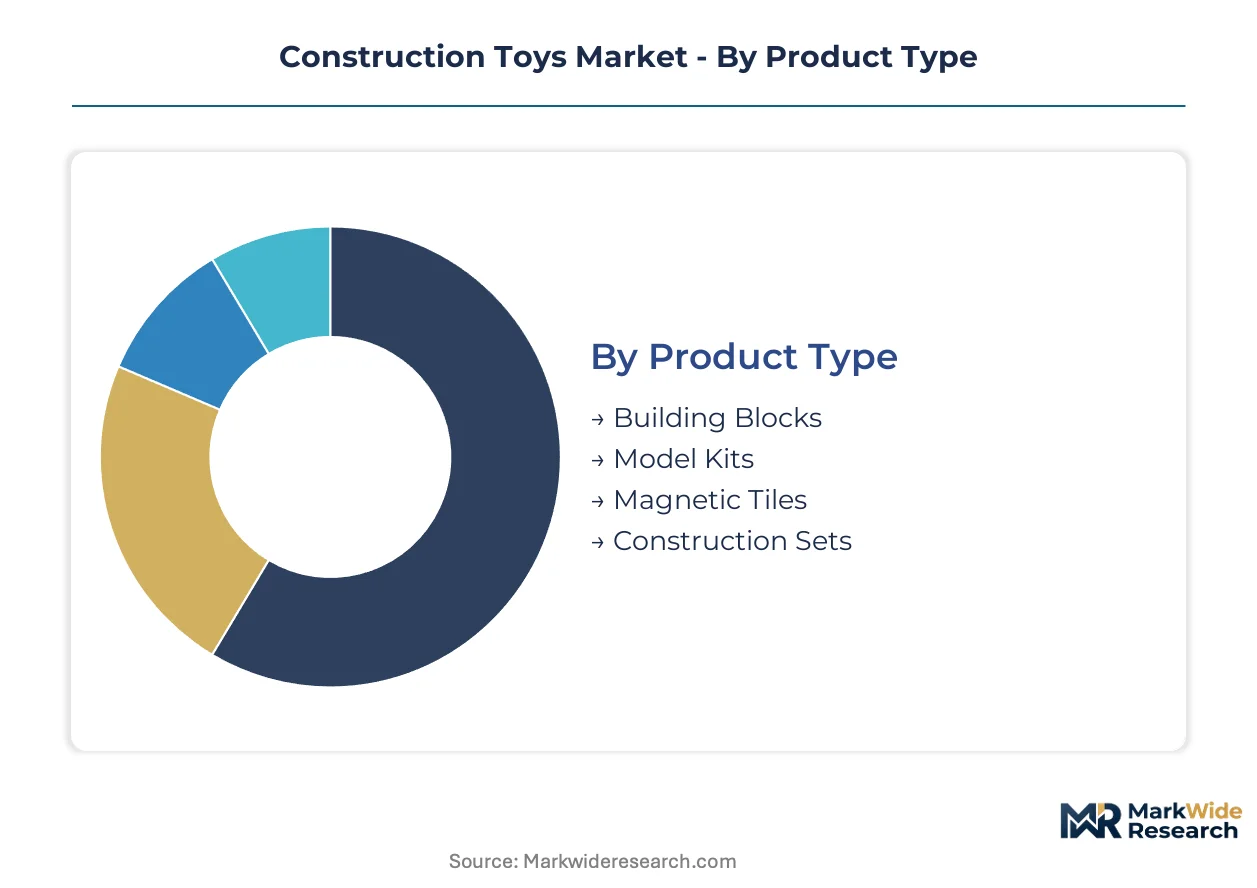
The construction toys market segments into distinct categories, each addressing specific consumer needs and manufacturing complexities. Understanding these divisions helps manufacturers align product development with market demand and regulatory compliance. Each segment carries unique implications for material science, production scale, and distribution strategies.
Product Type:
The capital intensity across construction toy product types varies significantly, driven by tooling costs and material processing requirements.
- Building Blocks:These foundational toys consist of standardized, interlocking plastic pieces, primarily ABS, designed for open-ended creative assembly. Demand for traditional building blocks remains robust, particularly in developed economies where established brands like LEGO maintain strong market presence.
- Model Kits:These sets typically include pre-designed components for constructing specific replicas, often requiring adhesive or more intricate assembly than blocks. Enthusiast communities and hobbyists in North America and Europe drive consistent demand for detailed model kits.
- Magnetic Tiles:Comprising plastic frames with embedded magnets, these toys allow for rapid 2D and 3D construction through magnetic attraction. This category represents the fastest-growing segment, commanding higher price points due to innovative play patterns and strong appeal in educational settings.
- Construction Sets:These often include a mix of components like beams, connectors, and wheels, enabling the creation of functional models or structures. Educational institutions increasingly integrate construction sets into STEM curricula across various countries.
Most installed capacity flows through Building Blocks. Expansion is steepest in Magnetic Tiles.
Age Group:
Customer engagement models for construction toys differ substantially across age groups, reflecting varied developmental needs and play patterns.
- Toddlers:Products for this group feature large, chunky pieces with simple connection mechanisms, prioritizing safety and gross motor skill development. Parents prioritize non-toxic, durable materials for toddlers in markets like Germany and Japan.
- Preschoolers:Toys for preschoolers focus on larger, simpler components, promoting safety and ease of use while introducing basic construction concepts. Educational content and imaginative play are central to product design for this demographic.
- School Age:This segment demands more complex systems, often incorporating themes, detailed instructions, and opportunities for STEM learning. Government initiatives promoting STEM education in the US and China significantly boost demand for school-age construction toys.
- Teens:Products for teens often involve advanced engineering, robotics integration, or highly detailed model building, appealing to hobbyists and collectors. Augmented reality integration is emerging as a differentiation strategy for teen-focused products.
Preschoolers represent a foundational consumer base. The School Age segment consistently drives product innovation.
Material:
Supply chain concentration heavily influences material choices, with petroleum-based plastics dominating volume but bio-derived alternatives gaining traction.
- Plastic:Traditional construction toys predominantly use petroleum-based plastics like ABS, offering durability and precise molding capabilities. Volatile polymer costs create margin pressure for manufacturers reliant on conventional plastic feedstocks.
- Wood:Wooden construction toys are often favored for their natural aesthetic, tactile qualities, and perceived environmental benefits. Brands leveraging sustainable wood sourcing command premium prices from eco-conscious parents in Western Europe.
- Metal:Metal components are typically found in more advanced construction sets or model kits, providing structural integrity and realistic detailing. Adult hobbyists and collectors appreciate the durability and authenticity of metal-based construction.
- Foam:Foam construction pieces are lightweight, soft, and safe for younger children, often used in larger-scale, less intricate building activities. Preschool programs in North America utilize foam blocks for collaborative play environments.
Plastic materials command the largest production volume. Wood is gaining share due to sustainability mandates.
Theme:
Thematic segmentation caters to diverse consumer interests, from broad appeal to niche collector markets.
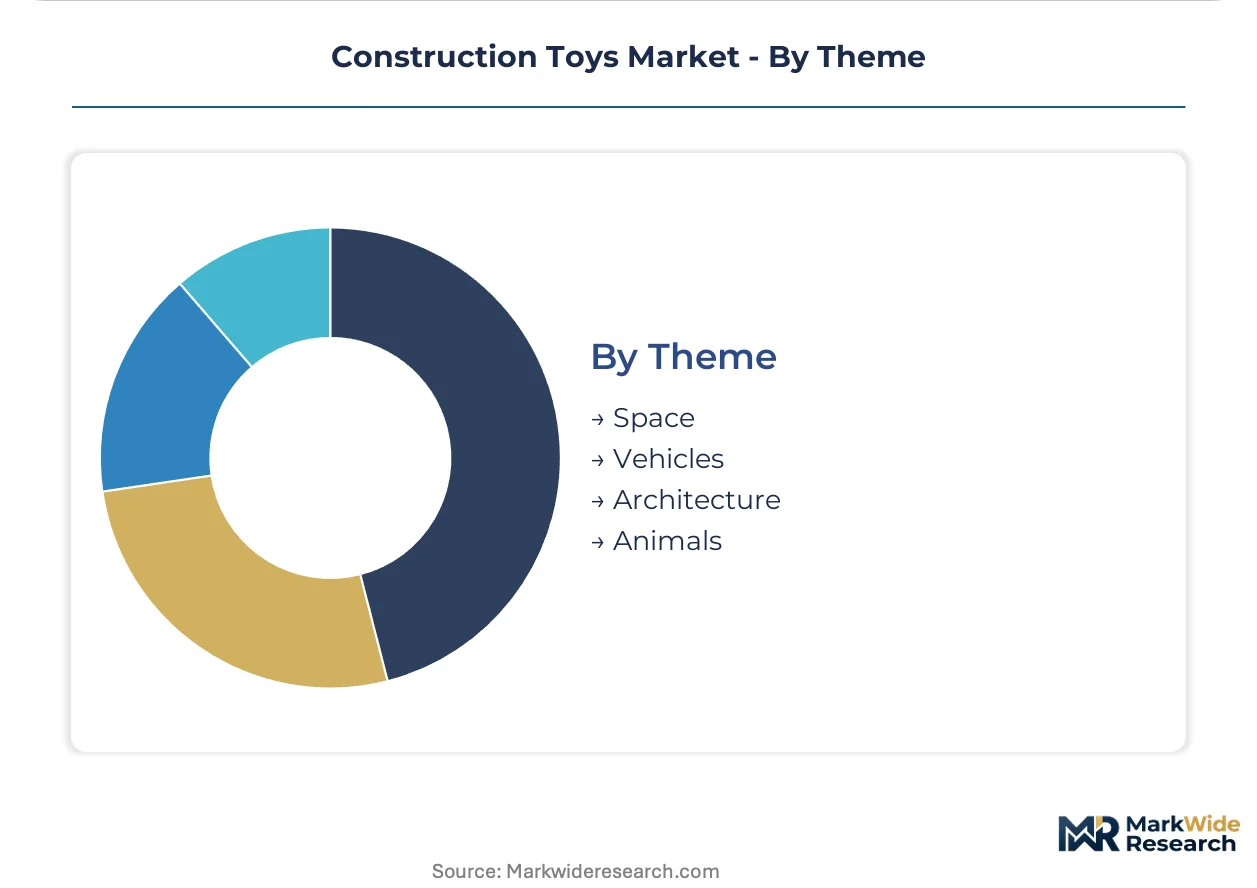
- Space:These themes often depict rockets, spacecraft, and extraterrestrial environments, inspiring imaginative play and scientific curiosity. Space-themed sets frequently align with STEM educational goals, particularly for school-age children.
- Vehicles:This theme includes cars, trucks, trains, and aircraft, appealing to a broad demographic across all age groups. Licensed intellectual property from popular franchises significantly boosts sales for vehicle-themed construction toys.
- Architecture:Architecture themes focus on replicating famous landmarks or designing original structures, often appealing to adult hobbyists and older children. Augmented reality applications are enhancing architectural sets by providing interactive building guides and virtual tours.
- Animals:Animal-themed construction toys often feature creatures from various habitats, encouraging imaginative storytelling and biological exploration. Younger children show strong engagement with animal-focused building sets.
Vehicles themes consistently attract a wide consumer base. Architecture themes are expanding quickly among adult hobbyists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region, a significant manufacturing and consumer hub, drives substantial demand for construction toys, particularly those emphasizing educational value. This region benefits from both domestic manufacturing capabilities and a large, affluent consumer base. Market expansion across various geographies reflects specific economic conditions, regulatory frameworks, and cultural priorities for child development.
China
Rising disposable incomes and a strong cultural emphasis on early childhood development fuel consumer spending on premium construction toys in China. The country's GB standards for toy safety ensure product quality, influencing manufacturing processes. Manufacturing clusters in the Pearl River Delta actively innovate in sustainable materials and advanced production techniques for construction toys.
United States
Government initiatives promoting STEM education in primary schools significantly boost institutional demand for construction toys as learning aids across the United States. The US Consumer Product Safety Improvement Act (CPSIA) mandates stringent testing, shaping material choices and design. Technology hubs in California explore augmented reality integration to enhance physical play experiences.
Germany
A strong consumer preference for durable, high-quality educational toys defines the German market, with sustainability a key purchasing factor. The EU's Toy Safety Directive and CE marking requirements heavily influence product design and material sourcing. Bavaria remains a center for toy manufacturing and design, focusing on precision engineering and safety.
India
Increasing household incomes and a growing middle class expand the consumer base for construction toys, particularly those with demonstrable educational benefits in India. The Bureau of Indian Standards (BIS) sets national toy safety standards, guiding local manufacturers. Major metropolitan areas like Delhi-NCR represent significant consumer markets for both traditional and innovative building sets.
Japan
High safety standards and a cultural appreciation for intricate design and educational tools contribute to consistent demand for construction toys in Japan. Japanese Industrial Standards (JIS) ensure product quality and consumer trust in toy manufacturing. Tokyo's design studios and retail centers often introduce advanced construction toy concepts and thematic innovations.
Construction Toys Market Key Industry Players
Global majors compete with regional champions across product innovation and market reach, shaping the competitive dynamics of the construction toys sector. The market exhibits a tiered structure, with a few dominant players at the premium end and numerous specialized manufacturers addressing niche segments. Strategic archetypes include material innovators, intellectual property licensors, and educational value providers. Portfolio diversification and geographic expansion represent common competitive moves among market participants.
Specialists in material innovation and brand legacy, such as LEGO Group, anchor the premium segment, consistently investing in bio-derived polymers and advanced R&D. Diversified consumer goods entity Mattel, through its Mega Bloks brand, occupies a strong position by leveraging licensed intellectual property and material science advancements. Meanwhile, Magna-Tiles exemplifies the rapid expansion within the magnetic tile category, attracting new consumers with innovative play patterns and commanding higher price points.
| Leading Market Players |
|---|
| Magformers |
| Playmobil |
| LEGO Group |
| Spin Master |
| Mega Bloks |
| Mattel |
| Magna-Tiles |
| BanBao |
| Hasbro |
| Others |
Cost & Logistics Intelligence
Bio-derived polymer integration recalibrates production costs while diversifying material sourcing networks for construction toy manufacturers. This shift impacts profitability and supply chain resilience across the industry.
Pricing Analysis
Volatile polymer costs directly influence construction toy pricing, with manufacturers often passing fluctuations to consumers. Pricing stratifies across premium, standard, and economy tiers, driven by brand premium and material composition. Digital entertainment competition intensifies cost compression, particularly in the standard segment. Preschool parents exhibit high price sensitivity, while adult hobbyists demonstrate lower elasticity for specialized sets.
Supply Chain Analysis
Skilled labor availability in manufacturing hubs like China and Vietnam is critical for precision molding and assembly of construction toys. The supply chain centers on these nations, alongside Poland, for high-volume production, drawing from ABS plastic, rare-earth magnets, and emerging bio-polymers. Single-source vulnerability for specialized magnetic components presents a structural risk. Distribution runs through both traditional retail channels and expanding direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction toys market operates as a regulatory compounder, with the EU's Toy Safety Directive and US CPSIA driving continuous product innovation and material safety standards. These regulations compel manufacturers to invest in R&D for compliant and safe products.
For Market Incumbents: Lock in core market share by continuously innovating in sustainable materials, leveraging significant R&D investment in bio-derived polymers. Expand licensed intellectual property portfolios to counter digital entertainment competition and maintain brand relevance. Strengthen distribution channels, especially direct-to-consumer platforms, to deepen customer relationships. Ensure compliance with evolving safety regulations like the EU's CE marking requirements to protect brand integrity.
For New Entrants and Emerging Players: Government initiatives promoting STEM education in the US and China open a window for innovative educational toy brands. Target the magnetic tile category and augmented reality-integrated sets, particularly within the school-age segment in Latin American markets. Differentiate through a strong educational value proposition and robust safety certifications. Leverage agile manufacturing to respond quickly to niche market demands.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional plastic block manufacturers facing material cost volatility. Focus on brands demonstrating strong intellectual property and clear sustainable material roadmaps for long-term viability over the coming 5-10 years. Acquisition targets should include specialists in magnetic tiles or augmented reality integration. Scaling of bio-polymer production by smaller players represents a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports global demand for premium construction toys and reduces lead times for key markets. |
| Backward Integration | Secures supply of sustainable materials, mitigating volatile polymer costs for manufacturers. |
| Product Launch | Captures new consumer segments with augmented reality-integrated sets and offers premium differentiation. |
| DTC Channel Expansion | Cultivates brand communities and provides direct control over pricing and customer data. |
| Sustainability Repositioning | Addresses consumer and regulatory pressure for environmental responsibility, enhancing brand perception. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from product development executives, R&D directors, supply chain managers, and retail buyers. This primary research is validated against extensive secondary sources, including EU Toy Safety Directive reports and US CPSIA compliance documents. Bottom-up and top-down triangulation ensures data accuracy. Company annual reports also informed the analysis.
Market modeling was conducted at a granular level across product type, age group, material, and theme, and regional regulatory frameworks. The analytical framework incorporates time-series analysis and regression modeling over the projection horizon. Compound annual growth rates were derived from historical data and projected market dynamics. Key forecast inputs include consumer spending patterns and government STEM initiatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical shifts or unforeseen material supply disruptions. Forecasts reflect documented assumptions regarding regulatory stability and consumer behavior. Material deviation in volatile polymer costs or new digital entertainment forms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Decompression Toys Market
Toys and Games
Table Top Games Market
Toys and Games
Dartboard Market
Toys and Games
Coaster Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Claw Machine Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Global Toys Market
Toys and Games
Ride-Ons Market
Toys and Games
Sustainable Toys Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Global Blind Boxes Market
Toys and Games
Inflatable Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Glow Sticks Market
Toys and Games
Animation Toys Market