
 Toy Cars Market | 2026-2036
Toy Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Cars Market Analysis
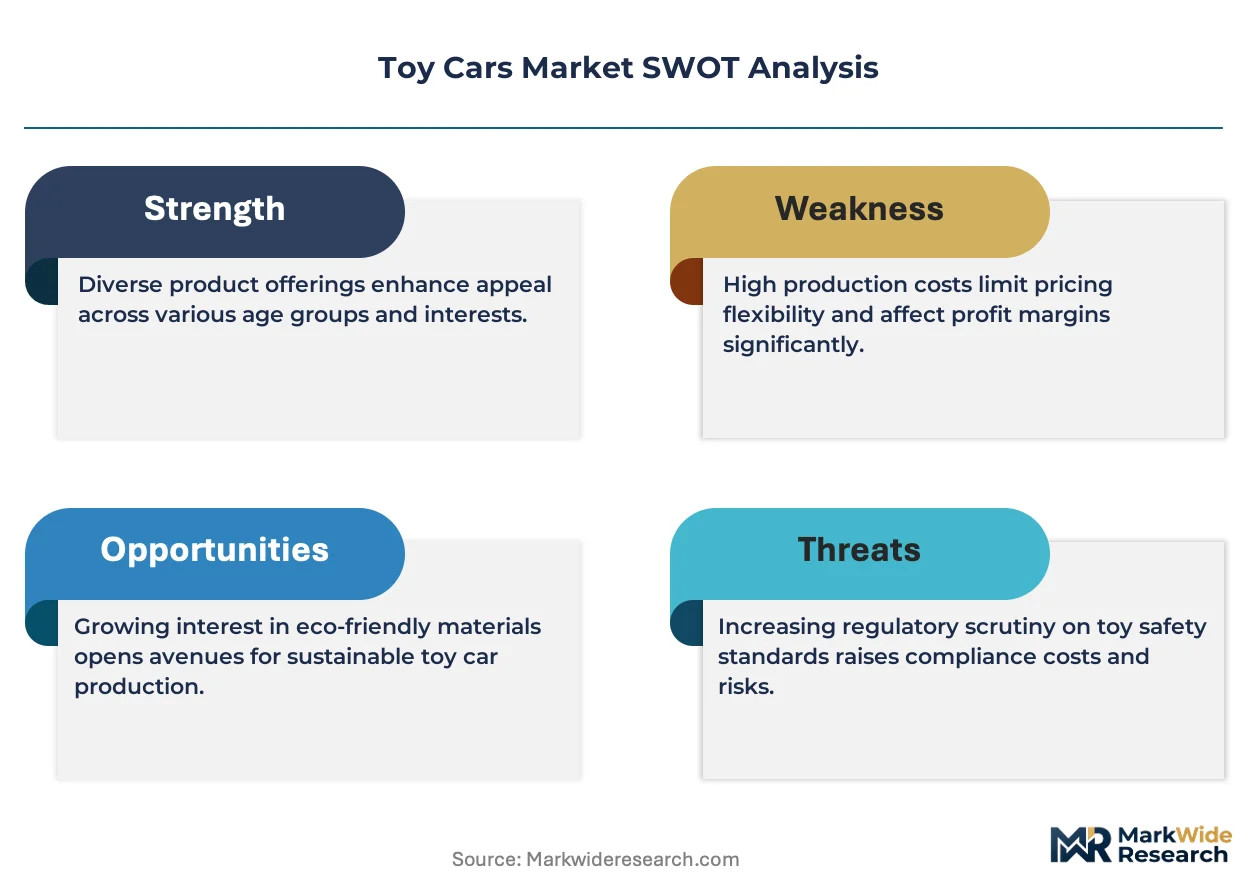
Aftermarket parts and customization accessories is reconfiguring margin pools away from base vehicle sales toward higher-attachment-rate ecosystems. Mattel leverages its Hot Wheels brand architecture to dominate track-compatible expansion packs and limited-edition releases. The Lego Group anchors premium positioning through buildable vehicle sets that merge construction play with automotive themes. Majorette competes on European retail shelf space through licensed die-cast replicas tied to French and German OEM partnerships.
Toy cars are scaled miniature vehicles, typically manufactured through zinc-alloy die-casting or injection-molded ABS plastic, designed for play, display, or educational purposes with functional parameters including scale ratios, rolling resistance, and crash durability. Die-cast production occupies the highest margin tier due to metal content precision and collector-grade finishing requirements. Remote-controlled segments lead technology intensity with servo mechanisms and lithium-polymer power systems. Collector demand within the end-user dimension sustains price premiums for limited-production runs and vintage authenticity verification.
The Consumer Product Safety Commission governs small-part regulations and lead-content limits for toys sold in the United States, directly shaping material selection and age-grading decisions by manufacturers. REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy-metal additives in painted and plated components, forcing reformulation of traditional die-cast coatings. China's GB standards and SAMR oversight govern both domestic market access and export certification for the world's largest production cluster. Stakeholders must monitor evolving battery-transport regulations as remote-controlled segments electrify and cross-border e-commerce channels expand.
Market Dynamics
Collector-grade die-cast manufacturing is concentrating production expertise in Dongguan and Shantou, while REACH and CPSIA compliance costs are forcing mid-tier producers toward ABS plastic alternatives or exit.
Growth Catalysts
- Remote-control electrification:Lithium-polymer battery systems and brushless motor adoption in hobby-grade segments are expanding average selling prices and attachment rates for charging infrastructure.
- REACH substance restrictions:Phased bans on cadmium and lead stabilizers in European markets are accelerating reformulation investments that differentiate compliant producers from gray-market competitors.
- Adult collector demographics:Precision-engineered 1:18 and 1:43 scale replicas are commanding sustained premiums through limited-production runs and vintage authentication services.
Market Restraints
- Zinc alloy price volatility:London Metal Exchange zinc fluctuations directly compress die-cast margins, forcing producers to index raw material clauses or absorb quarterly cost swings.
- Dongguan supply concentration:Over 60 percent of precision die-cast tooling capacity sits within 50 kilometers of this Guangdong cluster, creating single-point vulnerability to power rationing or labor disruptions.
- Digital play substitution:Mobile-based racing simulation applications are capturing discretionary spending from pre-teen segments traditionally served by entry-level pull-back vehicles.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and DMart shelf-space allocations for licensed automotive replicas remain underpenetrated relative to Southeast Asian per-capita toy spending benchmarks.
- CE marking harmonization:Mutual recognition agreements between EU and Gulf Cooperation Council states are reducing duplicate testing costs for exporters targeting Saudi and UAE markets simultaneously.
- 3D-printed customization kits:FDM and resin-printed aftermarket body shells are converging with traditional die-cast chassis, enabling micro-batch personalization without tooling investment.
Industry Challenges
- Dual-carbon compliance timelines:China's MEE carbon intensity targets for zinc smelting are forcing foundry partners to retrofit emissions controls or relocate, extending supplier qualification cycles by 8-12 months.
- Licensed IP enforcement:OEM trademark agreements require audit-ready supply chain documentation that many tier-two decorators cannot provide, narrowing the vendor pool for premium replica programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Cars Market |
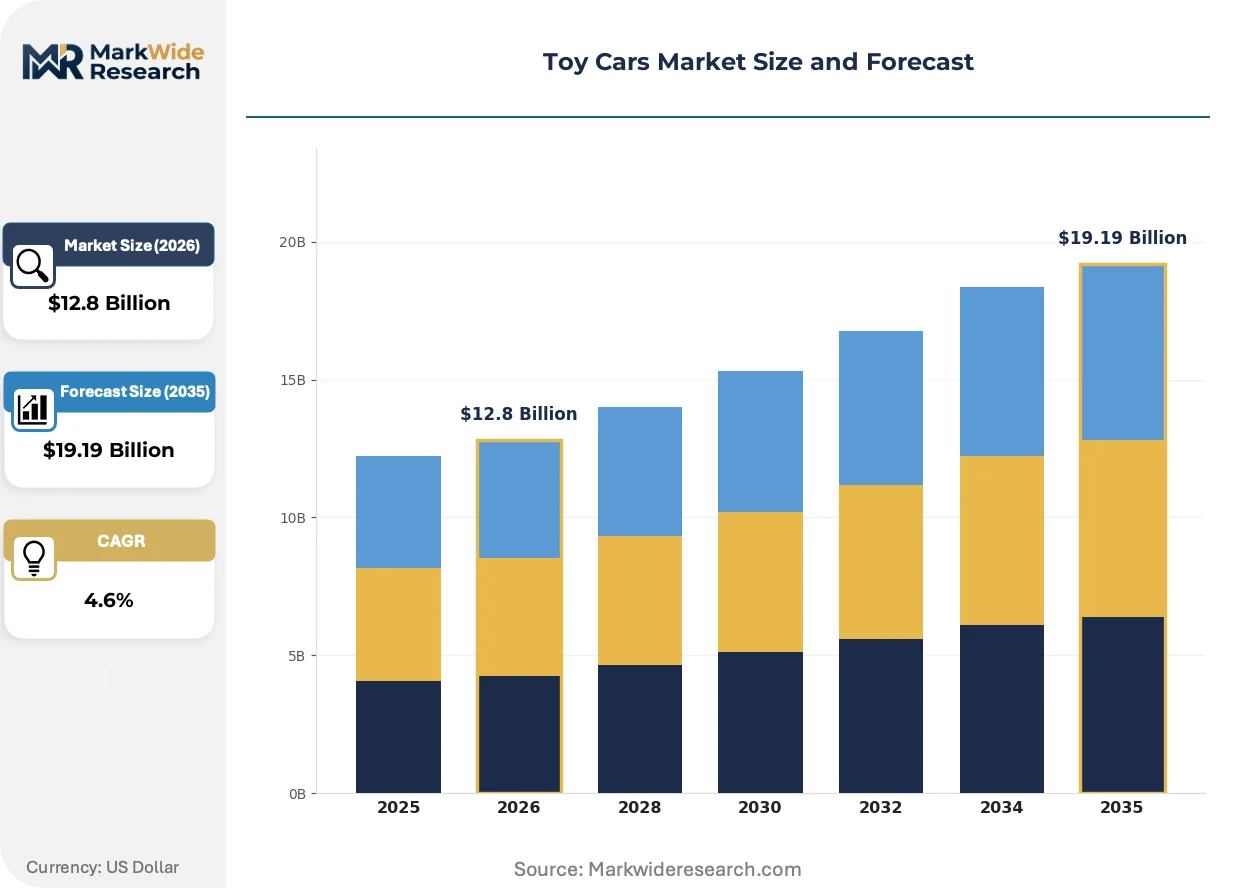
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Cast, Plastic, Remote-Controlled, Pull-Back End User: Children, Collectors, Educators, Hobbyists Distribution Channel: Retail Stores, Online Platforms, Toy Shows, Specialty Shops Age Group: Toddlers, Preschoolers, School-Aged, Teens |
| Companies Covered | Hasbro, Maisto, Mattel, Auto World, Majorette, Hot Wheels, Bandai Namco Holdings, Jada Toys, The Lego Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Cars Market Emerging Trajectories
Physical-digital convergence is redefining what constitutes a "complete" toy car purchase, with embedded NFC chips and companion applications now standard in mid-tier and above segments.
Die-cast zinc alloy production is hybridizing with polymer sub-assemblies to reduce unit weight and shipping costs while maintaining collector-grade surface finish. Premium manufacturers in Shantou are adopting this hybrid construction for 1:24 scale releases targeting North American hobby shop distribution. The approach is compressing traditional all-metal positioning as a pure luxury tier rather than a quality default.
ECHA's SCIP database requirements under the Waste Framework Directive are mandating article-level substance disclosure for toys containing Candidate List SVHCs above 0.1 percent. European importers now demand granular supply chain documentation from Chinese decorators, with non-compliant shipments facing port-of-entry rejection. Small-batch collectible producers are responding by consolidating plating and painting steps to reduce chemical complexity and audit burden.
Collector purchasing has migrated from hobby shop counter sales toward authenticated secondary market platforms with embedded condition grading. Japanese auction houses and German specialist dealers are integrating blockchain provenance tracking for vintage 1:43 releases, displacing informal collector-to-collector transactions. This channel shift is most visible in DINK household segments across Tokyo, Munich, and Los Angeles metropolitan areas.
Toy Cars Market Segmentation
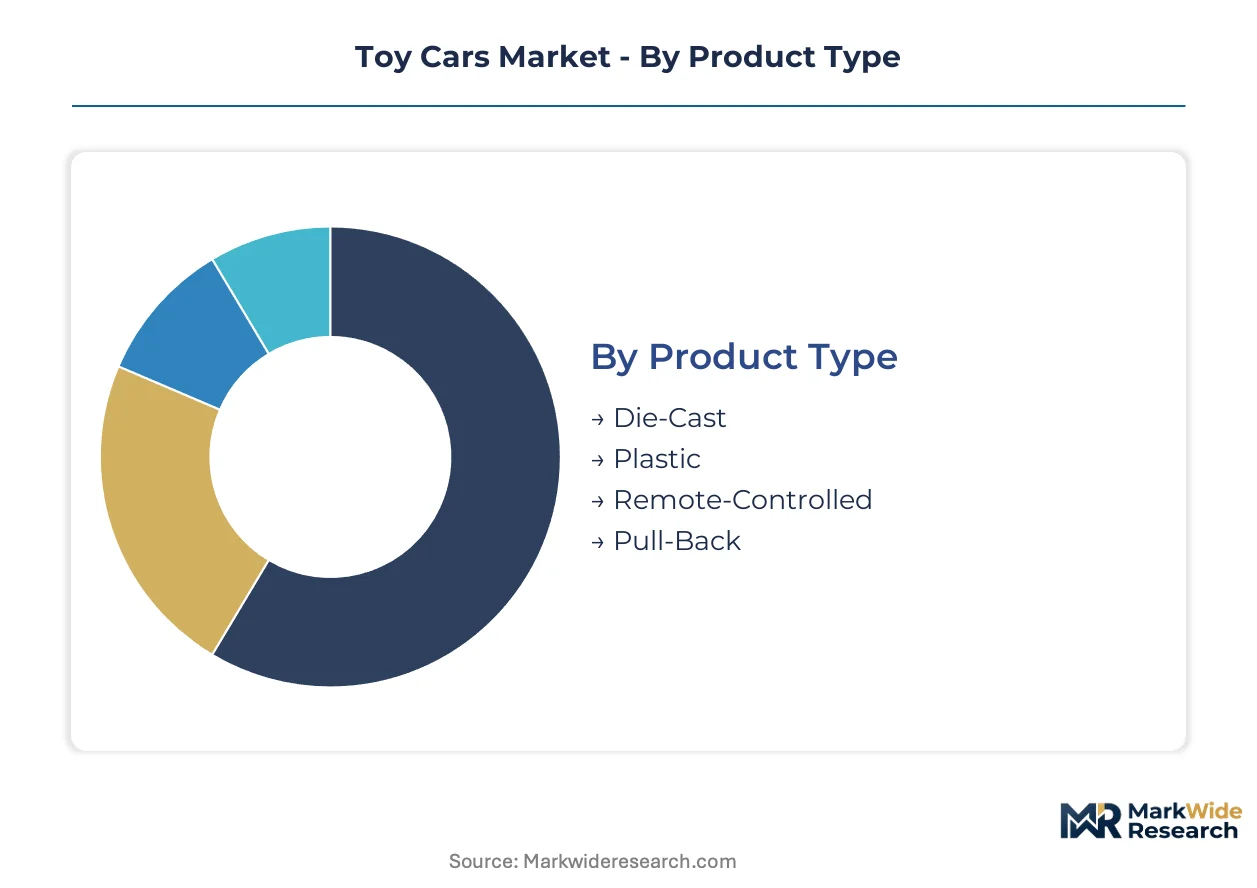
Segmentation in the toy cars market reveals divergent margin structures and compliance burdens across material types and buyer motivations. Precision-engineered collector-grade products command sustained premiums through authentication services, while mass-market plastic variants face acute margin pressure from raw material volatility and digital substitution.
Product Type:
Mature die-cast manufacturing anchors the value chain in Dongguan and Shantou, while emerging electrification in remote-controlled segments is redefining technology intensity and average selling prices.
- Die-Cast:Zinc-alloy die-casting with precision tooling delivers collector-grade surface finish and weight authenticity. REACH and CPSIA compliance costs are forcing mid-tier producers toward exit or hybrid construction. Demand concentrates in authenticated secondary market platforms with embedded condition grading.
- Remote-Controlled:Lithium-polymer battery systems and brushless motor adoption in hobby-grade segments expand attachment rates for charging infrastructure. Adult hobbyists in Munich, Tokyo, and Los Angeles metropolitan areas sustain price premiums for precision servo mechanisms and modular upgrade paths.
- Plastic:Injection-molded ABS construction dominates volume throughput for entry-level segments, though zinc price volatility has compressed margins for producers without indexed raw material clauses.
- Pull-Back:Friction-motor simplicity targets toddler and preschool segments with lowest unit cost, facing direct displacement from mobile-based racing simulation applications capturing pre-teen discretionary spending.
Die-cast handles the majority of throughput; remote-controlled is the fastest mover on share.
End User:
Cost tier stratification separates authentication-driven collector purchases from volume-driven child and educator procurement, with hobbyists occupying an intermediate technology-intensity position.
- Collectors:Precision-engineered 1:18 and 1:43 scale replicas command sustained premiums through limited-production runs and blockchain provenance tracking. ECHA SCIP database requirements are mandating article-level substance disclosure, consolidating vendor pools toward audit-ready decorators.
- Hobbyists:Servo mechanism customization and aftermarket parts ecosystems drive repeat purchase behavior. Chinese GB standards and SAMR oversight govern both domestic market access and export certification for electrified segments.
- Children:Safety testing protocols under CPSIA and REACH shape age-grading decisions and small-part regulations for mass-market distribution.
- Educators:STEM-aligned construction play merges automotive themes with instructional applications, favoring buildable vehicle sets with documented learning outcomes.
Collectors generate the highest margin per unit; hobbyists show the steepest expansion trajectory in attachment-rate economics.
Distribution Channel:
Geography of purchase is fragmenting from consolidated retail toward authenticated digital platforms and specialized physical events, with channel choice correlating to buyer sophistication and product tier.
- Online Platforms:Cross-border e-commerce expansion demands monitoring of evolving battery-transport regulations for remote-controlled segments. Japanese auction houses and German specialist dealers integrate blockchain provenance tracking, displacing informal collector-to-collector transactions.
- Specialty Shops:Hobby shop counter sales retain importance for servo mechanism demonstration and immediate parts availability, though authenticated secondary market platforms are capturing vintage 1:43 transactions.
- Retail Stores:Reliance Retail and DMart shelf-space allocations in India remain underpenetrated relative to Southeast Asian per-capita toy spending benchmarks.
- Toy Shows:Physical events concentrate limited-edition releases and direct manufacturer engagement for collector-grade die-cast programs.
Online platforms handle the majority of authenticated collector throughput; specialty shops retain the fastest-climbing share in hobby-grade electrification.
Age Group:
Application of play evolves from motor-skill development through competitive digital convergence, with each tier presenting distinct safety compliance and margin profiles.
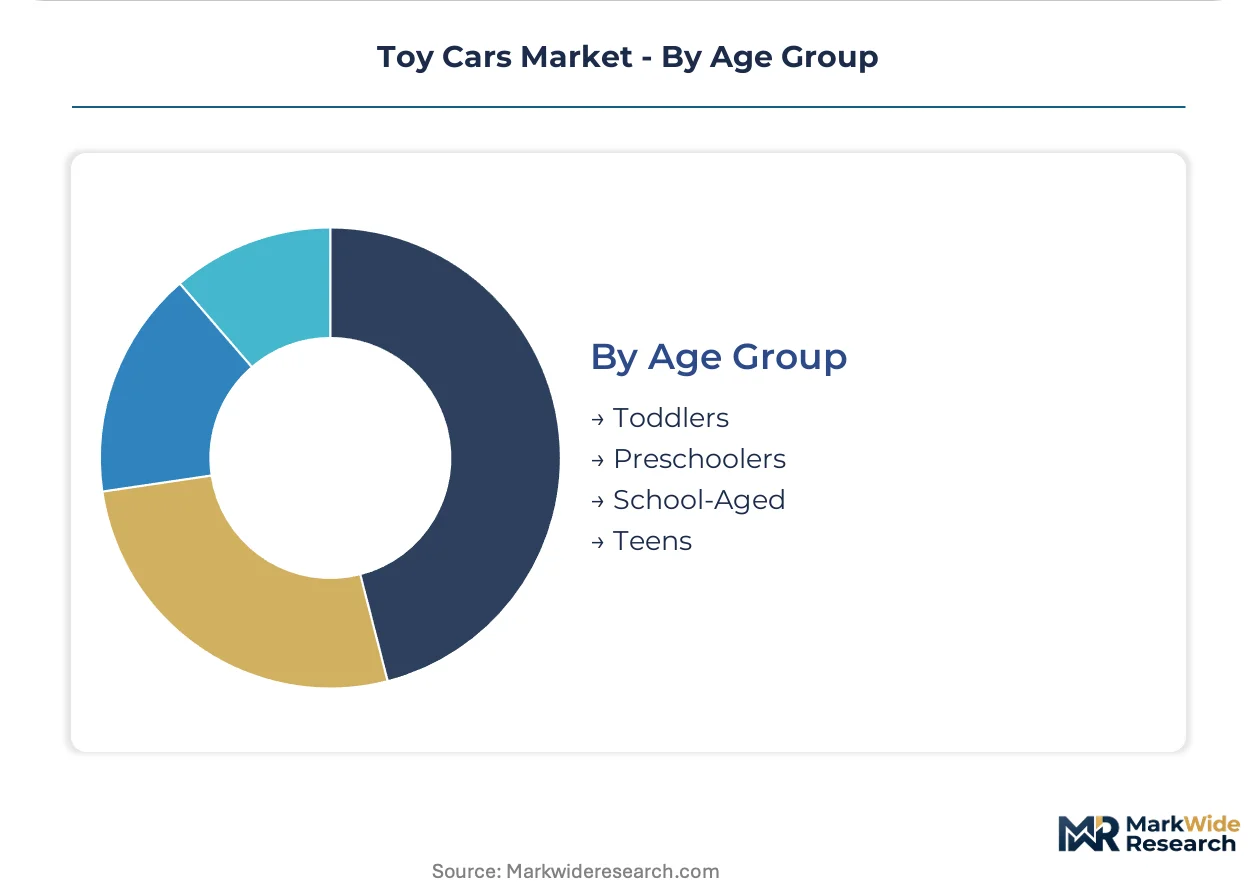
- School-Aged:Track-compatible expansion packs and construction-vehicle hybrids merge physical play with emerging digital companion applications. Mattel leverages Hot Wheels brand architecture to dominate this attachment-rate ecosystem.
- Teens:Hobby-grade remote-controlled segments with lithium-polymer power systems capture technology-intensity demand, with CE marking harmonization reducing duplicate testing costs for EU-GCC simultaneous export.
- Preschoolers:Small-part regulations and lead-content limits under CPSC governance directly constrain material selection and construction complexity.
- Toddlers:Simplest friction-motor and push-vehicle formats face earliest digital substitution risk from mobile-based racing simulations.
School-aged segments anchor volume throughput; teens represent the segment gaining share fastest through electrification and customization depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collector-grade die-cast consumption concentrates in German and Japanese metropolitan markets with authentication-driven purchasing patterns, while China's domestic market absorbs volume-oriented plastic and remote-controlled segments through rapidly maturing retail infrastructure.
United States
CPSC small-part regulations and CPSIA lead-content limits shape age-grading decisions for mass-market distribution. California's Proposition 65 disclosure requirements add compliance layers for plated components entering West Coast ports. Los Angeles and New York metropolitan areas anchor authenticated secondary market activity for vintage 1:43 scale releases.
Germany
ECHA SCIP database mandates under the Waste Framework Directive force article-level substance disclosure from Chinese decorators. Munich and Frankfurt metropolitan areas sustain premium pricing for precision-engineered 1:18 replicas with blockchain provenance tracking. KBA licensing frameworks influence OEM partnership structures for die-cast replica programs.
China
GB standards and SAMR oversight govern both domestic market access and export certification for the world's largest production cluster. Dual-carbon compliance timelines from MEE force foundry partners to retrofit emissions controls or relocate. Dongguan and Shantou industrial zones concentrate over 60 percent of precision die-cast tooling capacity within 50 kilometers.
Japan
METI industrial standards and consumer safety protocols shape import requirements for electrified remote-controlled segments. Tokyo and Osaka metropolitan areas drive authenticated collector purchasing through integrated auction house platforms with embedded condition grading. Blockchain provenance tracking for vintage releases displaces informal collector-to-collector transactions.
India
BIS certification requirements and evolving toy safety standards under CDSCO oversight are tightening market access for imported die-cast and plastic segments. Reliance Retail and DMart shelf-space allocations for licensed automotive replicas remain underpenetrated relative to Southeast Asian per-capita toy spending benchmarks. Maharashtra and Gujarat industrial corridors are emerging as alternative manufacturing locations for export-oriented producers seeking China-plus-one strategies.
Toy Cars Market Vendor Landscape
Capability concentration sits with precision die-cast specialists; scale advantage sits with diversified toy conglomerates with track-compatible ecosystem architectures. The market structures around three tiers: premium collector-grade manufacturers with OEM licensing depth, mass-market brands with retail shelf-space dominance, and hybrid construction-play specialists merging automotive themes with buildable formats. Dominant competitive moves include portfolio diversification into aftermarket parts ecosystems and strategic partnerships with automotive OEMs for replica licensing programs.
Within the premium collector-grade tier, Majorette exemplifies European die-cast positioning through licensed OEM partnerships, while Auto World occupies a position in authenticated vintage replication. At the diversified conglomerate end, Mattel anchors mass-market scale with track-compatible expansion architectures, and The Lego Group represents the construction-play hybrid archetype merging buildable formats with automotive theming. Bandai Namco Holdings sits within the Japanese specialist tier with integrated entertainment property licensing.
| Leading Market Players |
|---|
| Hasbro |
| Maisto |
| Mattel |
| Auto World |
| Majorette |
| Hot Wheels |
| Bandai Namco Holdings |
| Jada Toys |
| The Lego Group |
| Others |
Supply Flow & Price Mechanics
Dongguan and Shantou's concentration of precision die-cast tooling capacity anchors margin capture at the decorator and brand-holder tiers, while zinc price volatility transmits directly through to collector-grade pricing premiums. Mid-tier producers absorb cost swings or exit toward ABS plastic alternatives, fragmenting margin pools across material tiers.
Pricing Analysis
Long-term offtake contracts with indexed raw material clauses dominate die-cast supply relationships, insulating premium manufacturers from London Metal Exchange zinc fluctuations. Three-tier pricing structure across collector-grade, hobbyist, and mass-market levels differentiates on certification depth and OEM licensing authenticity. Cost compression in entry-level plastic segments intensifies because digital play substitution erodes volume throughput. Mass-market child segments exhibit highest price sensitivity; authenticated collector buyers show inelastic demand for blockchain-provenanced vintage releases.
Supply Chain Analysis
REACH and RoHS substance restrictions limit flows of cadmium-stabilized and lead-plated components into European distribution channels, forcing reformulation at Chinese decorator tiers. Supply concentrates in China, Vietnam, and India for die-cast and plastic assembly, with component sourcing drawn from Malaysian and Indonesian resin suppliers. Single-source vulnerability concentrates in Dongguan's 50-kilometer tooling cluster. Distribution runs through authenticated secondary market platforms for collector segments and mass retail shelf space for child-oriented SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical-digital convergence in toy cars represents a high-growth disruption as NFC-embedded vehicles and companion applications redefine purchase completeness. ECHA SCIP database mandates and China's dual-carbon compliance timelines accelerate capability separation between audit-ready producers and gray-market competitors.
For Market Incumbents: Pre-empt margin erosion in mass-market die-cast by consolidating plating and painting steps to reduce chemical complexity audit burdens. Deepen backward integration into zinc alloy foundry partnerships before MEE carbon intensity targets force supplier relocation cycles. Prioritize track-compatible ecosystem architectures that capture repeat purchase behavior through expansion pack attachment.
For New Entrants and Emerging Players: Pursue white-space positioning in India's underpenetrated organized retail channels, where Reliance Retail and DMart shelf allocations lag Southeast Asian per-capita benchmarks. Target 3D-printed aftermarket body shell customization as a micro-batch entry path converging with traditional die-cast chassis. Lead with direct-to-collector digital platforms featuring embedded condition grading rather than retail distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward precision die-cast specialists with OEM licensing depth and audit-ready supply chain documentation over mass-market plastic assemblers facing digital substitution. Long-term viability across a 5-10 year window favors hybrid construction-play capabilities merging automotive theming with STEM-aligned educational positioning. Monitor blockchain provenance tracking adoption rates in Japanese and German auction house platforms as the signal for authenticated secondary market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Licensing Partnership | Secures KBA-influenced replica programs with German and French automotive manufacturers. |
| Physical-Digital Integration | Embeds NFC chips and companion applications to redefine complete purchase value. |
| Supply Chain Consolidation | Reduces ECHA SCIP audit burden by merging plating and painting chemical steps. |
| India Retail Expansion | Captures underpenetrated shelf space at Reliance Retail and DMart relative to Southeast Asia. |
| Carbon-Compliant Foundry Sourcing | Aligns with MEE dual-carbon timelines to avoid 8-12 month supplier qualification delays. |
Methodological Framework
Desk research of customs trade records, OEM licensing filings, and ECHA regulatory databases preceded structured interviews with die-cast production managers, European toy safety compliance officers, aftermarket parts distributors, and collector platform operators. Secondary validation drew from SAMR certification registries, GB standards documentation, and authenticated secondary market transaction data. Bottom-up segment sizing triangulated against top-down production cluster capacity estimates across Dongguan and Shantou industrial zones.
Assumptions around REACH substance restriction phase-in schedules and lithium-polymer battery transport regulation evolution were held fixed across the projection horizon, while zinc price volatility scenarios and digital substitution rates were stress-tested. Segmentation dimensions modeled include material construction type, end-user motivation archetype, distribution channel format, and regional regulatory cluster. CAGRs were derived from production capacity expansion plans and authenticated platform transaction velocity trends. Hobby-grade electrification attachment rates and 3D-printed aftermarket convergence pace served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in discretionary household spending patterns or cross-border e-commerce logistics costs would shift the trajectory. Material shifts in China's MEE enforcement intensity or ECHA SVHC Candidate List expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Wooden Toys Market
Toys and Games
Claw Machine Market
Toys and Games
Remote Control Toys Market
Toys and Games
Toy Collectibles Market
Toys and Games
Toys and Games Market
Toys and Games
Dartboard Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
US Sex Toys Market
Toys and Games
Global Fidget Toys Market