
 Cloud Ceilometer Market | 2026-2036
Cloud Ceilometer Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Ceilometer Market Insights
ICAO Annex 3 standards for automated meteorological observations is shifting procurement criteria toward certified digital ceilometers with real-time data transmission. Vaisala leverages its aviation certification portfolio to sustain premium positioning across European and Asian airport authorities. Campbell Scientific anchors its presence in research-grade installations through ruggedized designs optimized for polar and alpine deployments.
A cloud ceilometer measures cloud base height using upward-directed electromagnetic pulses, with LIDAR variants emitting near-infrared laser pulses at wavelengths near 910 nanometers and calculating altitude via time-of-flight detection. The instrument serves meteorological services, aviation operations, and atmospheric research by delivering continuous vertical visibility profiles without human observation. Laser ceilometers dominate commercial procurement due to established reliability in all-weather conditions, while LIDAR technology segments command attention for multi-layer cloud detection capabilities. Aviation safety applications concentrate the largest installed base, though environmental research segments show expanding uptake for aerosol boundary layer studies.
FAA certification requirements under AC 150/5220-16B shape product development timelines for North American suppliers, while EASA CS-ADR-DSN provisions drive equivalent compliance investments across European manufacturers. China's GB/T 33694 meteorological instrument standards and the national CAAC airworthiness framework create parallel certification pathways for domestic and imported equipment. Stakeholders must monitor evolving dual-use export control classifications affecting LIDAR component sourcing.
Market Dynamics
Aviation meteorology infrastructure is undergoing a certification-driven equipment refresh cycle, with regulatory mandates for automated cloud base reporting forcing replacement of legacy human-observer systems at airports and research stations.
Growth Catalysts
- ICAO Annex 3 Compliance Mandates:Aviation authorities in China, India, and Indonesia are procuring certified digital ceilometers to meet international standards for automated meteorological observations at commercial airports.
- LIDAR Technology Maturation:Multi-layer cloud detection capabilities are expanding addressable applications beyond aviation into atmospheric boundary layer research and aerosol monitoring programs.
- Airport Modernization Programs:China's CAAC airworthiness framework and regional meteorological administration deployments are driving concentrated demand for ground-based weather sensor networks.
Market Restraints
- Precision Optics Supply Concentration:Near-infrared laser diodes and photon-counting detectors rely on specialized Japanese and German component suppliers, creating single-source vulnerability.
- Dual-Use Export Controls:LIDAR component classifications under multilateral export control regimes restrict technology transfer and complicate supply chain planning for manufacturers.
- Installation Cost Structure:Site preparation, calibration infrastructure, and integration with existing meteorological data networks impose capital barriers for smaller regional airports.
Strategic Opportunities
- Environmental Research Expansion:Climate monitoring programs in Brazil and South Africa are deploying ceilometers for aerosol vertical profiling and pollution boundary layer studies.
- Offshore Energy Applications:North Sea and Gulf of Mexico wind farm operators require continuous cloud base data for turbine icing prediction and power output forecasting.
- Smart City Integration:Urban meteorological networks in Singapore and Dubai are embedding ceilometers within multi-sensor environmental monitoring poles for real-time air quality management.
Industry Challenges
- Calibration Technician Scarcity:Specialized expertise in laser alignment, time-of-flight verification, and traceable altitude reference standards is concentrated among aging personnel at national meteorological institutes.
- Legacy System Interoperability:Digital ceilometers must interface with decades-old aviation weather message formats and proprietary airport data networks, extending deployment timelines.
- Certification Timeline Compression:FAA AC 150/5220-16B and EASA CS-ADR-DSN validation cycles create multi-year product development horizons that misalign with procurement funding windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Ceilometer Market |
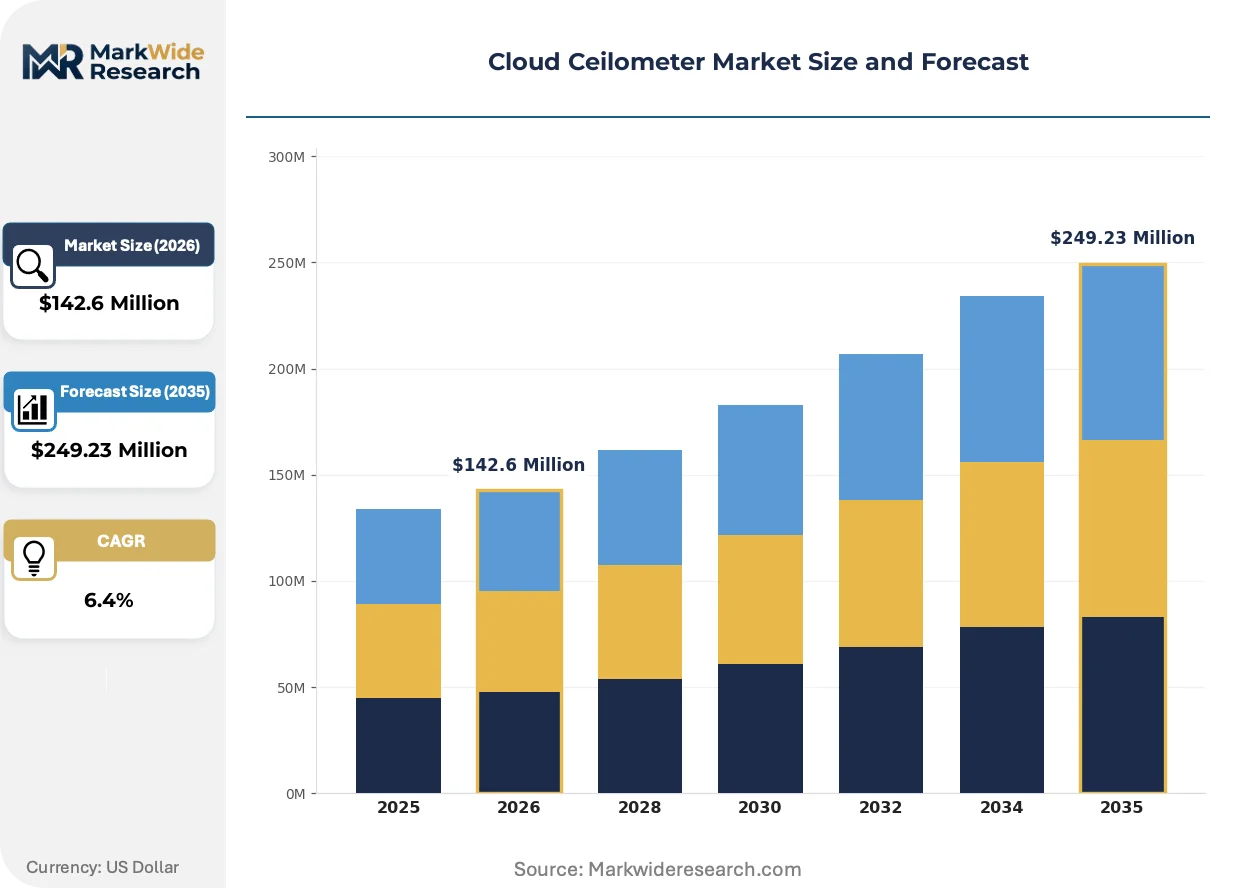
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $249.23 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Ceilometers, Ultrasonic Ceilometers, Infrared Ceilometers, Radar Ceilometers, Microprocessor-Based Ceilometers Technology: LIDAR, Doppler Radar, Time-of-Flight, Differential Absorption, Signal Processing Algorithms Application: Meteorological Monitoring, Aviation Safety, Environmental Research, Climate Studies, Air Traffic Control End User: Meteorological Agencies, Aviation Authorities, Research Institutes, Defense Organizations, Private Weather Services |
| Companies Covered | Vaisala, Campbell Scientific, BIRAL, Lufft, RAYMETRICS SA, Eliasson Engineering, MTECH Systems, Everisetech, Shandong Fengtu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Ceilometer Market Trends and Innovations
Meteorological instrumentation is converging around solid-state photonics and edge computing architectures, with cloud ceilometer design priorities shifting from standalone measurement accuracy toward networked sensor fusion and predictive algorithm integration.
Single-photon avalanche diode arrays are rewriting detection sensitivity thresholds in modern ceilometer architectures. Research-grade atmospheric observatories in Switzerland and Australia are deploying these solid-state receivers to capture faint returns from high-altitude cirrus layers previously invisible to analog photomultiplier systems. The technology is compressing the performance gap between aviation-certified units and research instruments, enabling dual-use product platforms.
China's GB/T 33694 meteorological instrument standards are tightening certification requirements for electromagnetic compatibility and environmental sealing. Domestic manufacturers must now demonstrate operation across expanded temperature and humidity ranges before CAAC airworthiness approval. European and Asian suppliers are responding with modular housing designs that isolate optical benches from thermal cycling, extending field calibration intervals.
Buyer organizations are consolidating sensor procurement under national meteorological service frameworks rather than airport-by-airport acquisition. China's national meteorological administration now centrally specifies ceilometer configurations for regional airports, compressing vendor negotiation cycles and favoring suppliers with established service networks. This concentration is most visible across provincial airports in Sichuan and Yunnan provinces, where standardized deployment protocols are accelerating installation velocity.
Cloud Ceilometer Market Segmentation
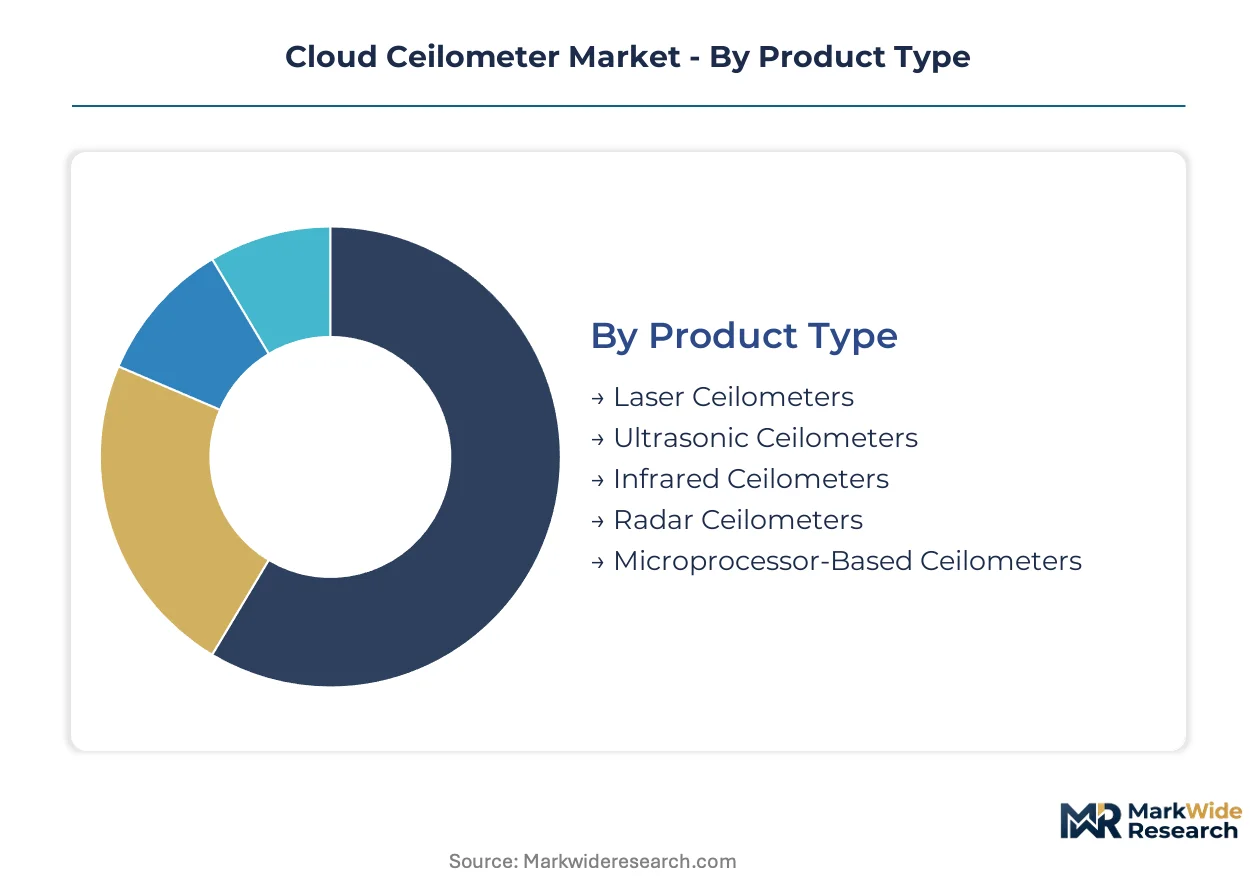
Cloud ceilometer procurement patterns diverge sharply across certification tiers, with aviation-certified units commanding premium positioning against research-grade alternatives. Product specifications, detection technologies, and end-user compliance requirements create distinct addressable markets with incompatible procurement cycles.
Product Type:
Certification burden varies by detection mechanism: laser-based systems require FAA AC 150/5220-16B or EASA CS-ADR-DSN validation for aviation deployment, while ultrasonic and microprocessor variants face lighter meteorological instrument standards.
- Laser Ceilometers:Near-infrared laser diodes emitting at 910 nanometers dominate commercial aviation procurement through proven all-weather reliability. Demand concentrates at Chinese regional airports under CAAC airworthiness framework mandates for automated cloud base reporting.
- Ultrasonic Ceilometers:Acoustic pulse-echo systems measure cloud base via sound propagation velocity, avoiding laser safety classification complications. Research institutes in polar regions favor these units for reduced optical maintenance requirements in extreme cold.
- Infrared Ceilometers:Thermal radiation detection systems serve specialized fog monitoring applications at coastal airports.
- Radar Ceilometers:Microwave-based altimetry penetrates precipitation events that obscure optical sensors.
- Microprocessor-Based Ceilometers:Integrated computing architectures enable edge-processing of multi-sensor fusion data for smart city deployments.
Leading the category by volume: Laser Ceilometers. Growing fastest: Microprocessor-Based Ceilometers.
Technology:
Detection methodology determines addressable application scope, with time-of-flight architectures saturating aviation markets while differential absorption opens atmospheric chemistry revenue streams.
- LIDAR:Light detection and ranging systems capture multi-layer cloud structure through single-photon avalanche diode arrays. Swiss and Australian atmospheric observatories deploy these for high-altitude cirrus detection previously invisible to analog systems.
- Doppler Radar:Velocity-sensing microwave systems measure hydrometeor motion for turbulence prediction. Offshore wind farm operators in the North Sea require continuous data streams for turbine icing forecasts.
- Time-of-Flight:Pulse-interval measurement dominates certified aviation installations through traceable altitude reference standards.
- Differential Absorption:Wavelength-pair techniques quantify water vapor profiles for climate boundary layer studies.
- Signal Processing Algorithms:Machine learning-based cloud boundary detection reduces false positives in urban aerosol environments.
Dominant by installed base: Time-of-Flight. Steepest expansion trajectory: Signal Processing Algorithms.
Application:
End-use context dictates performance specifications and procurement authority, with aviation safety applications requiring regulatory certification unavailable to research or climate monitoring segments.
- Aviation Safety:Automated cloud base reporting at commercial airports replaces human observers under ICAO Annex 3 mandates. China's national meteorological administration centrally specifies configurations for Sichuan and Yunnan provincial airports.
- Meteorological Monitoring:National weather service networks demand continuous vertical visibility profiles for synoptic forecasting. Brazil and South Africa deploy units for aerosol vertical profiling and pollution boundary layer studies.
- Environmental Research:Atmospheric chemistry programs require research-grade sensitivity without aviation certification overhead.
- Climate Studies:Long-term trend monitoring networks prioritize calibration stability over real-time transmission protocols.
- Air Traffic Control:Tower visibility systems integrate with existing airport data networks through legacy message format compatibility.
Highest revenue concentration: Aviation Safety. Expanding most quickly: Environmental Research.
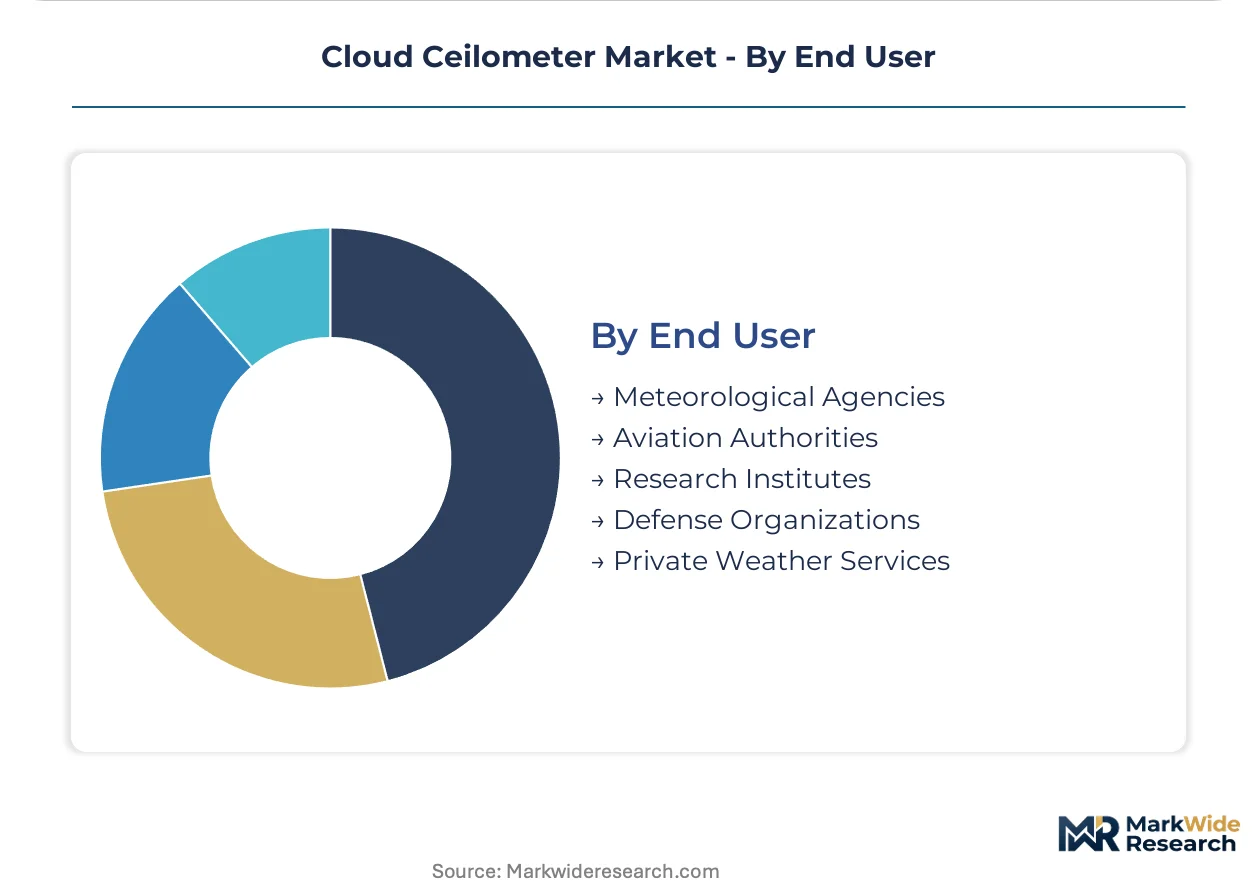
End User:
Procurement authority centralization varies by institutional type, with meteorological agencies consolidating specifications while defense organizations maintain classified requirements.
- Meteorological Agencies:National weather services in China, India, and Indonesia drive volume procurement through centralized framework agreements. Standardized deployment protocols compress vendor negotiation cycles and favor suppliers with established service networks.
- Aviation Authorities:Airport operators under FAA, EASA, and CAAC jurisdiction require certified equipment with multi-year validation cycles that misalign with procurement funding windows.
- Research Institutes:University and government laboratories prioritize detection sensitivity over regulatory compliance, enabling dual-use product platforms.
- Defense Organizations:Military meteorological units require ruggedized designs with electromagnetic spectrum security features.
- Private Weather Services:Commercial forecasting firms seek cost-optimized configurations for renewable energy and agricultural advisory markets.
Commanding procurement volume: Meteorological Agencies. Gaining share fastest: Private Weather Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume through centralized meteorological administration frameworks, while aviation modernization programs across Germany, India, Japan, and the United States create distributed demand nodes for certified cloud base measurement systems.
China
CAAC airworthiness mandates and GB/T 33694 meteorological instrument standards drive replacement of legacy observer systems at regional airports. The national meteorological administration centrally specifies ceilometer configurations for Sichuan and Yunnan provincial airports, compressing vendor negotiation cycles. Deployment velocity accelerates across western provinces where automated weather networks expand coverage gaps.
Germany
EASA CS-ADR-DSN certification requirements shape procurement criteria for aviation-certified digital ceilometers at Frankfurt and Munich hub airports. The country's national meteorological service operates dense ground-based sensor networks for synoptic forecasting. Bavarian alpine research stations deploy ruggedized units for boundary layer studies in extreme cold conditions.
India
Airports Authority of India procurement under ICAO Annex 3 compliance timelines targets automated cloud base reporting at tier-2 and tier-3 airports. The national meteorological department expands vertical visibility profiling for monsoon forecasting operations. Maharashtra and Karnataka state airports concentrate installation activity under centralized framework agreements.
Japan
METI industrial standards and JIS certification pathways govern meteorological instrument procurement for aviation and research applications. Single-photon avalanche diode arrays gain traction at atmospheric observatories for high-altitude cirrus detection. Tokyo and Osaka metropolitan airports anchor demand for real-time data transmission capabilities.
United States
FAA AC 150/5220-16B certification timelines extend product development horizons for North American suppliers serving commercial airport operators. National Weather Service networks require continuous vertical visibility profiles for severe weather warning systems. Texas and Florida coastal airports drive specialized demand for precipitation-penetrating detection technologies.
Cloud Ceilometer Market Competitive Landscape
Finnish and German producers anchor the premium certification tier; Chinese fabricators hold volume positions in domestic procurement frameworks. The vendor base structures around three archetypes: aviation-certification specialists with multi-year validation track records, research-grade instrument builders optimizing for polar and alpine deployments, and emerging domestic suppliers capturing centralized administration contracts. Competitive moves concentrate on modular housing designs that isolate optical benches from thermal cycling, and service network density that accelerates installation velocity across provincial airport clusters.
Within the aviation-certification tier, Vaisala exemplifies premium positioning through established EASA and CAAC compliance portfolios. Campbell Scientific occupies a position among research-grade specialists with ruggedized designs. Shandong Fengtu represents the domestic Chinese archetype capturing share under centralized meteorological administration frameworks.
| Leading Market Players |
|---|
| Vaisala |
| Campbell Scientific |
| BIRAL |
| Lufft |
| RAYMETRICS SA |
| Eliasson Engineering |
| MTECH Systems |
| Everisetech |
| Shandong Fengtu |
| Others |
Pricing and Supply Chain Analysis
Near-infrared laser diode spot prices on the Tokyo Metal Exchange cascade through three distinct pricing tiers as optical component scarcity concentrates bargaining power among Japanese and German precision optics suppliers serving aviation-certified and research-grade ceilometer manufacturers.
Pricing Analysis
Volume concentrates in standard-grade time-of-flight systems for Chinese regional airports while margins concentrate in research-grade LIDAR platforms with single-photon avalanche diode arrays. Price differentiation hinges on EASA CS-ADR-DSN certification tier and field service network density. Cost compression in the standard tier intensifies as domestic Chinese manufacturers capture centralized meteorological administration contracts. Aviation authorities exhibit lowest price sensitivity due to multi-year validation requirements, while private weather services face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for photon-counting detectors and laser diode assemblies concentrate in Germany and Japan, extending component lifecycles for research-grade installations. Manufacturing draws from German precision optics, Japanese near-infrared laser diodes, and Chinese machined housings. Single-source vulnerability in avalanche photodiode arrays creates supply chain risk. Distribution runs through national meteorological service framework agreements rather than airport-direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud ceilometer market operates as a vertical-integration race where captive control over photon-counting detector supply separates margin leaders from price-takers in the standard aviation tier.
For Market Incumbents: Anchor premium positioning through backward integration into single-photon avalanche diode array sourcing, insulating against Japanese component supply volatility. Deepen service network density across Sichuan and Yunnan provincial airport clusters to defend against domestic Chinese entrants capturing centralized administration contracts. Prioritize modular housing designs that compress field calibration intervals under tightening GB/T 33694 environmental sealing requirements. For New Entrants and Emerging Players: Launch via research-grade atmospheric observatory channels in Switzerland and Australia, bypassing multi-year FAA and EASA certification barriers. Target environmental research segments in Brazil and South Africa where aerosol boundary layer studies demand detection sensitivity without aviation compliance overhead. Pursue white-label partnerships with established meteorological instrument distributors to accelerate installation velocity. For Investors and Strategic Acquirers: The window for entry favors research-grade specialists with solid-state photonics capabilities and established polar deployment track records. Long-term viability centers on dual-use product platforms that bridge aviation certification and atmospheric chemistry applications. Monitor CAAC centralized procurement framework expansions into western Chinese provinces as inflection signals for domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photon-Counting Detectors | Captive supply of single-photon avalanche diode arrays reduces Japanese component dependency and compresses cost structures. |
| Modular Housing Design Standardization | Isolation of optical benches from thermal cycling extends calibration intervals under GB/T 33694 temperature range expansions. |
| Service Network Density Expansion | Provincial airport cluster coverage accelerates installation velocity under China's centralized meteorological administration frameworks. |
| Research-Grade Channel Entry | Atmospheric observatory deployments in Switzerland and Australia bypass multi-year aviation certification timelines. |
| Dual-Use Product Platform Development | Single architecture serving aviation and environmental research segments maximizes R&D leverage across divergent procurement cycles. |
Research Methodology
Independent corroboration across meteorological instrument procurement officers, aviation authority certification engineers, and atmospheric research facility directors underwrites the qualitative findings in this study. Primary interviews with national weather service administrators, airport operations managers, and LIDAR systems integrators combined with secondary validation from FAA AC 150/5220-16B filings, EASA CS-ADR-DSN documentation, and CAAC airworthiness bulletins. Bottom-up installation data triangulates against top-down meteorological administration budget allocations.
Rate-of-change decomposition separates volume growth from price trajectory across the projection horizon. The analytical framework models product type, detection technology, application tier, and end-user procurement authority. CAGRs derive from segment-level adoption curves calibrated against ICAO Annex 3 compliance timelines and centralized framework agreement velocity in China. Forecast inputs incorporate LIDAR component export control classification shifts and solid-state photonics maturation curves.
The model assumes a particular technology adoption path; alternative pathways for single-photon avalanche diode array cost reduction would alter the outlook. Forecasts reflect assumptions regarding CAAC procurement centralization and EASA certification timeline stability. Practitioners should monitor dual-use export control regime expansions and GB/T 33694 electromagnetic compatibility requirement tightenings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Cloud Engineering Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Global Cloud Monitoring Market