
 Cloud Workflow Market | 2026-2036
Cloud Workflow Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Workflow Market Analysis
The cloud workflow sector is pivoting around a widening capability gap between premium AI-orchestrated platforms and commodity task-automation tools. Microsoft Power Automate leverages its Office 365 integration to dominate mid-market productivity automation, while IBM Watsonx Orchestrate anchors enterprise-grade AI agent deployment with governance-layer specialization. Salesforce Agentforce competes on CRM-native workflow intelligence, embedding orchestration directly inside customer data platforms.
Cloud workflow denotes the design, execution, and monitoring of business processes through distributed cloud infrastructure, typically orchestrated via API-connected microservices with sub-second latency thresholds and auto-scaling compute pools. Its primary commercial purpose is to replace manual handoffs and on-premises middleware with event-driven automation that spans organizational boundaries. The Service Type dimension shows Software as a Service occupying the deepest margin pools due to recurring subscription economics, while Function as a Service represents the fastest-expanding tier as developers decompose monolithic workflows into serverless components. Deployment patterns reveal Hybrid Cloud sustaining the largest project pipelines as regulated industries retain sensitive data on private nodes while bursting transactional workloads to public infrastructure.
The US Federal Risk and Authorization Management Program and the EU GDPR framework shape vendor roadmaps by mandating encryption standards, audit logging, and geographic data residency that inflate engineering overhead but also raise barriers to unqualified entrants. ISO 27001 certification has become a de facto procurement filter for enterprise buyers evaluating cloud workflow suppliers. Stakeholders must monitor how emerging AI agency regulations in Brussels and Washington redefine liability for autonomous workflow decisions.
Market Dynamics
Healthcare providers in the United States and Germany are accelerating migration from on-premises BPM suites to cloud-native orchestration platforms, compressing replacement cycles from seven years to under three as patient volume volatility demands elastic infrastructure.
Growth Catalysts
- Federal cloud-first directives:US agencies must default to cloud solutions under OMB mandates, forcing legacy system retirements and opening procurement pipelines for FedRAMP-authorized vendors.
- EU AI Act compliance architectures:Automated workflow decisions now require auditable governance layers, driving demand for platforms with built-in explainability and human-in-the-loop checkpoints.
- Serverless function decomposition:Developers are fragmenting monolithic workflows into event-driven microservices, expanding consumption of Function-as-a-Service compute tiers.
Market Restraints
- Cross-border data residency costs:Germany's BSI and France's ANSM mandates require regional cloud nodes, inflating infrastructure overhead for pan-European deployments.
- Specialized talent scarcity:DevOps engineers with hybrid cloud and compliance automation skills command premium compensation, constraining mid-market implementation velocity.
- Legacy middleware entrenchment:SAP and Oracle workflow engines retain deep integration with ERP systems, creating switching friction even where cloud alternatives outperform.
Strategic Opportunities
- India's digitization push:The country's PLI scheme for IT hardware and BIS cloud security standards are catalyzing domestic workflow platform adoption among manufacturing SMEs.
- Edge-cloud orchestration convergence:Industrial IoT deployments in Japan and South Korea require workflow engines that coordinate factory-floor sensors with centralized analytics.
- API marketplace distribution:Pre-built connector ecosystems reduce implementation timelines, enabling vendors to bypass traditional systems integrator channels.
Industry Challenges
- FedRAMP authorization timelines:US federal certification requires 12-18 months of security documentation and third-party assessment, delaying revenue recognition for emerging vendors.
- Multi-cloud interoperability gaps:Workflow state management across AWS, Azure, and GCP nodes demands proprietary abstraction layers that fragment vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Workflow Market |
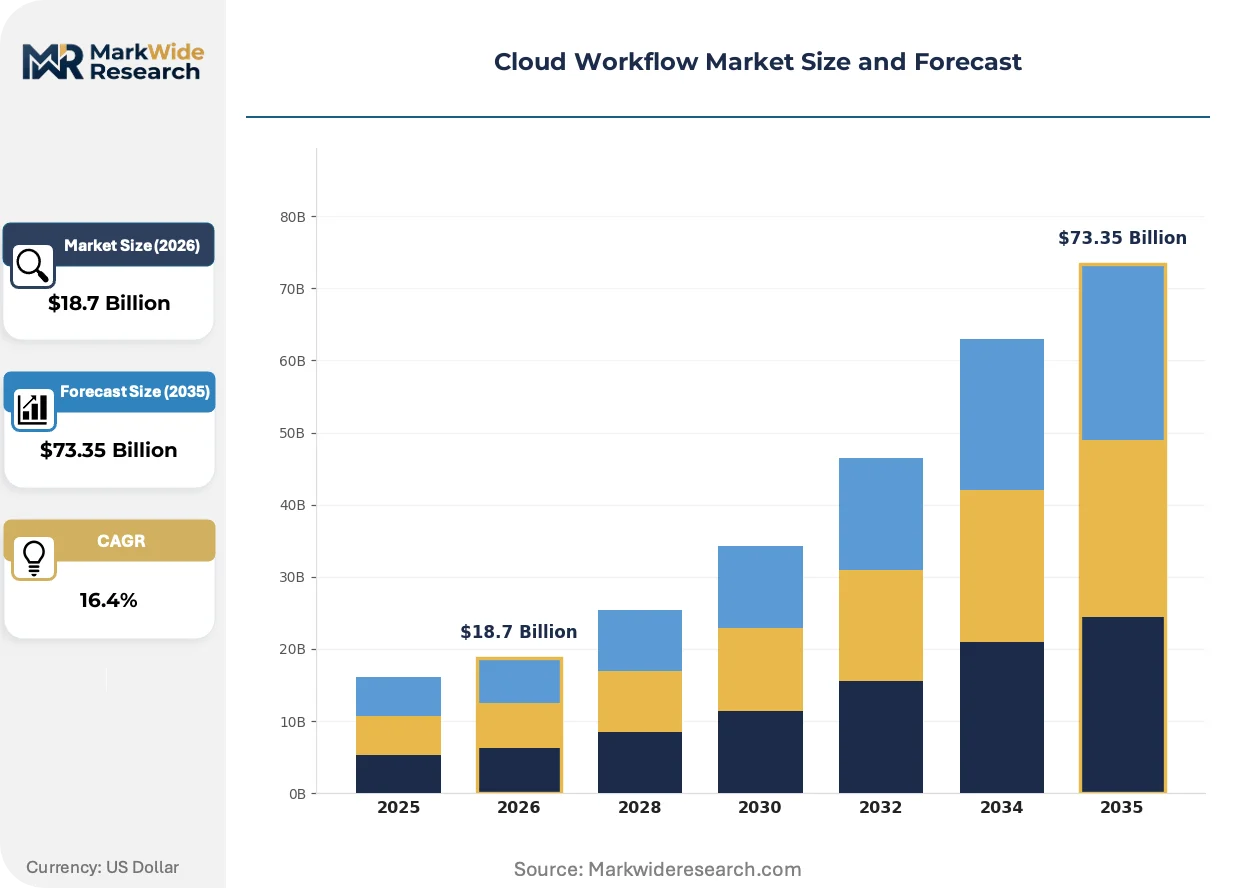
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User: Small Enterprises, Large Enterprises, Government Institutions, Non-Profits Application: Document Management, Task Automation, Project Management, Collaboration Tools |
| Companies Covered | Workato, Salesforce Agentforce, Microsoft Power Automate, Prompts.ai, IBM Watsonx Orchestrate, Google Cloud Vertex AI, Tray.io, CloudBolt, AWS Bedrock AgentCore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Workflow Market Emerging Trajectories
Agentic AI capabilities are redefining workflow automation from rule-based execution toward autonomous decision-making, forcing platform vendors to embed governance frameworks that satisfy emerging liability regimes.
Large language models are integrating retrieval-augmented generation into orchestration interfaces, enabling natural language workflow design. Healthcare administrators in the United States are piloting these tools for patient intake automation, compressing deployment timelines from months to weeks. The structural consequence is that technical implementation is integrating with conversational interfaces, reducing dependency on specialized developer resources.
The EU AI Act's risk classification framework is mandating conformity assessments for high-risk automated decision systems. Workflow vendors serving financial services and healthcare must now document algorithmic transparency and maintain human oversight mechanisms. German insurers and French hospitals are prioritizing platforms with pre-certified governance modules to accelerate procurement compliance.
Enterprise buyers are consolidating vendor relationships around platforms offering unified observability across SaaS, PaaS, and on-premises nodes. Procurement committees in regulated industries now require single-pane monitoring as a mandatory evaluation criterion, displacing point solutions. This pattern is most pronounced in US healthcare systems managing HIPAA-compliant data flows across hybrid environments.
Cloud Workflow Market Segmentation
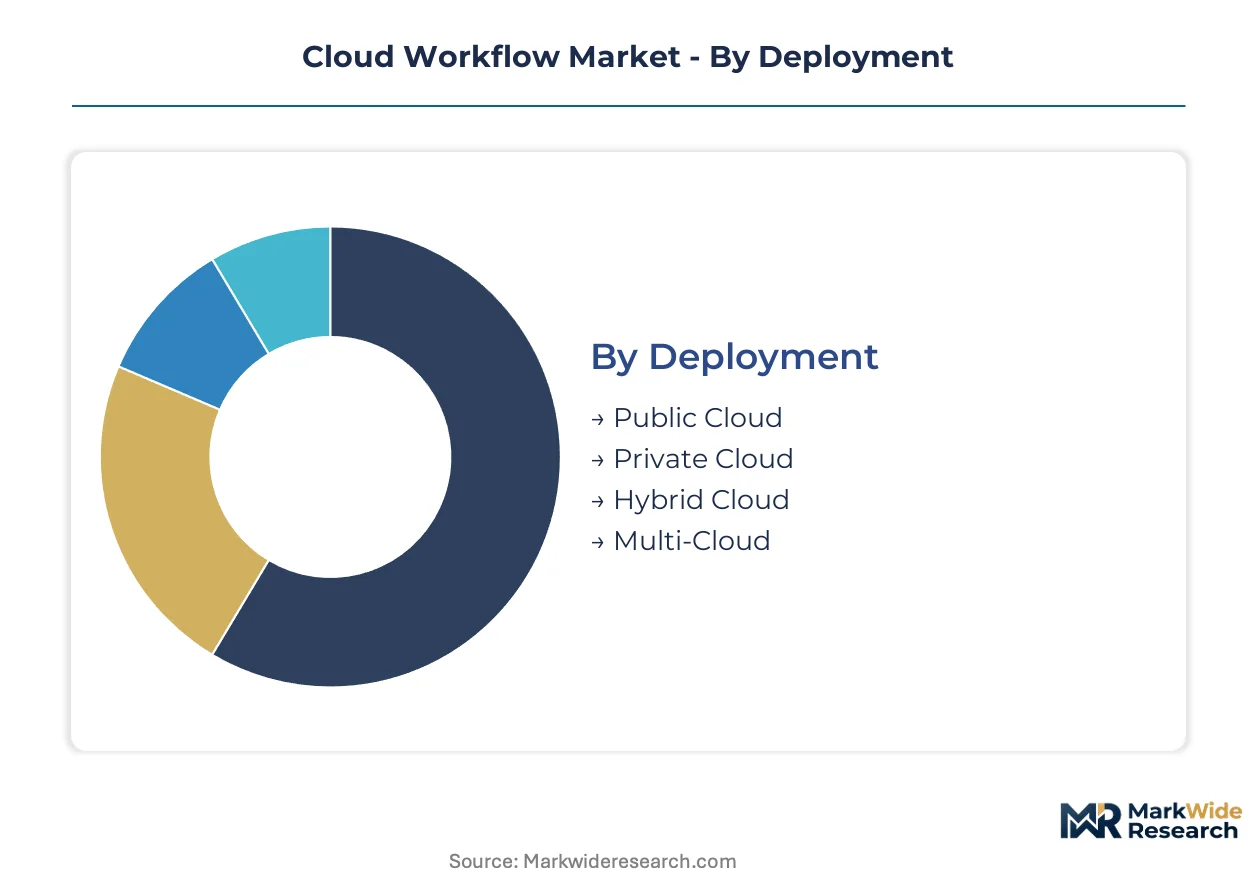
Cloud workflow segmentation reveals how infrastructure choices, service tiers, and buyer profiles reshape vendor economics. Deployment architecture and service type decisions determine capital intensity, while end-user scale and application focus dictate pricing power and retention rates.
Deployment:
Capital intensity peaks where physical infrastructure control intersects with compliance overhead, separating high-investment private nodes from variable-cost public alternatives.
- Public Cloud:Shared infrastructure pools deliver elastic compute with zero upfront hardware commitment. Demand concentrates among US digital-native startups and mid-market SaaS vendors seeking rapid scaling without data center CapEx, though GDPR data residency rules and FedRAMP boundaries constrain workload placement for regulated entities.
- Private Cloud:Dedicated hardware deployments within enterprise premises or single-tenant colocation facilities. German automotive manufacturers and French hospital networks absorb this tier's premium to satisfy BSI and ANSM sovereignty mandates, trading scalability for audit control and air-gapped security postures.
- Hybrid Cloud:Orchestrated workload distribution across on-premises nodes and public infrastructure bursts. US healthcare systems managing HIPAA-compliant patient data flows anchor sensitive records on private nodes while pushing analytics workloads to AWS or Azure, optimizing cost against compliance risk.
- Multi-Cloud:Active-active deployment across two or more hyperscaler environments to mitigate vendor lock-in and geographic failure domains. Financial services firms in London and Singapore leverage this architecture for regulatory resilience, though workflow state synchronization across AWS, Azure, and GCP fragments engineering resources and inflates operational complexity.
Hybrid Cloud absorbs the bulk of installed capacity among regulated industries; Function as a Service within deployment pipelines is expanding most quickly as serverless abstraction layers mature.
Service Type:
Margin profiles diverge sharply between high-touch managed infrastructure and low-friction consumption models, with developer-facing tiers commanding premium unit economics through usage-based billing.
- Software as a Service:Pre-built workflow applications delivered through browser interfaces with standardized configuration. Enterprise procurement committees in US federal agencies and German manufacturing conglomerates gravitate toward SaaS for predictable OpEx and rapid deployment, though customization limits create integration friction with legacy ERP systems.
- Function as a Service:Event-triggered compute units executing discrete workflow steps without persistent server management. Developer teams at Indian manufacturing SMEs and Japanese industrial IoT deployers adopt FaaS to decompose monolithic processes into granular, independently scalable microservices, compressing time-to-production for new automation logic.
- Platform as a Service:Managed development environments abstracting infrastructure provisioning while retaining application-level control. Mid-market technology vendors in Bangalore and Tel Aviv leverage PaaS tiers to accelerate connector development and API marketplace expansion without building underlying orchestration engines.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through programmatic interfaces. Large enterprises with mature DevOps capabilities retain IaaS for workload-specific optimization, though operational burden shifts cost structures toward in-house platform engineering teams.
SaaS captures the deepest recurring revenue pools; FaaS is climbing the fastest as event-driven architecture displaces provisioned capacity planning.
End User:
Procurement sophistication and compliance surface area scale with organizational complexity, concentrating vendor R&D investment on entities with multi-year contract horizons.
- Large Enterprises:Complex governance requirements spanning multiple jurisdictions and business units. US Fortune 500 manufacturers and European pharmaceutical conglomerates demand FedRAMP authorization, ISO 27001 certification, and regional data residency as baseline procurement filters, extending sales cycles but locking in multi-million-dollar annual commitments.
- Government Institutions:Sovereign cloud mandates and public audit trails dominate vendor selection. US federal agencies under OMB cloud-first directives and EU member state digital ministries prioritize pre-certified platforms with human-in-the-loop governance modules to satisfy emerging AI Act liability frameworks.
- Small Enterprises:Price-sensitive adopters prioritizing rapid deployment over customization depth. Indian textile exporters and Brazilian agricultural cooperatives leverage standardized SaaS tiers with pre-built connectors to common productivity suites, accepting functional constraints for sub-thousand-dollar monthly subscriptions.
- Non-Profits:Grant-dependent budgets and volunteer-driven implementation capacity. US healthcare NGOs and international development organizations seek discounted pricing tiers and donor-reporting workflow templates, representing fragmented demand with limited expansion potential for premium feature roadmaps.
Large Enterprises anchor vendor profitability; Government Institutions are gaining share fastest as sovereign cloud procurement pipelines accelerate.
Application:
Workflow automation value crystallizes around document velocity and cross-functional coordination pain points, with integration depth determining switching costs.
- Task Automation:Rule-based execution of repetitive operational steps across disconnected systems. US insurance claims processors and German logistics operators deploy this application tier to compress manual handoff latency, with ROI visibility driving rapid procurement decisions.
- Collaboration Tools:Real-time coordination interfaces embedding workflow triggers within communication streams. Distributed engineering teams at South Korean electronics manufacturers and Israeli cybersecurity vendors adopt these capabilities to synchronize agile development pipelines across time zones.
- Document Management:Version-controlled repositories with approval routing and compliance archiving. French legal services firms and Swiss pharmaceutical regulatory teams prioritize this application for audit trail generation and retention policy enforcement.
- Project Management:Resource allocation and milestone tracking with dependency mapping. Construction consortia in UAE and infrastructure planners in Australia leverage these workflows for multi-stakeholder coordination, though adoption lags where Gantt-chart discipline conflicts with informal execution cultures.
Task Automation absorbs the bulk of workflow engine utilization; Collaboration Tools are expanding most quickly as hybrid work patterns persist.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors cloud workflow platform development, housing dense concentrations of AI-orchestration engineering talent and venture capital deployment. The Bay Area's infrastructure shapes product roadmaps that subsequently diffuse to enterprise buyers across national boundaries.
United States
Federal agencies under OMB cloud-first directives drive procurement volume for FedRAMP-authorized platforms. HIPAA compliance requirements shape vendor engineering priorities for healthcare workflow deployments. Healthcare systems in Boston and Minneapolis anchor hybrid cloud implementations, bursting analytics workloads to public infrastructure while retaining patient records on private nodes.
Germany
Automotive manufacturers and industrial conglomerates absorb premium private cloud deployments to satisfy BSI sovereignty mandates. The EU AI Act's risk classification framework compels workflow vendors to embed human-in-the-loop governance modules. Munich and Stuttgart industrial corridors concentrate demand for air-gapped security postures with audit-controlled data residency.
India
PLI scheme incentives for IT hardware and BIS cloud security standards catalyze domestic platform adoption among manufacturing SMEs. Bangalore and Hyderabad technology clusters drive Function-as-a-Service consumption as developer teams decompose monolithic processes into serverless microservices. Mumbai financial institutions pilot API marketplace distribution models.
Japan
Industrial IoT deployments in Nagoya and Osaka manufacturing belts require workflow engines coordinating factory-floor sensors with centralized analytics. METI digital transformation subsidies accelerate edge-cloud orchestration convergence. Tokyo enterprise buyers prioritize unified observability across hybrid environments.
United Kingdom
London financial services firms leverage multi-cloud architectures for regulatory resilience across AWS, Azure, and GCP nodes. The Information Commissioner's Office enforces GDPR-aligned audit logging standards. Cambridge and Manchester technology clusters concentrate mid-market SaaS adoption for rapid deployment without data center CapEx.
Cloud Workflow Market Vendor Landscape
Premium-margin players sit above commodity-margin players across governance-layer specialization and AI-orchestration depth. The vendor base stratifies into three tiers: hyperscale cloud natives with integrated productivity suites, enterprise-grade AI agent platforms with compliance architectures, and API-centric integration specialists. Consolidation pressure intensifies as procurement committees demand single-pane observability. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through regional compliance certification.
Within the enterprise AI-orchestration tier, IBM Watsonx Orchestrate and Salesforce Agentforce exemplify governance-layer specialization, embedding auditable decision frameworks for regulated industries. Microsoft Power Automate occupies a position bridging mid-market productivity automation with hyperscale infrastructure, leveraging Office 365 integration density to compress procurement cycles.
| Leading Market Players |
|---|
| Workato |
| Salesforce Agentforce |
| Microsoft Power Automate |
| Prompts.ai |
| IBM Watsonx Orchestrate |
| Google Cloud Vertex AI |
| Tray.io |
| CloudBolt |
| AWS Bedrock AgentCore |
| Others |
Supply Flow & Price Mechanics
Serverless function decomposition is compressing unit economics for cloud workflow execution while redistributing supply concentration toward hyperscaler data center clusters in Northern Virginia, Frankfurt, and Singapore. This architectural shift simultaneously erodes traditional per-seat pricing power and concentrates infrastructure procurement leverage among AWS, Azure, and GCP operators.
Pricing Analysis
Outcome-based pricing tied to workflow throughput and automation yield anchors enterprise SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized governance modules from commodity task-automation tools. Pricing pressure stems from Function-as-a-Service consumption models displacing provisioned capacity planning. Small enterprises exhibit highest price sensitivity, while government institutions absorb premiums for pre-certified compliance architectures.
Supply Chain Analysis
Freight costs for specialized hardware remain negligible as software delivery dominates distribution economics. Compute infrastructure concentrates in the United States, Germany, and India where hyperscaler regions intersect with data sovereignty mandates. Supply chains draw from semiconductor foundries in Taiwan, memory manufacturers in South Korea, and networking equipment producers in China. Single-source vulnerability around AI accelerator chips poses structural risk. Distribution runs through direct hyperscaler marketplaces and API-first developer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud workflow automation sits in a technology-transition phase as agentic AI capabilities displace rule-based orchestration engines. Legacy BPM suites face compressed replacement cycles as elastic infrastructure demands reshape procurement criteria.
For Market Incumbents: Deploy governance-layer specialization as the primary defensive lever. Embed EU AI Act-compliant explainability modules and human-in-the-loop checkpoints to preempt regulatory displacement. Accelerate ISO 27001 and FedRAMP certification pipelines to raise barriers against emerging entrants. Consolidate around unified observability platforms as procurement committees displace point solutions.
For New Entrants and Emerging Players: Begin with API marketplace distribution models targeting Indian manufacturing SMEs under PLI scheme incentives. White-space concentration exists in edge-cloud orchestration for Japanese industrial IoT deployments. Pursue serverless-native architectures to bypass incumbent integration entrenchment with SAP and Oracle workflow engines.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking governance-layer capabilities. Long-term viability favors vendors with pre-certified compliance modules and recurring SaaS revenue depth. Monitor FedRAMP authorization timelines as an inflection signal for federal procurement pipeline velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified observability across hybrid environments satisfies US healthcare HIPAA compliance requirements. |
| Geographic Expansion | Regional compliance certification accelerates EU AI Act procurement pipelines in Germany and France. |
| Strategic Partnership | Systems integrator alliances bypass traditional channel friction for mid-market SaaS adoption. |
| Product Launch | Agentic AI capabilities with built-in governance satisfy emerging liability frameworks in Brussels. |
| Acquisition of Specialist Firm | Serverless abstraction layers compress time-to-production for event-driven microservices development. |
Methodological Framework
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineer assessments underwrites the qualitative findings. Primary fieldwork engaged cloud architects at US healthcare systems, DevOps leads at German automotive manufacturers, and integration specialists at Indian technology clusters. Secondary validation drew from hyperscaler capex disclosures, SEC filings of publicly traded workflow vendors, and EU regulatory submission databases. Bottom-up segment sizing triangulated against top-down market aggregation.
Rate-of-change decomposition across deployment models, organization scales, and vertical applications structured the analytical framework. Segmentation dimensions modeled include public-private-hybrid-multi-cloud architecture, SaaS-PaaS-FaaS-IaaS service tiers, and regional adoption patterns shaped by data sovereignty mandates. CAGRs were derived from elasticity-adjusted growth curves incorporating AI agency regulatory velocity and serverless adoption trajectories. Industry-specific inputs included FedRAMP authorization pipeline data and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; government institution forecasts carry tighter precision than non-profit projections due to visible procurement pipeline documentation. Forecasts reflect documented assumptions around regulatory implementation schedules and hyperscaler capacity expansion plans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Cloud Data Quality Radar Market