
 Global Health Cloud Market | 2026-2036
Global Health Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Global Health Cloud Market Foresight
North American hyperscaler infrastructure is broadening its dedicated health cloud footprint. Amazon Web Services leverages specialized HIPAA-compliant architectures to anchor federal and hospital contracts. Microsoft competes through deep integration with existing clinical workflows and enterprise productivity stacks. Oracle sustains relevance via its vertical push into electronic health records and revenue cycle management systems.
Health cloud denotes a specialized cloud computing environment engineered to store, process, and exchange protected health information with adherence to strict encryption, access control, and audit trail protocols; its primary purpose is to enable scalable clinical data interoperability while reducing on-premise IT capital burden for healthcare delivery organizations. The solution type dimension shows electronic health records and telemedicine platforms commanding the largest installed bases, while clinical analytics is gaining fastest as health systems prioritize population health insights over transactional record-keeping. Within deployment, hybrid cloud architectures are absorbing disproportionate investment as institutions balance latency-sensitive imaging workloads against cost-efficient archival storage.
FDA oversight of software-as-medical-device, HIPAA security rule enforcement by the Department of Health and Human Services, and the EU AI Act's risk classification for clinical decision-support algorithms collectively elevate compliance architecture to a competitive differentiator rather than a cost center. Health Canada and the PMDA in Japan are converging toward similar algorithmic transparency mandates, fragmenting certification pathways for vendors with transnational ambitions. Stakeholders must now decide whether to architect for the strictest jurisdictional standard upfront or absorb retrofit costs as regulatory parity spreads.
Market Dynamics
Hybrid cloud architectures are absorbing disproportionate investment as hospital systems balance latency-sensitive imaging workloads against cost-efficient archival storage, fundamentally restructuring procurement priorities for infrastructure vendors.
Growth Catalysts
- EU AI Act risk classification:The regulation's tiered approach to clinical decision-support algorithms is compelling healthcare providers to upgrade cloud governance frameworks, creating immediate infrastructure refresh cycles.
- Telemedicine platform consolidation:Post-pandemic virtual care workflows now require scalable, interoperable backends that only specialized health cloud environments can provision reliably.
- Germany's sovereign health cloud buildout:Siemens Healthineers and hospital networks are constructing domestic capacity, generating concentrated demand for compliant data residency solutions.
Market Restraints
- Cross-border data friction:GDPR's extraterritorial enforcement and the EU AI Act's data governance requirements are fragmenting certification pathways for vendors with transnational ambitions.
- Specialized talent scarcity:Health cloud architecture demands hybrid expertise spanning clinical informatics, cybersecurity, and cloud engineering that existing labor pools cannot supply.
- Legacy system entrenchment:Decades of on-premise electronic health record deployments create technical debt that retards migration velocity even where cloud economics are favorable.
Strategic Opportunities
- Clinical analytics acceleration:Population health insights are displacing transactional record-keeping as the primary value proposition, opening whitespace for predictive modeling platforms.
- Japan's algorithmic transparency convergence:PMDA mandates are aligning with EU standards, creating regulatory harmonization that simplifies multi-jurisdictional product strategy.
- Federal contract anchoring:HIPAA-compliant architectures are securing long-term infrastructure commitments from United States government health programs and integrated delivery networks.
Industry Challenges
- Interoperability standardization delays:Competing health data exchange protocols prevent seamless patient record portability across cloud environments.
- Software-as-medical-device recertification:FDA oversight of algorithm updates forces continuous compliance monitoring that strains vendor operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Health Cloud Market |
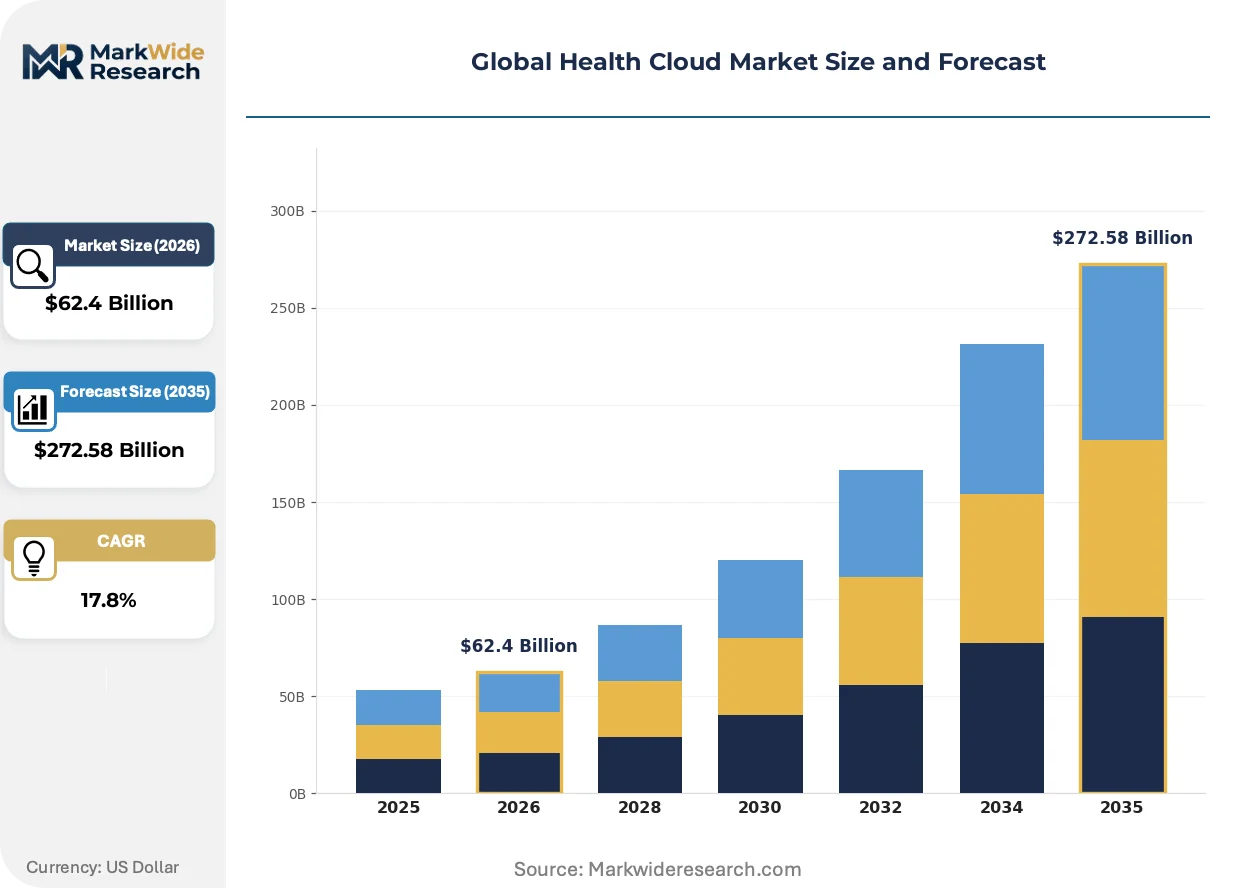
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $272.58 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Cloud, Public Cloud, Hybrid Cloud, Community Cloud Solution Type: Electronic Health Records, Telemedicine Platforms, Clinical Analytics, Revenue Cycle Management, Patient Engagement Application: Remote Patient Monitoring, Health Data Management, Medical Imaging, Virtual Consultations, Drug Development End User: Hospitals, Diagnostic Centers, Research Institutes, Insurance Companies, Pharmaceutical Firms |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Oracle, Salesforce, Siemens Healthineers, Koninklijke Philips, athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Health Cloud Market Shifts & Advancements
Federated learning architectures and zero-trust security models are actively displacing perimeter-based defenses in health cloud deployments, while regulatory pressure accelerates algorithmic transparency tooling.
Federated learning infrastructure is unifying distributed training of clinical AI models without centralizing sensitive patient data. Academic medical centers and pharmaceutical researchers are adopting these frameworks to collaborate across institutional boundaries. This approach is unifying previously siloed research cohorts while compressing time-to-insight for rare disease studies.
The EU AI Act's high-risk system classification is mandating conformity assessments for clinical decision-support algorithms before market deployment. Vendors must now maintain technical documentation, human oversight protocols, and accuracy metrics that exceed prior CE marking requirements. European hospital procurement committees are prioritizing pre-certified solutions, advantaging incumbents with compliance infrastructure already operational.
Subscription-based infrastructure provisioning is displacing capital-intensive on-premise ownership among mid-size hospital systems. Chief information officers now favor operational expenditure models that align cloud costs with patient volume fluctuations. This shift is most visible in United States regional health networks consolidating previously independent facility IT estates.
Global Health Cloud Market Segmentation
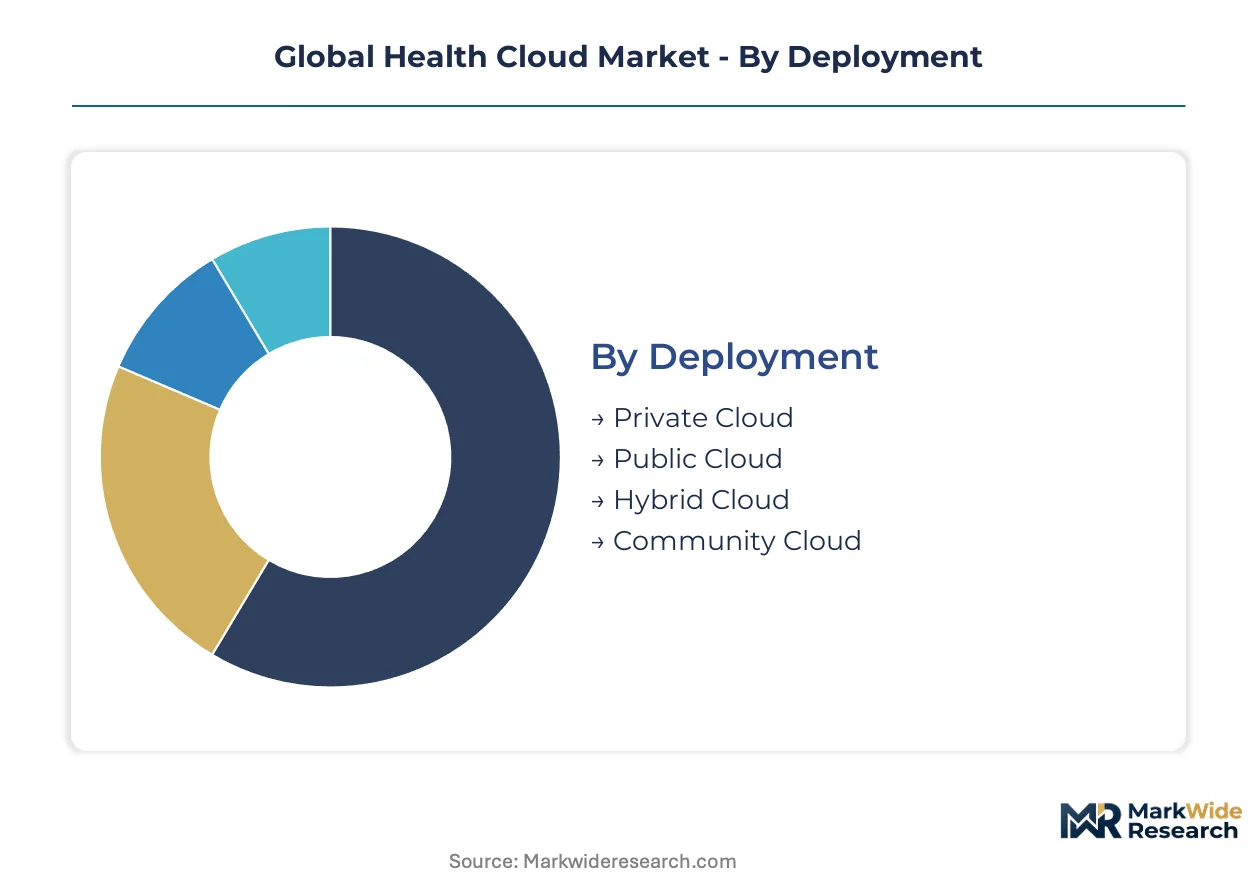
Health cloud procurement varies sharply by infrastructure topology, clinical workload, and regulatory exposure. Buyers weigh data residency mandates against elasticity needs when selecting deployment models. Solution preferences diverge between transaction-heavy providers and insight-driven health systems.
Deployment:
Buyers prioritize latency performance and compliance architecture when committing to infrastructure topology.
- Private Cloud:Dedicated single-tenant environments isolate patient data within institutional firewalls. German hospital networks and Siemens Healthineers sovereign cloud buildouts favor this model to satisfy GDPR data residency requirements.
- Public Cloud:Multi-tenant hyperscale infrastructure delivers elastic compute for variable clinical workloads. United States federal health programs anchor long-term contracts on HIPAA-compliant AWS and Microsoft architectures.
- Hybrid Cloud:Split architectures balance real-time imaging processing against cold archival storage. United States regional health networks consolidating independent facility IT estates favor operational expenditure alignment with patient volume fluctuations.
- Community Cloud:Shared infrastructure serving affiliated healthcare organizations with common compliance frameworks. Research consortiums and integrated delivery networks pool resources to amortize specialized security investments.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Solution Type:
Procurement patterns track the shift from transactional record-keeping toward predictive clinical intelligence.
- Electronic Health Records:Core clinical data repositories supporting longitudinal patient documentation. Oracle sustains market presence through vertical integration into revenue cycle management and EHR consolidation plays.
- Telemedicine Platforms:Virtual care delivery infrastructure requiring scalable, interoperable backends. Post-pandemic workflow permanence drives replacement of ad-hoc video tools with purpose-built health cloud environments.
- Clinical Analytics:Population health insight engines processing multi-source data for predictive modeling. Academic medical centers in the United States prioritize these platforms for rare disease cohort studies.
- Revenue Cycle Management:Financial operations automation spanning claims processing to patient billing. Mid-size hospital systems favor subscription provisioning to align costs with reimbursement volatility.
- Patient Engagement:Consumer-facing portals and mobile applications for appointment scheduling and health education. European hospital procurement committees prioritize solutions with pre-certified EU AI Act conformity assessments.
Electronic Health Records dominate installed base; Clinical Analytics expands most quickly.
Application:
Workload characteristics determine infrastructure investment intensity across clinical domains.
- Remote Patient Monitoring:Continuous physiological data ingestion from wearable and home-based devices. Chronic disease management programs in Japan align with PMDA algorithmic transparency mandates.
- Health Data Management:Master data governance and interoperability orchestration across disparate clinical systems. GDPR extraterritorial enforcement complicates cross-border health data flows for multinational deployments.
- Medical Imaging:High-resolution radiology storage and AI-assisted diagnostic interpretation. Latency-sensitive PACS workloads favor edge-proximate hybrid architectures over pure cloud migration.
- Virtual Consultations:Synchronous video encounters integrated with clinical documentation workflows. United States regional networks consolidate previously siloed telehealth point solutions.
- Drug Development:Secure collaboration environments for pharmaceutical research and clinical trial data management. Federated learning frameworks enable cross-institutional AI training without centralizing sensitive patient records.
Medical Imaging commands infrastructure spend; Remote Patient Monitoring shows steepest expansion trajectory.
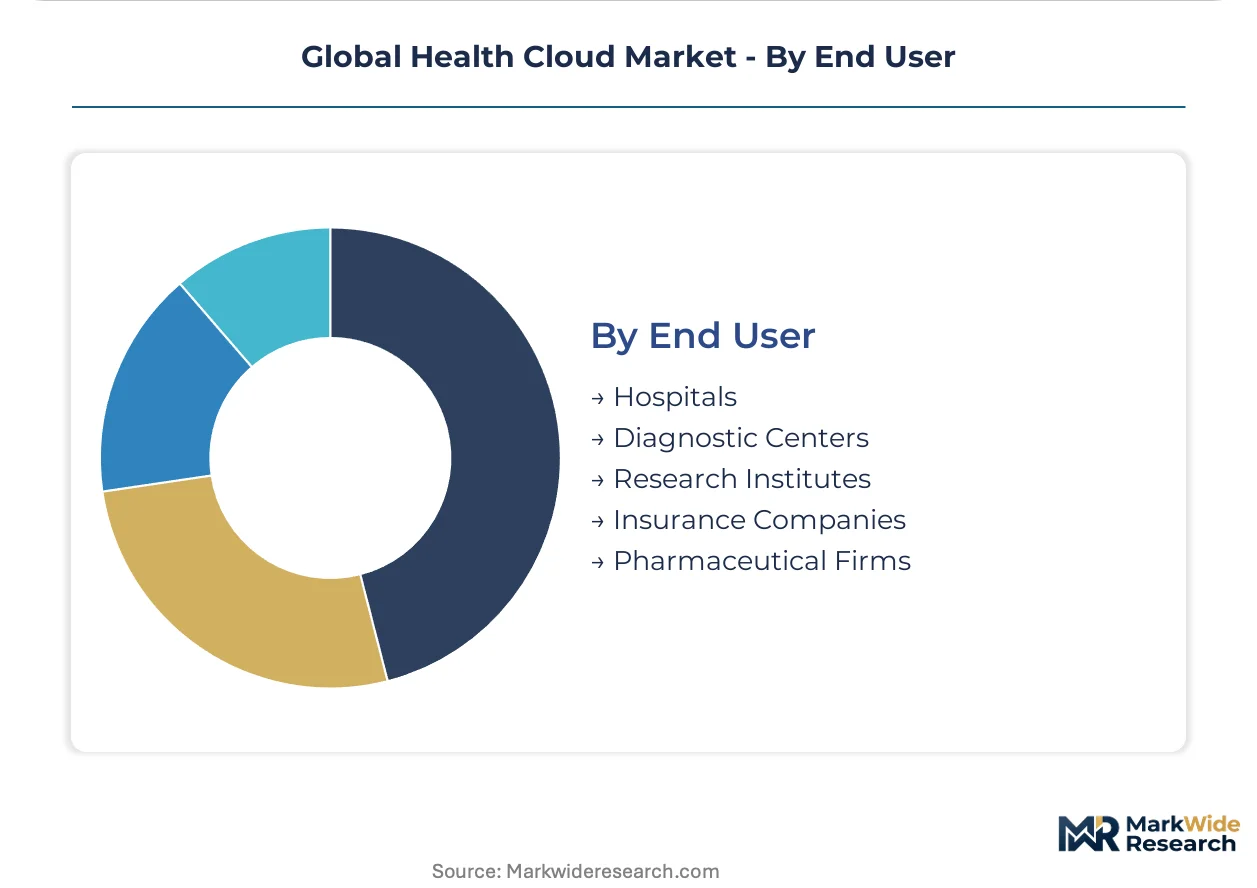
End User:
Organizational scale and regulatory exposure shape cloud maturity and procurement sophistication.
- Hospitals:Acute care delivery organizations with complex multi-departmental IT requirements. United States integrated delivery networks drive disproportionate hybrid cloud investment.
- Diagnostic Centers:Specialized imaging and laboratory service providers with high-throughput data generation. German radiology networks participate in sovereign health cloud capacity construction.
- Research Institutes:Academic and government laboratories conducting population-scale health studies. Federated learning adoption concentrates at United States academic medical centers and European pharmaceutical collaborators.
- Insurance Companies:Payers analyzing claims patterns and risk stratification across member populations. HIPAA security rule enforcement elevates compliance architecture to competitive differentiator status.
- Pharmaceutical Firms:Drug manufacturers managing clinical trial data and real-world evidence platforms. EU AI Act high-risk system classification mandates conformity assessments for algorithmic decision-support tools.
Hospitals anchor volume; Research Institutes drive specialized architecture innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure and specialized health IT talent pools concentrate demand generation across distinct national markets. Regulatory divergence around patient data residency and algorithmic governance fragments procurement patterns. Sovereign cloud buildouts in Germany and Japan exemplify how industrial policy reshapes vendor selection criteria.
United States
Federal health programs and integrated delivery networks drive hyperscale contract volumes. HIPAA security rule enforcement by the Department of Health and Human Services elevates compliance architecture to procurement differentiator status. The Washington D.C.-to-Boston corridor anchors concentration of health cloud engineering talent and federal contracting expertise.
Germany
Siemens Healthineers and hospital networks are constructing domestic sovereign capacity to satisfy data localization mandates. GDPR extraterritorial enforcement and the EU AI Act's risk classification for clinical algorithms tighten governance requirements. The Munich-Frankfurt corridor concentrates health IT vendor operations and academic medical center pilot deployments.
Japan
Chronic disease management programs and aging demographics accelerate remote patient monitoring platform adoption. PMDA algorithmic transparency mandates converge toward EU standards, simplifying multi-jurisdictional product certification. The Tokyo-Osaka axis hosts pharmaceutical research consortia deploying federated learning frameworks for cross-institutional AI training.
United Kingdom
National Health Service consolidation of previously independent trust IT estates creates procurement scale for hybrid cloud architectures. NHS Digital interoperability mandates and post-Brexit data adequacy negotiations complicate cross-border health data flows. London's health tech cluster attracts venture investment in clinical analytics platforms serving population health programs.
India
Telemedicine platform proliferation and government digital health infrastructure investment expand addressable market. CDSCO oversight of software-as-medical-device and proposed data protection legislation create evolving compliance parameters. Bengaluru and Hyderabad concentrate health tech engineering talent and startup activity in clinical workflow automation.
Global Health Cloud Market Competitive Landscape
Global majors compete with regional champions across compliance architecture and clinical workflow integration. The vendor base organizes around three strategic archetypes: hyperscale infrastructure providers with dedicated health cloud verticals, enterprise software vendors with vertical EHR consolidation plays, and medical technology specialists building sovereign data residency solutions. Competitive moves concentrate on M&A for workflow integration capabilities and strategic partnerships for regulatory certification acceleration.
Within the hyperscale tier, Amazon Web Services, Microsoft, and Oracle occupy positions exemplifying divergent market entry strategies. AWS anchors federal and hospital contracts through specialized HIPAA-compliant architectures. Microsoft represents deep integration plays with existing clinical productivity stacks. Oracle exemplifies vertical consolidation approaches into electronic health records and revenue cycle management systems.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Salesforce |
| Siemens Healthineers |
| Koninklijke Philips |
| athenahealth |
| Others |
Supply & Pricing Matrix
Hyperscale data center power pricing indices in Northern Virginia and Frankfurt cascade through health cloud provisioning tiers, compressing margins for mid-tier vendors while anchoring premium pricing for HIPAA-compliant and GDPR-sovereign deployments.
Pricing Analysis
Warranty and compliance-certification bundling separates premium health cloud tiers from unbundled infrastructure-only offerings. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade (FDA 510(k) pathway completion, EU AI Act conformity assessment) and geographic data residency. Pricing pressure stems from hyperscale commoditization of baseline compute, forcing mid-tier vendors toward specialized clinical workflow integration. Mid-size United States regional health networks exhibit highest price sensitivity; German sovereign cloud buyers accept premium positioning for guaranteed GDPR data localization.
Supply Chain Analysis
Specialized health cloud engineering talent scarcity in Bengaluru, Hyderabad, and the Washington D.C.-to-Boston corridor constrains delivery capacity for compliant architecture deployments. Supply concentration draws from Taiwan for advanced server silicon, Ireland for EU data center infrastructure, and Germany for precision medical device integration components. Single-source vulnerability sits with NVIDIA GPU allocations for clinical AI training workloads. Distribution runs through direct enterprise sales teams for hospital systems and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized health cloud architecture talent scarcity props pricing power for vendors with pre-built compliance infrastructure, creating supply-constrained conditions favoring incumbents with certified delivery capacity.
For Market Incumbents: To counter hyperscale commoditization pressure, anchor federal and integrated delivery network contracts through HIPAA-compliant architecture pre-certification. Deepen backward integration into clinical analytics platforms to capture population health insight budgets displacing transactional EHR spending. For New Entrants and Emerging Players: Cloud-native telemedicine backend specialization offers the most penetrable white-space, as post-pandemic virtual care workflow consolidation demands scalable infrastructure. Target India's mid-tier hospital networks through CDSCO-aligned software-as-medical-device certification pathways and subscription-based operational expenditure models. For Investors and Strategic Acquirers: Distressed-cycle entries favor clinical analytics specialists with EU AI Act pre-certification in Germany and Japan, where PMDA convergence creates regulatory harmonization. Watch federated learning framework adoption rates at United States academic medical centers as inflection signal for platform consolidation viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Pre-Certification | European hospital procurement committees now prioritize pre-certified clinical decision-support algorithms over retrofit-capable alternatives. |
| Federated Learning Platform Development | Academic medical centers in the United States and pharmaceutical researchers adopt distributed AI training to collaborate across institutional boundaries. |
| Hybrid Cloud Architecture Specialization | United States regional health networks consolidate independent facility IT estates with latency-sensitive imaging workloads balanced against archival storage. |
| Sovereign Health Cloud Capacity Construction | Siemens Healthineers and German hospital networks build domestic data residency infrastructure satisfying GDPR localization mandates. |
| Clinical Workflow Integration Partnership | Microsoft leverages deep enterprise productivity stack integration to anchor hospital system contracts against AWS federal specialization. |
Research Methodology
SEC 10-K filings from hyperscale infrastructure providers, CMS Medicare reimbursement databases, and EU AI Act implementation guidance documents formed the secondary backbone. Primary interviews with hospital chief information officers, biomedical engineers, GPO contracts managers, and health cloud platform engineers combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across deployment model adoption curves informed the analytical framework. Segmentation dimensions modeled include infrastructure topology, clinical workload type, regulatory exposure tier, and regional certification pathway complexity. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Forecast inputs incorporated hyperscale data center capex disclosures and hospital IT budget allocation surveys.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act audit frequency or FDA software-as-medical-device recertification timelines would shift vendor competitive positioning. Forecasts reflect assumptions about compliance cost trajectories and interoperability standardization progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Global Cloud Discovery Market