
 Cloud Native Technologies Market | 2026-2036
Cloud Native Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Native Technologies Market Analysis
GDPR is rebalancing data residency requirements across European cloud native deployments, compelling vendors to engineer region-specific isolation layers. Microsoft Azure sustains heavy investment in confidential computing enclaves for regulated European workloads. Google Cloud differentiates through Anthos multi-cloud orchestration that navigates fragmented sovereignty rules. Amazon Web Services dominates dedicated local zones, extending physical infrastructure control to national governments.
Cloud native technologies encompass containerized application architectures orchestrated through systems like Kubernetes, enabling elastic scaling through declarative infrastructure-as-code definitions and automated service discovery. These platforms eliminate OS-level dependencies via lightweight runtime isolation, primarily serving enterprises seeking to decouple software release velocity from underlying hardware provisioning cycles. Microservices architectures fragment monolithic codebases into independently deployable units, concentrating margin pools in API gateway and service mesh layers where traffic management complexity escalates. Serverless computing captures fastest growth among technology segments by abstracting all infrastructure management, though containers retain dominant deployment volume across hybrid cloud configurations bridging on-premises and public environments.
FDA scrutiny of cloud-hosted medical device software through 21 CFR Part 820 quality system regulations shapes healthcare vertical adoption patterns, forcing container image provenance tracking. EMA guidelines on GxP data integrity extend to cloud native audit trails, while HIPAA security rule enforcement by OCR elevates encryption-at-rest standards for patient-facing microservices. Stakeholders must weigh sovereign cloud mandates against interoperability costs as national regulators fragment certification requirements.
Market Dynamics
Financial services firms are accelerating container adoption to modernize core banking platforms, while the EU AI Act imposes algorithmic transparency mandates on automated cloud workloads, creating a dual pressure of modernization urgency and compliance complexity.
Growth Catalysts
- Container orchestration:Kubernetes has become the de facto standard for elastic scaling through declarative infrastructure-as-code definitions, with enterprises decoupling software release velocity from hardware provisioning cycles.
- EU AI Act compliance:Algorithmic transparency mandates on automated cloud workloads are forcing enterprises to adopt observable, auditable cloud native architectures.
- Automotive OEM demand:German manufacturers are building sovereign cloud native stacks for connected vehicle data pipelines, concentrating demand in regulated industrial verticals.
Market Restraints
- Specialized talent scarcity:Shortages of Kubernetes-certified platform engineers and site reliability engineers inflate labor costs and extend deployment timelines.
- Multi-cloud fragmentation:Divergent sovereignty requirements across EU member states force redundant infrastructure investments that erode economies of scale.
- Legacy system entanglement:Core banking and healthcare record systems resist containerization due to hardcoded OS dependencies and proprietary middleware.
Strategic Opportunities
- Confidential computing:Hardware-based enclaves for regulated European workloads address GDPR-mandated data residency through cryptographic isolation rather than physical infrastructure duplication.
- Serverless abstraction:Function-as-a-service platforms capture fastest growth by eliminating node management entirely, appealing to enterprises with limited DevOps capacity.
- Healthcare vertical expansion:FDA 21 CFR Part 820 quality system regulations and EMA GxP guidelines create certified cloud native demand for medical device software and audit trail integrity.
Industry Challenges
- Container image provenance:Healthcare and financial services require immutable supply chain tracking for every layer in distributed microservices architectures.
- Service mesh complexity:Traffic management, mTLS certificate rotation, and observability instrumentation across hundreds of ephemeral pods overwhelm existing operational teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Native Technologies Market |
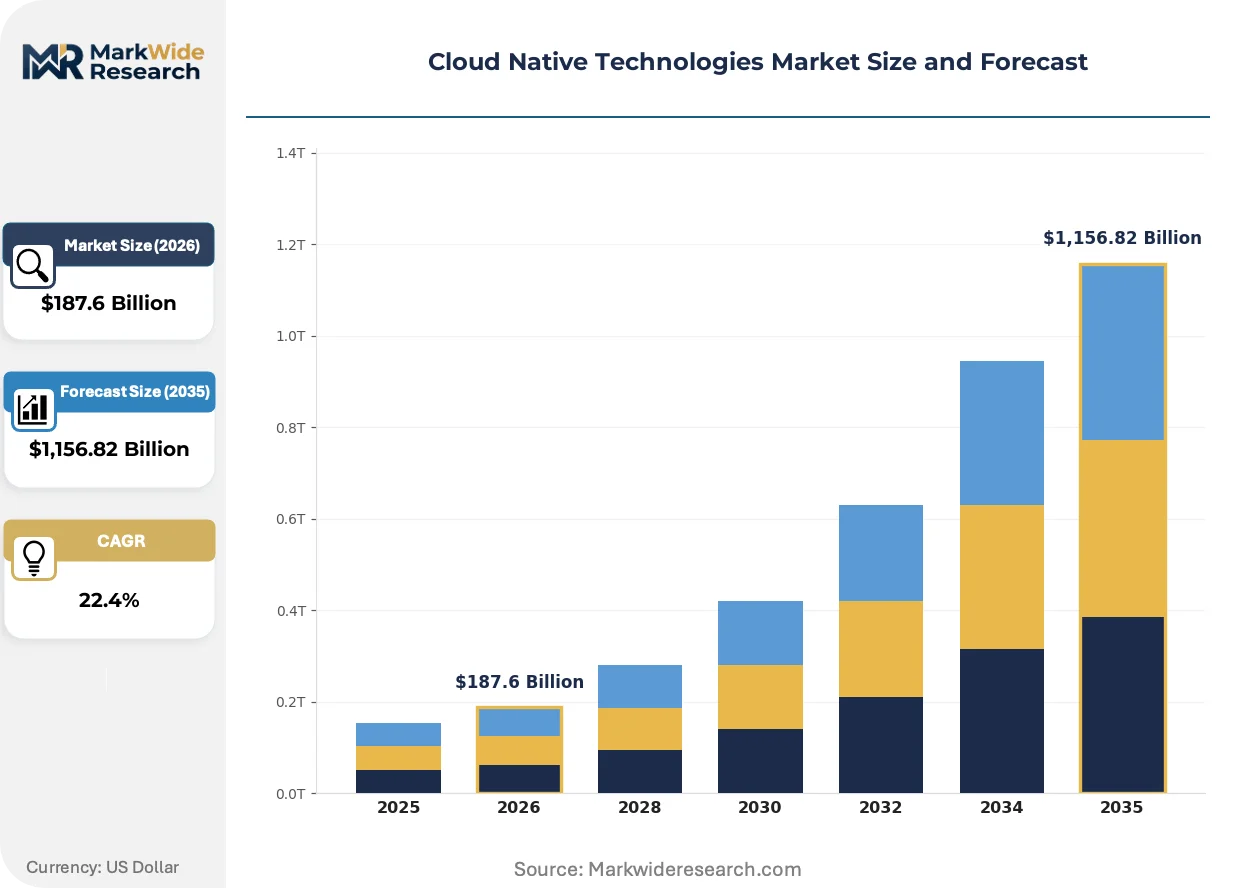
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $1,156.82 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Microservices, Containers, Serverless Computing, Service Mesh Industry Vertical: Financial Services, Telecommunications, Healthcare, Retail Solution Offering: Monitoring Tools, CI/CD Pipelines, API Management, Development Frameworks |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Corporation, IBM, Alibaba Cloud, Huawei Cloud, Tencent Cloud, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Native Technologies Market Emerging Trajectories
Cloud native architectures are fragmenting monolithic codebases into independently deployable units, concentrating competitive advantage in API gateway and service mesh layers where operational complexity escalates fastest.
GitOps is automating infrastructure lifecycle management through version-controlled declarative configurations, with platform teams at financial services and automotive OEMs adopting it aggressively to reduce configuration drift. This operational model compresses incident recovery times and enforces audit trails that satisfy EU AI Act transparency requirements.
GDPR is rebalancing data residency requirements across European cloud native deployments, compelling vendors to engineer region-specific isolation layers rather than centralized global architectures. Microsoft Azure sustains heavy investment in confidential computing enclaves for regulated European workloads, while Google Cloud differentiates through Anthos multi-cloud orchestration that navigates fragmented sovereignty rules.
Buyer procurement patterns are hardening around sovereign cloud mandates that prioritize national data control over interoperability and cost efficiency. German automotive OEMs and French healthcare systems now specify domestic infrastructure zones as non-negotiable contract terms, fragmenting vendor addressable markets and elevating dedicated local zone investments by hyperscalers.
Cloud Native Technologies Market Segmentation
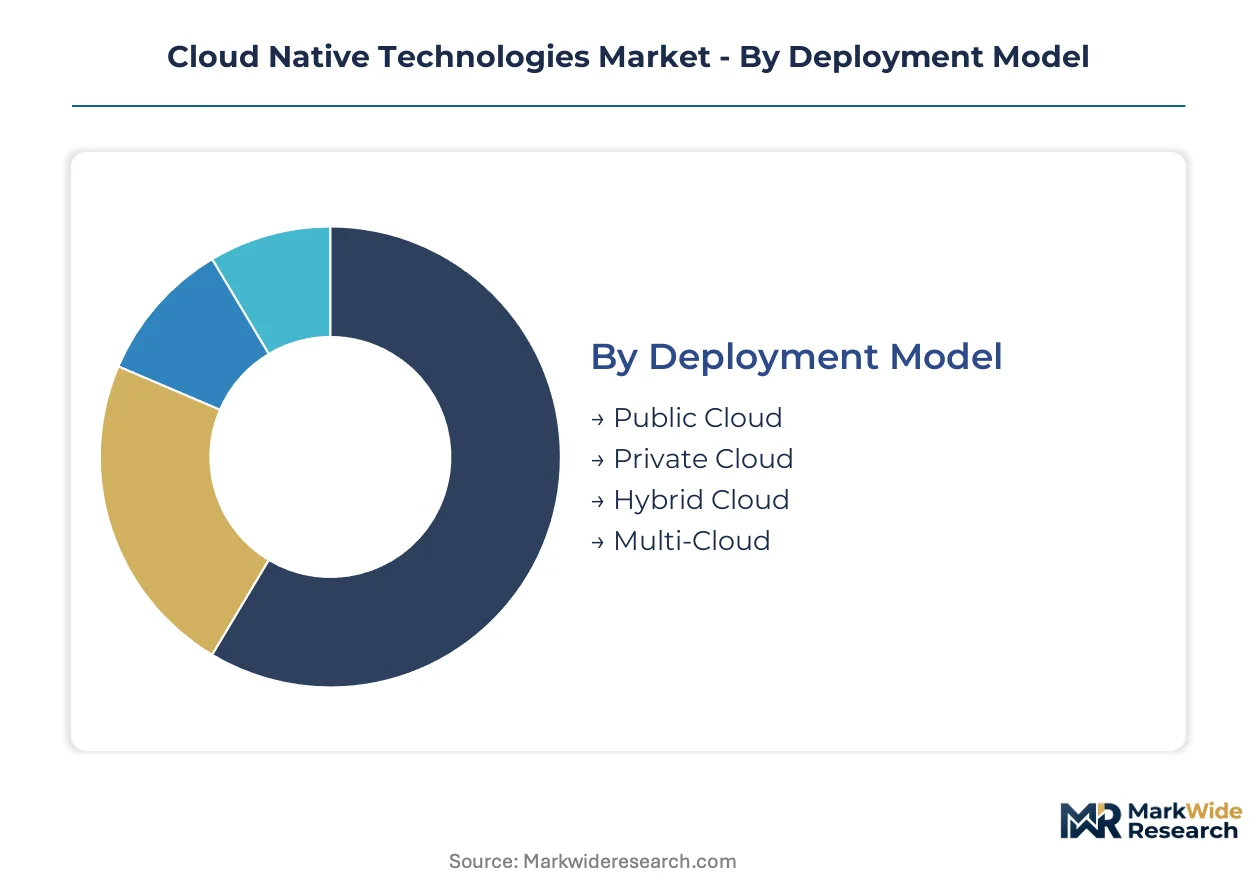
Cloud native architectures fragment along deployment topology and abstraction layers, with procurement decisions increasingly driven by sovereignty mandates and legacy system constraints rather than pure performance optimization.
Deployment Model:
Standalone cloud environments serve isolated compliance requirements, while embedded multi-cloud configurations integrate orchestration across heterogeneous infrastructure estates.
- Public Cloud:Hyperscaler-managed infrastructure delivers elastic compute through shared tenant isolation. German automotive OEMs and French healthcare systems now specify domestic infrastructure zones as non-negotiable contract terms, fragmenting vendor addressable markets.
- Hybrid Cloud:Workload portability bridges on-premises data centers with public capacity pools, enabling financial services firms to modernize core banking platforms without full cloud migration. Kubernetes federation across boundaries introduces operational complexity that elevates platform engineering costs.
- Private Cloud:Dedicated infrastructure serves classified government workloads and proprietary industrial control systems with complete physical isolation.
- Multi-Cloud:Orchestration layers abstract vendor-specific APIs, though divergent sovereignty requirements across EU member states force redundant infrastructure investments.
Public cloud leads volumes today; multi-cloud is gaining share fastest.
Technology:
Abstraction depth determines operational overhead, with lower-level runtime technologies commanding larger deployment volumes and higher-layer platforms capturing expanding margins.
- Containers:Lightweight OS-level virtualization packages applications with dependencies into portable images. FDA scrutiny through 21 CFR Part 820 quality system regulations forces container image provenance tracking across healthcare deployments.
- Serverless Computing:Function-as-a-service platforms eliminate node management entirely, appealing to enterprises with limited DevOps capacity. This segment climbs fastest as event-driven architectures displace always-on container clusters for intermittent workloads.
- Microservices:Decomposed application architectures fragment monolithic codebases into independently deployable units, concentrating margin pools in API gateway layers.
- Service Mesh:Sidecar proxies manage traffic, security, and observability across distributed services, though mTLS certificate rotation and instrumentation overwhelm existing operational teams.
Containers lead volumes today; serverless computing is expanding most quickly.
Industry Vertical:
Regulatory intensity varies sharply across sectors, with life sciences and financial services facing audit trail mandates that consumer-facing industries bypass.
- Financial Services:Container adoption accelerates for core banking platform modernization, while EU AI Act algorithmic transparency mandates impose dual pressure of modernization urgency and compliance complexity.
- Healthcare:EMA guidelines on GxP data integrity extend to cloud native audit trails, and HIPAA security rule enforcement elevates encryption-at-rest standards for patient-facing microservices.
- Telecommunications:Network function virtualization replaces proprietary hardware with containerized packet processing at the network edge.
- Retail:Elastic scaling supports seasonal demand spikes without overprovisioning baseline capacity.
Financial services leads volumes today; healthcare is climbing the fastest.
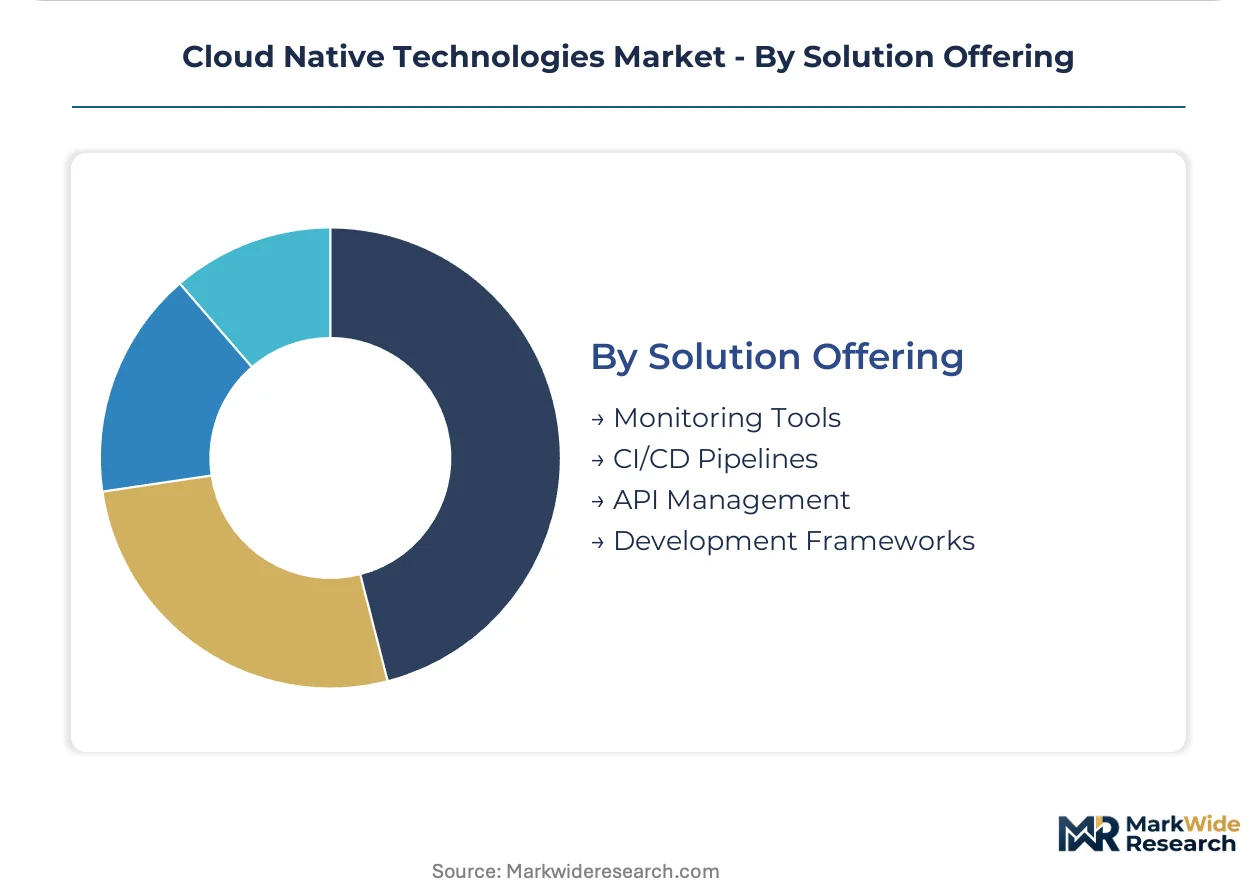
Solution Offering:
Tooling procurement concentrates in pipeline automation and observability layers where vendor switching costs accumulate fastest.
- CI/CD Pipelines:Automated build-test-deploy workflows compress release cycles from weeks to hours. GitOps adoption at automotive OEMs enforces version-controlled declarative configurations that satisfy EU AI Act audit requirements.
- Monitoring Tools:Distributed tracing and metrics aggregation tackle observability gaps across ephemeral container fleets. Platform teams demand unified telemetry as service mesh complexity escalates.
- API Management:Gateway layers control traffic routing, rate limiting, and protocol translation between microservices.
- Development Frameworks:Pre-configured scaffolding accelerates containerized application construction with embedded security scanning.
Monitoring tools lead volumes today; CI/CD pipelines show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud native technologies originated in Silicon Valley's hyperscaler data centers before diffusing through financial hubs and manufacturing clusters worldwide. The technology stack now penetrates regulated industries across distinct national markets with varying sovereignty requirements.
United States
Financial services firms in New York and Chicago drive container adoption for core banking modernization, while healthcare systems in Boston and the Research Triangle face FDA 21 CFR Part 820 scrutiny for medical device software. The SEC's cybersecurity disclosure rules now mandate cloud workload transparency for publicly traded enterprises.
Germany
Automotive OEMs in Stuttgart and Munich build sovereign cloud native stacks for connected vehicle data pipelines under KBA oversight. The EU AI Act's algorithmic transparency mandates intersect with Germany's BSI IT security standards, forcing dual compliance architectures for automated manufacturing systems.
United Kingdom
London's fintech cluster accelerates Kubernetes deployment for payment infrastructure, while NHS trusts in Manchester and Birmingham navigate HIPAA-equivalent data residency requirements. The Financial Conduct Authority's operational resilience rules now explicitly cover third-party cloud service providers.
Japan
Tokyo's financial institutions modernize legacy mainframe systems through hybrid cloud configurations, with METI promoting cloud native adoption in manufacturing supply chains. Osaka-based electronics manufacturers deploy edge-native containers for factory automation under revised JIS standards.
India
Bengaluru's IT services exporters build multi-tenant Kubernetes platforms for global clients, while Mumbai's banks navigate RBI data localization mandates for payment systems. The MeitY's cloud computing guidelines now require government workloads to run on empaneled domestic infrastructure providers.
Cloud Native Technologies Market Vendor Landscape
The competitive structure tilts toward hyperscale cloud providers with integrated platform stacks. Three distinct archetypes populate the vendor landscape: full-stack infrastructure operators with managed Kubernetes services, enterprise software incumbents retrofitting legacy portfolios, and regional cloud specialists serving data sovereignty requirements. M&A activity concentrates on container security and observability tooling acquisitions, while strategic partnerships between hardware vendors and orchestration platforms accelerate confidential computing deployments.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by infrastructure breadth and regional zone expansion. These entities exemplify the platform-operator archetype through integrated compute-storage-networking stacks with native Kubernetes control planes. Chinese market presence falls to Alibaba Cloud, Huawei Cloud, and Tencent Cloud, which anchor sovereign cloud strategies under domestic regulatory frameworks. Oracle Corporation and IBM represent the enterprise-legacy transition archetype, retrofitting database and middleware franchises for containerized deployment patterns.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Corporation |
| IBM |
| Alibaba Cloud |
| Huawei Cloud |
| Tencent Cloud |
| SAP |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across hyperscaler infrastructure stacks anchors supply position and pricing power, with AWS, Azure, and Google Cloud consolidating orchestration layers while regional specialists fragment at the sovereignty-compliant edge. This integration choice concentrates margin capture in managed Kubernetes control planes and API gateway layers, leaving container runtime pricing exposed to commodity pressure from open-source alternatives.
Pricing Analysis
Bundled managed services versus unbundled self-hosted infrastructure splits cloud native procurement, with hyperscalers capturing premium through integrated compute-storage-networking stacks while independent vendors compete on modular tooling. Pricing stratifies across enterprise-grade sovereign deployments, standard multi-tenant configurations, and developer-tier consumption models, with EU AI Act compliance costs widening spreads between certified and uncertified offerings. Cost compression in container runtime licensing intensifies as Red Hat and SUSE compete with zero-cost alternatives, though observability and security tooling retain pricing resilience. Financial services firms demonstrate lowest price sensitivity due to regulatory mandates, while retail and media segments drive hardest bargain on per-node compute rates.
Supply Chain Analysis
Regional distribution centers for sovereign cloud infrastructure concentrate in Germany, France, and the Netherlands to satisfy GDPR data residency requirements, with hyperscalers establishing dedicated local zones rather than centralized European hubs. Hardware dependencies draw from Taiwan for confidential computing enclaves, South Korea for high-performance memory modules, and the United States for specialized networking silicon. Single-source vulnerability around ARM-based server processors threatens supply continuity as cloud native workloads shift from x86 architectures. Distribution runs through direct enterprise sales teams for regulated verticals and channel partners for mid-market developer tooling adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud native technologies function as a geographic-arbitrage play where labor cost differentials between Western Europe and India create margin expansion opportunities for platform engineering services, while regulatory divergence between EU AI Act jurisdictions and US FDA pathways fragments standardization returns.
For Market Incumbents: Anticipate margin erosion in commoditized container runtime layers by deepening investment in confidential computing enclaves and sovereign cloud certifications that lock in regulated European workloads. Defensive consolidation through acquisition of observability and service mesh specialists addresses operational complexity pain points that overwhelm enterprise platform teams. Kubernetes distribution maintenance costs threaten incumbents lacking managed service revenue streams.
For New Entrants and Emerging Players: Begin with healthcare vertical expansion where FDA 21 CFR Part 820 and EMA GxP guidelines create certified demand gaps that hyperscalers address slowly. Target German automotive OEMs building sovereign stacks for connected vehicle pipelines, where national data control requirements exclude global platform defaults. Go-to-market through systems integrators with existing KBA and BSI compliance relationships accelerates trust acquisition.
For Investors and Strategic Acquirers: Roll-up economics work for container security and GitOps tooling specialists because platform engineering teams consolidate vendor relationships to reduce integration overhead across ephemeral infrastructure fleets. Long-term viability hinges on embedding into CI/CD pipelines where switching costs accumulate fastest. Watch hyperscaler capex allocation to dedicated local zones as the signal for sovereign cloud market maturation versus continued fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Investment | Hardware-based enclaves satisfy GDPR-mandated data residency for German automotive OEMs under KBA oversight. |
| GitOps Platform Integration | Version-controlled infrastructure automation compresses incident recovery for financial services firms facing EU AI Act audits. |
| Healthcare Compliance Certification | FDA 21 CFR Part 820 quality system alignment opens medical device software deployments to cloud native architectures. |
| Multi-Cloud Orchestration Partnership | Anthos-equivalent abstraction layers navigate fragmented sovereignty rules across EU member states. |
| Regional Local Zone Expansion | Dedicated infrastructure zones in France and Germany address non-negotiable domestic data control contract terms. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, platform engineering directors, cloud procurement officers, and Kubernetes site reliability engineers with secondary validation against hyperscaler capex disclosures, SEC filings, container runtime adoption surveys, and EU regulatory implementation guidance. Bottom-up sizing of container cluster deployments and top-down triangulation against infrastructure software revenue disclosures anchored volume estimates.
Segment-weighting approaches distributed forecast contributions across deployment models, abstraction technologies, industry verticals, and solution offerings, with explicit modeling of sovereignty-driven procurement delays and legacy system containerization friction. CAGRs derived from elasticity-adjusted adoption curves and regulatory compliance timeline assumptions, incorporating FDA guidance evolution on medical device software and EU AI Act implementation sequencing as scenario inputs.
Several conditions sit outside the modeled scope, including abrupt hyperscaler pricing wars, open-source foundation governance disruptions, and nation-state data localization mandates beyond current EU, Indian, and Chinese frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market