
 Telecom Cloud Orchestration Market | 2026-2036
Telecom Cloud Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Cloud Orchestration Market Analysis
India is narrowing its vendor shortlist for domestic telecom cloud infrastructure as Reliance Jio and Bharti Airtel scale 5G standalone core deployments. Red Hat sustains technology leadership through its OpenShift platform integrated with telco-specific network function virtualization stacks. Nutanix competes by extending hyperconverged infrastructure into edge orchestration layers for radio access network virtualization. CloudBolt anchors mid-market penetration with multi-cloud cost governance tools tailored to European telecom budgets.
Telecom cloud orchestration denotes the automated provisioning, scaling, and lifecycle management of virtualized network functions across distributed cloud infrastructure, typically operating at sub-50 millisecond latency thresholds for 5G ultra-reliable low-latency communication workloads. Its primary purpose is to replace hardware-centric network appliances with software-defined instances that operators deploy, patch, and retire without physical site visits. Hybrid cloud deployments now command the largest addressable spend as operators retain sensitive subscriber data on-premises while bursting analytics workloads to public infrastructure. Communication as a Service offerings represent the fastest-expanding service type segment, driven by API-first programmable voice and messaging platforms that enterprises consume through telecom operator marketplaces. Microservices architecture is displacing monolithic virtual network function packaging, enabling granular scaling of individual network components during traffic spikes.
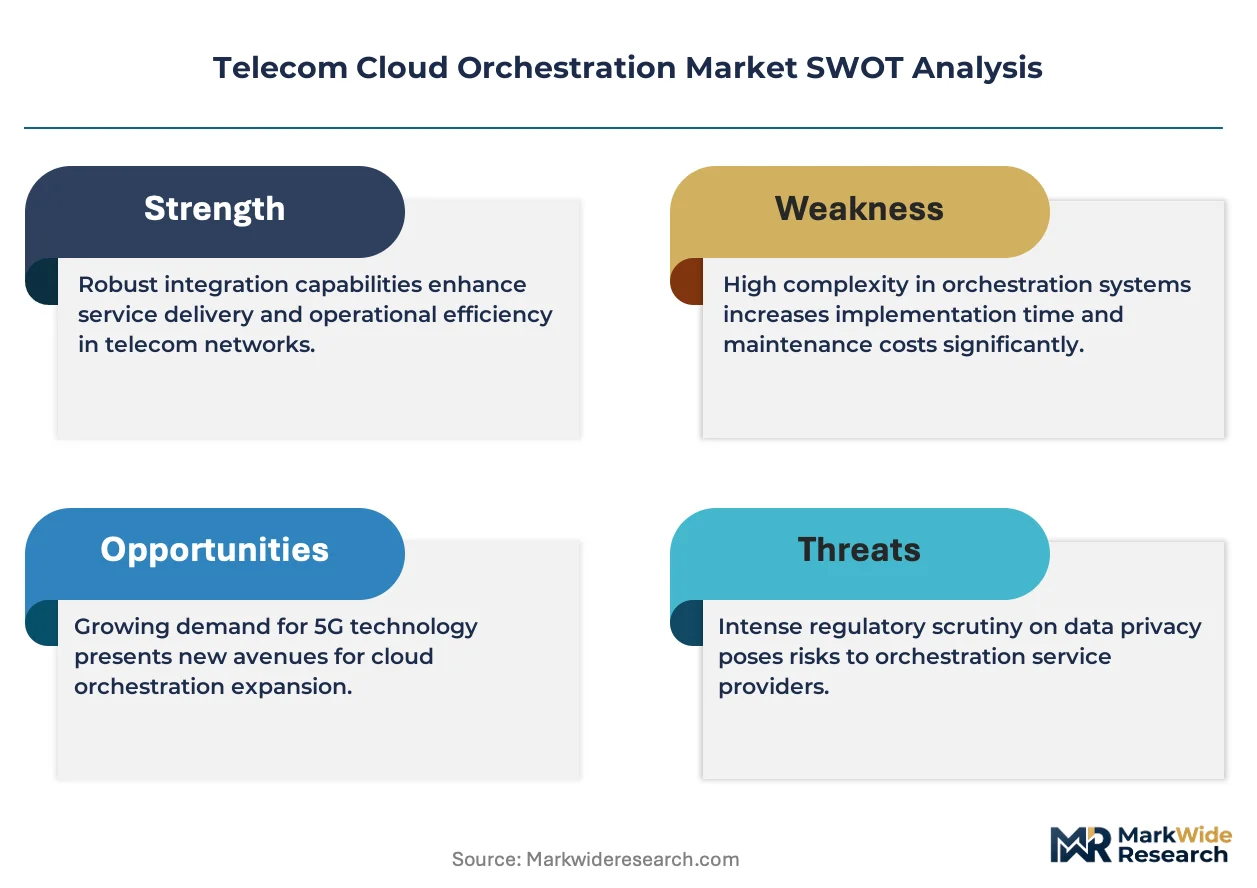
The European Telecommunications Standards Institute, the Federal Communications Commission, and India's Telecom Regulatory Authority each enforce distinct data localization and interoperability mandates that shape procurement specifications for cloud orchestration stacks. ETSI's NFV standards framework dictates reference architectures that vendors must certify against to participate in European operator tenders, while TRAI's cloud infrastructure guidelines for Indian telecom operators mandate domestic data residency for lawful interception compliance. Stakeholders must monitor divergence between regional certification requirements, as fragmentation in compliance regimes threatens to fragment vendor addressable markets and inflate engineering overhead for multi-territory deployments.
Market Dynamics
Cloud-native network function virtualization is compressing deployment cycles for 5G core infrastructure, forcing operators to rebuild operational workflows around continuous integration pipelines rather than hardware procurement calendars.
Growth Catalysts
- ETSI NFV Standards Framework:European operators mandate certified reference architectures for orchestration stack procurement, creating compliant vendor ecosystems that accelerate deployment velocity.
- 5G Standalone Core Workloads:Mobile network operators in India and Germany are migrating control plane functions to containerized environments, driving orchestration platform investments.
- API-First Programmable Voice:Enterprise demand for embedded communications through telecom marketplaces is expanding Communication as a Service consumption models.
Market Restraints
- Specialized Engineering Talent Scarcity:Kubernetes expertise for telco-grade workloads commands premium compensation, inflating implementation costs for mid-tier operators.
- Domestic Equipment Concentration:Sovereign cloud mandates in Germany and India limit vendor pool depth, constraining price competition for critical infrastructure components.
- Latency Floor Constraints:Sub-50 millisecond thresholds for ultra-reliable low-latency communication workloads restrict viable geographic distribution of orchestration nodes.
Strategic Opportunities
- Edge Orchestration Layers:Radio access network virtualization at cell tower aggregation points creates greenfield deployment opportunities for hyperconverged infrastructure extensions.
- TRAI Cloud Infrastructure Guidelines:India's data residency mandates for lawful interception compliance are catalyzing domestic facility construction and local vendor partnerships.
- Microservices Architecture Convergence:Granular scaling of individual network components during traffic spikes enables pay-per-use economics that displace capacity overprovisioning.
Industry Challenges
- Monolithic VNF Migration Complexity:Operators struggle to decompose legacy virtual network function packaging without service disruption during transition windows.
- Multi-Territory Certification Overhead:Divergence between ETSI, FCC, and TRAI compliance regimes fragments engineering resources and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Cloud Orchestration Market |
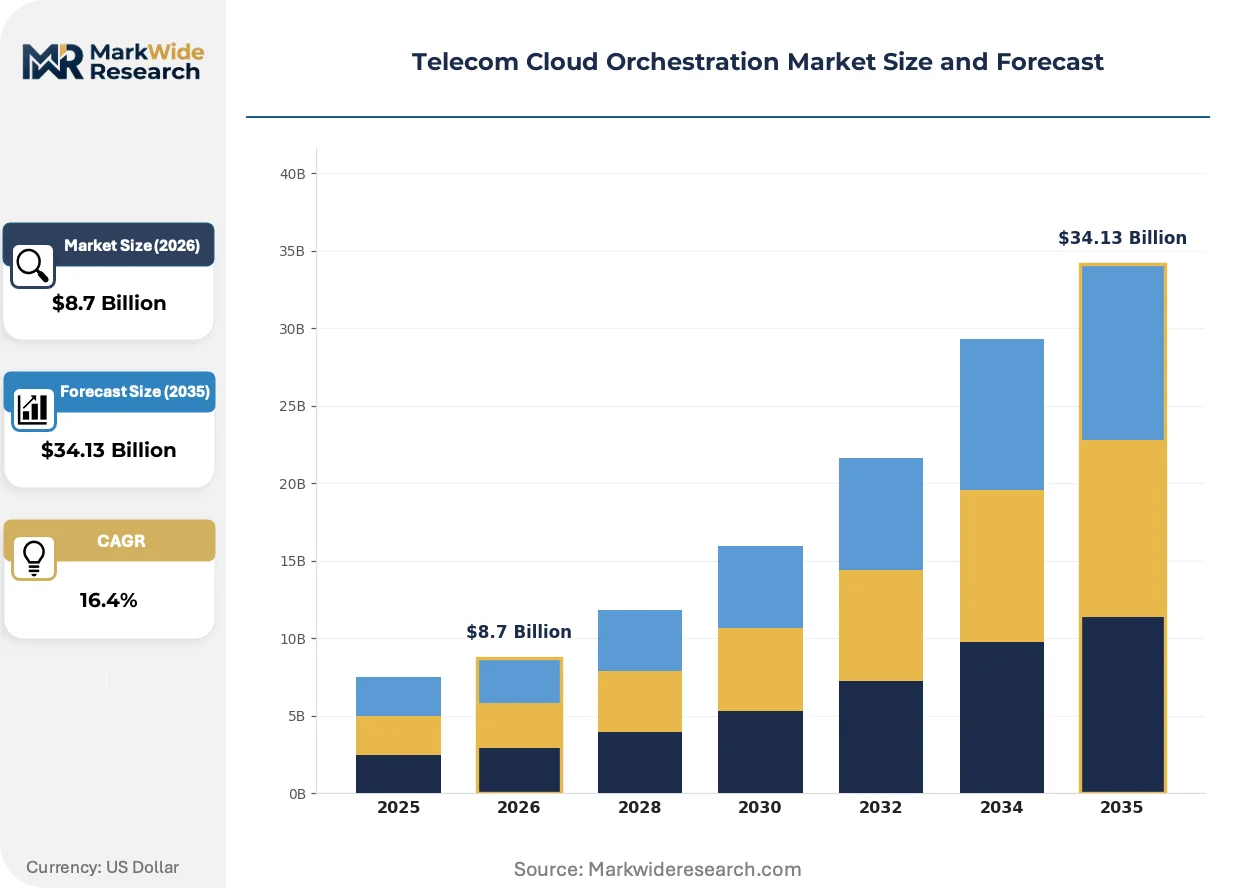
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Communication as a Service End User: Telecom Operators, Service Providers, Enterprises, Resellers Technology: NFV, SDN, APIs, Microservices |
| Companies Covered | CloudBolt, CloudHealth, Holori, Apptio, Flexera, Red Hat, Nutanix, Turbonomic, Morpheus Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Cloud Orchestration Market Emerging Trajectories
Distributed cloud architectures are redefining where network intelligence resides, shifting orchestration control from centralized data centers toward radio edge and subscriber premises.
Containerized packet core software is virtualizing mobile gateway functions that previously required dedicated hardware appliances. Tier-one operators in Germany and India are deploying these cloud-native user plane functions at scale, collapsing provisioning timelines from months to hours. This transition is virtualizing the boundary between transport and compute infrastructure, enabling dynamic resource allocation during congestion events.
The European Union's NIS2 Directive is mandating cybersecurity risk management across essential telecom infrastructure supply chains. Operators must now document orchestration platform vulnerabilities and incident response protocols for national regulators. German mobile network operators are restructuring procurement specifications to prioritize vendors with certified security development lifecycles, compressing qualification timelines for compliant suppliers.
Enterprise buyers are consolidating communications procurement through telecom operator marketplaces rather than direct SaaS relationships. Manufacturing and logistics verticals in Germany are consuming API-first voice and messaging through integrated orchestration portals, displacing standalone unified communications contracts. This channel migration is most pronounced in industrial automation clusters where low-latency guarantees are bundled with connectivity services.
Telecom Cloud Orchestration Market Segmentation
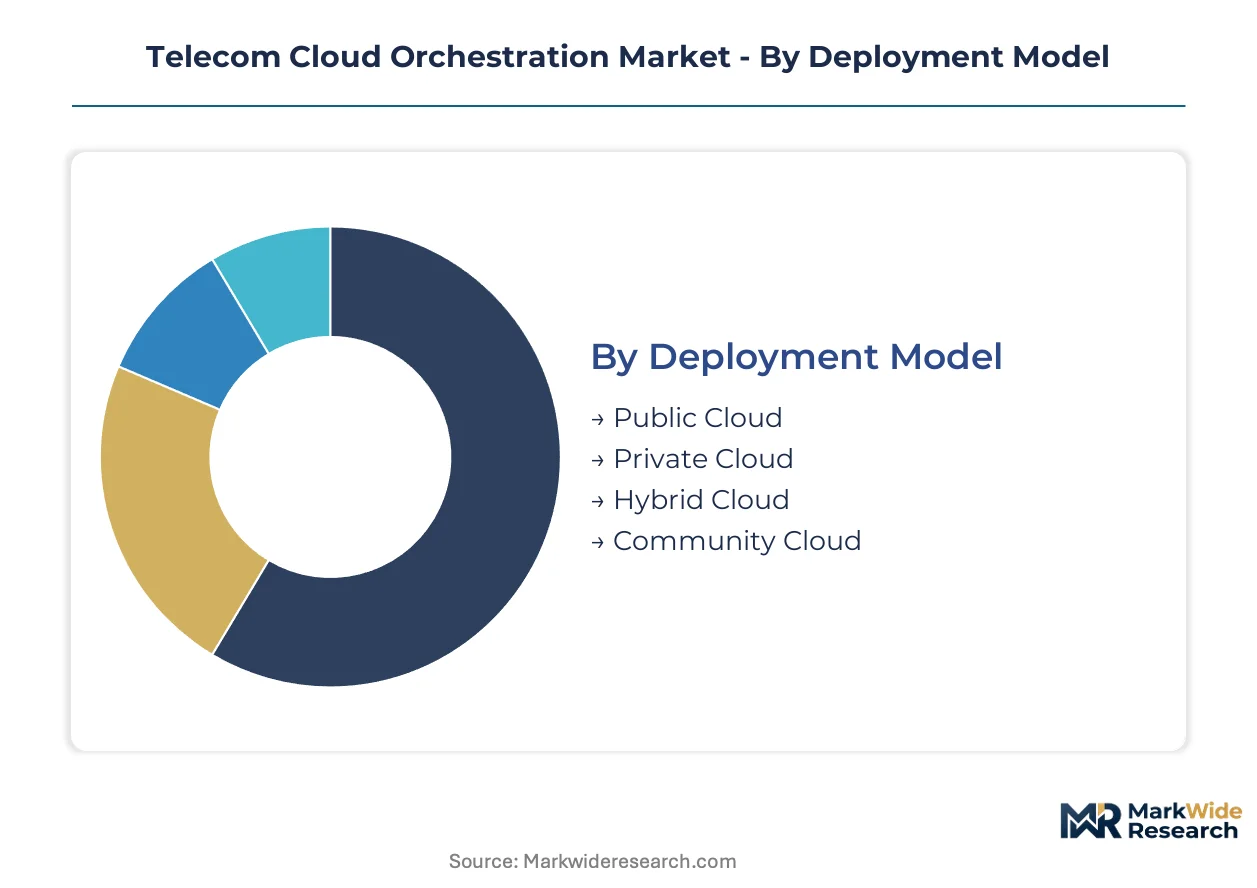
Telecom cloud orchestration procurement patterns diverge sharply across deployment architectures and consumption models. Operators calibrate infrastructure choices against latency mandates, data sovereignty requirements, and workload sensitivity tiers.
Deployment Model:
Mature private cloud installations coexist with emerging edge-native community deployments across operator footprints.
- Public Cloud:Burst capacity for non-sensitive analytics workloads operates under shared infrastructure economics. German operators leverage public cloud for subscriber behavior modeling while retaining core network functions on-premises, constrained by GDPR data residency interpretations.
- Private Cloud:Dedicated infrastructure hosts 5G core control planes and lawful interception systems under single-tenant isolation. Indian operators mandate private deployments for subscriber authentication databases per TRAI cloud infrastructure guidelines.
- Hybrid Cloud:Orchestration layers automate workload placement across on-premises and public infrastructure based on policy engines.
- Community Cloud:Shared facilities among operator consortiums reduce capital intensity for rural coverage expansion.
Private cloud retains volume leadership; community cloud holds the steepest expansion curve.
Service Type:
Cost tier stratification separates infrastructure-heavy contracts from lightweight API consumption models.
- Infrastructure as a Service:Bare-metal compute and storage resources provisioned through self-service portals enable rapid network function instantiation. Telecom operators in Germany deploy IaaS for virtualized radio access network elements at cell tower aggregation points.
- Communication as a Service:Programmable voice, messaging, and video APIs embed directly into enterprise applications through operator marketplaces. Manufacturing verticals in India consume CaaS for industrial automation alerting systems bundled with 5G connectivity.
- Platform as a Service:Managed Kubernetes environments abstract container orchestration complexity from network engineering teams.
- Software as a Service:Pre-configured orchestration dashboards deliver operational visibility without infrastructure ownership.
Infrastructure as a Service dominates current procurement volumes; Communication as a Service is expanding most quickly.
End User:
Customer type fragmentation spans capital-intensive network builders and margin-focused intermediaries.
- Telecom Operators:Mobile network operators deploy orchestration stacks to virtualize packet core, radio access, and transport functions across multi-vendor environments. Deutsche Telekom and Vodafone operate sovereign cloud facilities for latency-sensitive network functions.
- Enterprises:Large manufacturers and logistics providers procure orchestrated communications through operator marketplaces rather than direct SaaS relationships, prioritizing bundled latency guarantees.
- Service Providers:Systems integrators and managed service providers operate orchestration layers on behalf of mid-tier operators lacking internal platform expertise.
- Resellers:Channel partners aggregate orchestration services for small and medium enterprises without direct operator relationships.
Telecom operators retain volume leadership; enterprises hold the steepest expansion curve.
Technology:
Architecture maturity separates production-grade virtualization from emerging microservices decomposition patterns.
- NFV:Network function virtualization replaces dedicated hardware appliances with software instances running on commodity servers. ETSI NFV standards frameworks dictate reference architectures that vendors must certify against for European operator tenders.
- Microservices:Granular container packaging enables independent scaling of authentication, charging, and policy functions during traffic spikes. Indian operators decompose monolithic core network elements into microservices for 5G standalone deployments.
- SDN:Software-defined networking abstracts control plane intelligence from data plane forwarding hardware.
- APIs:RESTful and gRPC interfaces expose orchestration capabilities to external systems and partner ecosystems.
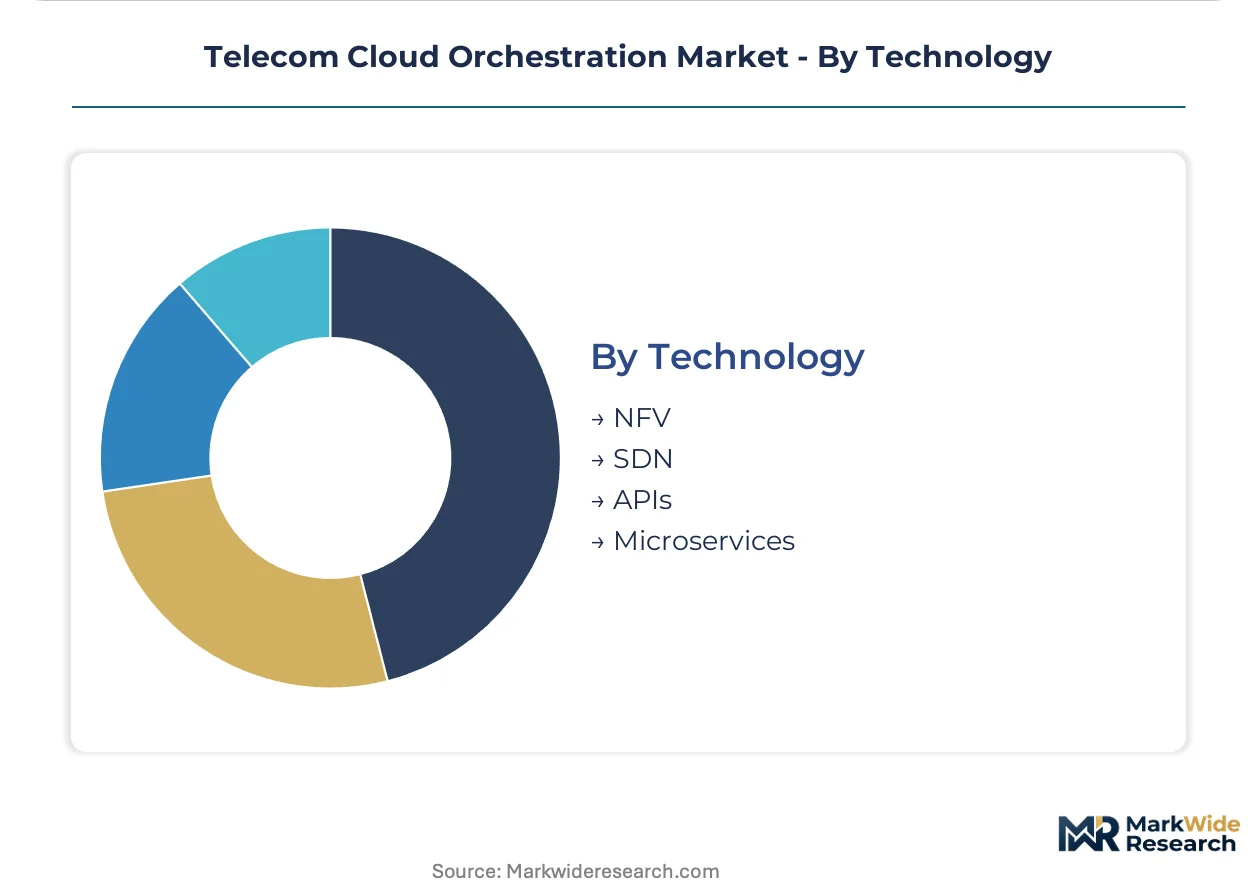
NFV retains volume leadership; microservices holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure vendors concentrate engineering resources across Germany, India, and the United States where 5G standalone core deployments consume the highest orchestration platform volumes. Sovereign data residency mandates and latency-sensitive network function requirements reshape procurement patterns in each jurisdiction.
Germany
Deutsche Telekom and Vodafone are constructing sovereign cloud facilities for ultra-reliable low-latency communication workloads. The EU's NIS2 Directive mandates cybersecurity risk management documentation across essential telecom infrastructure supply chains. Bavaria hosts multiple edge data center clusters where mobile network operators deploy containerized user plane functions at cell tower aggregation points.
India
Reliance Jio and Bharti Airtel are scaling 5G standalone core deployments through domestic vendor shortlists for telecom cloud infrastructure. TRAI's cloud infrastructure guidelines mandate domestic data residency for lawful interception compliance. Karnataka's Bengaluru technology corridor anchors engineering centers where operators validate microservices architectures for packet core virtualization.
United States
Mobile network operators burst analytics workloads to public infrastructure while retaining sensitive subscriber data on-premises under FCC regulatory interpretations. The Federal Communications Commission enforces distinct data localization and interoperability mandates that shape procurement specifications for cloud orchestration stacks. Northern Virginia's data center concentration supports orchestration node distribution for sub-50 millisecond latency thresholds.
United Kingdom
Telecom operators calibrate hybrid cloud deployments against GDPR data residency interpretations for subscriber behavior modeling. The national telecom regulator enforces cybersecurity requirements that align with ETSI NFV standards frameworks for vendor certification. London's financial services cluster drives demand for API-first programmable voice platforms through operator marketplaces.
Japan
Mobile network operators deploy orchestration layers for radio access network virtualization at cell tower aggregation points. METI guidelines shape industrial automation procurement where manufacturing verticals consume low-latency communications bundled with connectivity services. The Kanto region around Tokyo concentrates vendor engineering resources for Kubernetes-based telco-grade workload certification.
Telecom Cloud Orchestration Market Vendor Landscape
Platform specialists and infrastructure incumbents split the market into distinct capability tiers. Consolidation pressures concentrate around certified compliance with ETSI NFV standards frameworks and TRAI data residency mandates. Three archetypes dominate: open-source platform providers with telco-specific integrations, hyperconverged infrastructure vendors extending into edge orchestration, and multi-cloud cost governance specialists targeting mid-market European budgets. Competitive moves center on strategic partnerships with mobile network operators and geographic expansion into sovereign cloud facility construction.
Within the open-source platform tier, Red Hat and Nutanix exemplify divergent architectural approaches to network function virtualization. Red Hat occupies a position anchored in Kubernetes-based container orchestration with telco-grade certification pathways. Nutanix represents hyperconverged infrastructure convergence toward edge-native deployment models. CloudBolt sits within the cost governance archetype, targeting mid-tier operators with multi-cloud budget optimization tooling. Each vendor archetype faces distinct qualification pressures: open-source platforms must certify against regional NFV frameworks, infrastructure vendors must demonstrate sub-50 millisecond latency compliance, and governance specialists must adapt to sovereign cloud procurement specifications.
| Leading Market Players |
|---|
| CloudBolt |
| CloudHealth |
| Holori |
| Apptio |
| Flexera |
| Red Hat |
| Nutanix |
| Turbonomic |
| Morpheus Data |
| Others |
Supply Flow & Price Mechanics
Bavaria's edge data center clusters concentrate orchestration platform capacity for European mobile network operators, compressing margins for mid-tier vendors unable to achieve ETSI NFV certification at scale. This geographic concentration amplifies pricing power for certified suppliers while forcing uncertified competitors toward commodity service tiers.
Pricing Analysis
ETSI NFV Standards Framework dictates the pricing tier structure across European procurement, separating certified reference architecture vendors from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects compliance grade, volume scale, and after-sales service bundling. Cost compression in the economy tier intensifies because domestic equipment mandates in Germany and India limit vendor pool depth. Mid-tier operators exhibit highest price sensitivity, while tier-one mobile network operators prioritize certification premiums over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for semiconductor components in orchestration hardware. Manufacturing concentrates in Taiwan, South Korea, and the United States for advanced server processors and networking silicon. Component sourcing draws from German precision manufacturing for industrial-grade server chassis, Japanese memory modules, and Chinese commodity compute hardware. Distribution runs through systems integrators and managed service providers who operate orchestration layers on behalf of resource-constrained operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom cloud orchestration represents a platform-economics inflection where API-first programmable voice marketplaces are displacing direct enterprise SaaS relationships, rewarding vendors who achieve embedded status within operator ecosystems.
For Market Incumbents: Entrench certification advantages by deepening ETSI NFV reference architecture compliance ahead of NIS2 Directive enforcement deadlines. Expand sovereign cloud facility partnerships in Germany and India to lock out emerging competitors lacking domestic data residency capabilities. Kubernetes talent scarcity threatens implementation timelines; captive training programs or acquisition of certified engineering teams anchors delivery reliability.
For New Entrants and Emerging Players: Establish a beachhead in edge orchestration layers for radio access network virtualization, where greenfield deployment timelines favor agile vendors over legacy platform incumbents. Target Indian domestic vendor shortlists by aligning with TRAI cloud infrastructure guidelines for lawful interception compliance. Go-to-market leverage rests on microservices architecture expertise that accelerates 5G standalone core decomposition timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because containerized network functions are collapsing the boundary between hardware procurement and continuous integration pipelines. Acquisition targets should display certified compliance with at least two regional NFV frameworks plus existing operator production deployments. Monitor divergence between ETSI, FCC, and TRAI certification requirements as the signal indicating vendor consolidation pressure versus fragmentation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding orchestration stacks within Deutsche Telekom and Vodafone sovereign cloud facilities locks in multi-year recurring revenue. |
| Geographic Expansion | Constructing domestic data centers in Karnataka's Bengaluru corridor satisfies TRAI lawful interception mandates for Reliance Jio and Bharti Airtel. |
| Strategic Partnership | Aligning with systems integrators extends reach to mid-tier operators lacking internal Kubernetes expertise for telco-grade workloads. |
| Acquisition of Specialist Firm | Absorbing microservices architecture specialists accelerates decomposition of monolithic virtual network functions without service disruption. |
| Product Launch | Introducing API-first programmable voice platforms through operator marketplaces captures enterprise communications procurement consolidation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with network engineering directors, cloud procurement officers, regulatory compliance leads, and systems integrator executives; and secondary validation against ETSI NFV certification databases, TRAI regulatory filings, SEC hyperscaler capex disclosures, and operator tender documentation. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending projections.
Forecast inputs span deployment model segmentation, service type consumption patterns, technology architecture maturity, and end-user procurement behavior across the projection horizon. CAGRs derive from modeled adoption curves for 5G standalone core virtualization, microservices decomposition timelines, and sovereign cloud facility construction pipelines. Industry-specific inputs include ETSI NFV certification velocity, NIS2 Directive compliance cost assumptions, and TRAI data residency mandate enforcement timing.
Sensitivities concentrate around regulatory divergence between ETSI, FCC, and TRAI frameworks, Kubernetes talent availability constraints, and sovereign cloud mandate expansion beyond Germany and India. Forecasts reflect documented assumptions regarding operator procurement cycle acceleration and containerization adoption rates. Material shifts in regional certification reciprocity agreements or latency threshold relaxations for ultra-reliable low-latency communication workloads would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud-Enabling Technology Market