
 Cloud Data Quality Radar Market | 2026-2036
Cloud Data Quality Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Data Quality Radar Market Analysis
Healthcare provider demand for real-time patient data validation is hardening as clinical systems migrate to multi-cloud environments. Informatica leverages deep integration with enterprise data catalogs to sustain its position among large healthcare networks. IBM anchors its competitive stance through AI-augmented data quality modules embedded within its cloud platform. Datadog competes aggressively on observability convergence, extending its monitoring stack into data pipeline health metrics.
Cloud Data Quality Radar encompasses automated profiling, cleansing, and monitoring tools that continuously assess structured and semi-structured data across distributed cloud architectures, typically operating at sub-second latency thresholds to flag anomalies before downstream consumption. Its primary commercial purpose is to prevent revenue leakage, compliance breaches, and operational failures caused by degraded data pipelines. The Deployment dimension shows Hybrid Cloud configurations capturing the strongest margin pools as enterprises retain sensitive workloads on-premises while bursting analytics to public infrastructure. Within Solution categories, Data Enrichment is expanding fastest as organizations layer third-party signals onto first-party records to sharpen AI model outputs. Compliance Standard segmentation reveals GDPR-aligned modules commanding premium pricing in European procurement cycles due to audit-documentation requirements.
FDA scrutiny of AI-enabled diagnostic tools is pushing healthcare providers toward validated data provenance systems that satisfy 21 CFR Part 11 electronic record standards. HIPAA obligations around protected health information continue to shape encryption and access-control specifications for cloud data quality platforms serving US providers. ISO 27001 certification has become a baseline procurement filter rather than a differentiator across enterprise RFP processes. Stakeholders should monitor how emerging state-level privacy laws in the US fragment compliance requirements beyond federal frameworks.
Market Dynamics
Real-time AI inference pipelines are compressing latency tolerances for data quality validation, forcing vendors to rearchitect profiling engines from batch-oriented to stream-native processing frameworks.
Growth Catalysts
- EU AI Act audit mandates:European enterprises must embed machine-readable data lineage documentation into cloud pipelines, creating procurement pull for compliant tooling.
- Healthcare multi-cloud migration:Clinical systems distributing workloads across AWS, Azure, and Google Cloud require unified quality governance spanning heterogeneous environments.
- FDA 21 CFR Part 11:AI-enabled diagnostic submissions demand validated electronic records with complete provenance trails, hardening provider investment in audit-ready platforms.
Market Restraints
- Hyperscaler concentration risk:Three cloud providers control infrastructure pricing for quality tooling deployments, limiting vendor margin autonomy.
- Specialized talent scarcity:Shortage of engineers fluent in both distributed systems architecture and domain-specific data semantics constrains implementation velocity.
- Encryption overhead:HIPAA-mandated field-level encryption adds compute cost and latency to real-time anomaly detection pipelines.
Strategic Opportunities
- State-level privacy fragmentation:Emerging US regulations beyond federal frameworks create demand for configurable compliance modules adaptable to California, Virginia, and Colorado statutes.
- Observability convergence:Integration of data quality metrics with application performance monitoring represents unclaimed white space in enterprise tooling budgets.
- Third-party signal layering:Data enrichment solutions combining first-party records with external demographic and behavioral feeds are penetrating underdeveloped mid-market accounts.
Industry Challenges
- Legacy system integration friction:Mainframe and on-premise data warehouses resist seamless API connectivity with cloud-native quality engines.
- ISO 27001 certification timelines:Six-to-twelve month audit cycles delay vendor eligibility for enterprise RFP shortlists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Data Quality Radar Market |
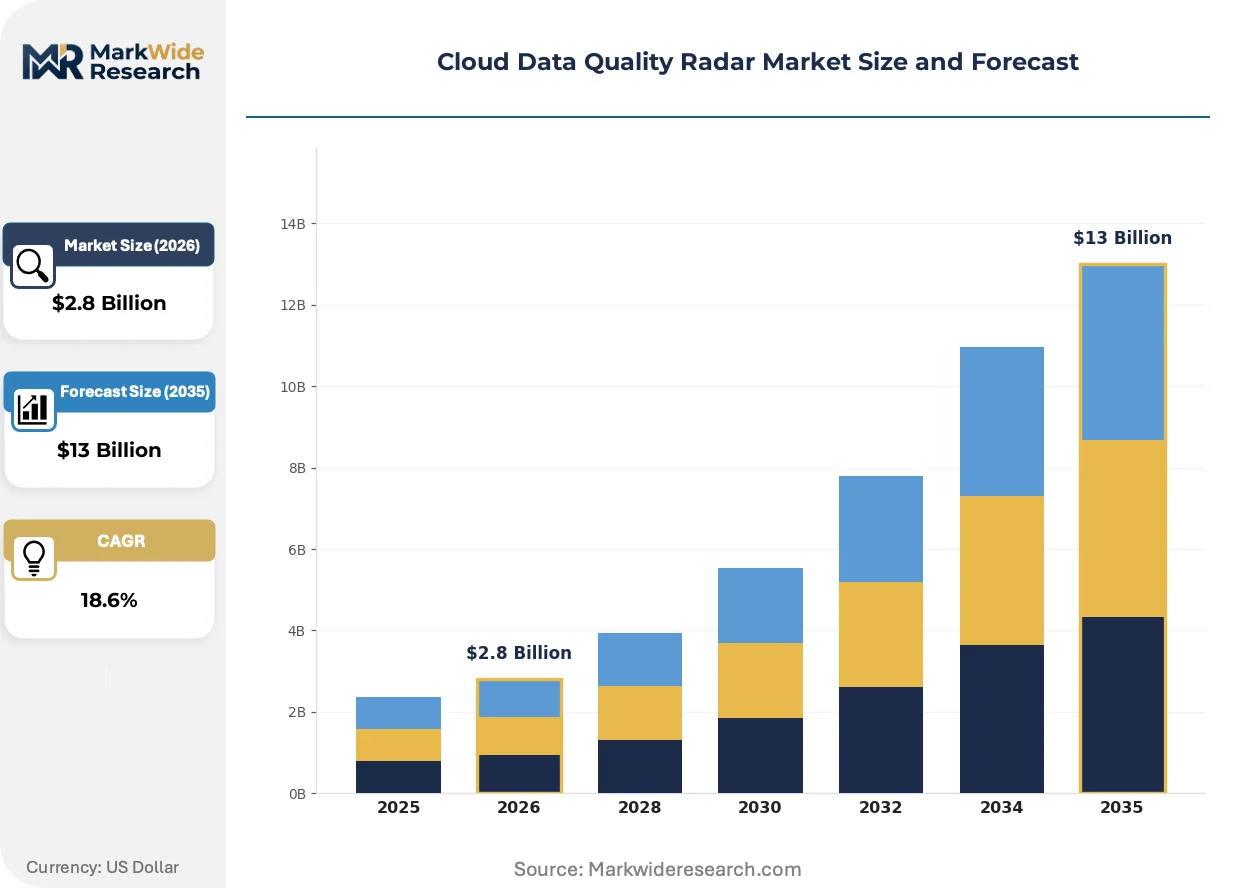
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: Data Profiling, Data Cleansing, Data Integration, Data Enrichment Compliance Standard: GDPR, CCPA, HIPAA, ISO 27001 End User: Financial Services, Healthcare Providers, Retailers, E-Commerce |
| Companies Covered | Informatica, Pacific Data Integrators, Advanced Radar Company, Datadog, Splunk, Dynatrace, New Relic, IBM, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Data Quality Radar Market Emerging Trajectories
Stream processing architectures are displacing batch-oriented quality frameworks as AI inference demands sub-second anomaly detection. Vendors are racing to embed profiling logic directly within data pipeline execution engines rather than operating as external validation layers.
Embedded data quality agents is modularizing across containerized microservices, allowing healthcare networks to deploy lightweight validation modules at specific pipeline nodes without full-platform commitments. Mayo Clinic and Kaiser Permanente are piloting this approach for patient record ingestion flows. The fragmentation is compressing traditional platform licensing models into componentized consumption.
GDPR-aligned audit documentation modules command premium positioning in European procurement cycles as the EU AI Act amplifies documentation burdens. German and French healthcare systems now require machine-readable lineage exports for any AI training data. Vendors without automated compliance artifact generation are losing RFP participation rights.
Enterprise buyers are consolidating vendor relationships, preferring quality tooling bundled within existing cloud contracts rather than standalone procurement. This pattern concentrates in United States financial services, where CISO offices prioritize reduced integration surface area. Independent vendors face pressure to embed within hyperscaler marketplaces or risk exclusion from shortlists.
Cloud Data Quality Radar Market Segmentation
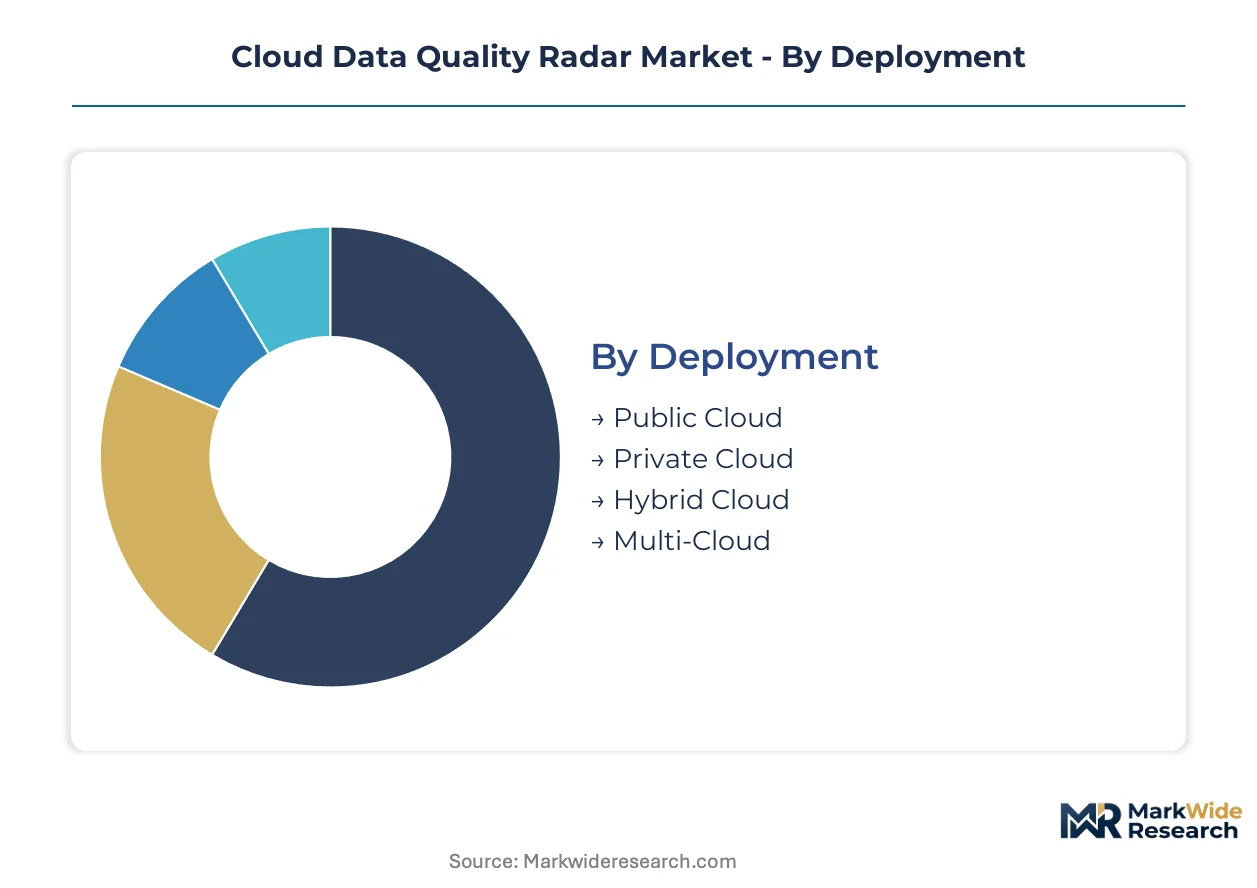
Cloud Data Quality Radar deployments fragment across infrastructure architectures, regulatory regimes, and vertical workflows. Procurement patterns diverge sharply by certification burden and latency tolerance. Understanding these fault lines exposes where margin pools concentrate and where vendor positioning faces structural pressure.
Deployment:
ISO 27001 certification functions as a baseline filter across all deployment modes, though audit complexity varies significantly by infrastructure control plane.
- Public Cloud:Fully managed quality engines running on hyperscaler infrastructure eliminate capital expenditure for compute scaling. Demand concentrates among mid-market retailers lacking dedicated platform engineering teams, constrained by shared-tenancy security reviews.
- Private Cloud:Dedicated quality infrastructure deployed within enterprise-controlled data centers satisfies HIPAA field-level encryption mandates without external data egress. German healthcare networks and US hospital systems anchor procurement volume here.
- Hybrid Cloud:Split architectures retain sensitive profiling workloads on-premises while bursting anomaly detection to public infrastructure. Financial services firms in the United States favor this mode for real-time risk analytics with audit-segregated data lakes.
- Multi-Cloud:Federated quality governance spanning AWS, Azure, and Google Cloud simultaneously. Mayo Clinic and Kaiser Permanente pilot this for patient record validation across distributed clinical systems.
Leading the category by volume: Hybrid Cloud. Growing fastest: Multi-Cloud.
Solution:
Cost tiering separates premium compliance-integrated modules from commodity profiling tools, with enrichment services commanding the widest pricing spreads.
- Data Profiling:Automated statistical analysis of schema, distribution, and quality metrics across structured and semi-structured sources. Financial services deploy this for pre-trade risk data validation, squeezed by sub-second latency requirements.
- Data Cleansing:Standardization, deduplication, and outlier correction workflows. Retailers processing high-velocity transaction streams represent the anchor demand segment, though margin compression is acute.
- Data Integration:ETL pipeline health monitoring with embedded quality gates. Healthcare providers migrating from legacy EHR systems drive implementation backlog, constrained by HL7 FHIR interoperability gaps.
- Data Enrichment:Third-party signal layering onto first-party records using demographic, behavioral, and geographic external feeds. US e-commerce platforms and AI model training pipelines are expanding most quickly here.
Commanding premium pricing: Data Enrichment. Steepest expansion trajectory: Data Enrichment.
Compliance Standard:
Geography determines which certification modules activate in procurement cycles, with European mandates carrying the heaviest documentation burdens.
- GDPR:Machine-readable data lineage documentation with automated audit artifact generation. EU AI Act mandates harden requirements for German and French healthcare systems, disqualifying vendors lacking automated compliance exports.
- CCPA:California consumer privacy rights with opt-out data processing provisions. US retailers and e-commerce platforms face expanding obligations as Virginia, Colorado, and Connecticut statutes proliferate.
- HIPAA:Protected health information safeguards requiring field-level encryption and access logging. US healthcare providers anchor demand, with FDA 21 CFR Part 11 layering additional provenance requirements for diagnostic AI submissions.
- ISO 27001:Information security management certification functioning as a baseline RFP filter rather than differentiator. Six-to-twelve month audit cycles delay vendor eligibility for enterprise shortlists.
Widest pricing premium: GDPR-aligned modules. Fastest regulatory expansion: CCPA and state-level US privacy laws.
End User:
Customer type determines latency tolerance, with real-time inference pipelines compressing quality validation windows to sub-second thresholds.
- Financial Services:Real-time risk analytics and trading data validation driving stream-native architecture adoption. CISO offices prioritize reduced integration surface area through hyperscaler-bundled procurement.
- Healthcare Providers:Clinical data integrity for patient safety and FDA submission compliance. Multi-cloud migration is fragmenting governance requirements across AWS, Azure, and Google Cloud environments.
- Retailers:High-velocity transaction processing with inventory and customer data synchronization. Cost pressure favors commodity cleansing tools over premium enrichment modules.
- E-Commerce:Product catalog validation and recommendation engine data quality. Third-party signal layering for personalization AI represents the fastest-growing solution attachment.
Driving premium solution attach: Financial Services. Expanding most quickly: Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in the United States, Germany, and India are concentrating procurement authority for cloud data quality tooling as hyperscaler partnerships and regulatory mandates reshape deployment decisions.
United States
Financial services firms in New York and Chicago are driving demand for real-time risk analytics with sub-second latency requirements. HIPAA and FDA 21 CFR Part 11 obligations harden compliance specifications for healthcare providers migrating clinical systems to multi-cloud environments. The Mayo Clinic in Minnesota pilots federated quality governance across AWS, Azure, and Google Cloud for patient record validation.
Germany
Automotive manufacturers and healthcare networks in Bavaria and Baden-Württemberg require machine-readable data lineage documentation under EU AI Act mandates. GDPR-aligned audit modules command premium pricing in procurement cycles as German regulators disqualify vendors lacking automated compliance exports. Berlin-based enterprises anchor European demand for hybrid cloud configurations retaining sensitive workloads on-premises.
United Kingdom
London financial institutions prioritize bundled procurement through hyperscaler marketplaces to reduce integration surface area. The Information Commissioner's Office enforcement patterns shape encryption and access-control specifications for cloud data quality platforms. Manchester and Edinburgh healthcare systems are consolidating vendor relationships around ISO 27001-certified tooling.
India
Bengaluru and Hyderabad technology hubs are expanding mid-market adoption of data enrichment solutions for AI model training pipelines. The Digital Personal Data Protection Act is compelling enterprises to embed auditable provenance into cloud pipelines. Mumbai financial services firms are negotiating hyperscaler partnerships for real-time transaction validation.
Japan
Tokyo and Osaka manufacturing conglomerates require unified quality governance spanning distributed cloud architectures for supply chain analytics. METI guidelines on data sovereignty influence private cloud deployment preferences for sensitive industrial data. Yokohama healthcare networks are piloting embedded data quality agents for patient record ingestion flows.
Cloud Data Quality Radar Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated hyperscaler partnerships dominating United States financial services procurement while fragmented independent vendors compete for European healthcare accounts. Three strategic archetypes occupy distinct positions: cloud-native observability platforms extending into data pipeline health metrics, enterprise software incumbents embedding quality modules within broader data management suites, and specialized data integration consultancies with deep vertical expertise. M&A activity concentrates on acquiring stream-native processing capabilities, while geographic expansion through hyperscaler marketplace listings represents the second dominant competitive move.
Within the enterprise software tier, Informatica and IBM exemplify incumbents leveraging deep integration with enterprise data catalogs to sustain positioning among large healthcare networks. Datadog occupies a position among observability-first platforms competing aggressively on convergence between data quality metrics and application performance monitoring. These three anchors illustrate how vendor archetypes map to divergent procurement priorities across regulated industries.
| Leading Market Players |
|---|
| Informatica |
| Pacific Data Integrators |
| Advanced Radar Company |
| Datadog |
| Splunk |
| Dynatrace |
| New Relic |
| IBM |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Engineers fluent in distributed systems architecture and domain-specific data semantics cluster in Bengaluru and Hyderabad, creating labor-cost differentials that widen spreads between premium compliance-integrated modules and commodity profiling tools. These talent concentrations in India compress margins for mid-market offerings while sustaining pricing power for GDPR-aligned audit documentation modules in European procurement cycles.
Pricing Analysis
Short lead times for ISO 27001 certification completion command premium positioning in enterprise RFP shortlists, while vendors with pre-certified tooling compete on standard-tier SaaS subscriptions. Pricing stratifies across premium compliance-integrated modules, standard stream-native processing frameworks, and economy-grade batch-oriented profiling tools, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies as hyperscaler marketplace bundling reduces standalone vendor negotiating leverage. Mid-market retailers lacking dedicated platform engineering teams exhibit highest price sensitivity, while German healthcare networks under EU AI Act mandates show lowest sensitivity due to audit-documentation requirements.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke patterns for cloud-native quality tooling delivery, with hyperscaler marketplaces functioning as primary downstream channels. Engineering talent pools concentrate in the United States, India, and Germany, while compute infrastructure draws from AWS, Azure, and Google Cloud data center footprints globally. Single-source vulnerability around hyperscaler infrastructure pricing limits vendor margin autonomy across deployment modes. Distribution runs through direct enterprise sales for large healthcare networks and financial services firms, with self-service marketplace listings penetrating mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around engineers fluent in both distributed systems architecture and domain-specific data semantics prop pricing power for vendors with established certification credentials and hyperscaler marketplace presence.
For Market Incumbents: Lock in hyperscaler marketplace positioning to defend against observability-first platforms extending into data pipeline health metrics. Deepen integration with enterprise data catalogs to sustain positioning among large healthcare networks migrating clinical systems to multi-cloud environments. Prioritize automated GDPR compliance artifact generation to maintain RFP participation rights in European procurement cycles. For New Entrants and Emerging Players: Hyperscaler marketplace listings as a self-service route penetrate mid-market accounts in India and US e-commerce segments with reduced sales friction. Target data enrichment solutions for AI model training pipelines in underdeveloped mid-market accounts, where third-party signal layering commands widest pricing spreads. Emphasize lightweight embedded data quality agents for containerized microservices deployments to bypass full-platform commitment barriers. For Investors and Strategic Acquirers: Re-rating potential sits with stream-native processing specialists given real-time AI inference pipeline demands compressing latency tolerances. Acquisition candidates with automated compliance export capabilities and established ISO 27001 credentials offer longest-term viability within tightening regulatory frameworks. Monitor EU AI Act enforcement patterns in Germany and France as inflection indicator for documentation-heavy procurement cycle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding quality modules within hyperscaler marketplaces reduces integration surface area for CISO offices in US financial services. |
| Acquisition of Specialist Firm | Stream-native processing capabilities address sub-second latency requirements for real-time risk analytics in trading environments. |
| Strategic Partnership | Mayo Clinic and Kaiser Permanente pilot federated governance across AWS, Azure, and Google Cloud for patient record validation. |
| Product Launch | GDPR-aligned audit documentation modules capture premium positioning in European procurement cycles under EU AI Act mandates. |
| Geographic Expansion | Bengaluru and Hyderabad technology hubs expand mid-market adoption of data enrichment solutions for AI model training pipelines. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and hospital procurement databases formed the secondary backbone, supplemented by customs records tracking cloud infrastructure equipment flows. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists validated segmentation assumptions around deployment preferences and compliance module attach rates. Bottom-up sizing of vendor-reported subscription revenues combined with top-down triangulation against enterprise software spending patterns across the analysis window.
Historical trendline analysis of SaaS pricing trajectories and certification timeline data informed the projection framework across deployment models, organization size tiers, vertical workflows, integration complexity levels, and regional adoption patterns. Segmentation dimensions modeled include public-private-hybrid-multi-cloud architectures, solution categories from profiling through enrichment, compliance standards from GDPR through state-level US privacy laws, and end-user verticals from financial services through healthcare. CAGRs derived from regression analysis of vendor revenue disclosures and enterprise procurement survey data, with AI inference pipeline latency requirements and regulatory documentation burdens as key forecast inputs.
The model holds under stable hyperscaler partnership structures and regulatory enforcement continuity; deviation in EU AI Act implementation timelines or state-level US privacy law fragmentation would shift demand concentration patterns. Forecasts reflect documented assumptions around talent pool expansion rates and certification automation technology maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Cloud Native Technologies Market