
 Global Cloud-Based PLM Market | 2026-2036
Global Cloud-Based PLM Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud-Based PLM Market Foresight
ISO 27001 certification is unwinding the competitive landscape for cloud-based PLM providers, elevating compliance costs for mid-tier entrants while favoring established platforms. Dassault Systèmes leverages its 3DEXPERIENCE cloud architecture to anchor aerospace and automotive accounts with integrated digital twin capabilities. Siemens AG sustains competitive pressure through Teamcenter X, competing on manufacturing execution system adjacencies and shop-floor connectivity. PTC Inc. differentiates via Windchill's IoT-native design, specializing in closed-loop feedback between field assets and engineering change orders.
Cloud-based product lifecycle management denotes a software delivery model hosting product data, engineering workflows, and cross-functional collaboration tools on remote server infrastructure accessible via web protocols, typically employing multi-tenant architectures with REST API interoperability and role-based access controls spanning CAD vaulting, BOM validation, and supplier portal integration. The primary commercial purpose centers on collapsing iteration cycles between design, sourcing, and manufacturing stakeholders while preserving audit trails for regulated industries. Hybrid Cloud deployment captures the dominant margin pool as enterprises balance sensitive IP retention on private nodes with supplier collaboration via public interfaces, while Quality Management solution offerings are expanding fastest as FDA 21 CFR Part 11 traceability requirements and EU MDR technical documentation obligations push pharmaceutical developers and medical device manufacturers toward validated cloud quality systems.
FDA 21 CFR Part 11, EU MDR, and ISO 27001 collectively shape market access by mandating electronic signature integrity, design history file traceability, and information security management system audits for vendors serving regulated end users. EMA's evolving guidance on computerized systems validation and Japan's PMDA QMS ministerial ordinances further fragment compliance requirements, forcing platform providers to maintain geography-specific certification portfolios rather than universal SaaS templates. Stakeholders must monitor divergence between FDA's risk-based software validation approach and EU MDR's prescriptive technical documentation standards when selecting multi-tenant architectures that cannot be retrofitted for jurisdictional variance without substantial re-platforming costs.
Market Dynamics
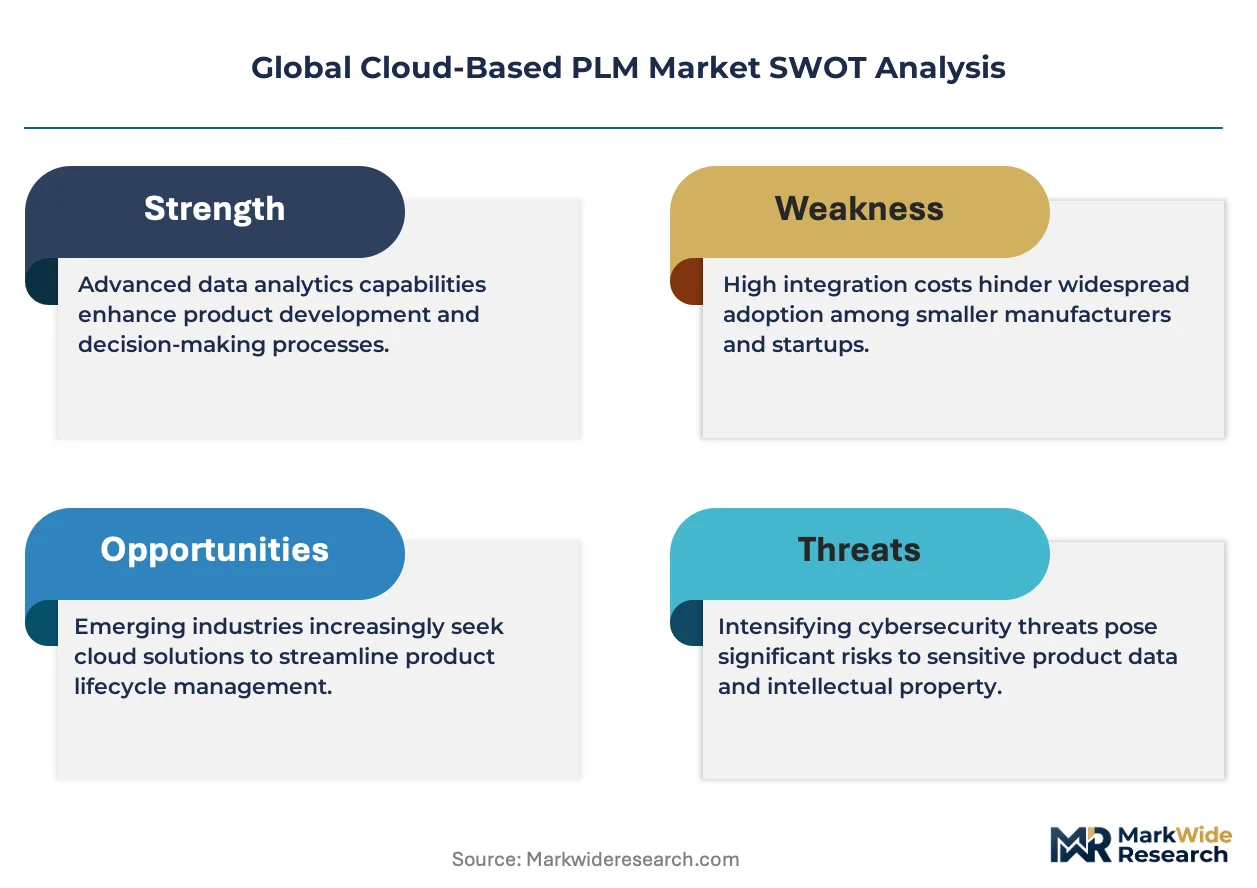
ISO 27001 certification requirements and the EU AI Act are fragmenting vendor qualification pathways, forcing platform providers to maintain parallel compliance architectures rather than unified global deployments.
Growth Catalysts
- Defense procurement modernization:US Department of Defense mandates for digital engineering environments are accelerating SaaS migrations among aerospace suppliers seeking CMMC 2.0 alignment.
- EU MDR technical documentation obligations:Medical device manufacturers face compressed submission timelines that cloud-native quality systems address through automated design history file traceability.
- Digital thread architectures:Closed-loop feedback between IoT field assets and engineering change orders is collapsing iteration cycles for industrial equipment OEMs.
Market Restraints
- Data sovereignty compliance costs:Germany's BSI baseline protection requirements and France's ANSSI cloud security certifications impose redundant audit burdens on multi-tenant architectures.
- Hybrid integration complexity:Enterprises retaining sensitive IP on private nodes while extending supplier collaboration via public interfaces face API governance challenges that extend deployment timelines.
- Specialized talent scarcity:Shortages of professionals holding simultaneous expertise in FDA 21 CFR Part 11 validation and cloud infrastructure architecture constrain implementation velocity.
Strategic Opportunities
- Japan's PMDA QMS digitization:Ministerial ordinance revisions creating validated computerized systems pathways for pharmaceutical developers represent underpenetrated demand.
- Automotive battery supply chain traceability:EU Battery Regulation digital product passport requirements are generating new quality management module demand among cell manufacturers.
- AI-native design assistance:Convergence of generative engineering tools with PLM data lakes enables predictive BOM validation that reduces sourcing errors.
Industry Challenges
- Legacy CAD vault migration:Decades of proprietary file formats and undocumented design intent create data loss risks during cloud transitions.
- Cross-jurisdictional audit trail reconciliation:FDA's risk-based software validation approach diverges from EU MDR prescriptive documentation standards, forcing platform customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud-Based PLM Market |
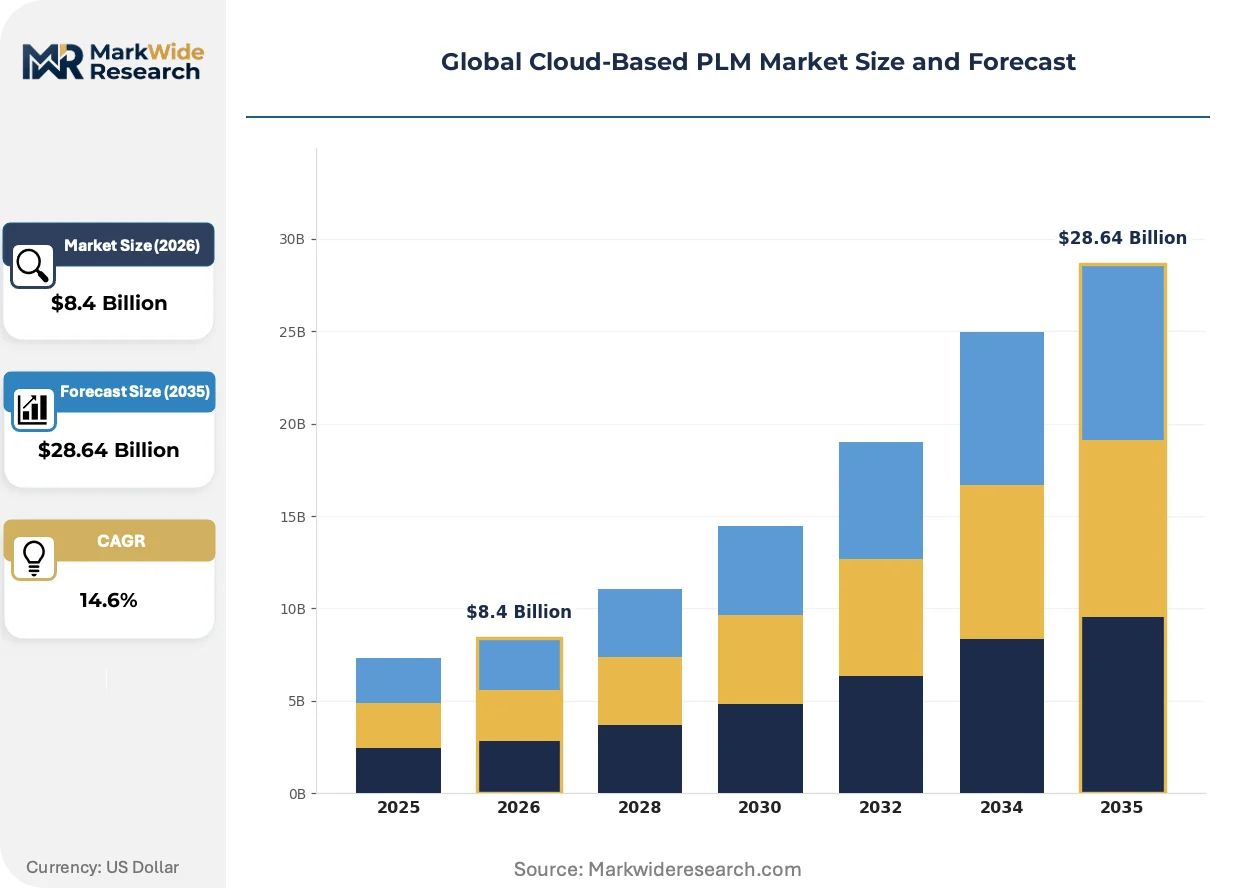
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Product Data Management, Collaboration, Quality Management, Change Management, Compliance Management Use Case: Design Collaboration, Document Management, Bill of Materials Management, Supplier Management, Project Management End User Industry: Consumer Electronics Firms, Aerospace Manufacturers, Pharmaceutical Developers, Apparel Brands |
| Companies Covered | Dassault Systèmes, Siemens AG, PTC Inc., Oracle Corporation, SAP SE, Autodesk Inc., Arena Solutions Inc., Aras, Razorleaf Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud-Based PLM Market Shifts & Advancements
Multi-model AI integration and sovereign cloud architectures are reconfiguring how engineering data flows across organizational boundaries and regulatory jurisdictions.
Generative design assistants trained on PLM-resident CAD libraries are displacing manual parametric modeling workflows in automotive and aerospace engineering centers. Tier 1 suppliers in Germany and Japan are deploying these tools for topology optimization tasks that previously required dedicated simulation specialists. The compression of design iteration cycles is enabling concurrent engineering models that collapse traditional stage-gate handoffs.
The EU AI Act's risk classification framework for high-stakes industrial applications is mandating explainability requirements for automated engineering decision systems. PLM vendors must now embed algorithmic audit trails that satisfy conformity assessment body scrutiny. Medical device developers in Ireland and the Netherlands are piloting these capabilities ahead of notified body expectations.
Subscription-based platform access with usage-scaled pricing is replacing perpetual license models among mid-market industrial machinery producers. German Mittelstand manufacturers are consolidating vendor relationships around integrated SaaS suites rather than best-of-breed point solutions. This procurement consolidation concentrates purchasing power with platforms demonstrating cross-functional workflow coverage.
Global Cloud-Based PLM Market Segmentation
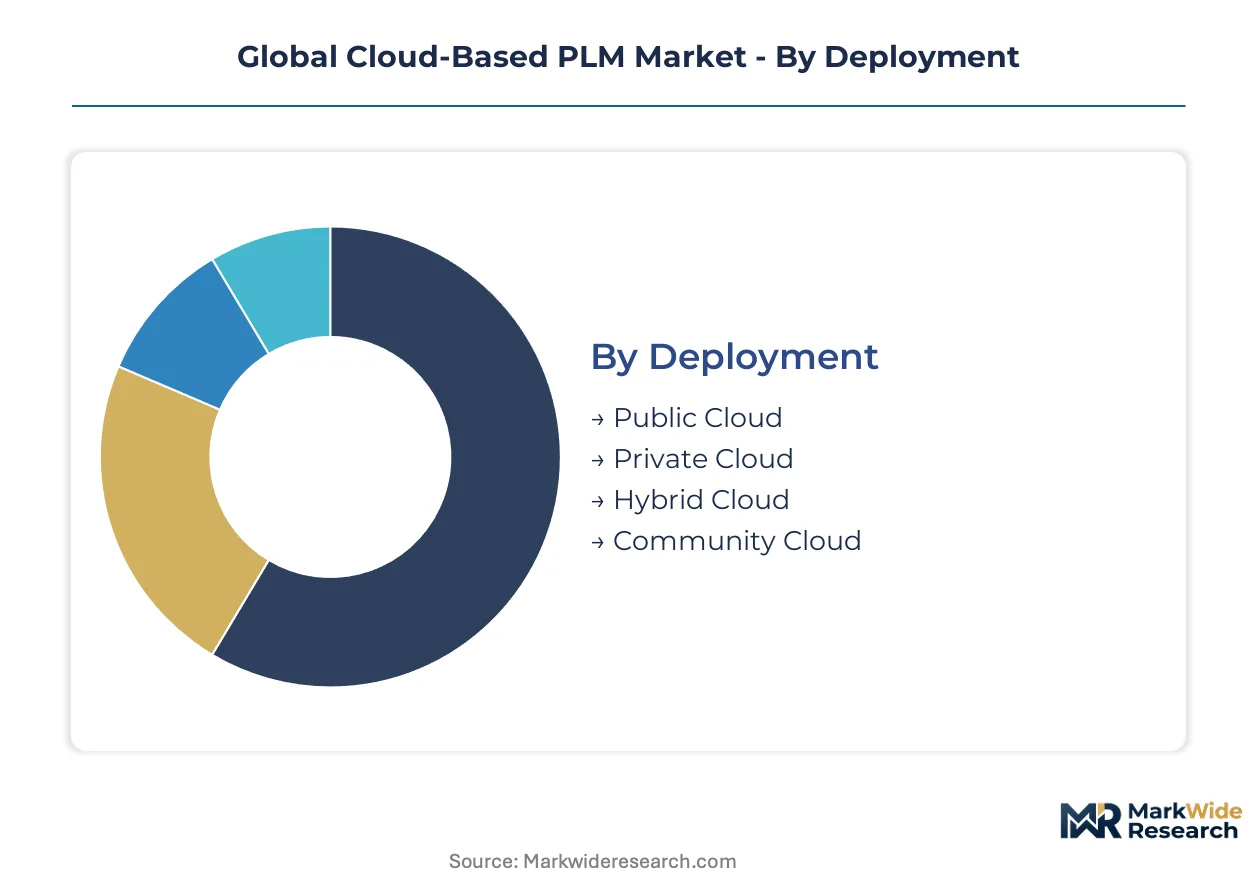
Cloud-based PLM segmentation reveals how deployment architectures, solution modules, and industry-specific compliance requirements fragment vendor addressable markets. Each dimension carries distinct substitution pressures from adjacent enterprise software categories and legacy on-premise systems.
Deployment:
Private Cloud deployments face the strongest substitution threat from sovereign cloud offerings and edge-hybrid alternatives as data residency requirements harden across Germany, France, and Japan.
- Public Cloud:Multi-tenant architectures deliver cost efficiency through shared infrastructure and automated scaling. Aerospace suppliers in the United States migrate legacy vaults to public nodes for supplier portal access, though CMMC 2.0 alignment constrains adoption for defense-facing programs.
- Hybrid Cloud:Enterprises retain sensitive IP on private nodes while extending collaboration via public interfaces. German automotive OEMs deploy this architecture to satisfy BSI baseline protection requirements without sacrificing Tier 2 supplier connectivity.
- Private Cloud:Single-tenant dedicated infrastructure serves pharmaceutical developers bound by FDA 21 CFR Part 11 validation protocols and EU MDR technical documentation mandates.
- Community Cloud:Shared infrastructure restricted to industry consortium members addresses cross-competitive collaboration needs among French aerospace suppliers.
Hybrid Cloud anchors the volume base while Public Cloud gains share at the steepest rate among mid-market machinery producers consolidating vendor relationships.
Solution Offering:
Margin concentration varies sharply across modules, with compliance-heavy offerings commanding premium pricing against commoditized collaboration tools.
- Quality Management:Validated computerized systems address FDA 21 CFR Part 11 traceability and EU MDR design history file obligations. Medical device manufacturers in Ireland and the Netherlands pilot automated audit trail capabilities ahead of notified body expectations.
- Product Data Management:CAD vaulting and BOM validation form the technical core of PLM architectures. Aerospace engineering centers in the United States leverage these capabilities for digital thread implementations linking field assets to engineering change orders.
- Collaboration:Web-based review and markup tools enable distributed stakeholder participation. Apparel brands deploy these modules for seasonal collection coordination across Asian manufacturing partners.
- Change Management:Workflow engines govern engineering change order propagation through supply chains. Automotive battery cell manufacturers utilize these tools for EU Battery Regulation digital product passport compliance.
- Compliance Management:Regulatory content libraries and submission templates serve pharmaceutical developers navigating EMA guidance divergence from FDA risk-based validation approaches.
Product Data Management anchors the volume base while Quality Management climbs the fastest as regulated industries accelerate SaaS migrations.
Use Case:
Application-level segmentation tracks how engineering workflows fragment across functional boundaries and organizational hierarchies.
- Design Collaboration:Concurrent engineering platforms enable real-time CAD review across distributed teams. German Mittelstand machinery producers deploy these capabilities to compress stage-gate handoffs previously requiring physical co-location.
- Bill of Materials Management:Multi-level BOM validation and sourcing integration reduce procurement errors. Consumer electronics firms in Japan utilize these tools for component obsolescence prediction and last-time-buy optimization.
- Document Management:Controlled repository services with electronic signature integrity serve regulated documentation requirements. Pharmaceutical developers maintain these systems for regulatory submission archives.
- Supplier Management:Portal-based qualification and performance tracking extend quality systems to external partners. Aerospace Tier 1 suppliers in France deploy these modules for ANSSI-certified collaboration with sub-tier vendors.
- Project Management:Stage-gate milestone tracking and resource allocation tools coordinate complex product introductions. Apparel brands utilize these capabilities for seasonal calendar synchronization across global sourcing offices.
Bill of Materials Management anchors the volume base while Design Collaboration expands most quickly under generative engineering tool integration.
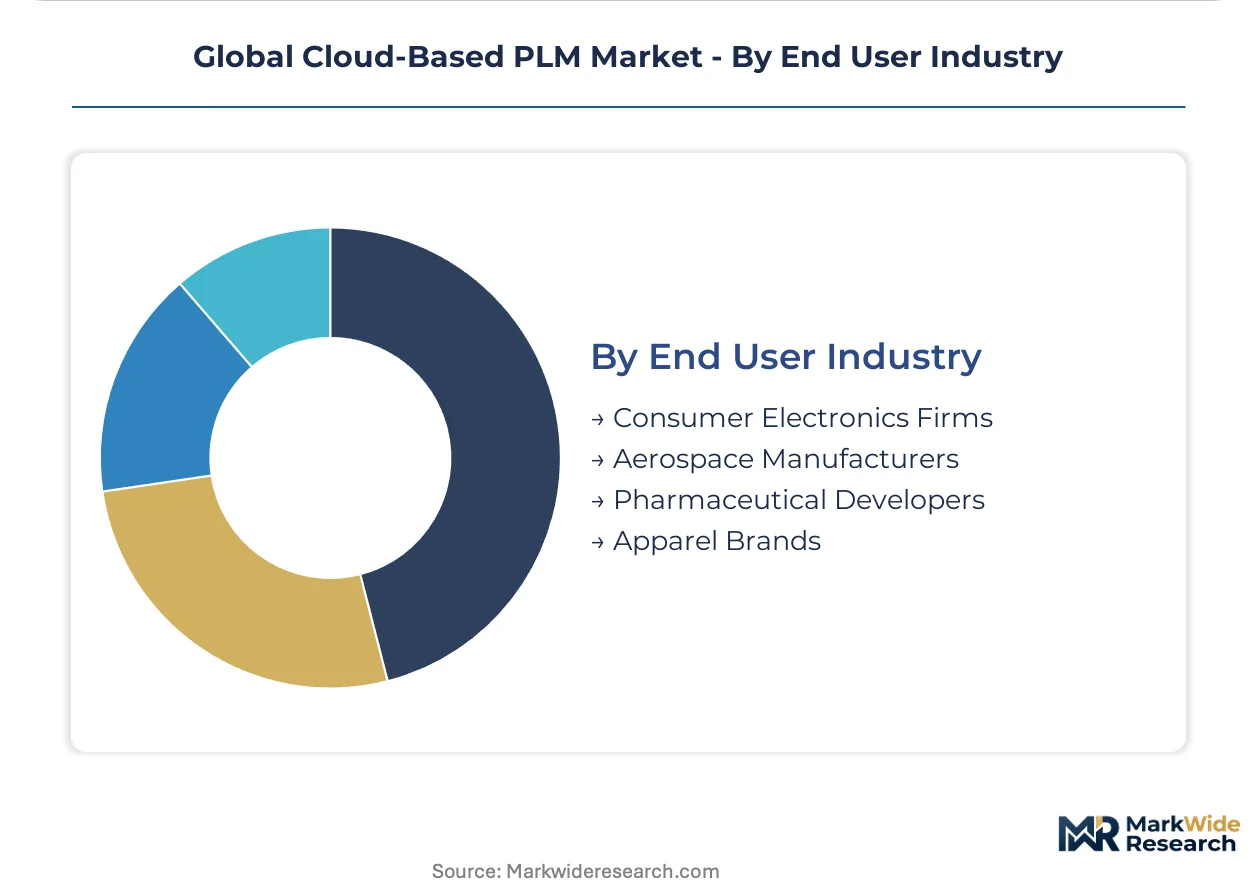
End User Industry:
Industry verticals impose divergent certification and workflow requirements that reshape platform configuration priorities.
- Aerospace Manufacturers:Digital engineering environments supporting CMMC 2.0 alignment and digital thread architectures. US Department of Defense procurement mandates accelerate SaaS migrations among defense suppliers.
- Pharmaceutical Developers:Validated quality systems addressing FDA 21 CFR Part 11, EU MDR, and Japan PMDA QMS ministerial ordinances. EMA computerized systems validation guidance creates parallel compliance pathway requirements.
- Consumer Electronics Firms:Rapid iteration platforms for compressed product lifecycles and global supply chain coordination. Short development calendars prioritize collaboration module deployment over compliance-heavy alternatives.
- Apparel Brands:Seasonal collection management and supplier sustainability tracking. EU Green Deal digital product passport requirements are generating new module demand for material traceability.
Aerospace Manufacturers anchor the volume base while Pharmaceutical Developers show the steepest expansion trajectory under regulatory digitization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 mandates and EU MDR digitization deadlines are redrawing procurement priorities across national boundaries. Defense modernization programs and pharmaceutical traceability requirements are accelerating cloud migrations in concentrated industrial clusters.
United States
Defense procurement mandates from the Department of Defense are compelling aerospace suppliers toward CMMC 2.0-aligned digital engineering environments. FDA risk-based software validation frameworks shape vendor selection for pharmaceutical developers. Greater Boston and the Pacific Northwest host dense concentrations of medical device and aerospace engineering centers migrating legacy vaults to SaaS architectures.
Germany
BSI baseline protection requirements and ANSSI cloud security certifications impose redundant audit burdens on multi-tenant architectures serving automotive OEMs. EU MDR technical documentation obligations compress submission timelines for medical device manufacturers. Bavaria and Baden-Württemberg anchor Mittelstand machinery producers consolidating vendor relationships around integrated SaaS suites.
Japan
PMDA QMS ministerial ordinance revisions create validated computerized systems pathways for pharmaceutical developers. METI industrial digitization incentives support cloud adoption among precision machinery manufacturers. The Kanto region around Tokyo concentrates consumer electronics firms deploying rapid iteration platforms for compressed product lifecycles.
France
ANSSI cloud security certifications and EU AI Act risk classification frameworks mandate explainability requirements for automated engineering systems. EMA computerized systems validation guidance fragments compliance requirements for pharmaceutical exporters. The Île-de-France region hosts aerospace Tier 1 suppliers deploying ANSSI-certified collaboration portals with sub-tier vendors.
India
PLI scheme incentives for electronics manufacturing are generating quality management module demand among contract manufacturers serving export markets. CDSCO digitization initiatives align with global regulatory traceability standards. Karnataka and Tamil Nadu concentrate engineering services providers building cloud-native PLM implementation capabilities for multinational clients.
Global Cloud-Based PLM Market Competitive Landscape
Listed leaders compete with private specialists across compliance certification depth and industry-specific workflow integration. The vendor base stratifies between platforms maintaining parallel geography-specific certification portfolios and mid-tier entrants facing elevated ISO 27001 compliance costs. Three archetypes dominate: established enterprise software conglomerates with manufacturing execution adjacencies, cloud-native specialists competing on deployment velocity, and private equity-backed platforms consolidating point solutions. Competitive moves center on sovereign cloud partnerships and generative engineering tool integration.
Within the enterprise conglomerate tier, Dassault Systèmes, Siemens AG, and PTC Inc. occupy positions defined by manufacturing software heritage and digital twin capabilities. These France-based, Germany-based, and US-based entities respectively exemplify archetypes anchored in aerospace engineering workflows, shop-floor connectivity integration, and IoT-native design feedback loops. Their competitive positioning reflects decades of proprietary CAD vault accumulation and validated quality system deployment in regulated industries.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Siemens AG |
| PTC Inc. |
| Oracle Corporation |
| SAP SE |
| Autodesk Inc. |
| Arena Solutions Inc. |
| Aras |
| Razorleaf Corp. |
| Others |
Supply & Pricing Matrix
Multi-tenant infrastructure scale economies at hyperscaler facilities in the United States and Germany compress unit economics for established platforms while elevating fixed-cost barriers for mid-tier entrants, concentrating pricing power among vendors holding parallel FDA, EU MDR, and ISO 27001 certification portfolios.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 21 CFR Part 11-validated deployments commanding substantial premiums over baseline ISO 27001 offerings. Subscription-based SaaS pricing with usage-scaled tiers dominates, though pharmaceutical developers show lowest price sensitivity given compliance imperatives while mid-market machinery producers drive hardest bargain consolidation around integrated suites. Cost compression in standard-tier collaboration modules intensifies as cloud-native specialists compete on deployment velocity, eroding margins for point-solution vendors lacking compliance depth.
Supply Chain Analysis
The United States and Germany anchor hyperscaler data center capacity serving aerospace and automotive OEMs, while Ireland and the Netherlands host specialized sovereign cloud facilities for EU MDR-regulated medical device developers. Software development labor pools in India and Poland feed implementation and customization services, with delivery timelines tethered to specialized talent holding simultaneous FDA validation and cloud architecture expertise. Single-source vulnerability concentrates in hyperscaler substrate provision, with distribution running through direct enterprise sales teams supplemented by systems integrator channels for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement modernization cycles and pharmaceutical regulatory digitization deadlines position this market for cyclical recovery, with CMMC 2.0 alignment mandates and EU MDR technical documentation obligations creating sustained upgrade demand across installed bases.
For Market Incumbents: Secure CMMC 2.0 certification pathways ahead of US Department of Defense procurement deadlines to anchor aerospace supplier relationships against cloud-native entrants lacking defense compliance depth. Invest in generative engineering tool integration to defend against specialized AI-native design assistants displacing manual parametric workflows in German and Japanese Tier 1 supplier engineering centers. For New Entrants and Emerging Players: Differentiate on sovereign cloud deployment velocity for EU AI Act high-risk system classifications, targeting French aerospace Tier 1 suppliers and Irish medical device developers ahead of notified body expectations. Penetrate Japan's PMDA QMS digitization pathway for pharmaceutical developers, where validated computerized systems demand runs ahead of incumbent platform localization. For Investors and Strategic Acquirers: Cloud-native quality management specialists with EU MDR automated audit trail capabilities represent the most defensible acquisition profile, given regulatory digitization tailwinds and limited vendor supply. Long-term viability hinges on parallel certification portfolio maintenance rather than single-jurisdiction SaaS templates, with recalibration signals appearing in EMA-FDA guidance divergence announcements and Japan PMDA ministerial ordinance revision timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | ANSSI-certified French facilities satisfy EU AI Act data residency requirements for aerospace collaboration. |
| Generative Design Integration | PLM-resident CAD library training compresses topology optimization cycles for German automotive suppliers. |
| Quality Management Module Expansion | FDA 21 CFR Part 11 validation protocols capture pharmaceutical developer upgrade budgets ahead of submission deadlines. |
| Hybrid Deployment Architecture | BSI-compliant private nodes with public supplier portals address German Mittelstand IP protection requirements. |
| Regulatory Content Library Investment | EMA-FDA divergence tracking reduces re-platforming costs for multi-jurisdictional medical device exporters. |
Research Methodology
A spread of perspectives from aerospace procurement officers, pharmaceutical quality assurance directors, cloud platform engineers, and systems integration specialists converged on the working assumptions underlying demand forecasts. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) submission databases, EMA centralized procedure records, US Department of Defense procurement announcements, and hyperscaler capex disclosures. Bottom-up deployment modeling across deployment architectures, solution modules, and end-user industries triangulated against top-down market sizing from enterprise software spending patterns.
Segmentation dimensions modeled span deployment model, solution offering, use case, and end-user industry vertical, with additional granularity on regulatory jurisdiction clusters affecting certification requirements. CAGRs were derived from installation base migration rates and new customer acquisition velocity across the projection horizon. Forecast inputs incorporated CMMC 2.0 implementation timelines, EU MDR transition deadline effects, and Japan PMDA QMS digitization incentive uptake curves without year-specific anchoring.
Material uncertainties — regulatory guidance divergence, defense procurement cycle shifts, and hyperscaler capacity allocation decisions — sit outside the modeled envelope. Forecasts reflect assumptions about sustained compliance investment appetite and cloud migration momentum among regulated industries. Recalibration cycles align with material shifts in FDA risk-based validation guidance, EU AI Act enforcement precedence, and sovereign cloud certification expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Cloud-Based VDI Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Global Cloud Monitoring Market