
 Cloud Information Technology Service Management (ITSM) Market | 2026-2036
Cloud Information Technology Service Management (ITSM) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Information Technology Service Management (ITSM) Market Outlook
Agentic AI integration into service orchestration layers is rewriting how enterprises automate incident resolution and change governance. ServiceNow Inc. leverages native workflow engines to anchor premium positioning in enterprise accounts. BMC Software Inc. competes through deep mainframe-to-cloud bridging capabilities for legacy-heavy industries. Atlassian Corporation Plc differentiates via developer-centric ITSM tooling that collapses the boundary between DevOps and service operations.
Cloud Information Technology Service Management encompasses the design, delivery, and governance of IT services through cloud-hosted platforms that provide ticketing, asset tracking, and service catalog functions with guaranteed availability thresholds typically exceeding 99.9%. These systems serve as the operational backbone for enterprises seeking to replace on-premises ITIL frameworks with elastic, API-driven service fabrics. Hybrid Cloud deployment now captures the most complex procurement conversations as organizations straddle data sovereignty requirements against scalability demands. AI-Powered Chatbots within the Technology segment represent the fastest capability expansion area, though Analytics Dashboards retain the strongest margin profile due to embedded BI licensing structures. Incident Management remains the most mature Service Type, while Change Management shows accelerated attach rates as regulatory pressure intensifies on software supply chain governance.
FDA scrutiny of software-as-a-service platforms in healthcare IT environments shapes vendor qualification requirements for patient data handling. The EU AI Act and GDPR jointly compel European buyers to embed algorithmic transparency and data residency controls into ITSM procurement specifications. NIST cybersecurity frameworks in the US further harden baseline security expectations for federal and defense-adjacent deployments. Stakeholders must weigh the pace of autonomous agent deployment against emerging algorithmic accountability obligations that will reshape vendor liability and customer due diligence protocols.
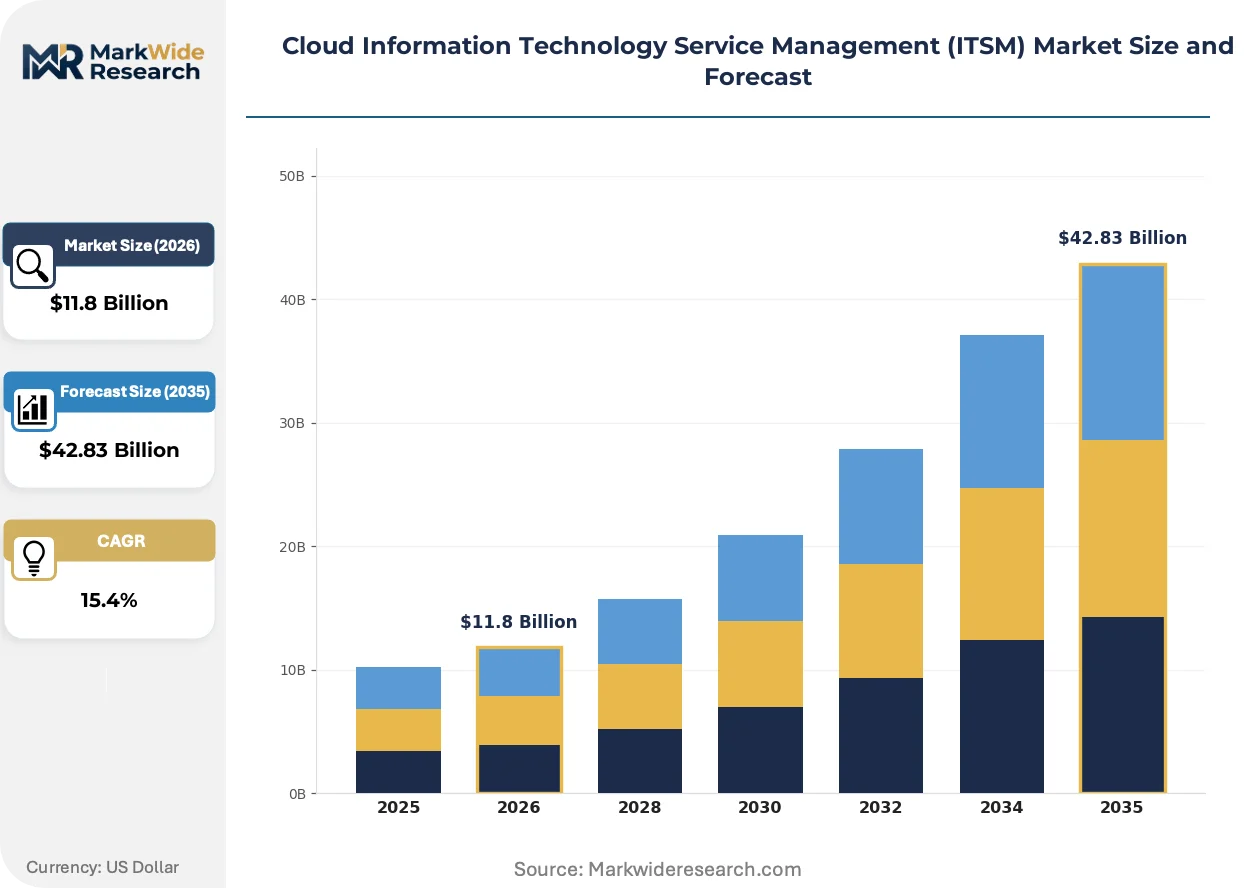
Market Dynamics
Agentic AI deployment across service orchestration layers is compressing incident resolution timelines and forcing vendors to embed autonomous decision-making into core ITSM workflows, fundamentally restructuring how enterprises negotiate platform contracts and capability roadmaps.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises now require audit-ready ITSM workflows with embedded algorithmic transparency controls, expanding procurement specifications for governance-native platforms.
- Healthcare service desk modernization:Hospital systems are replacing legacy ticketing infrastructure with cloud-hosted alternatives to streamline patient-facing IT operations and reduce clinical downtime.
- Predictive incident management:German industrial manufacturers are converging operational technology monitoring with ITSM platforms to anticipate equipment failures before production disruption occurs.
Market Restraints
- Data residency compliance costs:Multi-tenant cloud architectures face friction from GDPR localization requirements and divergent national data sovereignty laws across European member states.
- Legacy system integration debt:Mainframe-dependent enterprises in financial services and government sectors encounter technical limitations when bridging decades-old COBOL workflows to API-driven service fabrics.
- Specialized talent scarcity:The shortage of professionals combining ITIL governance expertise with cloud-native architecture skills constrains enterprise implementation velocity.
Strategic Opportunities
- Operational technology convergence:Manufacturing facilities in Germany and Japan are integrating ITSM platforms with industrial IoT sensor networks, creating unified command centers for cyber-physical system management.
- Federal procurement tailwinds:NIST cybersecurity framework adoption across US defense-adjacent agencies is mandating enhanced logging and access controls that favor compliant cloud ITSM vendors.
- DevOps-tooling unification:Developer-centric ITSM configurations that collapse boundaries between incident response and software deployment pipelines remain underpenetrated outside technology-native enterprises.
Industry Challenges
- Algorithmic accountability protocols:Enterprises deploying autonomous incident resolution agents face unresolved liability frameworks when automated decisions cause service degradation or data exposure.
- Hybrid deployment complexity:Organizations straddling on-premises retention requirements against cloud scalability demands encounter integration friction that extends implementation timelines and inflates professional services dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Information Technology Service Management (ITSM) Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $42.83 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Incident Management, Change Management, Problem Management, Asset Management End User: Large Enterprises, SMEs, Government, Educational Institutions Technology: AI-Powered Chatbots, Automation Tools, Self-Service Portals, Analytics Dashboards |
| Companies Covered | IBM Corporation, ManageEngine, ServiceNow Inc., Zendesk, SolarWinds Corp., Atlassian Corporation Plc, Freshworks Inc., Micro Focus International Plc, BMC Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Information Technology Service Management (ITSM) Market Strategic Shifts
Service orchestration architectures are undergoing fundamental reconstruction as autonomous systems displace rule-based automation, regulatory frameworks harden compliance requirements, and buyer procurement models pivot toward consumption-aligned contracting structures.
Agentic AI systems are virtualizing tier-1 support functions through natural language interfaces that interpret unstructured incident reports, route tickets without human triage, and execute remediation scripts against predefined guardrails. Financial services institutions in Singapore and London are deploying these capabilities at scale, compressing mean-time-to-resolution metrics by eliminating queue-based handoffs between support tiers. This virtualization is collapsing the traditional labor arbitrage model that anchored offshore service desk economics, forcing providers to restructure delivery cost bases around platform licensing rather than headcount.
The EU AI Act's risk-classification framework is mandating algorithmic impact assessments for ITSM platforms deploying automated decision-making in high-stakes operational environments. Vendors must now document training data provenance, model performance benchmarks, and human oversight mechanisms before European enterprise deployment. Healthcare providers in France and the Netherlands are most affected, requiring vendors to retrofit existing chatbot and predictive routing engines with explainability layers that satisfy national regulator interpretations of the Act.
Enterprise buyers are consolidating vendor relationships around platforms offering unified service catalogs spanning IT, HR, and facilities workflows, displacing point solutions that previously dominated functional silos. This consolidation is compressing procurement cycles as CIOs negotiate enterprise-wide platform agreements rather than departmental best-of-breed selections. The pattern is most visible in US healthcare systems and German automotive suppliers, where procurement functions are mandating ITSM standardization to reduce integration tax and security review overhead across subsidiary operations.
Cloud Information Technology Service Management (ITSM) Market Segmentation
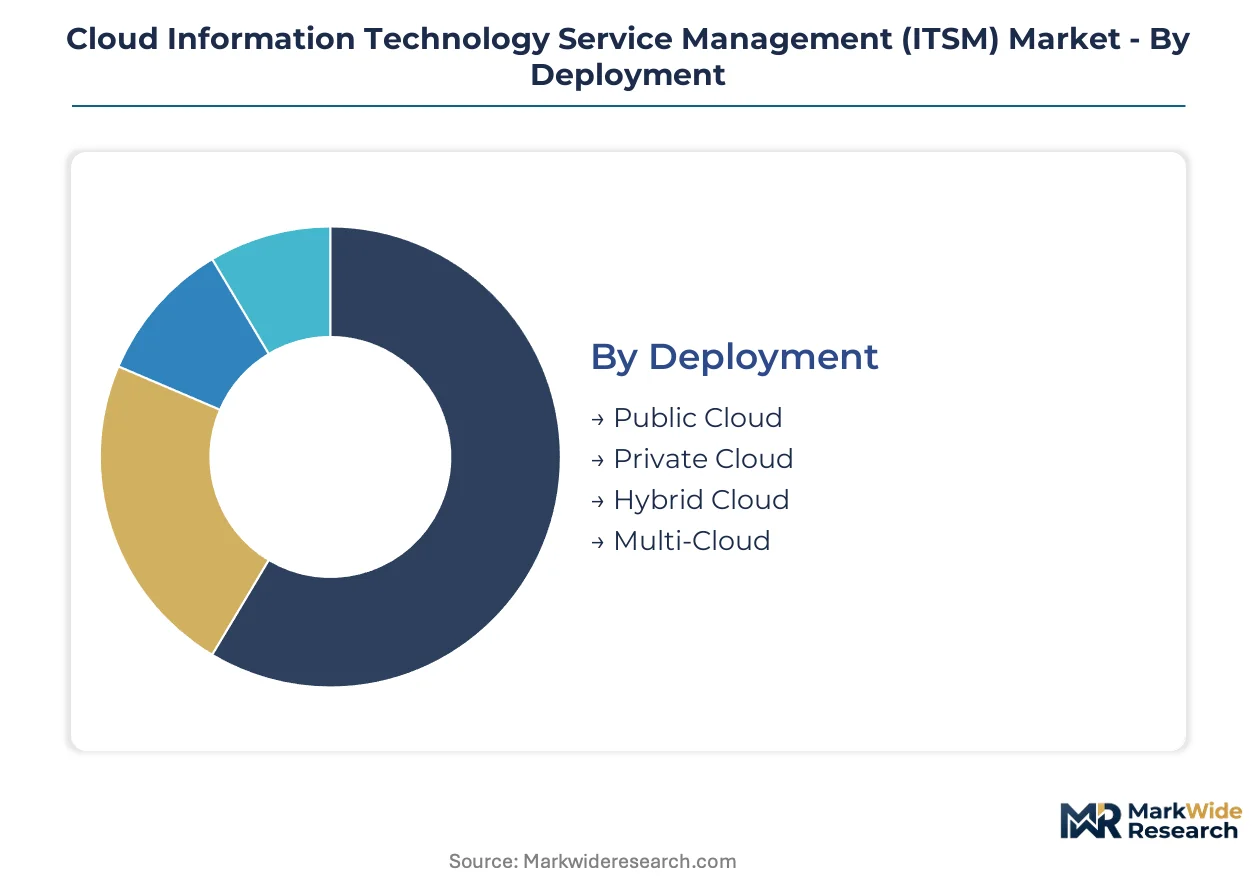
Cloud ITSM procurement patterns diverge sharply across deployment architectures, service maturity levels, and organizational scale. Vendors must align platform roadmaps with how specific buyer segments negotiate security, compliance, and automation trade-offs.
Deployment:
Mature public cloud offerings now coexist with emerging sovereign and edge-distributed alternatives that address data residency mandates.
- Public Cloud:Multi-tenant SaaS architectures deliver elastic capacity provisioning and rapid feature updates without infrastructure ownership. Healthcare systems in the United States prioritize FedRAMP-authorized public deployments to accelerate procurement timelines while satisfying HIPAA technical safeguards.
- Private Cloud:Single-tenant dedicated instances isolate compute and storage resources within customer-controlled environments. German automotive manufacturers mandate private deployments to satisfy KBA documentation requirements for production system audit trails.
- Hybrid Cloud:Orchestrated workload placement splits sensitive data processing on-premises while bursting transactional workloads to cloud infrastructure. Financial services institutions in Singapore deploy hybrid configurations to retain core banking data locally while leveraging cloud analytics for customer-facing dashboards.
- Multi-Cloud:Abstracted control planes distribute services across two or more hyperscaler environments to mitigate vendor lock-in and regional outage risks. Japanese electronics conglomerates adopt multi-cloud ITSM to satisfy METI supply chain resilience guidelines for critical operational technology.
Hybrid Cloud captures the most complex procurement conversations; Multi-Cloud holds the steepest expansion curve.
Service Type:
Functional specialization within ITSM platforms maps directly to organizational maturity in ITIL process adoption and automation depth.
- Incident Management:Real-time ticket routing, escalation orchestration, and service level agreement enforcement form the operational backbone of every ITSM deployment. Incident Management retains the highest attach rate across all buyer segments due to its universal applicability in minimizing service downtime.
- Change Management:Controlled workflow gates for software releases, infrastructure modifications, and configuration updates embed compliance documentation and risk assessment. European enterprises subject to EU AI Act mandates prioritize Change Management modules with embedded algorithmic change logs and rollback automation.
- Problem Management:Root cause analysis workflows and known error databases reduce recurring incident volumes through systematic defect elimination. Problem Management sees concentrated demand among telecommunications operators managing complex network infrastructure across multiple technology generations.
- Asset Management:Configuration item tracking, software license compliance, and hardware lifecycle management integrate with financial systems for total cost of ownership visibility. Asset Management accelerates most quickly in regulated industries facing intensified software supply chain governance requirements.
Incident Management retains volume leadership; Asset Management gains share fastest as regulatory pressure intensifies on configuration documentation.
End User:
Scale and governance requirements create distinct buying centers with divergent evaluation criteria and contract structures.
- Large Enterprises:Global IT organizations with thousands of service agents demand enterprise-wide platform standardization, advanced API extensibility, and dedicated customer success programs. Large Enterprises in the United States negotiate multi-year enterprise agreements with embedded professional services for legacy system migration.
- SMEs:Mid-market organizations prioritize rapid deployment templates, pre-configured ITIL workflows, and consumption-based pricing that aligns costs with actual ticket volumes. SMEs across India favor ITSM platforms with localized compliance reporting for RBI and SEBI audit requirements.
- Government:Public sector agencies mandate FedRAMP, StateRAMP, or equivalent security authorizations with enhanced logging for freedom of information and oversight compliance. Government buyers in Australia require IRAP-assessed cloud ITSM to satisfy TGA and defense-adjacent procurement standards.
- Educational Institutions:Universities and K-12 districts seek cost-optimized deployments with semester-aware licensing and student-facing self-service capabilities. Educational Institutions in Canada prioritize platforms with PIPEDA-aligned privacy controls for student information systems.
Large Enterprises dominate current procurement value; Government segment climbs the fastest as sovereign cloud mandates expand.
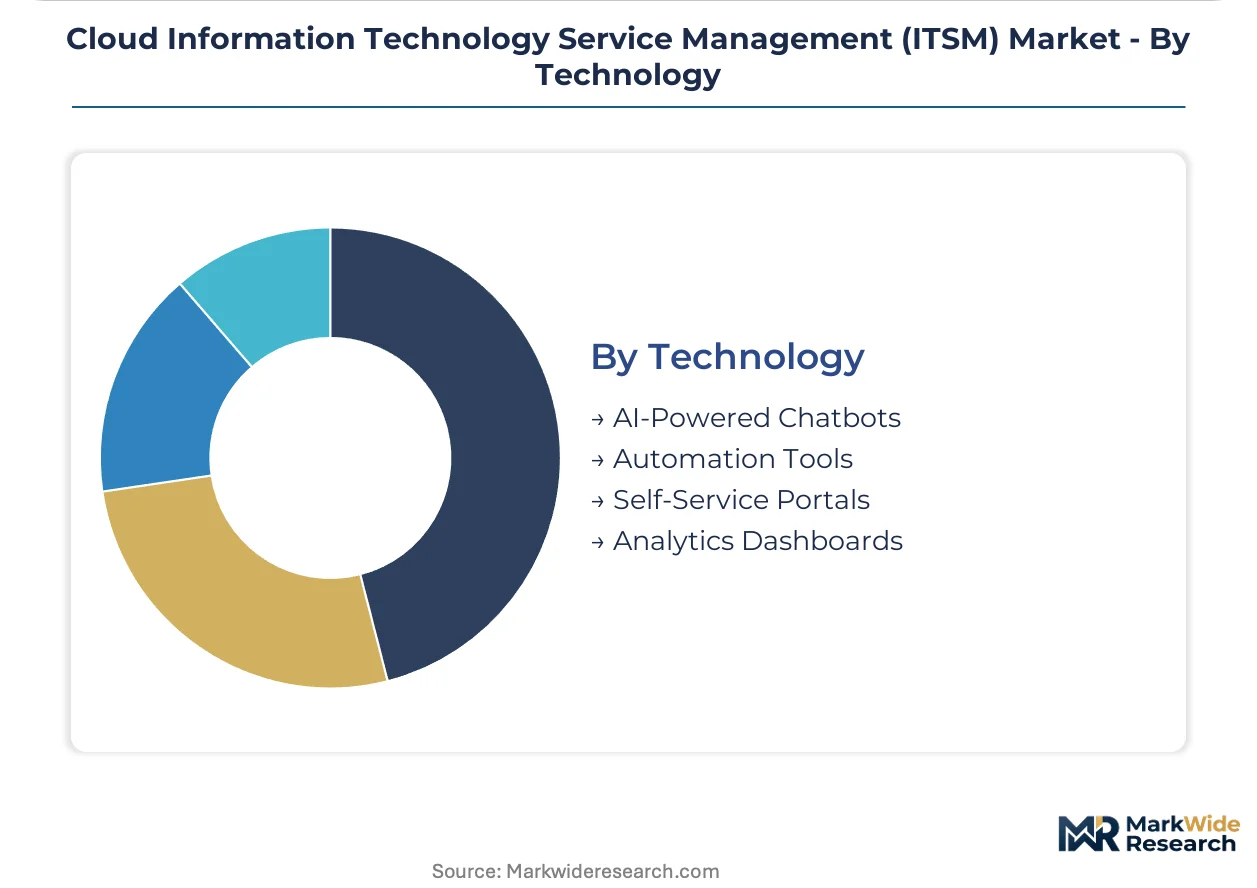
Technology:
Capability layers within cloud ITSM platforms differentiate through automation sophistication and user experience design.
- AI-Powered Chatbots:Natural language interfaces interpret unstructured user requests, execute diagnostic scripts, and resolve tier-1 incidents without human intervention. AI-Powered Chatbots expand most quickly as healthcare providers in the Netherlands deploy virtual agents to reduce clinical staff IT distraction.
- Automation Tools:Workflow engines trigger cross-system orchestration, provision resources, and enforce policy compliance through predefined runbook execution. Automation Tools see concentrated investment among German industrial manufacturers converging IT and operational technology monitoring.
- Self-Service Portals:Branded user interfaces enable request submission, knowledge base access, and service catalog browsing with minimal training requirements. Self-Service Portals retain the broadest penetration across all end-user segments due to immediate IT labor cost reduction.
- Analytics Dashboards:Embedded business intelligence visualizes service performance, team productivity, and cost allocation with drill-down capabilities for operational improvement. Analytics Dashboards command premium pricing through embedded BI licensing structures and executive reporting requirements.
Self-Service Portals retain volume leadership; AI-Powered Chatbots represent the steepest capability expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States and industrial manufacturers in Germany anchor procurement volume, while Singapore and Japan drive adoption of operational technology convergence. Regulatory fragmentation across data sovereignty and algorithmic accountability mandates shapes vendor qualification requirements.
United States
Federal agencies and defense-adjacent contractors demand FedRAMP-authorized platforms with NIST-aligned logging controls. HIPAA technical safeguard enforcement shapes healthcare ITSM procurement specifications. Hospital systems in the Greater Boston corridor replace legacy ticketing infrastructure with cloud-hosted alternatives to minimize clinical downtime.
Germany
Automotive suppliers and industrial machinery producers prioritize predictive incident management for cyber-physical system integration. KBA documentation requirements mandate private cloud deployments with audit-ready configuration trails. Manufacturing clusters in Bavaria and Baden-Württemberg converge ITSM platforms with industrial IoT sensor networks.
United Kingdom
Financial services institutions in London deploy agentic AI capabilities at scale to compress mean-time-to-resolution metrics. FCA operational resilience directives mandate embedded change governance and rollback automation. The City of London and Canary Wharf technology centers drive tier-1 support virtualization investments.
Singapore
Banking and maritime logistics operators adopt hybrid configurations to retain core transaction data locally while bursting analytics workloads to cloud infrastructure. MAS technology risk management guidelines harden baseline security expectations for financial ITSM deployments. The Marina Bay financial district anchors regional procurement value.
Japan
Electronics conglomerates and automotive OEMs distribute ITSM services across multi-cloud architectures to satisfy METI supply chain resilience guidelines. Data localization preferences favor domestic cloud partnerships for sensitive operational technology monitoring. Industrial corridors in Aichi Prefecture and the Kanto region lead platform standardization initiatives.
Cloud Information Technology Service Management (ITSM) Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Enterprise-grade workflow engines anchor premium positioning for global account penetration. Developer-centric tooling specialists capture mid-market velocity through rapid deployment templates. Legacy systems integrators defend installed base relationships through mainframe bridging capabilities. Dominant competitive moves include strategic partnerships with hyperscaler platforms and portfolio diversification into adjacent HR and facilities workflows.
Within the enterprise workflow tier, ServiceNow Inc. and BMC Software Inc. occupy positions defined by native automation depth and legacy integration reach respectively. Atlassian Corporation Plc anchors the developer-centric segment where tooling convergence between incident response and software deployment pipelines accelerates. These three entities exemplify how platform specialization maps to distinct buyer archetypes across regulated industries and technology-native enterprises.
| Leading Market Players |
|---|
| IBM Corporation |
| ManageEngine |
| ServiceNow Inc. |
| Zendesk |
| SolarWinds Corp. |
| Atlassian Corporation Plc |
| Freshworks Inc. |
| Micro Focus International Plc |
| BMC Software Inc. |
| Others |
Value Chain & Pricing Dynamics
Bavarian industrial corridors anchor cloud ITSM platform development capacity, where concentrated hyperscaler engineering talent pools and German automotive compliance requirements feed downstream pricing power toward enterprise buyers negotiating multi-year contracts.
Pricing Analysis
Cost-plus contracts with annual indexation to hyperscaler infrastructure rates anchor enterprise SaaS pricing, though AI-powered tier premiums now stratify across premium, standard, and economy tiers based on automation depth and audit-ready compliance modules. Price differentiation hinges on FedRAMP authorization tier and embedded EU AI Act explainability layers. Pricing pressure stems from open-source DevOps tooling alternatives eroding mid-market standard-tier margins. SMEs exhibit acute price sensitivity; defense-adjacent government buyers show inelastic demand for authorized premium tiers.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for cloud ITSM vendors dependent on semiconductor hardware and hyperscaler data center equipment. Engineering talent concentrates in Germany, United States, and India. Platform development draws from open-source frameworks, proprietary ML training pipelines, and third-party API ecosystems. Single-source vulnerability sits with hyperscaler compute capacity allocation. Distribution runs through direct enterprise sales teams, hyperscaler marketplace listings, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud ITSM platforms function as defensive-moat businesses where regulatory entrenchment creates sticky switching costs—once EU AI Act compliance workflows embed into hospital procurement specifications, displacement becomes prohibitively expensive.
For Market Incumbents: Harden platform stickiness by deepening native workflow engine capabilities that resist modular substitution from point solutions. Invest in FedRAMP and StateRAMP authorization expansion to capture accelerating government segment procurement. Defend against developer-centric challengers by collapsing incident response and software deployment pipeline boundaries through API-native tooling integration. For New Entrants and Emerging Players: Establish a beachhead in mid-market healthcare systems seeking rapid ITIL deployment templates without enterprise-grade customization overhead. Target Indian SME segments with RBI and SEBI-aligned compliance reporting modules that incumbent platforms address inadequately. Pursue channel partnerships with regional systems integrators possessing existing hospital procurement relationships rather than direct sales buildout. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because algorithmic accountability mandates and data sovereignty laws continuously raise compliance barriers that favor incumbent scale. Acquisition targets should display concentrated vertical expertise in healthcare or automotive compliance workflows rather than horizontal feature breadth. Monitor EU AI Act enforcement variance across member states as the signal indicating which national markets will consolidate fastest toward platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies IT, HR, and facilities workflows to reduce enterprise integration tax across subsidiary operations. |
| Acquisition of Specialist Firm | Captures vertical-specific compliance expertise in healthcare FDA workflows or German KBA audit requirements. |
| Strategic Partnership | Hyperscaler alliances accelerate FedRAMP authorization timelines and expand government marketplace presence. |
| Geographic Expansion | Sovereign cloud deployments in France and Netherlands satisfy EU AI Act national regulator interpretations. |
| Product Launch | Agentic AI tier-1 support virtualization compresses mean-time-to-resolution for Singapore financial services buyers. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and channel partners across healthcare, automotive, and financial services verticals; and secondary validation through SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement database analysis. Bottom-up deployment estimates triangulated against top-down market sizing from ITIL governance adoption benchmarks.
Forecast inputs across deployment model, organization size, vertical integration complexity, and regional adoption pattern were modeled over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro IT spending elasticity coefficients. Industry-specific inputs included EU AI Act implementation timelines and NIST cybersecurity framework adoption curves.
Stress conditions across hyperscaler pricing volatility, regulatory enforcement variance, and legacy system integration failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that algorithmic accountability protocols and data sovereignty mandates evolve as anticipated. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Colombia Information Technology (IT) Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Data Quality Radar Market