
 Global Church Management Software Market | 2026-2036
Global Church Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Church Management Software Market Foresight
GDPR compliance obligations across European member states is shifting procurement criteria toward vendors with certified data residency and breach-notification protocols. Pushpay anchors its position through integrated payment processing that reduces donor friction across Australian and North American congregations. Breeze ChMS differentiates through simplified onboarding designed for volunteer-led administrative teams without dedicated IT staff.
Church management software denotes a specialized application suite that centralizes member databases, contribution tracking, event coordination, and communication workflows through configurable cloud or on-premise architectures. Its primary commercial purpose is reducing administrative overhead while improving engagement visibility for religious and faith-based institutions. Cloud-based deployment leads structural growth due to minimal infrastructure requirements and automatic security patching, while donation management commands disproportionate R&D investment because recurring giving modules directly influence customer lifetime value. Parish churches represent the most mature end-user category, though faith-based organizations with multisite operations generate the highest per-account revenue.
FCC guidelines on telecommunications transparency intersect with GDPR data-processing rules to shape how vendors architect communication features and cross-border data flows. EDPB adequacy decisions and emerging state-level privacy statutes in the United States create fragmented compliance obligations that favor vendors with modular regional configurations. ISO 27001 certification increasingly functions as a baseline qualifier rather than a differentiator in procurement evaluations. Stakeholders must monitor whether AI-assisted sermon transcription and predictive giving analytics trigger novel regulatory classifications under the EU AI Act and analogous frameworks.
Market Dynamics
Cloud-native architectures are displacing legacy on-premise installations across faith-based institutions, compressing deployment timelines from months to days while triggering wholesale vendor consolidation around API-first platforms.
Growth Catalysts
- GDPR Data Residency Mandates:European congregations now require certified EU-based servers, accelerating replacement of non-compliant legacy systems and favoring vendors with Dublin or Frankfurt data centers.
- Mobile-First Giving Behaviors:Congregants under 45 increasingly expect tap-to-donate functionality, forcing churches to adopt integrated payment processing that reduces donor abandonment rates.
- Volunteer Administrator Dependency:Mid-sized parishes with zero dedicated IT staff prioritize zero-code configuration tools that enable non-technical leaders to manage member databases independently.
Market Restraints
- Cross-Border Data Transfer Friction:Schrems II rulings and EDPB adequacy uncertainty complicate US-EU data flows for cloud vendors serving multinational denominations.
- Subscription Cost Accumulation:Modular pricing for giving, communications, and event modules creates total cost of ownership surprises for budget-constrained parishes.
- Interoperability Gaps:Proprietary data formats from legacy providers lock historical member records behind expensive migration services.
Strategic Opportunities
- AI-Assisted Sermon Workflows:Transcription and multilingual translation tools unlock accessibility compliance and archive searchability for aging congregations.
- Sub-Saharan Africa Expansion:Mobile-money integration and low-bandwidth optimization address infrastructure gaps in Kenya, Nigeria, and Ghana.
- CSRD Reporting Alignment:European faith-based NGOs with commercial arms face sustainability disclosure requirements that church management platforms can streamline through automated data collection.
Industry Challenges
- Cybersecurity Skill Scarcity:Volunteer-led administrative teams lack capacity to interpret ISO 27001 audit reports or respond to breach notification timelines under GDPR Article 33.
- Multisite Synchronization Complexity:Real-time member data consistency across distributed campuses strains database architectures and creates duplicate record risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Church Management Software Market |
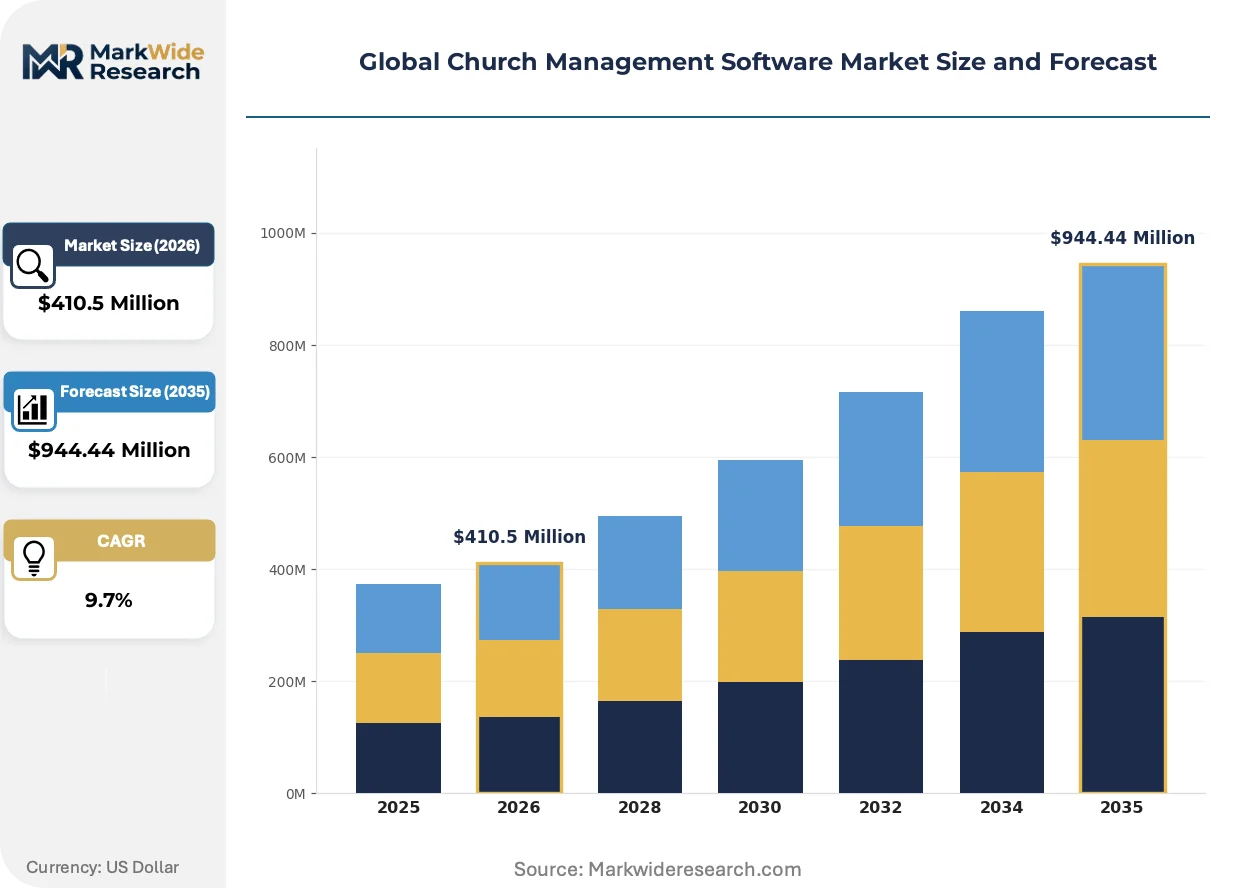
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $944.44 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile-Based Solution Type: Accounting, Attendance Tracking, Volunteer Management, Event Scheduling, Donation Management, Membership Management End User Type: Parish Churches, Community Centers, Faith-Based Organizations, Educational Ministries, Counseling Services Pricing Model: Subscription, One-Time License, Freemium, Pay Per User, Tiered Pricing |
| Companies Covered | Breeze ChMS, Tithely, Planning Center, Churchteams, Pushpay, Subsplash, Realm, Rock RMS, Churchtrac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Church Management Software Market Shifts & Advancements
Artificial intelligence and predictive analytics are embedding into core workflows, transforming how religious institutions anticipate giving patterns and personalize congregant engagement without expanding administrative headcount.
Natural language processing is automating sermon transcription, indexing, and searchable archive creation for pastoral teams. Megachurch networks in Texas and California deploy these tools at scale, compressing post-service content turnaround from 48 hours to under 90 minutes. This capability is automating previously manual media production roles and reshaping staffing models for communications departments.
The EU AI Act's risk classification framework is forcing vendors to assess whether predictive giving algorithms qualify as high-risk AI systems. Developers serving European dioceses now document training data provenance and human oversight protocols before deployment. French and German regulators are scrutinizing automated pastoral scheduling tools most aggressively, creating compliance lead times that lag North American release cycles.
Subscription fatigue among mid-sized buyers is fragmenting procurement authority away from denominational headquarters toward individual campus leaders. Self-service trials and month-to-month contracts displace traditional enterprise sales cycles in Australia and the United Kingdom. This shift concentrates vendor investment on onboarding automation and in-product education rather than field sales teams.
Global Church Management Software Market Segmentation
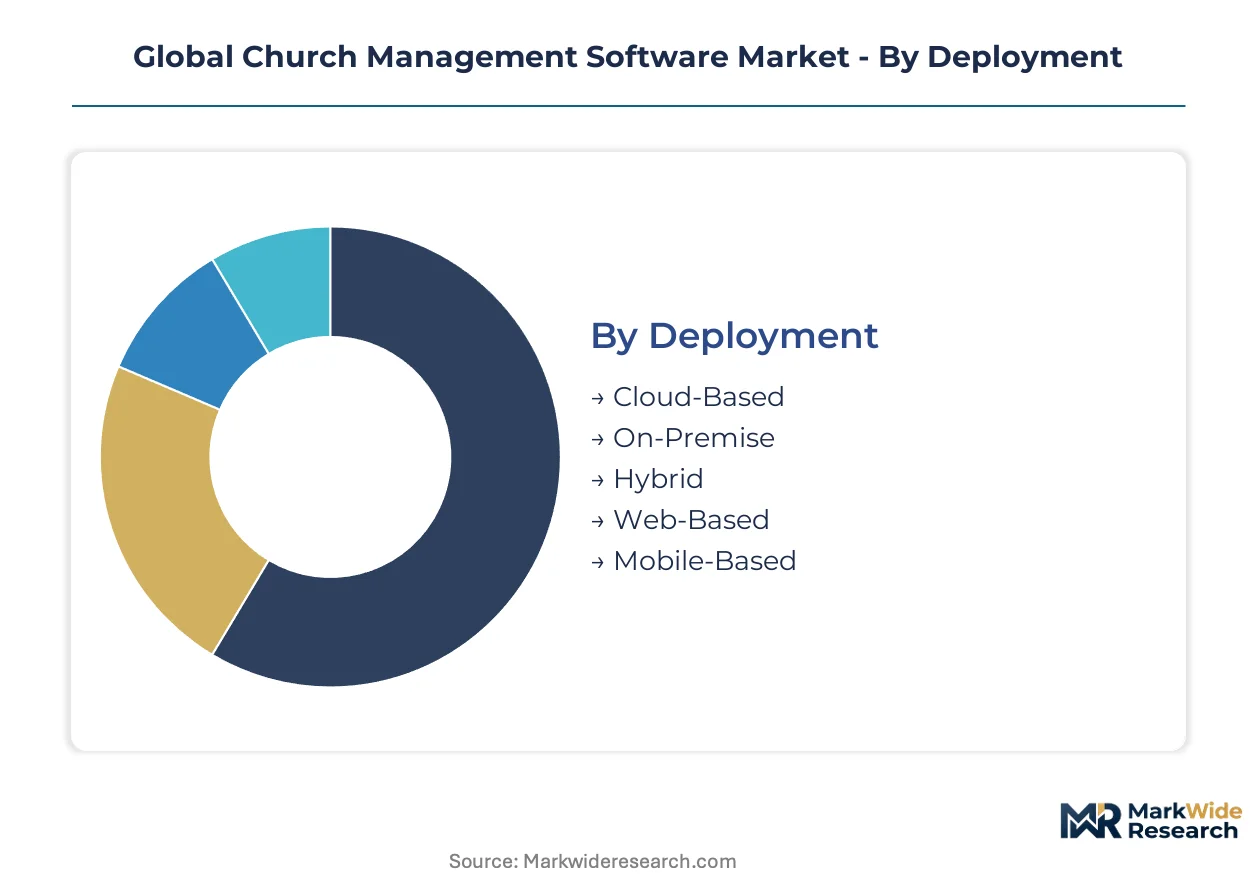
Church management software vendors architect their product portfolios around four intersecting dimensions that determine implementation complexity and recurring revenue potential. Deployment mode dictates infrastructure investment, while solution type shapes module bundling strategies. End user characteristics drive customization depth, and pricing model selection directly influences customer lifetime value calculations.
Deployment:
Customization demands intensify from fully managed cloud environments toward self-hosted architectures, creating a gradient of vendor control versus institutional autonomy.
- Cloud-Based:Multi-tenant SaaS architectures with automatic security patching eliminate server maintenance burdens for volunteer-led administrative teams. Congregations in the United States and Australia concentrate demand here, drawn by minimal upfront capital requirements and rapid deployment timelines measured in days rather than months.
- On-Premise:Self-managed installations on local servers or private data centers preserve complete data sovereignty for institutions with stringent governance requirements. German and French dioceses favor this model to satisfy GDPR Article 32 security obligations and resist cross-border transfer uncertainties under Schrems II rulings.
- Hybrid:Split architectures maintain sensitive member records on local infrastructure while pushing public-facing donation portals to cloud edge nodes. This configuration addresses bandwidth constraints in rural Australian parishes and Kenyan faith networks.
- Web-Based:Browser-accessible platforms without dedicated mobile applications reduce development overhead for vendors targeting budget-constrained community ministries.
- Mobile-Based:Native iOS and Android applications prioritize field pastoral work and youth ministry engagement over desktop administrative workflows.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as European congregations navigate compliance complexity.
Solution Type:
Functional breadth correlates directly with per-account revenue, creating tiered investment patterns across core administrative and specialized ministry tools.
- Donation Management:Recurring giving automation with ACH, credit card, and mobile wallet integration commands disproportionate R&D investment due to direct revenue impact on customer retention. Megachurch networks in Texas and California standardize on platforms with embedded payment processing to reduce donor abandonment.
- Membership Management:Centralized databases tracking contact information, family relationships, spiritual milestones, and communication preferences form the foundational layer upon which other modules depend. Parish churches across the United Kingdom and Australia treat this as the non-negotiable core purchase.
- Accounting:Fund accounting with donor-restricted gift tracking and automated IRS Form 990 preparation serves faith-based organizations with complex financial oversight requirements.
- Attendance Tracking:Check-in systems with child security protocols and demographic analytics support growth-focused congregations monitoring engagement patterns.
- Volunteer Management:Scheduling, background check integration, and role-based communication tools address labor scarcity in mid-sized parishes without dedicated staff.
- Event Scheduling:Room reservation, resource allocation, and registration workflows reduce administrative friction for multi-use facilities.
Module bundling concentrates around Membership Management and Donation Management pairings. Fastest adoption velocity appears in Volunteer Management as labor constraints intensify.
End User Type:
Organizational scale and operational complexity determine configuration depth, from standardized templates for homogeneous congregations to multisite orchestration for distributed networks.
- Parish Churches:Single-location congregations with traditional liturgical structures and established administrative routines represent the most mature buyer category with predictable renewal patterns. These institutions across Italy, Spain, and Poland prioritize stability over feature velocity.
- Faith-Based Organizations:Multisite networks and nonprofit arms of religious institutions generate the highest per-account revenue through enterprise-grade synchronization requirements and advanced reporting needs. Australian and US-based networks drive platform standardization through centralized procurement.
- Community Centers:Secular or interfaith facilities with rental income and program diversity require flexible booking modules and non-member transaction handling.
- Educational Ministries:Schools and seminaries integrate student information systems with donor alumni databases, creating hybrid functional demands.
- Counseling Services:Confidential case management with HIPAA-aligned note security and appointment scheduling serves pastoral care extensions with strict privacy obligations.
Deployment volume clusters in Parish Churches. Revenue expansion tilts toward Faith-Based Organizations with multisite complexity.
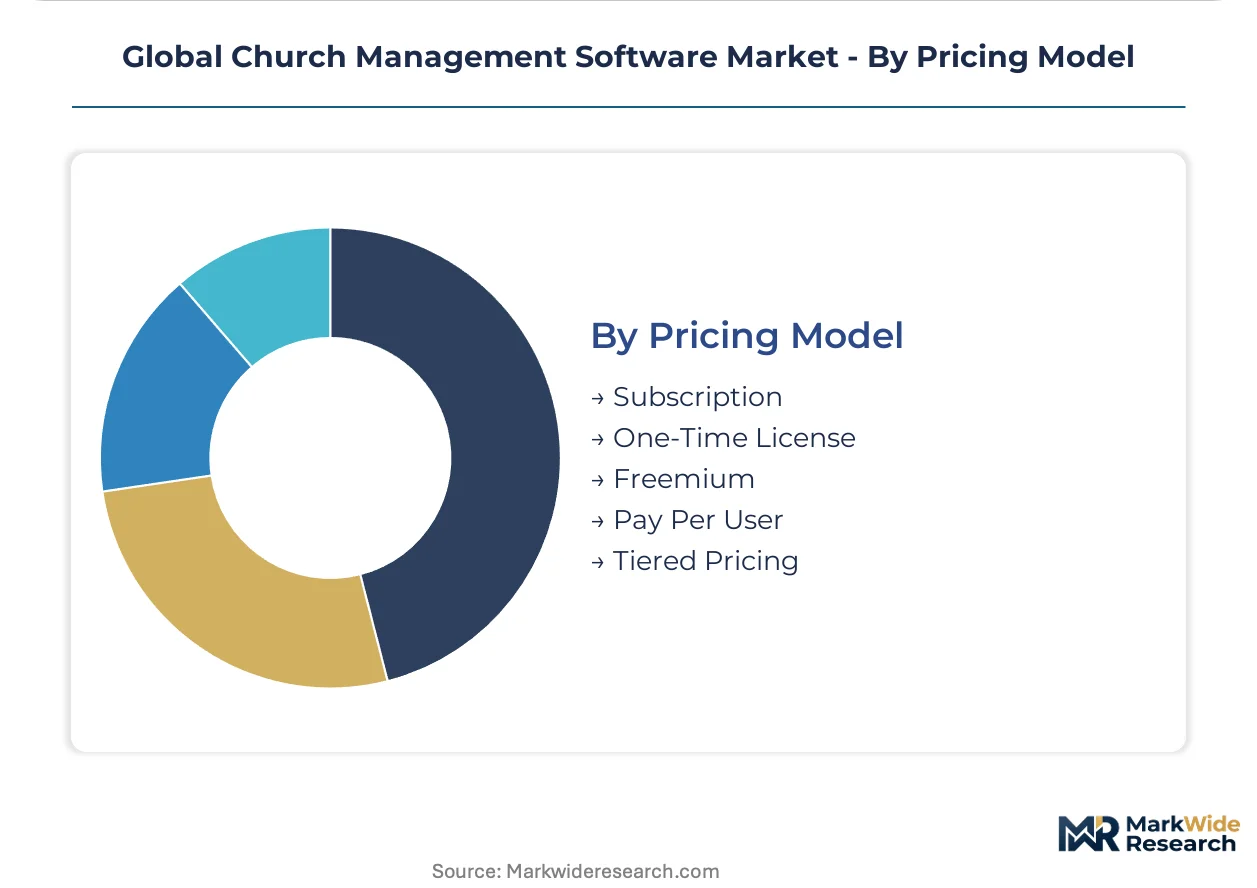
Pricing Model:
Revenue predictability versus accessibility trade-offs shape vendor strategies, with recurring structures dominating growth-oriented portfolios.
- Subscription:Monthly or annual recurring fees tied to congregation size or feature tier provide vendors with predictable revenue streams and customers with scalable cost structures. This model dominates North American and Australian markets where operational expenditure preferences prevail.
- Freemium:Core functionality at zero cost with premium module unlocks lowers barriers for startup congregations and rural ministries in Nigeria and Ghana testing digital transformation.
- One-Time License:Perpetual purchase with annual maintenance contracts persists in legacy on-premise installations and budget-capped European institutions.
- Pay Per User:Seat-based pricing aligns costs with actual administrative headcount, appealing to seasonal volunteer fluctuations.
- Tiered Pricing:Bundled packages separating basic, standard, and premium capability levels simplify procurement decisions for non-technical buyers.
Recurring revenue concentrates in Subscription structures. Fastest model experimentation occurs in Freemium approaches targeting price-sensitive expansion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Church management software originated in North American congregations seeking to digitize member records and donation tracking. The technology spread through English-speaking markets before adapting to European compliance requirements and emerging economies.
United States
Megachurch networks in Texas and California drive platform standardization through centralized procurement of multisite management tools. FCC telecommunications guidelines intersect with state-level privacy statutes to shape how vendors architect communication features and cross-border data flows. Dallas-Fort Worth and Orange County clusters host the densest concentrations of faith-based technology adopters.
Germany
GDPR Article 32 security obligations and Schrems II uncertainty push German dioceses toward on-premise or hybrid deployments with Frankfurt-based data residency. The country's national data protection regulator scrutinizes automated pastoral scheduling tools under emerging EU AI Act classifications. Bavarian and North Rhine-Westphalian parishes lead procurement volume for certified compliance solutions.
United Kingdom
Parish churches across England and Wales treat membership management as the non-negotiable core purchase, prioritizing stability over feature velocity. Post-Brexit data adequacy negotiations with Brussels create friction for cloud vendors serving multinational denominations. London and Southeast congregations concentrate demand for integrated accounting modules with donor-restricted gift tracking.
Australia
Mobile-first giving behaviors and tap-to-donate functionality expectations accelerate replacement of legacy systems in Sydney and Melbourne faith networks. The country's national data protection framework influences vendor selection criteria alongside operational expenditure preferences. Self-service trials and month-to-month contracts displace traditional enterprise sales cycles in this market.
Kenya
Mobile-money integration and low-bandwidth optimization address infrastructure gaps for faith networks in Nairobi and Mombasa. Freemium pricing models lower barriers for startup congregations testing digital transformation. Local parishes prioritize zero-code configuration tools that enable non-technical leaders to manage member databases independently.
Global Church Management Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light SaaS designers for procurement budgets across faith-based institutions. The vendor base clusters around three strategic tiers: enterprise-grade platforms serving multisite networks, mid-market solutions targeting volunteer-led administrative teams, and freemium offerings capturing price-sensitive expansion markets. Dominant competitive moves include API-first platform consolidation and geographic expansion through localized compliance configurations.
Within the mid-market tier, Breeze ChMS and Pushpay exemplify divergent specialization strategies—one through simplified onboarding for non-technical staff, the other through integrated payment processing reducing donor friction. Planning Center occupies a position representing the enterprise-grade vector with comprehensive module bundling. These three California and Washington State-based entities anchor the competitive structure visible in procurement patterns across North American and Australian congregations.
| Leading Market Players |
|---|
| Breeze ChMS |
| Tithely |
| Planning Center |
| Churchteams |
| Pushpay |
| Subsplash |
| Realm |
| Rock RMS |
| Churchtrac |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up SaaS specialists anchor vendor ownership across the Church Management Software Market, concentrating pricing discipline through recurring revenue models while compressing infrastructure costs via multi-tenant cloud architectures. Their portfolio consolidation strategies feed directly into subscription tiering that segments congregations by size and functional breadth.
Pricing Analysis
Subscription-based SaaS tiering dominates revenue capture, with three-tier pricing structure across premium, standard, and economy levels separating enterprise multisite networks from mid-sized parishes and startup congregations. Price differentiation rests on congregation size thresholds and module bundling depth, with integrated payment processing commanding sustained premiums. Cost compression in entry tiers is intensifying because freemium entrants from Sub-Saharan Africa force incumbent repricing. Megachurch networks in Texas and California exhibit lowest price sensitivity, while volunteer-led parishes in Kenya and Nigeria face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements for data center infrastructure push vendors to qualify multiple cloud providers, with primary compute capacity drawing from United States, Ireland, and Germany to satisfy divergent residency mandates. Raw material dependencies center on semiconductor components for edge servers, payment processing APIs, and mobile SDKs. Single-source vulnerability concentrates in payment gateway integrations where Stripe and PayPal alternatives lack feature parity. Distribution runs through direct digital sales channels with self-service onboarding displacing traditional enterprise field teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Church Management Software Market reads as a late-cycle quality story, with procurement authority fragmenting toward individual campus leaders who prioritize zero-code configuration over bundled enterprise suites. Demand is shifting toward premium specifications around GDPR-aligned data residency and AI-assisted sermon workflows.
For Market Incumbents: Deploy API-first platform consolidation to neutralize modular pricing fatigue threatening renewal rates. Incumbents should deepen payment processing integration to lock donor transaction data, while accelerating Frankfurt and Dublin data center certifications to preempt Schrems II compliance gaps. Volunteer administrator dependency creates stickiness for simplified onboarding, but freemium entrants from Kenya and Nigeria threaten price floors in expansion markets.
For New Entrants and Emerging Players: Enter via mobile-money integration targeting Nairobi and Lagos faith networks where infrastructure gaps exclude incumbent feature sets. The most penetrable segment comprises mid-sized parishes with zero dedicated IT staff seeking month-to-month contracts. A direct-to-congregation digital sales motion with in-product education replaces expensive field teams.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with certified EU data residency and stagnant North American growth. Long-term viability hinges on AI feature monetization and Sub-Saharan Africa expansion execution. The signal to watch is EDPB adequacy decision timing affecting US-EU data flow architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Sermon Workflow Launch | Automated transcription and multilingual translation unlock accessibility compliance for aging congregations in Bavarian parishes. |
| Mobile-Money Platform Integration | M-Pesa and Airtel Money connectivity addresses infrastructure gaps in Kenyan and Nigerian faith networks. |
| GDPR Data Residency Certification | Frankfurt and Dublin server deployments satisfy Schrems II uncertainty for German dioceses. |
| Zero-Code Configuration Rollout | Volunteer-led administrative teams in Australian parishes manage member databases without IT staff. |
| Freemium Market Entry | Core functionality at zero cost lowers barriers for startup congregations testing digital transformation in Ghana. |
Research Methodology
Bottom-up parish and faith-based organization modeling reconciled against top-down cloud vendor capacity tracking forms the analytical core of this study. Primary interviews with church administrative directors, denominational IT procurement officers, volunteer ministry coordinators, and SaaS platform product managers combined with secondary validation from SEC filings of publicly traded vendors, hyperscaler data center expansion disclosures, and GDPR enforcement action databases. Trade association membership records and cloud infrastructure capex announcements anchored supply-side triangulation.
Historical trendline analysis across deployment mode transitions and pricing model evolution informed projection frameworks. Segmentation dimensions modeled include cloud versus on-premise architecture, congregation size tier, functional module bundling, and regional regulatory cluster. CAGRs derived from installed base growth rates and replacement cycle compression across the analysis window. AI feature adoption curves and mobile-money penetration rates in Sub-Saharan Africa served as industry-specific forecast inputs.
Inputs from vendor financial disclosures and denominational procurement surveys were available through the study window; gaps in private mid-market SaaS company metrics introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding GDPR enforcement consistency and EU AI Act classification timelines. Deviation in EDPB adequacy decisions or Schrems II ruling evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Retail Core Banking Solution Market
Software & Services
Data Visualization Software Market
Software & Services
Automation Test Software Market
Software & Services
App Creation Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Online Lottery Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Taxi Booking Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Global Automotive Software Market
Software & Services
Commerce As a Service (Caas) Market