
 Chunky Sneaker Market | 2026-2036
Chunky Sneaker Market Size, Share, and Industry Trends Forecast 2026-2036
Chunky Sneaker Market Outlook
Direct-to-consumer digital channels is reshaping how chunky sneaker brands reach buyers, bypassing traditional wholesale gatekeepers. Nike leverages its SNKRS app ecosystem to sustain exclusive drop economics. Balenciaga anchors its luxury positioning through controlled scarcity and editorial placement. Puma competes via accessible price architecture without diluting its sportswear heritage.
Chunky sneakers are footwear distinguished by exaggerated midsole platforms, layered upper constructions, and visible cushioning systems typically measuring 40-60mm in heel stack height, designed for aesthetic statement and urban casual wear. Lifestyle product types dominate volume as fashion-forward consumers prioritize silhouette over performance function. Synthetic materials lead production scale due to cost efficiency and colorway flexibility, though leather variants command higher margin pools in the premium tier. The unisex end-user segment is expanding fastest as gender-neutral styling dissolves traditional demographic boundaries in footwear retail.
REACH chemical restrictions in Europe, California's Proposition 65 disclosure mandates, and China's GB standards for footwear safety collectively govern material composition and labeling requirements across major supply bases. These frameworks push manufacturers toward water-based adhesives and recycled rubber compounds to maintain market access. Stakeholders must monitor evolving substance restriction lists and regional enforcement intensity to preempt compliance-driven cost escalations.
Market Dynamics
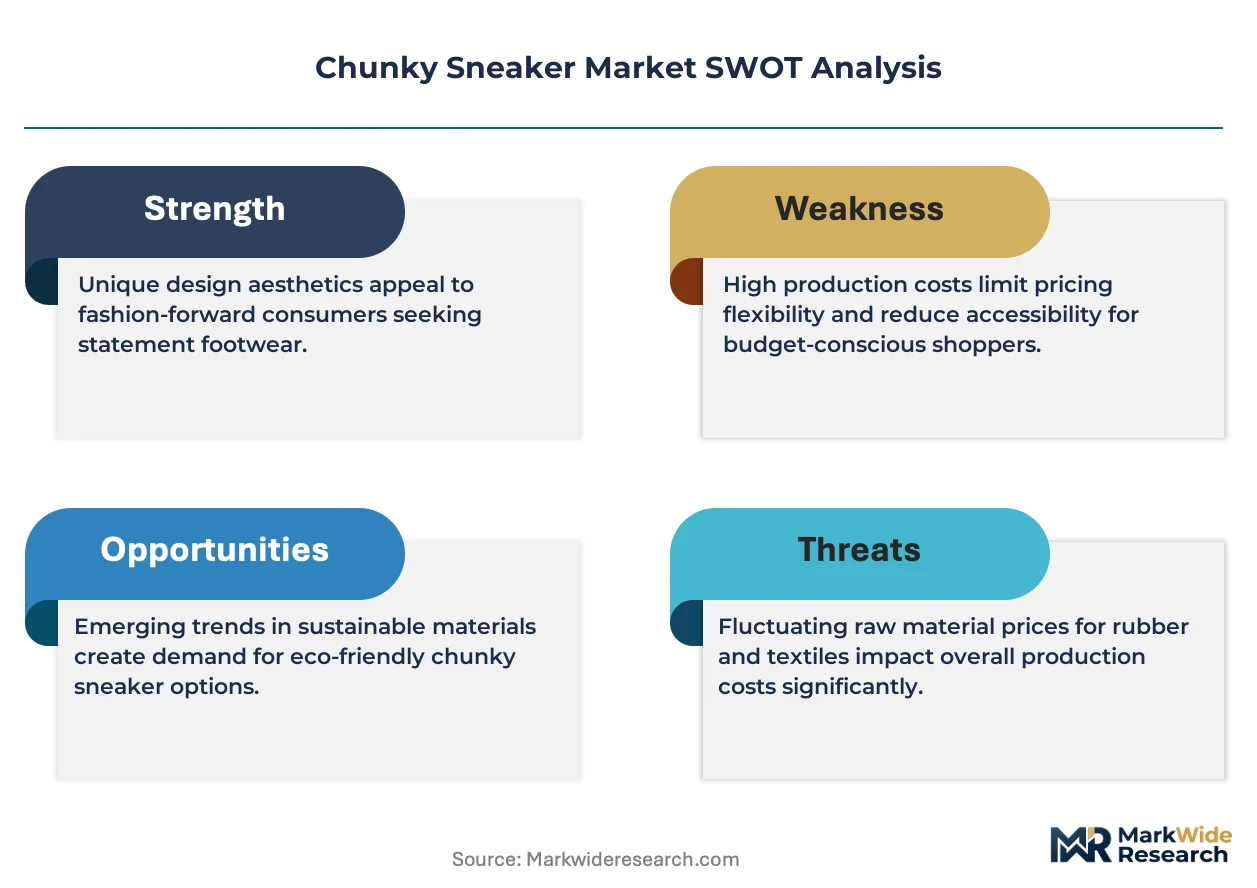
EU REACH chemical restrictions are forcing footwear manufacturers to reformulate adhesives and rubber compounds, creating a compliance-driven restructuring of material sourcing across the chunky sneaker supply base.
Growth Catalysts
- Seoul metropolitan fashion cluster:South Korea's concentrated streetwear culture generates disproportionate demand velocity for statement silhouettes, with local boutiques accelerating regional trend diffusion.
- REACH substance restriction lists:Tightening ECHA enforcement on phthalates and heavy metals is pushing early-adopter brands toward bio-based polyurethane midsoles that command premium positioning.
- Water-based adhesive migration:Manufacturing process shifts away from solvent-based bonding systems reduce volatile organic compound exposure while opening access to California's Proposition 65-compliant retail channels.
Market Restraints
- Petroleum-derived synthetic price volatility:EVA and TPU pellet costs fluctuate with crude oil indices, compressing margin predictability for volume-tier producers dependent on foam midsole platforms.
- Fujian province supply concentration:Over 60% of molded sole production clusters in China's southeastern manufacturing belt, exposing brands to single-point disruption from regional power rationing or logistics bottlenecks.
- Performance-function substitution:Technical running shoes with visible cushioning systems compete for the same aesthetic-conscious consumer wallet, fragmenting discretionary footwear spend.
Strategic Opportunities
- India's urban youth demographic:Metro cities Mumbai, Delhi, and Bangalore show nascent streetwear adoption with limited domestic chunky sneaker availability, creating first-mover whitespace for localized sizing and colorway development.
- Recycled rubber compound mandates:EU Green Deal circular economy requirements will favor manufacturers with established post-consumer waste integration capabilities, locking in preferred supplier status.
- Direct-to-consumer resale platform convergence:Authentication-enabled secondary marketplaces are capturing margin pools previously extracted by wholesale distributors, enabling brands to monetize scarcity economics directly.
Industry Challenges
- Footwear toxicologist talent scarcity:Specialized chemists capable of navigating ECHA SVHC candidate list updates and California OEHHA safe harbor calculations command premium compensation, constraining mid-tier manufacturer compliance capacity.
- Multi-jurisdiction labeling complexity:Simultaneous adherence to EU textile labeling, US FTC leather disclosure, and China GB 5296.5 standards requires dedicated regulatory operations infrastructure that smaller brands struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chunky Sneaker Market |
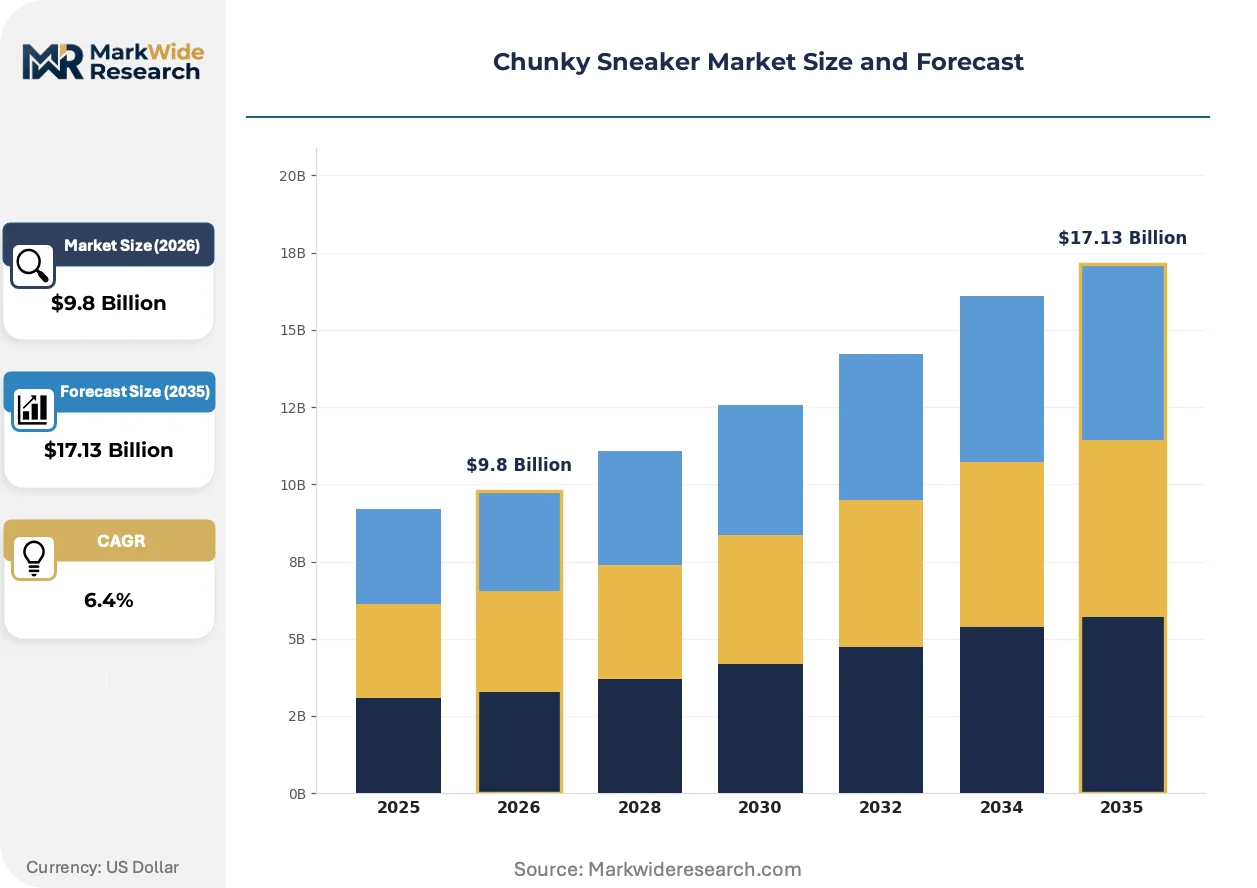
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running, Lifestyle, Casual, Sports End User: Men, Women, Unisex, Children Material: Leather, Synthetic, Mesh, Canvas Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Puma, Gucci, Adidas, Valentino, Louis Vuitton, Nike, Vans, Yeezy, Balenciaga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chunky Sneaker Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to reshape how chunky sneakers are constructed, distributed, and consumed across generational cohorts.
Bio-based polyurethane foam formulations are migrating from petroleum-derived predecessors as the primary midsole cushioning technology. Gen Z consumers in Seoul, Tokyo, and Los Angeles demonstrate measurable willingness to absorb 15-25% price premiums for plant-derived alternatives. This migration from conventional EVA is compressing the innovation cycle for heritage sportswear brands that lack captive biopolymer R&D pipelines.
California's Proposition 65 enforcement against unlabeled phthalate exposure is tightening disclosure requirements for footwear sold through US retail channels. The state's Office of Environmental Health Hazard Assessment has expanded warning obligations to include BPA in synthetic uppers, forcing brands to reformulate or re-label inventory bound for the US West Coast. Premium-tier manufacturers with established supply chain transparency systems are capturing shelf space from competitors facing compliance delays.
Secondary marketplace authentication is displacing traditional wholesale as the primary scarcity mechanism for limited releases. Resale platforms with embedded NFC verification chips are capturing consumer trust previously held by authorized retailers, compressing the primary-to-secondary price arbitrage window. This channel shift is most visible in South Korea's Seoul metropolitan area, where digital-native buyers now reference resale premiums before primary purchase decisions.
Chunky Sneaker Market Segmentation
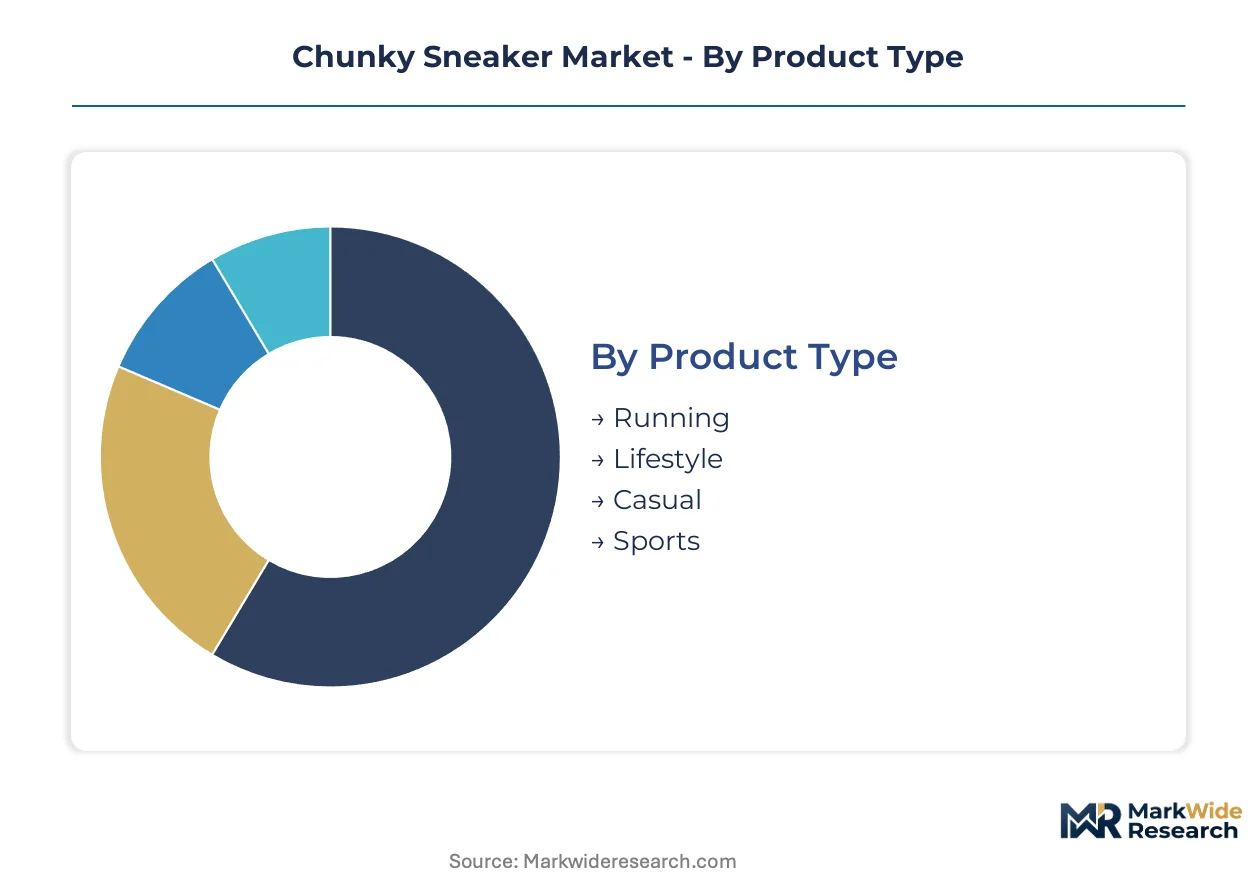
Chunky sneaker segmentation reveals how aesthetic function, material composition, and price architecture fragment demand across distinct consumer cohorts. Manufacturers must calibrate supply chains to serve divergent specifications—from petroleum-derived foam platforms to plant-based alternatives—while navigating tightening chemical compliance frameworks.
Product Type:
Application intent separates volume-oriented casual wear from performance-adjacent positioning and pure fashion statement.
- Lifestyle:Designed for aesthetic statement with exaggerated 40-60mm heel stacks and layered uppers, prioritizing silhouette over athletic function. Seoul's streetwear cluster drives disproportionate velocity for statement drops, with local boutiques accelerating regional diffusion through exclusive colorway partnerships.
- Casual:Balances visual bulk with everyday wearability through simplified upper constructions and moderate platform heights. European REACH compliance costs favor established brands with reformulated adhesive systems, squeezing smaller entrants dependent on solvent-based bonding.
- Running:Incorporates visible cushioning systems borrowed from technical footwear, competing for aesthetic-conscious consumers who fragment spend across performance and fashion categories.
- Sports:Retains heritage athletic branding with court-inspired silhouettes adapted for urban casual contexts rather than competitive use.
Lifestyle commands the established base. The steepest expansion runs through Casual.
End User:
Customer type boundaries dissolve as gender-neutral styling reconfigures traditional demographic targeting.
- Unisex:Fastest-expanding segment as Seoul, Tokyo, and Los Angeles consumers absorb 15-25% premiums for plant-derived midsole alternatives. Digital-native buyers reference resale premiums before primary purchase decisions, compressing the arbitrage window between release and secondary market.
- Women:Historically anchored demand through fashion-forward silhouette adoption, now facing share pressure from gender-neutral alternatives.
- Men:Streetwear origin segment retaining volume concentration in heritage sportswear brand portfolios.
- Children:Smallest addressable pool due to sizing limitations and parental preference for growth-accommodating footwear economics.
Women retains the volume anchor. Unisex climbs the fastest as styling conventions shift.
Material:
Cost efficiency and regulatory pressure reshape composition choices across price tiers.
- Synthetic:Petroleum-derived polyurethane and EVA foams dominate production scale through colorway flexibility and unit cost advantages. Crude oil price volatility compresses margin predictability for volume-tier producers dependent on foam midsole platforms.
- Leather:Commands premium positioning with higher margin pools, though California Proposition 65 disclosure mandates on BPA and phthalates force reformulation or re-labeling for US West Coast distribution.
- Mesh:Lightweight upper construction reducing material intensity while maintaining visual bulk through structural layering.
- Canvas:Lowest unit cost base with limited premium applicability, concentrated in accessible price architecture.
Synthetic holds the volume foundation. Bio-based alternatives within the synthetic category gain share fastest as ECHA enforcement tightens.
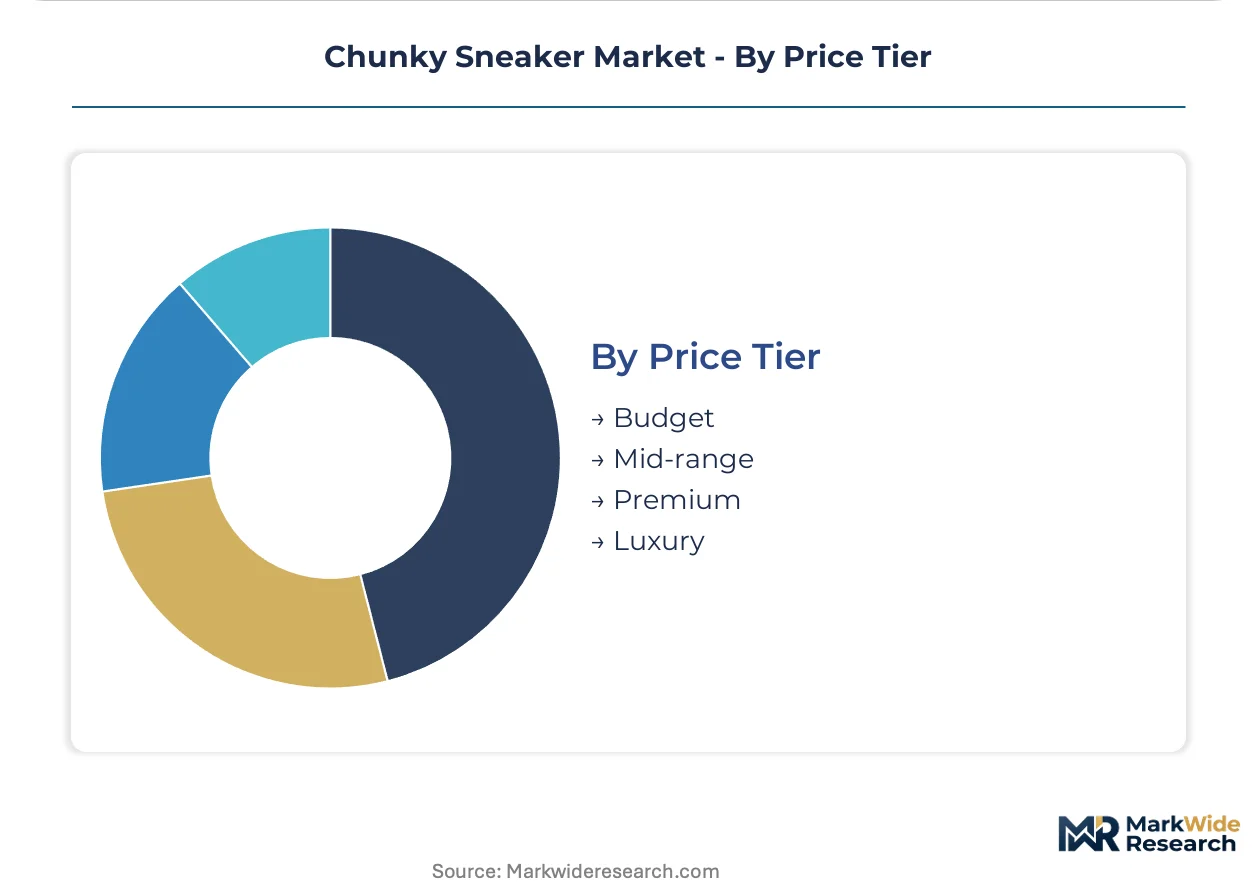
Price Tier:
Cost architecture determines distribution channel access and scarcity mechanics deployment.
- Premium:Controlled scarcity through direct-to-consumer drops and editorial placement, with established supply chain transparency systems capturing shelf space from compliance-delayed competitors.
- Mid-range:Accessible price points without heritage dilution, competing through sportswear authenticity and colorway velocity rather than exclusivity economics.
- Luxury:Highest positioning with limited production runs, authentication-enabled resale platforms capturing margin pools previously extracted by wholesale distributors.
- Budget:Volume-tier production exposed to Fujian province supply concentration risks, with over 60% of molded sole production clustering in China's southeastern manufacturing belt.
Mid-range anchors unit volume. Premium gains share fastest as authentication technology enables direct scarcity monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's streetwear distribution network, feeding Seoul's metropolitan fashion cluster with rapid turnaround logistics. Rotterdam's Maasvlakte container terminals enable EU REACH-compliant footwear to penetrate continental European retail channels efficiently.
United States
California's Proposition 65 enforcement drives BPA disclosure mandates for synthetic uppers bound for Los Angeles and San Francisco retail corridors. The state's Office of Environmental Health Hazard Assessment maintains strict warning obligations. West Coast distribution centers now demand reformulated inventory before shelf placement.
South Korea
Seoul's concentrated streetwear culture generates disproportionate velocity for statement silhouettes through exclusive boutique partnerships. The Korea Customs Service enforces strict import documentation for footwear materials. Local designers in Hongdae and Gangnam districts accelerate regional trend diffusion via limited colorway drops.
Germany
ECHA's REACH substance restriction lists push manufacturers toward bio-based polyurethane midsoles for EU market access. The Federal Institute for Risk Assessment monitors phthalate and heavy metal thresholds. Bavarian chemical suppliers near Munich develop compliant adhesive alternatives for premium footwear brands.
China
Fujian province hosts over sixty percent of molded sole production, clustering manufacturing in the southeastern belt. GB standards for footwear safety govern domestic and export compliance. Xiamen and Quanzhou factories face power rationing risks that expose brands to single-point disruption.
India
Mumbai, Delhi, and Bangalore demonstrate nascent streetwear adoption with limited domestic chunky sneaker availability. The Bureau of Indian Standards enforces labeling requirements for imported footwear. Local manufacturing capacity in Tamil Nadu and Gujarat remains underdeveloped for fashion-forward silhouettes.
Chunky Sneaker Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with material science and molding capabilities. The chunky sneaker market consolidates around heritage sportswear houses, luxury fashion conglomerates, and independent streetwear labels. Three archetypes dominate: scarcity-driven premium houses, accessible heritage brands, and celebrity-fronted independent ventures. Competitive moves center on direct-to-consumer app ecosystems and authentication-enabled resale platform partnerships.
Within the heritage sportswear tier, Adidas, Nike, and Puma represent distinct positioning vectors. Adidas anchors European sportswear authenticity with terrace culture lineage. Nike exemplifies scarcity economics through digital drop infrastructure. Puma occupies the accessible price architecture without heritage dilution. These three entities demonstrate how legacy athletic brands have bifurcated between premium exclusivity and volume accessibility.
| Leading Market Players |
|---|
| Puma |
| Gucci |
| Adidas |
| Valentino |
| Louis Vuitton |
| Nike |
| Vans |
| Yeezy |
| Balenciaga |
| Others |
Value Chain & Pricing Dynamics
Fujian province power rationing risk determines both pricing tier spreads and supply chain shape in the chunky sneaker market. Petroleum-derived synthetic price volatility compresses margin predictability for volume-tier producers while premium brands absorb bio-based polyurethane premiums through controlled scarcity mechanics.
Pricing Analysis
Volume-discount tiering structures separate luxury positioning from accessible heritage and budget tiers through scarcity mechanics and brand equity. Price differentiation hinges on certification compliance with EU REACH substance restrictions and California Proposition 65 disclosure mandates. Cost compression in the budget tier is intensifying because crude oil index fluctuations feed directly into EVA and TPU pellet costs. Streetwear enthusiasts in Seoul demonstrate the lowest price sensitivity, absorbing plant-derived midsole premiums, while value-conscious casual buyers in emerging markets resist price escalation.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become critical liquidity tools for mid-tier manufacturers navigating reformulation costs. Production draws from China, Vietnam, and Indonesia, with molded sole manufacturing concentrated in Fujian province. Raw material dependencies center on petroleum-derived polyurethane, recycled rubber compounds, and water-based adhesive systems. Single-source vulnerability from southeastern China power rationing exposes brands to fulfillment disruptions. Distribution runs through direct-to-consumer app ecosystems and authentication-enabled resale platforms that capture margin pools previously extracted by wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chunky sneaker market sits in early-cycle expansion as Gen Z streetwear adoption accelerates across Seoul, Tokyo, and Los Angeles metropolitan clusters. Penetration remains shallow in India's urban youth demographic, creating runway for localized entrants.
For Market Incumbents: Build regulatory compliance moats through captive toxicologist talent and multi-jurisdiction labeling infrastructure. Invest in backward integration into bio-based polyurethane R&D pipelines to compress innovation cycles for heritage brands lacking captive biopolymer capabilities. Defend against celebrity-fronted independent ventures by tightening direct-to-consumer app ecosystem control and exclusive boutique partnerships in Seoul's Hongdae and Gangnam districts.
For New Entrants and Emerging Players: India's metro cities Mumbai, Delhi, and Bangalore represent the most penetrable entry point given nascent streetwear adoption and limited domestic chunky sneaker availability. Localized sizing development and colorway partnerships with regional boutiques offer first-mover positioning before heritage brands establish supply chain presence. Deploy digital-native resale platform convergence as the primary go-to-market angle, leveraging authentication-enabled secondary marketplaces to build consumer trust without wholesale distribution investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with material science capabilities and direct-to-consumer infrastructure. Long-term viability across the five-to-ten year window hinges on post-consumer waste integration capabilities that lock in preferred supplier status under EU Green Deal circular economy requirements. Watch ECHA SVHC candidate list expansion velocity as the primary inflection indicator for compliance-driven cost escalations that reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Nike's SNKRS app demonstrates how exclusive drop economics bypass wholesale gatekeepers. |
| Bio-Based Material Transition | REACH substance restriction lists favor early adopters with plant-derived polyurethane midsole formulations. |
| Authentication Technology Integration | NFC-enabled resale platforms in Seoul compress primary-to-secondary arbitrage windows for limited releases. |
| Regional Manufacturing Footprint | Tamil Nadu and Gujarat capacity addresses India's nascent demand without Fujian concentration risk. |
| Sustainability Repositioning | Recycled rubber compound mandates under EU Green Deal lock in preferred supplier status for compliant manufacturers. |
Study Parameters
A spread of perspectives from brand managers at heritage sportswear houses, boutique buyers in Seoul's streetwear cluster, footwear toxicologists navigating ECHA compliance, and supply chain directors at molded sole manufacturers converged on the working assumptions. Primary interview insights combined with secondary validation from customs records, SEC footwear segment filings, and Korea Customs Service import documentation. Bottom-up sizing from individual brand drop calendars and top-down triangulation from regional retail audit data anchored volume estimates.
Demand-supply-balance framing across the analysis window modeled price elasticity for plant-derived alternatives against petroleum-derived synthetics. Segmentation dimensions included product type, end-user demographic, material composition, and price tier architecture. CAGRs derived from trend extrapolation of Seoul metropolitan fashion cluster velocity and regulatory compliance cost trajectories. Forecast inputs incorporated Gen Z willingness-to-pay premiums for bio-based materials and authentication-enabled resale platform penetration rates.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, ECHA enforcement intensity, or regional power rationing severity would shift the trajectory. Forecasts reflect documented assumptions about streetwear adoption curves and regulatory implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
UGG Boots Market
Footwear
High Heels Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Women's Luxury Footwear Market
Footwear
Premium Shoes Market
Footwear
Hiking Footwear Market
Footwear
Winter Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Driving Footwear Market
Footwear
Shoe Insoles Market
Footwear
E-Commerce Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Sneaker Boots Market
Footwear
Sneakers Market
Footwear
Leather Sneakers Market
Footwear
Indian Footwear Market