
 Footwear Manufacturing Machinery Market | 2026-2036
Footwear Manufacturing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Footwear Manufacturing Machinery Market Intelligence
Digital twin integration is reconfiguring how footwear factories simulate production workflows before physical deployment. Comelz S.p.A leverages advanced CAD-CAM nesting algorithms to optimize leather cutting yields for luxury brands. Atom S.p.A anchors its position through precision die-cutting systems that serve tanneries across Southern Europe. Dongguan Kingstone Shoe-making Machinery Co. Ltd. dominates hydraulic sole pressing equipment for mass-market producers in East Asia.
Footwear manufacturing machinery encompasses electromechanical systems engineered to cut, stitch, last, mold, and finish shoe components with tolerances typically ranging from 0.1 to 0.5 millimeters depending on material type. These systems execute forming, joining, and surface treatment operations that transform raw hides, synthetics, and rubber into finished upper and sole assemblies for commercial distribution. Injection molding machines command the largest installed base among product types due to polyurethane and thermoplastic rubber sole volumes, while automation systems represent the fastest-expanding technology segment as labor costs climb in traditional manufacturing centers. Cutting machines retain mature margins in developed markets where material waste reduction drives replacement cycles.
EU REACH restrictions on chromium-tanned leather chemicals and China's GB standards for industrial machinery safety compel equipment upgrades across export-oriented factories. The EPA's volatile organic compound limits for adhesive applications in US-based production further shape solvent-free bonding technology demand. Stakeholders must monitor how dual carbon goals in Asia and the EU Green Deal's embodied carbon tracking will recalibrate energy efficiency requirements for next-generation machinery procurement.
Market Dynamics
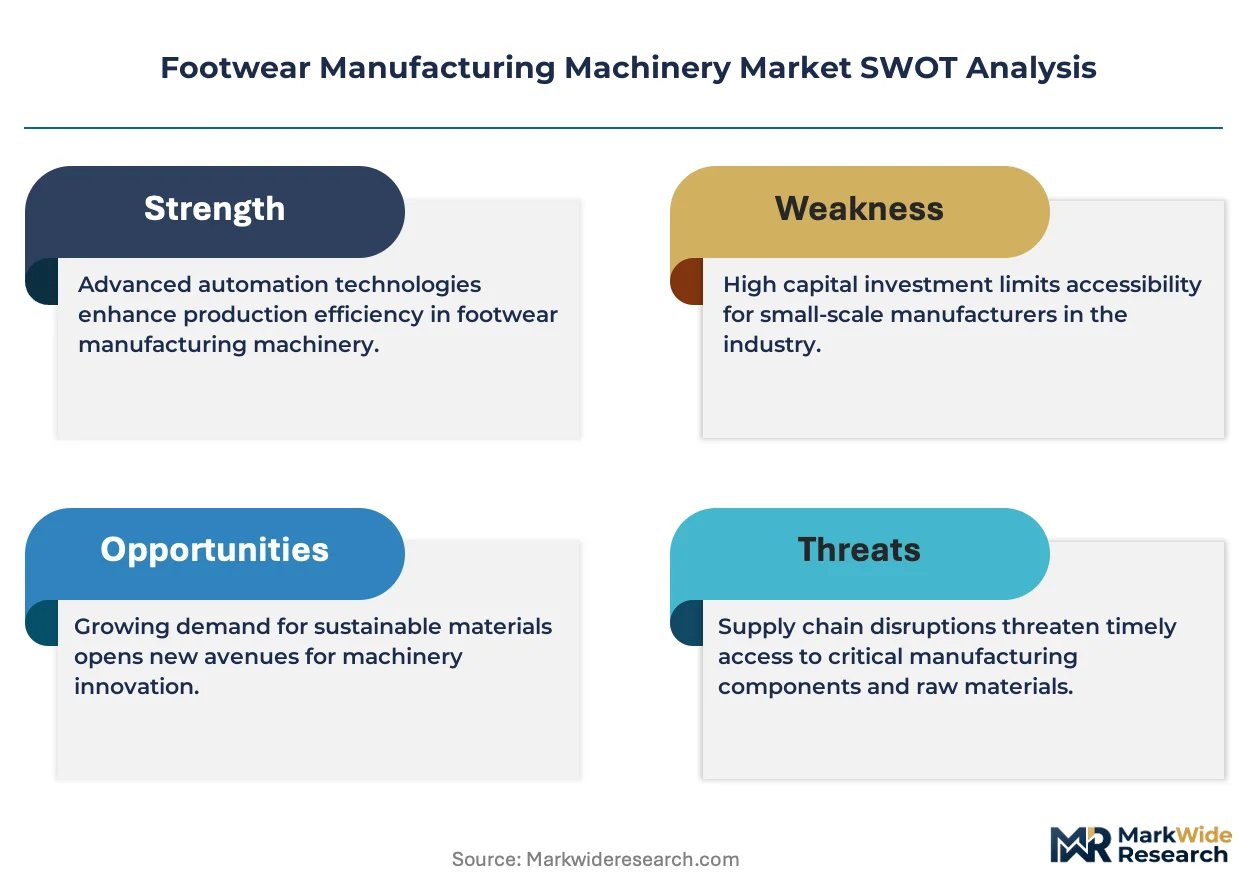
EU REACH restrictions on chromium-tanned leather chemicals and China's GB standards for industrial machinery safety are compelling factory owners to retire legacy equipment ahead of depreciation schedules, compressing replacement cycles from seven years to four in export-oriented facilities.
Growth Catalysts
- EU-Vietnam Free Trade Agreement:Athletic footwear exporters in Vietnam are expanding automated stitching lines to meet rules-of-origin quotas, driving machinery orders from Guangdong province suppliers.
- Digital Twin Simulation:Footwear factories are deploying virtual production workflows to test line configurations before physical installation, reducing commissioning time and material waste during ramp-up.
- REACH Compliance Deadlines:European tanneries face phased restrictions on hexavalent chromium processing, redirecting capital toward certified cutting and finishing systems that eliminate hazardous chemical exposure.
Market Restraints
- Steel and Servo Motor Cost Volatility:Precision cutting machines depend on specialty steel alloys and high-torque servo drives, with input price swings compressing OEM margins during contract negotiations.
- Guangdong Supply Concentration:Hydraulic sole pressing equipment production clusters in Dongguan, creating single-point vulnerability for Southeast Asian contract manufacturers dependent on just-in-time spare parts.
- Polyurethane Formulation Substitution:Bio-based midsole foams from algae and agricultural waste streams threaten demand for traditional injection molding machines optimized for petroleum-derived TPU.
Strategic Opportunities
- India PLI Scheme for Footwear:Production-linked incentives for large-scale manufacturing are attracting machinery vendors to establish service depots in Tamil Nadu and Uttar Pradesh industrial corridors.
- CE Marking Automation:Modular machinery platforms with pre-certified safety subsystems are reducing compliance timelines for mid-sized European tanneries seeking rapid equipment upgrades.
- Robotics-Cobotics Convergence:Collaborative robots with force-limiting controls are enabling small-batch luxury producers to automate lasting operations previously reserved for mass-market lines.
Industry Challenges
- Mechatronics Technician Scarcity:Factories in Vietnam and Indonesia struggle to recruit engineers capable of calibrating servo-driven stitching heads and maintaining predictive maintenance algorithms.
- Legacy PLC Integration:Brownfield installations require protocol bridges to connect 1990s-era programmable logic controllers with modern IoT-enabled monitoring systems, extending deployment timelines.
- Dual Carbon Certification:China's provincial energy audits and the EU Green Deal's embodied carbon tracking demand parallel documentation systems, multiplying compliance overhead for multinational equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Footwear Manufacturing Machinery Market |
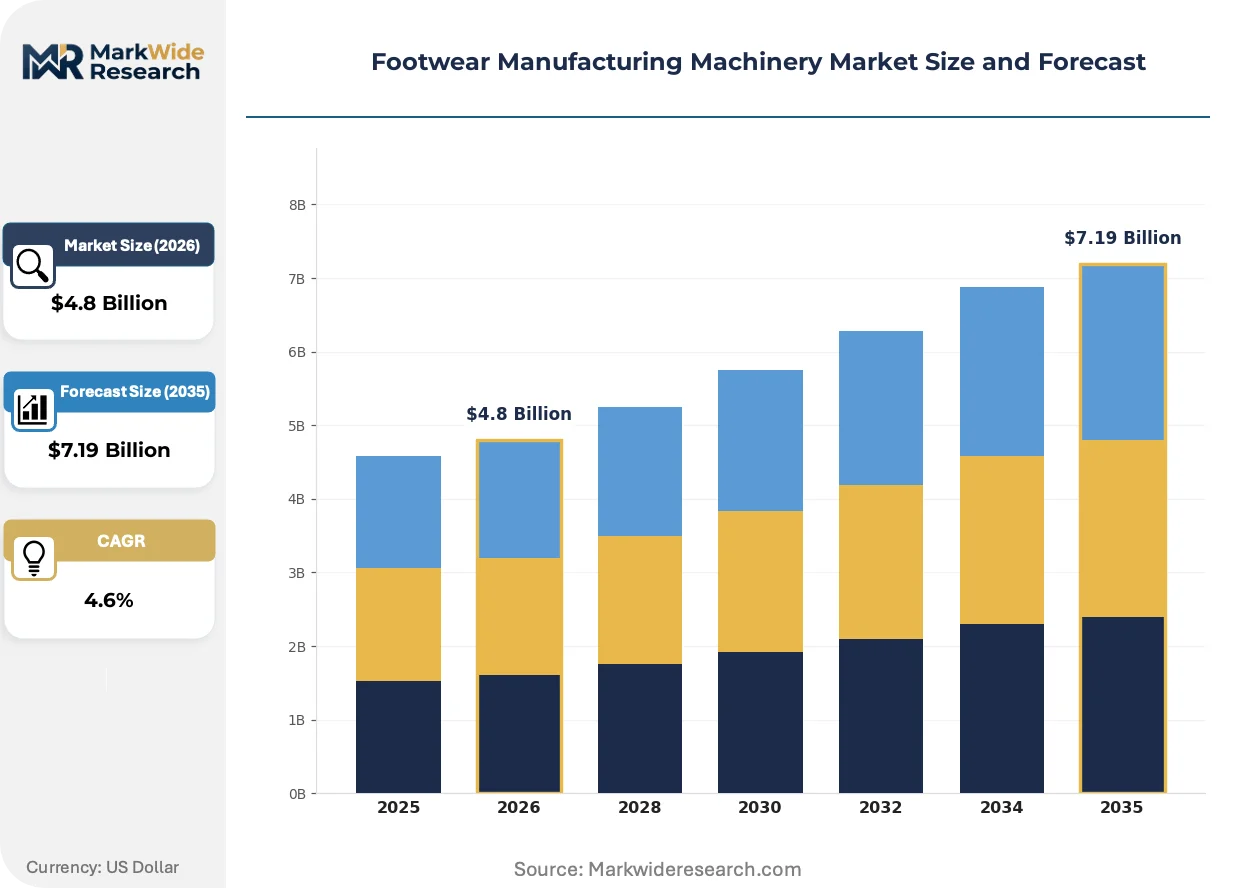
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sole Pressing Machines, Stitching Equipment, Cutting Machines, Lasting Machines, Injection Molding Machines Technology: Automation Systems, Computer Numerical Control, Hydraulic, Pneumatic, Mechanical Application: Sports Footwear, Casual Footwear, Formal Footwear, Safety Footwear, Orthopedic Footwear End User: Footwear Manufacturers, Contract Manufacturers, OEMs, Aftermarket Suppliers, Design Studios |
| Companies Covered | ALC Tecnologie Adesive S.r.l., Orisol Taiwan Ltd., Comelz S.p.A, True Ten Industrial Co. Ltd., Kou Yi Iron Works Co. Ltd., Atom S.p.A, Brustia Alfameccanica S.r.l., Gusbi SpA, Dongguan Kingstone Shoe-making Machinery Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Footwear Manufacturing Machinery Market Strategic Shifts & Innovations
Laser-guided leather nesting and AI-driven defect detection are compressing material yields below historical baselines while regulatory pressure on chemical processing accelerates solvent-free bonding technology adoption.
Ultrasonic welding systems for synthetic upper assembly are rendering obsolete traditional needle-and-thread stitching stations in high-volume athletic footwear plants. Nike and Adidas contract manufacturers in Vietnam and Indonesia are retrofitting existing lines at a pace that suggests majority adoption within three production cycles. The structural consequence is a collapse in demand for multi-needle post-bed machines previously considered standard equipment.
China's GB standards for industrial machinery safety mandate emergency stop response times under 500 milliseconds and force-limited collaborative operation zones. MIIT inspectors are conducting unannounced factory audits, rejecting export licenses for non-compliant equipment. Domestic machinery vendors in Zhejiang and Guangdong are redesigning control architectures to satisfy these thresholds, while European OEMs face recertification costs to maintain access.
After-sales service unbundling is separating hardware procurement from maintenance contracts in Southeast Asian markets. Contract manufacturers in Vietnam and Cambodia now source spare parts through independent distributors rather than captive OEM channels, compressing service margins and accelerating third-party retrofit markets for legacy Italian and German equipment.
Footwear Manufacturing Machinery Market Segmentation
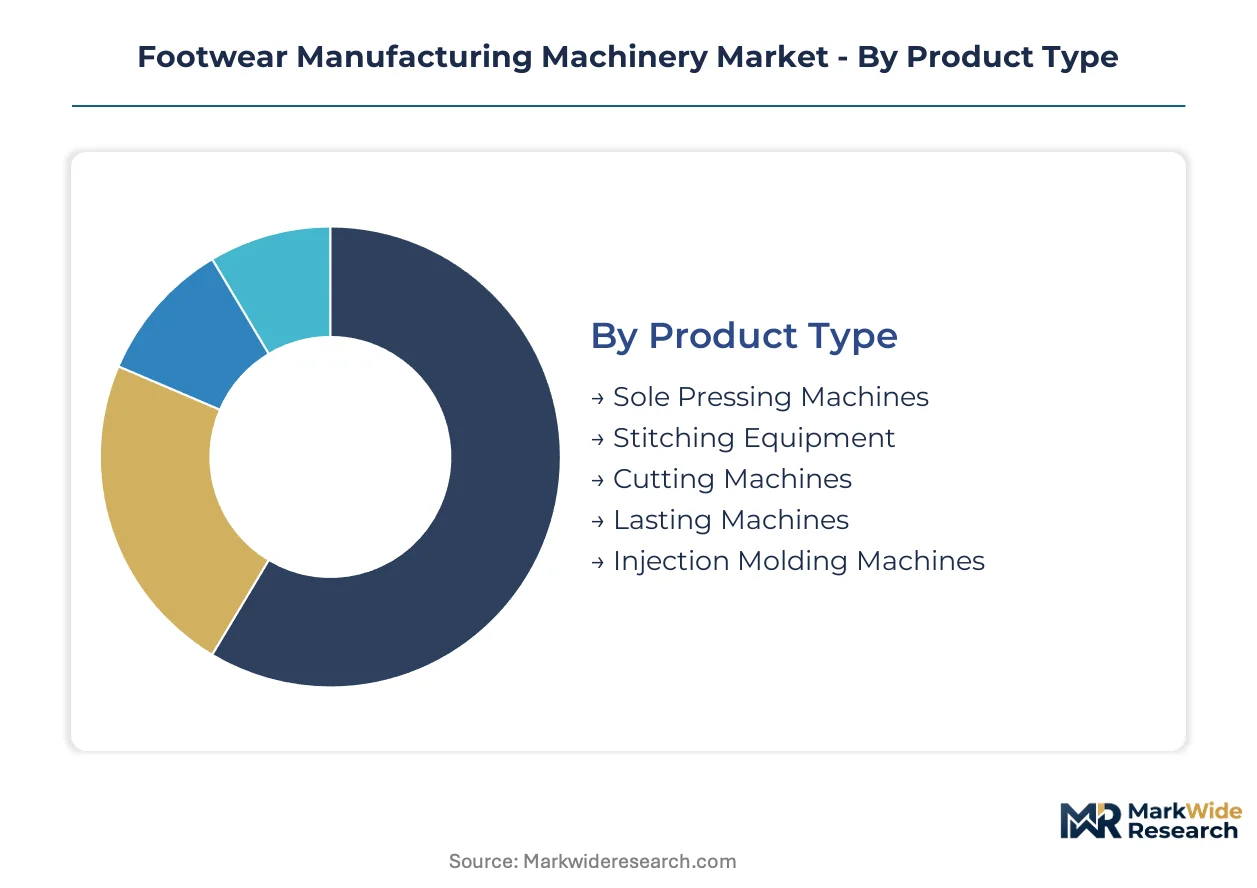
Segmentation in footwear manufacturing machinery reveals how distinct equipment categories demand specialized service architectures. Procurement patterns diverge sharply between mass-market injection molding lines requiring continuous technical support and precision cutting systems where calibration expertise determines operational uptime.
Product Type:
After-sales service intensity varies dramatically across equipment categories, with hydraulic systems demanding predictive maintenance contracts and mechanical platforms relying on component replacement programs.
- Injection Molding Machines:These systems process polyurethane and thermoplastic rubber compounds through heated barrel assemblies with clamping forces exceeding 500 tons. Demand concentrates in Vietnam's athletic footwear export zones where EU-Vietnam Free Trade Agreement rules-of-origin quotas drive capacity expansion. OEMs capture recurring revenue through mold refurbishment and barrel wear monitoring subscriptions.
- Cutting Machines:Die-cutting and laser-guided nesting platforms execute leather and synthetic material processing with tolerances approaching 0.1 millimeters. Italian tanneries facing REACH hexavalent chromium restrictions are retrofitting legacy equipment with certified dust extraction and chemical containment subsystems. Service intervals concentrate around blade replacement schedules and CAD-CAM software calibration cycles.
- Stitching Equipment:Multi-needle post-bed and automated sewing heads assemble upper components for mid-volume production lines.
- Sole Pressing Machines:Hydraulic and pneumatic compression systems bond outsole assemblies to lasted uppers through controlled pressure and temperature profiles.
- Lasting Machines:Mechanical and servo-driven toe and heel lasting equipment stretch upper materials over foot-shaped forms prior to sole attachment.
Injection molding machines hold the largest share; momentum sits with cutting machines as material waste reduction mandates accelerate replacement cycles.
Technology:
Capital deployment patterns across technology tiers reflect diverging risk appetites between established mechanical reliability and emerging digital integration.
- Automation Systems:Robotic material handling, vision-guided quality inspection, and autonomous guided vehicle networks coordinate factory workflows without human intervention. Guangdong province machine-tool clusters serve Vietnamese contract manufacturers expanding automated stitching capacity to meet export quotas. Integration complexity demands specialized commissioning engineers and continuous software update protocols.
- Computer Numerical Control:CNC platforms execute programmed toolpaths for precision cutting, drilling, and surface finishing operations with repeatability exceeding manual methods. Dongguan equipment vendors dominate this segment for East Asian mass-market producers seeking programmable flexibility across style changeovers. Training requirements for G-code programming and spindle maintenance create aftermarket service dependencies.
- Hydraulic:Fluid power systems deliver high-force compression and forming operations through piston-cylinder assemblies.
- Pneumatic:Compressed air actuation powers lighter-duty clamping, positioning, and material handling functions.
- Mechanical:Cam-driven and gear-based mechanisms provide cost-effective motion control for standardized production sequences.
Mechanical systems retain the largest installed base; automation systems are expanding most quickly as labor costs climb in traditional manufacturing centers.
Application:
End-use differentiation drives equipment specification divergence, with performance footwear demanding specialized forming capabilities and formal segments prioritizing finish quality.
- Sports Footwear:Athletic shoe production requires multi-density midsole molding, engineered mesh upper knitting, and automated assembly lines capable of style changeovers within hours. Nike and Adidas contract manufacturers in Vietnam and Indonesia are retrofitting facilities with ultrasonic welding systems that displace traditional stitching stations. Equipment specifications emphasize cycle time optimization and energy recovery systems.
- Safety Footwear:Industrial protective boots incorporate steel toe caps, puncture-resistant midsoles, and chemical-resistant compounds meeting occupational safety certifications. European manufacturers face dual pressure from REACH chemical restrictions and machinery safety directives, redirecting procurement toward certified automation platforms with documented compliance trails.
- Casual Footwear:Fashion-oriented production balances volume efficiency with material variety across leather, canvas, and synthetic constructions.
- Formal Footwear:Luxury dress shoe manufacturing emphasizes precision lasting and hand-finish emulation through controlled mechanical processes.
- Orthopedic Footwear:Custom therapeutic devices require adjustable molding platforms and small-batch production flexibility.
Sports footwear commands the largest equipment investment; orthopedic applications are gaining share fastest as aging demographics expand addressable markets.
End User:
Customer type determines contract structure preferences, with integrated manufacturers favoring bundled service agreements and independent suppliers pursuing component sourcing flexibility.
- Contract Manufacturers:Third-party production specialists operate multiple brand programs from shared facilities, demanding equipment with rapid changeover capabilities and modular tooling systems. Vietnam-based exporters serving EU markets are expanding automated lines to satisfy rules-of-origin documentation requirements. Procurement decisions prioritize equipment with pre-certified safety subsystems to compress compliance timelines.
- Footwear Manufacturers:Vertically integrated brand owners control design through distribution, specifying equipment aligned with proprietary construction methods and quality protocols. After-sales service unbundling has enabled independent spare parts sourcing, compressing OEM margins while accelerating third-party retrofit markets for legacy European equipment.
- OEMs:Original equipment manufacturers supply branded machinery platforms to downstream producers.
- Aftermarket Suppliers:Independent distributors provide spare parts, consumables, and refurbishment services outside captive OEM channels.
- Design Studios:Small-batch prototyping facilities require flexible equipment for sample development and limited production runs.
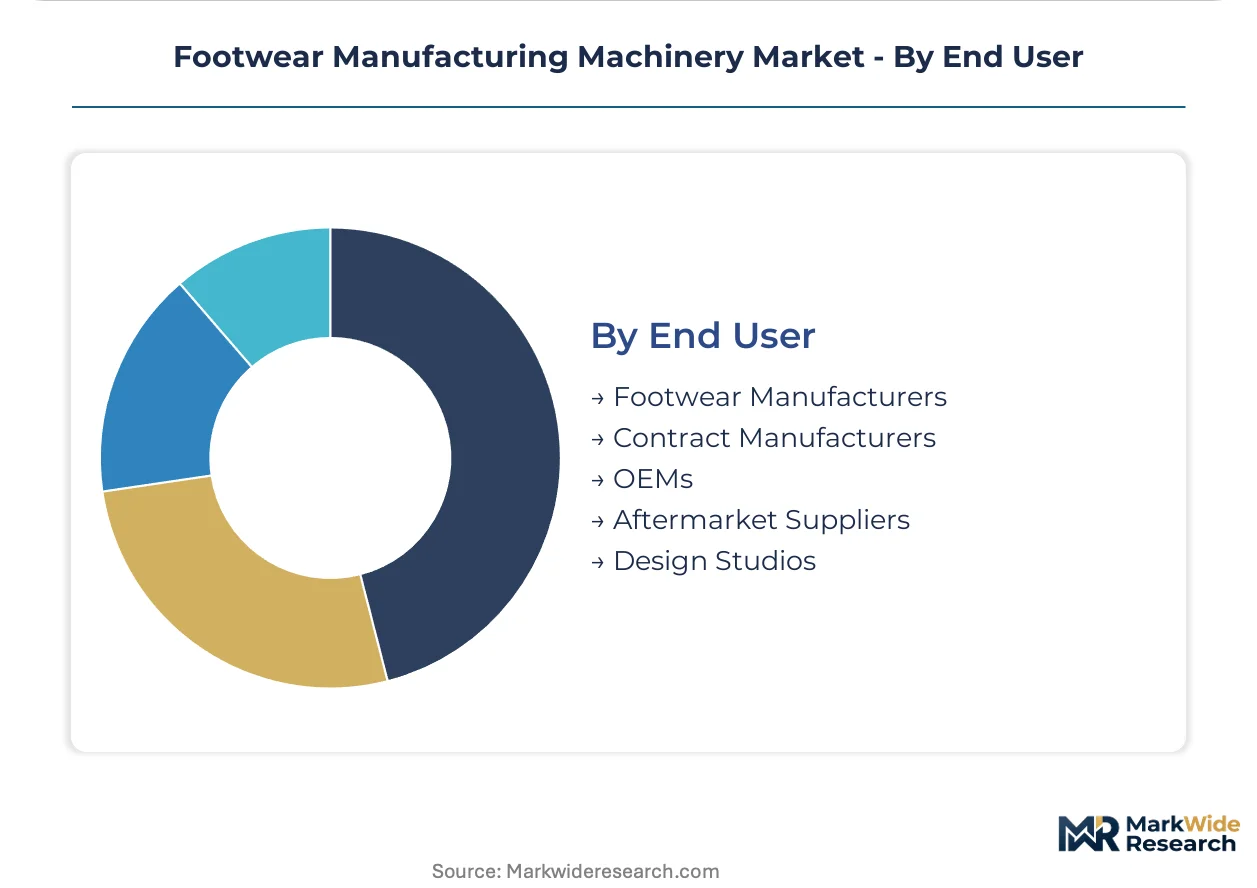
Contract manufacturers represent the largest customer segment; design studios are climbing the fastest as direct-to-consumer brand proliferation expands prototyping demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers in Vietnam and Indonesia dominate equipment procurement, while Italian tanneries and Chinese machine-tool clusters anchor supply-side capacity. Regulatory divergence across export markets is fragmenting compliance requirements.
Vietnam
Athletic footwear exporters are expanding automated stitching capacity to satisfy EU-Vietnam Free Trade Agreement rules-of-origin documentation. Ministry of Industry and Trade inspectors enforce machinery safety certifications for export license eligibility. Ho Chi Minh City industrial zones host Nike and Adidas contract manufacturers retrofitting lines with ultrasonic welding systems.
China
Guangdong province machine-tool clusters supply hydraulic sole pressing equipment to Southeast Asian contract manufacturers. MIIT unannounced audits enforce GB standards mandating emergency stop response times under 500 milliseconds. Dongguan vendors dominate domestic and regional procurement for mass-market producers.
Italy
Luxury tanneries face REACH phased restrictions on hexavalent chromium processing, redirecting capital toward certified cutting systems. ECHA compliance deadlines compress equipment replacement cycles from seven years to four. Arzignano leather district producers are retrofitting legacy equipment with dust extraction and chemical containment subsystems.
Indonesia
Contract manufacturers struggle to recruit mechatronics technicians capable of calibrating servo-driven stitching heads. National industrial standards agency regulations align with EU machinery safety directives for export market access. Batam and Jakarta industrial corridors attract machinery vendors establishing service depots for spare parts distribution.
Germany
Safety footwear manufacturers face dual pressure from REACH chemical restrictions and machinery safety directives. KBA and occupational safety regulators mandate documented compliance trails for automation platforms. Bavaria industrial regions host precision equipment specialists serving orthopedic and protective footwear segments.
Footwear Manufacturing Machinery Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented machinery categories. Italian and Chinese vendors anchor distinct tiers, with European OEMs capturing premium calibration-dependent segments and Guangdong fabricators dominating volume equipment. Strategic archetypes include precision-cutting specialists, hydraulic-system volume producers, and automation-integrating full-line suppliers. Competitive moves concentrate on CE marking modularization for compliance acceleration and after-sales service unbundling to capture spare parts markets.
Among Italian specialists, Comelz S.p.A and Atom S.p.A exemplify the precision-cutting archetype serving tanneries with material yield optimization. Dongguan Kingstone Shoe-making Machinery Co. Ltd. represents the Chinese volume-equipment tier, while Orisol Taiwan Ltd. occupies a position within the automation-integration segment. These three entities collectively illustrate how geographic specialization aligns with distinct buyer archetypes across luxury, mass-market, and technology-forward contract manufacturing segments.
| Leading Market Players |
|---|
| ALC Tecnologie Adesive S.r.l. |
| Orisol Taiwan Ltd. |
| Comelz S.p.A |
| True Ten Industrial Co. Ltd. |
| Kou Yi Iron Works Co. Ltd. |
| Atom S.p.A |
| Brustia Alfameccanica S.r.l. |
| Gusbi SpA |
| Dongguan Kingstone Shoe-making Machinery Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Guangdong's hydraulic pressing equipment sector is compressing supplier pricing power while simultaneously accelerating consolidation among Dongguan machine-tool clusters serving Vietnamese contract manufacturers.
Pricing Analysis
Cost-plus contracts indexed to specialty steel alloy and servo motor price indices dominate equipment procurement between Guangdong vendors and Southeast Asian buyers. Pricing stratifies across CE-certified automation platforms, GB-compliant domestic systems, and unbundled spare parts channels. Cost compression in standard hydraulic equipment is intensifying because Dongguan fabricators compete on volume for mass-market athletic footwear contracts. Contract manufacturers exhibit highest price sensitivity for sole pressing machinery, while luxury tanneries prioritize calibration-dependent cutting systems with premium service attachments.
Supply Chain Analysis
Specialty steel alloys from Germany and Japan, high-torque servo drives from Taiwan, and precision bearings from Switzerland feed into final assembly operations across Guangdong and Zhejiang provinces. Single-source vulnerability concentrates in Dongguan's hydraulic component machining capacity, where unannounced MIIT audits disrupt export license timelines. Distribution runs through captive OEM service networks for Italian precision equipment and independent spare parts distributors for Chinese volume machinery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control mechatronics technician pipelines and predictive maintenance algorithm development, as factories in Vietnam and Indonesia struggle to staff automated line commissioning.
For Market Incumbents: Insulate service revenue streams by embedding IoT-enabled monitoring subsystems that lock in recurring calibration contracts. Threats from ultrasonic welding substitution demand accelerated R&D in solvent-free bonding interfaces. Backward integration into servo motor supply secures margin control against input volatility. For New Entrants and Emerging Players: India's Tamil Nadu and Uttar Pradesh industrial corridors offer underpenetrated service depot opportunities as PLI scheme incentives attract footwear manufacturing capacity. Orthopedic footwear automation presents the most penetrable segment given aging demographics and small-batch production flexibility requirements. A go-to-market angle anchored to CE marking modularization compresses compliance timelines for mid-sized European tanneries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation-integrating full-line suppliers with predictive maintenance subscriptions. Long-term viability across the analysis window favors precision-cutting specialists with material yield optimization algorithms. The signal to watch is ultrasonic welding adoption rates in Vietnamese Nike and Adidas contract manufacturing facilities as an inflection indicator for traditional stitching equipment demand collapse.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Modularization | Pre-certified safety subsystems reduce ECHA compliance timelines for European tanneries. |
| Predictive Maintenance Subscriptions | IoT-enabled barrel wear monitoring captures recurring revenue from injection molding operators. |
| Backward Integration into Servo Supply | Upstream control over high-torque drives insulates margins against Taiwan component volatility. |
| Robotics-Cobotics Convergence | Force-limiting collaborative robots open luxury lasting automation to small-batch producers. |
| India Service Depot Expansion | Tamil Nadu and Uttar Pradesh depots capture PLI-driven machinery demand from footwear investors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with plant engineers at Vietnamese contract manufacturers, procurement leads at Guangdong machine-tool clusters, aftermarket service heads for Italian precision equipment, and maintenance directors at Indonesian athletic footwear facilities. Secondary validation drew from MIIT GB standards documentation, ECHA REACH restriction timelines, EU-Vietnam Free Trade Agreement rules-of-origin protocols, and customs data on machinery imports into Ho Chi Minh City industrial zones. Bottom-up equipment shipment tallies and top-down manufacturing capacity estimates were triangulated to anchor market sizing.
Calibration against historical replacement cycle compression and documented technology substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application end-use, and customer archetype, with regional regulatory cluster as an additional footwear-specific dimension. CAGRs were derived from elasticity-adjusted demand curves incorporating labor cost trajectories and compliance deadline impacts. Industry-specific forecast inputs encompassed ultrasonic welding retrofit rates and dual carbon audit penetration across Chinese provincial jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese automation vendors into European precision-cutting segments would shift outcomes beyond modeled ranges. Cross-checking against MIIT export license issuance data and ECHA pre-registration volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Waterproof Sneakers Market
Footwear
North America Footwear Market
Footwear
Men Formal Shoe Market
Footwear
Europe Barefoot Shoes Market
Footwear
Ankle Boots Market
Footwear
Leather Sneakers Market
Footwear
White Sneakers Market
Footwear
Self-Lacing Shoes Market
Footwear
Orthopedic Footwear Market
Footwear
GCC Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Formal Shoes Market
Footwear
Footwear Testing Services Market
Footwear
South America Athletic Footwear Market
Footwear
Global Espadrille Flats Market
Footwear
Athletic Footwear Market