
 Pet Food Bowl Market | 2026-2036
Pet Food Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Bowl Market Analysis
Millennial and Gen-Z pet owners are unwinding the traditional dominance of price-driven supermarket buyers in pet food bowl procurement. Petmate leverages vertical integration across plastic molding and distribution to sustain cost advantages in North American retail. IRIS USA anchors its position through manufacturing scale in injection-molded feeding systems for multi-pet households. Outward Hound differentiates via interactive and puzzle-feeding bowl designs that command shelf space in specialty channels.
Pet food bowls are purpose-built feeding vessels engineered from food-grade substrates including stainless steel alloys, BPA-free polymers, glazed ceramics, or tempered glass, with dimensional tolerances calibrated to species-specific muzzle geometry and portion requirements. Stainless steel variants dominate veterinary and commercial kennel procurement due to sanitization protocols, while ceramic and glass segments capture premium household demand where aesthetic integration with residential interiors drives selection. The style dimension reveals elevated and anti-slip configurations as the fastest-growing structural category, reflecting veterinary emphasis on joint health and feeding posture in aging pet populations.
FDA Center for Veterinary Medicine guidelines on food-contact material safety, combined with state-level California Proposition 65 enforcement on chemical disclosures, constrain substrate selection and labeling obligations for suppliers distributing in the United States. The EU REACH framework and F-Gas Regulation indirectly shape polymer sourcing decisions for manufacturers exporting into European markets. Stakeholders must monitor evolving veterinary nutrition science on feeding elevation and material biocompatibility as these findings increasingly migrate into breed-specific product specifications and retailer certification requirements.
Market Dynamics
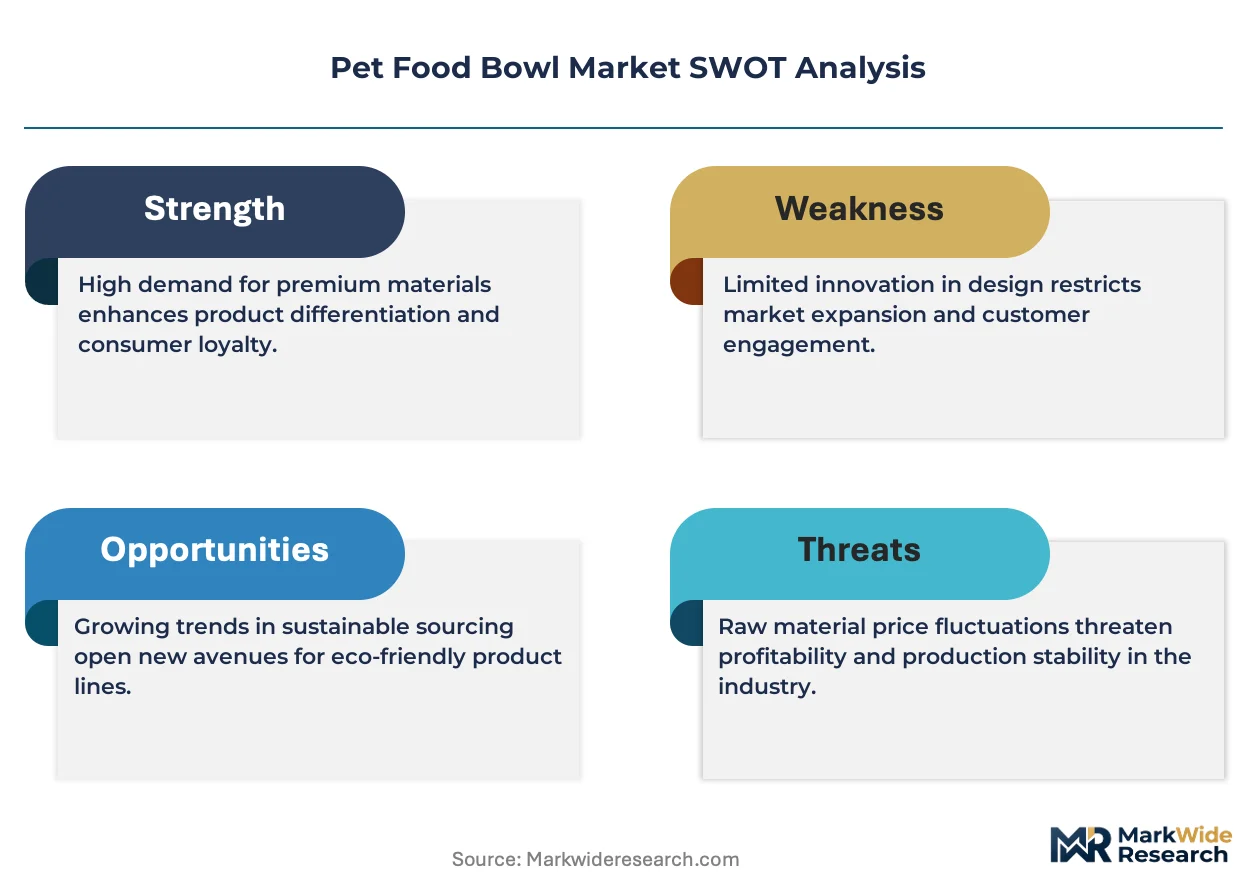
Pet humanization is compressing the mass-market premium gap as owners prioritize veterinary-endorsed feeding ergonomics and material safety certifications over price elasticity.
Growth Catalysts
- REACH chemical disclosure mandates:European manufacturers accelerating BPA-free polymer transitions ahead of enforcement deadlines, creating first-mover certification premiums in export markets.
- Elevated bowl configurations:Veterinary orthopedic research on cervical spine alignment in large breeds is driving breed-specific product development and specialist channel placement.
- China's pet ownership surge:Tier-1 city household formation patterns are expanding addressable demand for ceramic and tempered glass feeding vessels with interior design integration.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin stability for veterinary and kennel procurement contracts with fixed pricing terms.
- California Proposition 65 litigation exposure:Chemical disclosure non-compliance generates plaintiff bar targeting of imported ceramic glazes and polymer colorants.
- Silicone mat substitution:Low-cost feeding surface alternatives capture price-sensitive multi-pet household segments in mass retail.
Strategic Opportunities
- Germany's veterinary channel consolidation:Clinic network centralization creates bundled procurement contracts for breed-specific elevated feeding systems.
- Smart bowl sensor convergence:Integration of portion-tracking load cells with mobile application ecosystems opens subscription revenue models in wellness-focused households.
- EU F-Gas Regulation polymer sourcing:Fluoropolymer restrictions are accelerating bio-based polymer R&D partnerships with academic veterinary nutrition programs.
Industry Challenges
- Veterinary nutrition science translation lag:Peer-reviewed feeding posture studies require 18-24 month product development cycles before retail certification.
- Multi-material assembly complexity:Anti-slip base bonding with stainless steel carcasses generates warranty claims and return logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Bowl Market |
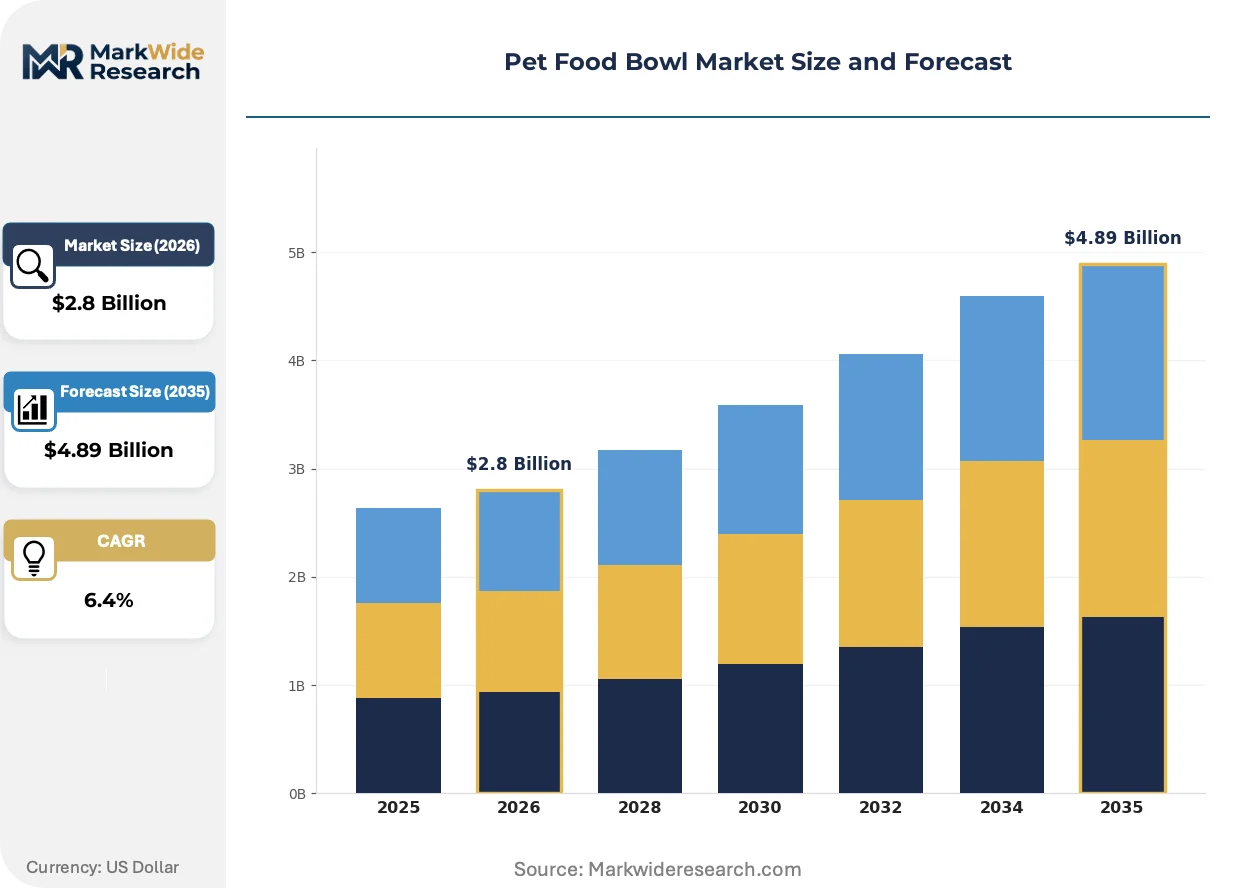
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Stainless Steel, Ceramic, Glass Size: Small, Medium, Large, Extra Large Style: Elevated, Traditional, Interactive, Travel Feature: Non-Slip, Dishwasher Safe, Customizable, Eco-Friendly |
| Companies Covered | Petmate, IRIS USA, Outward Hound, Trixie, KONG Company, PetSafe, Coastal Pet Products, Neater Pet Brands, GAMMA2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Bowl Market Emerging Trajectories
Material science and regulatory chemistry are redefining substrate hierarchies while distribution channels fragment between veterinary endorsement networks and direct-to-consumer wellness platforms.
Anti-microbial copper alloy infusions in stainless steel formulations is bifurcating the veterinary procurement segment. Large-breed kennel operators in the United States are adopting these substrates for reduced sanitization cycle frequency. The technology is compressing commodity-grade stainless steel into price-only supermarket channels while specialty manufacturers capture premium shelf space.
EU REACH SVHC candidate list expansions are forcing reformulation of polymer colorants and anti-slip rubber compounds. Manufacturers exporting into European markets must maintain dual inventory streams or absorb certification testing costs for unified product lines. Ceramic glaze suppliers in Portugal and Italy are most exposed given decorative pigment dependencies.
Subscription-based replenishment bundling is displacing single-unit retail purchases in urban millennial households. Chewy and Amazon's pet wellness verticals are capturing recurring revenue through automated bowl replacement schedules tied to life-stage nutrition transitions. This pattern concentrates in coastal United States metropolitan markets with high veterinary telehealth adoption rates.
Pet Food Bowl Market Segmentation
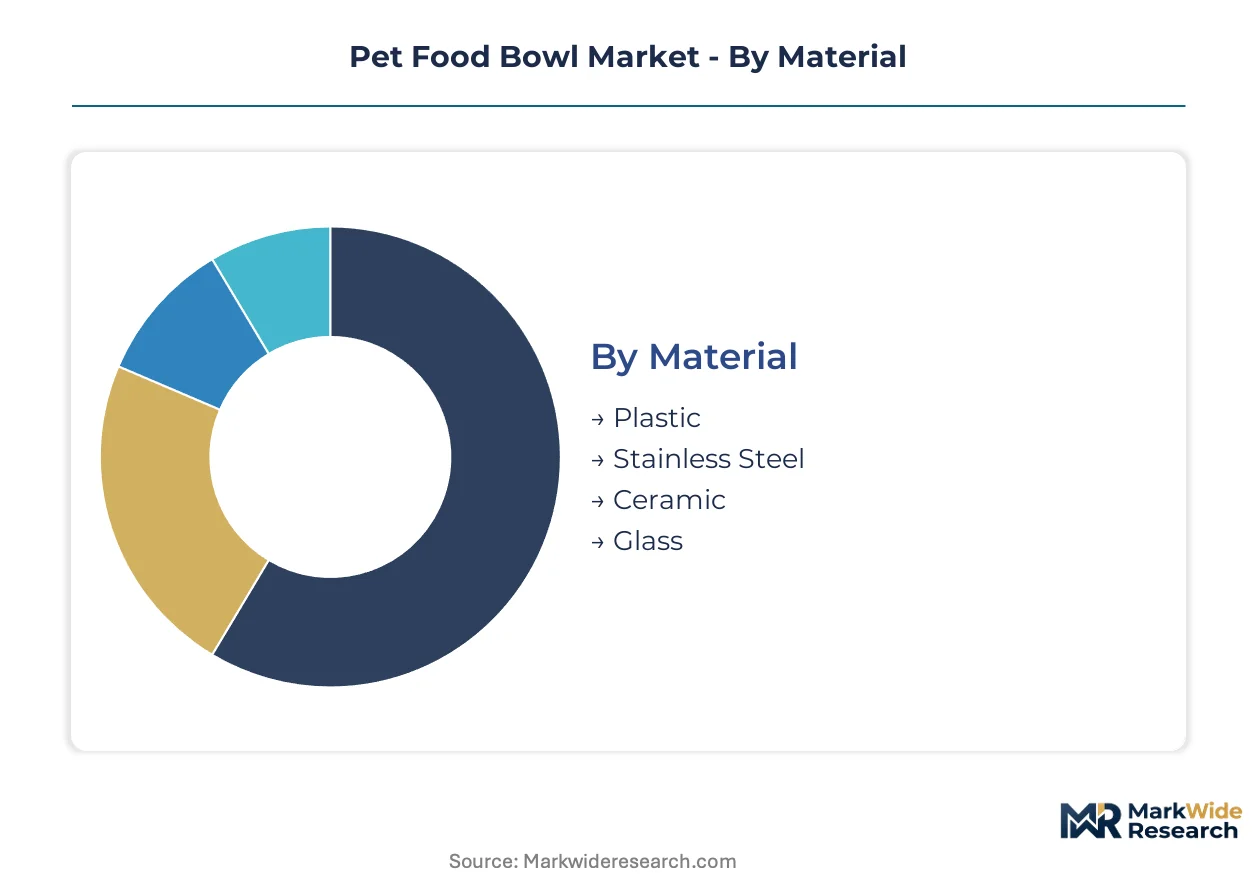
Pet food bowl segmentation reveals how material science, veterinary ergonomics, and household lifestyle patterns fragment procurement decisions across distinct price-performance tiers. Manufacturers must align substrate selection and dimensional specifications with channel-specific certification requirements and end-use durability demands.
Material:
Silicone mat substitutes and disposable feeding trays exert the strongest displacement pressure on commodity-grade polymer bowls in mass retail channels.
- Plastic:Injection-molded BPA-free polymers dominate volume production for multi-pet households and kennel operations. California Proposition 65 enforcement on chemical disclosures constrains colorant selection for suppliers distributing in the United States.
- Stainless Steel:Food-grade 304 and 316 alloys with antimicrobial copper infusions capture veterinary and commercial kennel procurement. Nickel and chromium price volatility compress margin stability for fixed-price contract manufacturers.
- Ceramic:Glazed stoneware and porcelain vessels target premium household demand where aesthetic integration with residential interiors drives selection. EU REACH SVHC candidate list expansions force reformulation of decorative pigments for export compliance.
- Glass:Tempered borosilicate formulations serve design-conscious urban consumers in China's Tier-1 cities. Thermal shock resistance specifications limit supplier base to specialized glassworks.
Stainless steel anchors the volume base in veterinary and institutional procurement while glass gains share at the steepest rate among millennial urban households.
Size:
Cost tier stratification separates premium ergonomic designs for large breeds from economy single-serve vessels targeting price-sensitive small-pet owners.
- Small:Compact vessels calibrated for toy breeds and feline muzzle geometry. Cat ownership expansion in German urban apartments concentrates demand here.
- Medium:Standard configurations for adult dogs between 10-25 kilograms. This tier captures the broadest household penetration across mass-market retail.
- Large:Reinforced structures engineered for breeds exceeding 25 kilograms with elevated base options. Veterinary orthopedic research on cervical spine alignment drives breed-specific product development in this segment.
- Extra Large:Heavy-duty feeding systems for giant breeds and multi-pet communal feeding. IRIS USA anchors manufacturing scale here for kennel and shelter procurement.
Medium sizes sustain the highest absolute shipment volumes while extra large configurations expand most quickly through veterinary channel consolidation.
Style:
Application-specific design separates posture-correcting elevated systems from portable travel formats targeting mobile pet ownership patterns.
- Elevated:Adjustable-height frameworks with anti-slip bases address joint health in aging pet populations. FDA Center for Veterinary Medicine guidelines on feeding ergonomics accelerate certification requirements.
- Traditional:Floor-level vessels with basic rim profiles serve price-driven supermarket channels. Commodity stainless steel and plastic variants dominate this mature segment.
- Interactive:Puzzle-feeding and slow-feed designs from Outward Hound command specialty retail shelf space. Behavioral enrichment claims require veterinary endorsement for premium positioning.
- Travel:Collapsible silicone and fabric-lined formats target airline-compliant pet transport. China's domestic tourism recovery concentrates demand in coastal metropolitan markets.
Traditional styles retain the largest installed base while elevated configurations climb the fastest through specialist veterinary endorsement networks.
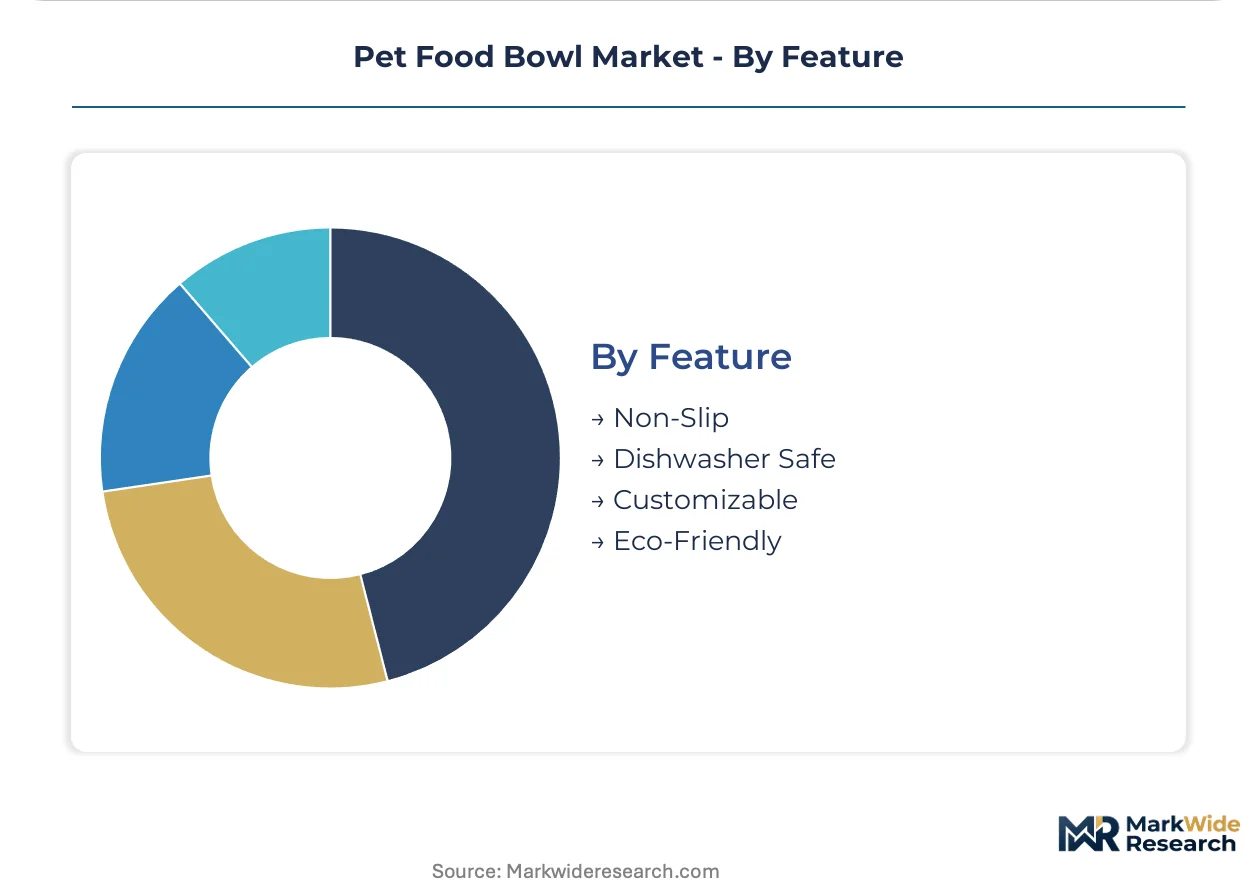
Feature:
Customer type differentiation separates wellness-focused households seeking smart-enabled portion tracking from sustainability-motivated buyers prioritizing circular material flows.
- Non-Slip:Thermoplastic elastomer base bonding with stainless steel carcasses. Multi-material assembly complexity generates warranty claims and return logistics costs.
- Dishwasher Safe:Temperature-resistant substrates meeting NSF/ANSI 51 food equipment standards. Veterinary clinics mandate this certification for sanitization protocol compliance.
- Customizable:Laser-etched personalization and modular color configurations. Subscription-based replenishment bundling through Chewy and Amazon concentrates in coastal United States markets.
- Eco-Friendly:Bio-based polymers and recycled content formulations. EU F-Gas Regulation restrictions on fluoropolymers accelerate R&D partnerships with academic veterinary nutrition programs.
Dishwasher-safe specifications dominate institutional procurement requirements while eco-friendly variants gain share fastest among Gen-Z first-time pet owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites North American import capacity for polymer resins and stainless steel alloys serving pet product manufacturing clusters across the United States.
United States
Millennial household formation in Austin and Denver concentrates demand for elevated ergonomic designs endorsed by veterinary orthopedic research. FDA Center for Veterinary Medicine guidelines on food-contact material safety constrain substrate selection for California distributors facing Proposition 65 enforcement. Injection-molding operations in Ohio and Pennsylvania supply mass-market retailers with BPA-free polymer vessels.
Germany
Veterinary clinic network consolidation in Bavaria and North Rhine-Westphalia creates bundled procurement contracts for breed-specific feeding systems. EU REACH SVHC candidate list expansions force reformulation of ceramic glazes and rubber compounds for export compliance. Stuttgart-area fabricators specialize in precision-engineered stainless steel carcasses for commercial kennel operators.
China
Tier-1 city household formation in Shanghai and Shenzhen expands addressable demand for tempered glass and ceramic vessels with interior design integration. SAMR food-contact material standards align with FDA guidelines for export-oriented manufacturers. Yangtze River Delta glassworks supply thermal-shock-resistant borosilicate formats to design-conscious urban consumers.
United Kingdom
Subscription-based replenishment adoption in Greater London concentrates recurring revenue through veterinary telehealth platforms. FSA food-contact material regulations and post-Brexit UK REACH implementation create dual compliance obligations for EU suppliers. Midlands-based distributors serve specialty pet retail chains with elevated configurations targeting aging pet populations.
Japan
Apartment-dwelling cat ownership in Tokyo and Osaka drives compact vessel demand calibrated to feline muzzle geometry. METI product safety standards and JIS food equipment certifications constrain import substrate selection. Nagoya-area ceramic producers supply glazed stoneware formats integrating with minimalist residential interiors.
Pet Food Bowl Market Vendor Landscape
Listed leaders compete with private specialists across material science capabilities and veterinary endorsement networks. The vendor base stratifies into three tiers: mass-market volume producers, specialty ergonomic designers, and veterinary channel integrators. Archetypes include backward-integrated polymer molders, design-forward ceramic studios, and clinic-network procurement consolidators. Capacity expansion and strategic partnerships dominate competitive moves as players secure alloy supply agreements and telehealth platform integrations.
Among North American fabricators, Petmate anchors the backward-integrated tier with captive plastic molding operations, while IRIS USA exemplifies manufacturing scale in injection-molded feeding systems. Outward Hound occupies a position within the specialty design archetype, representing interactive and puzzle-feeding configurations that command premium shelf space. These three players collectively illustrate how competitive positioning fragments across cost discipline, manufacturing scale, and behavioral enrichment innovation vectors.
| Leading Market Players |
|---|
| Petmate |
| IRIS USA |
| Outward Hound |
| Trixie |
| KONG Company |
| PetSafe |
| Coastal Pet Products |
| Neater Pet Brands |
| GAMMA2 |
| Others |
Supply Flow & Price Mechanics
Injection-molding capacity utilization across Ohio and Pennsylvania polymer clusters shapes both supply concentration and price floors for mass-market BPA-free vessels. Scale economies in captive molding operations compress per-unit costs for high-volume supermarket contracts while specialty ceramic studios in Portugal and Italy face elevated fixed-cost absorption at lower batch sizes.
Pricing Analysis
Volume-discount tiering structures stratify across premium veterinary-certified elevated systems, standard mid-market stainless steel formats, and economy polymer vessels for price-driven multi-pet households. Price differentiation hinges on FDA food-contact certification grade and antimicrobial copper-alloy infusion specifications. Cost compression in commodity-grade stainless steel intensifies as nickel and chromium price volatility squeezes fixed-contract manufacturers. Kennel procurement officers exhibit the highest price sensitivity, while design-conscious urban millennials in China's Tier-1 cities show the least.
Supply Chain Analysis
Inventory lead times for thermal-shock-resistant borosilicate glass extend longest due to specialized Yangtze River Delta glassworks capacity constraints. Manufacturing concentrates in China for tempered glass and ceramic vessels, the United States for injection-molded polymers, and Germany for precision-engineered stainless steel carcasses. Raw material dependencies include nickel-chromium alloys, BPA-free polymer resins, and decorative ceramic pigments. Single-source vulnerability runs through Yangtze River Delta glassworks for premium borosilicate formats. Distribution runs through premium pet specialty retailers, veterinary clinic networks, and direct-to-consumer wellness platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as millennial and Gen-Z pet owners unwind traditional supermarket channel dominance, creating niches for veterinary-endorsed ergonomic designers and telehealth-integrated subscription platforms.
For Market Incumbents: Secure alloy supply agreements with nickel-chromium producers to buffer margin compression from commodity price volatility. Secure veterinary endorsement networks before clinic consolidation in Germany and the United States hardens channel access for late movers. Backward integration into captive polymer molding sustains cost discipline against silicone mat substitutes. For New Entrants and Emerging Players: Differentiate on smart-enabled portion tracking with mobile application ecosystems to capture subscription revenue in wellness-focused coastal United States households. Target elevated ergonomic configurations for large-breed orthopedic applications where veterinary research lag creates 18-24 month white-space windows. Pursue direct-to-consumer launch through Chewy and Amazon pet wellness verticals with automated replacement scheduling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors design-forward ceramic studios with EU REACH compliance capabilities and telehealth platform integration prospects. Five-to-ten year viability rests on material science differentiation rather than commodity scale. Watch for FDA Center for Veterinary Medicine guidance expansion on feeding ergonomics as certification inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Endorsement Network Partnership | Clinic consolidation in Germany and the United States creates bundled procurement gatekeepers. |
| Antimicrobial Copper-Alloy Substrate Launch | FDA food-contact certification bifurcates veterinary procurement away from commodity stainless steel. |
| Smart Bowl Sensor Integration | Load-cell portion tracking with mobile ecosystems opens recurring subscription revenue models. |
| EU REACH-Compliant Ceramic Glaze Reformulation | SVHC candidate list expansions force decorative pigment transitions for export market access. |
| Direct-to-Consumer Subscription Platform | Automated replacement scheduling through Chewy and Amazon captures coastal millennial households. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with pet product manufacturing executives, veterinary procurement officers, specialty retail category managers, and polymer molding plant directors; and secondary validation through FDA Center for Veterinary Medicine guidance documents, EU REACH SVHC candidate list publications, SAMR food-contact standards filings, and trade customs records for polymer resins and stainless steel alloys. Bottom-up shipment estimates triangulated against top-down spending penetration models across household pet ownership cohorts.
Across the analysis window, the forecasting framework modeled material substrate, vessel size tier, structural style configuration, and feature specification as core segmentation dimensions. CAGRs derived from trend extrapolation of veterinary endorsement adoption rates, pet humanization spending elasticity, and regulatory compliance cost pass-through coefficients. Nickel-chromium price volatility assumptions and clinic network consolidation trajectories served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable pet ownership demographics and current FDA-EU regulatory enforcement intensity; material deviation in trade policy or veterinary nutrition science consensus would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UTI Cat Food Market
Pet Care Products
Pet Feeder Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Pet Collar Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Cat Calming Treats Market