
 China Hair Transplant Market | 2026-2036
China Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
China Hair Transplant Market Insights
The aesthetic medicine sector is repositioning hair restoration from a niche dermatology service to a mainstream consumer wellness category. Yonghe Hair Transplant dominates chain-scale operations across eastern China. Barley Microneedle Hair Transplant Hospital differentiates through proprietary microneedle instrumentation. Shanghai Jiahua Hair Transplant Hospital anchors premium positioning in the Yangtze River Delta.
China hair transplant services encompass surgical relocation of autologous follicular units from donor to recipient scalp zones, typically performed under local anesthesia with graft survival rates dependent on extraction precision and ischemia time management. The primary commercial purpose centers on androgenetic alopecia remediation for cosmetic and psychological outcomes. FUE procedure type leads volume due to reduced linear scarring and faster recovery profiles. Aesthetic center end users represent the fastest-growing channel as non-hospital medical beauty chains expand service menus. PRP therapy technology captures margin concentration through recurring session economics and consumable attachment rates.
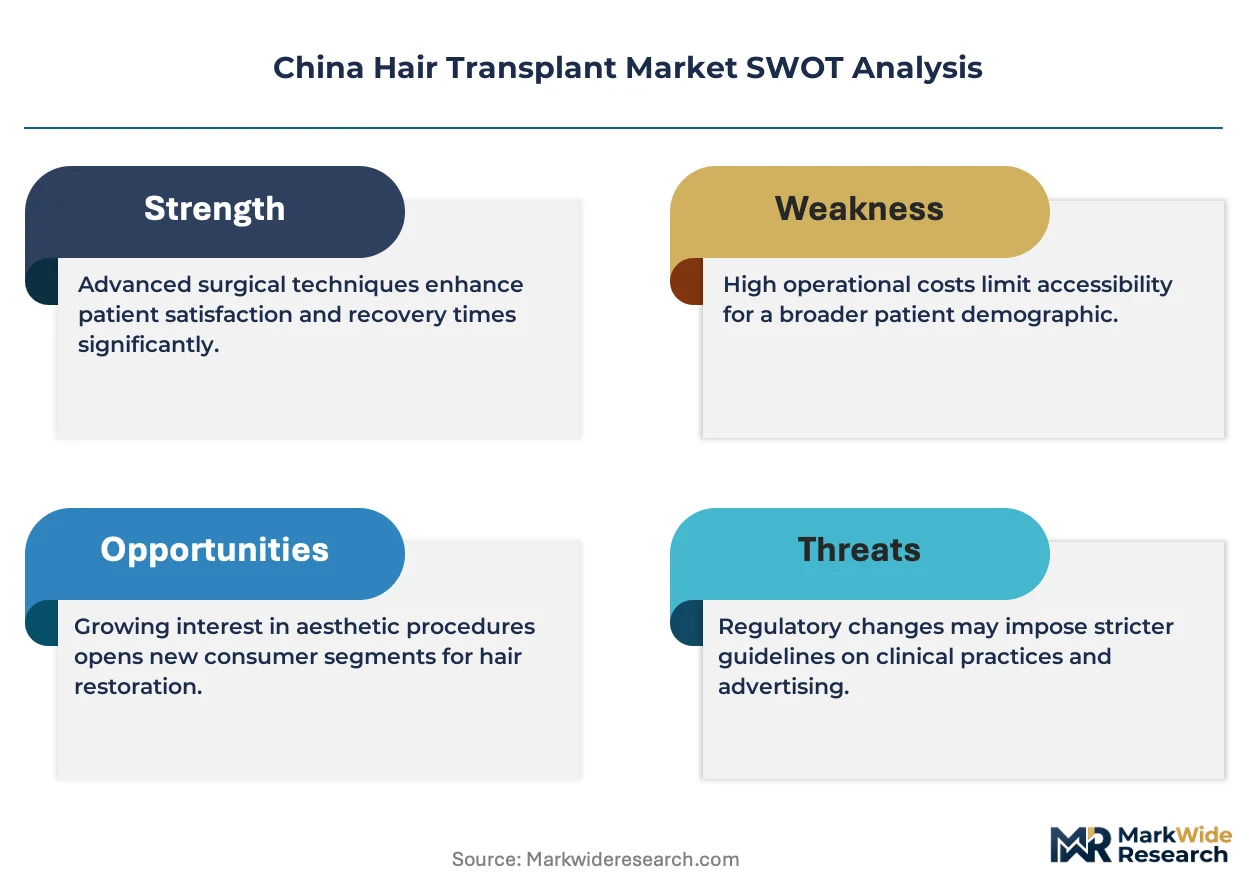
NMPA regulates implantable hair devices under Class II medical device frameworks, while SAMR oversees advertising claims and anti-unfair competition enforcement in clinic marketing. MEE environmental standards shape biomedical waste disposal costs for high-volume surgical centers. Stakeholders must monitor regulatory reclassification risks for robotic transplant systems and laser therapy equipment as innovation outpaces existing approval pathways.
Market Dynamics
NMPA medical device reclassification pressure is compressing approval timelines for robotic transplant systems while first-tier city clinics absorb premium positioning costs. This regulatory tightening coincides with supply concentration among eastern China surgical chains.
Growth Catalysts
- Urban Professional Demand:Young white-collar workers in Shanghai, Beijing, and Guangzhou metropolitan corridors prioritize FUE procedures for career-adjacent appearance optimization. This demographic shift normalizes hair restoration as standard wellness expenditure.
- PRP Therapy Economics:Platelet-rich plasma technology generates recurring revenue through session-based protocols and consumable attachment rates. Aesthetic centers expand service menus to capture this margin concentration.
- NMPA Class II Pathways:China's medical device regulator maintains clearer registration frameworks for implantable hair devices than neighboring jurisdictions. This regulatory clarity accelerates product-to-market velocity for compliant manufacturers.
Market Restraints
- Donor Scarcity Constraints:Autologous follicle supply limits procedure volume per patient. Surgeons face ceiling effects on graft density for advanced androgenetic alopecia cases.
- MEE Waste Compliance:China's Ministry of Ecology and Environment biomedical disposal standards elevate operational costs for high-volume surgical centers processing follicular unit waste streams.
- Robotic System Capital Intensity:Automated extraction platforms require seven-figure RMB investments. Independent clinics struggle to amortize equipment costs against procedure volume thresholds.
Strategic Opportunities
- Second-Tier City Penetration:Chengdu, Hangzhou, and Wuhan exhibit underdeveloped clinic density relative to disposable income growth. Early entrants capture brand positioning before market saturation.
- Female Patient Segmentation:Eyebrow and hairline contouring applications for women remain underserved. Specialized marketing and technique adaptation unlock this adjacent demographic.
- SAMR Advertising Clarity:China's State Administration for Market Regulation enforcement against misleading efficacy claims creates competitive advantage for compliant operators. Transparent outcome documentation differentiates premium providers.
Industry Challenges
- Surgeon Training Bottlenecks:FUE extraction precision requires 2,000+ graft supervised experience. Accredited training programs fail to match clinic expansion velocity.
- Cross-Platform Integration:Robotic systems, manual extraction tools, and post-operative monitoring software lack interoperability standards. Workflow friction degrades throughput metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Hair Transplant Market |
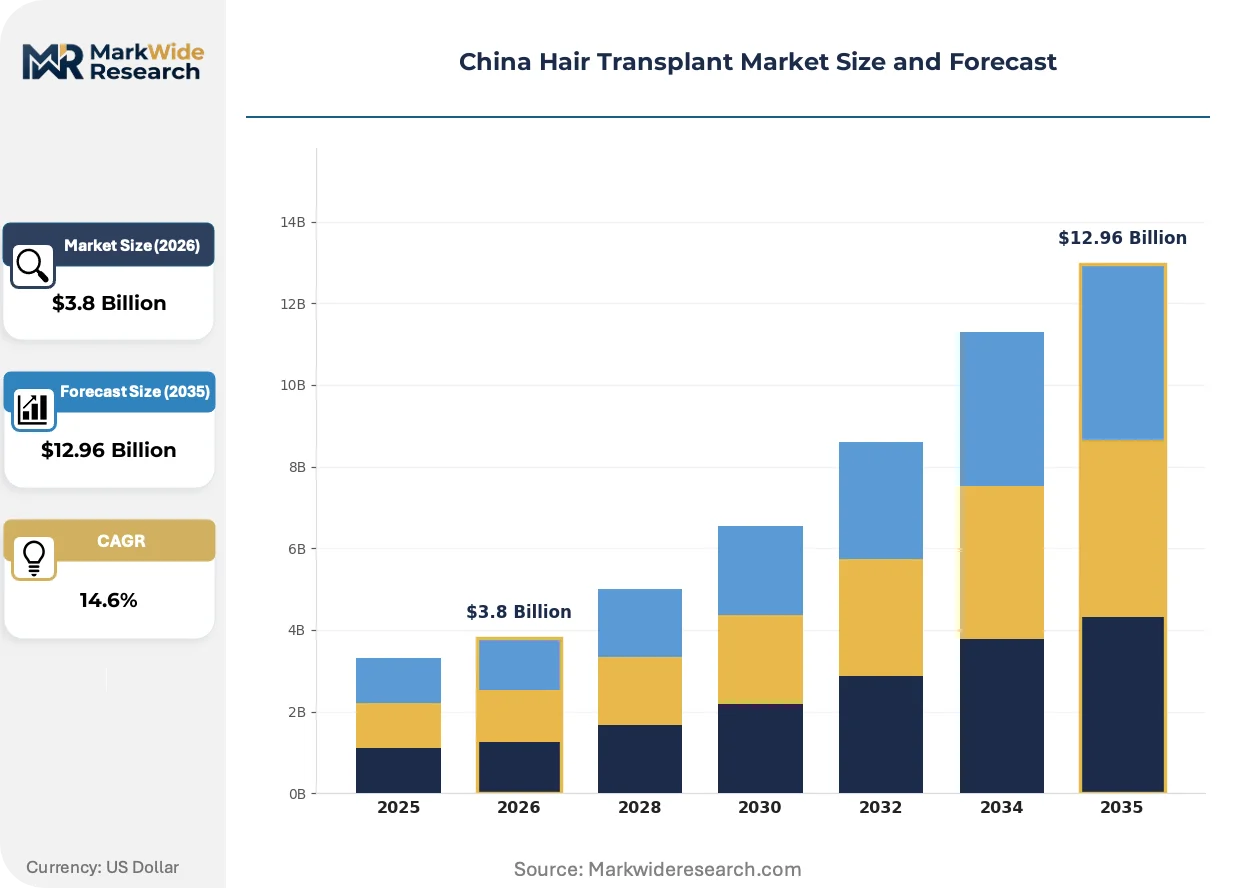
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, Robotic Transplant, Scalp MicroPigmentation End User: Clinics, Hospitals, Home Users, Aesthetic Centers Technology: Laser Therapy, PRP Therapy, Microneedling, Hair Growth Devices Age Group: 18-24, 25-34, 35-44, 45+ |
| Companies Covered | Yestar Medical, Guangzhou Huamei Medical, Yonghe Hair Transplant, Beijing Huazhong Hospital, Ningbo Jiangbei Hair Transplant Hospital, Barley Microneedle Hair Transplant Hospital, Shanghai Jiahua Hair Transplant Hospital, Elite Hair Clinic, Beijing 101 Hair Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Hair Transplant Market Trends and Innovations
Chinese hair restoration is pivoting from manual extraction dominance toward precision-automation and recurring-revenue service models. Technology convergence and regulatory clarity are compressing competitive differentiation cycles.
Robotic follicular unit extraction is consolidating market share among high-volume surgical centers. These systems reduce ischemia time through automated graft handling. Premium chains in Shanghai and Beijing deploy this technology to justify pricing premiums and standardize outcomes.
SAMR tightened enforcement against before-and-after advertising claims without clinical documentation. This policy shift elevates compliance costs for smaller operators. Market-leading clinics invest in institutional review board partnerships to generate defensible outcome data.
Young male professionals now research procedures through social media verification rather than clinic-direct channels. Third-party aesthetic platforms capture initial patient education and booking flow. This behavioral shift concentrates marketing spend on Key Opinion Leader partnerships and user-generated content strategies.
China Hair Transplant Market Segmentation
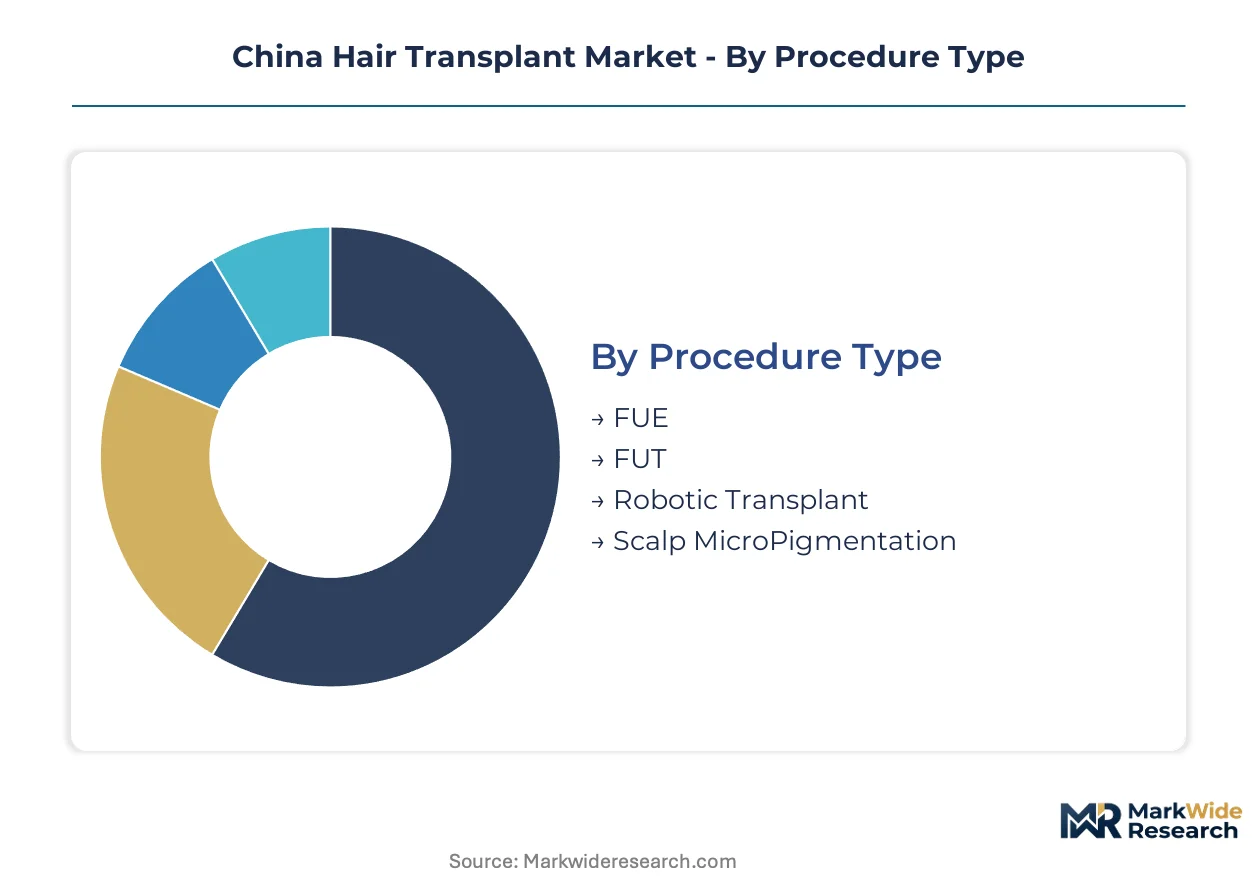
China's hair transplant market segments along four intersecting dimensions that determine pricing power, regulatory pathway, and customer lifetime value. Procedure type and technology selection drive upfront revenue, while end-user channel and age cohort shape recurring service economics.
Procedure Type:
Upgrade cycles in extraction technology are compressing as robotic systems displace manual FUE dominance in premium Shanghai and Beijing clinics.
- FUE:Follicular unit extraction removes individual grafts via micro-punch instrumentation, eliminating linear donor scarring. Young professionals in Guangzhou and Shenzhen metropolitan corridors prioritize this technique for faster return-to-work profiles and minimal visible recovery.
- FUT:Follicular unit transplantation harvests a donor strip for dissection into grafts, enabling higher graft yields per session. Patients with advanced androgenetic alopecia in tier-2 cities select FUT when maximizing graft count outweighs scar concealment concerns.
- Robotic Transplant:Automated extraction platforms standardize punch depth and angle through optical guidance systems. Yonghe Hair Transplant and Barley Microneedle chains deploy these systems to reduce technician-dependent outcome variance.
- Scalp MicroPigmentation:Cosmetic tattooing creates the illusion of hair density through dermal pigment deposition. This non-surgical alternative attracts price-sensitive patients and those with insufficient donor reserves for transplantation.
FUE sits at the top of the volume ranking, with robotic transplant climbing the fastest as chain operators amortize capital equipment across high-throughput centers.
End User:
Channel cost structures diverge sharply, with aesthetic centers capturing margin through bundled wellness packages while hospitals absorb regulatory compliance overhead.
- Aesthetic Centers:Non-hospital medical beauty chains integrate hair restoration into comprehensive appearance management menus. These facilities in Shanghai's Jing'an and Beijing's Chaoyang districts leverage PRP attachment rates and membership subscriptions for recurring revenue.
- Clinics:Specialized hair transplant facilities concentrate surgical expertise and graft processing infrastructure. Independent operators in Chengdu and Hangzhou compete on surgeon reputation and transparent pricing disclosure.
- Hospitals:Dermatology departments within tertiary hospitals manage complex cases and NMPA device trials. Public institutions face SAMR advertising restrictions that limit direct patient acquisition.
- Home Users:Consumer-grade laser caps and topical delivery systems serve maintenance and early intervention segments. E-commerce platforms capture this demand through direct-to-consumer marketing.
Aesthetic centers lead volume contribution, with home users gaining share fastest as device miniaturization improves portability and ease of use.
Technology:
Technology selection determines consumable attachment rates and session frequency, with PRP and microneedling generating superior recurring economics.
- PRP Therapy:Autologous platelet concentrate injection stimulates follicle angiogenesis through growth factor release. Shanghai Jiahua and premium Yangtze River Delta operators package PRP as post-transplant maintenance with quarterly refresh protocols.
- Microneedling:Percutaneous collagen induction creates microchannels for topical absorption and wound-healing response activation. Barley Microneedle Hospital's proprietary instrumentation differentiates through reduced procedure discomfort.
- Laser Therapy:Low-level light emission at 650nm wavelength modulates cellular metabolism in follicular units. Home-use device manufacturers target the 25-34 age bracket for preventive intervention.
- Hair Growth Devices:NMPA Class II regulated instruments include laser caps, LED helmets, and combination photobiomodulation systems. Registration pathway clarity accelerates compliant product introduction versus neighboring jurisdictions.
PRP therapy commands the highest margin concentration, with hair growth devices expanding most quickly through retail channel penetration.
Age Group:
Patient age correlates with procedure motivation, intervention timing, and willingness to accept surgical versus non-surgical solutions.
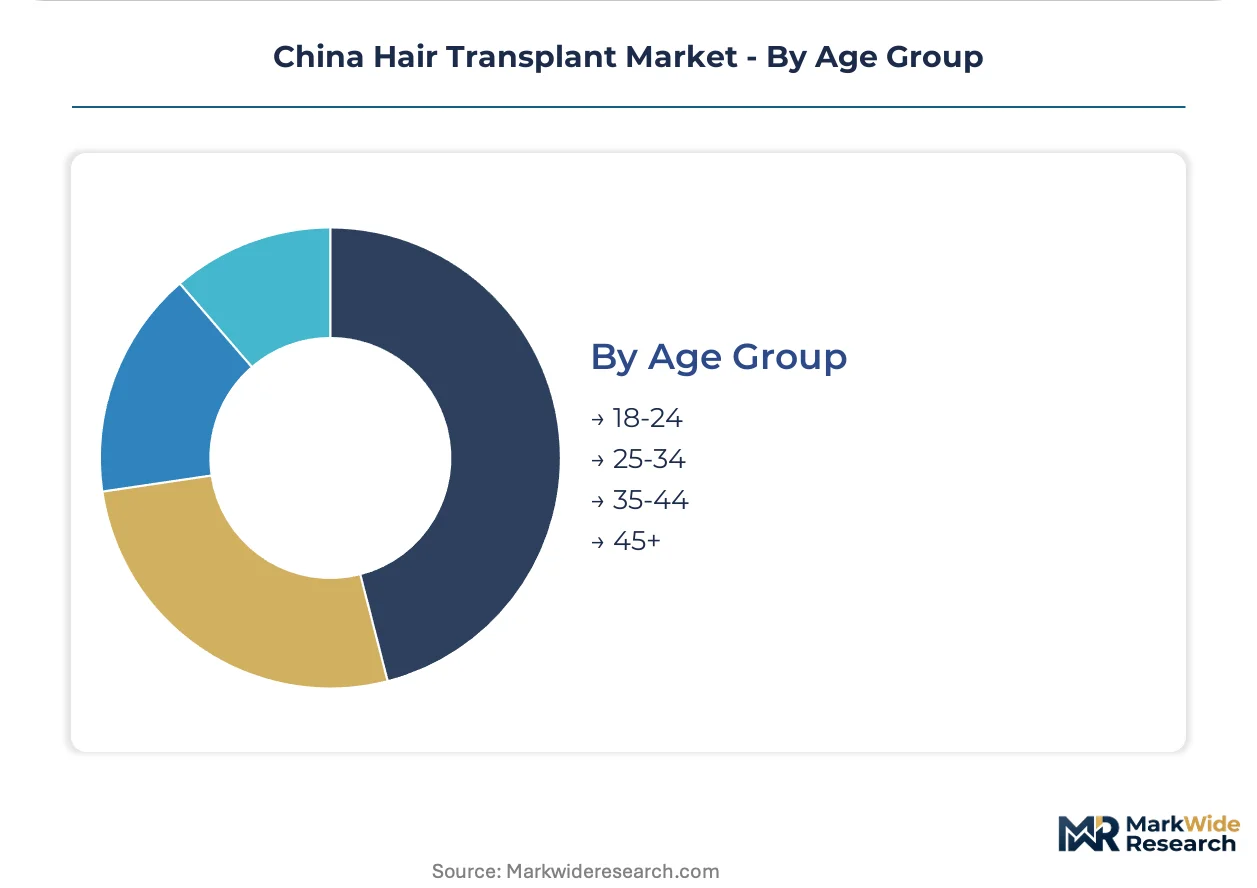
- 25-34:Peak surgical demand cohort combining disposable income accumulation with early-stage androgenetic alopecia progression. First-tier city white-collar workers in this bracket normalize hair restoration as career investment.
- 35-44:Established professionals pursuing comprehensive density restoration with higher graft count requirements. This segment demonstrates strongest response to combination therapy packaging.
- 18-24:Preventive and early-intervention focus with preference for non-surgical technologies and lifestyle modifications. Social media education drives awareness before surgical consideration.
- 45+:Advanced alopecia cases with limited donor supply, often requiring FUT maximization or scalp micropigmentation alternatives. Price sensitivity increases with competing health expenditures.
The 25-34 bracket dominates procedure volume, with the 18-24 segment showing steepest expansion trajectory as preventive intervention normalizes among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinic operators migrate toward eastern coastal provinces where NMPA compliance costs remain offset by higher procedure pricing power. This regulatory-arbitrage dynamic concentrates surgical capacity in jurisdictions with established medical beauty infrastructure.
Yangtze River Delta
Shanghai anchors premium FUE volume through white-collar demand from finance and technology sectors. SAMR advertising enforcement in this jurisdiction elevates compliance costs for smaller operators. Jing'an and Pudong districts host the highest clinic density per capita nationwide.
Pearl River Delta
Guangzhou and Shenzhen metropolitan corridors generate surgical demand from manufacturing executives and cross-border professionals. MEE biomedical waste standards impose elevated disposal costs on high-volume centers. Dongguan satellite clinics serve price-sensitive patients from manufacturing hubs.
Beijing-Tianjin-Hebei
Capital region clinics attract patients from northern provinces seeking surgeon reputation and tertiary hospital affiliations. NMPA Class II device registration pathways operate with greater procedural clarity than neighboring jurisdictions. Chaoyang district concentration supports premium positioning through KOL marketing networks.
Sichuan-Chongqing
Chengdu emerges as western China's surgical hub with disposable income growth outpacing clinic supply expansion. Provincial health commission oversight maintains consistent with national SAMR frameworks. Local operators capture patient flow from underserved Guizhou and Yunnan provinces.
Shandong Peninsula
Qingdao and Jinan metropolitan areas exhibit rising FUE demand from middle-management professionals. Environmental compliance costs under MEE standards remain below eastern coastal benchmarks. Regional chains expand from these bases into neighboring Henan and Jiangsu markets.
China Hair Transplant Market Competitive Landscape
Chain-scale expansion dominates the current landscape as operators amortize robotic equipment across multiple surgical centers. Market structure concentrates among three to five multi-city chains controlling premium positioning in first-tier corridors. Two strategic archetypes prevail: capital-intensive robotic deployers and surgeon-reputation-dependent independents. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among eastern China-based chains, Yonghe Hair Transplant, Barley Microneedle Hair Transplant Hospital, and Shanghai Jiahua Hair Transplant Hospital occupy positions within the premium-tier segment. Yonghe exemplifies the scale-driven archetype through multi-provincial presence. Barley Microneedle represents specialization through proprietary instrumentation differentiation. Shanghai Jiahua anchors Yangtze River Delta positioning through metropolitan corridor concentration. These three entities collectively illustrate how regulatory clarity and capital access determine competitive positioning in NMPA-compliant markets.
| Leading Market Players |
|---|
| Yestar Medical |
| Guangzhou Huamei Medical |
| Yonghe Hair Transplant |
| Beijing Huazhong Hospital |
| Ningbo Jiangbei Hair Transplant Hospital |
| Barley Microneedle Hair Transplant Hospital |
| Shanghai Jiahua Hair Transplant Hospital |
| Elite Hair Clinic |
| Beijing 101 Hair Care |
| Others |
Pricing and Supply Chain Analysis
Surgeon concentration in Shanghai, Beijing, and Guangzhou metropolitan corridors generates labor-cost differentials that widen pricing-tier spreads between premium robotic-equipped chains and manual-extraction independents. NMPA Class II device compliance costs concentrate among eastern China operators, compressing margins for smaller clinics while reinforcing tiered service economics.
Pricing Analysis
Direct-to-patient channel margins at aesthetic centers absorb SAMR advertising compliance overhead while hospital dermatology departments sacrifice markup flexibility for institutional credibility. Pricing stratifies across premium robotic FUE, standard manual extraction, and economy FUT tiers based on equipment amortization schedules and surgeon certification grade. Cost compression in the standard tier intensifies as chain operators deploy robotic systems to justify per-graft premiums. Price-sensitive manufacturing professionals in Dongguan and satellite cities drive volume at economy positioning, while finance-sector patients in Shanghai's Jing'an district demonstrate lowest price elasticity.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Shanghai coordinate hub-and-spoke patterns for follicular unit extraction punches, PRP centrifuge consumables, and laser therapy devices. Manufacturing concentrates in China, South Korea, and Germany for precision surgical instrumentation. Raw material dependencies include medical-grade titanium for micro-punches, sterile packaging films, and optical guidance components for robotic platforms. Single-source vulnerability runs through German-engineered extraction motors. Distribution runs through medical device distributors with NMPA licensing, bypassing general healthcare procurement channels for direct clinic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China's hair transplant market rests on PRP therapy attachment rates and robotic equipment utilization improvements that lower per-graft labor intensity. Premium-tier positioning in Yangtze River Delta corridors captures disposable income growth while standard-tier operators face cost compression from surgeon wage inflation.
For Market Incumbents: Anchor defensive positioning through backward integration into PRP consumable manufacturing and captive surgeon training academies. Yonghe Hair Transplant exemplifies scale-driven consolidation that amortizes robotic capital across multi-provincial footprints. Threats from microneedle technology specialists like Barley Hospital require proprietary instrumentation R&D investment. Channel control through aesthetic center partnerships defends against third-party platform disintermediation. For New Entrants and Emerging Players: Female patients seeking eyebrow and hairline contouring represent an underserved buyer archetype with premium pricing tolerance. Chengdu and Wuhan metropolitan corridors offer geographic white-space with disposable income growth outpacing clinic supply. Hangzhou's technology-sector professionals demonstrate early-adopter profiles for preventive laser therapy protocols. Go-to-market positioning through social media KOL partnerships bypasses SAMR advertising restrictions that constrain incumbent hospital marketers. For Investors and Strategic Acquirers: Private equity firms with healthcare specialization are the most active acquirer in this space, targeting chain-scale operators with robotic deployment runway. Long-term viability across a 5-10 year window depends on NMPA regulatory clarity for next-generation automated systems. Acquisition target archetypes include second-tier city independents with surgeon reputation moats and underutilized PRP service capacity. The signal to watch is SAMR enforcement intensity against before-and-after advertising claims, which elevates compliance costs for sub-scale operators and accelerates consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic System Deployment | Yonghe and Barley chains standardize FUE outcomes while justifying per-graft pricing premiums in Shanghai corridors. |
| PRP Therapy Integration | Quarterly refresh protocols at Jiahua Hospital generate recurring revenue and consumable attachment economics. |
| Surgeon Training Academy | Accredited programs address 2,000-graft experience bottlenecks that constrain clinic expansion velocity. |
| Second-Tier City Expansion | Chengdu and Wuhan penetration captures brand positioning before disposable income growth saturates supply. |
| SAMR Compliance Investment | Institutional review board partnerships generate defensible outcome data under tightened advertising enforcement. |
Research Methodology
Bottom-up aesthetic center volume modeling reconciled against top-down NMPA device registration tracking forms the analytical core of this study. Primary interviews with hair transplant surgeons, aesthetic chain operations directors, NMPA regulatory consultants, and PRP consumable procurement managers combined with secondary validation from SAMR enforcement bulletins, MEE environmental compliance filings, hospital procurement databases, and medical device import customs records. Triangulation between procedure volume estimates and capital equipment deployment rates verified market sizing assumptions.
Input-output matrices across procedure type, technology selection, end-user channel, and age cohort segmentation drove volume and value outputs over the projection horizon. CAGRs derived from fitted growth curves applied to urban professional demographic expansion and disposable income elasticity estimates. Industry-specific forecast inputs included FUE graft survival rate improvements, robotic system penetration assumptions, and PRP session frequency protocols at premium Yangtze River Delta operators.
Inputs from NMPA registration databases and aesthetic center operational disclosures were available through the study window; gaps in independent clinic financial reporting introduce uncertainty bands around market concentration estimates. Forecasts reflect documented assumptions regarding regulatory pathway stability and surgeon training program expansion rates. SAMR advertising enforcement intensity and MEE biomedical waste cost inflation represent specific risk factors that could revise trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
UK Hair Transplant Market