
 Child Care Services Market | 2026-2036
Child Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Child Care Services Market Analytics
Asset-light franchising and third-party facility leasing is tilting competitive economics toward operators that avoid direct real estate ownership. KinderCare Learning Companies leverages its national footprint to negotiate favorable lease terms across multiple states. The Learning Experience sustains brand consistency through standardized curriculum modules delivered via franchise partners. Busy Bees North America anchors its expansion model on management contracts rather than property acquisition.
Child care services encompass supervised developmental, educational, and custodial programs for children from infancy through school age, typically delivered in licensed facilities meeting state-mandated square-footage per child, staff qualification minima, and curriculum frameworks aligned to early learning standards. The primary commercial purpose is enabling parental labor force participation while supporting cognitive, social, and physical development during formative years. Center-based delivery dominates value capture due to economies of scale in staffing and regulatory compliance, while hybrid models that blend in-person care with digital parent engagement tools represent the fastest-expanding delivery mode. Nanny services occupy a premium price tier serving high-income households seeking individualized attention, whereas after-school care segments compete on convenience proximity to elementary campuses.
US state licensing boards, the Office of Child Care within the Administration for Children and Families, and local health departments collectively shape market access through facility inspections, background check mandates, and curriculum accreditation requirements. The EPA and OSHA extend influence through indoor air quality standards and workplace safety rules affecting staff retention costs. Stakeholders must monitor pending federal child care subsidy expansions and state-level pre-K universalization proposals that would redraw reimbursement mechanics and competitive positioning across delivery modes.
Market Dynamics
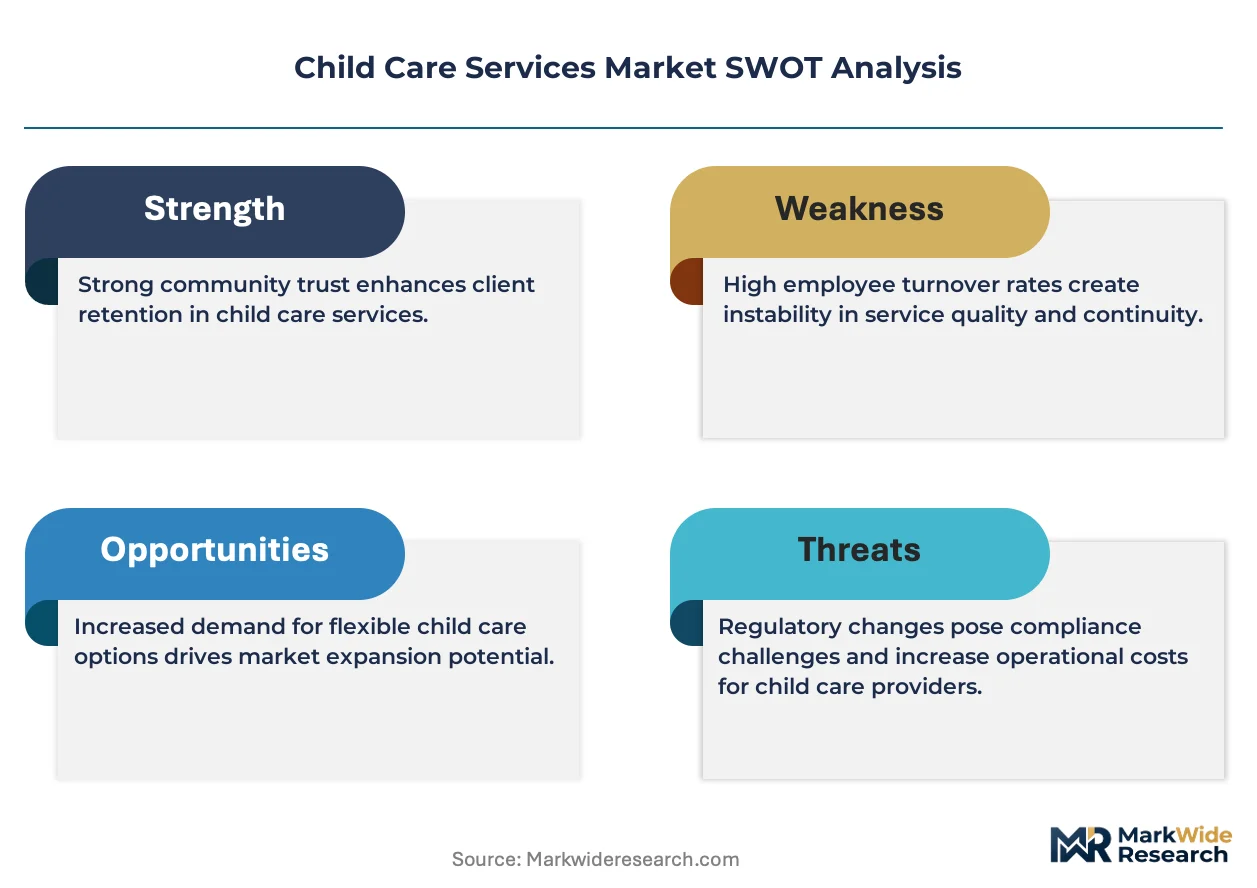
Dual-income household expansion is compressing demand cycles for licensed child care slots while tightening staff-to-child ratio mandates under the Child Care and Development Block Grant reauthorization reshape facility economics across the United States.
Growth Catalysts
- Labor Force Participation:Female workforce re-entry rates in Texas and California metropolitan corridors are driving wait-list accumulation for center-based slots.
- Curriculum Accreditation:State-level pre-K universalization proposals in Illinois and New York are expanding reimbursable service categories for licensed operators.
- Technology Integration:Digital parent engagement platforms are reducing administrative overhead while improving retention metrics for franchise networks.
Market Restraints
- Wage Compression:Early childhood educator minimum wage mandates in Massachusetts and Washington are squeezing operating margins without proportional fee elasticity.
- Real Estate Concentration:Facility leasing costs in urban California corridors consume disproportionate revenue share versus suburban Texas markets.
- Regulatory Fragmentation:Inconsistent square-footage per child requirements across state licensing boards complicate multi-state expansion templates.
Strategic Opportunities
- Employer-Sponsored Care:Corporate on-site and near-site facility partnerships with Fortune 500 campuses represent underpenetrated B2B channels.
- Hybrid Delivery Models:Blended in-person care with asynchronous developmental content creates subscription revenue streams beyond hourly billing.
- Infant Care Expansion:Sub-12-month programming carries premium pricing power and lower competitive density in most metropolitan statistical areas.
Industry Challenges
- Credential Pipeline:CDA (Child Development Associate) certification completion rates lag program expansion timelines in high-growth counties.
- Background Check Latency:FBI fingerprint processing delays in several state systems extend staff onboarding beyond regulatory minimums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Care Services Market |
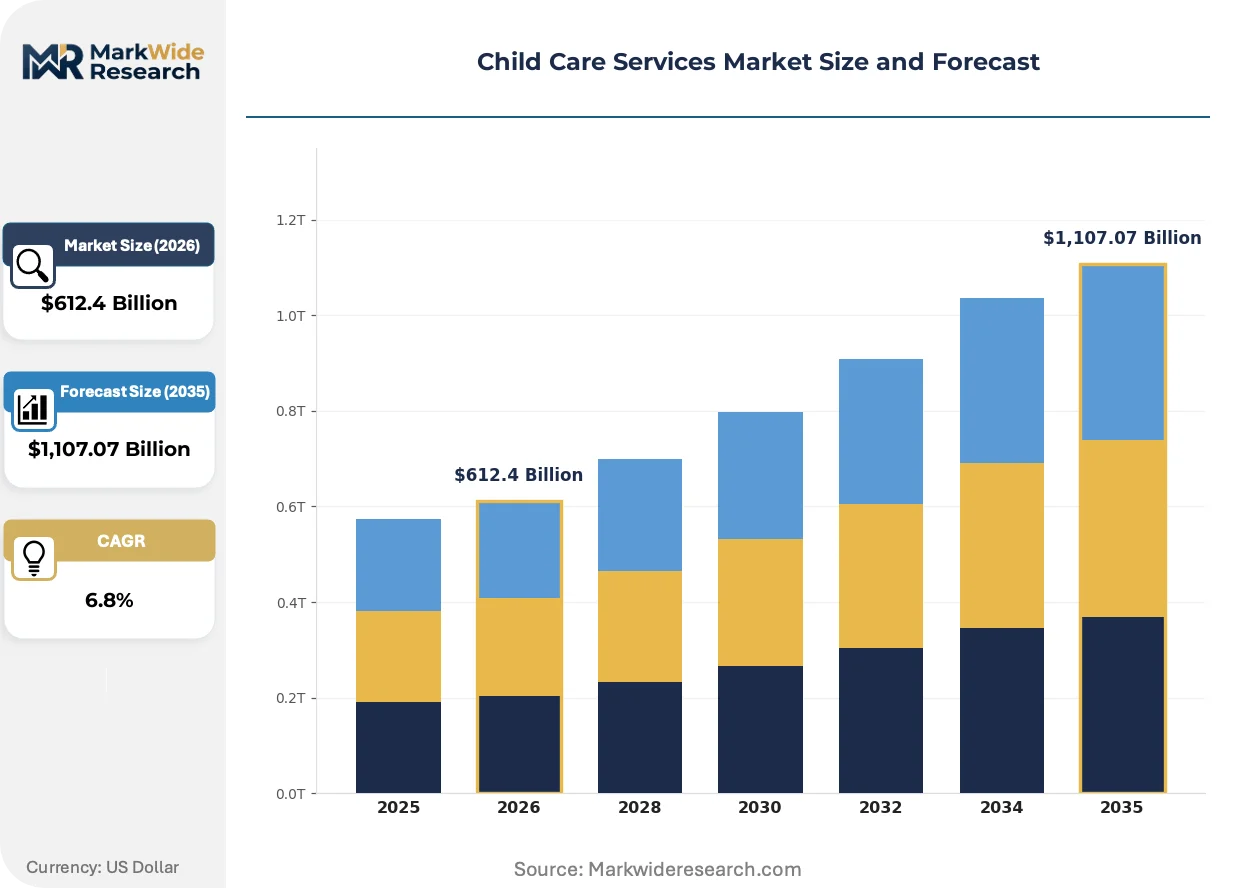
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare, Preschool, Nanny Services, After-school Care Age Group: Infants, Toddlers, Preschoolers, School-age Delivery Mode: In-home, Center-based, Hybrid, Online Payment Structure: Hourly, Weekly, Monthly, Annual |
| Companies Covered | Childcare Network, The Learning Experience, KinderCare Learning Companies, Busy Bees North America, Kiddie Academy, Learning Care Group, Child Development Schools, Sunshine House, Cadence Education, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Care Services Market Evolving Landscape
Operational technology is compressing administrative burdens while regulatory pressure intensifies around developmental outcome documentation and workforce credentialing standards.
Child care management software is digitizing enrollment workflows, billing reconciliation, and developmental milestone tracking into unified platforms. Center-based operators in Florida and Georgia are deploying these systems fastest, with franchise networks mandating standardized dashboards across locations. This consolidation is digitizing back-office functions previously handled through paper-based state reporting systems, freeing director-level staff for classroom quality oversight.
The US Child Care and Development Block Grant reauthorization tightens staff qualification documentation and safety inspection frequencies. Facility operators must now maintain continuous compliance records accessible to state licensing boards and the Office of Child Care within 48-hour windows. Center-based providers in high-growth Texas corridors are responding by hiring dedicated compliance officers, a role previously bundled under site director responsibilities.
Employer-sponsored child care benefits are displacing direct consumer payment as the primary access mechanism in technology and healthcare sectors. Large employers in Seattle, Austin, and Boston are contracting directly with center networks for guaranteed slot allocations, bypassing traditional individual wait-list dynamics. This channel shift concentrates purchasing power with benefits administrators rather than parent consumers, altering pricing negotiation leverage for multi-site operators.
Child Care Services Market Segmentation
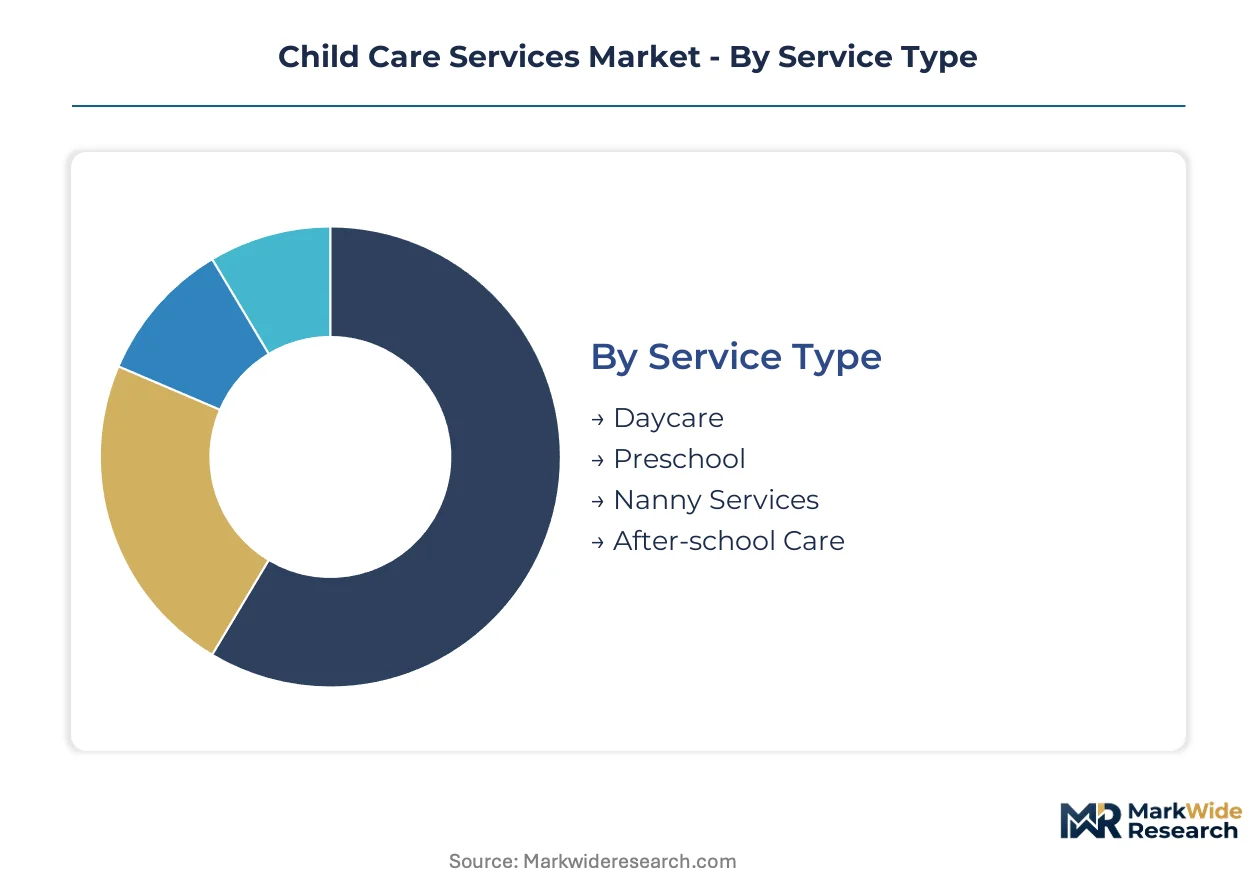
Segmentation in child care services determines facility design, staffing ratios, and regulatory compliance pathways. Operators configure capacity and curriculum differently across service types, age brackets, and delivery modes. Payment structures directly shape cash flow predictability and customer retention mechanics.
Service Type:
Cost tier differentiation separates licensed facilities from premium individualized services, with reimbursement eligibility varying sharply across categories.
- Daycare:Licensed facilities provide supervised custodial care for extended daily hours, typically operating under state-mandated staff-to-child ratios and square-footage minimums. Demand concentrates in Texas and California metropolitan corridors where dual-income household density compresses wait-list cycles for center-based slots.
- Preschool:Structured early learning programs emphasize developmental curricula aligned to state pre-K standards, often requiring lead teachers with CDA certification or equivalent credentials. Illinois and New York universalization proposals are expanding reimbursable service categories for licensed preschool operators, redirecting subsidy flows toward accredited providers.
- Nanny Services:In-home individualized care commands premium pricing tiers serving high-income households seeking flexible scheduling and personalized attention.
- After-school Care:Convenience-driven programming competes on proximity to elementary campuses, with enrollment tied to school district calendars and transportation logistics.
Daycare commands the established base. The steepest expansion runs through Preschool as state funding mechanisms broaden.
Age Group:
Application requirements intensify for younger cohorts, with infant programming carrying the strictest regulatory oversight and highest staffing costs.
- Infants:Sub-12-month programming requires dedicated feeding protocols, safe sleep compliance, and specialized caregiver training under OSHA workplace safety rules. Massachusetts and Washington minimum wage mandates for early childhood educators squeeze operating margins disproportionately in this labor-intensive segment.
- Toddlers:Mobile children aged 12-36 months transition from individual care routines to small-group activities, demanding modified facility layouts with enhanced supervision densities.
- Preschoolers:Children aged 3-5 years access structured curriculum modules delivered through franchise-standardized programming or independent center-based models.
- School-age:Kindergarten-through-elementary cohorts require homework assistance and enrichment activities rather than foundational developmental programming.
Preschoolers command the established base. Infants are gaining share fastest due to premium pricing power and competitive whitespace.
Delivery Mode:
Volume scalability varies dramatically between asset-light distributed models and fixed-capacity center-based operations.
- Center-based:Licensed facilities achieve economies of scale in staffing compliance and curriculum delivery, dominating value capture across metropolitan statistical areas. Florida and Georgia operators are deploying unified management software fastest, digitizing enrollment workflows and developmental milestone tracking across multi-site networks.
- Hybrid:Blended in-person care with asynchronous developmental content and digital parent engagement tools creates subscription revenue streams beyond hourly billing structures.
- In-home:Individual caregivers operate under reduced regulatory burdens in most jurisdictions, serving niche demand for personalized scheduling.
- Online:Remote developmental content and virtual parent coaching represent emerging supplemental channels rather than primary care substitutes.
Center-based commands the established base. Hybrid delivery is climbing the fastest as technology integration reduces administrative overhead.
Payment Structure:
Customer type and purchasing context determine preference for predictability versus flexibility in billing arrangements.
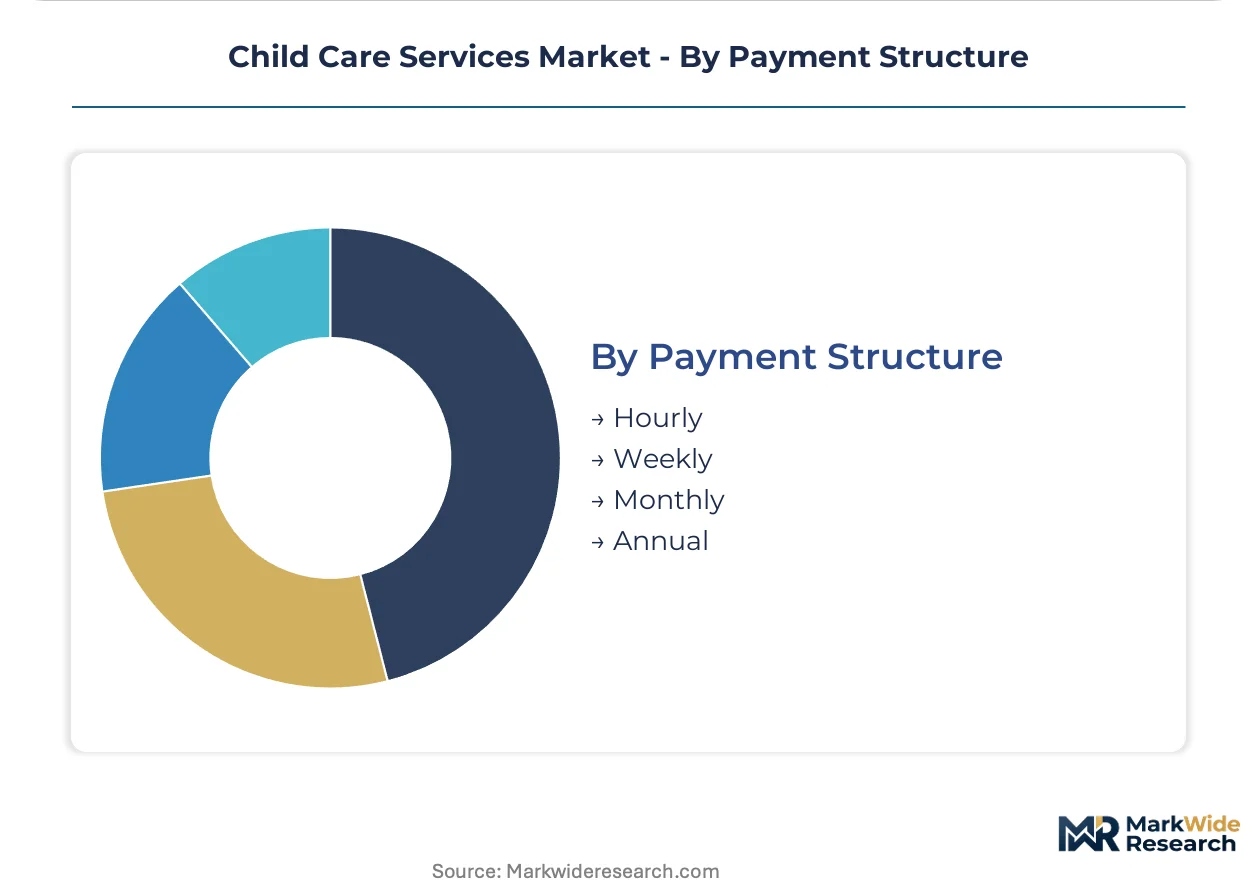
- Monthly:Recurring subscription billing dominates employer-sponsored benefit channels, with Fortune 500 benefits administrators in Seattle, Austin, and Boston contracting directly for guaranteed slot allocations.
- Annual:Prepaid enrollment packages lock in capacity commitments and improve cash flow visibility for multi-site operators managing lease obligations.
- Weekly:Short-cycle billing accommodates seasonal workforce fluctuations and irregular parental scheduling in hospitality and retail sectors.
- Hourly:Drop-in arrangements serve intermittent demand but complicate staffing ratios and regulatory compliance documentation.
Monthly commands the established base. Annual contracts are expanding most quickly as corporate partnerships concentrate purchasing power with benefits administrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility lease rates in urban California corridors consume revenue shares nearly double those in suburban Texas markets, creating a pricing-power asymmetry that reshapes operator economics across North American metropolitan clusters.
United States
Dual-income household density in Dallas-Fort Worth and Houston compresses wait-list cycles for center-based slots. The Child Care and Development Block Grant reauthorization tightens staff-to-child ratios and documentation requirements. Texas operators respond by hiring dedicated compliance officers, a role previously bundled under site director responsibilities.
Canada
Provincial universal pre-K expansion in Ontario and British Columbia redirects subsidy flows toward accredited providers. Health Canada and provincial licensing boards mandate continuous compliance records accessible within 48-hour windows. Toronto and Vancouver metropolitan areas concentrate employer-sponsored benefit contracting with Fortune 500 benefits administrators.
Germany
Female workforce re-entry rates in Bavaria and North Rhine-Westphalia drive demand for extended-hours programming. The KfW development bank finances facility expansion through low-interest municipal loans. Munich and Frankfurt operators deploy unified management software fastest, digitizing enrollment workflows across multi-site networks.
United Kingdom
London and Southeast England concentrate premium nanny services serving high-income households seeking flexible scheduling. Ofsted inspection frequencies intensify around developmental outcome documentation. Birmingham and Manchester center-based operators respond by standardizing curriculum modules through franchise partnerships.
Australia
Child Care Subsidy program reforms in New South Wales and Victoria expand reimbursable service categories for accredited operators. The Australian Children's Education and Care Quality Authority tightens workforce credentialing standards. Sydney and Melbourne metropolitan corridors concentrate hybrid delivery adoption, blending in-person care with digital parent engagement tools.
Child Care Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in curriculum design and facility management. The vendor base organizes around three strategic archetypes: national franchise networks leveraging lease negotiation scale, regional center operators optimizing for local regulatory compliance, and employer-sponsored benefit administrators concentrating purchasing power. Dominant competitive moves include asset-light expansion through management contracts and technology integration reducing administrative overhead.
Within the national franchise tier, KinderCare Learning Companies and The Learning Experience exemplify platform-scale operators, while Busy Bees North America occupies a position emphasizing management contracts over property acquisition. These three entities represent contrasting geographic footprints and capital deployment strategies without altering the underlying competitive structure.
| Leading Market Players |
|---|
| Childcare Network |
| The Learning Experience |
| KinderCare Learning Companies |
| Busy Bees North America |
| Kiddie Academy |
| Learning Care Group |
| Child Development Schools |
| Sunshine House |
| Cadence Education |
| Others |
Value Network & Pricing Analysis
Dallas-Fort Worth and Houston metropolitan clusters concentrate center-based capacity expansion, compressing wait-list cycles and amplifying pricing power for licensed operators against fragmented in-home alternatives. This supply concentration interacts with wage mandates in coastal states to create a bifurcated cost structure across the national footprint.
Pricing Analysis
The customization-premium spread separates standardized center-based hourly billing from employer-sponsored guaranteed slot contracts. Three-tier pricing structure across premium, standard, and economy levels reflects staff qualification tiers under CDA certification pathways and state licensing board accreditation status. Pricing pressure stems from early childhood educator minimum wage mandates in Massachusetts and Washington squeezing operating margins without proportional fee elasticity. Employer-sponsored benefits administrators exhibit lowest price sensitivity, while hourly drop-in consumers face highest cost consciousness.
Supply Chain Analysis
Upstream feedstock for facility operations draws from commercial real estate leasing markets in Texas, California, and Florida, with curriculum content and child development training modules sourced from national accreditation bodies and franchise networks. Critical inputs include facility square footage meeting state-mandated per-child minimums, CDA-certified staffing pipelines, and digital parent engagement platforms. Single-source vulnerability concentrates in FBI fingerprint processing systems extending staff onboarding timelines. Distribution runs through franchise networks, management contract operators, and direct employer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as female workforce re-entry rates in Texas and California metropolitan corridors compress demand cycles for licensed slots. The recovery trajectory hinges on subsidy expansion mechanics rather than pure consumer discretionary recovery.
For Market Incumbents: Build regulatory compliance moats by hiring dedicated compliance officers previously bundled under site director responsibilities, responding to Child Care and Development Block Grant reauthorization documentation windows. Anchor capacity expansion in suburban Texas corridors where facility leasing costs consume lower revenue share than urban California markets. Vertical integration into curriculum design protects margin position against franchise royalty structures. For New Entrants and Emerging Players: Establish a beachhead in infant care programming where sub-12-month slots carry premium pricing power and lower competitive density across most metropolitan statistical areas. Target employer-sponsored benefit channels in Seattle, Austin, and Boston where Fortune 500 benefits administrators concentrate purchasing power. Deploy management contract models avoiding direct real estate ownership to compress capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-essential infrastructure play because dual-income household expansion sustains structural demand regardless of cyclical consumer confidence fluctuations. Acquisition targets should screen for multi-site operators with standardized curriculum modules and unified management software deployment. Monitor state-level pre-K universalization proposal passage as inflection signal for subsidy flow redirection toward accredited providers.| Strategic Initiative | Industry Significance |
|---|---|
| Employer-Sponsored Partnership | Fortune 500 benefits administrators in Austin and Boston concentrate guaranteed slot purchasing power outside traditional consumer channels. |
| Hybrid Delivery Integration | Blended in-person care with asynchronous developmental content creates subscription revenue streams beyond hourly billing structures. |
| Infant Care Expansion | Sub-12-month programming commands premium pricing with reduced competitive density in Dallas-Fort Worth and Houston corridors. |
| Compliance Infrastructure Investment | Dedicated compliance officer roles respond to 48-hour documentation windows under Child Care and Development Block Grant reauthorization. |
| Management Contract Scaling | Asset-light expansion through third-party facility leasing avoids capital intensity of direct real estate ownership. |
Research Methodology
A standing panel of center directors, franchise operations executives, state licensing board administrators, and employer benefits managers provided ongoing calibration across the study window. Primary interviews with these stakeholders combined with secondary validation against state child care subsidy databases, OSHA workplace safety filings, and Office of Child Care compliance records. Bottom-up facility capacity modeling and top-down household demand estimation were triangulated for convergence.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions including service type, age group, delivery mode, and payment structure. CAGRs were derived from enrollment velocity trends, regulatory capacity constraints, and subsidy expansion mechanics. Forecast inputs incorporated staff-to-child ratio mandate changes, real estate lease rate trajectories, and digital platform adoption curves.
Stress conditions across educator wage mandate acceleration, subsidy appropriation volatility, and real estate cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about labor force participation trajectories and regulatory implementation timelines. Cross-checking against state licensing board capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Digital English Language Learning Market
Education & Training
Vocational English Course Counselling Solution Market
Education & Training
Early Childhood Education Market
Education & Training
US Child Care Market
Education & Training
Global Learning Management Systems (LMS) Market
Education & Training
English Learning App Market
Education & Training
Poland Higher Education Market
Education & Training
Student Response System Market
Education & Training
Leadership Development Program Market
Education & Training
UAE Private K12 Education Market
Education & Training
Global Digital Education Market
Education & Training
Back to School Market
Education & Training
Frontline Workers Training Market
Education & Training
School ERP Software Market
Education & Training
North America Digital Education Market
Education & Training
E-Learning Market