
 School ERP Software Market | 2026-2036
School ERP Software Market Size, Share, and Industry Trends Forecast 2026-2036
School ERP Software Market Insights
The EU Green Deal is repositioning procurement criteria for educational technology across European institutional buyers, compelling vendors to demonstrate energy-efficient cloud infrastructure and carbon-transparent supply chains. SAP SE leverages its extensive enterprise architecture to anchor institutional clients seeking unified finance and HR modules. Oracle Corporation sustains competitive pressure through database-centric ERP stacks that dominate large university deployments. Microsoft Corporation extends its education cloud ecosystem by integrating Teams and Azure Active Directory into school administrative workflows.
School ERP software constitutes an integrated information system that centralizes academic, financial, and operational data management for educational institutions, typically featuring role-based access controls, API-driven interoperability with learning management systems, and real-time dashboard analytics for administrative decision-making. Cloud-based deployment leads segment adoption as districts abandon capital-intensive on-premise server maintenance, while hybrid architectures retain traction among institutions with legacy infrastructure dependencies. Multi-tenant SaaS configurations represent the fastest-growing deployment category, enabling vendors to achieve economies of scale while reducing per-customer provisioning costs.
GDPR in Europe, FERPA in the United States, and India's DPDP Act collectively tighten consent frameworks and cross-border data transfer rules governing student information systems, forcing ERP vendors to regionalize data residency and encryption standards. ISO 27001 certification has become a baseline procurement filter rather than a differentiator in institutional RFP processes. Stakeholders must monitor how generative AI integration into attendance prediction and personalized learning pathways triggers novel liability exposures under emerging algorithmic accountability regimes.
Market Dynamics
Cloud migration is compressing capital expenditure cycles for K-12 districts while the EU AI Act imposes algorithmic accountability requirements on predictive analytics modules embedded in student information systems.
Growth Catalysts
- FERPA Compliance Mandates:US school districts face audit pressure to modernize data governance, accelerating replacement of legacy on-premise systems with encrypted cloud architectures that automate consent management and audit trails.
- India's Digital Attendance Directives:State education boards in Maharashtra, Karnataka, and Uttar Pradesh now mandate biometric or RFID-based attendance tracking, forcing thousands of private and government schools to procure integrated ERP modules.
- API Interoperability Standards:Learning Management System vendors are opening RESTful endpoints that enable real-time gradebook synchronization, compelling ERP providers to build connector ecosystems or lose procurement bids.
Market Restraints
- Cross-Border Data Localization:India's DPDP Act and GDPR's Schrems II rulings force vendors to maintain sovereign data centers, fragmenting infrastructure economics and raising per-deployment costs for multi-national providers.
- Legacy Infrastructure Lock-In:Rural districts in the US Midwest retain on-premise servers due to unreliable broadband, constraining SaaS penetration and forcing vendors to maintain parallel codebases.
- Substitution by Free Tier Products:Google Workspace for Education and Microsoft's no-cost school offerings capture basic administrative workflows, compressing pricing power for standalone ERP vendors at the entry tier.
Strategic Opportunities
- Generative AI Tutoring Convergence:Large language models integrated into ERP portals enable personalized learning pathway recommendations, creating upsell potential beyond administrative functions into instructional technology budgets.
- Indonesia's Digital Education Roadmap:The Ministry of Education's 2023-2030 masterplan mandates national student ID interoperability, opening procurement windows for ERP vendors with localized Bahasa Indonesia interfaces and Sharia-compliant fee modules.
- Subscription-to-Outcome Pricing:Vendors can pilot performance-based contracts tied to measurable administrative efficiency gains—reduced fee collection cycles, faster transcript turnaround—aligning vendor revenue with district KPIs.
Industry Challenges
- ISO 27001 Certification Bottlenecks:The 12-18 month audit timeline delays market entry for mid-size vendors, ceding early-mover advantage to incumbents with existing certification portfolios.
- Interoperability Tax:Each LMS, SIS, and state reporting system demands custom API development, consuming 25-40% of engineering capacity and fragmenting product roadmaps across customer segments.
- Cybersecurity Talent Scarcity:School districts lack internal expertise to evaluate zero-trust architecture claims, extending sales cycles and requiring vendors to absorb implementation risk through managed security service bundles.
Report Scope
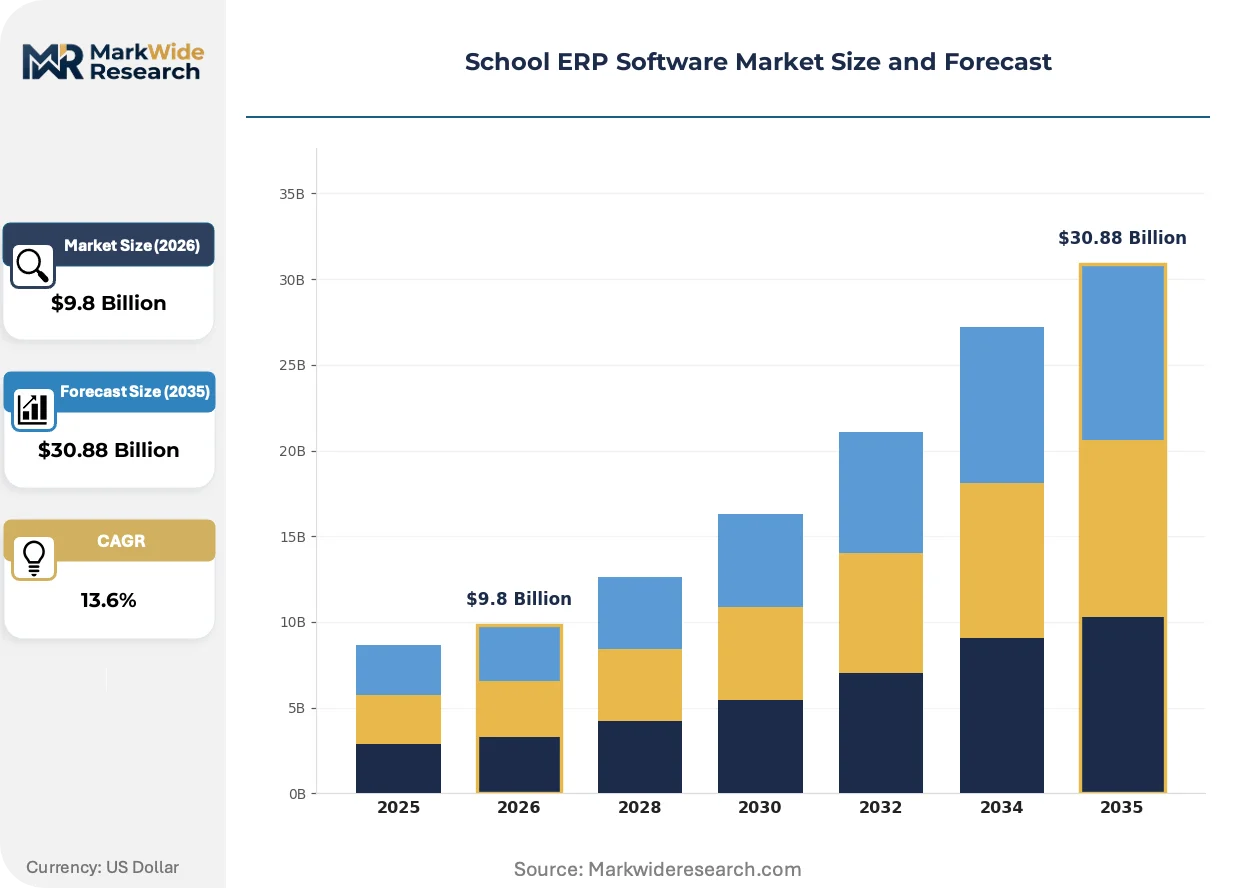
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School ERP Software Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.88 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Open Source End User: K-12 Schools, Colleges, Universities, Vocational Institutions Functionality: Fee Management, Admission Management, Attendance Tracking, Learning Management Deployment: Single Tenant, Multi-Tenant, SaaS, Private Cloud |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, PowerSchool Holdings, Inc., Ellucian Company L.P., Blackboard, Skyward, Tyler Technologies, Instructure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School ERP Software Market Trends and Innovations
Artificial intelligence is penetrating core administrative workflows while regulatory frameworks harden around student data processing, and procurement authority centralizes at state and federal levels away from individual campuses.
Machine learning attendance prediction algorithms are automating early-warning systems for chronic absenteeism. Districts in Texas and Florida are deploying these modules district-wide following pilot programs. The technology is automating counselor workload prioritization by flagging at-risk students before manual review thresholds trigger.
The EU AI Act's risk classification system categorizes student emotion recognition and biometric identification as high-risk applications. Vendors must now submit conformity assessments and maintain human-in-the-loop oversight for predictive disciplinary analytics. European deployments are responding by stripping affective computing features from standard modules and offering them as separately contracted add-ons with explicit opt-in workflows.
Consolidated state-level purchasing cooperatives are displacing individual district RFP processes. Texas Education Agency's cooperative contracts and California's K-12 High Speed Network now aggregate demand across hundreds of districts, compressing vendor sales cycles but demanding steeper volume discounts and standardized feature sets. This concentration is most visible in the southeastern United States where state digital learning plans centralize ERP procurement decisions at the department of education level rather than local school board authority.
School ERP Software Market Segmentation
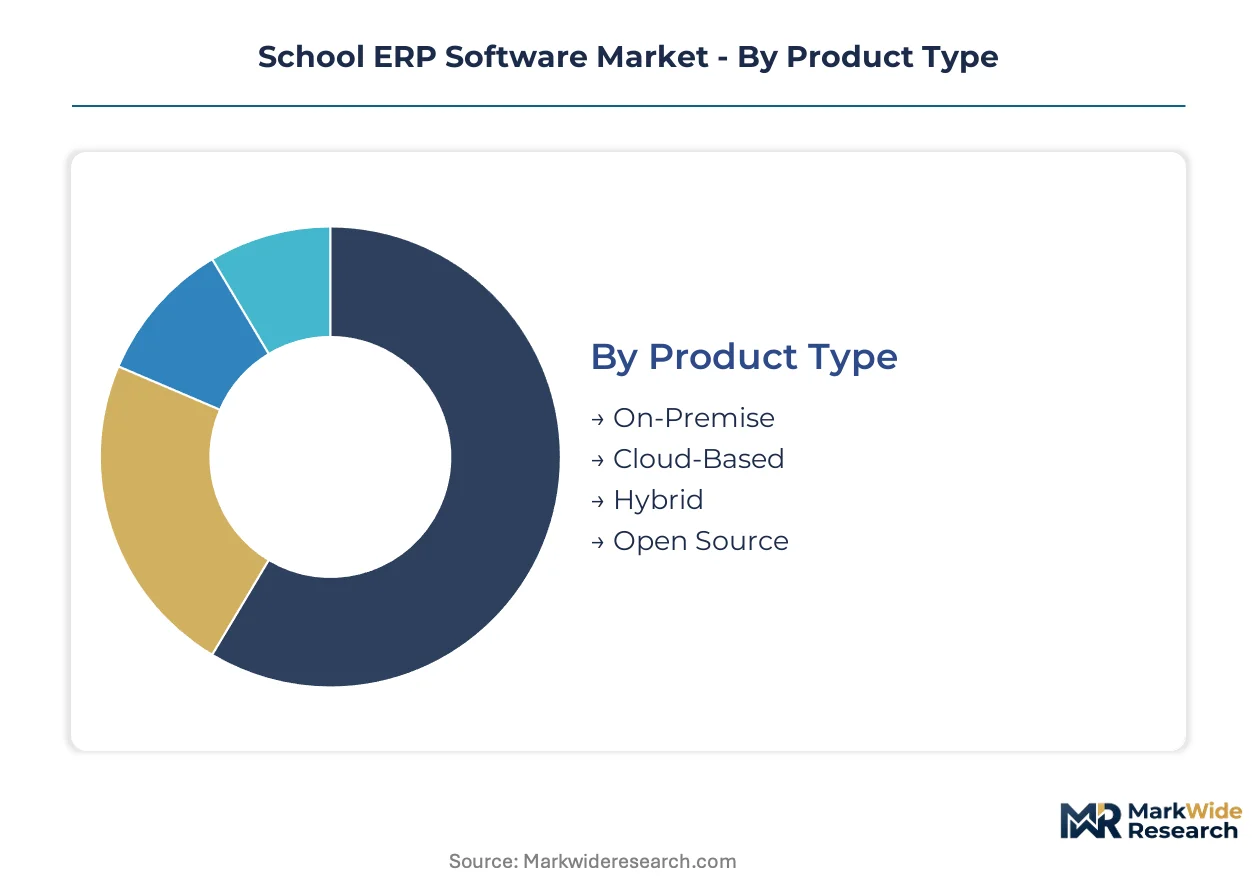
Segmentation in school ERP software reveals how procurement authority, technical architecture, and regulatory exposure reshape vendor strategy. Districts and universities select configurations based on legacy infrastructure, compliance jurisdiction, and whether administrative or instructional modules dominate their digital transformation priorities.
Product Type:
Integration depth varies sharply across deployment models, with standalone systems serving rural districts lacking IT staff while embedded platforms feed data lakes for predictive analytics.
- On-Premise:Server infrastructure resides within institutional data centers, requiring dedicated IT personnel for patch management and backup protocols. US Midwest rural districts retain this architecture due to unreliable broadband infrastructure, constraining SaaS migration despite higher total cost of ownership.
- Cloud-Based:Multi-tenant SaaS configurations eliminate capital expenditure cycles and automate security updates through vendor-managed infrastructure. Maharashtra and Karnataka state education boards in India mandate cloud attendance modules, accelerating district-wide procurement of browser-native platforms.
- Hybrid:Core financial data remains on-premise while student-facing modules migrate to cloud tiers, accommodating FERPA audit requirements without full infrastructure replacement.
- Open Source:Community-developed codebases like Fedena and OpenEduCat enable customization for niche regulatory environments, particularly among European vocational institutions seeking GDPR-compliant self-hosting.
Cloud-based configurations lead volumes today; hybrid deployments are gaining share fastest among institutions with legacy dependencies.
End User:
Cost tier segmentation separates capital-constrained K-12 districts from research-intensive universities with dedicated procurement offices.
- K-12 Schools:District-wide deployments emphasize attendance automation, fee transparency, and parent portal integration. Texas Education Agency cooperative contracts aggregate demand across hundreds of districts, compressing vendor pricing power.
- Colleges:Admissions pipeline management and alumni relationship modules dominate functionality requirements. Indonesian private colleges under the Digital Education Roadmap drive localized Bahasa interface development.
- Universities:Research grant administration, HR payroll integration, and multi-campus consolidation justify premium ERP stacks. Oracle database-centric architectures retain dominance in large university deployments.
- Vocational Institutions:Shorter program cycles demand accelerated transcript turnaround and industry partnership tracking. EU Green Deal procurement criteria prioritize energy-efficient cloud infrastructure for these publicly funded entities.
K-12 Schools anchor current revenue concentration; Vocational Institutions show steepest expansion trajectory under national digital education mandates.
Functionality:
Application maturity separates commoditized administrative modules from emerging AI-enhanced instructional features.
- Fee Management:Automated collection cycles, payment gateway integration, and audit-ready ledger exports constitute baseline procurement requirements. India's DPDP Act mandates encryption standards for financial student data, forcing vendors to regionalize hosting.
- Admission Management:Document verification workflows, enrollment forecasting, and waitlist automation reduce registrar office staffing needs. Uttar Pradesh state board digitization directives expand addressable market for these modules.
- Attendance Tracking:Biometric and RFID systems generate early-warning feeds for chronic absenteeism intervention. EU AI Act risk classification strips emotion recognition from standard offerings, requiring explicit opt-in contracting.
- Learning Management:Gradebook synchronization, curriculum mapping, and outcome analytics bridge administrative and instructional technology budgets. RESTful API interoperability with Canvas and Blackboard determines procurement viability.
Fee Management dominates current deployment volumes; Learning Management is climbing the fastest as districts merge administrative and instructional technology budgets.
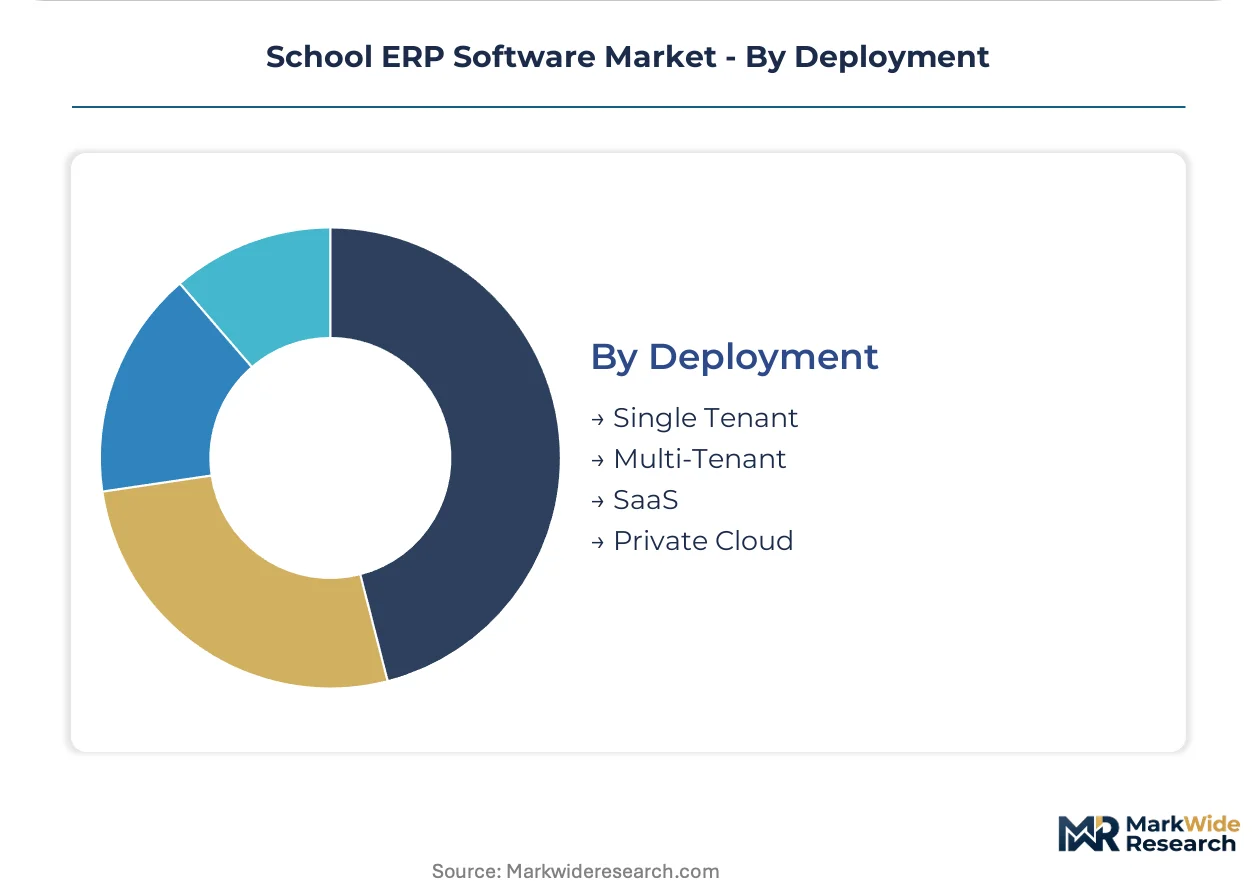
Deployment:
Customer type and margin profile separate single-district implementations from scaled multi-tenant architectures serving thousands of institutions.
- Single Tenant:Dedicated infrastructure instances serve large university systems or consolidated state contracts, permitting customization without neighbor noise. California's K-12 High Speed Network procurement operates at this scale.
- Multi-Tenant:Shared codebases with data isolation achieve vendor economies of scale while reducing per-customer provisioning costs. This configuration expands most quickly among mid-size US districts abandoning on-premise maintenance.
- SaaS:Browser-native delivery eliminates client-side installation and enables mobile-first parent engagement portals. Google's no-cost education offerings compress pricing power at this tier.
- Private Cloud:Sovereign data residency satisfies GDPR Schrems II rulings and India's DPDP Act localization mandates, fragmenting infrastructure economics for multinational providers.
Multi-Tenant architectures lead current adoption; Private Cloud is expanding most quickly under data sovereignty enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The school ERP software industry traces its commercial roots to the United States, where early mainframe-based student information systems emerged in the 1970s to manage exploding K-12 enrollment data. Cloud migration subsequently redistributed development gravity toward India and European compliance hubs, creating today's polycentric supply structure.
United States
Texas Education Agency cooperative contracts aggregate procurement across hundreds of districts, compressing vendor pricing power while accelerating cloud migration. FERPA audit pressure forces modernization of legacy on-premise systems with encrypted architectures. Dallas-Fort Worth and Austin metropolitan clusters host implementation specialists serving southwestern state digital learning plans.
India
State education boards in Maharashtra, Karnataka, and Uttar Pradesh mandate biometric attendance and fee transparency modules, creating immediate procurement windows. The Digital Personal Data Protection Act imposes encryption standards and cross-border transfer restrictions on student financial data. Bangalore and Hyderabad technology corridors concentrate vendor development centers building localized SaaS platforms.
Germany
Vocational institutions under federal-state education compacts drive demand for energy-efficient cloud infrastructure aligned with EU Green Deal procurement criteria. GDPR and the EU AI Act impose conformity assessments on predictive analytics modules. Munich and Stuttgart industrial regions anchor deployments integrating apprenticeship tracking with corporate HR systems.
Indonesia
The Ministry of Education's 2023-2030 Digital Education Roadmap mandates national student ID interoperability across 17,000 islands. Sharia-compliant fee modules and Bahasa Indonesia interfaces become baseline procurement requirements. Jakarta and Surabaya metropolitan areas concentrate pilot implementations for national rollout templates.
United Kingdom
Multi-academy trusts centralize procurement authority away from individual schools, favoring vendors with unified finance and HR modules. The Information Commissioner's Office enforces GDPR Schrems II rulings on cross-border data residency. London and Manchester education technology clusters host vendors serving both domestic academies and Commonwealth export markets.
School ERP Software Market Competitive Landscape
Capital-heavy enterprise software producers compete with asset-light SaaS specialists across deployment tiers, creating a bifurcated structure where database-centric stacks serve large universities and modular cloud-native platforms capture K-12 districts. The vendor base separates into three strategic archetypes: integrated enterprise suites, education-focused vertical specialists, and open-source community distributions. Dominant competitive moves include API ecosystem expansion to capture LMS interoperability contracts and geographic localization to satisfy data sovereignty mandates.
Within the integrated enterprise tier, SAP SE and Oracle Corporation exemplify database-centric architectures that retain dominance in large university deployments requiring unified finance and HR modules. Microsoft Corporation anchors the cloud-native vector, extending education ecosystems through Teams and Azure Active Directory integration into administrative workflows. PowerSchool Holdings, Inc. occupies a position among vertical specialists concentrating exclusively on K-12 student information systems.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| PowerSchool Holdings, Inc. |
| Ellucian Company L.P. |
| Blackboard |
| Skyward |
| Tyler Technologies |
| Instructure |
| Others |
Pricing and Supply Chain Analysis
Enterprise-grade certification tiers split procurement budgets from entry-level SaaS subscriptions, creating parallel supply chains where ISO 27001-audited vendors command premium pricing while commodity cloud providers compete on per-seat economics. This bifurcation concentrates margin capture among database-centric stack providers serving large university systems, while modular specialists absorb cost pressure from Google's no-cost education offerings and Microsoft's bundled administrative tools.
Pricing Analysis
Subscription-based SaaS licensing with volume-scaled per-seat tiers anchors vendor revenue models, with differentiation resting on FERPA audit automation depth and API connector ecosystem breadth. Google's Workspace for Education and Microsoft's no-cost school compressions squeeze standalone ERP margins at the entry tier, while Oracle and SAP sustain pricing power among research-intensive universities requiring unified finance-HR-research grant modules. District procurement officers exhibit acute price sensitivity in K-12 cooperative contracts, whereas university CIOs prioritize integration depth over per-seat cost.
Supply Chain Analysis
Freight costs for server hardware and edge computing equipment factor marginally into hybrid deployment economics, though cloud-native delivery eliminates physical logistics for pure-SaaS configurations. Development labor concentrates in India's Bangalore and Hyderabad technology corridors, with sales engineering clustered in Texas and California education procurement hubs. The supply chain draws from Ireland and Frankfurt for GDPR-compliant data center infrastructure, and rests on single-source vulnerability in NVIDIA GPU allocations for generative AI module training. Distribution runs through state-level purchasing cooperatives in Texas and California, bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
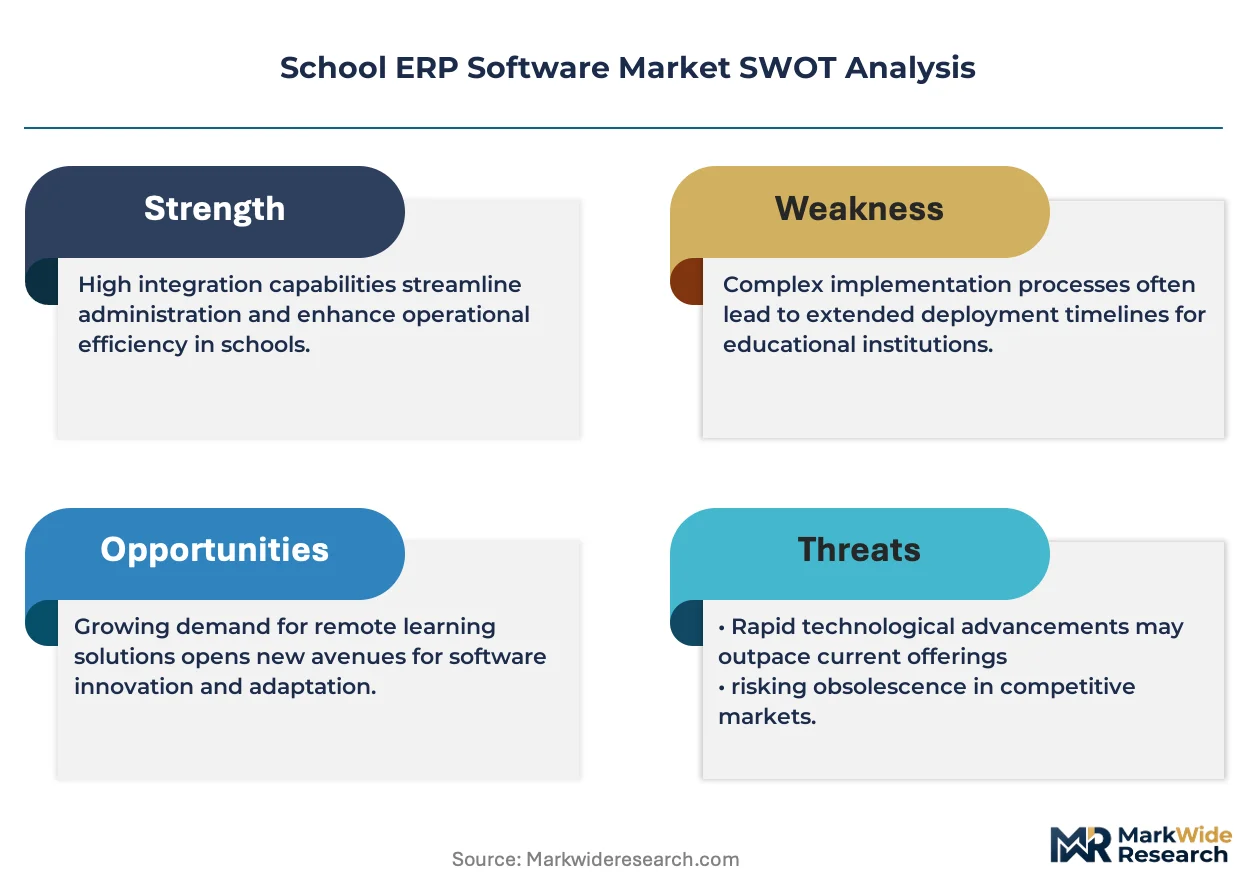
Vendors can exploit geographic arbitrage between India's DPDP Act-mandated data localization costs and the EU AI Act's conformity assessment burdens, positioning Singapore or UAE hosting as intermediate compliance zones with lower operational overhead.
For Market Incumbents: Acquire specialized API interoperability firms to lock in LMS connector ecosystems before RESTful standardization commoditizes integration layers. SAP and Oracle should deepen backward integration into sovereign cloud infrastructure to defend margin position against rising data residency compliance costs. Threat substitution from Google's education bundling demands counter-positioning through managed security service bundles that districts cannot replicate internally. For New Entrants and Emerging Players: Begin with Indonesia's Digital Education Roadmap procurement windows, where Bahasa Indonesia localization and Sharia-compliant fee modules create immediate addressable market before multinational incumbents adapt. Target vocational institutions under EU Green Deal procurement criteria, where energy-efficient cloud claims differentiate bids. A channel partnership with state digital learning agencies accelerates credentialing for cooperative contract eligibility. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size vendors face ISO 27001 certification bottlenecks that delay market entry against incumbent certification portfolios. Long-term viability favors platforms with generative AI tutoring convergence potential that captures instructional technology budgets beyond administrative modules. Watch for inflection where state-level purchasing cooperatives displace individual district RFP authority, compressing viable vendor counts.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | RESTful connectors with Canvas and Blackboard determine procurement viability in Texas cooperative contracts. |
| Geographic Localization | Bahasa Indonesia interfaces and Sharia-compliant modules unlock Indonesia's 2023-2030 Digital Education Roadmap. |
| Generative AI Integration | Personalized learning pathway recommendations capture instructional budgets beyond administrative ERP functions. |
| Sovereign Cloud Infrastructure | GDPR Schrems II and India's DPDP Act data residency mandates fragment infrastructure economics for multi-tenant providers. |
| Subscription-to-Outcome Pricing | Performance contracts tied to fee collection cycle reductions align vendor revenue with district KPIs in Maharashtra state mandates. |
Research Methodology
Direct dialogue with K-12 district CIOs, university procurement officers, ERP implementation specialists, and state education agency technology directors grounded qualitative assessments in operational reality. Secondary validation drew from FERPA audit disclosure databases, EU AI Act conformity assessment registries, India's DPDP Act implementation guidelines, and SEC filings of publicly traded education technology vendors. Bottom-up segment sizing triangulated against top-down education IT spending forecasts from national statistical offices.
Bottom-up modeling aggregated individual district and university procurement patterns across deployment model, institution size, and integration complexity dimensions, while top-down analysis calibrated aggregate spending against education technology budget surveys. CAGRs derived from fitted growth curves across the projection horizon, with cross-validation against historical cloud migration rates in comparable public sector verticals. Forecast inputs incorporated biometric attendance mandate rollout timelines in Indian state education boards and EU AI Act enforcement phase transitions.
Several conditions sit outside the modeled scope, including potential FERPA regulatory amendments, broadband infrastructure investment shocks affecting rural SaaS penetration, and generative AI liability frameworks that could recast vendor risk profiles. Forecasts reflect documented assumptions about procurement authority centralization and data sovereignty enforcement trajectories. Stakeholders should weight assumptions against their own operating context and regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
VR Education Market
Education & Training
Virtual Reality in Education Market
Education & Training
Leadership Development Program Market
Education & Training
Personal Development Market
Education & Training
Canada Executive Education Program Market
Education & Training
Flipped Classroom Market
Education & Training
E-Learning Services Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
K-12 Testing and Assessment Market
Education & Training
In-Person Learning Market
Education & Training
Higher Education Learning Systems Market
Education & Training
Asia-Pacific Management Consulting Services Market
Education & Training
Global Mechatronics and Robotics Courses Market
Education & Training
E-Learning Market
Education & Training
Edtech and Smart Classroom Market
Education & Training
Online Examination Service Market