
 Plastic Color Concentrates Market | 2026-2036
Plastic Color Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Color Concentrates Market Outlook
Automotive exterior and interior applications is expanding as lightweighting trends intensify polymer substitution for metal components. BASF SE leverages its pigment chemistry portfolio to serve tier-one automotive suppliers with heat-stable formulations. Clariant sustains leadership in halogen-free flame-retardant color concentrates for electric vehicle battery housings. Ampacet Corporation specializes in custom color matching for automotive OEM specification programs across multiple continents.
Plastic color concentrates are highly loaded dispersions of pigments or dyes in polymer carrier resins, typically containing 15-80% active colorant by weight, engineered for homogeneous distribution during melt processing. These concentrates enable precise color control while minimizing raw material waste and cleaning downtime in continuous production environments. Masterbatches dominate volume flows due to their compatibility across injection molding and extrusion platforms, while liquid concentrates capture specialized segments requiring rapid color changeovers in blow molding operations. Metallic and fluorescent color types command premium positioning in consumer goods and cosmetics packaging where shelf differentiation determines purchasing decisions.
REACH restrictions on heavy metal pigments and FDA Title 21 food-contact notifications govern formulation choices for suppliers serving European and North American end users. ECHA substance evaluations and state-level chemical disclosure laws in California are forcing reformulation investments toward organic and mineral pigment alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations that threaten certain performance additives commonly co-formulated with color concentrates.
Market Dynamics
REACH substance evaluations and FDA food-contact notifications are forcing simultaneous reformulation across European and North American supply chains, compressing product development cycles while expanding R&D budgets for compliant pigment alternatives.
Growth Catalysts
- Electric vehicle battery housings:Halogen-free flame-retardant color concentrates meet thermal management requirements as polymer substitution accelerates in automotive lightweighting programs.
- FDA Title 21 compliance:Food-contact material standards drive reformulation investments toward mineral and organic pigment systems for packaging applications.
- Germany's manufacturing base:Concentrated plastics processing capabilities sustain demand for high-precision masterbatch solutions in automotive and industrial sectors.
Market Restraints
- Titanium dioxide volatility:Raw material cost swings in white pigment feedstocks compress margins for standard color concentrate formulations.
- Heavy metal pigment phase-out:ECHA restrictions on cadmium and lead-based colorants force expensive reformulation without immediate price recovery mechanisms.
- Per- and polyfluoroalkyl substance regulations:Emerging restrictions on PFAS threaten performance additives commonly co-formulated with color concentrates.
Strategic Opportunities
- India's packaging sector:Underpenetrated demand for sustainable colorant solutions in food and beverage applications offers expansion potential for compliant suppliers.
- Recyclable black plastics:Near-infrared detectable color concentrates enable circular economy compliance as sorting infrastructure expands.
- PLI scheme incentives:India's production-linked incentive framework supports domestic manufacturing scale-up for polymer processing inputs.
Industry Challenges
- Color matching expertise:Shortage of formulation chemists with cross-polymer compatibility knowledge extends custom development timelines.
- Dual certification requirements:Simultaneous REACH and FDA compliance creates testing bottlenecks and documentation burdens.
- Legacy extrusion integration:Retrofitting continuous production lines for rapid color changeover demands capital-intensive equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Color Concentrates Market |
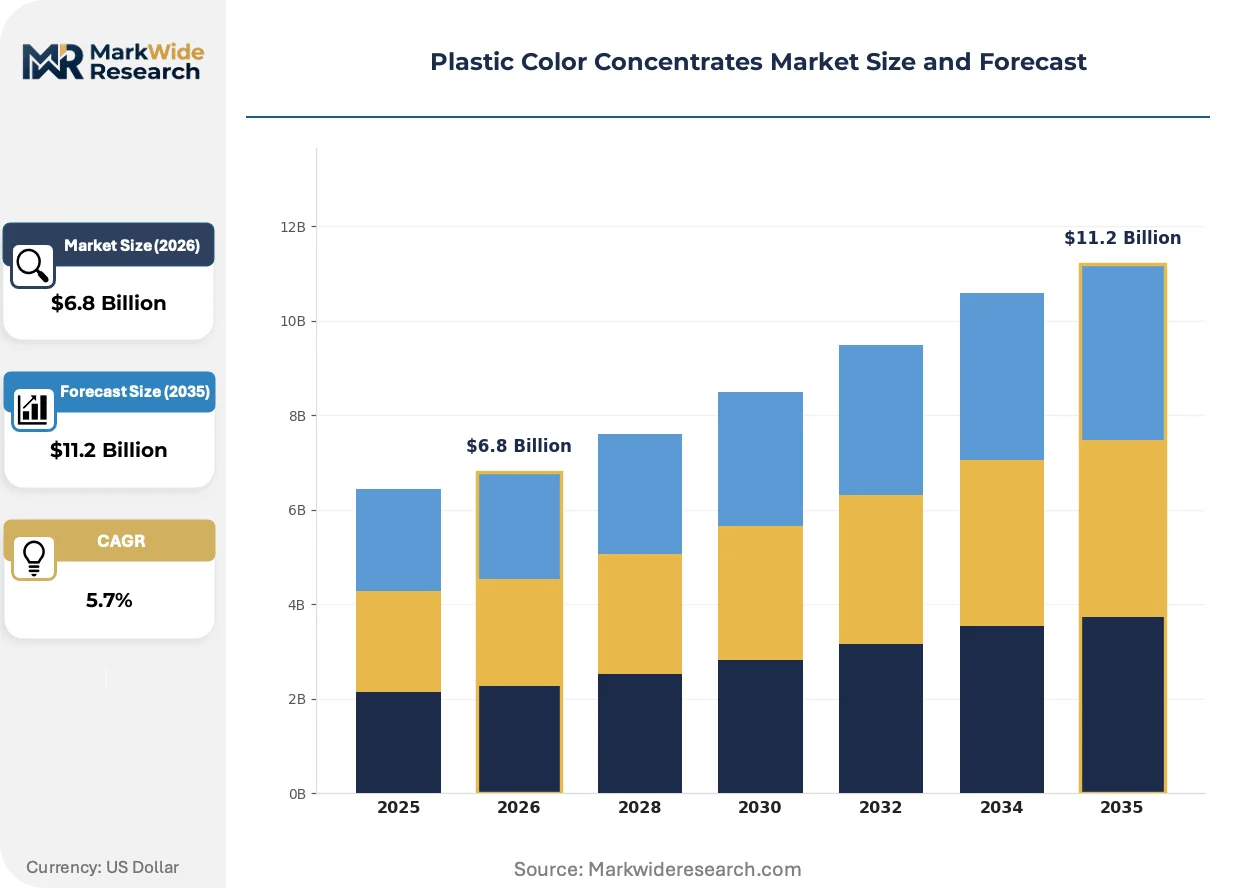
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masterbatches, Compounds, Liquid Concentrates, Powder Concentrates End User: Packaging, Automotive, Consumer Goods, Textiles Color Type: Opaque, Transparent, Metallic, Fluorescent Application: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | Clariant, BASF SE, LyondellBasell Industries Holdings B.V., Cabot Corporation, Ampacet Corporation, PolyOne Corporation, Avient Corporation, Ferro Corporation, Tosaf Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Color Concentrates Market Strategic Shifts
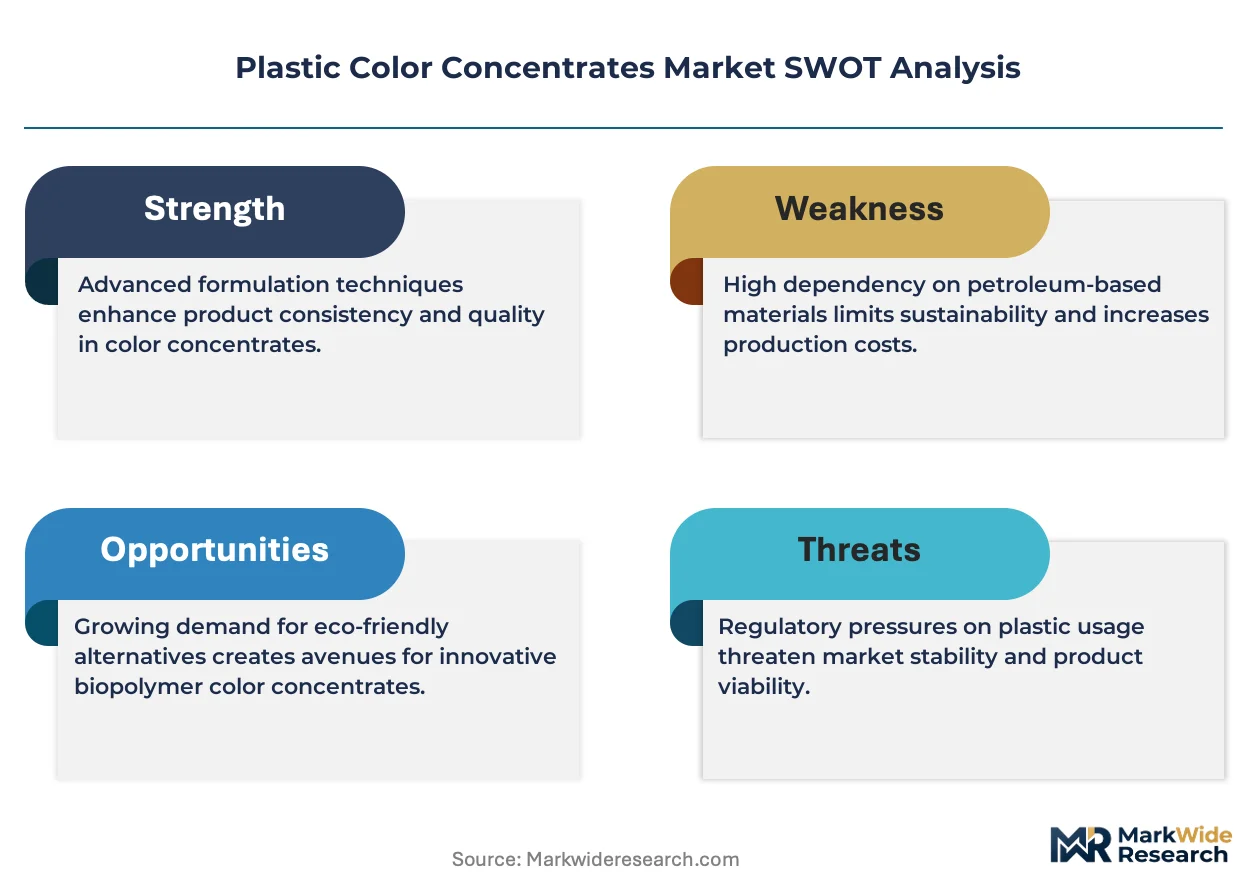
Formulation science and regulatory compliance are converging to reshape competitive capabilities, with pigment chemistry expertise becoming the primary differentiator as substance restrictions proliferate across jurisdictions.
Bio-based carrier resins are expanding into masterbatch formulations as processors seek Scope 3 emissions reductions. Automotive tier-one suppliers in Germany and packaging converters in India are piloting these systems at commercial scale. The technology is expanding into applications previously reserved for petroleum-derived carriers, though thermal stability limitations constrain adoption in high-temperature processing.
REACH authorization requirements for chromium-based pigments are eliminating legacy formulation options for outdoor durability applications. European compounders must now qualify complex inorganic color pigments or coated organic alternatives, extending qualification cycles by 12-18 months. The construction and agricultural equipment segments face the steepest reformulation costs as weathering performance standards tighten.
Direct compounder relationships are displacing distributor channels for volume buyers seeking technical integration support. Major packaging groups in Brazil and automotive OEMs in Germany now require on-site color laboratories and just-in-time delivery commitments. This consolidation of procurement decision-making favors suppliers with regional technical service infrastructure over commodity masterbatch traders.
Plastic Color Concentrates Market Segmentation
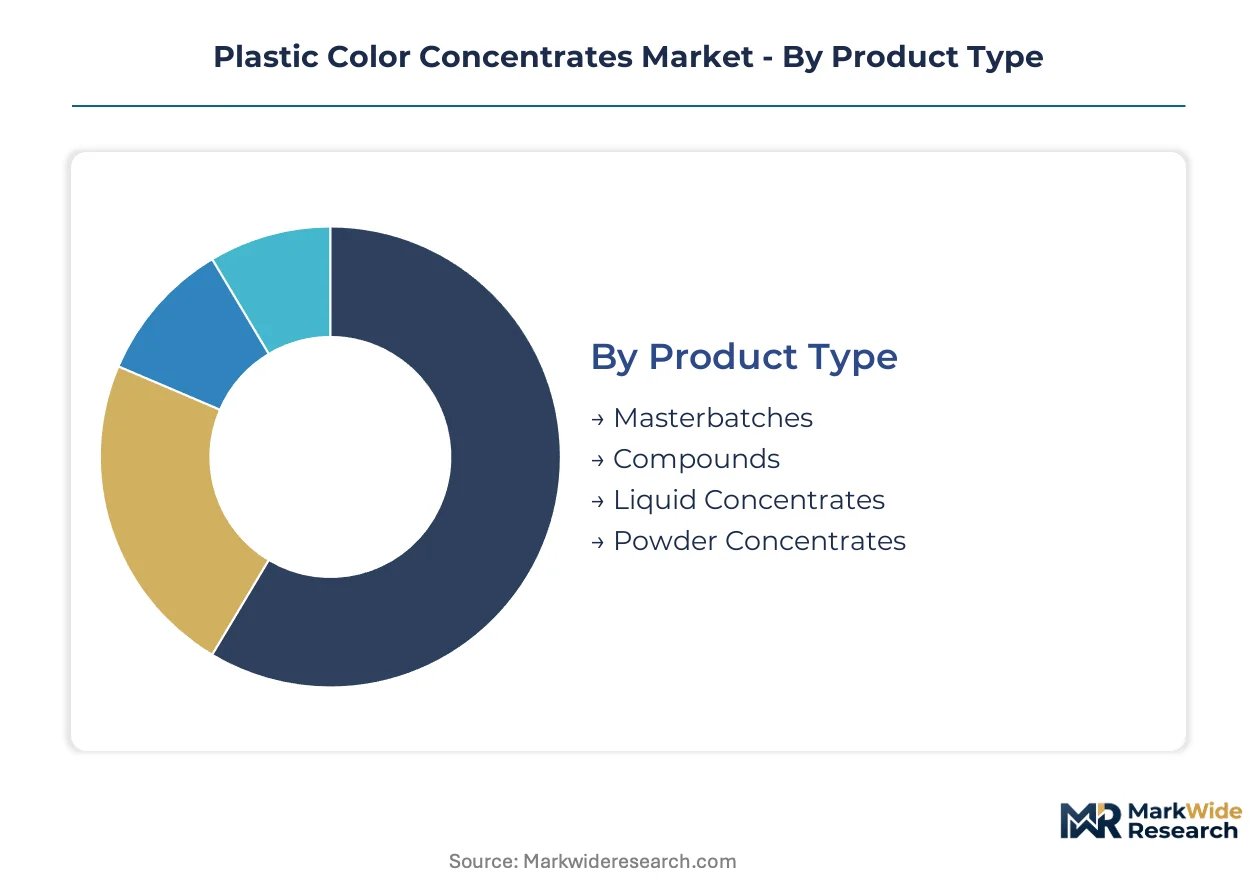
Segmentation in plastic color concentrates reveals how formulation chemistry, processing method, and end-use durability requirements create distinct competitive arenas. Suppliers must align technical capabilities with specific polymer processing environments rather than pursuing horizontal coverage.
Product Type:
Masterbatches function as standalone additive systems integrated at the processing machine, while liquid and powder concentrates embed directly into compounder operations or specialized coating lines.
- Masterbatches:Highly loaded pellets containing 15-80% active colorant dispersed in carrier resins enable precise dosing during injection molding and extrusion. Demand concentrates in German automotive supply chains and Indian packaging converters where continuous production favors pelletized handling systems. REACH-compliant formulations now dominate European procurement specifications.
- Compounds:Pre-colored polymer resins delivered in ready-to-process form eliminate downstream blending operations for medical device manufacturers and electronics housings. Brazilian industrial compounders favor this format for multi-material assembly lines requiring exact color matching across component suppliers.
- Liquid Concentrates:Pumpable dispersions serve blow molding operations demanding rapid color changeovers without equipment purging cycles.
- Powder Concentrates:Free-flowing pigment-resin blends target rotational molding and dip-coating applications where liquid carriers create processing complications.
Volume placements concentrate in Masterbatches; the faster expansion belongs to Liquid Concentrates.
End User:
Cost tier differentiation separates commodity packaging applications from specification-driven automotive programs where thermal stability and weathering performance command substantial formulation premiums.
- Packaging:Food-contact compliance under FDA Title 21 and FSSAI standards drives mineral and organic pigment adoption for beverage bottles, flexible films, and rigid containers. Indian converters expanding under PLI scheme incentives represent the steepest demand trajectory for sustainable colorant solutions.
- Automotive:Exterior body panels and interior trim require heat-stable formulations surviving paint-line temperatures and UV exposure. German tier-one suppliers specify halogen-free flame-retardant concentrates for electric vehicle battery housings as polymer substitution accelerates.
- Consumer Goods:Cosmetics and electronics packaging utilize metallic and fluorescent effects for shelf differentiation in competitive retail environments.
- Textiles:Synthetic fiber coloration demands dispersible concentrates compatible with melt-spinning temperatures and downstream dye-fastness requirements.
Revenue margins peak in Automotive; the broadest volume base sits in Packaging.
Color Type:
Application maturity separates established opaque formulations from emerging transparent and specialty effect technologies where technical qualification cycles extend procurement timelines.
- Opaque:Titanium dioxide and carbon black loaded systems provide complete light blocking for dairy packaging and agricultural film. Raw material cost volatility in white pigment feedstocks compresses margins for standard formulations serving Brazilian construction applications.
- Transparent:Dye-based concentrates enabling see-through aesthetics in premium cosmetics and electronics packaging command formulation expertise for clarity retention during processing.
- Metallic:Aluminum flake and coated mica dispersions create reflective finishes for automotive trim and luxury consumer goods where surface appearance determines purchasing decisions.
- Fluorescent:High-visibility organic pigments serve safety equipment and promotional packaging requiring attention-grabbing color intensity under varied lighting conditions.
Specification density concentrates in Metallic; the technology investment intensity peaks in Fluorescent.
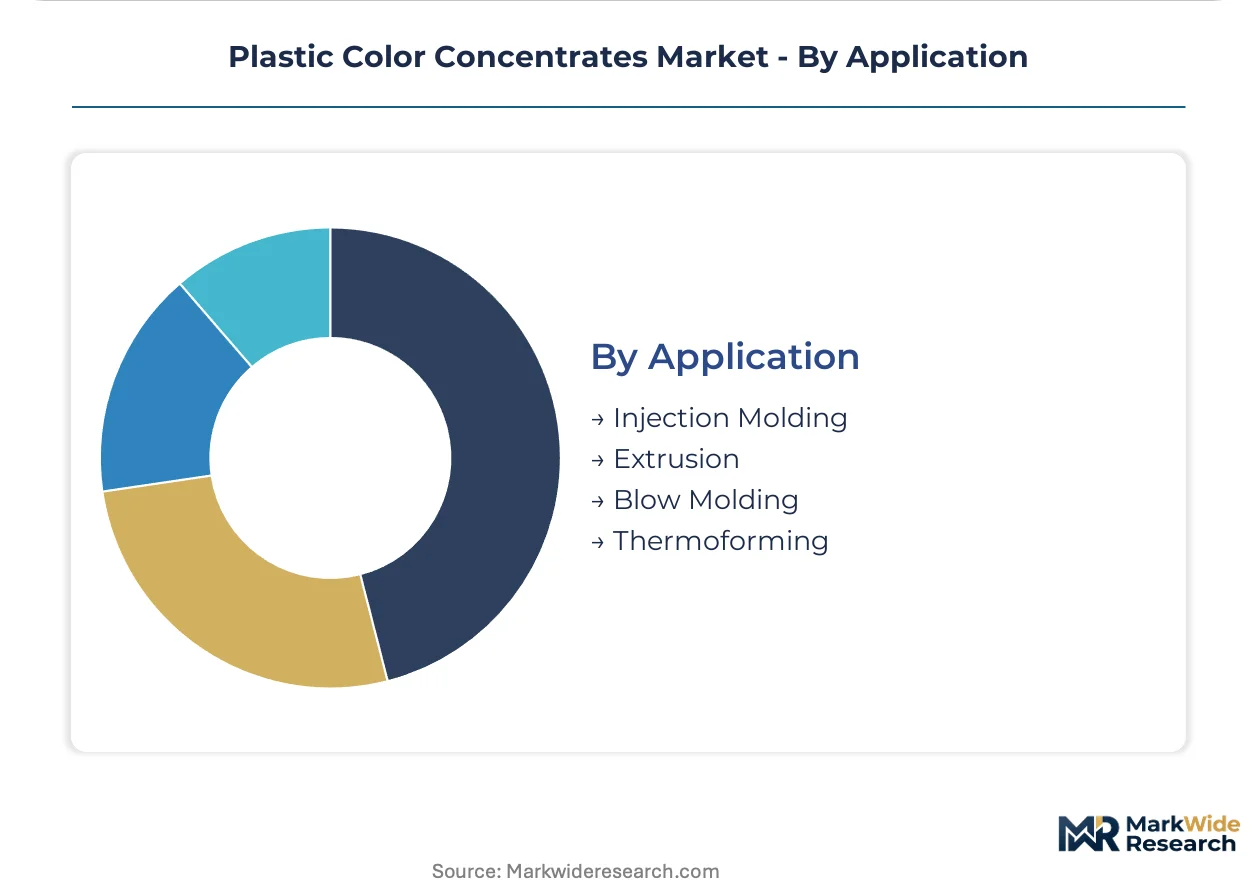
Application:
Processing temperature and shear environment dictate carrier resin selection and pigment thermal stability requirements across molding and extrusion platforms.
- Injection Molding:High-pressure, high-temperature processing of engineering resins demands heat-stable concentrates with precise melt flow characteristics. German automotive molders specify masterbatches qualified across multiple polymer bases to prevent color drift in thin-wall components.
- Extrusion:Continuous profile and sheet production favors pelletized masterbatches with consistent bulk density for gravimetric feeding systems. Indian pipe and film extruders drive volume for standard color formulations.
- Blow Molding:Parison formation and stretch ratios require concentrates with excellent dispersion to prevent visual defects in bottle walls.
- Thermoforming:Sheet preheating and vacuum forming operations utilize concentrates optimized for sag resistance and uniform draw-down across deep cavities.
Equipment penetration concentrates in Injection Molding; the processing complexity premium belongs to Blow Molding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Brazil concentrate polymer processing investments through tax incentives and duty exemptions, accelerating regional manufacturing scale-up for color concentrate suppliers.
Germany
Automotive lightweighting programs at BMW and Volkswagen drive demand for heat-stable masterbatches in battery housings and exterior panels. REACH authorization requirements for chromium-based pigments force compounders toward complex inorganic alternatives. Bavaria's chemical corridor around Ludwigshafen hosts BASF SE's pigment chemistry operations serving tier-one automotive suppliers.
India
Packaging converters expanding under PLI scheme incentives represent the steepest demand trajectory for food-contact compliant colorants. FSSAI standards for food-contact materials drive mineral and organic pigment adoption in beverage bottles and flexible films. Gujarat's polymer processing cluster near Ahmedabad attracts masterbatch suppliers seeking proximity to extrusion and blow molding operations.
Brazil
Construction film and agricultural applications sustain volume demand for titanium dioxide loaded opaque formulations despite raw material cost volatility. ANVISA regulations for food-contact plastics reshape formulation requirements for packaging suppliers. São Paulo's industrial belt concentrates compounder operations serving multi-material assembly lines for consumer goods and electronics.
United States
FDA Title 21 food-contact notifications govern formulation choices for packaging suppliers serving North American end users. State-level chemical disclosure laws in California accelerate reformulation investments toward organic pigment systems. Texas Gulf Coast petrochemical corridors integrate color concentrate production with downstream polymer processing for injection molding and extrusion platforms.
China
GB standards for food-contact materials and evolving environmental regulations under MEE oversight reshape formulation requirements for domestic and export-oriented suppliers. Yangtze River Delta manufacturing zones concentrate blow molding operations for beverage packaging demanding rapid color changeover capabilities. Zhejiang and Jiangsu provinces host masterbatch producers scaling to serve both domestic converters and export markets.
Plastic Color Concentrates Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation chemistry expertise becoming the primary differentiator as substance restrictions proliferate. The vendor base organizes into three tiers: integrated chemical conglomerates with captive pigment supply, independent masterbatch specialists with regional technical service networks, and compounders serving specification-driven automotive and medical device programs. Capacity expansion and strategic partnerships dominate competitive moves as suppliers seek to secure compliant raw material access and embed with volume buyers through on-site color laboratories.
Within the integrated chemical tier, BASF SE and Clariant exemplify archetypes combining pigment chemistry heritage with polymer dispersion capabilities. Ampacet Corporation occupies a position among independent specialists with multi-continental technical service infrastructure. These three anchors illustrate how competitive positioning increasingly depends on regulatory compliance breadth rather than geographic coverage alone.
| Leading Market Players |
|---|
| Clariant |
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Cabot Corporation |
| Ampacet Corporation |
| PolyOne Corporation |
| Avient Corporation |
| Ferro Corporation |
| Tosaf Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up masterbatch specialists in Europe and North America exert pricing discipline through centralized procurement of titanium dioxide and organic pigments, while sovereign-backed producers in China and India leverage state-supported feedstock access to undercut contract rates for standard formulations. This ownership fragmentation produces divergent margin structures: financial sponsors prioritize EBITDA recovery through formula surcharges, whereas state-linked compounders absorb cost volatility to secure volume placement with automotive OEMs and packaging converters.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to custom color-matching orders from German automotive tier-ones, whereas spot inventory of standard black and white masterbatches trades at discounts to annual contract rates. The dominant pricing structure separates premium FDA-certified food-contact formulations from standard industrial grades, with price differentiation driven by certification tier and volume scale. Pricing pressure stems from titanium dioxide feedstock volatility compressing margins on opaque white formulations. Commodity packaging converters exhibit highest price sensitivity, while medical device manufacturers accept substantial premiums for batch-traceable compounds.
Supply Chain Analysis
Freight costs from Ludwigshafen to Bavarian automotive plants and from Ahmedabad to Mumbai packaging corridors represent 8-12 percent of delivered concentrate value, incentivizing regional production placement. Supply concentrates in Germany, India, and China, with raw material dependencies on titanium dioxide feedstocks from Ukraine and Australia, organic pigment intermediates from China, and carrier resins from Gulf Coast petrochemical complexes. Single-source vulnerability in chromium-based pigment alternatives following REACH authorization restrictions poses structural risk. Distribution runs through direct compounder relationships displacing distributor channels for volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a consolidation play as simultaneous REACH and FDA compliance investments force sub-scale compounders toward exit or acquisition. Regulatory dual-certification burdens favor suppliers with captive technical service infrastructure.
For Market Incumbents: Acquire formulation chemist talent pools and on-site color laboratory assets to defend against emerging Indian compounders with PLI scheme backing. Priority levers include backward integration into organic pigment synthesis and capacity expansion in Gujarat to serve packaging converters with just-in-time delivery commitments. ECHA restrictions on heavy metal pigments threaten legacy formulation portfolios without reformulation investment. For New Entrants and Emerging Players: FSSAI compliance requirements in India open a window for mineral pigment specialists to capture share from multinational incumbents with slower local qualification cycles. White-space targets include near-infrared detectable black concentrates for recyclable plastics and bio-based carrier masterbatches for Scope 3-conscious automotive suppliers. Go-to-market through direct technical partnerships with São Paulo industrial compounders offers lowest customer acquisition cost. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European masterbatch specialists with REACH-compliant portfolios and stranded seller dynamics from family ownership transitions. Long-term viability centers on pigment chemistry expertise as primary moat rather than geographic coverage. Signal to watch: ECHA substance evaluation announcements triggering forced divestitures of non-compliant formulation lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Pigment Synthesis | Captive supply of REACH-compliant alternatives secures margin recovery from reformulation investments. |
| On-Site Color Laboratory Deployment | BMW and Volkswagen tier-one suppliers require just-in-time technical integration support for battery housing programs. |
| Bio-Based Carrier Masterbatch Scale-Up | Automotive lightweighting programs in Germany pilot petroleum-derived resin replacements for Scope 3 targets. |
| Near-Infrared Detectable Black Concentrate Development | European sorting infrastructure expansion creates compliant recyclable black plastic demand from packaging groups. |
| Joint Venture with Indian PLI-Backed Compounders | Gujarat polymer processing clusters offer proximity to fastest-growing food-contact packaging converter base. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with masterbatch plant managers, automotive tier-one procurement leads, packaging converter technical directors, and pigment distribution channel partners. ECHA substance evaluation databases, FDA Title 21 food-contact notifications, and FSSAI compliance registries provided regulatory trajectory inputs. Bottom-up modeling of formulation-grade demand and top-down validation against polymer processing capacity data ensured cross-check integrity.
Granularity-level modeling deployed product type, end-use industry, color chemistry, and processing application dimensions at country-level resolution across the analysis window. CAGRs derived from regression analysis of historical pigment consumption against polymer processing output indices, with explicit modeling of electric vehicle battery housing demand and PLI scheme incentive effects on Indian packaging investment. Forecast inputs included REACH authorization timelines and titanium dioxide feedstock price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for bio-based carrier thermal stability breakthroughs would alter the outlook for high-temperature automotive applications. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and pigment substitution cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Metallic Pigments Market