
 Outdoor Kitchen Cabinets Market | 2026-2036
Outdoor Kitchen Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Kitchen Cabinets Market Analysis
Skilled marine-fabrication labor migrating from boat-building regions is reorganizing how outdoor cabinet manufacturers scale weather-resistant production. Danver Stainless Outdoor Kitchens leverages its metalworking heritage to sustain premium positioning in coastal markets. Bull Outdoor Products anchors its competitive stance through broad distribution across home improvement channels. NatureKast Products differentiates via specialized polymer formulations that resist UV degradation in high-humidity climates.
Outdoor kitchen cabinets are weather-resistant storage and preparation enclosures engineered from stainless steel, marine-grade polymer, or treated hardwood, typically featuring sealed seams, adjustable leveling systems, and thermal insulation rated for ambient temperature swings. These systems serve the primary commercial purpose of extending residential food preparation, beverage service, and entertainment functions into exterior living zones. Stainless steel and polymer material types command the dominant margin pools due to their durability premiums and lower lifetime replacement frequency, while modular installation types are gaining fastest as homeowners seek reconfigurable layouts that adapt to evolving outdoor entertainment needs. Matte and textured finish types occupy mature demand positions, though painted finishes are expanding as custom color-matching to exterior architecture becomes a specification priority.
EPA guidelines on volatile organic compound emissions shape powder-coating processes and finish chemistry selections for domestic manufacturers, while ISO 9227 salt-spray testing standards govern corrosion-resistance claims in coastal-market product positioning. The Consumer Product Safety Commission maintains oversight on structural stability requirements for freestanding units in wind-exposed installations. Stakeholders must monitor evolving state-level building code amendments that classify outdoor kitchens as permanent structures, since these reclassifications would trigger permitting requirements and alter installation-type demand patterns.
Market Dynamics
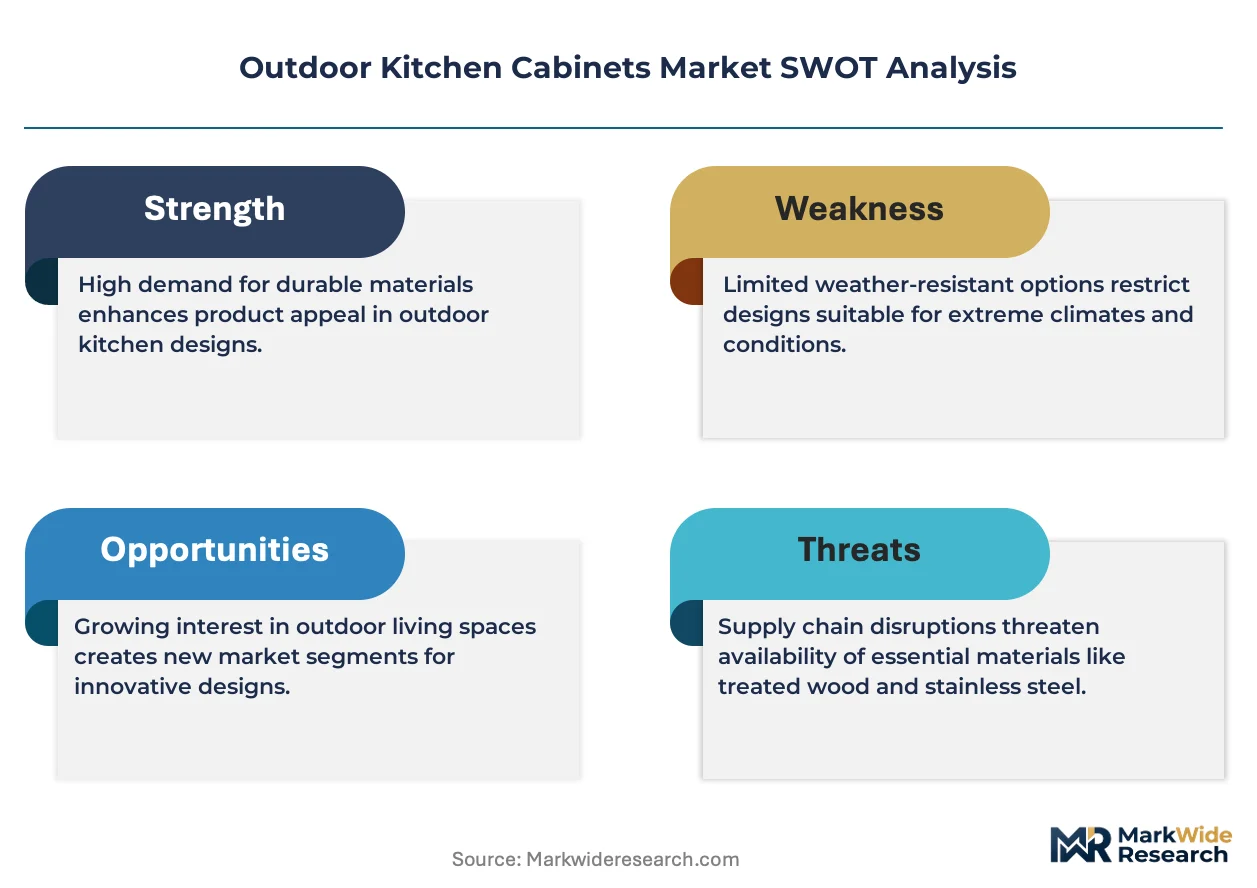
Marine-grade polymer chemistry is displacing treated hardwood as the dominant substrate specification, compressing replacement cycles and redistributing margin pools toward specialized compound formulators with coastal distribution networks.
Growth Catalysts
- Sun Belt residential construction:Year-round outdoor entertainment culture in Florida, Arizona, and Texas sustains cabinet refresh demand at double the frequency of seasonal climates.
- EPA VOC emission guidelines:Powder-coating compliance investments by domestic manufacturers create technical barriers that protect established coastal producers from low-cost import competition.
- Marine-fabrication labor migration:Skilled metalworkers relocating from declining boat-building regions in the Great Lakes and Northeast are reorganizing regional production capacity.
Market Restraints
- 316L stainless steel price volatility:Nickel and molybdenum input cost swings compress fabrication margins during procurement lag periods.
- ISO 9227 salt-spray certification backlog:Third-party testing facility congestion in coastal states delays product launches by four to six months.
- Modular aluminum framing substitution:Lightweight extrusion systems from pergola and shade structure manufacturers are capturing perimeter cabinet applications.
Strategic Opportunities
- Mountain West second-home markets:Colorado and Utah vacation property segments remain underpenetrated by premium weather-resistant cabinet offerings.
- Integrated smart-appliance convergence:Partnerships between cabinet fabricators and outdoor refrigeration OEMs are creating specification-locked entertainment systems.
- State-level building code reclassification:Pending amendments in California and Florida that would trigger permitting requirements for permanent outdoor kitchen structures favor established local installers with municipal relationships.
Industry Challenges
- Marine welding certification scarcity:AWS D3.6-certified fabricators command wage premiums that strain mid-tier manufacturer labor models.
- Multi-material thermal expansion engineering:Stainless-polymer hybrid cabinet systems require proprietary gasket systems that extend R&D timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Kitchen Cabinets Market |
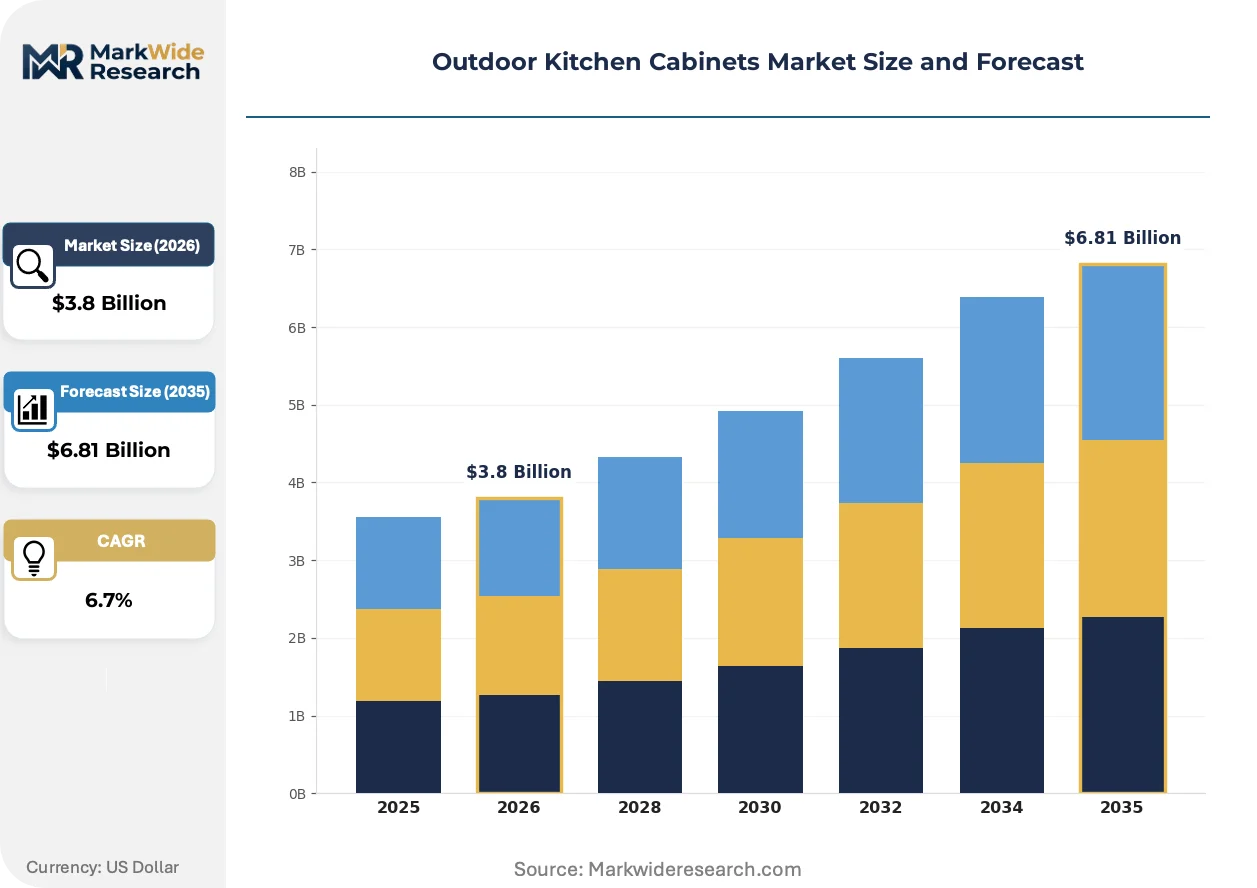
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Stainless Steel, Polymer, Aluminum Finish Type: Matte, Glossy, Textured, Painted Style: Modern, Rustic, Traditional, Contemporary Installation Type: Built-In, Freestanding, Modular, Custom |
| Companies Covered | American Outdoor Cabinets, Bull Outdoor Products, Danver Stainless Outdoor Kitchens, Coyote Outdoor Living, NatureKast Products, NewAge Products, Brown Jordan, Grillnetics, Ideal Cabinetry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Kitchen Cabinets Market Emerging Trajectories
Digital color-matching workflows and predictive corrosion modeling are compressing specification cycles while elevating finish durability expectations across coastal and inland markets simultaneously.
Marine-grade polymer formulation is bifurcating cabinet demand into two distinct specification tiers. High-end residential buyers in hurricane-prone counties specify UV-stabilized compounds with 25-year warranties, while inland second-home markets accept shorter-rated formulations at lower price points. This material divergence is compressing the mid-tier segment and forcing fabricators to commit to single-substrate production lines.
EPA guidelines on volatile organic compound emissions are reshaping powder-coating chemistry selection across domestic manufacturing. Low-temperature cure formulations now dominate new equipment investments, though these systems require longer line times that constrain throughput. Coastal producers with legacy high-bake infrastructure face stranded asset risk as state environmental agencies tighten enforcement timelines.
Specification behavior among residential architects is rotating toward integrated outdoor kitchen systems rather than component procurement. Design firms now bundle cabinet, appliance, and structural elements into single-source contracts, compressing the traditional three-tier distribution channel. This consolidation is most visible in Texas and Florida metropolitan markets where large-scale residential developers maintain preferred vendor lists.
Outdoor Kitchen Cabinets Market Segmentation
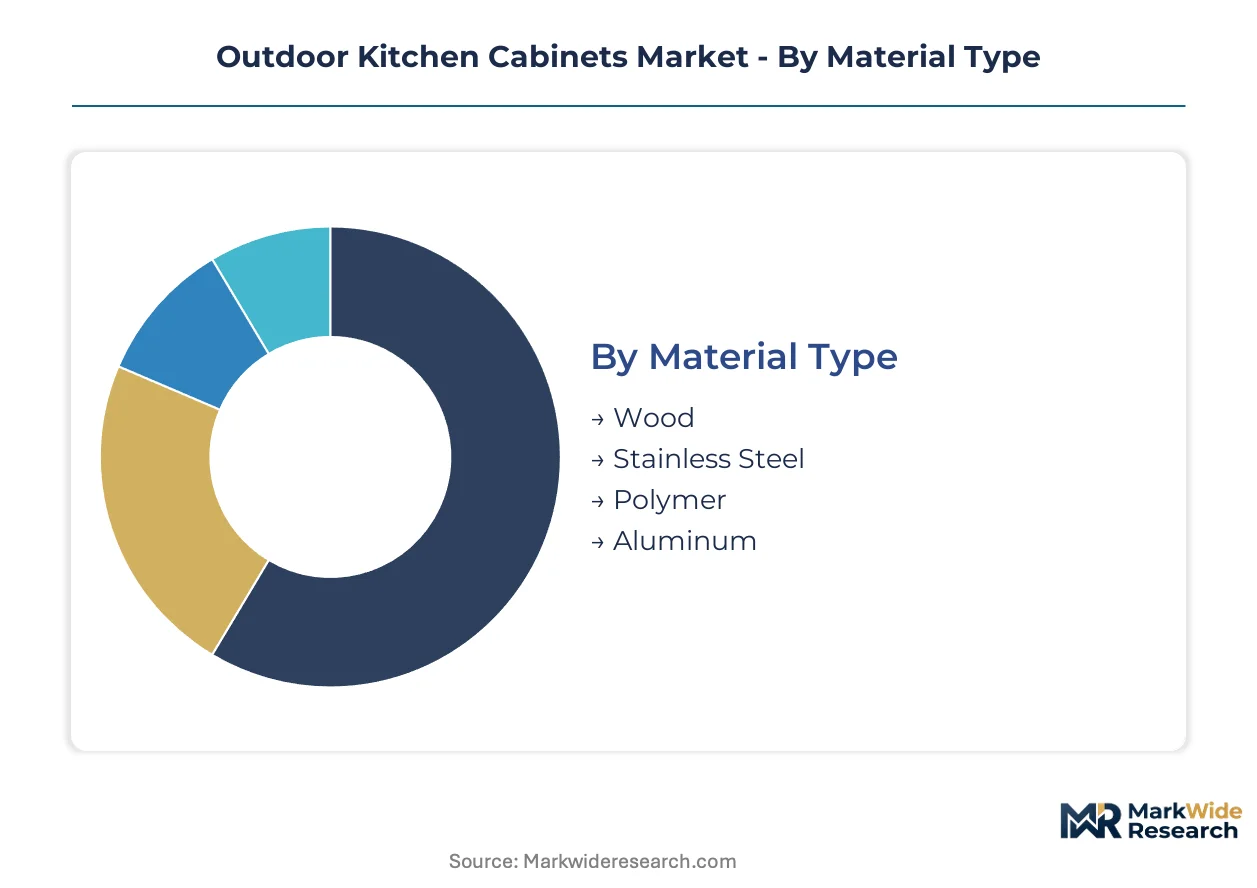
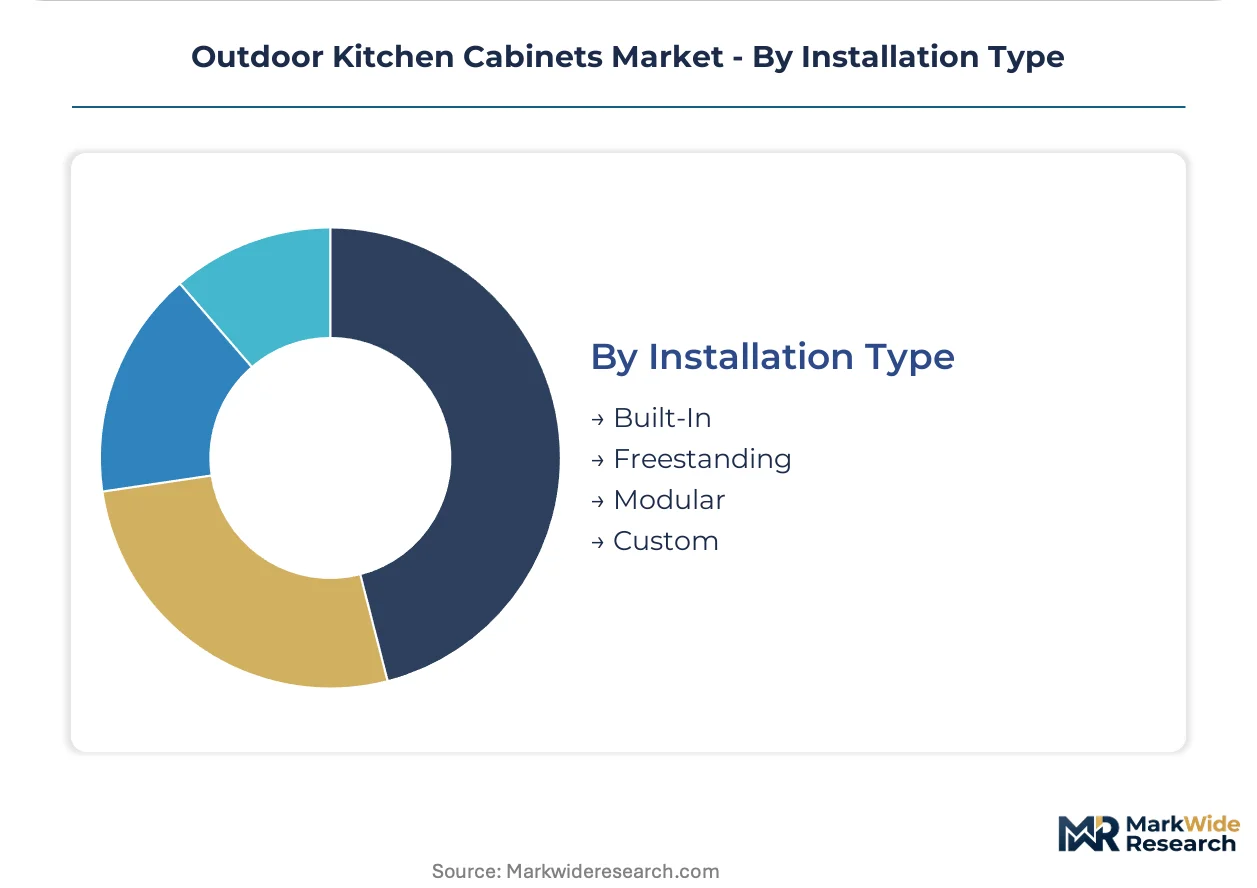
Outdoor kitchen cabinet segmentation reveals how material chemistry and installation architecture shape procurement patterns across coastal and inland markets. Specification behavior diverges sharply between hurricane-zone durability requirements and seasonal-climate aesthetic priorities.
Material Type:
EPA VOC emission guidelines and ISO 9227 salt-spray standards create divergent compliance burdens across substrate categories, redistributing fabrication capacity toward certified coastal producers.
- Stainless Steel:Marine-grade 316L alloy formulations deliver superior chloride resistance for salt-air environments. Demand concentrates in Florida and Texas coastal counties where building codes mandate corrosion-resistant substrates for permanent outdoor structures. Nickel and molybdenum price volatility compresses fabrication margins during procurement lag periods.
- Polymer:UV-stabilized marine-grade compounds resist thermal degradation in high-humidity climates. Specification is climbing fastest in Arizona and Nevada desert markets where extreme temperature swings exceed metal fatigue tolerances. Compound formulators with coastal distribution networks capture expanding margin pools.
- Wood:Treated hardwood substrates serve budget-conscious replacement cycles in seasonal climates with limited exposure windows.
- Aluminum:Lightweight extrusion systems from adjacent pergola manufacturers capture perimeter cabinet applications through lower installed weight.
Established volume favors stainless steel; emerging adoption favors polymer.
Finish Type:
Cost tier differentiation separates specification-grade architectural matching from standard catalog offerings.
- Painted:Custom color-matching workflows now dominate high-end residential specification. Texas and Florida metropolitan architects bundle painted finishes into single-source outdoor kitchen contracts. Low-temperature powder-coating cure systems constrain throughput for domestic manufacturers.
- Textured:Matte-embossed surfaces conceal minor impact damage in high-traffic entertainment zones. Demand concentrates in Mountain West second-home markets where rustic architecture dominates vacation property design.
- Matte:Flat-finish stainless treatments occupy mature demand positions across mid-tier replacement cycles.
- Glossy:High-sheen polymer topcoats serve commercial hospitality venues prioritizing visual impact over scratch concealment.
Premium specification favors painted; durability-conscious procurement favors textured.
Style:
Customer type segmentation separates developer-driven standardization from architect-led customization.
- Modern:Clean-line minimalism with integrated appliance concealment. Large-scale residential developers in Sun Belt states specify modern styling for master-planned community standardization. Design firms bundle modern cabinet systems with structural and appliance elements.
- Rustic:Distressed wood-look polymer and hammered-metal textures. Colorado and Utah vacation property segments drive specification for mountain-architecture compatibility.
- Traditional:Raised-panel door profiles with decorative hardware. Mature demand in Northeast seasonal markets with established outdoor entertainment infrastructure.
- Contemporary:Transitional styling bridging modern and traditional elements. Gaining share fastest among renovation contractors serving evolving homeowner preferences.
Production scale favors modern; customization margin favors rustic.
Installation Type:
Supply concentration in modular systems is reorganizing distribution channel relationships away from traditional three-tier structures.
- Modular:Reconfigurable layouts adapt to evolving outdoor entertainment needs without full replacement. Home improvement channel distribution anchors competitive positioning for mid-tier manufacturers. AWS D3.6-certified welding scarcity constrains quality-consistency at scale.
- Built-In:Permanent structural integration triggers municipal permitting requirements under pending California and Florida code amendments. Established local installers with municipal relationships capture specification-locked projects.
- Freestanding:Portable units serve rental property and temporary event applications with minimal site preparation.
- Custom:Site-fabricated systems serve architect-specified projects with non-standard dimensional requirements.
Channel efficiency favors modular; regulatory compliance favors built-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA guidelines on volatile organic compound emissions anchor United States regulatory frameworks for outdoor kitchen cabinet manufacturing, creating compliance barriers that protect domestic coastal producers from import competition.
United States
Year-round outdoor entertainment culture in Florida, Arizona, and Texas sustains cabinet refresh demand at double the frequency of seasonal climates. The Consumer Product Safety Commission maintains oversight on structural stability requirements for freestanding units in wind-exposed installations. Skilled marine-fabrication labor migrating from declining Great Lakes boat-building regions is reorganizing regional production capacity toward coastal manufacturing clusters.
Canada
Seasonal climate patterns concentrate demand in Ontario and British Columbia metropolitan corridors with limited exposure windows. Health Canada and PMRA guidelines influence treated wood substrate approvals for exterior residential applications. Toronto-area distributors serve cross-border specification flows into northern United States renovation markets.
Germany
REACH compliance and RoHS directives shape powder-coating chemistry selections for European-bound export production. Precision metalworking traditions in Baden-Württemberg support stainless steel fabrication quality standards. Munich and Stuttgart architectural firms specify weather-resistant outdoor kitchen systems for alpine second-home developments.
Australia
Coastal salt-air exposure drives marine-grade polymer specification in Queensland and New South Wales residential construction. The country's national building code amendments increasingly classify outdoor kitchens as permanent structures, triggering municipal permitting requirements. Sydney and Melbourne design firms bundle cabinet, appliance, and structural elements into single-source contracts.
United Arab Emirates
High-humidity coastal conditions and extreme temperature swings exceed metal fatigue tolerances, favoring UV-stabilized polymer formulations. MOHAP oversight influences material safety standards for residential hospitality installations. Dubai and Abu Dhabi luxury residential developers maintain preferred vendor lists for integrated outdoor entertainment systems.
Outdoor Kitchen Cabinets Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the outdoor kitchen cabinets market. Premium-tier fabricators with marine-fabrication heritage capture coastal specification-locked projects, while mid-tier manufacturers anchor home improvement channel distribution through modular system offerings. Three strategic archetypes dominate: certified coastal specialists with AWS D3.6 welding capabilities, polymer compound formulators with UV-stabilization intellectual property, and broad-line outdoor living brands with multi-category portfolio scale. Competitive moves concentrate on geographic expansion into underpenetrated Mountain West second-home markets and strategic partnerships with outdoor refrigeration OEMs for specification-locked entertainment systems.
Among United States-based fabricators, Danver Stainless Outdoor Kitchens and Bull Outdoor Products exemplify divergent positioning archetypes. Danver occupies the certified coastal specialist tier, leveraging metalworking heritage for premium market positioning. Bull anchors the broad distribution archetype through home improvement channel penetration. NatureKast Products represents the polymer formulation specialist category, with compound expertise addressing high-humidity climate durability requirements. These three players illustrate how substrate specialization and channel strategy segmentation create distinct competitive territories within the market structure.
| Leading Market Players |
|---|
| American Outdoor Cabinets |
| Bull Outdoor Products |
| Danver Stainless Outdoor Kitchens |
| Coyote Outdoor Living |
| NatureKast Products |
| NewAge Products |
| Brown Jordan |
| Grillnetics |
| Ideal Cabinetry |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at certified coastal fabricators creates scale economies that compress per-unit fixed costs while elevating price floors for uncertified competitors. Marine-grade polymer compounders with dedicated Sun Belt distribution networks capture margin premiums through volume commitments that lock in feedstock pricing.
Pricing Analysis
Geographic price spreads between Florida coastal counties and Mountain West second-home markets exceed material cost differentials alone. Three-tier pricing structure across premium, standard, and economy levels separates AWS D3.6-certified fabricators from home improvement channel suppliers and import competitors. Price differentiation centers on ISO 9227 salt-spray certification tier and after-sales warranty bundling. Cost compression in mid-tier stainless steel fabrication is intensifying because nickel and molybdenum procurement lag periods compress margins during volatility spikes. Renovation contractors serving seasonal climates exhibit highest price sensitivity, while Sun Belt residential developers maintain lowest sensitivity due to specification-locked vendor relationships.
Supply Chain Analysis
Inventory strategy preferences favor just-in-time polymer resin procurement from Texas and Louisiana petrochemical corridors, though 316L stainless steel fabricators maintain strategic stockpiles against nickel price volatility. Geographic supply concentration centers on United States coastal manufacturing clusters, Chinese powder-coating equipment suppliers, and German precision metalworking component sources. Raw material dependencies include marine-grade polymer compounds, 316L stainless steel alloy, and low-VOC powder-coating formulations. Single-source vulnerability in AWS D3.6-certified welding labor pools constrains quality-scaling for modular system producers. Distribution runs through home improvement retail channels for mid-tier manufacturers and direct specification relationships for certified coastal specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against lightweight aluminum extrusion systems from adjacent pergola manufacturers that capture perimeter cabinet applications through lower installed weight and faster installation cycles.
For Market Incumbents: Consolidate AWS D3.6-certified welding capacity through exclusive labor agreements or captive training programs to defend against modular aluminum framing substitution. Deepen backward integration into marine-grade polymer compound formulation to capture margin pools migrating from fabrication toward specialized chemistry suppliers. For New Entrants and Emerging Players: Anchor in Colorado and Utah vacation property segments where premium weather-resistant cabinet offerings remain underpenetrated by established coastal fabricators. Target rustic-style polymer formulations with mountain-architecture compatibility as the most penetrable aesthetic tier, leveraging direct relationships with regional design-build contractors rather than three-tier distribution channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among polymer compound formulators with UV-stabilization intellectual property and long-term supply agreements with Sun Belt fabricators. Long-term viability over the projection horizon favors acquisition targets with coastal distribution infrastructure and municipal installer relationships ahead of pending California and Florida building code reclassifications. Watch for ISO 9227 salt-spray certification backlog resolution as inflection indicator for product launch velocity and market share capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin pools migrating from fabrication toward specialized UV-stabilization chemistry suppliers in high-humidity climates. |
| AWS D3.6 Certification Investment | Creates technical barriers protecting coastal producers from low-cost import competition under tightening EPA VOC enforcement. |
| Mountain West Distribution Expansion | Addresses underpenetrated Colorado and Utah vacation property segments with rustic-style compatibility requirements. |
| Smart-Appliance OEM Partnership | Locks specification relationships through integrated outdoor refrigeration and entertainment system bundling. |
| Low-Temperature Powder-Coating Conversion | Aligns domestic manufacturing with state environmental agency enforcement timelines while constraining throughput capacity. |
Methodological Framework
Desk research of EPA enforcement records, ISO 9227 certification databases, and Sun Belt residential construction permit filings preceded structured interviews with marine-fabrication plant managers, polymer compound R&D directors, home improvement channel buyers, and municipal building code officials. Primary fieldwork with coastal cabinet fabricators and Mountain West design-build contractors combined with secondary validation through customs trade data and SEC filings from adjacent outdoor living equipment suppliers. Bottom-up segment sizing triangulated against top-down construction spending allocation models across the analysis window.
Variance-decomposition across material type, finish tier, installation architecture, and regional climate zone shaped the analytical framework. Segmentation dimensions modeled include substrate chemistry, corrosion-resistance certification level, style category, and channel structure throughout the forecast period. CAGRs derived from replacement cycle frequency differentials between Sun Belt year-round and seasonal climate markets, with industry-specific inputs capturing marine-fabrication labor migration patterns and powder-coating compliance investment trajectories.
Underlying assumptions cover stable EPA VOC enforcement timelines and ISO 9227 salt-spray certification capacity expansion, with deviation risk concentrated in nickel-molybdenum alloy price volatility and pending state-level building code reclassification outcomes. Forecasts reflect these conditions without scenario-weighted probability assignments. Revision becomes warranted when aluminum extrusion substitution rates in perimeter cabinet applications cross thresholds that compress stainless steel and polymer addressable market boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Patio Furniture Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Outdoor Furniture Market