
 Garden Rooms Market | 2026-2036
Garden Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Rooms Market Insights
United Kingdom manufacturing capacity for modular garden structures is narrowing as timber supply chains face post-Brexit import recalibration. Crane Garden Buildings leverages vertical integration across design-to-installation workflows to sustain delivery timelines. Swift Unlimited Garden Rooms anchors its competitive position through bespoke configuration platforms. Green Retreats specializes in turnkey home office solutions, occupying the premium segment with rapid on-site assembly capabilities.
Garden rooms are prefabricated or site-built ancillary structures typically ranging from fifteen to fifty square meters, engineered with timber framing, composite insulation, and weather-resistant cladding to create thermally efficient habitable spaces separate from primary dwellings. Their primary commercial purpose centers on expanding functional living area without traditional construction permits or property extension complexity. Insulated cabin and home office product types command the dominant volume share as remote working space applications drive specification upgrades toward enhanced thermal performance and year-round usability. Timber material selection retains structural preference for aesthetic compatibility with residential landscaping, though composite panels are gaining specification in commercial small-business deployments where maintenance minimization outweighs traditional material preference.
UK permitted development rights and building control regulations shape product dimensioning, with maximum eaves heights and overall footprint limits directly constraining standard module designs. ECHA REACH compliance on treated timber preservatives and the EU F-Gas Regulation's residual influence on UK-imported HVAC components affect material sourcing and climate system specifications. Stakeholders must monitor evolving national planning policy frameworks and building safety standards as local authority interpretation of permitted development thresholds creates demand fragmentation across England, Scotland, and Wales.
Market Dynamics
Hybrid work permanence is restructuring demand specifications across the UK garden rooms sector, with employers mandating dedicated home office infrastructure and homeowners seeking year-round habitable ancillary space insulated to primary dwelling standards.
Growth Catalysts
- Permitted Development Rights:England's streamlined planning exemptions for structures below 2.5m eaves height eliminate traditional construction permitting delays, accelerating purchase-to-occupancy timelines for individual homeowners.
- Remote Work Infrastructure Mandates:Major employers in financial services and technology sectors now specify dedicated home office space as a condition of hybrid employment, directly stimulating specification upgrades toward enhanced thermal performance and dedicated HVAC systems.
- Timber-Composite Hybrid Framing:Engineered timber systems incorporating recycled polymer cores are reducing material weight by 30% while maintaining structural load ratings, enabling crane-free installation in restricted-access residential plots.
Market Restraints
- Post-Brexit Timber Import Friction:Swedish and Baltic softwood supply chains face customs documentation bottlenecks at UK ports, extending lead times for pressure-treated structural framing by 6-10 weeks during peak construction seasons.
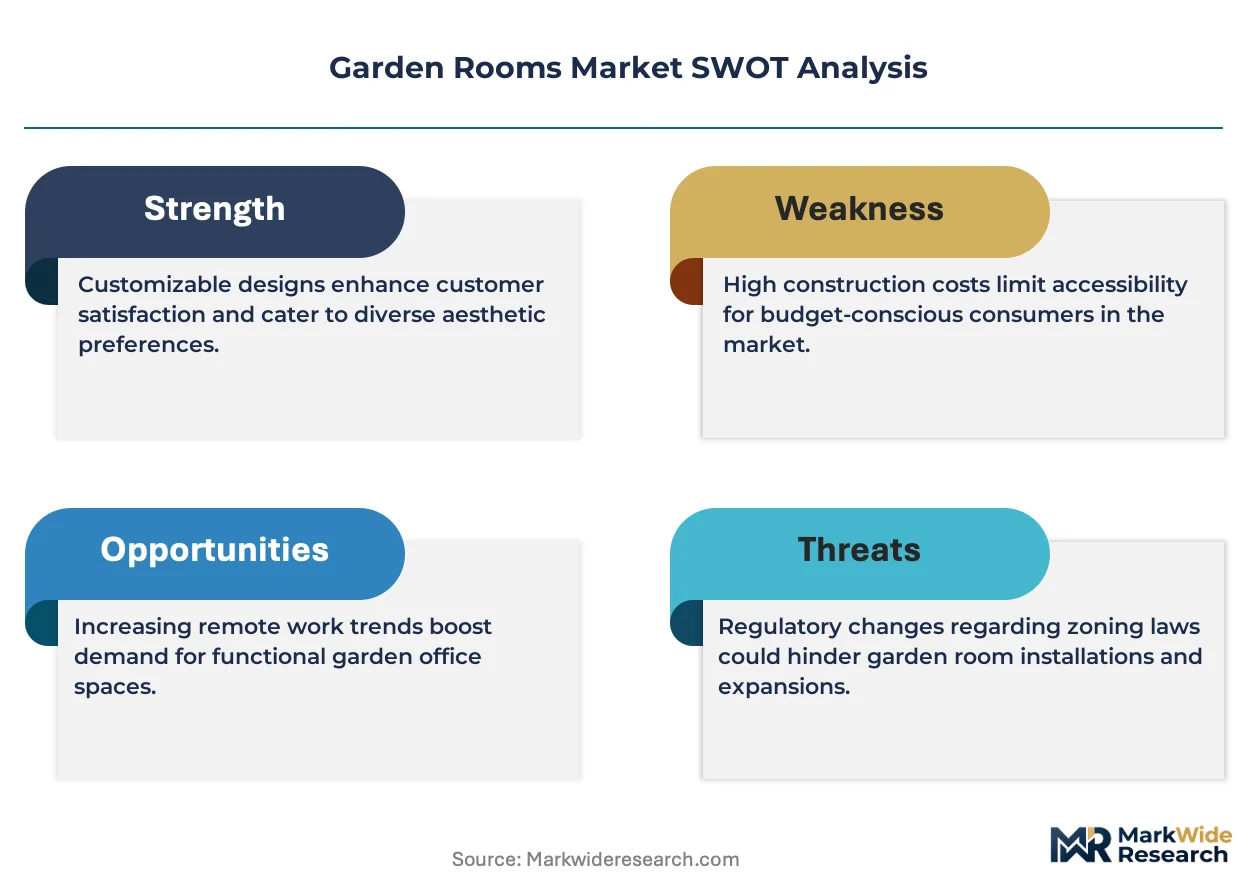
- Skilled Installation Labor Scarcity:Foundation preparation and weather-sealing trades exhibit acute regional shortages across England's Home Counties, constraining on-site completion capacity despite manufacturing output availability.
- Building Control Interpretation Variance:Local authority inspectors apply inconsistent standards for electrical certification and fire egress compliance, creating compliance uncertainty that delays final occupancy sign-off.
Strategic Opportunities
- Wales and Northern England Underpenetration:Property value differentials and smaller average garden footprints have suppressed adoption rates below 15% of southeastern England levels, presenting first-mover expansion potential for modular providers offering compact sub-20 square meter configurations.
- Small Business Commercial Deployment:Freelance consultants and micro-enterprises are repurposing garden structures as client-facing consultation spaces, creating demand for professional-grade acoustic insulation and separate utility metering.
- Green Building Certification Alignment:BREEAM and Passivhaus standards are migrating from commercial construction into residential ancillary space specifications, rewarding manufacturers with certified supply chains and documented embodied carbon calculations.
Industry Challenges
- Foundation Engineering Skill Gap:Ground condition assessment and helical pile specification expertise remains concentrated among legacy conservatory installers, creating quality variance as new market entrants scale installation teams.
- Integrated Smart Home Compatibility:Cabling infrastructure for fiber broadband, security systems, and automated climate control requires coordination with primary dwelling networks, complicating turnkey delivery promises and post-installation support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Rooms Market |
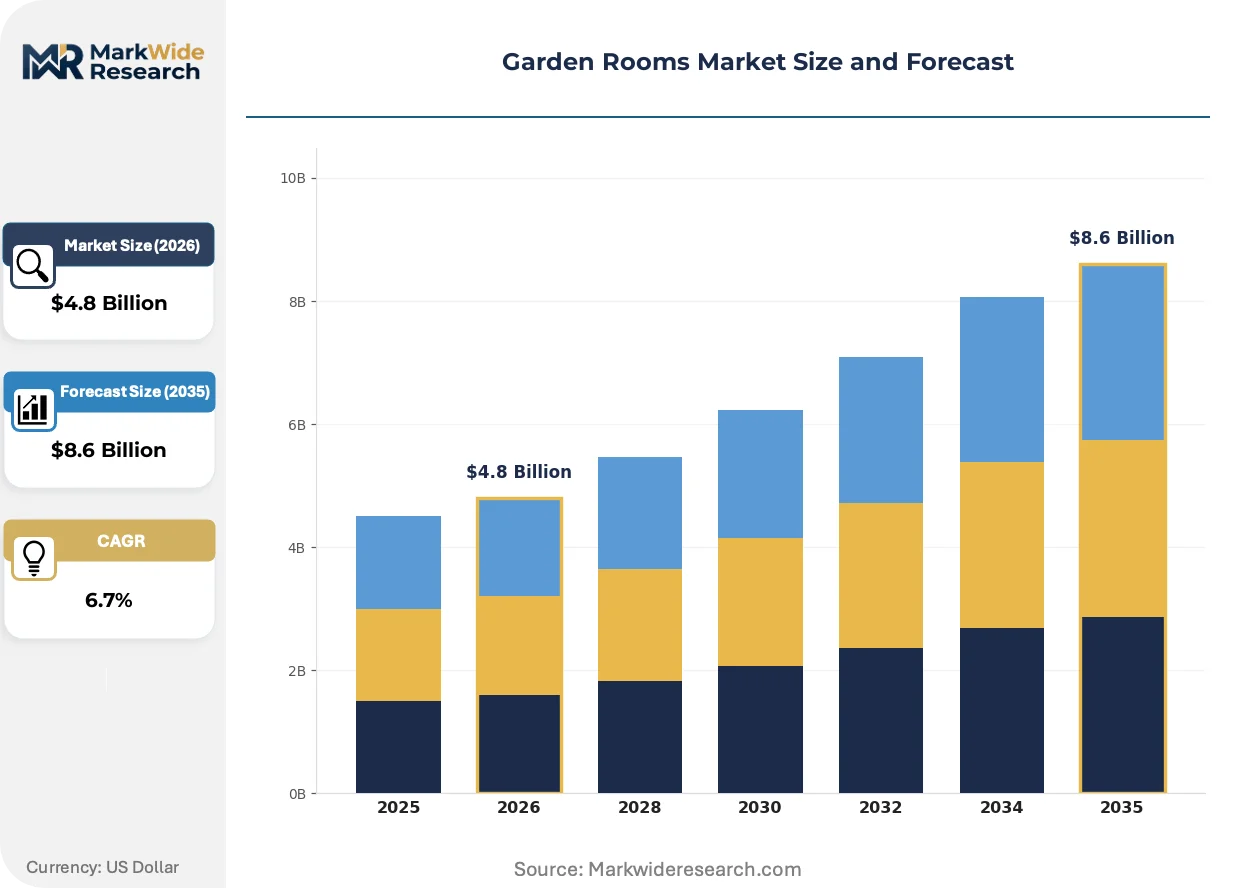
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Cabin, Glass Extension, Home Office, Summer Pavilion, Art Studio, Playroom Material: Timber, Aluminum, Composite Panels, Polycarbonate, PVC Application: Remote Working Space, Leisure Room, Fitness Studio, Entertainment Area, Guest Accommodation End User: Individual Homeowners, Property Developers, Educational Institutions, Small Businesses |
| Companies Covered | Crane Garden Buildings, Swift Unlimited Garden Rooms, Leka Garden Rooms, Westbury Garden Rooms, Tiger Modular, Smart Modular Buildings, Eden Garden Rooms, Oeco Garden Rooms, Green Retreats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Rooms Market Trends and Innovations
Specification convergence between primary residential construction and ancillary garden structures is elevating performance benchmarks, with buyers now expecting equivalent thermal efficiency, connectivity infrastructure, and finish quality across both building categories.
Building information modeling software is digitizing the design-to-manufacturing workflow for timber-framed modular structures. Regional fabricators in Kent and Surrey are adopting parametric configuration tools that auto-generate cutting schedules and structural calculations from customer input variables. This capability is compressing quotation-to-production cycles from three weeks to four days while reducing material wastage rates.
The UK's residual alignment with EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in split-system heat pumps specified for garden office climate control. Installers are pivoting toward R32 and propane-based alternatives with lower global warming potential ratings. This transition most affects premium turnkey providers whose bundled HVAC specifications must now accommodate equipment refresh cycles and technician retraining obligations.
Buyers are consolidating supplier relationships around single-source design-installation-maintain contracts rather than fragmented procurement of structure, foundation, and utility connections. This pattern concentrates contract value with vertically integrated providers and marginalizes pure manufacturing specialists lacking installation capabilities. The shift is most pronounced in London commuter belt counties where time-constrained professional households prioritize turnkey certainty over component cost optimization.
Garden Rooms Market Segmentation
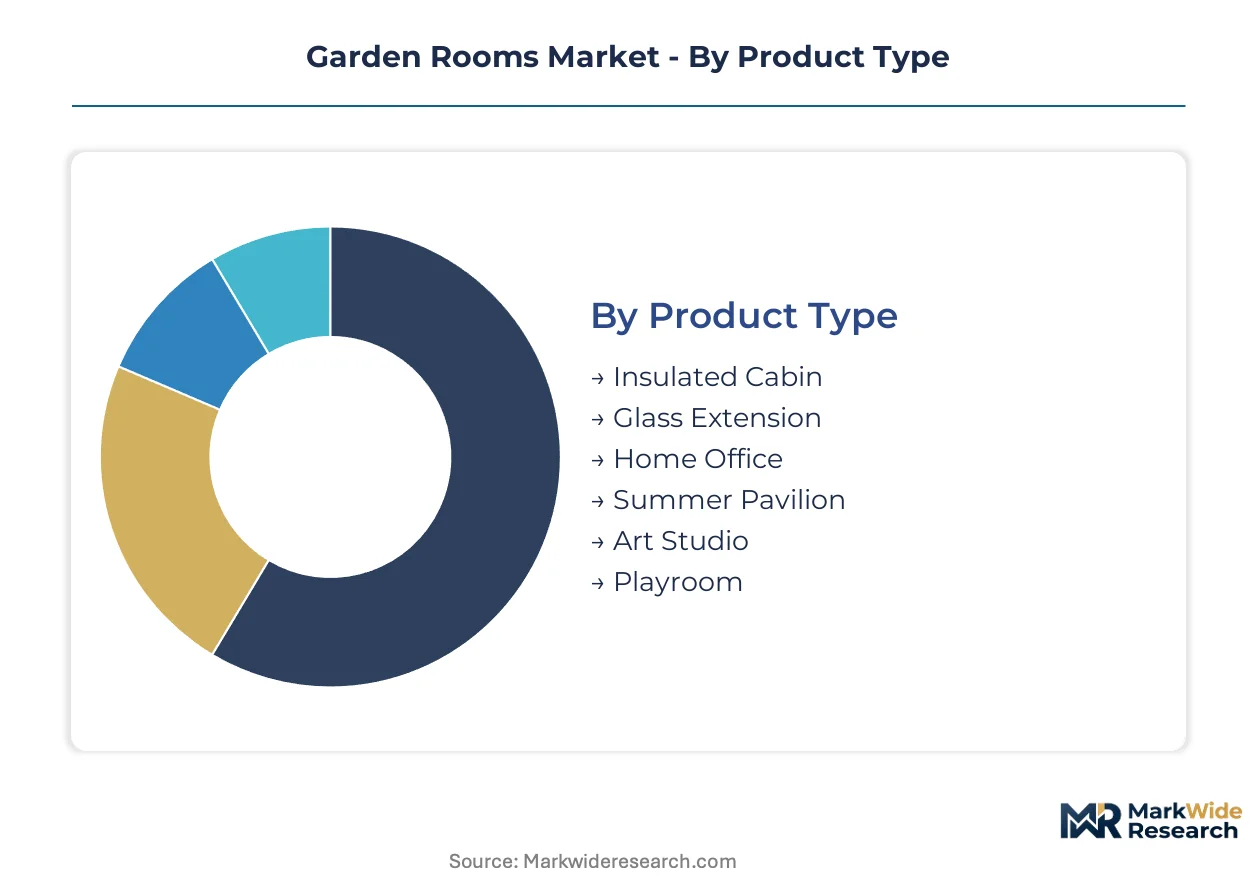
Product architecture and specification choices in garden rooms directly determine planning pathway complexity, thermal performance thresholds, and installation economics. Segmentation reveals how remote working mandates are restructuring demand concentration across traditional leisure-oriented categories.
Product Type:
Application purpose shapes structural engineering requirements, insulation specifications, and glazing ratios across the six product categories.
- Insulated Cabin:Engineered with 100mm+ mineral wool or PIR core insulation and double-glazed fenestration to achieve U-values below 0.35 W/m²K. Demand concentrates in England's Home Counties where hybrid work policies at financial services employers mandate year-round habitable ancillary space.
- Home Office:Purpose-configured with dedicated HVAC, Category 6 data cabling, and acoustic dampening to 45dB for video conferencing. Southeast England's professional households drive specification upgrades toward Passivhaus-aligned thermal envelopes.
- Glass Extension:Structural aluminum framing with low-emissivity glazing maximizes natural light penetration for horticultural applications.
- Summer Pavilion:Open-sided or partially enclosed timber structures prioritize ventilation over thermal performance for seasonal occupation.
- Art Studio:North-facing rooflights and dust extraction provisions accommodate creative production requirements.
- Playroom:Safety-rated glazing and rounded corner specifications address child occupancy regulations.
Insulated Cabin commands the established base. The steepest expansion runs through Home Office.
Material:
Material selection balances aesthetic integration with residential settings against maintenance burden and structural load characteristics.
- Timber:Pressure-treated softwood or thermally modified hardwood framing clad in cedar, larch, or composite weatherboarding. Swedish and Baltic supply chains face post-Brexit customs documentation friction extending procurement timelines.
- Composite Panels:Recycled polymer-wood fiber extrusions with integrated color-through finish eliminate re-staining cycles. Commercial small-business deployments in urban fringe locations favor specification for maintenance minimization.
- Aluminum:Powder-coated structural systems enable slender sightlines for contemporary architectural expressions.
- Polycarbonate:Multi-wall extruded sheets provide diffuse daylighting for horticultural and studio applications.
- PVC:Cellular extruded profiles offer cost-optimized weatherproofing for entry-level configurations.
Timber retains the volume anchor. Composite Panels are climbing the fastest as maintenance-averse commercial buyers enter the market.
Application:
End-use purpose determines spatial planning, services integration, and regulatory classification thresholds.
- Remote Working Space:Dedicated ergonomic layouts with 2.4m minimum ceiling heights, task lighting circuits, and fiber broadband termination points. Technology sector employers in Cambridge and Reading commuter belts now stipulate such infrastructure as hybrid employment conditions.
- Leisure Room:Flexible open-plan configurations accommodating seating, storage, and occasional guest sleeping.
- Fitness Studio:Reinforced flooring for equipment loads and enhanced ventilation for moisture management.
- Entertainment Area:Integrated audio-visual cabling and bar/kitchenette provisions for social hosting.
- Guest Accommodation:Sanitary facilities and sleeping areas trigger building control scrutiny for permanent habitation classification.
Remote Working Space has seized the growth pole. Leisure Room holds the installed legacy base.
End User:
Customer type dictates procurement pathway, specification authority, and post-installation support expectations.
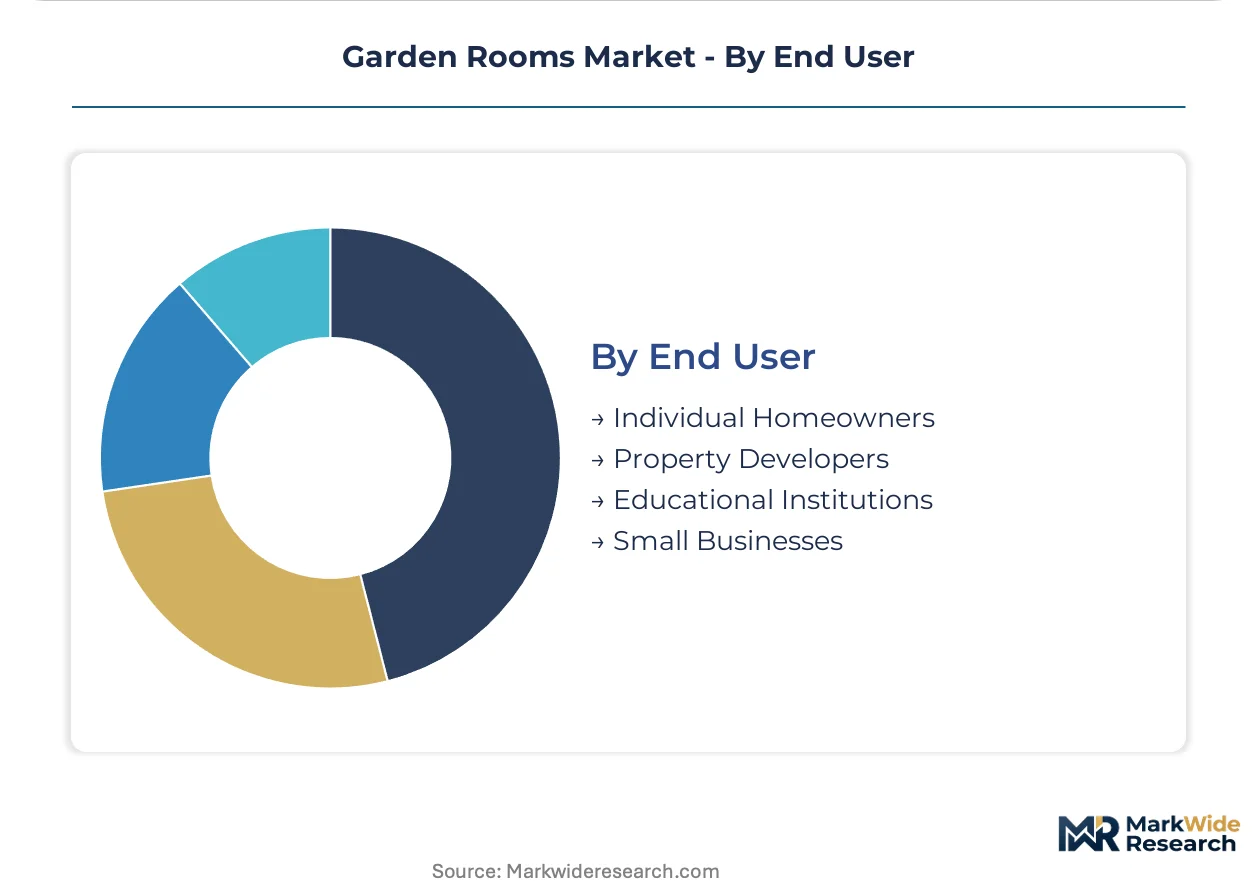
- Individual Homeowners:Direct purchasers prioritizing turnkey delivery certainty and single-point warranty accountability. London commuter belt counties exhibit highest penetration where property values justify premium modular construction.
- Small Businesses:Freelance consultants and micro-enterprises repurposing structures as client-facing consultation spaces with professional-grade acoustic treatment.
- Property Developers:Volume procurement for new-build garden plots seeking permitted development compliance without planning delays.
- Educational Institutions:Schools and colleges specifying modular classrooms or therapy spaces within constrained site footprints.
Individual Homeowners dominate current deployment. Small Businesses are gaining share fastest as freelance professionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Felixstowe anchors UK garden room supply chains, handling pressure-treated timber imports from Swedish and Baltic producers that feed manufacturing clusters across Kent and Surrey.
United Kingdom
England's Home Counties generate concentrated demand as hybrid work policies at London financial services firms mandate dedicated home office infrastructure. Permitted development rights eliminate planning delays for structures below 2.5m eaves height, accelerating purchase-to-occupancy timelines. Manufacturing clusters in Kent and Surrey leverage parametric design software to compress quotation-to-production cycles from weeks to days.
Germany
Freelance professionalization across Berlin and Munich metropolitan areas stimulates demand for client-facing consultation spaces with professional-grade acoustic treatment. The country's national building regulator enforces strict energy efficiency standards that elevate thermal performance specifications toward Passivhaus alignment. Fabricators in Bavaria and Baden-Württemberg specialize in timber-composite hybrid framing systems that reduce material weight while maintaining structural load ratings.
France
Île-de-France commuter belt households seek year-round habitable ancillary space as remote work arrangements stabilize across technology and consulting sectors. The country's national environmental agency implements REACH-aligned chemical safety protocols affecting treated timber preservative specifications. Regional producers in Auvergne-Rhône-Alpes concentrate on compact sub-20 square meter configurations for urban plots with restricted garden footprints.
Netherlands
Randstad urban density constraints drive specification toward crane-free installation systems for restricted-access residential plots. The country's national environmental regulator enforces F-Gas Regulation-aligned phase-down of hydrofluorocarbon refrigerants in heat pump climate systems. Fabricators in the Eindhoven region integrate building information modeling workflows that auto-generate cutting schedules from customer configuration inputs.
Sweden
Domestic softwood supply chains face export documentation friction to UK ports, extending lead times for pressure-treated structural framing during peak construction seasons. The country's national forestry and environmental regulator maintains sustainable sourcing certification requirements that shape export timber specifications. Production clusters in southern timber regions concentrate on engineered timber systems with recycled polymer cores.
Garden Rooms Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between vertically integrated design-to-installation providers and pure manufacturing specialists lacking field capabilities. Three archetypes dominate: turnkey solution bundlers, modular configuration platforms, and heritage timber craftspeople. Competitive moves concentrate on backward integration into captive timber supply and geographic expansion into underpenetrated regional markets.
Among UK-based fabricators, Crane Garden Buildings anchors the vertically integrated tier through design-to-installation workflow control, Swift Unlimited Garden Rooms occupies the bespoke configuration platform position, and Green Retreats exemplifies premium turnkey specialization with rapid on-site assembly capabilities. These three represent distinct strategic postures within a market consolidating around single-source contract relationships rather than fragmented component procurement.
| Leading Market Players |
|---|
| Crane Garden Buildings |
| Swift Unlimited Garden Rooms |
| Leka Garden Rooms |
| Westbury Garden Rooms |
| Tiger Modular |
| Smart Modular Buildings |
| Eden Garden Rooms |
| Oeco Garden Rooms |
| Green Retreats |
| Others |
Pricing and Supply Chain Analysis
Post-Brexit customs documentation friction at UK ports determines both pricing tier spreads and supply chain shape, compressing margins on Swedish and Baltic timber-dependent products while rewarding fabricators with captive supply or alternative sourcing. Buyers face extended procurement timelines that stratify market access between time-sensitive premium purchasers and price-elastic economy segments.
Pricing Analysis
Volume-discount tiering structures separate turnkey installation bundles from component-only supply, with premium providers commanding 40-60% markups for single-source accountability. Price differentiation hinges on thermal certification grade and geographic delivery complexity, with Passivhaus-aligned specifications capturing substantial premiums. Cost compression in the economy tier intensifies as import timber bottlenecks force material substitution toward composite alternatives. Small businesses exhibit highest price sensitivity, while London commuter belt professional households prioritize delivery certainty over component cost optimization.
Supply Chain Analysis
Swedish and Baltic softwood feedstock anchors structural framing supply, with secondary inputs drawn from German engineered timber and Chinese composite panel producers. Raw material dependencies center on pressure-treated softwood, PIR insulation cores, and low-global-warming-potential heat pump refrigerants. Single-source vulnerability concentrates in UK port customs clearance capacity, where documentation bottlenecks cascade through manufacturing schedules. Distribution runs through vertically integrated design-to-installation providers rather than fragmented component wholesalers, concentrating contract value with field-capable fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from conservatory installers repurposing legacy expertise into garden room construction, a threat that commoditizes basic specification tiers. Market consolidation around turnkey delivery favors providers with installation control.
For Market Incumbents: Entrench competitive position through backward integration into captive timber supply chains and parametric design software deployment that compresses quotation-to-production cycles. Counter conservatory installer encroachment by embedding building control compliance expertise into standard service bundles. Prioritize certification investment in BREEAM and Passivhaus alignment to elevate specification floors beyond substitute reach. For New Entrants and Emerging Players: Build out installation capabilities in Wales and Northern England, where property value differentials have suppressed adoption below southeastern England levels. Target compact sub-20 square meter configurations for urban fringe plots with restricted garden footprints. Pursue freelance consultant segments with professional-grade acoustic treatment as the primary go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with design-to-installation workflow control. Long-term viability across a 5-10 year window rests on regulatory adaptation capacity as permitted development thresholds evolve. Monitor local authority building control interpretation variance as the critical inflection signal for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive sourcing from Swedish and Baltic producers insulates against post-Brexit customs documentation friction. |
| Parametric Design Platform Deployment | Auto-generated cutting schedules from Kent and Surrey fabricators compress quotation-to-production cycles dramatically. |
| Passivhaus Certification Investment | Thermal performance alignment commands premium positioning as hybrid work mandates elevate specification floors. |
| Installation Capability Expansion | Field teams in Wales and Northern England address acute regional labor scarcity constraining market penetration. |
| Smart Home Integration Partnership | Fiber broadband and climate control coordination with primary dwelling networks differentiates turnkey providers. |
Research Methodology
Initial hypotheses were tested against primary input from garden room fabricators, installation contractors, building control inspectors, and hybrid work policy managers at financial services employers, then refined through secondary validation. Customs documentation data from UK port authorities, timber trade association reports, permitted development rights filings, and HVAC equipment import records anchored supply-side assessment. Bottom-up segmentation modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product architecture, material specification, application purpose, and end-user procurement pathway. CAGRs were derived from installed base growth rates and replacement cycle analysis, incorporating hybrid work policy permanence assumptions and building control regulatory evolution as industry-specific forecast inputs.
Stress conditions across timber import lead times, skilled labor availability, and local authority compliance interpretation variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about permitted development rights stability and employer infrastructure mandates. Cross-checking against UK planning portal application data and conservatory sector shipment volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Middle-East Christmas Tree Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Outdoor Furniture Market