
 Brush Rocker Market | 2026-2036
Brush Rocker Market Size, Share, and Industry Trends Forecast 2026-2036
Brush Rocker Market Outlook
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers, forcing reformulation investments that smaller competitors struggle to fund. Mersen leverages its vertical integration into carbon raw material sourcing to absorb these compliance costs without margin erosion. Schunk Carbon Technology anchors its position through R&D intensity in high-temperature composite formulations. Helwig Carbon Products differentiates via specialized distribution channels serving North American motor repair facilities.
A brush rocker is a mechanical component that maintains consistent brush-to-commutator or brush-to-slip-ring contact pressure in rotating electrical machines, typically fabricated from carbon-graphite composites, metal-impregnated carbon, or resin-bonded materials with specified electrical resistivity between 10 and 100 μΩ·m and operating temperature thresholds exceeding 150°C. Electric rockers dominate installed base volumes across industrial motor fleets, though hybrid rockers are gaining fastest in precision automotive applications where variable load conditions demand adaptive contact force. Medium-size units capture the deepest margin pools by balancing unit economics against the customization requirements that small and extra-large variants impose on production lines.
The EPA regulates particulate emissions from carbon brush manufacturing processes in the United States, while China's MEE enforces dual carbon goals that constrain energy-intensive carbonization stages. Germany's KBA mandates specific brush contact material standards for railway traction motors, creating a certification barrier for non-European suppliers. Stakeholders must monitor how evolving carbon border adjustment mechanisms and material traceability requirements reshape supplier qualification timelines across major procurement regions.
Market Dynamics
Electric vehicle motor maintenance protocols are tightening procurement specifications across automotive supplier networks, forcing brush rocker manufacturers to absorb compliance costs while defending margin positions in a market where carbon composite formulations determine competitive viability.
Growth Catalysts
- REACH compliance mandates:European carbon emission regulations are elevating product specifications for brush contact materials, creating qualification barriers that favor suppliers with in-house carbonization capabilities.
- EV motor fleet expansion:Automotive workshops in Germany and Japan are expanding brush rocker procurement volumes as electric vehicle maintenance schedules standardize component replacement intervals.
- Carbon composite advances:Resin-bonded material formulations with enhanced thermal thresholds above 150°C are opening applications in high-speed traction motors for railway systems.
Market Restraints
- Petroleum coke price volatility:Primary carbon feedstock cost swings compress margins for non-integrated manufacturers lacking captive supply arrangements.
- Chinese supply concentration:Energy-intensive carbonization capacity clusters in specific industrial zones, exposing procurement timelines to regional power rationing under dual carbon enforcement.
- Metal-impregnated carbon substitution:Sintered bronze alternatives are capturing share in low-speed industrial motor applications where electrical resistivity requirements are less stringent.
Strategic Opportunities
- Precision automotive hybrid rockers:Variable load condition applications in electric power steering systems present white space for adaptive contact force technologies.
- US Midwest supplier cluster proximity:Geographic concentration of automotive OEMs in Michigan and Ohio enables just-in-time inventory partnerships with tier-one motor repair facilities.
- MEE dual carbon policy tailwinds:China's energy efficiency mandates are accelerating domestic supplier consolidation, creating partnership openings for foreign composite technology licensors.
Industry Challenges
- High-temperature composite R&D talent scarcity:Specialized polymer chemists and carbon materials engineers command premium compensation, constraining mid-tier supplier innovation pipelines.
- KBA railway certification timelines:German Federal Motor Transport Authority brush contact material approvals require extended validation cycles that delay new product commercialization.
- Legacy fleet interoperability:Electric rocker retrofits into existing commutator motor installations demand precise dimensional tolerances that strain quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brush Rocker Market |
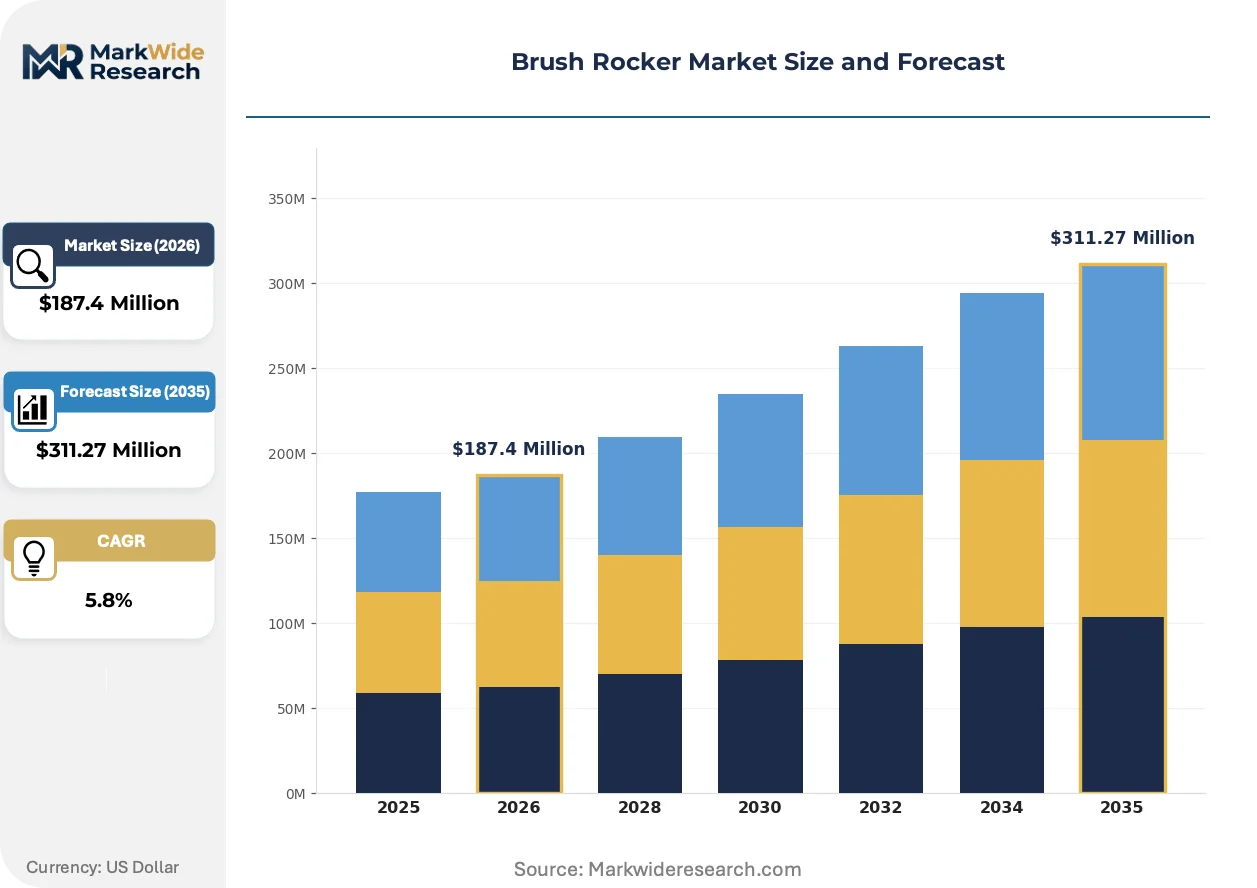
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rockers, Manual Rockers, Hybrid Rockers, Pneumatic Rockers End User: Manufacturing Units, Construction Sites, Automotive Workshops, Art Studios Size: Small, Medium, Large, Extra Large Installation: Portable, Fixed, Adjustable, Wall-mounted |
| Companies Covered | Mersen, Schunk Carbon Technology, Helwig Carbon Products, Morgan Advanced Materials, Toyo Tanso Co., Ltd., SGL Carbon, Nava Bharat Ventures Limited, Ohio Carbon Industries, Tokai Carbon Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brush Rocker Market Strategic Shifts
Material science breakthroughs and regulatory stringency are converging to reshape competitive positioning in brush rocker manufacturing, with formulation expertise emerging as the primary differentiator in supplier selection criteria.
Carbon-graphite composites with engineered electrical resistivity between 10 and 100 μΩ·m are absorbing market share from traditional metal-impregnated variants in high-frequency motor applications. Railway traction motor manufacturers in Germany are adopting these formulations fastest, driven by KBA-mandated contact reliability standards. The technology is absorbing compliance costs that would otherwise erode supplier margins under REACH reformulation requirements.
EPA particulate emission regulations on carbon brush manufacturing processes are forcing production facility upgrades across North American suppliers. The industrial consequence is capital migration toward enclosed carbonization systems with thermal oxidizer integration. Small-batch custom brush rocker producers serving motor repair facilities face the steepest compliance burden relative to their revenue base.
Automotive OEMs are consolidating vendor bases around suppliers capable of delivering NMPA-certified materials with full batch traceability. Tier-one motor component distributors are displacing traditional job-shop procurement channels in the United States Midwest manufacturing belt. This concentration is most visible in Michigan, where electric vehicle powertrain suppliers now mandate direct supplier relationships for brush contact components.
Brush Rocker Market Segmentation
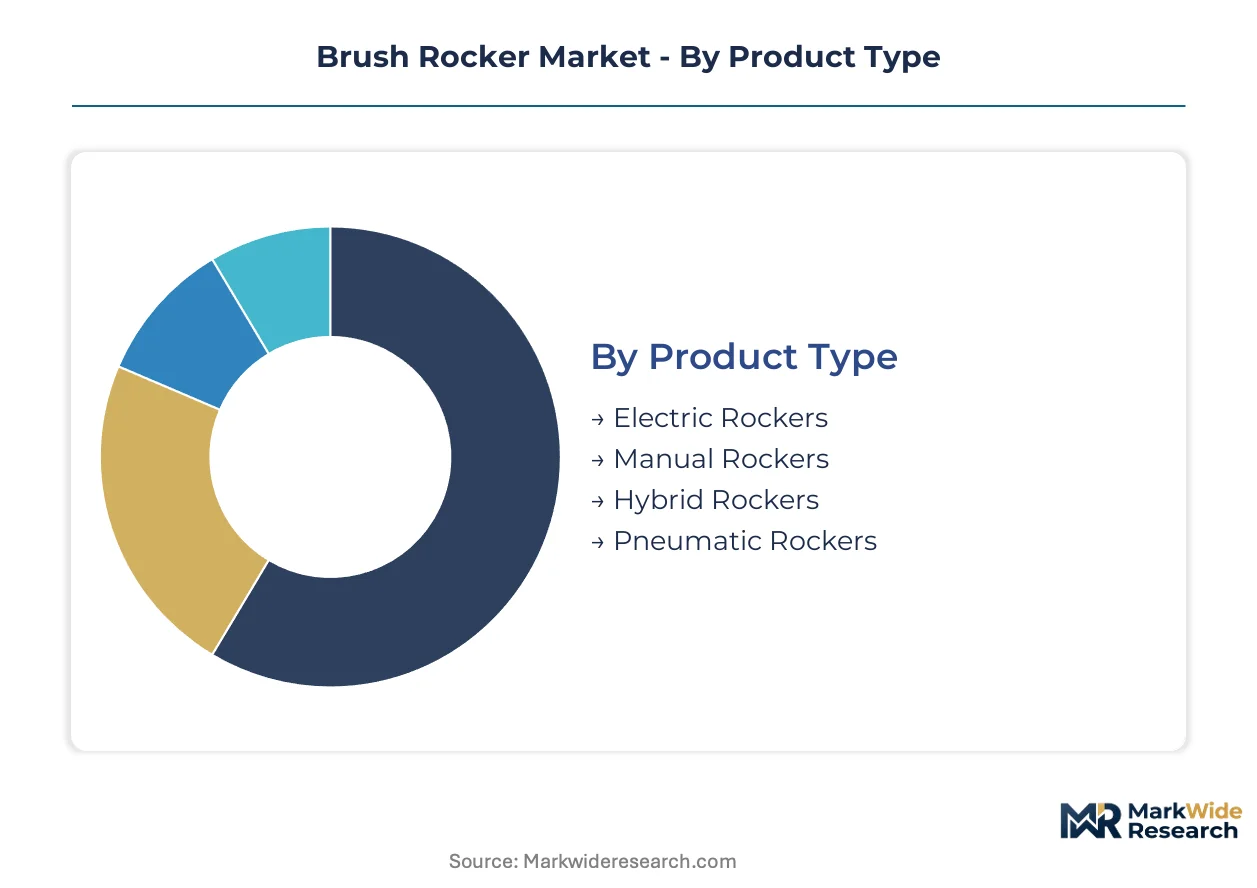
Brush rocker procurement patterns diverge sharply across application contexts, with industrial motor fleets favoring standardized electric units while precision automotive applications demand adaptive hybrid configurations. Material specification tiers and installation constraints create distinct margin architectures that reshape supplier qualification requirements.
Product Type:
Standardization dominates high-volume electric rocker production, whereas hybrid configurations require intensive customization to match variable load motor profiles.
- Electric Rockers:Spring-loaded mechanisms with fixed contact pressure profiles, typically fabricated from carbon-graphite composites with electrical resistivity between 10 and 100 μΩ·m. Demand concentrates in United States Midwest manufacturing belt where automotive supplier clusters drive volume procurement for industrial motor fleets. EPA particulate emission regulations on carbon brush manufacturing processes elevate compliance costs for non-integrated suppliers.
- Hybrid Rockers:Adaptive contact force technologies combining mechanical and electromechanical actuation elements. Expansion is fastest in German and Japanese automotive workshops where electric vehicle motor maintenance protocols tighten replacement interval specifications. KBA-mandated contact reliability standards for railway traction motors favor these formulations in high-speed applications.
- Manual Rockers:Hand-adjusted pressure mechanisms for legacy commutator motor installations requiring precise dimensional tolerances.
- Pneumatic Rockers:Compressed-air actuated systems deployed in heavy industrial environments with extreme thermal cycling.
Most installed capacity flows through Electric Rockers. Expansion is steepest in Hybrid Rockers.
End User:
Cost tier stratification separates capital-intensive manufacturing procurement from price-sensitive art studio purchases, with automotive workshops occupying the premium-mid tier.
- Manufacturing Units:High-volume procurement of standardized medium-size electric rockers for industrial motor fleets. Demand clusters in Michigan and Ohio automotive supplier networks where tier-one motor component distributors consolidate vendor bases around NMPA-certified materials with full batch traceability.
- Automotive Workshops:Specialized procurement of precision hybrid rockers for electric power steering systems and EV motor maintenance. German workshops anchor European demand as REACH compliance mandates elevate product specifications for brush contact materials.
- Construction Sites:Portable installation preferences drive demand for ruggedized pneumatic and manual rocker variants.
- Art Studios:Small-batch procurement of entry-tier manual rockers with minimal customization requirements.
Manufacturing Units absorb the deepest volume pools. Automotive Workshops command the strongest pricing power.
Size:
Volume-maturity dynamics favor medium-size production economics while extra-large variants strain quality control systems with dimensional tolerance demands.
- Medium:Balances unit economics against customization overhead that small and extra-large variants impose. Captures the deepest margin pools across United States Midwest supplier clusters and German railway traction motor applications. Resin-bonded material formulations with thermal thresholds exceeding 150°C open high-speed motor applications in this size class.
- Small:Precision applications in electric power steering and compact industrial drives. Japanese automotive OEMs specify these for space-constrained EV powertrain components.
- Large:Heavy industrial motor installations in mining and steel processing.
- Extra Large:Railway traction and marine propulsion systems requiring extended validation cycles under KBA certification protocols.
Medium units concentrate production capacity. Small units gain share fastest in precision automotive electrification.
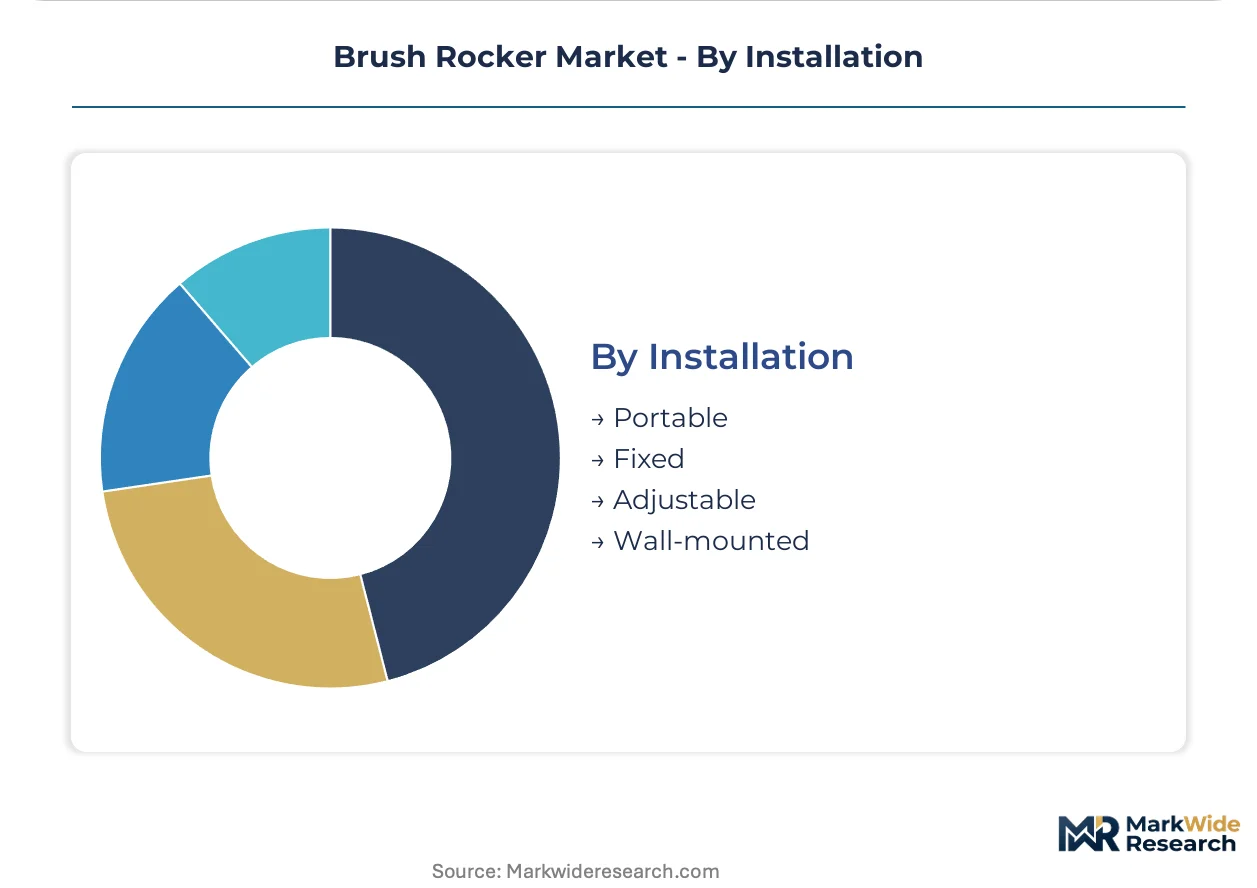
Installation:
Supply concentration in enclosed carbonization systems with thermal oxidizer integration favors fixed installations, while portable variants face steepest compliance burdens relative to revenue base.
- Fixed:Permanent mounting in industrial motor housings with integrated cooling. Dominates manufacturing unit procurement in China where MEE dual carbon goals constrain energy-intensive carbonization capacity.
- Portable:Field-service configurations for motor repair facilities. Small-batch producers face capital migration pressures from EPA particulate emission regulations.
- Adjustable:Modular pressure calibration for variable load conditions in hybrid automotive applications.
- Wall-mounted:Compact configurations for art studios and light commercial environments.
Fixed installations anchor the installed base. Adjustable configurations climb fastest in adaptive contact force applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized carbon materials engineers and polymer chemists concentrate in German industrial zones, Japanese precision manufacturing corridors, and the United States Midwest automotive belt, anchoring regional competitive advantages in brush rocker fabrication.
United States
Automotive supplier clusters in Michigan and Ohio drive procurement volume for industrial motor fleets. EPA particulate emission regulations on carbon brush manufacturing processes force capital migration toward enclosed carbonization systems with thermal oxidizer integration. Tier-one motor component distributors in Detroit consolidate vendor bases around NMPA-certified materials with full batch traceability.
Germany
Railway traction motor manufacturers and automotive workshops anchor European demand for precision hybrid rockers. KBA mandates specific brush contact material standards that create certification barriers for non-European suppliers. Industrial concentration in Bavaria and Baden-Württemberg hosts REACH-compliant carbon composite formulation expertise.
China
Domestic supplier consolidation accelerates under MEE dual carbon goals that constrain energy-intensive carbonization capacity. Energy efficiency mandates create partnership openings for foreign composite technology licensors. Carbonization capacity clusters in specific industrial zones expose procurement timelines to regional power rationing.
Japan
Automotive OEMs specify small-size precision rockers for space-constrained EV powertrain components. METI industrial standards govern material specifications for high-temperature composite applications. Manufacturing corridors around Nagoya and Osaka concentrate adaptive contact force technology development.
Brush Rocker Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Carbon materials conglomerates leverage backward integration into petroleum coke sourcing to absorb feedstock volatility. Pure-play specialists anchor positions through R&D intensity in high-temperature formulations. Strategic moves concentrate on geographic expansion into US Midwest supplier clusters and technology licensing partnerships under China's MEE policy tailwinds.
Among French and German carbon technology groups, Mersen and Schunk Carbon Technology occupy positions exemplifying conglomerate-scale material science capabilities. Helwig Carbon Products represents the North American specialist archetype serving motor repair facility distribution channels. These three anchors illustrate how supplier selection criteria increasingly favor formulation expertise over volume scale.
| Leading Market Players |
|---|
| Mersen |
| Schunk Carbon Technology |
| Helwig Carbon Products |
| Morgan Advanced Materials |
| Toyo Tanso Co., Ltd. |
| SGL Carbon |
| Nava Bharat Ventures Limited |
| Ohio Carbon Industries |
| Tokai Carbon Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM consolidation around NMPA-certified materials with full batch traceability is forcing suppliers to absorb certification costs while defending margin positions in a market where carbon composite formulation expertise determines competitive viability.
Pricing Analysis
The bundled-versus-unbundled service split separates premium suppliers offering integrated formulation-development partnerships from commodity producers competing on per-unit spot pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-compliant carbon-graphite composites commanding substantial premiums over metal-impregnated alternatives. Cost compression in standard-tier electric rockers is intensifying because petroleum coke price volatility squeezes non-integrated manufacturers. Tier-one motor component distributors exhibit lowest price sensitivity, while small-batch motor repair facilities face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from German railway traction motor manufacturers and US Midwest automotive OEMs mandate multi-supplier qualification, spreading procurement across China, Germany, and Japan to mitigate concentration risk. Carbon feedstock draws from petroleum coke suppliers in the United States and China, resin systems from German specialty chemical producers, and precision machining capacity from Japanese manufacturing corridors. Single-source vulnerability in energy-intensive carbonization stages exposes timelines to regional power rationing under China's MEE dual carbon enforcement. Distribution runs through tier-one motor component distributors consolidating vendor bases in Michigan and Ohio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brush rocker market functions as a stable compounder anchored by irreversible fleet electrification mandating standardized maintenance protocols and replacement interval specifications across automotive and industrial motor applications.
For Market Incumbents: Anticipate sintered bronze substitution threats in low-speed industrial segments by accelerating R&D intensity in high-temperature composite formulations exceeding 150°C thermal thresholds. Anchor positions through backward integration into petroleum coke sourcing to absorb feedstock volatility without margin erosion. Prioritize KBA certification pipeline investments to defend German railway traction motor share against emerging Asian competitors. For New Entrants and Emerging Players: MEE dual carbon goals in China open a window for foreign composite technology licensors to partner with domestic suppliers facing energy-intensive carbonization capacity constraints. Target precision automotive hybrid rockers for electric power steering systems where adaptive contact force technologies remain underpenetrated. Pursue US Midwest supplier cluster proximity through just-in-time inventory partnerships with tier-one motor repair facilities in Michigan and Ohio. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play specialists possessing captive carbonization capabilities and established KBA or NMPA certification pipelines. The five-to-ten-year viability window favors acquisition targets with demonstrated formulation expertise in resin-bonded composites rather than volume-scale commodity producers. Watch for inflection in carbon border adjustment mechanism implementation timelines reshaping supplier qualification economics across European procurement regions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Feedstock | Captive petroleum coke sourcing absorbs price volatility compressing non-integrated competitor margins. |
| KBA Certification Pipeline Investment | German Federal Motor Transport Authority approvals create multi-year barriers against non-European suppliers. |
| Precision Hybrid Rocker Development | Adaptive contact force technologies address variable load conditions in electric power steering systems. |
| US Midwest Distribution Partnership | Geographic proximity to Michigan and Ohio automotive OEMs enables just-in-time inventory relationships. |
| MEE Policy Tailwind Licensing | China's energy efficiency mandates accelerate domestic supplier consolidation creating technology transfer openings. |
Study Parameters
Direct dialogue with carbon materials engineers, automotive procurement managers at tier-one motor component distributors, plant managers at carbonization facilities, and railway traction motor maintenance directors grounded qualitative insights. Secondary validation drew from EPA enforcement records on particulate emissions, KBA certification databases, NMPA material registration filings, and customs trade data tracking carbon-graphite composite flows. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, size, and installation segmentation dimensions.
Bottom-up volume modeling aggregated individual application demand curves while top-down approaches cross-referenced industrial motor fleet data and EV powertrain production forecasts across the projection horizon. Segmentation dimensions included electric versus hybrid rocker technology, manufacturing versus automotive workshop end-use, medium versus small size classes, and fixed versus portable installation configurations. CAGRs derived from regression analysis of historical procurement patterns adjusted for regulatory phase-in schedules and material substitution elasticities. Forecast inputs incorporated REACH reformulation cost curves and MEE dual carbon policy implementation timelines.
Revisions become necessary when carbon border adjustment mechanisms accelerate implementation, petroleum coke supply disruptions persist beyond seasonal patterns, or KBA certification timelines compress substantially. Deviation in China's regional power rationing severity under dual carbon enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Spray Covers Market