
 Retractable Awnings Market | 2026-2036
Retractable Awnings Market Size, Share, and Industry Trends Forecast 2026-2036
Retractable Awnings Market Outlook
Aluminum frame construction is broadening the addressable market for premium retractable awnings by reducing weight and extending corrosion resistance in coastal environments. Stobag leverages its European manufacturing footprint to sustain cost discipline across motorized product lines. SunSetter anchors the North American direct-to-consumer channel with simplified installation protocols. Somfy differentiates through proprietary automation ecosystems that integrate with residential building management systems.
Retractable awnings are deployable shade structures consisting of a tensioned fabric membrane mounted on a folding or rolling frame mechanism, typically spanning 8 to 40 feet in projection length, designed to reduce solar heat gain and ultraviolet exposure for adjacent building surfaces. They serve primarily as adaptive building envelopes that modulate thermal loads and extend usable outdoor floor area without permanent structural commitment. Motorized awnings command the dominant share of value generation due to integration with wind sensors and smartphone controls, while semi-automated variants represent the fastest-expanding category as price-sensitive buyers seek partial automation. Acrylic fabric dominates material selection for colorfastness and breathability, though vinyl fabrics are capturing share in commercial applications demanding waterproof performance and extended duty cycles.
The US Environmental Protection Agency references solar shading in Energy Star building guidelines, while the EU Green Deal and F-Gas Regulation indirectly shape demand by tightening cooling-efficiency requirements for commercial structures. Germany's KBA and France's national building codes both recognize retractable shading as qualifying thermal improvement measures for renovation subsidies. Stakeholders must monitor how municipal zoning amendments treat projection limits and wind-load ratings, as these parameters increasingly determine product configurability and installation cost structures.
Market Dynamics
Municipal energy codes across suburban North America are rewriting installation economics by classifying retractable shading as qualifying thermal envelope improvements, compressing payback periods for motorized systems and redrawing competitive positioning between premium fabricators and mass-market assemblers.
Growth Catalysts
- Building efficiency mandates:Germany's KBA and France's national renovation subsidy frameworks now explicitly recognize retractable awnings as thermal improvement measures, channeling public capital into residential upgrades.
- Smart-home convergence:Integration with wind sensors and smartphone controls is pulling motorized systems into new construction specifications across Australia's efficiency-rated housing developments.
- Coastal corrosion resistance:Aluminum frame advances are opening addressable demand in Florida, California, and Mediterranean shoreline municipalities where salt exposure previously excluded metal-framed products.
Market Restraints
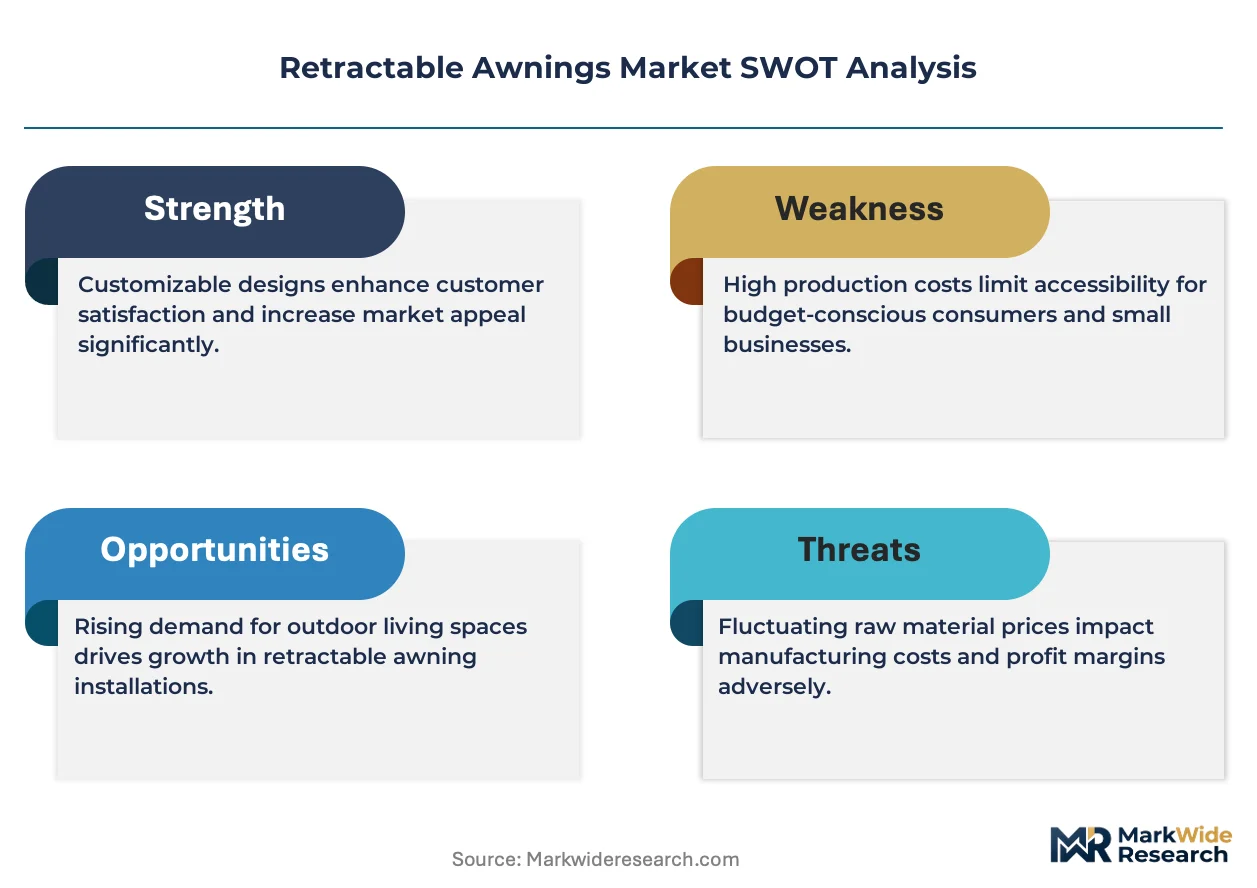
- Aluminum price volatility:Frame material input costs swing with LME trading patterns, squeezing margin structures for mid-tier fabricators without captive extrusion capacity.
- Fabric supply concentration:Acrylic membrane production clusters in Western European textile centers, exposing North American assemblers to transatlantic shipping disruptions and currency hedging costs.
- Permanent structure substitution:Pergolas with fixed louvered roofs are capturing shade-seeking homeowners who prioritize storm resilience over deployable flexibility.
Strategic Opportunities
- Commercial building retrofits:EU Green Deal cooling-load reduction targets are creating specification pipelines for large-span motorized systems across aging office stock in France and Germany.
- Direct-to-consumer channel expansion:Simplified installation protocols are enabling bypass of traditional contractor networks, compressing customer acquisition costs for digitally native entrants.
- Sensor-to-BMS integration:Convergence of photovoltaic triggers with residential building management systems is opening premium pricing tiers in efficiency-conscious Australian suburbs.
Industry Challenges
- Wind-load certification complexity:Municipal zoning amendments are fragmenting approval standards across jurisdictions, forcing fabricators to maintain multiple test documentation libraries.
- Installation workforce scaling:Demand for skilled technicians who can integrate motorized systems with existing electrical infrastructure is outstripping vocational training pipeline output in rapidly suburbanizing counties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retractable Awnings Market |
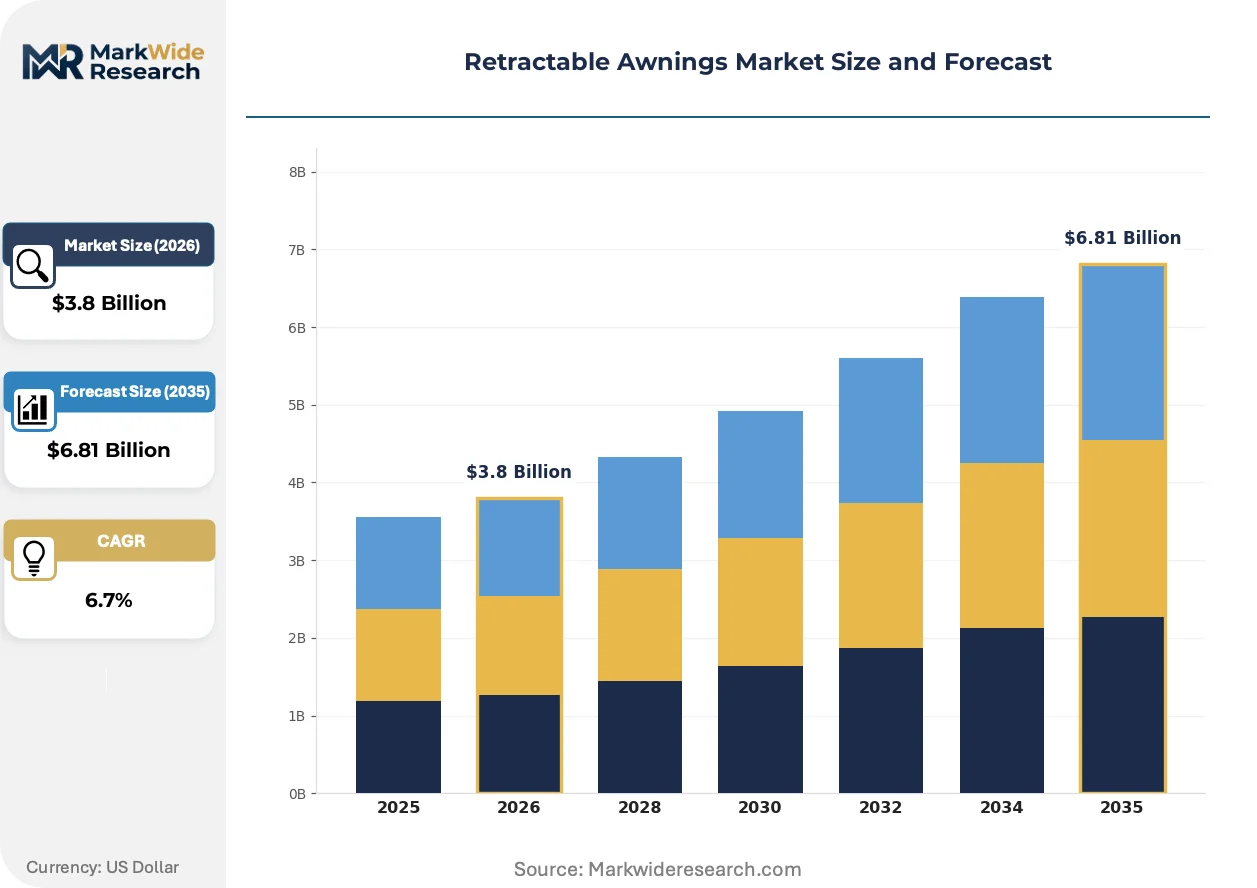
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Awnings, Motorized Awnings, Semi-automated Awnings, Fixed Awnings Material: Acrylic Fabric, Polyester Fabric, Vinyl Fabric, Aluminum Frame Application: Residential Use, Commercial Use, Outdoor Events, Patio Coverage Installation Type: Wall-mounted, Freestanding, Window-mounted, Retractable Roof Systems |
| Companies Covered | Marygrove Awnings, Stobag, SunSetter, Luxaflex, Helioscreen, Sunesta, Advaning, Aleko, Somfy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retractable Awnings Market Strategic Shifts
Fabrication techniques and control architectures are converging to compress installed costs while extending operational lifespans, with particular intensity around automation integration and material substitution.
Aluminum-extrusion framing systems are modularizing the physical installation process, allowing on-site assembly without specialized welding equipment. Regional contractors across Florida and California are adopting these systems to reduce crew specialization requirements. The technology is modularizing supply chain footprints by enabling flat-pack shipping and local final assembly, compressing landed costs for distant markets.
The EU F-Gas Regulation is tightening cooling-efficiency requirements for commercial structures, indirectly elevating retractable shading in renovation specifications. Building energy auditors in France and Germany now routinely model solar heat gain reduction from deployable awnings. Commercial property managers are responding by prioritizing motorized systems with automated deployment triggers in capital planning cycles.
Buyer preference is rotating toward outcome-based specification rather than component-centric procurement, with architects bundling shading performance guarantees into envelope design contracts. This pattern is displacing traditional fabric-versus-frame sourcing decisions in German commercial new-build projects. The shift is most visible in efficiency-rated residential developments across Australian metropolitan peripheries where whole-building energy modeling dominates vendor selection.
Retractable Awnings Market Segmentation
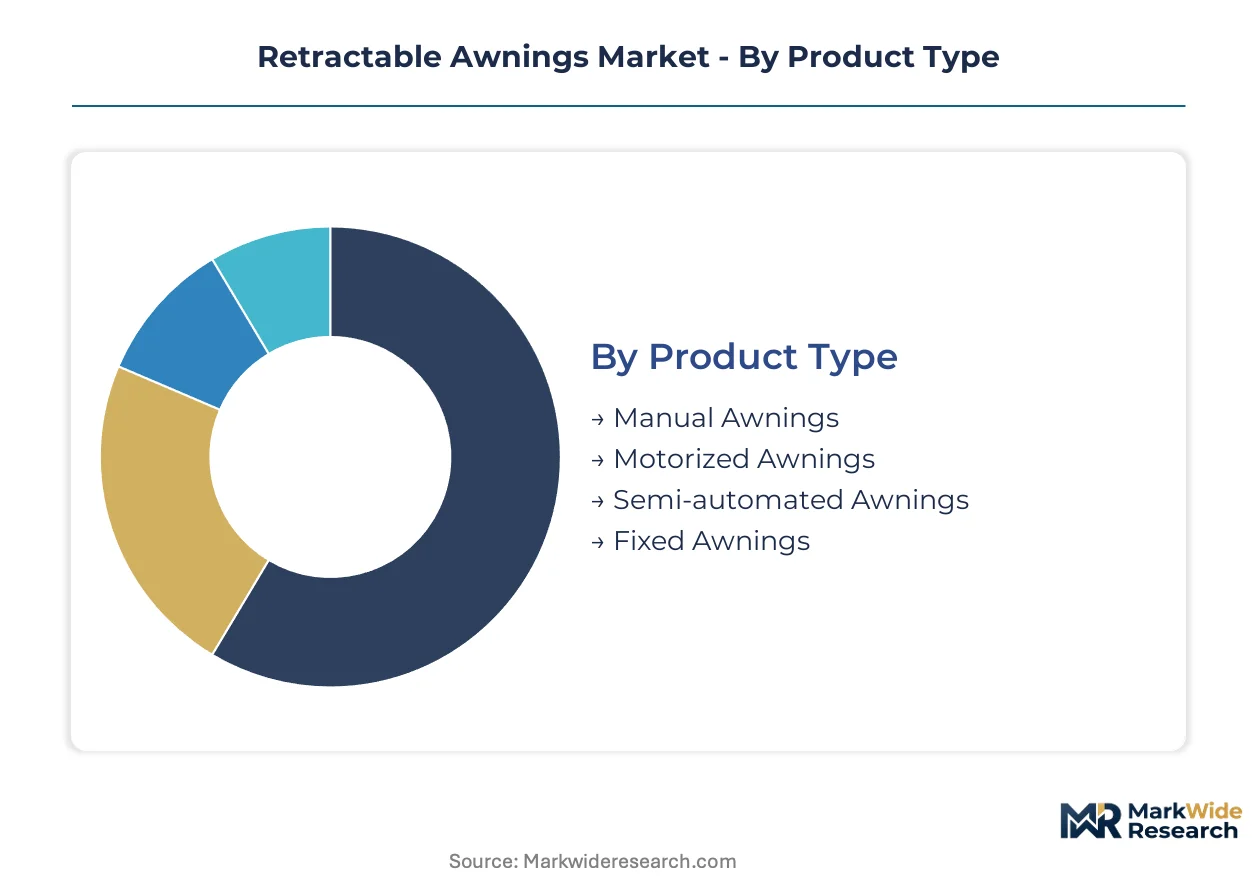
Retractable awning procurement decisions hinge on upgrade cycles that range from immediate fabric replacement to full system modernization. Understanding how product type, material, application, and installation method intersect with these replacement timelines reveals where specification power concentrates and margin pools form.
Product Type:
Replacement cycles vary dramatically across automation tiers, with motorized systems demanding electrical infrastructure upgrades that extend project timelines and inflate total installed cost.
- Motorized Awnings:These systems integrate wind sensors, smartphone controls, and building management system interfaces. Demand concentrates in German and Australian efficiency-rated housing developments where KBA standards and NatHERS ratings reward automated solar heat gain reduction.
- Semi-automated Awnings:Partial automation with manual override capabilities captures price-sensitive buyers seeking wind-responsive deployment without full electrical integration. Australian suburban homeowners expanding covered outdoor living spaces drive fastest uptake in this tier.
- Manual Awnings:Hand-crank or pull-rod operation dominates entry-level residential retrofits where electrical access is limited.
- Fixed Awnings:Permanent non-retractable structures serve commercial facades requiring constant weather protection without operational complexity.
Motorized Awnings sits at the top of the volume ranking, with Semi-automated Awnings climbing the fastest.
Material:
Material selection tracks directly to environmental exposure severity and duty cycle expectations, with coastal salt corrosion and commercial waterproofing demands splitting procurement patterns.
- Acrylic Fabric:Solution-dyed acrylic membranes deliver colorfastness and breathability for residential applications. Specifiers in Mediterranean shoreline municipalities and Florida coastal counties prioritize this material for UV resistance without thermal degradation.
- Aluminum Frame:Extruded aluminum construction reduces weight and extends corrosion resistance in salt-exposed environments. California and Florida contractors are modularizing flat-pack assembly protocols to compress installation labor costs.
- Vinyl Fabric:PVC-coated polyester substrates capture commercial applications demanding waterproof performance and extended duty cycles in high-traffic hospitality settings.
- Polyester Fabric:Uncoated or lightly coated woven polyester serves budget-conscious residential segments with moderate climate exposure.
Acrylic Fabric holds the dominant procurement position, though Aluminum Frame is gaining share fastest as coastal building codes tighten corrosion-resistance requirements.
Application:
Application segmentation maps to regulatory incentive structures, with residential energy-efficiency subsidies and commercial cooling-load mandates creating divergent specification pathways.
- Residential Use:Single-family and multi-family homeowners deploy retractable shading to extend usable outdoor floor area and reduce air conditioning loads. Suburban North American municipalities now classify these installations as qualifying thermal envelope improvements under stricter energy codes.
- Commercial Use:Office buildings, retail facades, and hospitality venues specify large-span motorized systems to meet EU Green Deal cooling-efficiency targets. French and German building energy auditors model solar heat gain reduction from deployable awnings in renovation specifications.
- Patio Coverage:Dedicated outdoor dining and entertainment space coverage drives demand for weather-responsive deployment in restaurant and residential settings.
- Outdoor Events:Temporary and seasonal deployment for festivals, markets, and sporting venues favors rapid-install freestanding systems.
Residential Use commands the largest installed base, while Commercial Use is expanding most quickly as EU F-Gas Regulation tightens cooling-efficiency requirements.
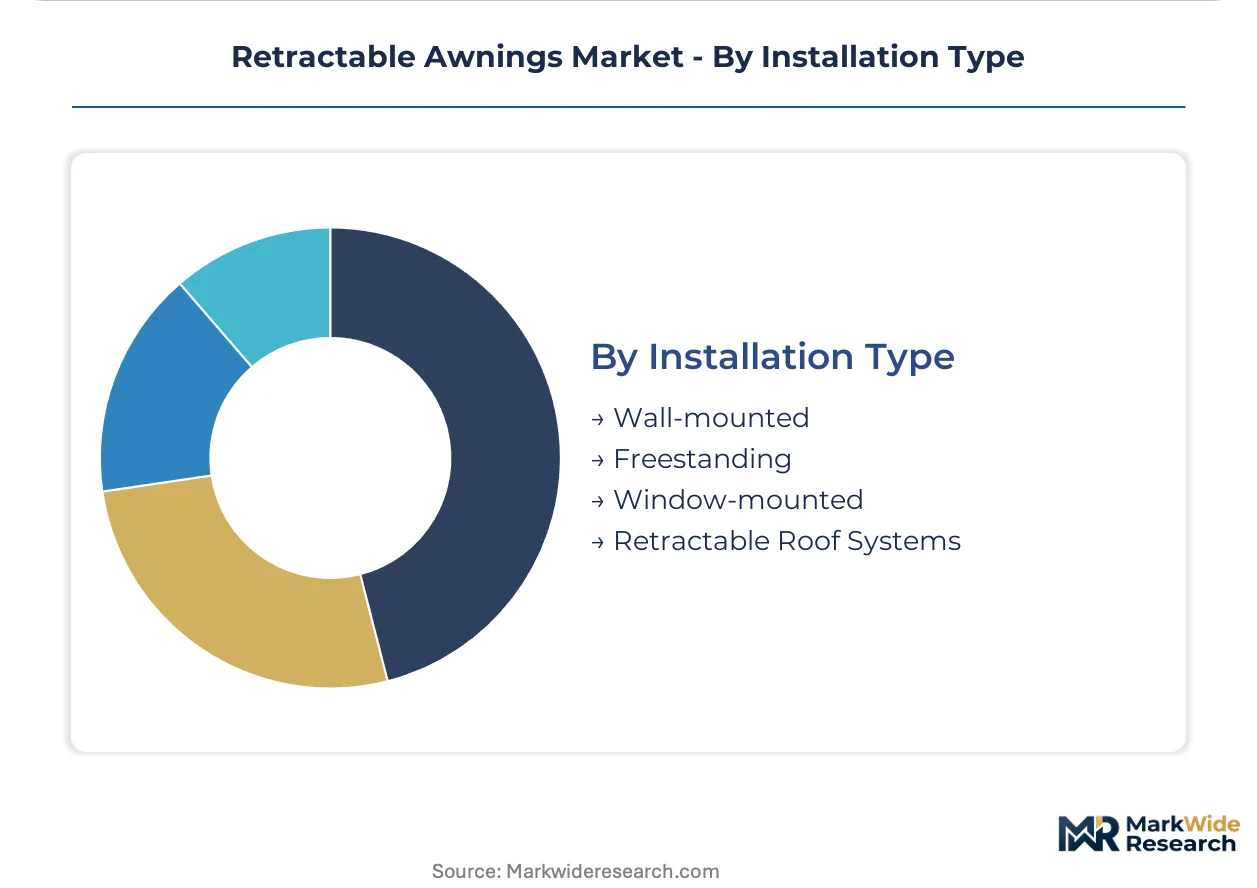
Installation Type:
Installation method determines zoning approval complexity and wind-load certification requirements, with wall-mounted systems facing fragmented municipal projection limits across jurisdictions.
- Wall-mounted:Direct facade attachment integrates with existing building envelopes and electrical infrastructure. This method dominates suburban North American residential retrofits where municipal zoning amendments increasingly govern projection limits and wind-load ratings.
- Retractable Roof Systems:Large-span overhead structures serve commercial courtyards and hospitality venues requiring complete weather protection. EU commercial property managers prioritize these systems with automated deployment triggers in capital planning cycles.
- Freestanding:Ground-anchored structures bypass facade attachment requirements for properties with structural limitations or historic preservation constraints.
- Window-mounted:Compact projection systems shade individual glazing units without full patio coverage, common in urban multi-family housing.
Wall-mounted retains the highest deployment frequency, with Retractable Roof Systems showing the steepest expansion trajectory in European commercial retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban municipalities across Germany, the United States, and Australia are rewriting energy codes to classify retractable shading as thermal envelope improvements. Fabricators in these markets capture renovation subsidies and new construction specifications by aligning product certification with local wind-load and corrosion-resistance standards.
United States
Florida and California contractors deploy aluminum-framed systems to meet coastal corrosion requirements in salt-exposed counties. The EPA references solar shading in Energy Star building guidelines, channeling specification toward motorized systems with wind sensors. SunSetter anchors the direct-to-consumer channel from its Massachusetts base with simplified installation protocols that bypass traditional contractor networks.
Germany
KBA standards recognize retractable awnings as qualifying thermal improvement measures for renovation subsidies, compressing payback periods for motorized installations. The EU F-Gas Regulation tightens cooling-efficiency requirements for commercial structures, elevating deployable shading in building energy audits. Stobag leverages its European manufacturing footprint to sustain cost discipline across motorized product lines serving efficiency-rated housing developments.
Australia
NatHERS ratings reward automated solar heat gain reduction in suburban metropolitan peripheries. Building efficiency standards now explicitly recognize retractable shading for cooling-load reduction, pulling motorized systems into new construction specifications. Somfy differentiates through proprietary automation ecosystems that integrate with residential building management systems across efficiency-conscious suburbs.
France
National building codes recognize retractable shading as qualifying thermal improvement measures, channeling public capital into residential upgrades. The EU Green Deal cooling-load reduction targets create specification pipelines for large-span motorized systems across aging office stock. Building energy auditors in Paris and Lyon routinely model solar heat gain reduction from deployable awnings in renovation specifications.
Canada
Health Canada guidelines intersect with provincial energy efficiency programs to incentivize solar shading in residential retrofits. Municipal zoning amendments in Ontario and British Columbia increasingly govern projection limits and wind-load ratings for wall-mounted installations. Contractors in the Greater Toronto Area adopt modular aluminum-extrusion framing systems to reduce crew specialization requirements and compress installation labor costs.
Retractable Awnings Market Competitive Environment
Global majors compete with regional champions across automation tiers and distribution channels. The vendor base clusters around three strategic archetypes: European fabricators with captive manufacturing and KBA-aligned certification, North American direct-to-consumer specialists with simplified installation protocols, and automation-technology licensors with proprietary sensor-to-BMS integration. Competitive positioning hinges on M&A activity consolidating regional installer networks and strategic partnerships bridging fabric supply with local assembly capacity.
Among European fabricators, Stobag and Somfy exemplify divergent archetypes within the premium tier. Stobag represents the manufacturing-integrated model with cost discipline across motorized product lines, while Somfy occupies a position as the automation-technology anchor with proprietary ecosystem integration. SunSetter anchors the North American direct-to-consumer vector with installation protocols that compress customer acquisition costs. Marygrove Awnings and Sunesta sit within the regional specialist tier, serving contractor-dependent channels with project-scale customization capabilities.
| Leading Market Players |
|---|
| Marygrove Awnings |
| Stobag |
| SunSetter |
| Luxaflex |
| Helioscreen |
| Sunesta |
| Advaning |
| Aleko |
| Somfy |
| Others |
Value Chain & Pricing Dynamics
LME aluminum price volatility cascades through retractable awning manufacturing into three distinct pricing tiers, with frame material swings compressing margins for mid-tier fabricators lacking captive extrusion capacity while premium European producers absorb shocks through backward-integrated supply chains.
Pricing Analysis
Input-cost pass-through from aluminum extrusions and acrylic fabric imports shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on automation integration depth and KBA-aligned certification status for German subsidy eligibility. Cost compression in the standard tier intensifies because aluminum price volatility squeezes mid-market assemblers without captive supply. Residential direct-to-consumer buyers exhibit highest price sensitivity, while commercial property managers pursuing EU Green Deal compliance show lowest sensitivity to premium motorized systems.
Supply Chain Analysis
Skilled technician availability constrains motorized system output in rapidly suburbanizing Florida and Australian metropolitan peripheries, forcing fabricators to compete for installation workforce against broader construction trades. Manufacturing concentrates in Germany, China, and regional North American assembly hubs. Production draws from acrylic membrane supply clustered in Western European textile centers, aluminum extrusion feedstock tied to LME trading patterns, and vinyl-coated polyester substrates from Asian coating facilities. Single-source vulnerability runs through transatlantic fabric shipping lanes. Distribution runs through contractor networks, direct-to-consumer platforms, and commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium motorized tiers where smart-home integration commands pricing power, while aluminum-extrusion modularity compresses installation labor costs across coastal markets.
For Market Incumbents: Deepen backward integration into aluminum extrusion capacity to insulate margin structures from LME volatility. Expand certified installer network density in Florida and California counties where coastal corrosion requirements favor captive frame production. Pergola substitution with fixed louvered roofs threatens deployable flexibility positioning. For New Entrants and Emerging Players: Begin with semi-automated awnings in Australian suburban peripheries where NatHERS ratings reward partial automation without full electrical infrastructure. Target price-sensitive residential expansions of covered outdoor living spaces. Deploy simplified installation protocols to bypass traditional contractor networks and compress customer acquisition costs. For Investors and Strategic Acquirers: Consolidation pressure builds where regional installer networks fragment across municipal zoning jurisdictions with divergent wind-load certification requirements. Long-term viability favors automation-technology licensors with proprietary sensor-to-BMS integration capabilities over pure manufacturing plays. Watch for inflection when EU F-Gas Regulation enforcement tightens commercial cooling-efficiency audit stringency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive frame production insulates German fabricators from LME price volatility and coastal corrosion requirements. |
| Sensor-to-BMS Integration Development | Somfy's proprietary automation ecosystems capture premium pricing in Australian efficiency-conscious suburbs. |
| Direct-to-Consumer Channel Expansion | SunSetter's simplified installation protocols compress customer acquisition costs in North American residential markets. |
| KBA Certification Investment | Qualification for German renovation subsidies channels public capital into motorized system upgrades. |
| Modular Flat-Pack Assembly Protocols | Regional California and Florida contractors reduce crew specialization requirements and landed costs for distant markets. |
Study Parameters
Coverage spans North America, Western Europe, and Australia-Pacific, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged awning fabricator operations directors, municipal building code officials, commercial property energy auditors, and residential contractor installation crews. Secondary sources included EPA Energy Star guidelines, KBA subsidy framework documentation, EU F-Gas Regulation implementation reports, and NatHERS technical manuals. Bottom-up demand modeling from replacement cycle analysis converged with top-down market sizing from trade flow data.
Granularity extended to product type automation tier, frame material composition, application segment, and installation method across the analysis window. CAGRs derived from regression of historical replacement patterns against regulatory incentive phase-in schedules. Industry-specific inputs captured wind-load certification fragmentation across municipal jurisdictions and aluminum price elasticity in frame cost structures.
Several conditions sit outside the modeled scope, including extreme weather event frequency impacts on fabric replacement cycles and potential tariff restructuring on transatlantic textile imports. Forecasts reflect assumptions about regulatory incentive continuity and skilled workforce pipeline expansion. Material deviation in EU Green Deal enforcement intensity or LME aluminum price regime shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Middle-East Christmas Tree Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Luxury Outdoor Furniture Market