
 North America Awnings Market | 2026-2036
North America Awnings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Awnings Market Outlook
The North America awnings market is recalibrating around a widening split between premium motorized systems with smart-home integration and commodity fixed awnings competing on installation cost alone. Sunesta LLC leverages proprietary automation engineering to command higher margins in the retractable segment, while Sunsetter Products, Inc. sustains mass-market reach through direct-to-consumer channel control. Awning-Tech LLC specializes in custom fabrication for commercial hospitality clients, anchoring a niche where project scale offsets lower unit frequency.
An awning is a secondary covering attached to a building's exterior wall, typically comprising a fabric membrane tensioned over an aluminum or steel frame and engineered to block solar radiation while permitting ventilation beneath its canopy. Fabric awnings utilizing solution-dyed acrylic achieve UV resistance above 98% and remain the dominant material choice for residential wall-mounted installations across warm-climate states. Motorized retractable systems represent the fastest-growing product category, driven by integration with home automation protocols and rising expectations for weather-responsive operation. Fixed aluminum awnings retain share in commercial applications where structural permanence and minimal maintenance anchor procurement decisions over fifteen-plus year horizons.
The U.S. Department of Energy establishes performance benchmarks for solar heat gain coefficient reduction through exterior shading, while ASTM International maintains fabric tensile strength and flame-resistance standards that govern commercial installation approvals. Health Canada and the Canadian Standards Association coordinate parallel certification requirements that shape cross-border product compliance costs for manufacturers serving both markets. Stakeholders must monitor evolving municipal energy codes in California and Florida, where exterior shading mandates in new construction are tightening and will determine which fabricators can scale certified product lines fast enough to capture specification-driven demand.
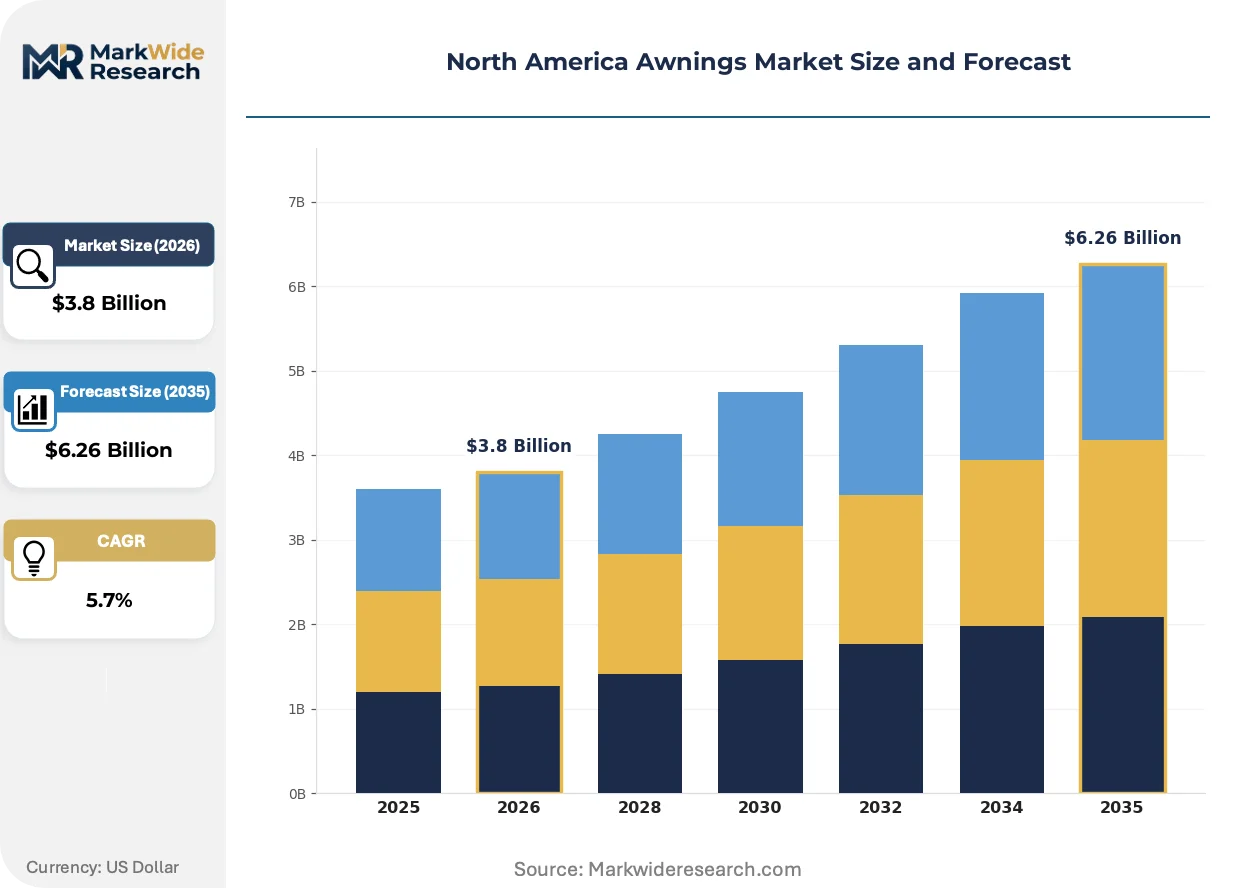
Market Dynamics
Commercial hospitality operators across the United States are expanding covered outdoor seating to capture year-round revenue streams, creating specification pressure that favors motorized retractable systems over fixed alternatives.
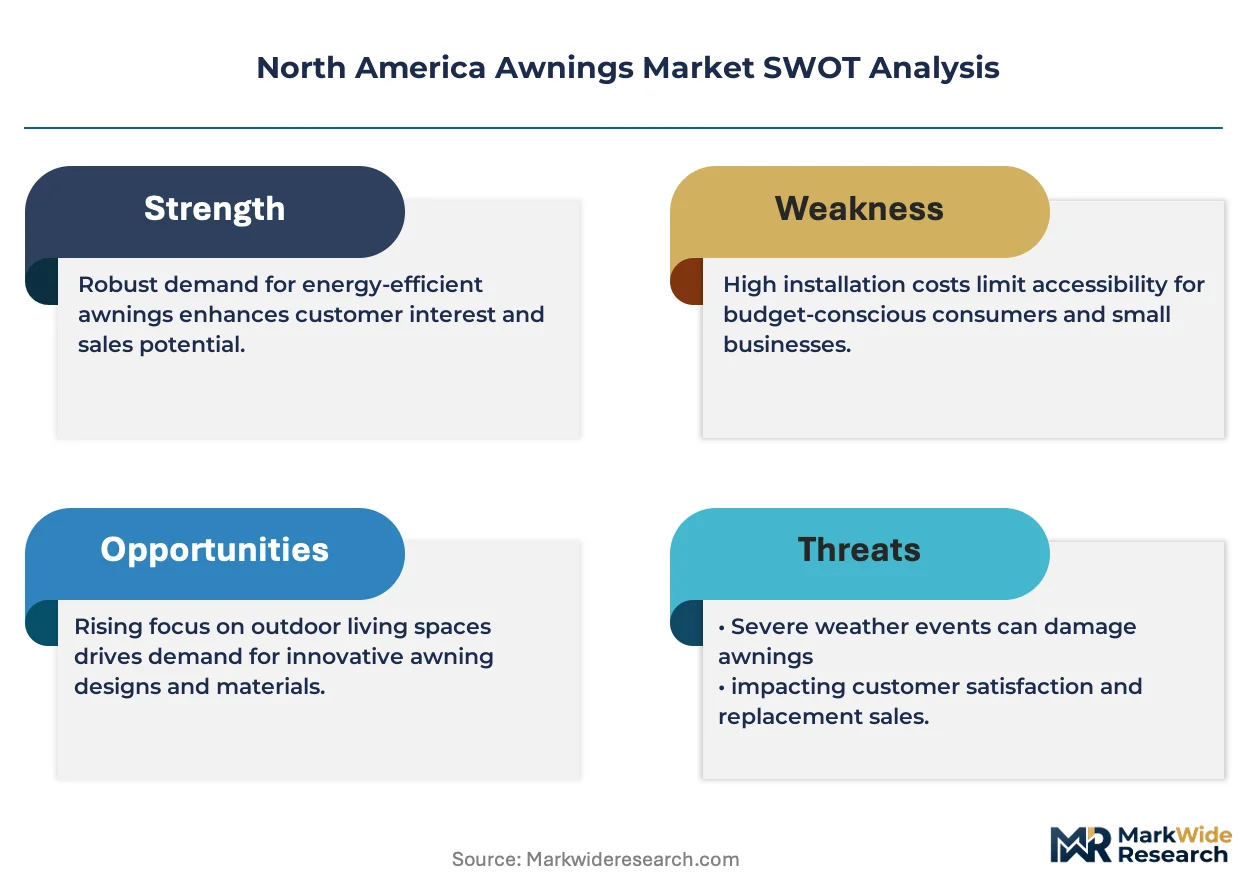
Growth Catalysts
- DOE Cool Roof Programs:The U.S. Department of Energy's exterior shading incentives reward solar heat gain reduction, accelerating specification of certified awnings in new commercial construction across Sun Belt states.
- Smart-Home Integration:Home automation protocol adoption in residential retrofit markets pulls demand toward motorized retractable systems with weather-responsive sensors and app-based control.
- Fabric Performance Advancement:Solution-dyed acrylic materials achieving UV resistance above 98% extend replacement cycles and justify premium pricing in coastal and high-altitude installations.
Market Restraints
- Aluminum Input Volatility:Frame fabrication depends on extruded aluminum pricing, exposing fabricators to commodity swings that compress margin on fixed-awning contracts bid six to nine months ahead.
- Regional Supply Concentration:Motorized system component sourcing clusters in specific Midwest manufacturing corridors, creating vulnerability to localized disruption for retractable-awning assemblers.
- Permanent Structure Codes:Municipal building departments in hurricane-prone jurisdictions classify certain retractable awnings as permanent structures, triggering engineering review delays that stall project timelines.
Strategic Opportunities
- Canadian Market Underpenetration:Health Canada and CSA certification requirements have limited cross-border product availability, creating first-mover advantage for fabricators achieving parallel compliance.
- California Title 24 Mandates:Exterior shading requirements in new residential construction are tightening, positioning certified fabricators to capture specification-driven volume in the state's largest metro corridors.
- Direct-to-Contractor Digital Platforms:E-procurement channels connecting commercial hospitality developers with custom fabricators are compressing traditional distributor markups and accelerating project velocity.
Industry Challenges
- Automation Engineering Talent Scarcity:Motorized system development requires mechatronics expertise that competes with broader IoT and automotive sectors for limited skilled labor pools.
- ASTM Certification Timeline Compression:Commercial fabric flame-resistance testing and tensile strength validation cycles extend product launch schedules, disadvantaging smaller fabricators against established certificated portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Awnings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Fixed, Portable, Motorized Material: Fabric, Aluminum, Wood, Plastic Application: Residential, Commercial, Hospitality, Outdoor Spaces Installation Type: Wall-Mounted, Freestanding, Window, Roof |
| Companies Covered | Awake Windows & Doors, Kohltech Windows, Roniso, Sunsetter Products, Inc., Sunesta LLC, Regency Plus Windows, H Window, Awning-Tech LLC, Airtite Windows, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Awnings Market Strategic Shifts
Fabrication methods and control systems are converging to reshape how awnings are specified, installed, and operated across residential and commercial end-uses.
Photovoltaic fabric integration is decentralizing power supply for motorized retractable units. Hospitality operators in Arizona and Nevada are specifying solar-embedded canopies to eliminate external wiring runs. This technology is decentralizing electrical infrastructure requirements and opening rooftop and remote patio locations previously cost-prohibitive for motorized shading.
The U.S. Department of Energy's updated cool roof and shade program benchmarks are tightening solar heat gain coefficient thresholds for qualifying exterior shading devices. Commercial developers in Texas and Florida are pre-specifying compliant awnings to secure incentive eligibility and expedite permitting. Fabricators with pre-certified product lines are capturing specification share from competitors facing validation backlogs.
Homeowner buying patterns are compressing replacement cycles for aging fixed awnings. Residential customers in Sun Belt states are trading ten-year-old stationary canopies for motorized alternatives during whole-home automation retrofits. Big-box retail channels and direct-to-consumer platforms are capturing this replacement volume, pressuring traditional dealer-installer networks in suburban California and Florida markets.
North America Awnings Market Segmentation
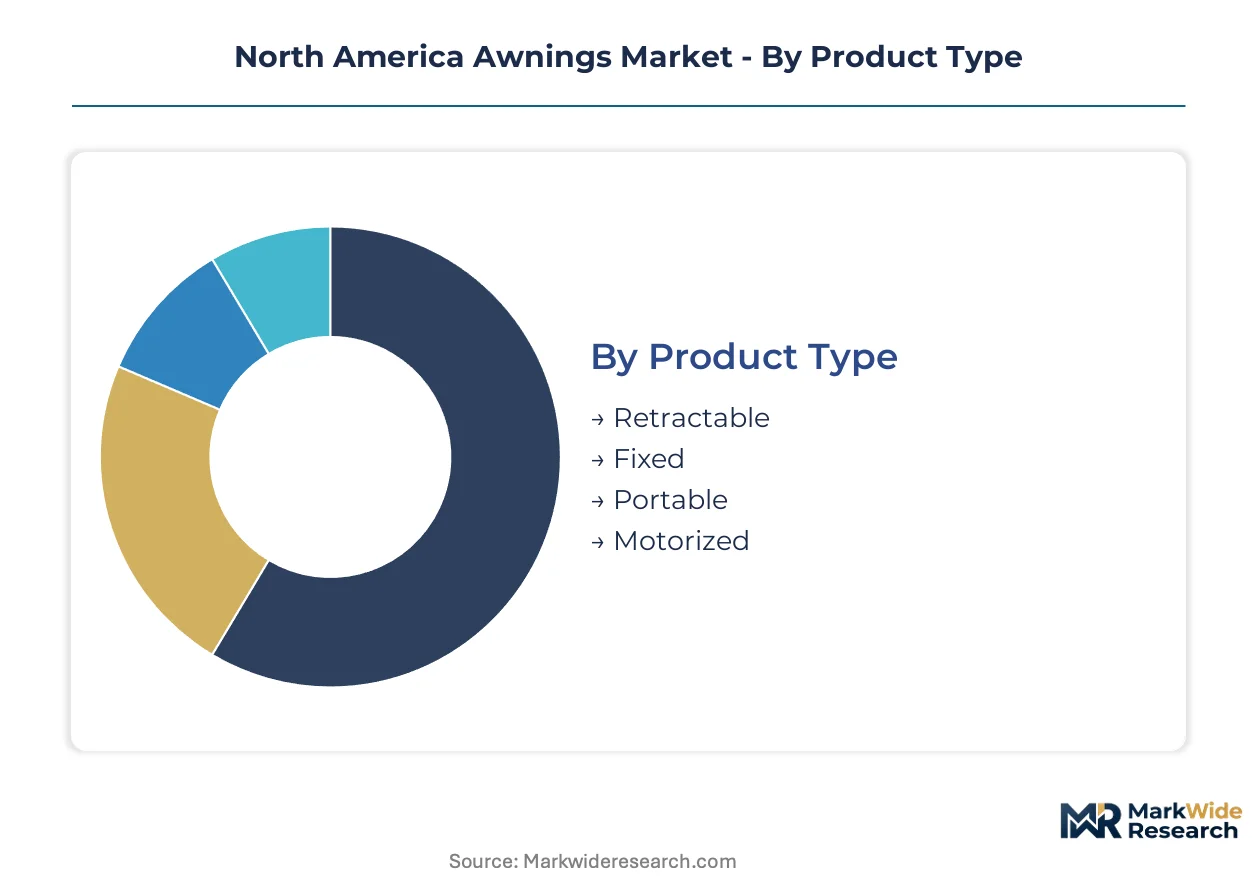
Segmentation in the North America awnings market reveals how capital deployment, material selection, and end-use requirements fragment procurement patterns across residential retrofits and commercial new construction. Understanding these splits enables fabricators to align production capacity with specification-driven demand corridors.
Product Type:
Capital intensity varies sharply across this category, with motorized retractable systems demanding the highest upfront engineering and component investment.
- Retractable:Fabric membrane tensioned over folding aluminum armatures enables seasonal deployment and weather-responsive operation. Demand concentrates in Sun Belt residential markets where homeowners trade aging fixed canopies for automation-compatible upgrades during whole-home retrofit cycles.
- Motorized:Integrated mechatronics with app-based control and sensor-driven retraction command premium pricing and require dedicated automation engineering talent. Procurement from commercial hospitality developers in Arizona, Nevada, and Florida favors these systems for covered patio revenue capture.
- Fixed:Stationary aluminum or steel frameworks deliver structural permanence with minimal maintenance overhead. Commercial installations in hurricane-prone jurisdictions specify these for code compliance and long-term durability.
- Portable:Freestanding frame-and-canopy systems deploy without permanent anchoring. Seasonal demand from event rental operators and residential consumers in temperate climate zones drives volume.
Most installed capacity flows through Fixed systems in commercial applications. Expansion is steepest in Motorized as smart-home integration reshapes residential procurement.
Material:
Raw material cost tiers and performance specifications drive divergent sourcing strategies across climate zones and end-use durability requirements.
- Fabric:Solution-dyed acrylic achieves UV resistance above 98% and dominates residential wall-mounted installations across warm-climate states. Replacement cycles extend with coastal and high-altitude formulations.
- Aluminum:Extruded and formed sheet metal delivers structural rigidity with minimal maintenance. Procurement from commercial developers prioritizes these for fifteen-plus year operational horizons in Texas and Florida.
- Wood:Cedar and redwood frames serve aesthetic-driven residential specifications in heritage districts and luxury coastal construction. Limited volume due to maintenance burden and moisture vulnerability.
- Plastic:Molded polymer components reduce unit cost for entry-level portable and fixed applications. Big-box retail channels in suburban California and Florida markets capture this volume.
Fabric commands the largest share of residential retrofit activity. Aluminum is gaining specification share fastest in commercial new construction incentivized by DOE cool roof programs.
Application:
End-use scale and project velocity create distinct customer profiles that shape fabricator go-to-market investments and channel partnerships.
- Commercial:Office, retail, and institutional installations prioritize solar heat gain reduction and ADA-compliant covered walkways. Specification through architects and general contractors in Sun Belt metro corridors drives certified product demand.
- Hospitality:Restaurants, hotels, and entertainment venues expand covered outdoor seating to capture year-round revenue streams. Arizona and Nevada operators specify solar-embedded motorized systems to eliminate external wiring infrastructure.
- Residential:Single-family and multi-family retrofits dominate unit volume. Direct-to-consumer platforms and big-box retail channels are compressing traditional dealer-installer networks in California and Florida.
- Outdoor Spaces:Parks, recreational facilities, and municipal installations represent intermittent project-based demand. Procurement through public agency bidding processes favors lowest-compliant-bid suppliers.
Residential generates the highest unit volume through replacement cycles. Hospitality is expanding most quickly as covered patio seating becomes structurally essential to revenue models.
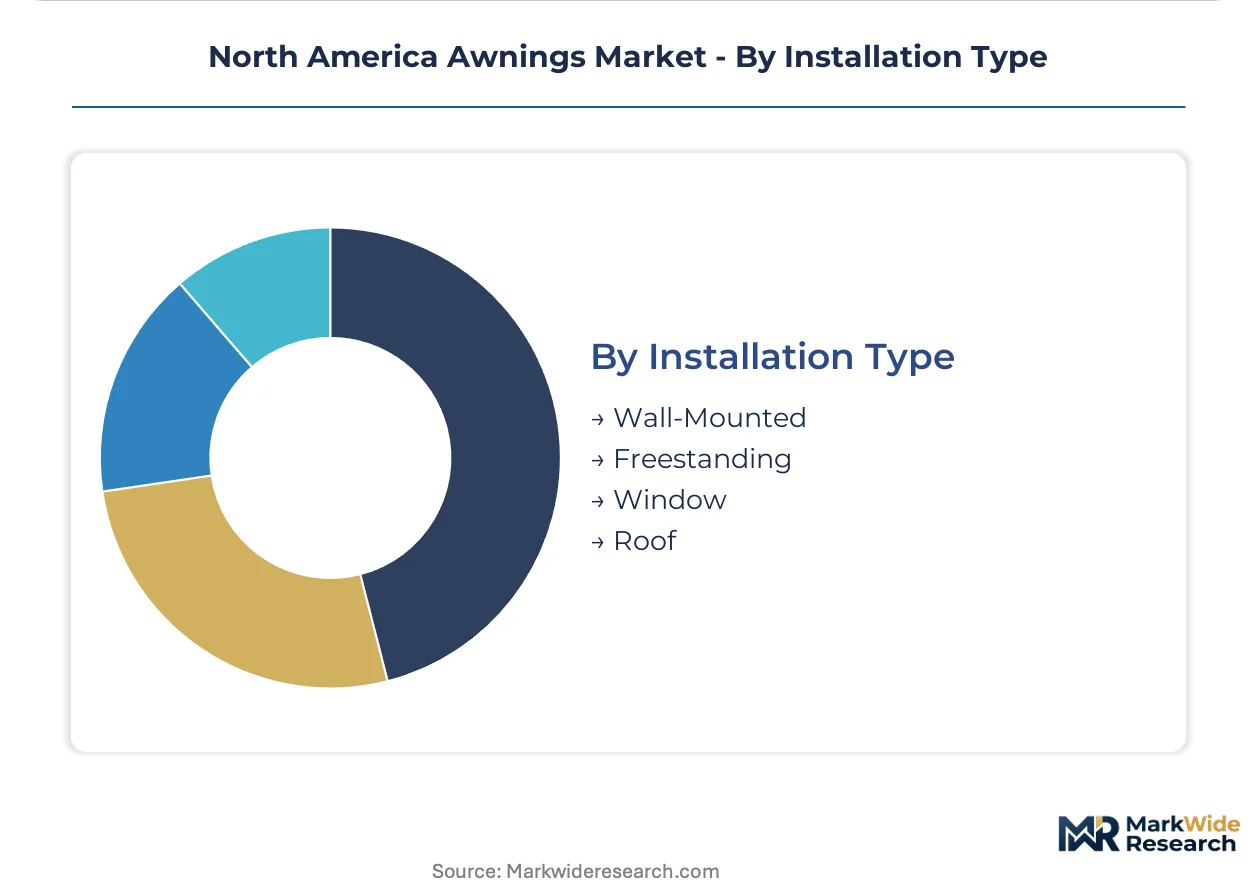
Installation Type:
Structural attachment methods determine engineering review requirements, permit timelines, and installer specialization barriers.
- Wall-Mounted:Bracket attachment to vertical building envelopes constitutes the dominant residential configuration. Installation velocity favors experienced crews in suburban Sun Belt markets with standardized framing practices.
- Roof:Structural integration with standing seam or membrane roofing systems requires specialized waterproofing expertise. Commercial developers in Texas pre-specify these for incentive eligibility under tightened energy codes.
- Freestanding:Self-supporting frame structures bypass building envelope attachment requirements. Demand from hospitality operators seeking flexible patio configurations in leased spaces drives specification.
- Window:Projecting canopies above individual fenestrations address solar heat gain at the room level. Limited to residential and small commercial retrofits where whole-building shading is cost-prohibitive.
Wall-Mounted systems carry the largest installed base across residential applications. Roof-integrated configurations are climbing the fastest as California Title 24 mandates tighten exterior shading requirements for new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication talent clusters in the Midwest and Sun Belt anchor North American production capacity, with automation engineering expertise concentrating in Michigan and Ohio manufacturing corridors. Cross-border compliance capabilities separate integrated operators from regional-only competitors.
United States
Commercial hospitality developers in Arizona and Nevada specify solar-embedded motorized systems for covered patio revenue capture. The U.S. Department of Energy's cool roof and shade programs incentivize solar heat gain reduction through certified exterior shading. Los Angeles and Phoenix metro corridors drive specification volume under tightening California Title 24 and municipal energy codes.
Canada
Health Canada and CSA certification requirements have limited cross-border product availability, creating first-mover advantage for compliant fabricators. Health Canada coordinates parallel certification with the Canadian Standards Association that shapes compliance costs for manufacturers serving both markets. Ontario and Quebec construction markets show underpenetration relative to U.S. Sun Belt intensity.
Mexico
Aluminum extrusion and component sourcing clusters near Monterrey supply fabricators across the border region. Mexican manufacturing regulations govern maquiladora operations that feed retractable system assembly in Texas and California. Baja California and Nuevo León host emerging fabrication capacity serving southwestern U.S. distribution channels.
North America Awnings Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where premium motorized systems and commodity fixed awnings occupy distinct competitive spaces. The vendor base fragments between automation-engineering specialists and installation-scale operators competing on channel control. Three archetypes dominate: proprietary automation engineers commanding retractable margins, direct-to-consumer volume players, and custom fabrication specialists serving commercial hospitality. Competitive moves concentrate on certification portfolio expansion and e-procurement platform development to compress distributor markups.
Among automation-focused specialists, Sunesta LLC and Sunsetter Products, Inc. exemplify divergent positioning strategies—one leveraging proprietary engineering for premium retractable systems, the other sustaining mass-market reach through direct channel control. Awning-Tech LLC anchors the custom fabrication tier where commercial hospitality project scale offsets lower unit frequency.
| Leading Market Players |
|---|
| Awake Windows & Doors |
| Kohltech Windows |
| Roniso |
| Sunsetter Products, Inc. |
| Sunesta LLC |
| Regency Plus Windows |
| H Window |
| Awning-Tech LLC |
| Airtite Windows |
| Others |
Value Chain & Pricing Dynamics
Aluminum LME pricing volatility cascades through North American awning fabrication, compressing margins on fixed-awning contracts bid six to nine months ahead while pushing procurement toward fabric-dominant retractable systems where material cost represents a smaller share of delivered price.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the North America awnings market. Project-based pricing dominates commercial hospitality specifications where installation, engineering review, and post-sale maintenance bundle into single-contract awards. Price differentiation hinges on certification tier — ASTM-certified commercial fabricators command substantial premiums over uncertified competitors — and automation integration level. Cost compression in commodity fixed-awning tiers intensifies as big-box retail channels disintermediate traditional dealer-installer networks. Residential retrofit buyers exhibit highest price sensitivity, while hospitality developers prioritize total cost of ownership over upfront unit cost.
Supply Chain Analysis
Domestic-content mandates in California Title 24 and Florida energy code enforcement are reshaping sourcing patterns toward U.S.-based aluminum extruders and solution-dyed acrylic weavers. Component supply concentrates in Michigan, Ohio, and northern Mexico maquiladora corridors, with motorized system actuators and sensors drawing from Midwest automation engineering clusters. Raw material dependencies rest on primary aluminum ingot, solution-dyed acrylic fiber, and steel framing alloy. Single-source vulnerability concentrates in specialized mechatronics components where limited qualified suppliers serve the retractable-awning segment. Distribution runs through three-tier structures: manufacturer-direct for large commercial projects, regional distributor networks for residential retrofits, and big-box retail for portable and entry-level fixed systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America awnings market functions as a stable compounder where building code tightening in Sun Belt states generates specification-driven replacement cycles with limited demand elasticity.
For Market Incumbents: Deepen automation engineering capabilities to defend retractable-awning margins against emerging IoT-platform entrants with superior software integration. Expand ASTM and CSA certification portfolios to capture California Title 24 and Canadian specification volume before validation backlogs disqualify competitors. Prioritize backward integration into aluminum extrusion to buffer commodity price swings compressing fixed-awning profitability. For New Entrants and Emerging Players: The price-point gap between premium motorized systems and economy fixed awnings offers white-space opportunity for mid-tier automation-capable fabricators. Target Canadian commercial construction where Health Canada and CSA certification barriers have limited cross-border availability. Pursue direct-to-contractor digital platforms to compress traditional distributor markups and accelerate project velocity in Arizona and Nevada hospitality markets. For Investors and Strategic Acquirers: Asymmetric upside sits with custom fabrication specialists serving commercial hospitality where project scale offsets lower unit frequency and creates sticky specification relationships. Five-to-ten year viability hinges on regulatory compliance scalability rather than manufacturing asset intensity. Monitor municipal energy code adoption velocity in Texas and Florida as the primary inflection signal for specification-driven volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Achievement | Unlocks Canadian commercial specification share currently limited by cross-border compliance barriers. |
| Photovoltaic Fabric Integration | Eliminates external wiring infrastructure for Arizona and Nevada hospitality operators seeking flexible patio deployment. |
| Direct-to-Contractor Platform Launch | Compresses distributor markups and accelerates project velocity in commercial hospitality development pipelines. |
| Backward Integration into Extrusion | Captive aluminum supply buffers commodity price volatility compressing fixed-awning contract margins. |
| Smart-Home Protocol Certification | Secures specification preference in residential retrofit markets integrating shading into whole-home automation. |
Study Parameters
Multiple input streams — structured interviews with awning fabricators and commercial hospitality developers, regulatory filing analysis, and trade data reconciliation — were combined to construct market estimates. Primary fieldwork engaged automation engineering directors, commercial contractor procurement leads, municipal building code officials, and residential retrofit channel managers. Secondary validation drew from U.S. Department of Energy cool roof program documentation, ASTM International certification registries, California Energy Commission Title 24 filings, and Health Canada product approval databases. Bottom-up unit economics and top-down construction spending allocation were triangulated to anchor volume and value estimates.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to baseline installation counts. Segmentation dimensions modeled include product type (retractable, motorized, fixed, portable), material category (fabric, aluminum, wood, plastic), application (commercial, hospitality, residential, outdoor spaces), and installation configuration (wall-mounted, roof-integrated, freestanding, window). CAGRs were derived from regression analysis against construction permit velocity, energy code adoption timelines, and replacement cycle compression patterns. Industry-specific forecast inputs incorporated solar heat gain coefficient threshold tightening and smart-home protocol penetration curves.
Caveats apply where aluminum commodity price spikes, municipal permitting delays in hurricane-prone jurisdictions, or mechatronics component supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding continued Sun Belt population growth and sustained DOE incentive program funding. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Middle-East Christmas Tree Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Patio Furniture Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Retractable Awnings Market