
 Europe Awnings Market | 2026-2036
Europe Awnings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Awnings Market Insights
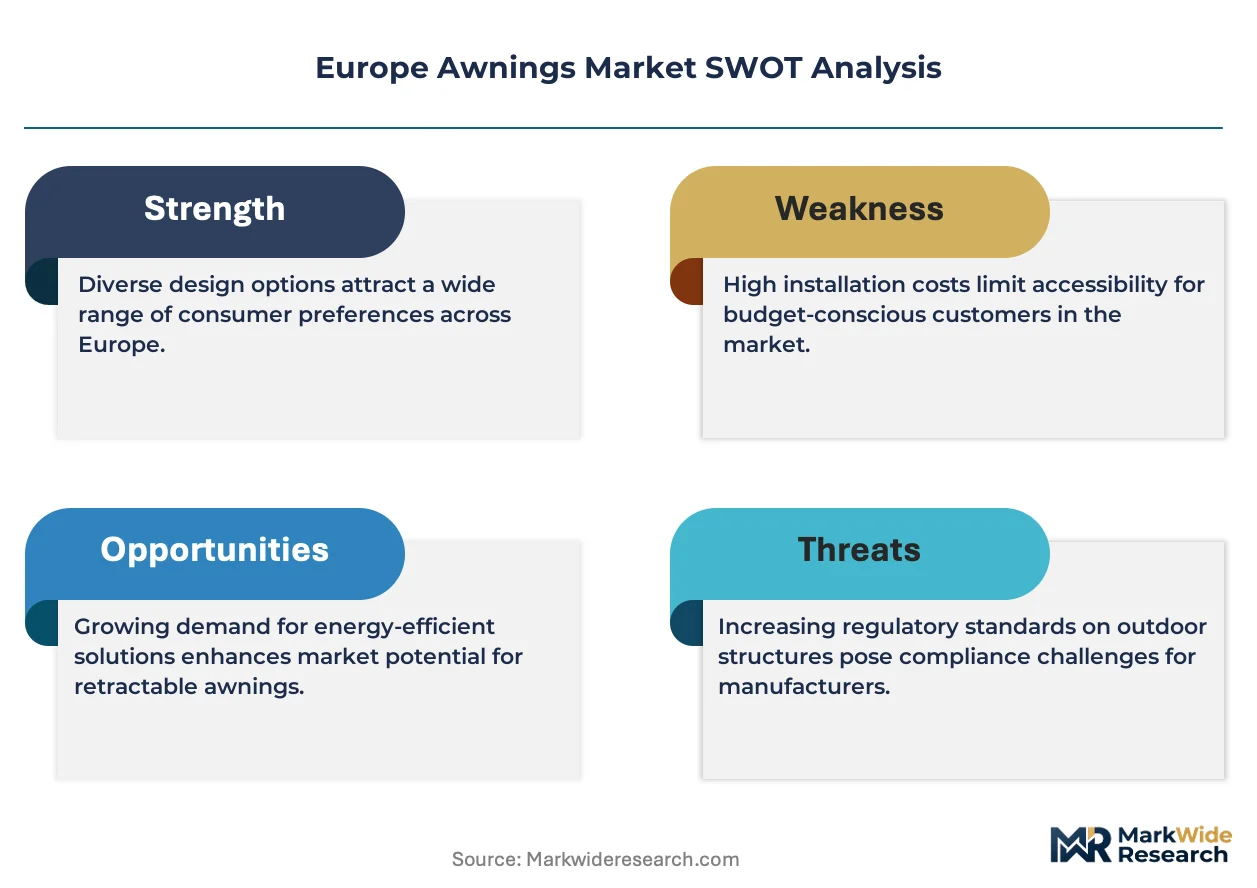
CE marking under the Construction Products Regulation is unwinding competitive access across the Europe Awnings Market, filtering out suppliers unable to demonstrate mechanical resistance and fire-reaction compliance. Warema Renkhoff SE leverages its German manufacturing base to sustain broad distribution across Central European commercial channels. Markilux GmbH anchors its position through intensive R&D in sensor-driven automation for retractable systems. Serge Ferrari Group differentiates via specialized high-performance membrane engineering for tensioned architectural fabric structures.
An awning is a secondary covering attached to a building facade, typically comprising aluminum frames with acrylic, polyester, or PVC-coated fabric membranes engineered to withstand wind loads of 80-120 km/h while blocking solar radiation. Its primary purpose is to reduce interior cooling demand and extend usable outdoor floor area for commercial and residential properties. Fabric materials dominate volume shipments across Europe, though motorized retractable installations command the strongest margin pools due to integrated automation and custom sizing requirements. Fixed aluminum systems retain steady share in commercial applications where permanent weather protection takes priority over flexibility.
The EU Green Deal and national transpositions through Germany's Building Energy Act shape demand by mandating solar shading as a cooling-load reduction measure, while France's RT2012 thermal regulation and forthcoming RE2020 revisions enforce stricter envelope performance standards. ECHA REACH compliance further constrains coating chemistries and flame-retardant treatments available to fabric suppliers. Stakeholders must monitor how the EU AI Act and emerging smart-building certification schemes reshape the competitive bar for connected awning systems with automated weather response.
Market Dynamics
The EU Green Deal's cooling-load mandates are compressing specification timelines across the Europe Awnings Market, forcing fabricators to pre-certify membrane assemblies before project bidding. Motorized retractable systems absorb disproportionate engineering resources as building-integrated automation becomes a compliance pathway rather than a luxury add-on.
Growth Catalysts
- Germany's Building Energy Act:Solar shading requirements for new commercial construction are pulling demand toward high-performance tensioned systems with documented thermal performance coefficients.
- Outdoor hospitality terraces:Spanish and Italian restaurant operators are expanding covered seating capacity to capture year-round revenue, prioritizing wind-rated retractable installations over fixed alternatives.
- Sensor-driven automation:Integration of wind and solar sensors into retractable mechanisms reduces manual operation labor while extending membrane service life through proactive retraction.
Market Restraints
- Aluminum frame cost volatility:Primary aluminum price swings tied to energy-intensive smelting operations in Central Europe compress margin predictability for frame fabricators.
- REACH compliance friction:ECHA restrictions on perfluorinated chemistry limit durable water-repellent coating options, forcing reformulation cycles that delay product launches.
- Fixed aluminum substitution:Permanent canopy structures in commercial logistics and retail applications capture projects where flexibility is deprioritized, constraining retractable system addressable market.
Strategic Opportunities
- Polish residential renovation:Underpenetrated premium housing stock in Warsaw and Kraków corridors offers retrofit volume as EU cohesion funds flow toward energy-efficiency upgrades.
- EU AI Act convergence:Smart-building certification schemes are creating compliant product categories for connected awnings with automated weather response, opening specification channels previously closed to conventional suppliers.
- Direct-to-developer digital channels:Configurator platforms bypass traditional architectural specification gatekeepers, capturing margin and compressing quote-to-order cycles for standardized commercial projects.
Industry Challenges
- CE marking timeline compression:Construction Products Regulation mechanical resistance testing and fire-reaction certification now require 14-18 month validation cycles, straining product pipeline management.
- Automation integration complexity:BACnet and KNX protocol compatibility demands are forcing fabricators to maintain multi-standard engineering teams or outsource control system development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Awnings Market |
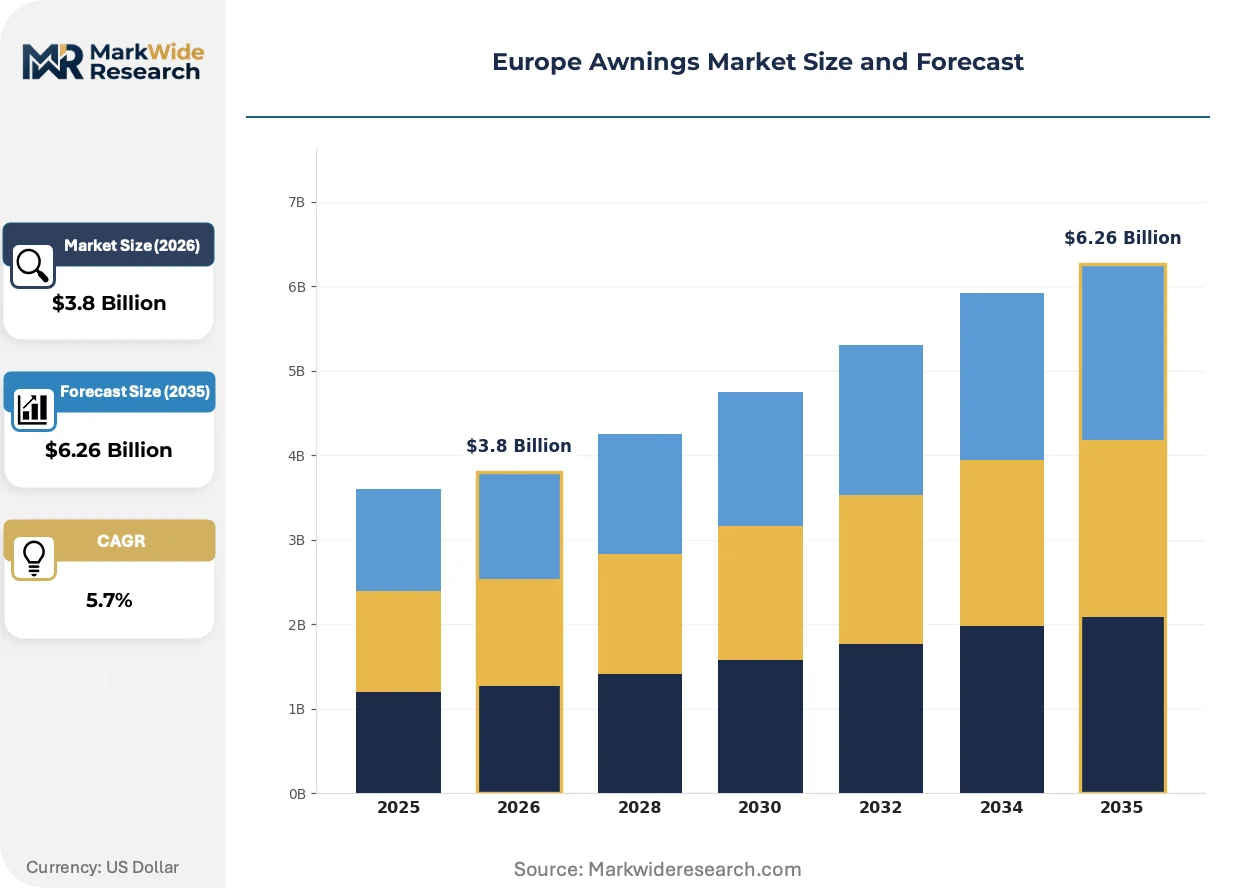
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fabric, Aluminum, PVC, Vinyl Application: Residential, Commercial, Hospitality, Recreational Installation Type: Retractable, Fixed, Portable, Motorized Size: Small, Medium, Large, Custom |
| Companies Covered | MHZ Hachtel GmbH & Co. KG, Stobag AG, Markilux GmbH, Commercial Awnings Limited, Serge Ferrari Group, Warema Renkhoff SE, Mitjavila, Corradi S.r.l., Gibus, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Awnings Market Trends and Innovations
Fabric membrane engineering and control system architectures are diverging along performance-versus-cost axes, with premium specifications absorbing sensor fusion while economy tiers strip automation to preserve price accessibility.
Photovoltaic-integrated membrane laminates are bifurcating the specification landscape. These building-integrated photovoltaics generate on-site power while providing solar shading, attracting German commercial developers pursuing nearly-zero-energy building certification. Standard awning fabricators without electrical integration capabilities are retreating toward purely passive shading projects, compressing their addressable premium segment.
France's RE2020 thermal regulation revision is tightening envelope performance standards for new construction, explicitly recognizing external solar shading as a primary cooling-load reduction measure. Project developers in the Île-de-France and Provence-Alpes-Côte d'Azur regions are now pre-specifying motorized retractable systems with documented solar factor performance. Fabric suppliers without certified test data are losing specification access to building permit authorities.
Architects and facility managers are consolidating vendor relationships around full-service maintenance contracts rather than transactional equipment procurement. French hospital and university estates are leading this shift, bundling membrane replacement, motor servicing, and sensor calibration under multi-year agreements. Distributors without technical service capabilities are being displaced from institutional channels, concentrating supply relationships with vertically integrated manufacturers.
Europe Awnings Market Segmentation
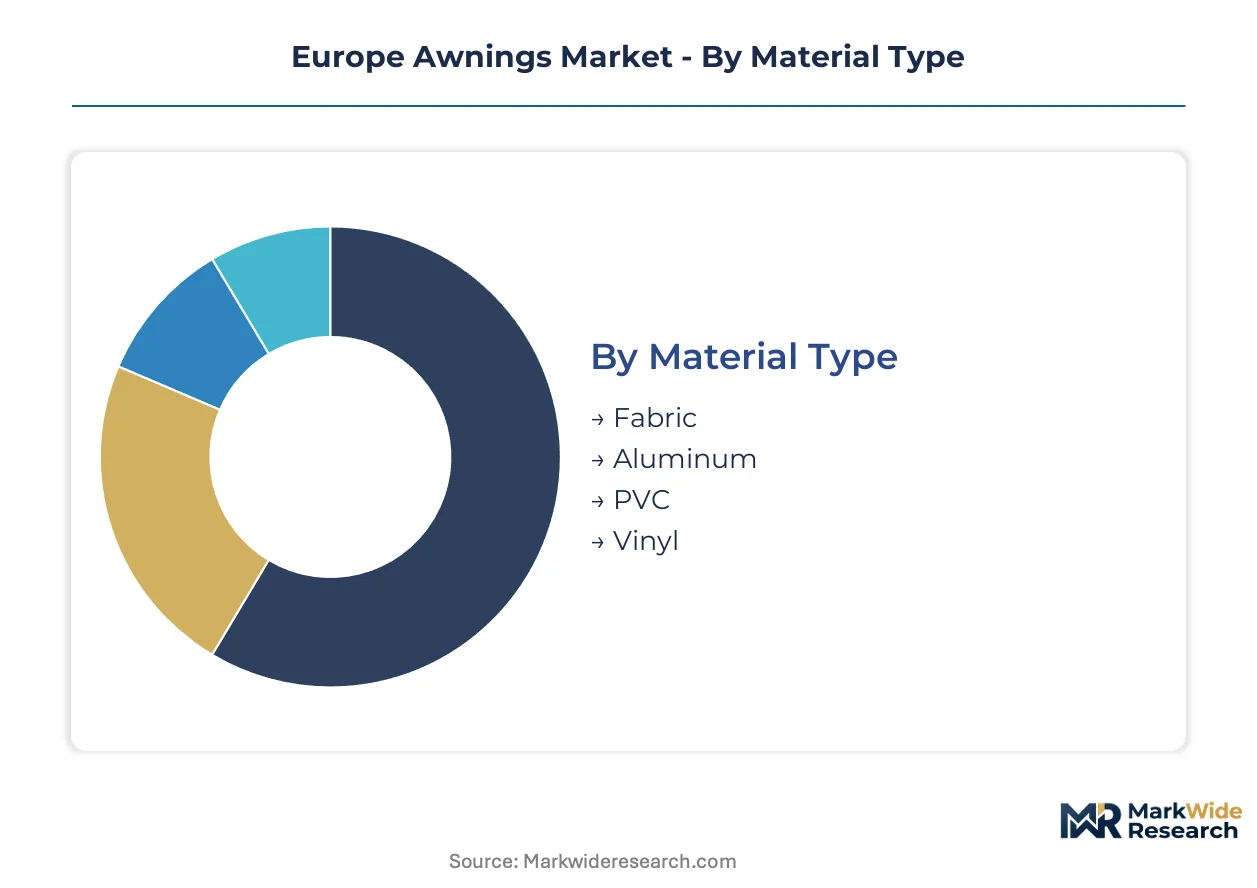
Material composition and installation mechanics segment the Europe Awnings Market into distinct competitive arenas where substitution pressures vary sharply. Specification decisions in German commercial construction and Spanish hospitality drive divergence between premium engineered systems and commodity alternatives.
Material Type:
Fixed aluminum canopy structures exert substitution pressure on fabric membranes in logistics and retail applications where permanent weather protection outweighs flexibility requirements.
- Fabric:Acrylic, polyester, and PVC-coated membranes engineered for 80-120 km/h wind loads dominate volume shipments across European commercial and residential channels. Spanish and Italian hospitality operators prioritize wind-rated fabric systems for terrace expansions capturing year-round revenue.
- Aluminum:Rigid extruded frames with powder-coated finishes serve permanent commercial installations where durability trumps reconfigurability. German logistics facilities specify fixed aluminum canopies for loading bay weather protection under Building Energy Act compliance pathways.
- PVC:Thermoplastic membranes offer cost-accessible weather barriers for seasonal recreational applications and temporary commercial deployments. REACH restrictions on plasticizer chemistry constrain formulation flexibility for European suppliers.
- Vinyl:Laminated vinyl substrates provide economy-tier residential solutions with limited service life expectations. Polish renovation contractors specify vinyl for budget-constrained retrofit projects accessing EU cohesion funds.
Fabric anchors the volume base while aluminum gains share in commercial permanency applications.
Application:
Commercial end-use concentration in France and Germany pulls specification toward motorized systems with documented thermal performance coefficients.
- Residential:Premium renovation demand concentrates in German and French suburban housing stock where Building Energy Act and RE2020 regulations mandate solar shading for cooling-load reduction. Motorized retractable systems with sensor integration command strongest margin pools.
- Commercial:Office and retail estate managers specify full-service maintenance contracts bundling membrane replacement and motor servicing. French hospital and university estates lead this vendor consolidation trend.
- Hospitality:Spanish and Italian restaurant operators expand covered seating capacity with wind-rated retractable installations. Outdoor terrace revenue capture drives preference for automated weather-response systems.
- Recreational:Campsite and marina operators deploy portable and semi-permanent structures with seasonal installation cycles. Mediterranean coastal municipalities regulate membrane fire-reaction compliance for public safety.
Commercial applications concentrate specification value while hospitality expands most quickly across Southern European markets.
Installation Type:
Automation integration complexity segments the competitive field between vertically integrated manufacturers and component assemblers lacking BACnet and KNX protocol capabilities.
- Retractable:Articulated arm and lateral guide systems enable flexible deployment for variable weather conditions. French RE2020 revisions explicitly recognize external solar shading as primary cooling-load reduction measure.
- Fixed:Permanent frame structures eliminate mechanical complexity at cost of configurability. Commercial logistics applications in Germany and Benelux prioritize fixed systems for 24/7 weather protection.
- Portable:Freestanding and temporary structures serve event and seasonal recreational markets. ECHA REACH compliance constrains coating chemistries for portable frame suppliers.
- Motorized:Integrated drive mechanisms with wind and solar sensors reduce manual operation labor while extending membrane service life. CE marking under Construction Products Regulation requires 14-18 month validation cycles for mechanical resistance certification.
Retractable systems anchor the volume base while motorized configurations climb the fastest in premium residential and commercial segments.
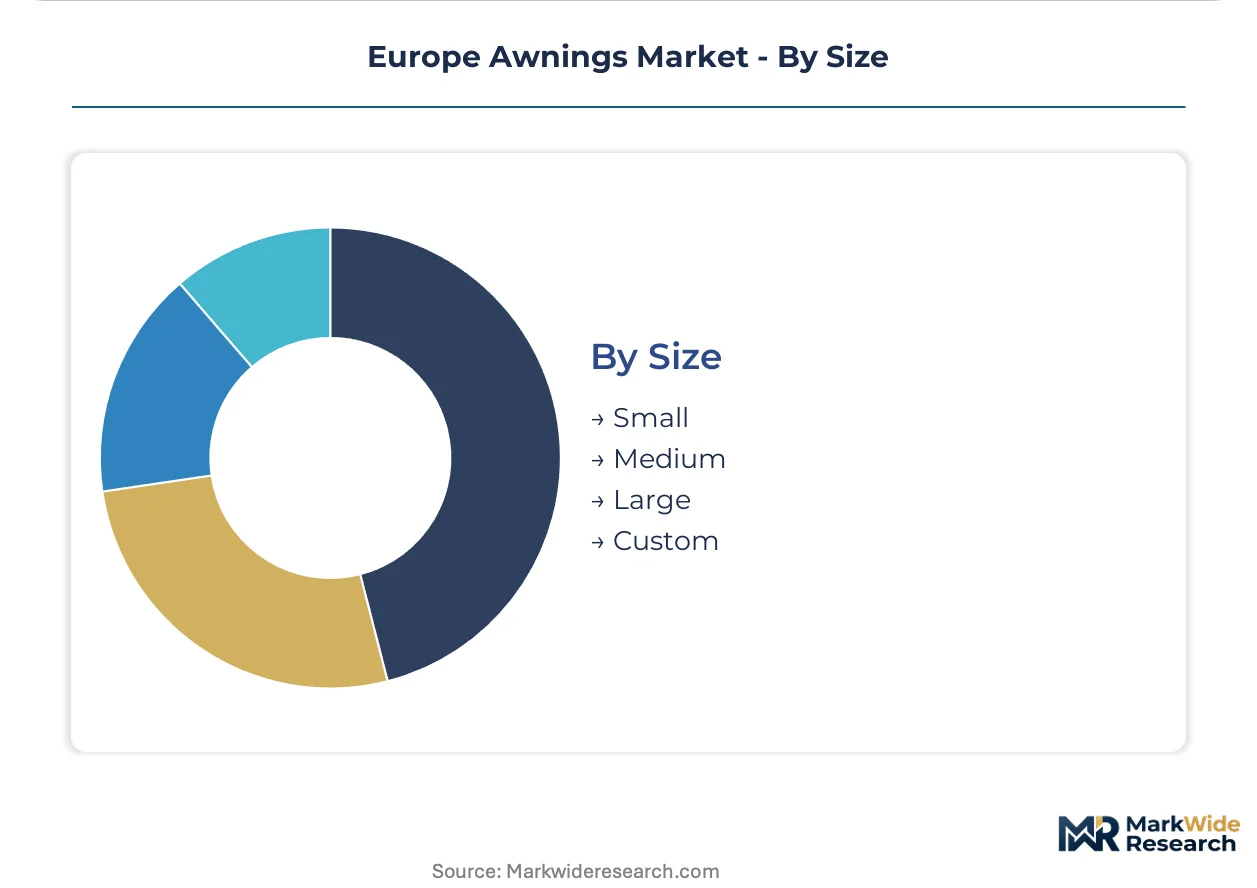
Size:
Custom sizing requirements fragment procurement patterns between standardized commercial projects suited for digital configurator platforms and architect-specified bespoke installations.
- Small:Balcony and window-scale systems serve apartment and townhouse applications. German multi-family residential renovation accesses Building Energy Act subsidies for solar shading installation.
- Medium:Terrace and storefront dimensions match standardized frame extrusion lengths for cost-efficient manufacturing. French retail chains specify medium-format motorized systems for consistent brand presentation.
- Large:Restaurant terrace and commercial courtyard spans require engineered wind-load calculations and foundation integration. Italian hospitality operators in Rome and Milan corridors drive demand for large-format tensioned structures.
- Custom:Non-standard dimensions and architectural integration demands absorb disproportionate engineering resources. Direct-to-developer digital channels bypass traditional architectural specification gatekeepers for standardized commercial projects.
Medium formats anchor the volume base while custom specifications gain share in architect-driven premium developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial estate managers and hospitality operators across Western Europe drive specification intensity, with regulatory pressure from the EU Green Deal fragmenting demand patterns between premium automated systems and compliance-grade alternatives.
Germany
Building Energy Act mandates pull demand toward high-performance tensioned systems with documented thermal coefficients. Munich and Stuttgart corridors concentrate commercial renovation activity where motorized retractable installations dominate specification. Warema Renkhoff SE leverages its domestic manufacturing base to sustain distribution across Central European channels.
France
RE2020 thermal regulation revisions explicitly recognize external solar shading as primary cooling-load reduction measure. Île-de-France and Provence-Alpes-Côte d'Azur regions pre-specify motorized systems with certified solar factor performance. Hospital and university estates bundle membrane replacement and motor servicing under multi-year maintenance contracts.
Italy
Rome and Milan hospitality corridors drive demand for large-format wind-rated retractable structures on restaurant terraces. Outdoor seating expansion captures year-round revenue as operators prioritize automated weather-response systems over fixed alternatives. Mediterranean coastal municipalities enforce membrane fire-reaction compliance for public safety.
Spain
Barcelona and Madrid restaurant operators expand covered terrace capacity with wind-rated fabric installations. EU Green Deal cooling-load standards accelerate specification timelines for commercial hospitality projects. Andalusian coastal municipalities regulate seasonal recreational deployments with REACH-compliant coating requirements.
Poland
Warsaw and Kraków premium housing stock offers retrofit volume as EU cohesion funds flow toward energy-efficiency upgrades. Budget-constrained renovation contractors specify economy-tier vinyl systems for residential applications. Building Energy Act-aligned subsidies accelerate solar shading adoption in multi-family residential segments.
Europe Awnings Market Competitive Landscape
Player mix skews toward mid-cap regional specialists with deep fabrication expertise and limited pan-European scale. Market structure concentrates supply relationships around vertically integrated manufacturers capable of delivering full-service maintenance contracts. Three archetypes dominate: German-engineered automation specialists, Mediterranean hospitality-focused fabricators, and membrane engineering laboratories serving architectural tension structures. Competitive moves center on CE marking pre-certification investments and direct-to-developer digital channel development.
Within the German-engineered tier, Warema Renkhoff SE and Markilux GmbH exemplify vertically integrated specialists combining domestic manufacturing with sensor-driven automation capabilities. Serge Ferrari Group occupies a distinct position as a membrane engineering laboratory serving tensioned architectural applications. Among hospitality-focused fabricators, Corradi S.r.l. and Gibus represent Mediterranean specialists with concentrated terrace-installation expertise. Stobag AG and MHZ Hachtel GmbH & Co. KG anchor the premium motorized segment through sustained R&D in building-integrated automation systems.
| Leading Market Players |
|---|
| MHZ Hachtel GmbH & Co. KG |
| Stobag AG |
| Markilux GmbH |
| Commercial Awnings Limited |
| Serge Ferrari Group |
| Warema Renkhoff SE |
| Mitjavila |
| Corradi S.r.l. |
| Gibus |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with German aluminum extruders lock in frame supply visibility while insulating fabricators from spot price volatility in energy-intensive smelting operations. These contractual structures bundle membrane procurement with motor drive assemblies, compressing quote-to-order cycles for commercial developers seeking CE-marked system packages.
Pricing Analysis
Cost-plus contracts indexed to LME primary aluminum and acrylic fiber spot markets dominate commercial procurement, with German frame fabricators passing through energy cost adjustments quarterly. Three-tier pricing structure across premium sensor-integrated, standard motorized, and economy manual tiers differentiates by automation depth and CE certification tier. Pricing pressure stems from REACH-compliant coating reformulation costs, with margins tightening most acutely in vinyl residential segments where Polish contractors face budget caps on EU cohesion-funded retrofits.
Supply Chain Analysis
Strait of Gibraltar transit underwrites acrylic fiber supply from Asian petrochemical complexes, exposing membrane fabricators to bunker fuel surcharge volatility. German aluminum extrusion and Italian textile weaving anchor component supply, with motor drives sourced from Swiss and Austrian automation specialists. Single-source vulnerability concentrates in wind sensor modules, where BACnet protocol compatibility demands force reliance on specialized control system vendors. Distribution runs through architect-specification channels for bespoke installations and direct-to-developer digital platforms for standardized commercial formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of multi-protocol automation engineering talent constrains product pipeline velocity, with CE marking validation cycles extending to 18 months for newcomers lacking pre-certified membrane assemblies. This capability gap favors incumbents with captive testing facilities and established notified body relationships.
For Market Incumbents: Fortify specification lock-in through multi-year maintenance contracts bundling membrane replacement and sensor calibration, displacing distributor-only competitors from French hospital and university estates. Deepen backward integration into high-performance membrane weaving to capture margin pools retreating from commodity vinyl segments, while accelerating pre-certification investments under Construction Products Regulation to compress rival bid timelines. For New Entrants and Emerging Players: Post-installation technical service gaps in Southern European hospitality channels offer white-space entry, with Spanish and Italian terrace operators prioritizing rapid response maintenance over equipment procurement relationships. Target Polish residential renovation corridors through economy-tier vinyl configurations aligned with EU cohesion fund disbursement timelines, leveraging direct-to-developer digital configurators to bypass architectural specification gatekeepers. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated manufacturers with captive CE marking capabilities and established notified body relationships. Acquisition screening should prioritize mid-scale German and French fabricators possessing in-house membrane engineering and sensor integration competencies. Watch ECHA REACH amendment timelines for perfluorinated chemistry restrictions as inflection indicators that would force accelerated reformulation investment and consolidate supply relationships toward compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Compresses 14-18 month validation cycles, locking specification access ahead of EU Green Deal enforcement deadlines. |
| Backward Integration into Membrane Weaving | Captures margin retreating from commodity vinyl segments while securing REACH-compliant coating formulation control. |
| Direct-to-Developer Digital Channel Launch | Bypasses architectural specification gatekeepers, capturing standardized commercial project volume with compressed quote-to-order cycles. |
| Multi-Protocol Automation Engineering Buildout | Addresses BACnet and KNX compatibility demands, opening smart-building certification channels previously closed to conventional suppliers. |
| Full-Service Maintenance Contract Expansion | Consolidates vendor relationships in French institutional estates, displacing distributor-only competitors from recurring revenue streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association datasets, and customs import records. Primary interviews engaged awning fabricator operations directors, architectural specification consultants, commercial estate facility managers, and notified body certification officers across German, French, Italian, and Spanish markets. Secondary validation drew from ECHA REACH substance restriction updates, Construction Products Regulation harmonized standards documentation, and EU Green Deal national transposition texts. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts.
Segmentation dimensions modeled span material composition, installation mechanics, application vertical, and regional regulatory cluster, with value outputs calibrated across the projection horizon. CAGRs derive from trend-line extrapolation of specification intensity and replacement cycle analysis, cross-checked against energy-efficiency subsidy disbursement trajectories and hospitality terrace expansion permits.
Forecasts assume regulatory continuity in EU Green Deal implementation and ECHA REACH enforcement; material policy shifts would require re-modeling. Revision becomes warranted when aluminum price volatility or REACH amendment timelines cross thresholds that alter fabricator margin structures or product launch cadences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Patio Furniture Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
Middle-East Christmas Tree Market