
 Floating Fountains Market | 2026-2036
Floating Fountains Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Fountains Market Foresight
Aftermarket service revenue for nozzle replacement, pump overhaul, and seasonal winterization is reshaping profitability dynamics across the floating fountains value chain. OASE GmbH leverages its European service depot network to capture recurring maintenance contracts. Crystal Fountains Inc. anchors its North American position through specialized architectural fountain integration. Suzhou Gold Ocean Co., Ltd. competes on manufacturing scale for standardized electric-powered units destined for Asian municipal bids.
Floating fountains are self-contained water circulation devices that rest on reservoir surfaces, typically employing submersible pumps rated between 1 and 75 horsepower to project water through programmable nozzle arrays while simultaneously oxygenating the water column. Their primary commercial purpose spans aesthetic display, algae suppression, and aquatic ecosystem management in artificial lakes, retention ponds, and decorative basins. Solar-powered systems now lead municipal procurement channels where off-grid installation eliminates trenching costs, while hybrid configurations represent the fastest-growing segment as hospitality clients seek backup reliability for premium water resort displays. Permanent installations dominate the installed base but portable and seasonal categories are gaining share among golf courses and recreation centers requiring event-driven repositioning.
EPA Clean Water Act provisions and state-level stormwater management codes in the United States shape product specifications by mandating minimum dissolved oxygen thresholds that aerating fountains must achieve. CE marking under the EU Machinery Directive governs electrical safety and electromagnetic compatibility for units sold across European member states, while China's GB standards enforced by SAMR establish pump efficiency and material corrosion benchmarks for domestic manufacturers. Stakeholders must monitor evolving municipal sustainability procurement rules that increasingly preference solar-powered and low-vibration systems over legacy electric alternatives.
Market Dynamics
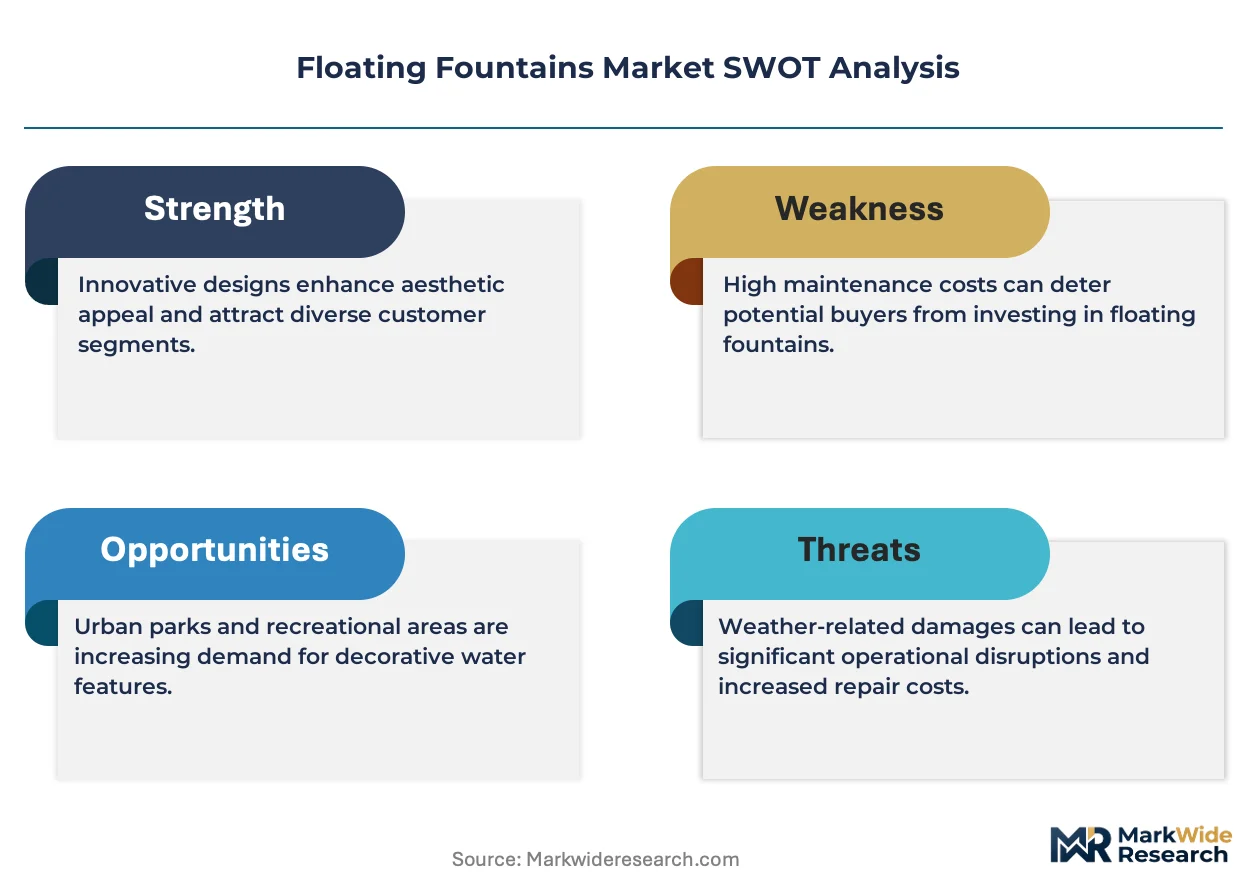
Municipal sustainability mandates are compressing replacement cycles for legacy electric-powered units while simultaneously elevating solar-hybrid configurations to default specification status in public procurement channels.
Growth Catalysts
- EPA Clean Water Act compliance:Stagnant water feature replacements in US municipal lake systems are accelerating procurement of aerating fountain systems that achieve mandated dissolved oxygen thresholds.
- Solar photovoltaic cost curves:Off-grid installation economics now eliminate trenching expenditures for remote reservoir sites, expanding addressable market coverage for park districts and golf courses.
- Water resort clustering:Hospitality development corridors in Florida, California, and Texas are generating concentrated demand for programmable display systems with backup reliability requirements.
Market Restraints
- Submersible pump supply concentration:Sourcing dependency on Asian manufacturing clusters for magnet motor assemblies creates lead time volatility and inventory carrying cost pressure.
- Stainless steel alloy input costs:Grade 316L corrosion-resistant housings face nickel and molybdenum price swings that compress margin on standardized municipal bid contracts.
- Winterization service bundling:Seasonal climate zones require mandatory pump extraction and storage protocols that add lifecycle cost burden versus permanent architectural fountain alternatives.
Strategic Opportunities
- Smart nozzle array convergence:Integration of IoT flow sensors with programmable LED lighting is opening premium tier positioning for hospitality clients seeking synchronized multimedia displays.
- Retention pond stormwater codes:Expanding state-level mandates for post-construction water quality management are creating specification pathways for aerating fountains in commercial real estate development.
- Aftermarket service unbundling:Specialized maintenance depots can capture recurring revenue streams through nozzle replacement contracts and predictive pump overhaul scheduling.
Industry Challenges
- Certification timeline compression:CE marking under the EU Machinery Directive and electromagnetic compatibility testing create multi-month approval bottlenecks for new product introductions.
- Legacy control system integration:Municipal parks departments operate fragmented SCADA architectures that require custom protocol bridges for remote fountain monitoring deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Fountains Market |
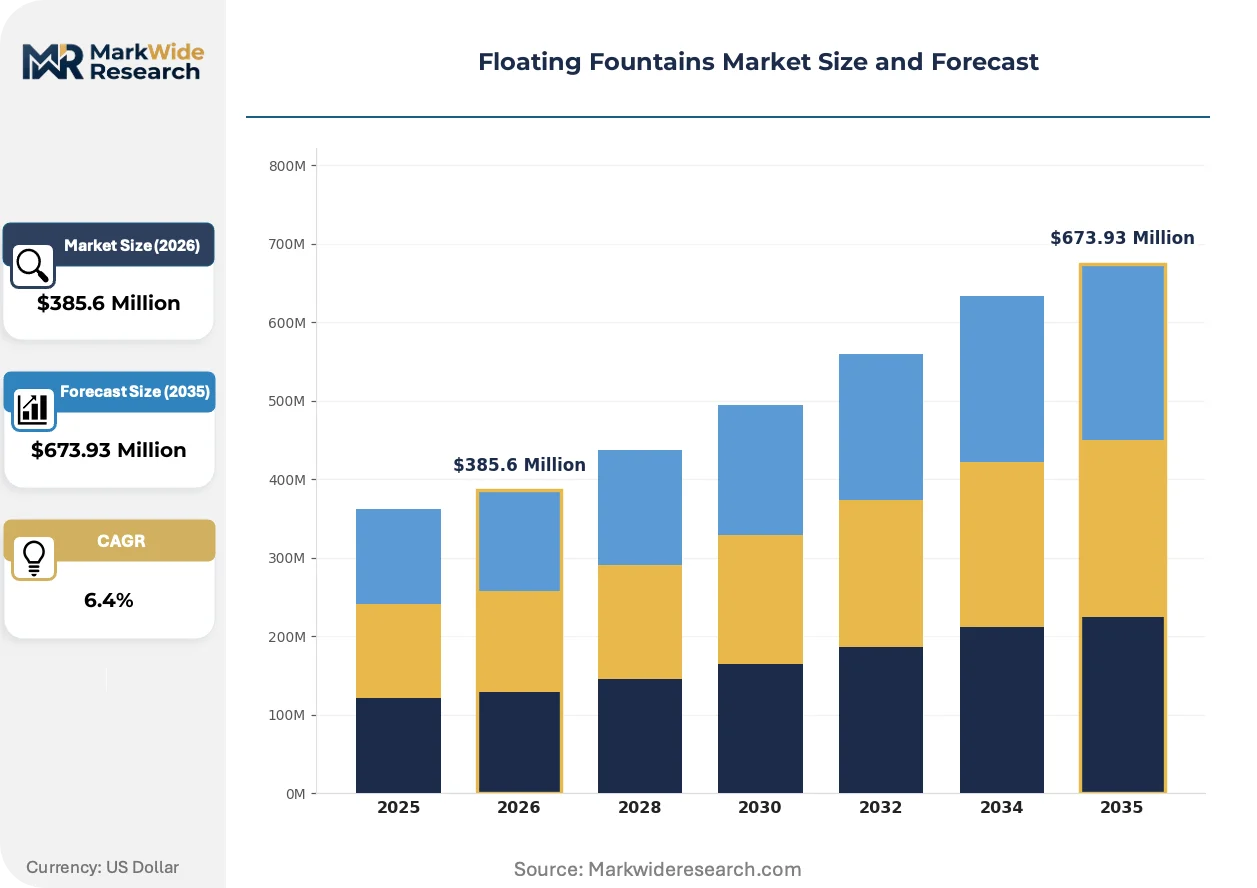
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar-Powered, Electric-Powered, Battery-Powered, Hybrid, Pneumatic Application: Parks, Hotels, Golf Courses, Commercial Complexes, Water Resorts Installation Type: Permanent, Portable, Semi-Permanent, Seasonal End User: Municipal Corporations, Hospitality Sector, Recreation Centers, Private Estates |
| Companies Covered | OASE GmbH, Aquarius Fountain & Aeration Ltd., Crystal Fountains Inc., Fountain Works Inc., Jetline Systems Ltd., Dolphin Aquatics Ltd., Suzhou Gold Ocean Co., Ltd., Lumiartecnia International, Water Dimension BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Fountains Market Shifts & Advancements
Product architecture is bifurcating between solar-dominant municipal specifications and hybrid-electric hospitality systems, while control intelligence migrates toward cloud-connected predictive maintenance platforms.
Photovoltaic pump drives are migrating from niche remote installations to standard municipal procurement specifications. Park districts in sunbelt states now specify solar-primary systems with grid-tie backup as default configurations. This technology shift is compressing demand for pure electric-powered units in public sector channels while expanding total addressable market coverage to off-grid reservoir sites previously deemed uneconomical for fountain deployment.
China's GB standards enforced by SAMR are tightening pump efficiency benchmarks and material corrosion resistance requirements for domestic manufacturers. Export-oriented suppliers must now maintain dual certification pathways to serve both domestic and international customers. European importers are responding by consolidating supplier relationships with Chinese manufacturers holding concurrent CE marking and updated GB compliance documentation.
Subscription-based maintenance contracts are displacing transactional service calls in the commercial installed base. Water resort operators and municipal parks departments now prioritize multi-year service agreements covering seasonal winterization, nozzle replacement, and pump overhaul over per-incident billing. This behavioral shift is most visible in Florida and Texas hospitality clusters where uptime guarantees carry premium contract value.
Floating Fountains Market Segmentation
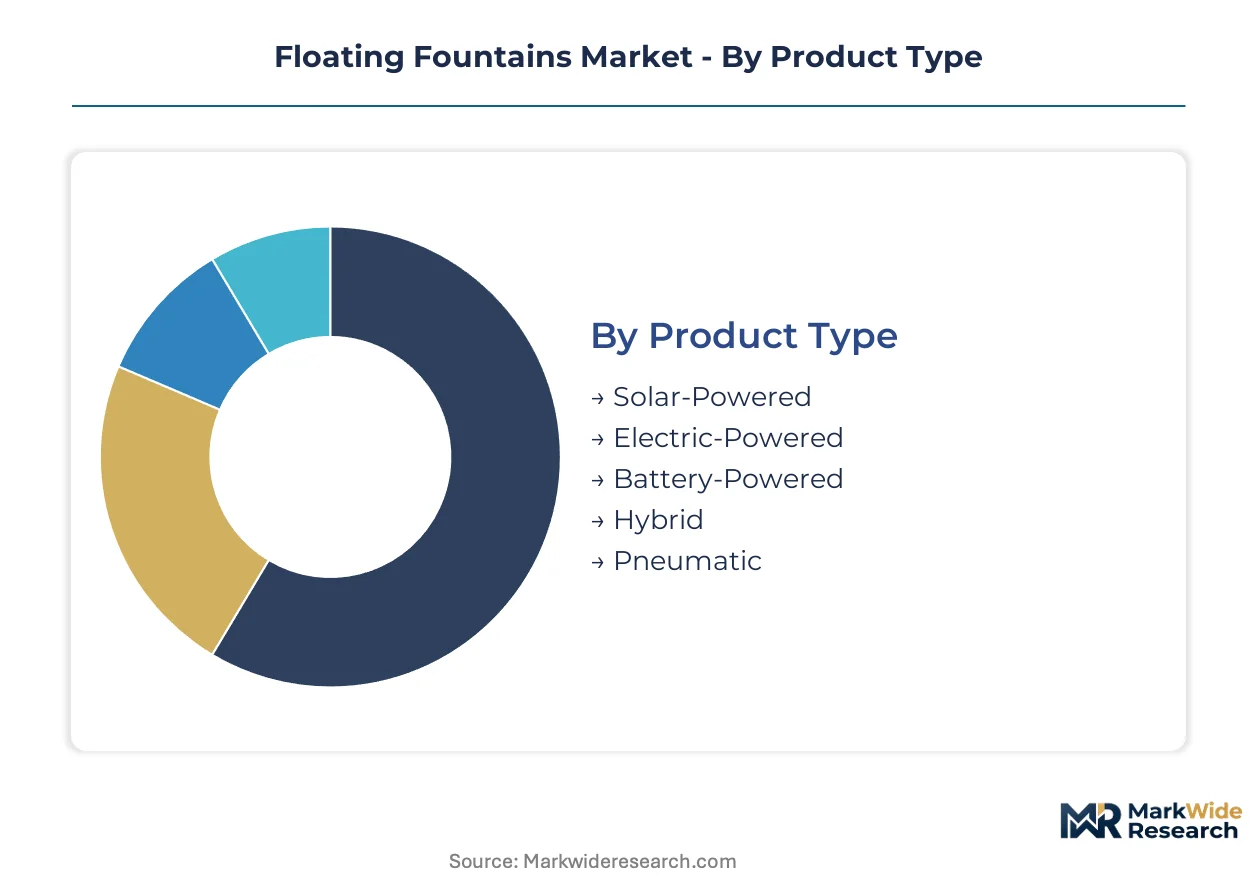
Power source configurations, installation permanence, and end-use procurement patterns define competitive positioning across the floating fountains value chain. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor targeting strategies.
Product Type:
Cost tier differentiation across power systems determines municipal procurement eligibility and hospitality premium positioning.
- Solar-Powered:Photovoltaic pump drives rated between 1 and 75 horsepower eliminate trenching expenditures for off-grid reservoir sites. Florida and Texas park districts now specify solar-primary systems as default configurations for remote lake restoration projects.
- Hybrid:Dual-source architectures combining photovoltaic arrays with grid-tie backup deliver reliability guarantees for water resort displays. Hospitality clusters in California prioritize these configurations for premium programmable nozzle arrays requiring uninterrupted operation.
- Electric-Powered:Legacy submersible motor assemblies face compressed replacement cycles under EPA Clean Water Act compliance mandates.
- Battery-Powered:Lithium-ion storage integration enables temporary installations without electrical infrastructure.
- Pneumatic:Compressed air-driven projection systems serve specialized architectural fountain integration requirements.
Electric-powered systems hold installed capacity. Hybrid configurations are rotating up the share rankings.
Application:
Customer type concentration varies sharply between aesthetic-driven hospitality spend and compliance-driven municipal procurement.
- Water Resorts:Programmable LED-synchronized displays with IoT flow sensors command premium tier positioning. Florida hospitality corridors generate concentrated demand for multimedia fountain systems with predictive maintenance platforms.
- Parks:Aerating fountain systems achieve mandated dissolved oxygen thresholds under EPA Clean Water Act provisions. Municipal lake restoration projects across sunbelt states specify these units for algae suppression and aquatic ecosystem management.
- Hotels:Architectural fountain integration requirements prioritize aesthetic synchronization with landscape design.
- Golf Courses:Event-driven repositioning needs favor portable and seasonal installation categories.
- Commercial Complexes:Retention pond stormwater codes create specification pathways for aerating fountains in post-construction water quality management.
Parks anchor municipal procurement volume. Water Resorts are climbing the fastest expansion trajectory.
Installation Type:
Permanence duration dictates service revenue bundling and winterization protocol requirements.
- Permanent:Fixed submersible pump installations with Grade 316L stainless steel housings dominate the installed base. These systems require predictive pump overhaul scheduling through multi-year maintenance agreements.
- Portable:Modular floating platforms enable rapid repositioning for event-driven deployment. Golf courses and recreation centers in seasonal climate zones prioritize these configurations for flexible reservoir coverage.
- Semi-Permanent:Anchored systems with seasonal extraction capabilities balance durability with repositioning flexibility.
- Seasonal:Mandatory pump extraction and storage protocols add lifecycle cost burden through specialized winterization service contracts.
Permanent installations dominate current deployment. Portable systems are gaining share among event-centric end users.
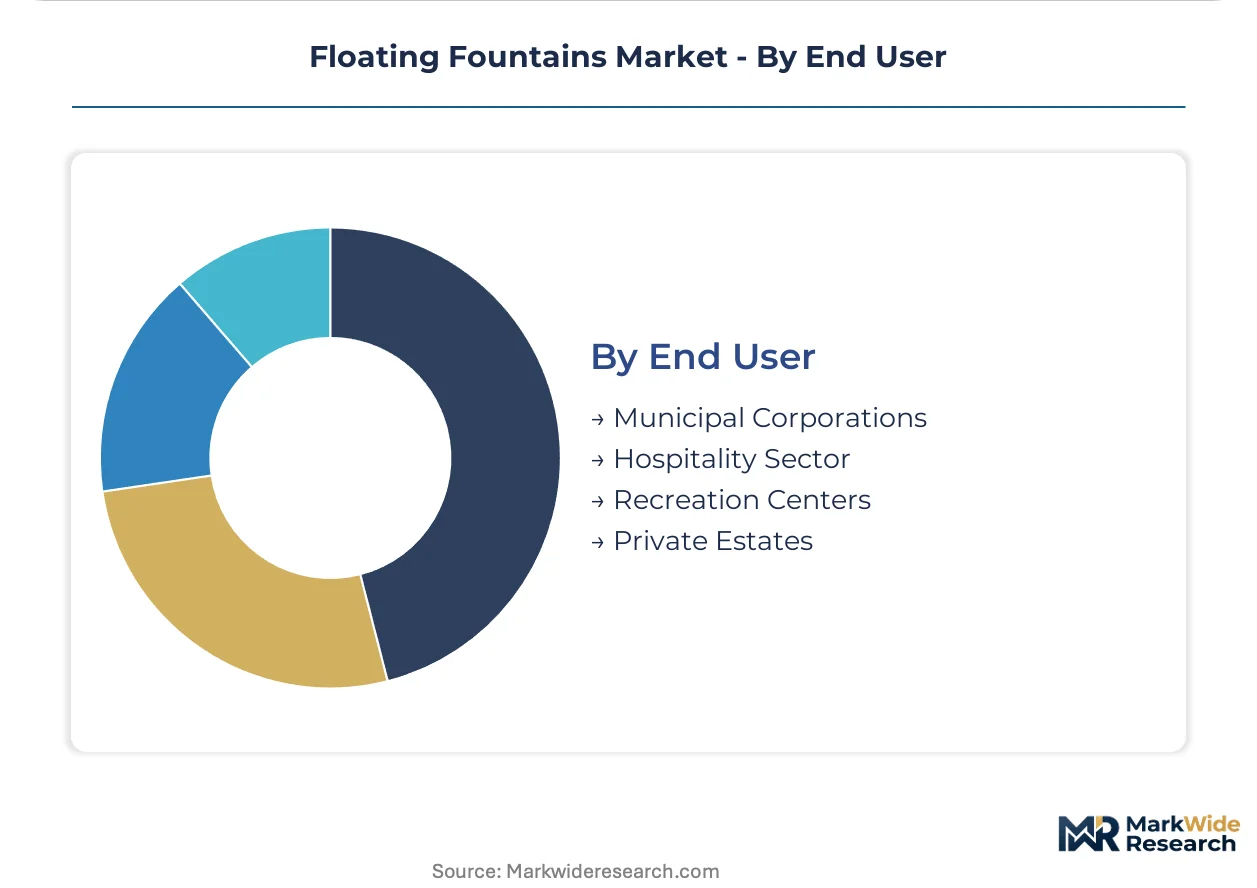
End User:
Procurement authority structures and budget cycles create distinct sales motion requirements across buyer categories.
- Municipal Corporations:Public procurement channels governed by sustainability mandates preference solar-powered and low-vibration systems. EPA compliance requirements accelerate replacement of stagnant water features with circulating models in urban lake systems.
- Hospitality Sector:Water resort operators prioritize subscription-based maintenance contracts covering seasonal winterization and uptime guarantees. Texas and Florida hospitality clusters drive concentrated demand for backup reliability specifications.
- Recreation Centers:Budget-constrained facilities favor standardized electric-powered units with transactional service arrangements.
- Private Estates:Custom architectural fountain integration projects require specialized nozzle array design and installation services.
Municipal Corporations anchor public sector procurement volume. The Hospitality Sector is expanding most quickly in premium-tier contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for submersible pump assemblies and stainless steel fountain housings clusters in China and Germany, with final system integration distributed across North American and European assembly facilities serving municipal and hospitality procurement channels.
United States
EPA Clean Water Act compliance mandates accelerate municipal lake restoration projects across Florida, California, and Texas. State-level stormwater management codes in these jurisdictions specify minimum dissolved oxygen thresholds that aerating fountains must achieve. Water resort clusters in Orlando and Miami generate concentrated procurement for programmable display systems with backup reliability specifications.
Germany
CE marking requirements under the EU Machinery Directive govern electrical safety and electromagnetic compatibility for units sold across European member states. Municipal sustainability procurement rules increasingly preference solar-powered and low-vibration systems over legacy electric alternatives. The OASE GmbH service depot network anchors aftermarket maintenance contract capture across Central European park districts.
China
GB standards enforced by SAMR establish pump efficiency and material corrosion benchmarks for domestic manufacturers. Export-oriented suppliers maintain dual certification pathways to serve both domestic and international customers. Suzhou Gold Ocean Co., Ltd. competes on manufacturing scale for standardized electric-powered units destined for Asian municipal bids.
United Kingdom
Retention pond stormwater codes create specification pathways for aerating fountains in commercial real estate development. The country's national environmental regulator enforces post-construction water quality management standards that elevate circulating water features over stagnant alternatives. London hospitality developments drive demand for architectural fountain integration with landscape design synchronization.
Canada
Health Canada and PMRA guidelines shape aquatic ecosystem management specifications for municipal procurement. Provincial park districts in Ontario and British Columbia specify solar-primary systems for remote reservoir sites where trenching costs previously rendered fountain deployment uneconomical. Seasonal winterization service bundling adds lifecycle cost burden through mandatory pump extraction protocols.
Floating Fountains Market Competitive Landscape
European service specialists and Asian manufacturing-scale operators split the market across premium aftermarket and standardized municipal bid channels. The vendor base organizes around three strategic archetypes: integrated fountain-aeration specialists with depot networks, manufacturing-scale fabricators serving public procurement, and architectural integration firms targeting hospitality developments. Competitive dynamics center on geographic service coverage expansion and solar-hybrid product portfolio diversification.
Within the integrated service tier, OASE GmbH anchors recurring maintenance contract capture through its European depot network. Among North American specialists, Crystal Fountains Inc. occupies a position exemplifying architectural fountain integration for hospitality clients. At the manufacturing-scale end, Suzhou Gold Ocean Co., Ltd. represents the archetype of standardized electric-powered unit production for municipal bid channels. These three entities collectively illustrate the geographic and capability segmentation defining competitive positioning.
| Leading Market Players |
|---|
| OASE GmbH |
| Aquarius Fountain & Aeration Ltd. |
| Crystal Fountains Inc. |
| Fountain Works Inc. |
| Jetline Systems Ltd. |
| Dolphin Aquatics Ltd. |
| Suzhou Gold Ocean Co., Ltd. |
| Lumiartecnia International |
| Water Dimension BV |
| Others |
Supply & Pricing Matrix
Suzhou manufacturing clusters anchor global submersible pump assembly capacity, concentrating magnet motor sourcing leverage among Asian fabricators and compressing margin negotiation space for European and North American system integrators bidding on municipal contracts.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates hospitality multimedia systems with IoT-enabled predictive maintenance from municipal solar-primary configurations and bid-commoditized electric-powered units. Cost compression in the standard tier intensifies because stainless steel alloy input volatility and Asian pump supply concentration squeeze fixed-bid profitability. Municipal procurement officers exhibit highest price sensitivity, while water resort operators prioritize uptime guarantees over per-unit hardware cost.
Supply Chain Analysis
Extended payment terms from European depot operators to Chinese pump manufacturers are becoming standard practice to manage working capital through seasonal demand cycles. Magnet motor assemblies and Grade 316L stainless steel housings draw from China, Germany, and South Korean supplier networks. Single-source vulnerability concentrates in photovoltaic inverter components for solar-hybrid configurations. Distribution runs through municipal procurement channels, hospitality project developers, and specialized fountain integration firms serving architectural specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based maintenance agreements are expanding faster than hardware unit sales, converting transactional nozzle replacement and winterization services into recurring revenue streams with multi-year contract tenures.
For Market Incumbents: Insulate service contract portfolios from solar-hybrid new entrants by deepening depot network density in Florida and Texas hospitality corridors. Prioritize CE marking and GB standards dual certification to maintain access across European and Chinese procurement channels. Capacity addition in Vietnamese pump assembly can offset magnet motor supply concentration risk. For New Entrants and Emerging Players: Establish a beachhead in portable and seasonal installation categories where golf courses and recreation centers lack incumbent service coverage. Battery-powered temporary systems represent the most penetrable segment given minimal electrical infrastructure requirements. A direct-to-municipal sales motion emphasizing trenching cost elimination can accelerate solar-primary adoption in remote reservoir sites. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with underoptimized fountain-aeration divisions lacking standalone service infrastructure. The installed base of permanent municipal systems offers predictable overhaul scheduling visibility across a 5-10 year replacement horizon. Monitor solar photovoltaic cost curve acceleration as inflection indicator for hybrid configuration margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Service Depot Network Expansion | Recurring maintenance contracts in Florida and Texas hospitality clusters capture multi-year revenue visibility. |
| Solar-Hybrid Product Portfolio Diversification | Dual-source architectures satisfy municipal sustainability mandates and hospitality backup reliability requirements simultaneously. |
| Dual Certification Investment | Concurrent CE marking and GB standards compliance opens European and Chinese procurement channels without product variant duplication. |
| IoT-Enabled Predictive Maintenance Platform | Cloud-connected flow sensors and pump health monitoring convert transactional service calls into subscription revenue streams. |
| Backward Integration into Pump Assembly | In-house magnet motor production reduces lead time volatility from Asian manufacturing concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal parks procurement officers, water resort operations directors, fountain integration specialists, and aftermarket service depot managers. Secondary validation drew from EPA Clean Water Act compliance filings, state-level stormwater management code databases, SAMR GB standards documentation, and EU Machinery Directive CE marking registries. Bottom-up unit shipment estimates across power source configurations were triangulated against top-down municipal budget allocation data for lake restoration projects.
Calibration against historical replacement cycle patterns and solar photovoltaic adoption curves anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include power source architecture, installation permanence duration, end-use procurement channel, and geographic regulatory cluster. CAGRs were derived from slope analysis of technology substitution curves and compliance-driven replacement acceleration. Forecast inputs incorporated stainless steel alloy price index trajectories and photovoltaic module cost curve assumptions.
Stress conditions across nickel and molybdenum input volatility, magnet motor supply lead time disruption, and municipal budget freeze scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA enforcement continuity and solar cost curve trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
Retractable Awnings Market