
 North America Residential Outdoor Gas Fire Pits Market | 2026-2036
North America Residential Outdoor Gas Fire Pits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Outdoor Gas Fire Pits Market Analytics
The vacation rental and hospitality-adjacent residential segment is consolidating as a demand anchor for premium gas fire pit installations. Solo Stove leverages direct-to-consumer channel control to capture digitally native buyers seeking design-forward portable units. Breeo Industries LLC anchors its position through specialized smokeless combustion technology leadership. The Outdoor GreatRoom Company LLC competes across built-in and tabletop configurations with sustained manufacturing scale in the upper Midwest.
North America residential outdoor gas fire pits are self-contained or permanently installed gas-burning appliances engineered for outdoor leisure heating, typically rated between 40,000 and 100,000 BTU and constructed from corrosion-resistant alloys or stone composites for weather durability. Their primary purpose centers on extending habitable outdoor living hours while providing controlled flame ambiance without wood combustion byproducts. Portable fire pits lead volume throughput due to lower entry price points and renter accessibility, though built-in fire pits command superior margin pools through contractor-dependent installation and custom hardscape integration. Steel dominates material throughput for its cost-efficiency and fabrication flexibility, while cast iron occupies the premium tier through thermal retention performance and heirloom positioning.
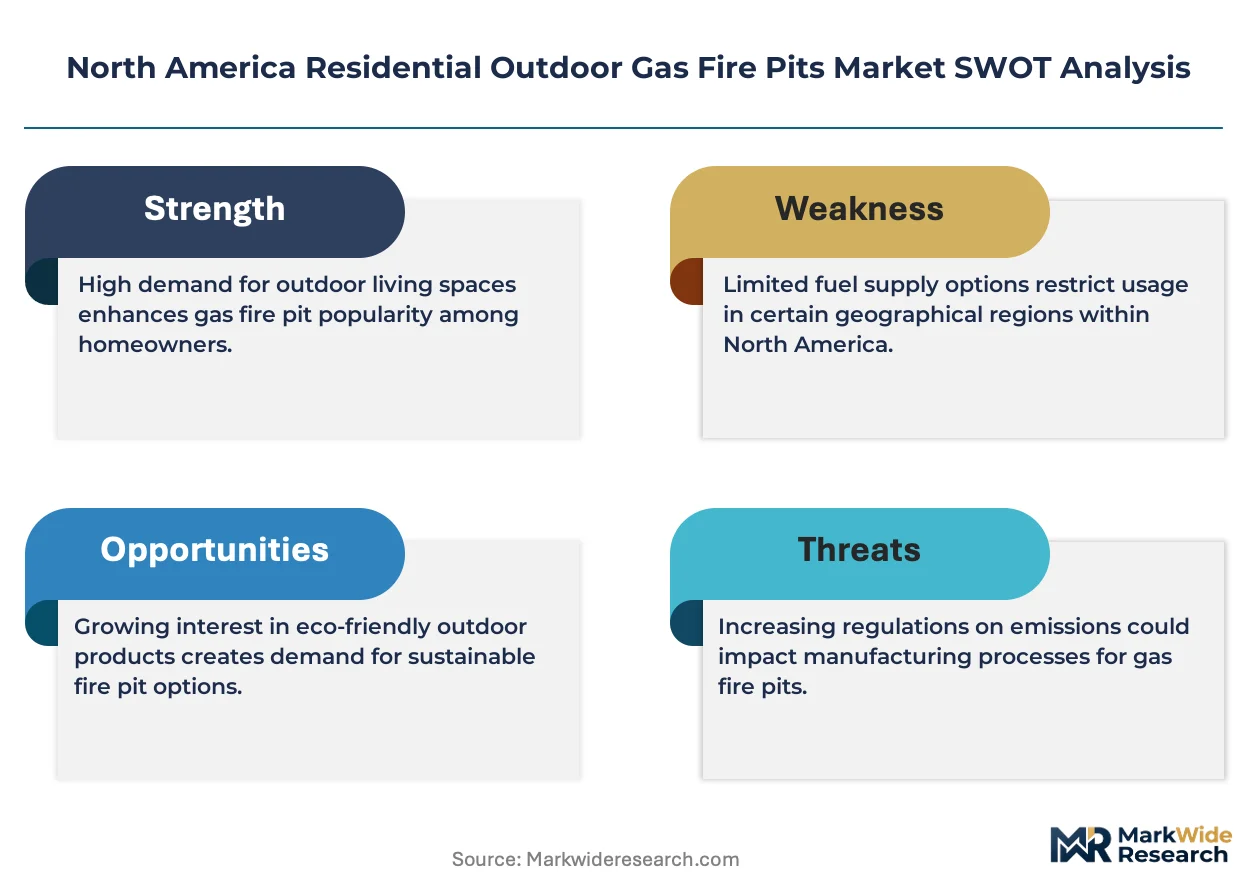
The CSA Group and Underwriters Laboratories shape product safety and market access through ANSI Z21.97 and CSA 2.41 certification mandates for outdoor gas appliances, with EPA regional haze regulations indirectly constraining propane sourcing in certain air quality non-attainment zones. The U.S. Department of Transportation and Transport Canada govern pressurized fuel cylinder transport standards that affect portable propane unit distribution logistics. Stakeholders must monitor evolving municipal fire codes and homeowner association covenants that increasingly restrict open-flame appliances in wildland-urban interface zones across California, Colorado, and British Columbia.
Market Dynamics
Single-family homeowners are consolidating outdoor living investments as a permanent lifestyle shift, permanently altering how gas fire pit manufacturers configure product portfolios and distribution channels across the United States and Canada.
Growth Catalysts
- CSA Group certification harmonization:Unified ANSI Z21.97 and CSA 2.41 standards streamline cross-border product launches between the United States and Canada, reducing duplicate testing costs for manufacturers.
- Vacation rental property investment:Airbnb and Vrbo hosts in Arizona, Florida, and Texas deploy premium built-in units to differentiate outdoor amenities and command nightly rate premiums.
- Smokeless combustion engineering:Secondary burn technology eliminates particulate emissions, expanding addressable markets into municipalities with strict open-flame ordinances.
Market Restraints
- Steel input cost volatility:Galvanized and stainless steel price swings compress fabrication margins, forcing mid-tier manufacturers toward thinner-gauge substitutes.
- Propane cylinder supply concentration:DOT-4BA240 cylinder production clusters in Ohio and Pennsylvania, creating regional bottlenecks during peak seasonal demand.
- Wood pellet substitution:Biomass-burning alternatives attract sustainability-focused buyers in Pacific Northwest and New England markets with abundant forestry waste streams.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Manitoba and Saskatchewan exhibit low installed-base density despite extended shoulder seasons suitable for outdoor heating.
- Smart home integration convergence:Bluetooth-enabled ignition and voice-control compatibility with Amazon Alexa and Google Home ecosystems differentiate premium SKUs.
- Direct-to-consumer channel maturation:Social commerce and influencer partnerships bypass traditional big-box retail markups, capturing digitally native millennial and Gen Z first-time homeowners.
Industry Challenges
- Welding and metal fabrication skill scarcity:Journeyman welder shortages in the upper Midwest constrain production scaling for custom hardscape-integrated units.
- Wildland-urban interface code fragmentation:California, Colorado, and British Columbia municipalities impose divergent setback and shutoff requirements, complicating SKU rationalization.
- CSA/UL certification timeline compression:Third-party testing laboratory backlogs extend product launch windows by four to six months during peak submission periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Outdoor Gas Fire Pits Market |
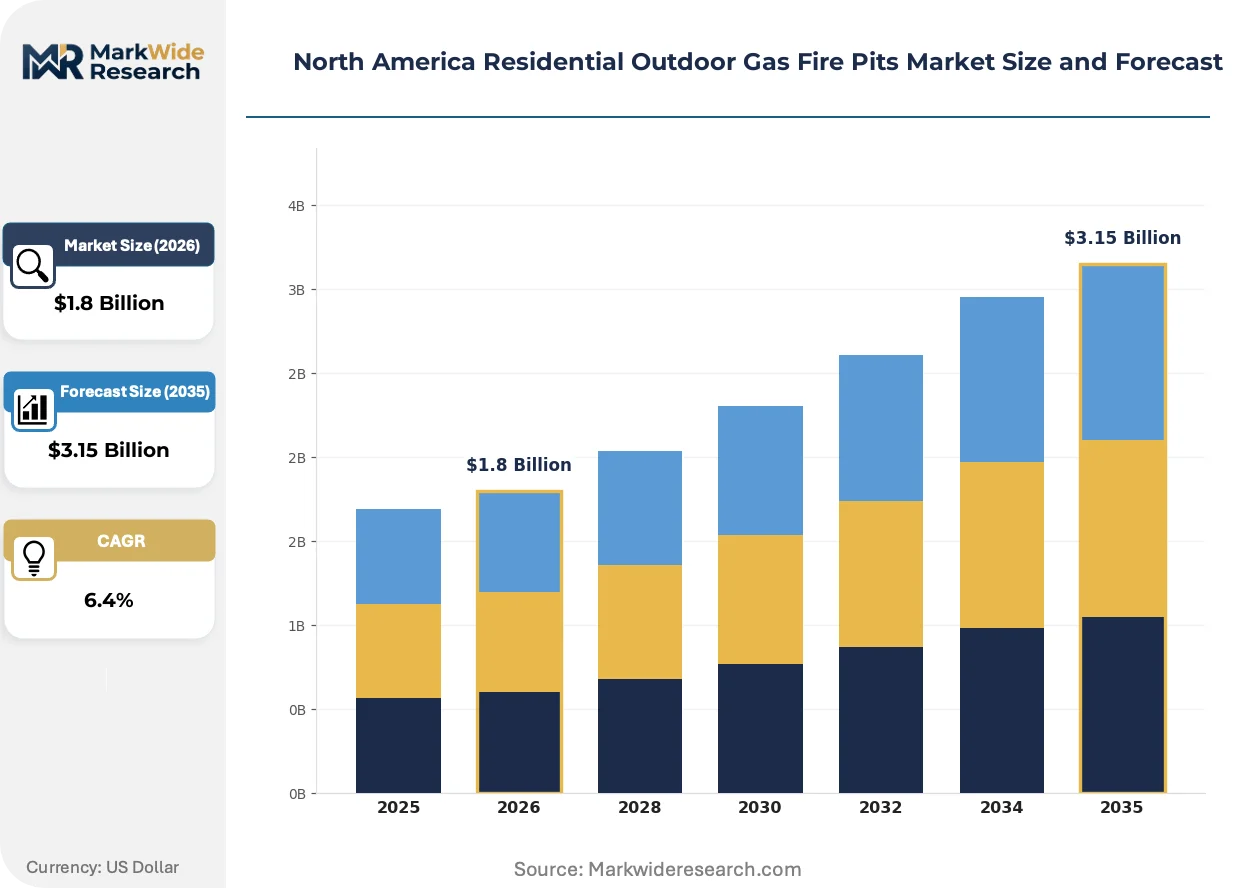
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Fire Pits, Built-In Fire Pits, Tabletop Fire Pits, Fire Bowls Material: Steel, Aluminum, Cast Iron, Stone Fuel Type: Natural Gas, Propane, Biogas, Others Design: Modern, Rustic, Traditional, Minimalist |
| Companies Covered | The Outdoor GreatRoom Company LLC, Solo Stove, Breeo Industries LLC, Fire Pit Art, Tropitone Furniture Co., Inc., The Blue Rooster Company, Ohio Flame, Inc., Warming Trends Inc., Hearth Products Controls, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Outdoor Gas Fire Pits Market Evolving Landscape
Product engineering and channel configuration are simultaneously converging toward modularity and digital integration, compressing traditional design-to-installation cycles while expanding addressable buyer segments beyond conventional outdoor furniture purchasers.
Modular fire pit systems with interchangeable burner inserts, media beds, and surround panels are unifying previously separate portable and built-in categories. Custom home builders in Texas and Georgia specify these platforms to accelerate project completion timelines. The technology is unifying contractor procurement patterns around single-vendor relationships rather than fragmented specialty sourcing.
The EPA's regional haze regulations and California Air Resources Board stationary source rules are tightening emissions thresholds for outdoor combustion appliances. Manufacturers now engineer sub-35,000 BTU low-NOx burners to preempt compliance mandates. Portable propane units face heightened scrutiny in San Joaquin Valley and Front Range air quality non-attainment zones, accelerating electric ignition and precision flame control adoption.
Subscription-based outdoor furniture leasing models are emerging as an alternative to outright purchase among urban renters in Toronto, Vancouver, and Seattle. Property management firms bundle gas fire pits with patio sets into seasonal refresh programs. This channel innovation concentrates in coastal metropolitan markets where housing turnover and space constraints discourage permanent installations.
North America Residential Outdoor Gas Fire Pits Market Segmentation
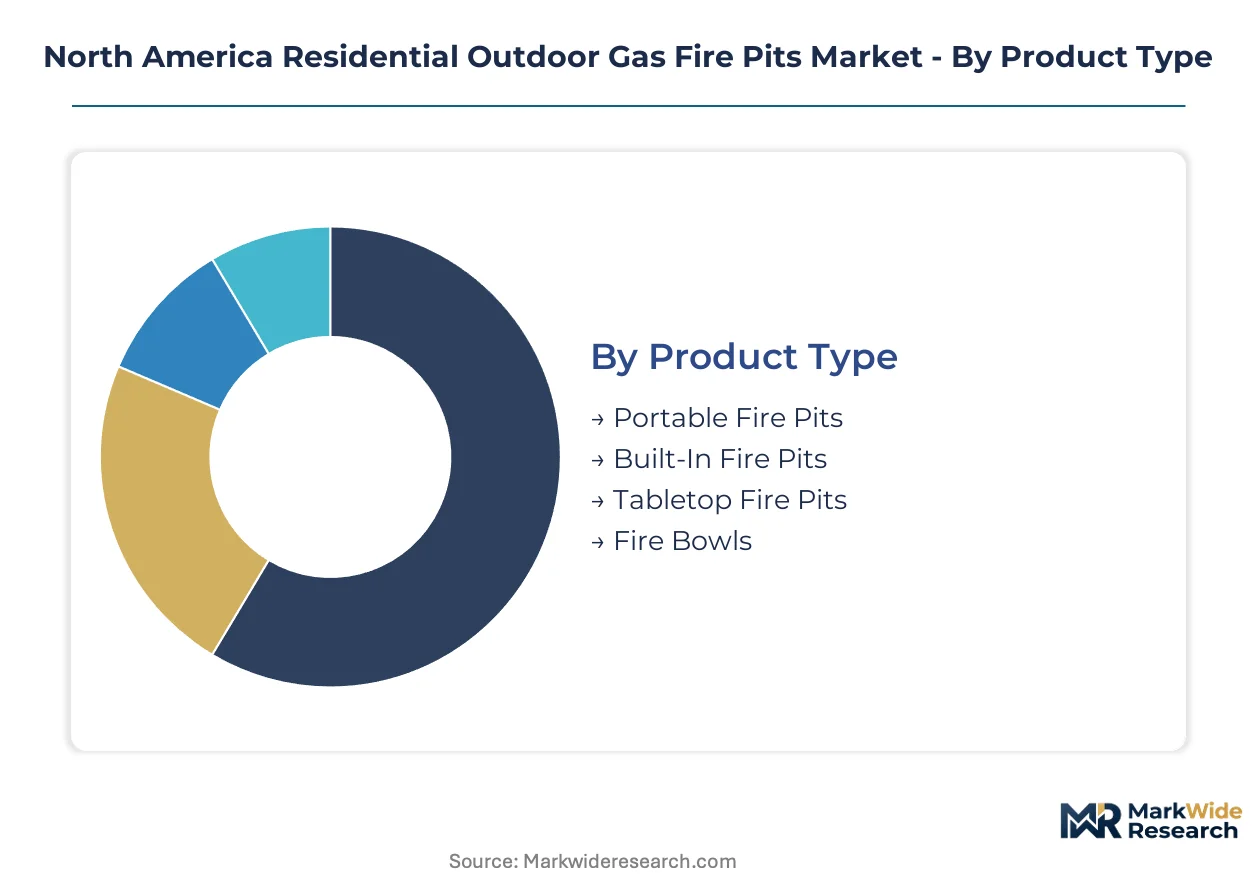
Segmentation in North America residential outdoor gas fire pits reveals how capital deployment, material sourcing, and design preferences fragment addressable demand across distinct buyer archetypes. Manufacturers configure production lines and inventory pools around these divisions to capture margin in contractor-driven versus consumer-direct channels.
Product Type:
Capital intensity varies sharply across installation requirements, with permanent hardscape integration demanding substantially higher upfront tooling and skilled labor allocation than portable alternatives.
- Portable Fire Pits:Self-contained propane units with DOT-certified cylinders and quick-connect fittings dominate unit volume through big-box retail and direct-to-consumer channels. Demand concentrates among Arizona and Florida renters seeking seasonal flexibility without structural modifications. CSA certification costs remain manageable due to standardized burner assemblies.
- Built-In Fire Pits:Hardscape-integrated systems requiring ANSI Z21.97 certification and licensed gas line installation command premium positioning in Texas and Georgia custom home construction. Capital requirements scale with burner BTU rating, media bed customization, and surround material procurement.
- Tabletop Fire Pits:Compact ethanol or propane units designed for balcony and small patio deployment target urban density markets in Toronto and Vancouver where space constraints limit full-size installations.
- Fire Bowls:Sculptural copper or concrete vessels with integrated burners occupy design-forward segments in California coastal markets, requiring specialized metal forming or precast concrete capabilities.
Portable fire pits absorb the bulk of installed capacity; built-in fire pits are expanding most quickly through vacation rental property upgrades.
Material:
Raw material selection directly determines thermal performance, weather durability, and finished goods pricing tiers across the value chain.
- Steel:Galvanized and powder-coated mild steel dominates fabrication throughput due to welding efficiency and gauge flexibility. Sun Belt contractors in Texas and Florida specify steel for cost-sensitive subdivision projects where replacement cycles align with home resale timelines.
- Cast Iron:High thermal mass alloys with machined burner interfaces occupy heirloom positioning in Midwest markets where extended shoulder seasons demand sustained radiant output. Foundry capacity constraints in Ohio and Pennsylvania limit scaling.
- Aluminum:Marine-grade alloys resist corrosion in Pacific Northwest and British Columbia coastal installations where salt air accelerates ferrous metal degradation.
- Stone:Cast concrete, granite, and manufactured stone composites integrate with hardscape aesthetics in Colorado and California custom residential projects requiring wildland-urban interface compliance.
Steel commands the greatest production volume; cast iron delivers the steepest per-unit margins through durability positioning.
Fuel Type:
Infrastructure availability and regulatory pressure on combustion emissions shape fuel selection across municipal jurisdictions.
- Natural Gas:Permanent plumbed connections eliminate cylinder logistics and deliver lowest operating cost where utility infrastructure exists. California municipalities with air quality non-attainment status increasingly mandate natural gas over propane for stationary installations.
- Propane:Portable cylinder systems dominate markets without natural gas lateral access, including rural Canadian Prairies and mountainous Colorado corridors. DOT transport regulations govern cylinder distribution from Ohio and Pennsylvania production clusters.
- Biogas:Renewable methane capture systems attract sustainability-focused buyers in Pacific Northwest markets with access to agricultural or wastewater digester supply.
- Others:Ethanol and gel fuel alternatives serve municipalities with strict open-flame prohibitions where gas combustion faces outright bans.
Propane retains the broadest geographic coverage; natural gas is gaining share fastest through new construction pre-plumbing.
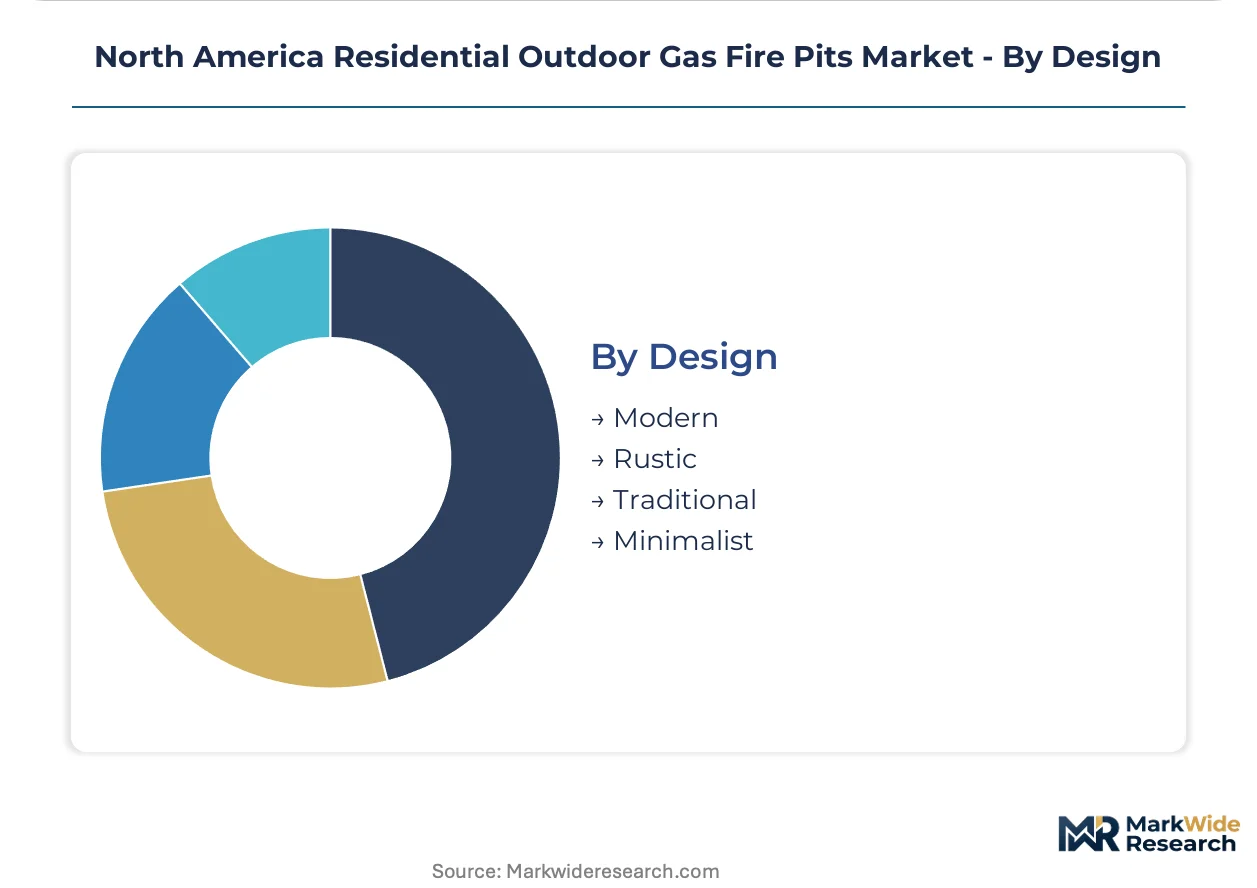
Design:
Aesthetic positioning segments buyer pools between architectural integration and standalone statement pieces.
- Modern:Clean geometric lines, linear burners, and neutral finishes align with contemporary California and Arizona residential architecture. Specified by design-build firms seeking visual continuity with pool and landscape elements.
- Rustic:Weathered steel patinas, simulated stone textures, and organic silhouettes target Colorado and Montana mountain markets where architectural vernacular emphasizes natural materiality.
- Traditional:Ornate cast details, copper accents, and classic fire bowl forms serve established suburban markets in Texas and Georgia with conventional landscape aesthetics.
- Minimalist:Reduced visual mass and hidden burner systems appeal to Scandinavian-influenced design preferences in Pacific Northwest urban cores.
Modern styling captures the largest specification share; minimalist designs are climbing the fastest through millennial first-time homeowner channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in the upper Midwest and Ohio River Valley, while consumption tilts toward Sun Belt states with extended outdoor seasons. Canadian demand remains underpenetrated relative to climate suitability. Cross-border certification harmonization enables unified product launches.
United States
Texas and Florida homeowners drive built-in installations through vacation rental upgrades and custom residential construction. EPA regional haze regulations constrain propane combustion in San Joaquin Valley and Front Range air quality non-attainment zones. Ohio and Pennsylvania host DOT-certified cylinder production clusters that supply portable unit distribution networks.
Canada
Manitoba and Saskatchewan exhibit low installed-base density despite shoulder seasons favorable to outdoor heating. CSA Group certification mandates under ANSI Z21.97 and CSA 2.41 standards streamline U.S. product entry but create testing backlogs during peak submission windows. Toronto and Vancouver concentrate subscription-based outdoor furniture leasing among urban renters.
California
Coastal metropolitan markets favor sculptural fire bowls and minimalist designs aligned with contemporary architecture. California Air Resources Board stationary source rules tighten emissions thresholds for outdoor combustion appliances. San Diego and Los Angeles custom home builders specify low-NOx burners to preempt compliance mandates.
Colorado
Mountain corridor municipalities impose divergent setback and shutoff requirements in wildland-urban interface zones. Front Range air quality regulations accelerate electric ignition adoption for portable propane units. Denver-Boulder design-build firms source modular systems to accelerate project completion timelines.
British Columbia
Vancouver's dense urban core favors compact tabletop units for balcony deployment where space constraints limit full-size installations. Provincial wildfire risk management policies increasingly restrict open-flame appliances in interface zones. Coastal salt air corrosion drives marine-grade aluminum specification over ferrous alternatives.
North America Residential Outdoor Gas Fire Pits Market Competitive Landscape
Top-tier vendors anchor CSA/UL-certified built-in systems, while mid-tier fabricators compete on portable unit volume through big-box retail and direct-to-consumer channels. The vendor base stratifies across certification depth, manufacturing scale, and channel control intensity. Three archetypes dominate: smokeless combustion specialists, design-forward direct-to-consumer brands, and hardscape-integrated system providers. Competitive moves concentrate on direct-to-consumer channel maturation and smart home integration partnerships.
Within the smokeless combustion tier, Breeo Industries LLC exemplifies technology-led positioning through specialized engineering capabilities. Solo Stove occupies the design-forward direct-to-consumer vector with digitally native buyer capture. The Outdoor GreatRoom Company LLC anchors the built-in and tabletop configuration segment through sustained manufacturing scale in the upper Midwest. These three entities represent distinct competitive archetypes rather than overlapping market positions.
| Leading Market Players |
|---|
| The Outdoor GreatRoom Company LLC |
| Solo Stove |
| Breeo Industries LLC |
| Fire Pit Art |
| Tropitone Furniture Co., Inc. |
| The Blue Rooster Company |
| Ohio Flame, Inc. |
| Warming Trends Inc. |
| Hearth Products Controls |
| Others |
Value Network & Pricing Analysis
Vacation rental host procurement consolidation for premium built-in units in Texas and Florida is forcing manufacturers to pre-position CSA-certified inventory closer to Sun Belt demand clusters, compressing working capital cycles and elevating spot pricing for expedited fulfillment.
Pricing Analysis
Short lead-time premiums dominate pricing architecture for custom hardscape-integrated systems, with contractors absorbing surcharges to maintain project timelines. Three-tier pricing structure across premium, standard, and economy levels separates CSA/UL dual-certified built-in units from single-certified portable alternatives and uncertified imports. Price differentiation hinges on certification depth and geographic delivery cost, with Canadian cross-border logistics adding freight burden. Cost compression in mid-tier steel fabrication is intensifying because galvanized coil volatility forces gauge substitution. Renter-accessible portable segments exhibit highest price sensitivity; custom home builders demonstrate lowest.
Supply Chain Analysis
Returns and refurbishment flows remain underdeveloped for outdoor gas appliances, though subscription leasing models in Toronto and Vancouver are piloting seasonal reverse logistics. Manufacturing concentrates in the United States upper Midwest and Ohio River Valley, with DOT-certified cylinder production anchored in Ohio and Pennsylvania. Raw material dependencies center on galvanized steel coil, stainless steel sheet, and cast iron foundry capacity. Single-source vulnerability clusters around Ohio-Pennsylvania cylinder fabrication during peak seasonal demand. Distribution runs through big-box retail networks, direct-to-consumer fulfillment centers, and contractor specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Journeyman welder scarcity across the upper Midwest is capping production scaling for custom hardscape-integrated units, propping pricing power for certified manufacturers with captive fabrication capacity.
For Market Incumbents: Deploy smart home integration partnerships to differentiate premium SKUs against wood pellet substitution threats in Pacific Northwest markets. Deepen backward integration into burner assembly production to insulate margins from steel input volatility. Prioritize CSA/UL certification pipeline investment to compress third-party testing backlogs and accelerate product launch windows. For New Entrants and Emerging Players: Begin with underpenetrated Canadian Prairie provinces where installed-base density lags climate suitability for outdoor heating. Target Manitoba and Saskatchewan through distributor partnerships with agricultural supply cooperatives. Pursue direct-to-consumer social commerce positioning to bypass established big-box retail gatekeeping. For Investors and Strategic Acquirers: The window for entry favors smokeless combustion technology specialists with proprietary secondary burn engineering. Long-term viability rests on EPA regional haze regulatory trajectory and wildland-urban interface code expansion. Monitor California Air Resources Board stationary source rulemaking as inflection indicator for low-NOx burner mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CSA/UL Dual Certification Investment | Accelerates cross-border product launches between United States and Canadian markets. |
| Smart Home Integration Partnership | Captures millennial first-time homeowners through Alexa and Google Home compatibility. |
| Backward Integration into Burner Assembly | Reduces dependency on third-party fabrication during peak seasonal demand surges. |
| Direct-to-Consumer Channel Expansion | Bypasses big-box retail markups through influencer partnerships and social commerce. |
| Modular Fire Pit System Development | Unifies contractor procurement patterns around single-vendor relationships in Texas and Georgia. |
Research Methodology
Document review covered CSA Group certification databases, EPA regional haze regulatory filings, and ANSI Z21.97 standard documentation, complemented by interviews with outdoor living product category managers, licensed gas contractors in Sun Belt states, vacation rental property operators, and steel fabrication procurement leads. Secondary validation drew from U.S. Census Bureau construction spending data, DOT cylinder transport regulations, and provincial wildfire risk management policies. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure projections.
Historical shipment patterns cross-referenced against industry panel input on inventory build rates and certification submission backlogs. Segmentation dimensions modeled include installation type, material grade, fuel infrastructure availability, and design aesthetic preference across the analysis window. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated welder labor market tightness indices and steel futures curve positioning.
Underlying measurement precision varies by segment; portable fire pit volume estimates carry tighter precision than custom built-in project pipelines. Forecasts reflect documented assumptions regarding shoulder season extension trends and municipal fire code harmonization. Practitioners should monitor California Air Resources Board rulemaking and Canadian Prairie distributor inventory builds for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
North America Awnings Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Middle-East Christmas Tree Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Wooden Decking Market