
 United States Outdoor Furniture Market | 2026-2036
United States Outdoor Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Outdoor Furniture Market Analytics
Digital design-to-manufacture workflows and automated CNC routing is reshaping how outdoor furniture producers prototype and scale custom collections. Brown Jordan Co. leverages its domestic manufacturing footprint to sustain rapid turnaround on made-to-order aluminum frames. Wayfair Inc. anchors the online channel through proprietary logistics networks that compress delivery windows for bulky items. Ethan Allen Interiors Inc. differentiates via vertical control over upholstery workshops that customize fabric treatments for UV resistance.
Outdoor furniture encompasses weather-engineered seating, tables, shade structures, and accessories built from moisture-resistant materials such as FSC-certified teak, powder-coated aluminum, and solution-dyed acrylic fabrics rated for colorfastness. These products serve residential patios, hotel pool decks, restaurant terraces, and municipal parks by extending usable exterior space across seasonal temperature swings. Wood and metal materials dominate value capture due to premium pricing on solid construction and heirloom positioning, while plastic segments compete on stackability and low-maintenance upkeep for commercial bulk procurement. The hospitality end-user channel represents the fastest-growing demand pool as hotel operators renovate exterior amenities to capture post-pandemic leisure travel spending.
EPA oversight of volatile organic compound emissions in finishes and California Air Resources Board standards on composite wood products constrain coating formulations and substrate sourcing across domestic supply chains. The Consumer Product Safety Commission monitors stability and entrapment risks in folding and reclining mechanisms, particularly for products targeting elderly users. ASTM International voluntary standards for sling and strap durability create de facto market access thresholds that retailers enforce through vendor qualification programs. Stakeholders must monitor evolving state-level extended producer responsibility proposals that could impose end-of-life collection obligations on manufacturers and reshape material selection economics.
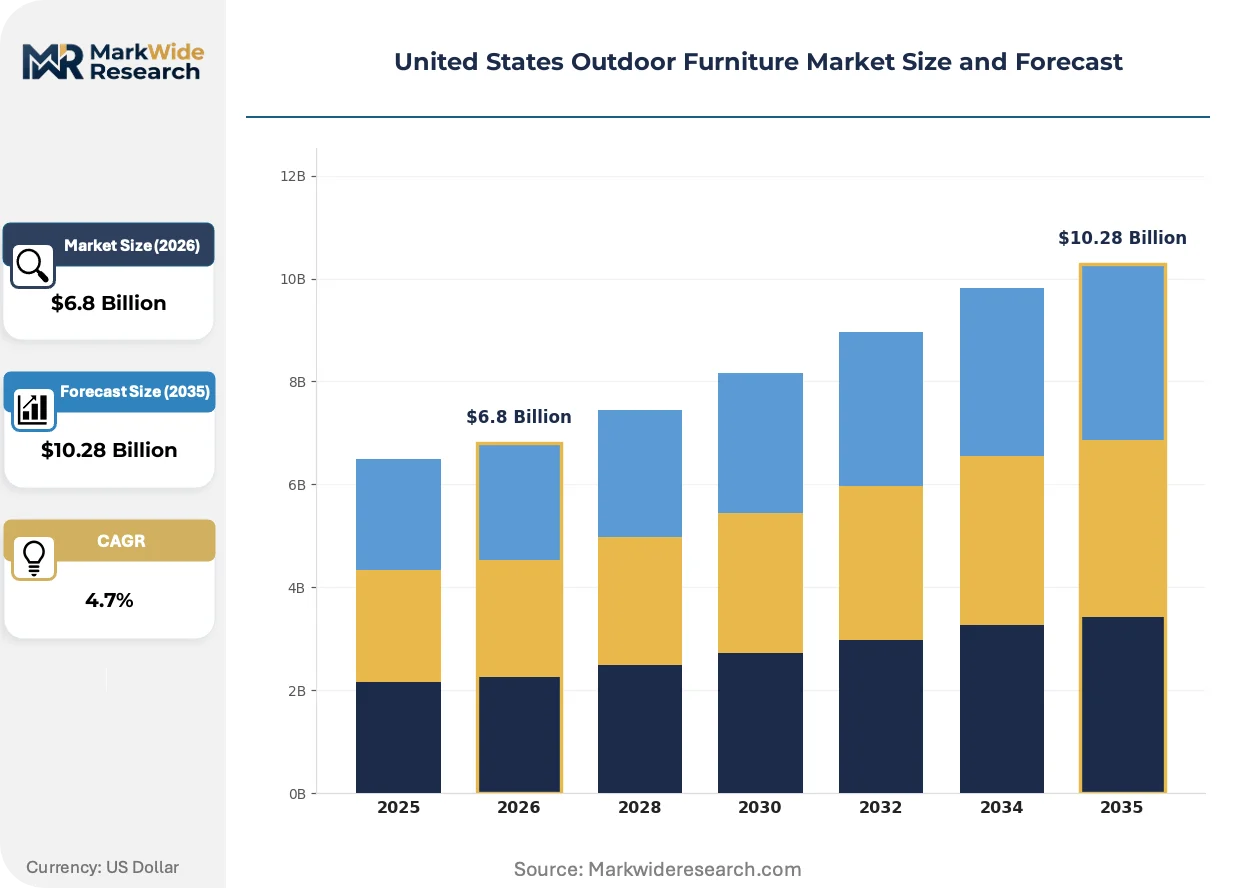
Market Dynamics
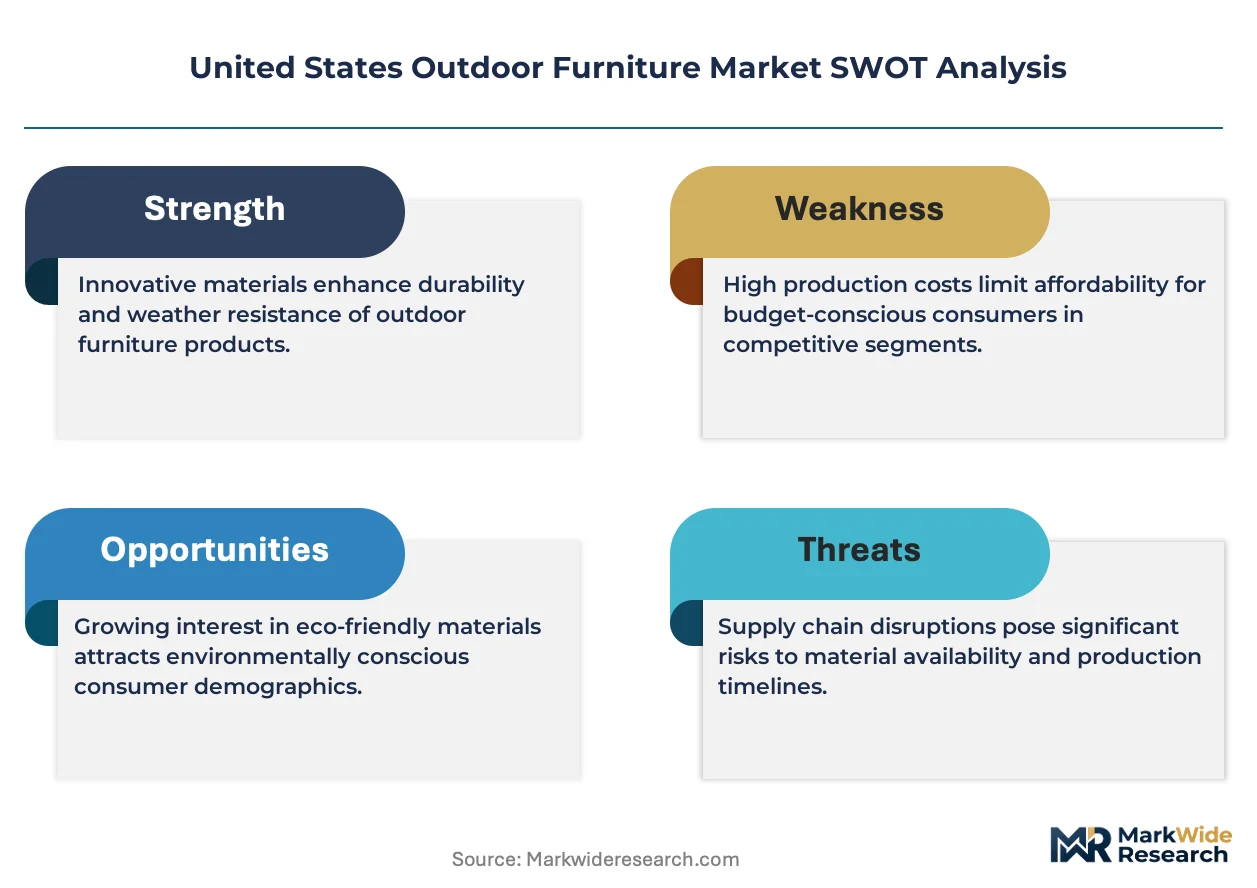
Residential backyard renovations are compressing replacement cycles for weather-resistant seating and dining sets across Sun Belt states, while EPA regulations on treated lumber and California's Proposition 65 chemical disclosure rules are forcing material substitutions toward certified sustainable alternatives.
Growth Catalysts
- Extended Outdoor Living Seasons:Florida, Texas, and Arizona households maintain year-round exterior space utilization, driving accelerated furniture refresh rates compared to northern climates.
- EPA Volatile Organic Compound Standards:Finish manufacturers reformulate water-based coatings to meet emissions thresholds, opening market share for low-VOC product lines.
- Hospitality Exterior Renovation Wave:Hotel operators prioritize pool deck and terrace amenity upgrades to capture post-pandemic leisure travel spending, expanding commercial procurement volumes.
Market Restraints
- Teak Supply Concentration:FSC-certified tropical hardwood sourcing clusters in Southeast Asian plantations, exposing manufacturers to shipping cost volatility and deforestation scrutiny.
- Powder-Coated Aluminum Input Costs:Energy-intensive smelting and pigment chemistry fluctuations compress margin structures for domestic frame producers.
- California Proposition 65 Compliance Burden:Chemical disclosure litigation exposure elevates insurance and labeling costs for products distributed nationally.
Strategic Opportunities
- Recycled Ocean Plastic Fabrication:Injection-molded poly lumber from recovered marine debris addresses sustainability premiums in coastal resort procurement.
- Direct-to-Consumer Logistics Innovation:White-glove delivery networks for bulky items bypass traditional retail markup structures in secondary metropolitan markets.
- Modular Shade Structure Integration:Pergola and canopy systems with integrated seating expand average transaction values in residential renovation projects.
Industry Challenges
- ASTM Sling Durability Certification Timelines:Extended laboratory testing protocols delay product launch windows for seasonal selling periods.
- Solution-Dyed Acrylic Upholstery Skill Shortage:Specialized sewing technicians for UV-resistant fabric construction command wage premiums that strain workshop capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Outdoor Furniture Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Loungers, Umbrellas Material: Wood, Metal, Plastic, Fabric End User: Residential, Commercial, Hospitality, Leisure Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Inter IKEA Holding BV, La-Z-Boy Inc., Ashley Furniture Industries, Inc., Wayfair Inc., The Home Depot Inc., Brown Jordan Co., Ethan Allen Interiors Inc., Lowes Co. Inc., Landscape Forms, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Outdoor Furniture Market Evolving Landscape
Digital design-to-manufacture workflows and automated CNC routing are compressing prototyping timelines for custom aluminum collections, while regulatory pressure on chemical disclosures accelerates material transparency investments across supply chains.
CNC routing automation is collapsing the gap between design file and finished frame production. Regional manufacturers serving Sun Belt markets now prototype made-to-order aluminum collections within 72-hour windows. This compression enables rapid SKU proliferation without inventory carrying costs, reshaping competitive positioning for mid-scale producers against import-dependent competitors.
California Air Resources Board standards on composite wood products are constraining substrate sourcing across domestic supply chains. Manufacturers reformulate medium-density fiberboard cores in tabletops to meet formaldehyde emission thresholds. The hospitality channel bears primary compliance burden, as hotel operators face liability exposure from interior-exterior furniture migration in mixed-use properties.
White-glove delivery unbundling is fragmenting traditional retail channel control. Direct-to-consumer platforms now capture bulky-item logistics through proprietary last-mile networks. Arizona and Florida metropolitan corridors exhibit highest adoption density, where seasonal population influxes sustain dedicated installation crew utilization rates.
United States Outdoor Furniture Market Segmentation
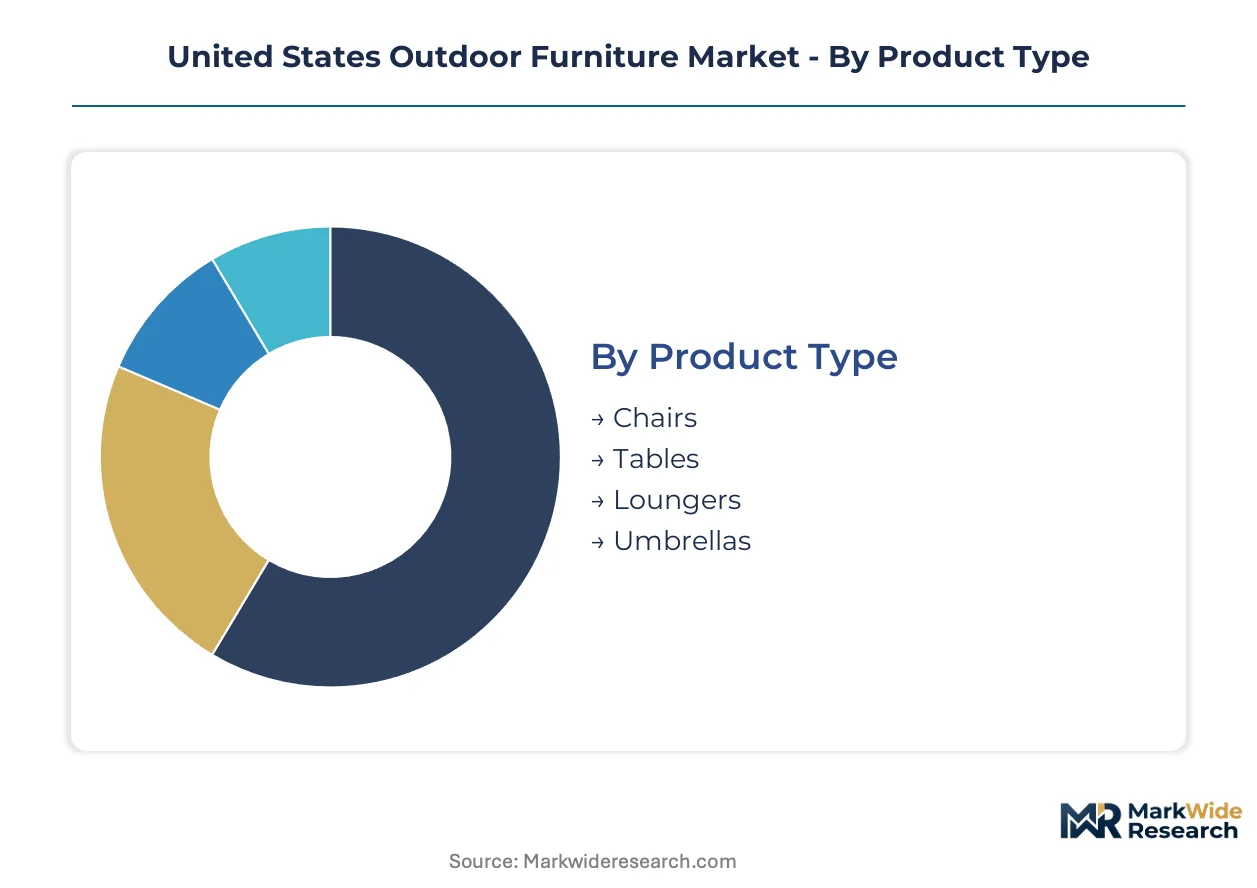
Outdoor furniture demand fragments across four distinct axes: physical form, substrate durability, buyer sophistication, and fulfillment speed. Each dimension carries different margin profiles and regulatory exposure, requiring manufacturers to calibrate production lines and inventory positions against specific segment economics.
Product Type:
Chairs anchor residential refresh cycles; tables command premium project spend; loungers and umbrellas capture hospitality amenity budgets.
- Chairs:Stackable resin and sling-back designs dominate volume for backyard entertaining sets. Sun Belt states drive replacement demand where UV degradation accelerates fabric fatigue on seating surfaces.
- Tables:Dining and chat-height surfaces utilize FSC-certified teak or powder-coated aluminum frames to meet California Air Resources Board formaldehyde thresholds in composite substrates.
- Loungers:Adjustable reclining mechanisms target poolside hospitality installations with ASTM stability certifications for elderly user safety.
- Umbrellas:Cantilever and market-style shade structures integrate solution-dyed acrylic canopies rated for colorfastness in extended sun exposure.
Established volume favors chairs; emerging adoption favors loungers.
Material:
Substrate selection determines warranty liability, shipping density, and end-of-life disposal obligations under evolving extended producer responsibility frameworks.
- Wood:FSC-certified tropical hardwoods command heirloom positioning and premium pricing in residential renovation projects. Southeast Asian plantation sourcing exposes manufacturers to shipping cost volatility and deforestation scrutiny from EPA compliance auditors.
- Metal:Powder-coated aluminum frames enable domestic CNC routing automation for rapid custom prototyping. Energy-intensive smelting and pigment chemistry fluctuations compress margin structures for domestic producers.
- Plastic:Injection-molded poly lumber from recycled ocean debris addresses sustainability premiums in coastal resort procurement channels.
- Fabric:Solution-dyed acrylic upholstery requires specialized sewing technicians for UV-resistant construction, creating wage premiums that strain workshop capacity.
Metal captures production efficiency gains; plastic gains share fastest on sustainability positioning.
End User:
Buyer sophistication spans DIY homeowners, facility managers, hotel operators, and municipal procurement officers with divergent specification requirements.
- Residential:Backyard renovation projects concentrate in Florida, Texas, and Arizona where extended outdoor living seasons compress replacement cycles for weather-resistant seating sets.
- Commercial:Restaurant terrace and corporate campus installations prioritize stackability and low-maintenance upkeep for bulk procurement efficiency.
- Hospitality:Hotel operators prioritize pool deck and terrace amenity upgrades to capture post-pandemic leisure travel spending, expanding commercial procurement volumes with the steepest expansion trajectory.
- Leisure:Municipal parks and campground installations face budget constraints that favor plastic segments with minimal upkeep requirements.
Residential maintains absolute volume; hospitality commands margin expansion.
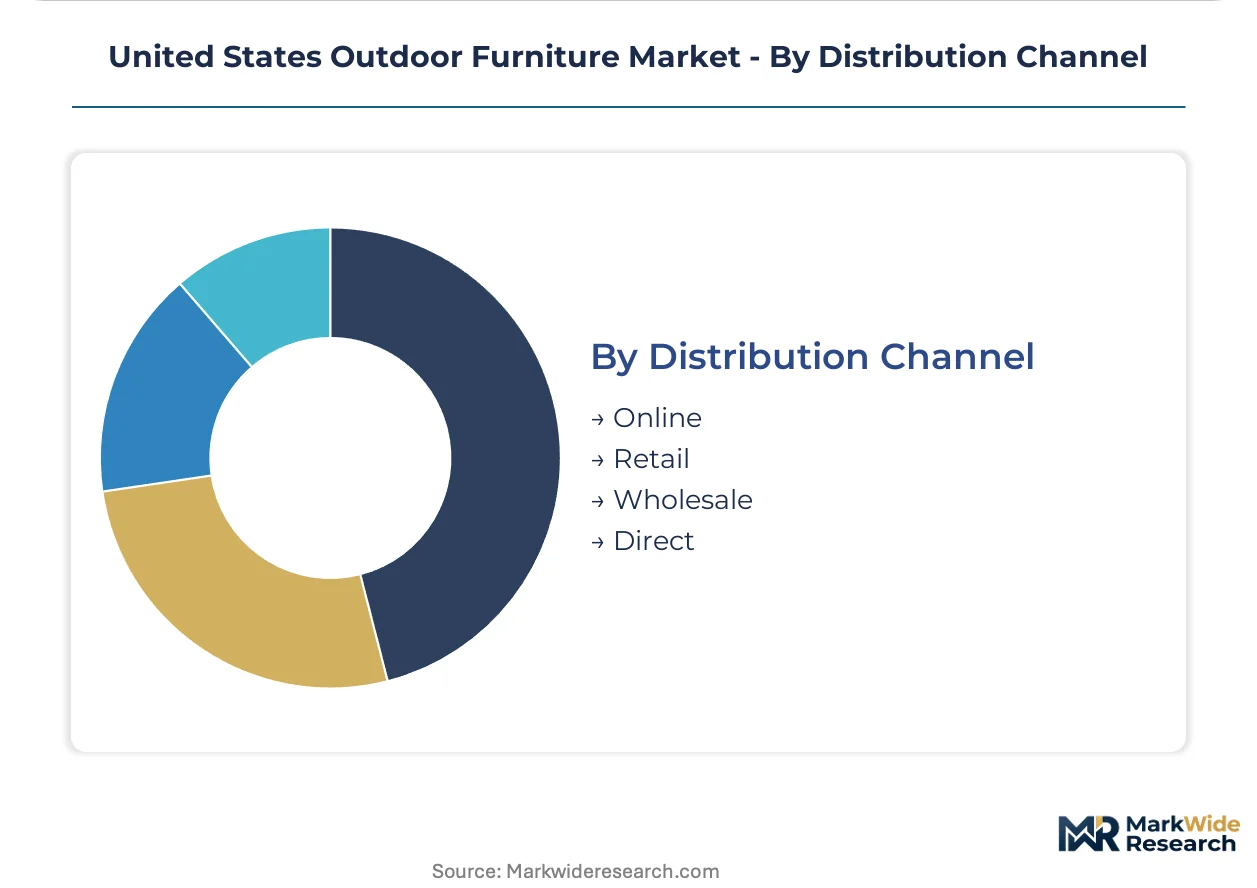
Distribution Channel:
Channel selection determines delivery speed, white-glove service attachment, and customer acquisition cost structures across metropolitan density gradients.
- Online:Proprietary logistics networks compress delivery windows for bulky items, with Arizona and Florida corridors exhibiting highest adoption density where seasonal population influxes sustain dedicated installation crew utilization.
- Retail:Big-box and specialty store footprints maintain tactile evaluation advantages for material quality assessment in suburban markets.
- Wholesale:Hospitality and commercial buyers leverage volume aggregation through furniture dealers with project specification expertise.
- Direct:Manufacturer-owned showrooms and design centers capture full margin on made-to-order collections with rapid turnaround capabilities.
Retail holds transaction frequency; direct gains on customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese and Indonesian manufacturers ship FSC-certified teak and powder-coated aluminum components to Sun Belt distributors serving Florida, Texas, and Arizona residential renovation contractors.
Florida
Year-round patio utilization drives replacement cycles for UV-resistant sling seating and cantilever umbrellas. EPA volatile organic compound standards on finishes elevate compliance costs for distributors sourcing from Southeast Asian suppliers. Miami-Dade and Tampa Bay metropolitan corridors concentrate white-glove installation networks serving seasonal snowbird populations.
Texas
Extended outdoor entertaining seasons sustain demand for modular dining sets and fire pit surrounds across Dallas-Fort Worth and Houston suburbs. California Air Resources Board formaldehyde thresholds on composite substrates constrain tabletop sourcing for manufacturers distributing nationally. Austin and San Antonio retail clusters anchor direct-to-consumer showroom expansion for domestic aluminum fabricators.
Arizona
Intense solar exposure accelerates fabric degradation on residential loungers and poolside seating, compressing refresh intervals. Proposition 65 chemical disclosure litigation exposure elevates insurance premiums for products sold through California-compliant distribution channels. Phoenix and Scottsdale metropolitan areas sustain dedicated last-mile installation crews through seasonal population influxes.
California
Stringent state-level regulations on treated lumber and composite wood emissions reshape material specifications for products entering the national supply chain. Los Angeles and San Diego design studios drive specification-grade hospitality procurement for coastal resort renovations. Bay Area municipalities pilot extended producer responsibility frameworks that could impose end-of-life collection obligations on manufacturers.
United States Outdoor Furniture Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market retailers with proprietary logistics networks and specialized manufacturers with domestic fabrication capabilities. Consolidation pressure concentrates among online platforms and big-box distributors, while fragmentation persists among regional metalworkers and upholstery workshops. Two strategic archetypes dominate: vertically integrated domestic producers controlling CNC routing and finishing operations, and asset-light digital platforms aggregating third-party inventory. Competitive moves center on last-mile delivery network expansion and rapid-turnaround customization capabilities.
Among specialty manufacturers with domestic fabrication footprints, Brown Jordan Co. and Ethan Allen Interiors Inc. exemplify vertical integration archetypes, while Wayfair Inc. occupies a position representing platform-based distribution scale. These three entities anchor distinct competitive vectors within the market structure.
| Leading Market Players |
|---|
| Inter IKEA Holding BV |
| La-Z-Boy Inc. |
| Ashley Furniture Industries, Inc. |
| Wayfair Inc. |
| The Home Depot Inc. |
| Brown Jordan Co. |
| Ethan Allen Interiors Inc. |
| Lowes Co. Inc. |
| Landscape Forms, Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic CNC routing facilities is pushing manufacturers toward premium pricing on rapid-turnaround aluminum collections while compressing margins on standard imported stock. Sun Belt distributors absorb higher per-unit costs to secure Florida and Arizona delivery slots during seasonal peak windows.
Pricing Analysis
The generation gap between legacy hand-finished teak heirloom collections and next-gen automated aluminum fabrication is widening price spreads across the residential channel. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified solid hardwood from powder-coated domestic frames and imported resin stackables. Cost compression in the metal tier is intensifying because energy-intensive smelting and pigment chemistry fluctuations squeeze domestic producers. Commercial facility managers exhibit highest price sensitivity due to bulk procurement volumes, while hospitality operators prioritize specification-grade durability over unit cost.
Supply Chain Analysis
Extended payment terms from Vietnamese and Indonesian plantation operators are restructuring working capital requirements for FSC-certified teak importers. Geographic concentration in Southeast Asian hardwood sourcing and Chinese aluminum smelting exposes manufacturers to shipping cost volatility and tariff exposure from trade policy shifts. Raw material dependencies center on tropical hardwood logs, aluminum billet, and solution-dyed acrylic fiber. Distribution runs through proprietary last-mile networks in Arizona and Florida corridors alongside traditional big-box retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States outdoor furniture market sits as a high-growth disruption driven by EPA volatile organic compound standards that are forcing finish reformulation and material substitution across domestic supply chains.
For Market Incumbents: Build certification moats around FSC chain-of-custody documentation and ASTM sling durability testing protocols to defend against low-cost resin importers. Expand captive CNC routing capacity in Texas and Florida to compress made-to-order turnaround below 72-hour windows. Deepen backward integration into powder-coating operations to offset pigment chemistry cost volatility. For New Entrants and Emerging Players: Pursue white-space opportunities in recycled ocean plastic fabrication for coastal resort procurement channels. Target secondary Sun Belt metropolitan markets where white-glove installation crew utilization rates sustain proprietary logistics economics. Enter through direct-to-consumer digital platforms with rapid-SKU customization capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because EPA and California Air Resources Board standards are permanently elevating compliance costs for non-certified competitors. Acquisition targets should cluster around domestic aluminum fabricators with automated routing capabilities and hospitality-focused upholstery workshops. Monitor ASTM certification backlog timelines as an inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic CNC Routing Expansion | Automated fabrication in Texas and Florida compresses prototyping windows below 72 hours. |
| FSC Certification Investment | Chain-of-custody documentation defends premium positioning against deforestation scrutiny. |
| Recycled Ocean Plastic Product Line | Injection-molded poly lumber addresses sustainability premiums in coastal resort procurement. |
| Proprietary Last-Mile Network Buildout | White-glove installation crews in Arizona and Florida corridors bypass retail markup structures. |
| Water-Based Coating Reformulation | Low-VOC finish lines capture share under EPA volatile organic compound standards. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with outdoor furniture manufacturing executives, hospitality procurement directors, residential renovation contractors, and EPA compliance officers; and secondary validation through customs import records, SEC 10-K filings, ASTM International standards documentation, and California Air Resources Board regulatory filings. Bottom-up segment sizing triangulated against top-down market value estimates derived from distributor revenue aggregations.
Forecast inputs span product type segmentation across chairs, tables, loungers, and shade structures; material tier differentiation between FSC-certified wood, powder-coated aluminum, recycled plastic, and solution-dyed acrylic; end-user channel splits across residential, commercial, hospitality, and leisure; and distribution mode variation between online platforms, retail footprints, wholesale dealers, and direct manufacturer showrooms. CAGRs were derived from regression analysis against historical replacement cycle data and seasonal demand patterns. Industry-specific inputs include Sun Belt population migration trends and hospitality renovation capex cycles.
Macroeconomic conditions sit as an overlay; deviation in residential construction permits, leisure travel spending, and ocean freight rates would shift the trajectory. Forecasts reflect documented assumptions around EPA enforcement intensity and extended producer responsibility adoption timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Wooden Decking Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Camping Furniture Market