
 Cajun Seasoning Market | 2026-2036
Cajun Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
Cajun Seasoning Market Analysis
FSMA traceability mandates are broadening the cost-of-entry calculus for artisanal seasoning producers seeking retail shelf placement. McCormick & Company sustains dominant retail distribution through its scale-advantaged sourcing infrastructure across pepper-growing regions. Slap Ya Mama leverages its Lake Charles heritage to anchor authentic Louisiana positioning in specialty channels. Conagra Brands competes through mass-market velocity, extending its seasoning portfolio into value-tier retail sets.
Cajun seasoning comprises a proprietary blend of paprika, cayenne pepper, garlic powder, onion powder, black pepper, and dried herbs, formulated to deliver characteristic heat, smoke, and aromatic complexity in single-application cooking. The blend serves commercial kitchens and home cooks seeking consistent flavor replication without ingredient procurement complexity. Powder and blend formats dominate volume, though rubs command higher per-unit margins in premium barbecue and blackened-protein applications. Sachet packaging leads food-service adoption, while bottles sustain household replenishment cycles in supermarket channels.
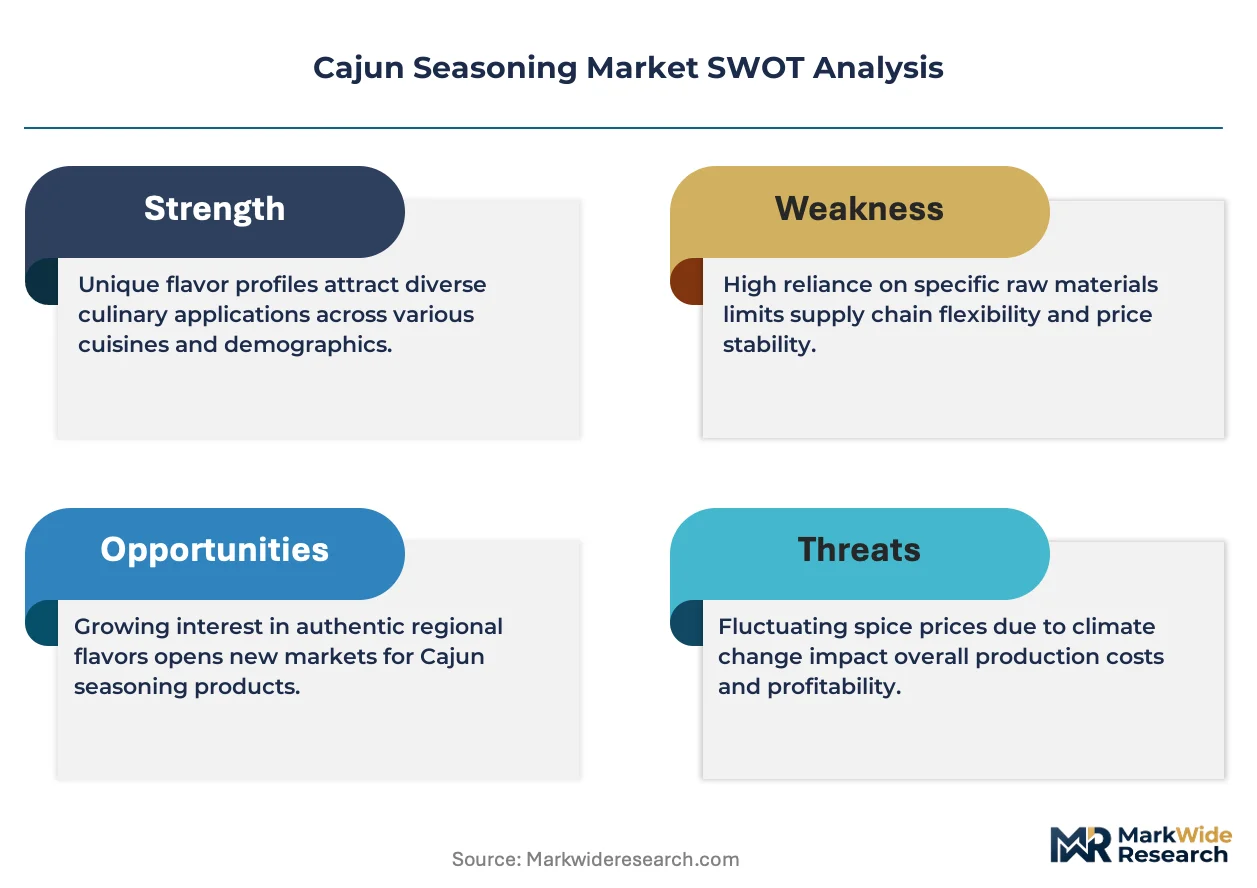
FDA food safety protocols and USDA organic certification requirements shape ingredient sourcing transparency and label claim substantiation for domestic manufacturers. State-level cottage food laws in Louisiana and Texas create fragmented compliance pathways for small-batch producers selling direct-to-consumer. Stakeholders must monitor evolving clean-label expectations and allergen declaration stringency as these forces reshape formulation flexibility and supplier qualification protocols.
Market Dynamics
The Cajun seasoning market is being fundamentally reshaped by the FDA's Food Safety Modernization Act traceability mandates, which are compressing the competitive set by raising compliance burdens for small-batch producers while advantaging scaled manufacturers with integrated supply-chain visibility systems.
Growth Catalysts
- Quick-service restaurant expansion:Chains across the southern United States are accelerating menu development around authentic Cajun profiles, creating sustained pull for standardized seasoning formats in food-service quantities.
- Heritage brand premiumization:Louisiana-origin labels leverage provenance narratives to command shelf-price premiums in specialty retail channels, reinforcing regional identity as a defensible positioning anchor.
- Clean-label formulation innovation:Consumer scrutiny of ingredient panels is driving reformulation toward single-source paprika and certified organic cayenne, opening new certification-driven market tiers.
Market Restraints
- Input cost volatility:Cayenne pepper and smoked paprika prices fluctuate with harvest yields in Mexico and Spain, compressing blender margins during supply-constrained cycles.
- Supply concentration risk:Premium paprika production clusters in specific Hungarian and Spanish regions, creating geographic vulnerability to climate-driven crop failures.
- Regulatory friction:State-level cottage food laws in Louisiana and Texas create fragmented compliance pathways that complicate multi-state distribution for artisanal producers.
Strategic Opportunities
- E-commerce direct-to-consumer channels:Digital-native subscription models enable small-batch producers to bypass retail slotting fees and build recurring revenue with heritage storytelling.
- Barbecue and blackened-protein rub applications:Higher-margin dry rub formats targeting outdoor cooking enthusiasts represent underexploited white space beyond traditional all-purpose blends.
- USDA organic certification tailwinds:Federal procurement preferences and retailer shelf-reset policies are expanding distribution access for certified-organic seasoning lines.
Industry Challenges
- Allergen declaration complexity:FDA stringency around spice-adulterant detection and sesame allergen labeling is extending formulation testing timelines and supplier qualification protocols.
- Legacy equipment integration:Smaller blenders face capital intensity when retrofitting batch-tracking systems to meet FSMA electronic record-keeping requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cajun Seasoning Market |
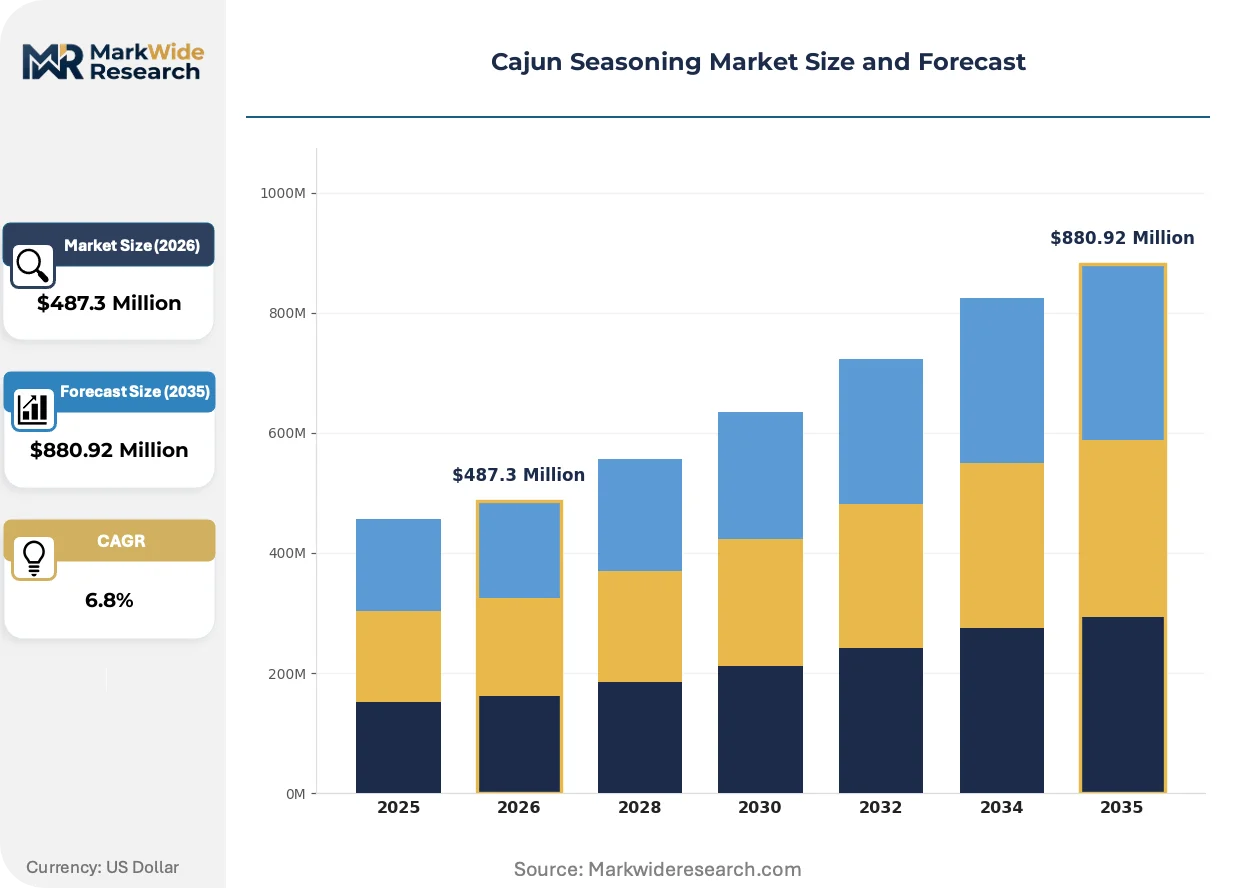
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blends, Rubs, Marinades, Powders Packaging Type: Bottles, Sachets, Tubs, Cans End User: Restaurants, Households, Food Manufacturers, Food Service Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Conagra Brands, Slap Ya Mama, McCormick & Company, Inc., Olam Group Limited, Ball's Cajun Foods, Inc., The Kraft Heinz Company, Louisiana Fish Fry, Rose Hill Foods Inc., Fiesta Spices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cajun Seasoning Market Emerging Trajectories
Active innovation across the Cajun seasoning landscape centers on traceability infrastructure, clean-label reformulation, and channel diversification, with technology investments now separating scalable competitors from artisanal operators facing compliance compression.
Blockchain-enabled lot-tracking systems are rewriting supply-chain accountability for premium seasoning brands. Mid-sized blenders in Louisiana and Texas are piloting distributed ledger verification for paprika and cayenne provenance. This transparency architecture is compressing the trust advantage previously held by heritage labels with established reputations.
The FDA's updated Food Safety Modernization Act traceability rules are mandating electronic record-keeping for spice blenders above defined volume thresholds. Compliance deadlines are forcing capital allocation toward batch-tracking software and supplier audit infrastructure. Smaller Louisiana producers are responding through cooperative purchasing of third-party verification services to spread fixed compliance costs.
Direct-to-consumer subscription models are displacing traditional supermarket replenishment cycles among digitally engaged home cooks. Heritage-focused brands are building recurring revenue through curated quarterly shipments featuring limited-batch regional variations. This channel pivot is most visible in Gulf Coast metropolitan areas where culinary identity drives sustained engagement with Louisiana-origin products.
Cajun Seasoning Market Segmentation
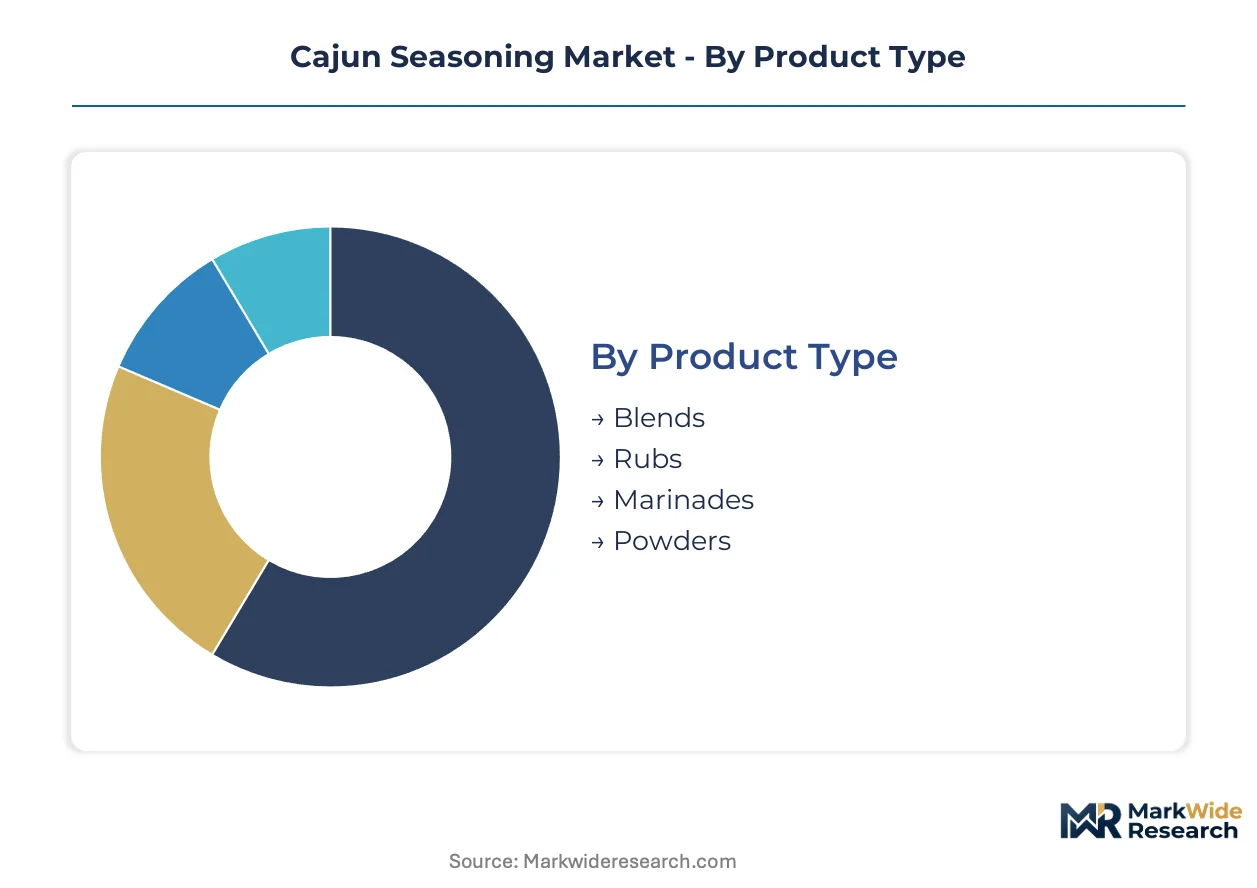
Cajun seasoning segmentation reveals distinct demand profiles across preparation formats, with commercial kitchens favoring bulk sachets while households gravitate toward replenishment-friendly bottles. Understanding these structural divides enables targeted portfolio allocation between food-service velocity and retail margin capture.
Product Type:
Standalone application formats dominate home cooking, while embedded systems serve protein processors seeking consistent flavor integration.
- Blends:All-purpose mixtures combining paprika, cayenne, garlic, and onion powders in standardized ratios for immediate deployment across proteins and vegetables. Louisiana quick-service restaurants specify blend formats for menu consistency across franchise locations. Blends lead volumes today; rubs are gaining share fastest.
- Rubs:Coarse-ground formulations with higher salt and sugar content engineered for crust formation during high-heat cooking. Outdoor cooking enthusiasts in Texas and Gulf Coast states drive premium pricing for blackened-fish and smoked-meat applications. Rubs command per-unit margins significantly above standard blends due to specialized application positioning.
- Marinades:Liquid-infused seasoning systems combining Cajun spice profiles with oil or vinegar carriers for protein penetration. Commercial kitchens value marinade formats for labor reduction in high-volume protein preparation.
- Powders:Fine-milled single-note or multi-spice preparations offering maximum surface adhesion and rapid flavor release. Powder formats serve industrial food manufacturers integrating Cajun profiles into snack coatings and processed proteins.
Blends anchor current revenue; rubs demonstrate the steepest expansion trajectory among preparation formats.
Packaging Type:
Cost tier stratification separates premium presentation formats from high-velocity commercial dispensing systems.
- Bottles:Glass or PET containers with shaker tops supporting controlled dispensing and pantry visibility. Household replenishment cycles in southern US states sustain supermarket velocity for 6-16 ounce bottle formats. Bottles dominate household channels; sachets expand most quickly in food-service penetration.
- Sachets:Single-serve foil or paper packets delivering pre-measured portions for commercial kitchen consistency. Quick-service restaurants specify sachet formats to eliminate measuring variance and reduce cross-contamination risk during peak service periods.
- Tubs:Wide-mouth plastic containers facilitating scoop access for high-frequency commercial use. Institutional food-service operators prefer tub formats for back-of-house efficiency in volume seasoning applications.
- Cans:Metal containers with resealable lids preserving aroma integrity for premium spice storage. Specialty retail channels favor can packaging for heritage brand differentiation and extended shelf-life claims.
Bottles generate the highest absolute volumes; sachets are climbing the fastest as restaurant chains standardize portion control.
End User:
Customer type determines specification complexity, with commercial accounts demanding lot traceability and home cooks prioritizing flavor accessibility.
- Restaurants:Full-service and limited-service operators requiring FSMA-compliant documentation and consistent heat-level specifications across delivery batches. Louisiana-origin independent restaurants specify heritage blends for menu authenticity signaling.
- Households:Home cooks seeking convenient flavor replication without ingredient procurement complexity. Digital-native consumers in Gulf Coast metropolitan areas demonstrate sustained engagement with subscription-based seasoning replenishment.
- Food Manufacturers:Industrial processors integrating Cajun profiles into coated snacks, frozen proteins, and shelf-stable prepared meals. These accounts demand certified-organic and clean-label ingredient sourcing with full supply-chain documentation.
- Food Service:Institutional operators including schools, hospitals, and corporate dining facilities prioritizing cost efficiency and allergen-controlled formulations. Food-service distributors specify bulk formats with extended shelf-life guarantees.
Restaurants consume the largest share by volume; food manufacturers are expanding most rapidly as processed food innovation accelerates.
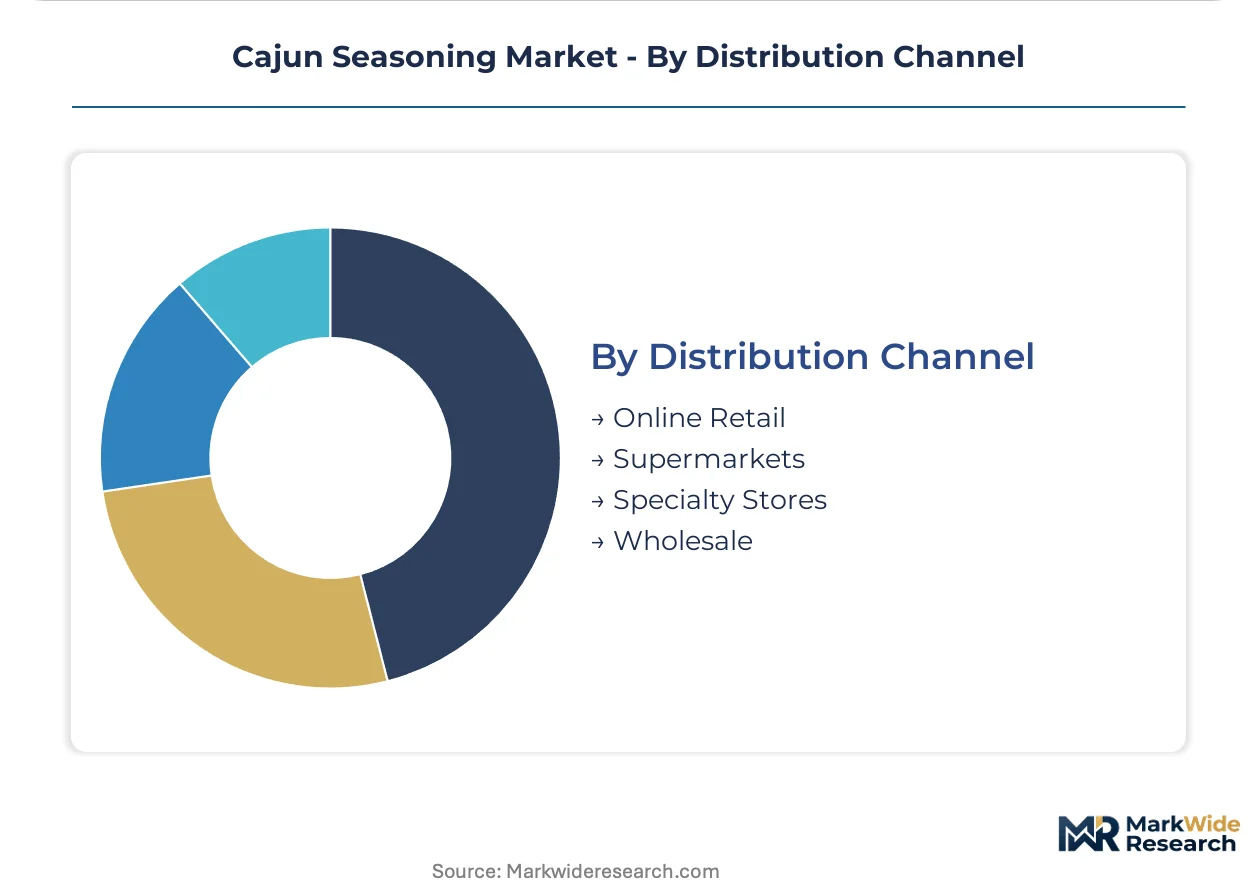
Distribution Channel:
Channel selection reflects customer procurement patterns, with digital platforms eroding traditional supermarket replenishment among engaged home cooks.
- Online Retail:Direct-to-consumer and marketplace platforms enabling heritage storytelling and subscription revenue models. E-commerce channels bypass slotting fee barriers that constrain artisanal producer access to physical retail.
- Supermarkets:Mass-market and regional grocery chains sustaining household replenishment through prominent shelf placement and promotional velocity. McCormick and Conagra dominate shelf-space allocation in this channel.
- Specialty Stores:Gourmet food retailers and Louisiana-focused heritage shops commanding premium pricing for provenance-authenticated products. Slap Ya Mama and regional craft blenders anchor positioning in specialty retail.
- Wholesale:Food-service distributors and restaurant supply warehouses handling bulk-format logistics for commercial kitchen procurement. Sysco and US Foods specifications drive standardization requirements in this channel.
Supermarkets retain volume leadership; online retail is gaining share fastest as direct-to-consumer models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cajun seasoning production clusters around heritage spice-blending workforces in Louisiana and adjacent Gulf Coast states, with diaspora communities in Texas and Mississippi sustaining craft-scale operations. Regional demand concentrates where Creole and Cajun culinary traditions anchor consumer identity.
United States
Quick-service restaurant chains across the southern United States specify Cajun profiles for menu differentiation, pulling industrial-scale blend volumes. The FDA's Food Safety Modernization Act mandates electronic traceability records for spice blenders above volume thresholds. Lake Charles anchors heritage production, where multi-generational blending families supply both retail and food-service channels.
Canada
Canadian food manufacturers integrate Cajun profiles into processed protein and snack coating applications for export markets. Health Canada maintains allergen labeling stringency that shapes import documentation requirements for US-origin seasonings. Toronto and Vancouver metropolitan areas concentrate specialty retail distribution for southern US heritage brands.
Mexico
Mexican pepper growers supply cayenne and paprika inputs to US-based Cajun blenders under seasonal procurement contracts. The country's national food safety regulator enforces pesticide residue limits that filter supplier eligibility for cross-border spice trade. Veracruz and Chihuahua cultivation zones experience price volatility that transmits directly to blender input costs.
United Kingdom
British supermarket chains stock Cajun seasoning as part of expanded world-food aisle assortments targeting home-cooking experimentation. The Food Standards Agency enforces strict allergen declaration protocols for imported spice blends. London and Manchester distribution hubs handle bulk import consolidation for retail and food-service redistribution.
Germany
German food processors source Cajun profiles for industrial meat and snack applications serving central European markets. EFSA guidelines on spice adulterant detection extend testing timelines for imported seasoning lots. Hamburg port facilities manage inbound spice flows from Mediterranean and Atlantic supply corridors.
Cajun Seasoning Market Vendor Landscape
The competitive structure tilts toward scaled manufacturers with integrated sourcing infrastructure and heritage-positioned regional specialists. Market concentration splits between mass-market velocity players and provenance-authenticated craft blenders. Two strategic archetypes dominate: vertically integrated spice conglomerates controlling pepper-growing regions, and Louisiana-origin family operations leveraging geographic identity. Competitive moves center on clean-label reformulation and direct-to-consumer channel bypass of retail slotting barriers.
Within the heritage-authentication tier, Slap Ya Mama and Ball's Cajun Foods occupy positions anchored by Lake Charles and Baton Rouge provenance narratives. McCormick & Company, Inc. represents the scale-driven archetype with distribution infrastructure spanning retail and food-service channels. Conagra Brands exemplifies mass-market velocity positioning through value-tier retail placement and processed food integration.
| Leading Market Players |
|---|
| Conagra Brands |
| Slap Ya Mama |
| McCormick & Company, Inc. |
| Olam Group Limited |
| Ball's Cajun Foods, Inc. |
| The Kraft Heinz Company |
| Louisiana Fish Fry |
| Rose Hill Foods Inc. |
| Fiesta Spices |
| Others |
Supply Flow & Price Mechanics
Cayenne pepper and smoked paprika harvest volatility in Mexico and Spain transmits directly through blender cost structures to retail shelf pricing, with premium Hungarian paprika shortages compressing margins for heritage-positioned Louisiana brands while mass-market competitors absorb shocks through volume-contract hedging.
Pricing Analysis
Unbundled ingredient sourcing separates premium heritage brands from economy-tier private labels, with certified-organic cayenne and single-origin paprika commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on USDA organic certification and Lake Charles provenance authentication for top tiers, while value-tier players compete on per-ounce efficiency. Pricing pressure stems from FDA traceability compliance costs disproportionately burdening small-batch producers. Quick-service restaurant procurement teams exhibit highest price sensitivity due to standardized menu cost targets, whereas specialty retail consumers absorb premiums for heritage storytelling.
Supply Chain Analysis
Freight cost inflation across Gulf Coast port corridors and overland routes from Veracruz growing regions is reshaping procurement geography for US-based blenders. Raw material dependencies center on Mexican cayenne, Spanish smoked paprika, and Hungarian sweet paprika for color consistency. Supply chain risk concentrates in climate-driven crop failures across concentrated Mediterranean and Atlantic growing zones. Distribution runs through Sysco and US Foods food-service networks for commercial accounts, with direct-to-consumer subscription models bypassing traditional retail slotting infrastructure for heritage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Food Safety Modernization Act traceability mandates are accelerating consolidation economics and advantaging scaled compliance infrastructure over artisanal craft operations.
For Market Incumbents: Hedge against input cost volatility through backward integration into pepper-growing regions or long-term offtake agreements with Veracruz and Chihuahua cultivation zones. Defend shelf position by accelerating clean-label reformulation ahead of evolving allergen declaration stringency, locking in supplier audit infrastructure that smaller competitors cannot replicate.
For New Entrants and Emerging Players: Capture white space in USDA organic-certified rub formats targeting Texas and Gulf Coast outdoor cooking enthusiasts, where premium positioning escapes direct price competition with mass-market blends. Exploit direct-to-consumer subscription models in metropolitan diaspora communities to bypass retail slotting fee barriers and build recurring revenue through heritage storytelling.
For Investors and Strategic Acquirers: Consolidation pressure builds where FSMA compliance costs exceed five percent of revenue for sub-scale Louisiana blenders lacking electronic batch-tracking systems. Target acquisition archetypes are heritage-authenticated regional brands with established provenance narratives and underutilized production capacity. The signal to watch is cooperative purchasing arrangements among artisanal producers, indicating distress-driven aggregation before formal M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pepper Growing | Captive supply of Mexican cayenne insulates blenders from Veracruz harvest volatility and trade friction. |
| USDA Organic Certification Investment | Federal procurement preferences and retailer shelf-reset policies expand distribution access for certified lines. |
| Direct-to-Consumer Channel Launch | Digital-native subscription models bypass supermarket slotting fees and build recurring revenue with heritage storytelling. |
| Blockchain Traceability Implementation | Distributed ledger verification for paprika and cayenne provenance compresses trust advantages of established heritage labels. |
| Cooperative Compliance Purchasing | Shared third-party verification services spread fixed FSMA costs among small-batch Louisiana producers facing capital constraints. |
Methodological Framework
Multiple input streams — structured interviews with spice procurement directors at quick-service restaurant chains, regulatory affairs specialists at FDA-registered blenders, and category buyers at food-service distributors — were reconciled against secondary validation from FDA FSMA guidance documents, USDA organic certification databases, and customs import records for paprika and cayenne shipments. Bottom-up volume estimates from individual blender production capacities were triangulated against top-down market sizing from retail audit data and food-service distribution volumes.
Data-stream reconciliation across product format segmentation, end-user channel splits, and regional demand clusters shaped the analytical framework over the projection horizon. Modeled dimensions include preparation format, packaging type, end-user category, and distribution channel, with CAGRs derived from historical volume trajectories and regulatory-driven compliance cost absorption rates. Industry-specific forecast inputs incorporated FDA enforcement timeline assumptions and quick-service restaurant menu development pipelines.
Harvest yield volatility in Mexican and Spanish growing regions, regulatory enforcement intensity around electronic traceability mandates, and quick-service restaurant menu cycle timing are the dominant revision risks that could compress or extend projected growth trajectories. Stakeholders should weight assumptions against their own operating context and supplier concentration exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Herbs and Spices Market