
 Back Therapy Kits Market | 2026-2036
Back Therapy Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Back Therapy Kits Market Outlook
China's manufacturing corridor for medical-grade neoprene and memory foam components is reshaping cost structures across the Back Therapy Kits Market. Sanofi leverages its pharmaceutical distribution network to bundle topical analgesics with complementary therapy devices in European markets. Bayer anchors its position through consumer health retail channels that place back braces and heating pads alongside pain relief portfolios. Medtronic competes in the powered segment with electrical stimulation platforms that integrate with orthopedic recovery protocols.
Back therapy kits encompass wearable and portable devices engineered for musculoskeletal relief, typically incorporating thermal elements, compressive textiles, or electro-stimulation modules operating at specified voltage and temperature thresholds for safe tissue interaction. Their primary commercial purpose centers on non-invasive pain management and postural support across home and clinical environments. Heating pads and back braces represent the most mature product categories with established reimbursement pathways, while foam rollers command premium positioning in sports clinic channels where physiotherapists prescribe specific density grades for myofascial release protocols. Memory foam and gel materials dominate the high-margin tier due to pressure-mapping customization and thermoregulation properties that differentiate clinical-grade offerings from standard retail alternatives.
The FDA's Class II device framework for transcutaneous electrical nerve stimulation units mandates 510(k) clearance, constraining market entry for unvalidated electrotherapy newcomers. CE marking under the EU Medical Device Regulation imposes clinical evidence requirements on back braces claiming therapeutic efficacy, shifting competitive advantage toward manufacturers with documented biomechanical testing. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for household electrical heating appliances, creating a dual compliance burden for brands distributing thermal therapy kits across multiple jurisdictions. Stakeholders must monitor evolving reimbursement eligibility criteria as health technology assessment bodies in Germany and France recalibrate coverage for preventive versus curative back support interventions.
Market Dynamics
The Back Therapy Kits Market pivots on reimbursement policy calibration in statutory health insurance systems, where coverage determinations for electrotherapy and compressive devices directly shape manufacturer volume commitments and channel investment priorities.
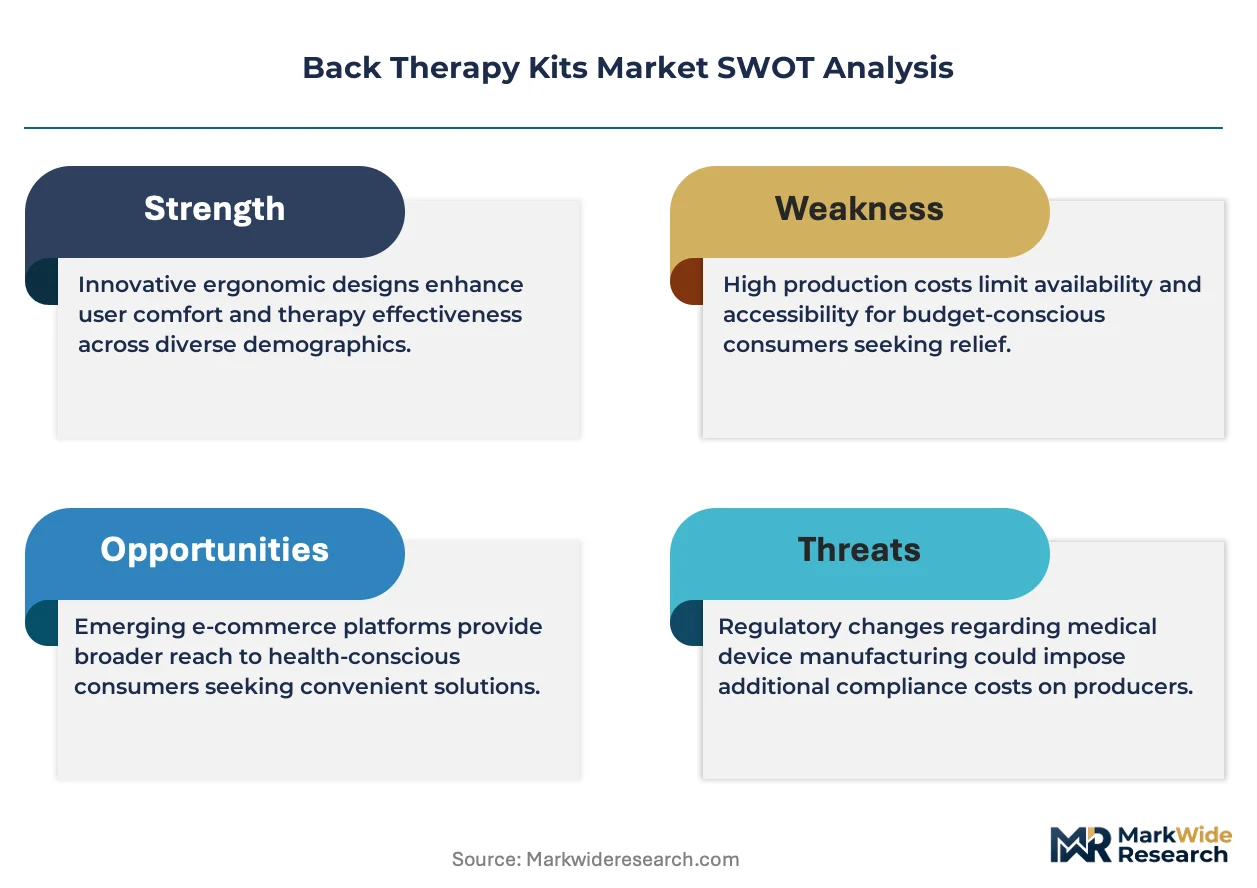
Growth Catalysts
- Statutory Reimbursement Mandates:Germany's statutory health insurance funds reimburse back braces and TENS units, creating predictable procurement volumes for manufacturers with CE-marked devices.
- Sports Medicine Integration:Physiotherapy clinics in Australia and the United Kingdom now prescribe density-calibrated foam rollers as standard myofascial release protocol, expanding clinical-grade demand.
- Memory Foam Process Innovation:Pressure-mapping customization capabilities in medical-grade neoprene production lines enable thermoregulation differentiation that commands premium positioning.
Market Restraints
- Input Cost Volatility:Medical-grade memory foam and gel formulations face petroleum-derived feedstock price swings that compress margin stability for mid-tier manufacturers.
- Supply Concentration Risk:China's manufacturing corridor dominates medical-grade neoprene output, creating single-source vulnerability for brands without secondary qualification programs.
- Regulatory Friction:FDA 510(k) clearance requirements for Class II powered muscle stimulators extend market entry timelines and elevate validation costs for electrotherapy entrants.
Strategic Opportunities
- Underpenetrated Preventive Segments:France's health technology assessment bodies are recalibrating coverage criteria toward preventive back support, opening reimbursement pathways previously restricted to curative interventions.
- Convergence of Thermal and Electrical Modalities:Hybrid devices combining TENS output with controlled thermal delivery address multi-mechanism pain management protocols favored by orthopedic recovery programs.
- Direct-to-Consumer Channel Expansion:Digital-native brands bypass traditional medical supply distributors by leveraging telehealth platform partnerships that bundle device prescription with remote physiotherapy consultation.
Industry Challenges
- Biomechanical Testing Capability Scarcity:Documented clinical evidence requirements under EU Medical Device Regulation strain manufacturers lacking in-house motion-capture laboratories or university research partnerships.
- Dual Compliance Burden:Brands distributing thermal therapy kits across Japan and the United States must simultaneously satisfy METI JIS standards for household electrical appliances and FDA thermal safety thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Therapy Kits Market |
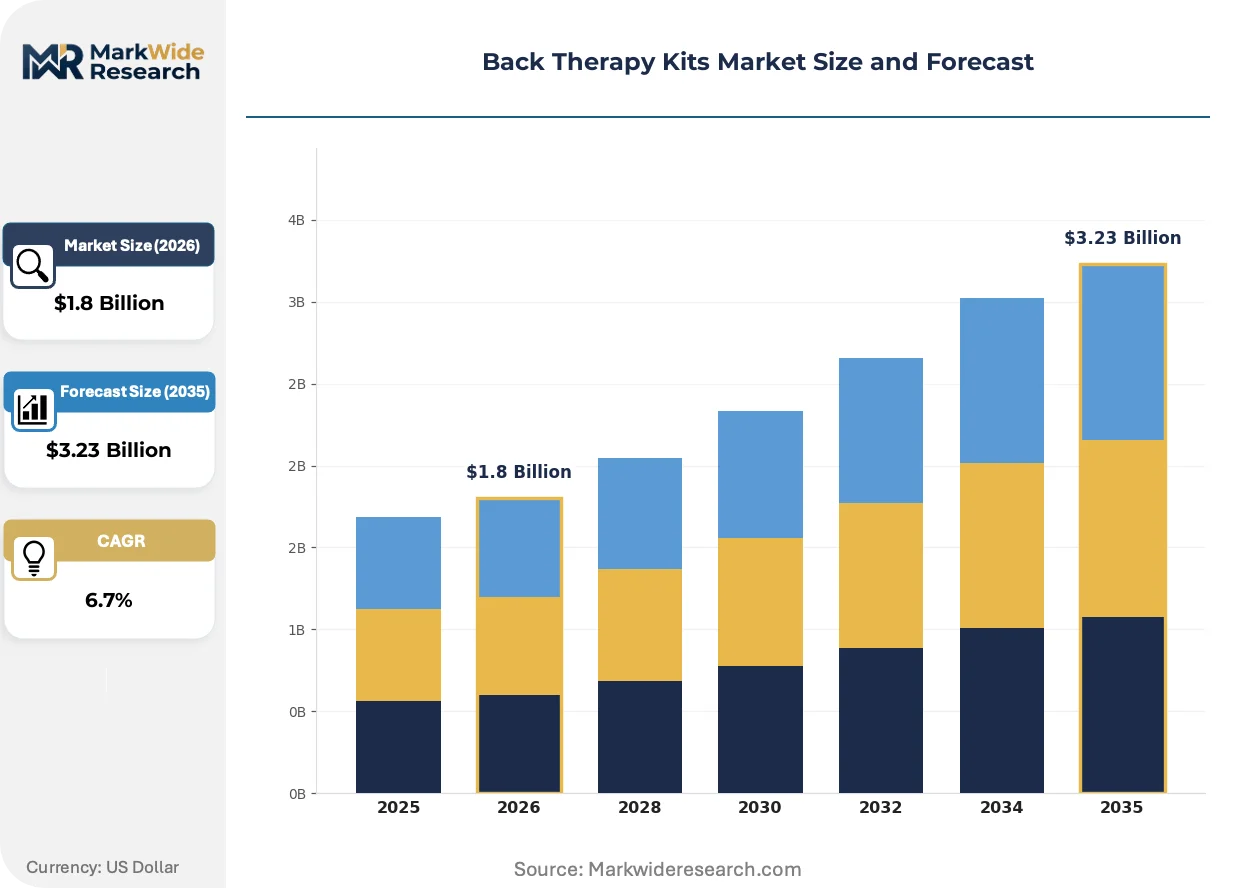
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pads, Medical Cushions, Foam Rollers, Back Braces End User: Home Users, Physiotherapists, Sports Clinics, Hospitals Application: Pain Relief, Posture Correction, Rehabilitation, Muscle Relaxation Material: Gel, Memory Foam, Cotton, Neoprene |
| Companies Covered | Sanofi, Bayer, Polar Products, DIH International, Tynor, Hocomo, Brooks Life Sciences, Alliance Spine, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Therapy Kits Market Strategic Shifts
Product architecture in back therapy kits is converging toward modular platforms that separate power and thermal cores from textile housings, enabling component upgrade paths and subscription-based consumable revenue models.
Smart textile integration with embedded pressure sensors and Bluetooth-enabled biofeedback loops is rendering obsolete passive back braces that lack real-time postural correction data. Sports rehabilitation centers in Germany and the Netherlands now specify sensor-equipped braces for athlete recovery protocols. The displacement of static compression garments compresses margin structures for manufacturers locked into purely mechanical product lines.
EU Medical Device Regulation clinical evidence requirements for therapeutic efficacy claims are restructuring competitive advantage toward manufacturers with documented biomechanical testing archives. CE marking timelines for back braces claiming postural correction have extended by nine to fourteen months since 2021. Smaller manufacturers without notified body relationships are exiting the European market or recategorizing products as wellness devices without therapeutic positioning.
Post-acute care facilities are consolidating vendor relationships through group purchasing organizations that demand outcome documentation and device utilization telemetry. Traditional durable medical equipment distributors lose share to integrated health system procurement offices that negotiate directly with manufacturers for standardized kit configurations. This concentration is most visible in the United States, where hospital-owned outpatient clinics now represent the fastest-growing channel for powered therapy systems.
Back Therapy Kits Market Segmentation
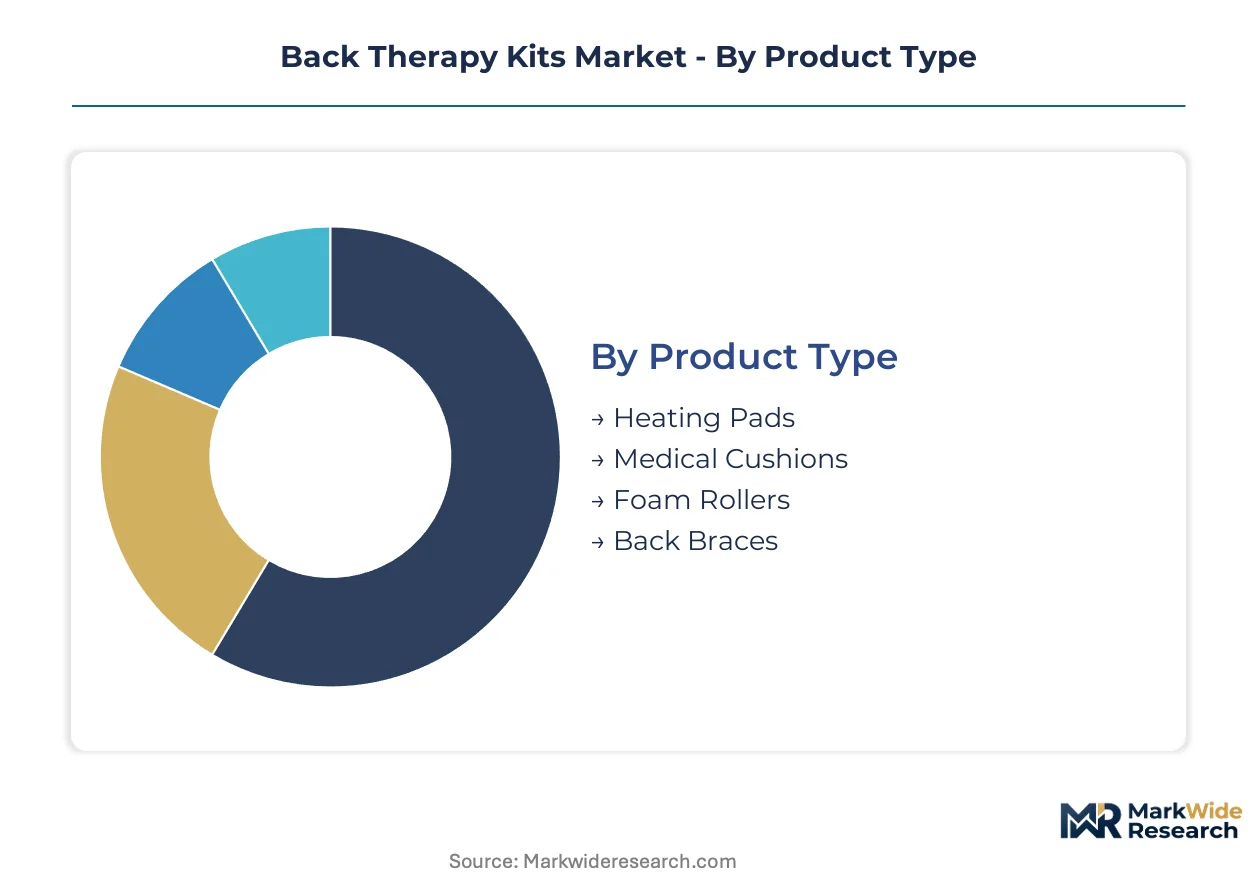
Back therapy kits fragment across multiple technical and commercial dimensions, with material composition and end-use channel determining reimbursement eligibility, margin structure, and regulatory pathway. Manufacturers configure product portfolios around these segment boundaries to optimize production scale against compliance investment.
Product Type:
After-sales service intensity varies sharply by product type, with powered electrotherapy units requiring calibration support and textile-based devices demanding minimal post-purchase intervention.
- Heating Pads:Electrical resistance elements embedded in moisture-resistant fabrics deliver controlled thermal therapy at specified wattage densities. Demand concentrates in German home care channels where statutory health insurance funds reimburse prescription-grade units for chronic pain management, though METI JIS standards in Japan create dual certification burdens for multi-territory brands.
- Back Braces:Rigid and semi-rigid orthotic structures incorporate adjustable compression systems and lumbar support panels. Sports clinics in Australia and the United Kingdom now specify sensor-equipped variants for athlete recovery protocols, displacing passive compression garments that lack real-time postural feedback.
- Medical Cushions:Pressure-distributing seating accessories engineered for coccyx and lumbar support in prolonged sitting applications. German physiotherapy practices prescribe density-calibrated models for workplace ergonomic interventions.
- Foam Rollers:Cylindrical myofascial release tools manufactured at specified density grades for targeted tissue manipulation. Clinical-grade demand is climbing fastest in sports rehabilitation centers.
Back braces hold the largest share; momentum sits with foam rollers.
End User:
Channel economics diverge by purchaser sophistication, with institutional procurement offices demanding outcome telemetry that home retail channels ignore.
- Home Users:Consumer-directed purchases through retail and e-commerce platforms prioritize convenience and price accessibility over clinical validation. Direct-to-consumer brands leverage telehealth partnerships to bundle device prescription with remote consultation.
- Sports Clinics:Performance-focused rehabilitation facilities specify density-calibrated foam rollers and sensor-equipped braces for athlete protocols. Group purchasing organizations in the United States consolidate vendor relationships through outcome documentation requirements.
- Physiotherapists:Independent practitioners and clinic networks prescribe back braces and TENS units where reimbursement pathways exist, particularly in Germany's statutory health insurance system.
- Hospitals:Acute and post-acute care facilities procure integrated therapy systems through centralized procurement offices, bypassing traditional durable medical equipment distributors.
Home users dominate volume; sports clinics are expanding procurement most quickly.
Application:
Functional positioning determines regulatory classification and reimbursement eligibility, with curative claims facing stricter evidence requirements than wellness positioning.
- Pain Relief:Thermal and electro-stimulation modalities targeting nociceptive and neuropathic pain pathways. FDA Class II classification for TENS units mandates 510(k) clearance, constraining electrotherapy market entry.
- Rehabilitation:Post-surgical and injury-recovery protocols requiring progressive loading and mobility restoration. EU Medical Device Regulation clinical evidence requirements extend CE marking timelines for therapeutic efficacy claims.
- Posture Correction:Biomechanical support systems addressing spinal alignment and load distribution. Smart textile integration with embedded pressure sensors is displacing passive braces lacking real-time feedback.
- Muscle Relaxation:Myofascial release and thermal modalities targeting soft tissue tension. Sports medicine integration in the Netherlands and Germany drives clinical-grade specification.
Pain relief commands the greatest revenue concentration; posture correction is gaining share fastest.
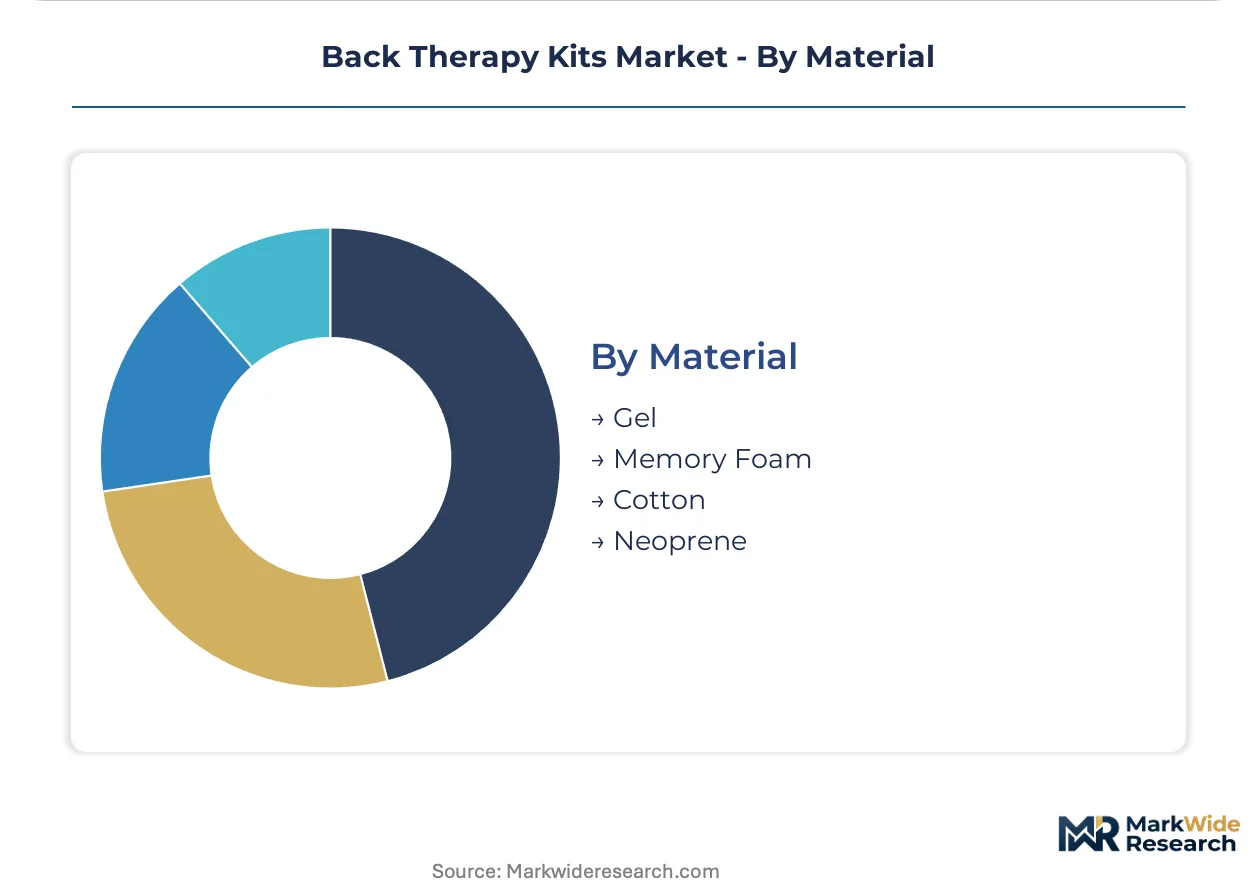
Material:
Input material selection governs thermoregulation performance, manufacturing cost structure, and supply chain geographic concentration.
- Memory Foam:Viscoelastic polyurethane formulations with pressure-mapping customization capabilities command premium positioning. China's manufacturing corridor dominates medical-grade output, creating single-source vulnerability.
- Neoprene:Synthetic rubber laminates providing compressive support and thermal retention. Petroleum-derived feedstock price volatility compresses margin stability for mid-tier manufacturers.
- Gel:Phase-change and viscoelastic gel formulations delivering thermoregulation and pressure distribution. High-margin tier differentiation depends on clinical-grade purity standards.
- Cotton:Natural fiber textiles for breathable, hypoallergenic applications with limited functional performance. Standard retail alternatives occupy economy positioning.
Memory foam holds the largest share; gel formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes back therapy kits through statutory reimbursement channels, while the United States purchases predominantly through retail and post-acute procurement offices, creating divergent demand profiles across developed markets.
United States
Hospital-owned outpatient clinics now represent the fastest-growing channel for powered therapy systems, bypassing traditional durable medical equipment distributors. FDA Class II classification for transcutaneous electrical nerve stimulation units mandates 510(k) clearance, constraining electrotherapy market entry timelines. The Boston-Minneapolis corridor hosts concentrated sports medicine research institutions driving clinical protocol innovation.
Germany
Statutory health insurance funds reimburse back braces and TENS units, creating predictable procurement volumes for manufacturers with CE-marked devices. EU Medical Device Regulation clinical evidence requirements extend CE marking timelines for therapeutic efficacy claims on posture-correcting braces. The Ruhr industrial belt maintains specialized textile manufacturing capacity for medical-grade neoprene components.
Japan
Aging demographics sustain home-use demand for thermal therapy devices with established JIS certification. METI enforces JIS standards for household electrical heating appliances, creating dual compliance burdens for multi-territory brands distributing thermal therapy kits. Osaka-based appliance manufacturers dominate domestic production of precision-controlled heating elements.
China
Manufacturing gravity concentrates in the Yangtze River Delta corridor for medical-grade neoprene and memory foam components, reshaping cost structures across export markets. NMPA medical device registration requirements apply to therapeutic claims on back braces entering domestic distribution. Shenzhen and Suzhou clusters specialize in pressure-mapping customization capabilities for premium-tier memory foam production.
Australia
Physiotherapy clinics prescribe density-calibrated foam rollers as standard myofascial release protocol, expanding clinical-grade demand beyond retail channels. TGA medical device regulations govern therapeutic claims on electrotherapy and compression devices distributed through practitioner channels. Melbourne and Sydney sports medicine institutes drive specification standards for athlete recovery equipment.
Back Therapy Kits Market Competitive Environment
Capability concentration sits with specialized orthopedic technology developers; scale advantage sits with diversified consumer health conglomerates. The market structures around three tiers: pharmaceutical-backed consumer health divisions with distribution network leverage, dedicated medical device manufacturers with regulatory validation archives, and emerging digital-native brands exploiting telehealth channel partnerships. Strategic moves center on portfolio convergence toward hybrid thermal-electrical modalities and direct procurement relationships with hospital group purchasing organizations.
Among pharmaceutical-backed consumer health operators, Sanofi and Bayer exemplify archetype positioning through European retail channel dominance and analgesic-device bundling strategies. Medtronic occupies the powered electrotherapy tier with electrical stimulation platforms integrating into orthopedic recovery protocols. These three anchors demonstrate how regulatory validation depth and distribution infrastructure scale determine competitive positioning across reimbursement-driven and direct-pay market segments.
| Leading Market Players |
|---|
| Sanofi |
| Bayer |
| Polar Products |
| DIH International |
| Tynor |
| Hocomo |
| Brooks Life Sciences |
| Alliance Spine |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta manufacturing corridor for medical-grade neoprene and memory foam components anchors downstream margin distribution, concentrating cost leverage with vertically integrated suppliers while compressing mid-tier manufacturers dependent on spot procurement.
Pricing Analysis
Long-term offtake agreements dominate procurement between major brands and Yangtze River Delta foam producers, insulating premium-tier manufacturers from petroleum-derived feedstock volatility that erodes spot-market buyers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared electrotherapy systems from CE-marked clinical braces and uncertified retail alternatives. Cost compression in standard-tier neoprene braces is intensifying because Chinese suppliers are absorbing margin pressure to maintain volume commitments. Home retail channels exhibit highest price sensitivity, while hospital procurement offices prioritize outcome telemetry over unit cost.
Supply Chain Analysis
Petroleum-derived polyurethane precursors and synthetic rubber feedstocks flow from integrated petrochemical complexes in China, South Korea, and Germany into medical-grade foam production lines. Medical-grade neoprene laminates, viscoelastic polyurethane formulations, and phase-change gel compounds constitute the critical input trinity for compressive and thermal devices. Single-source vulnerability concentrates in China's specialized textile manufacturing belt, where secondary qualification programs remain underdeveloped among Western brands. Distribution runs through hospital group purchasing organizations in the United States and statutory health insurance funds in Germany, bypassing traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from telehealth-integrated digital-native brands bundling remote physiotherapy consultation with device prescription, eroding the traditional medical supply channel advantage.
For Market Incumbents: Build regulatory validation archives as a moat against electrotherapy entrants lacking FDA 510(k) clearance timelines. Deepen backward integration into medical-grade neoprene production through partnerships with Ruhr industrial belt textile manufacturers. Secure long-term offtake agreements with Yangtze River Delta foam producers before feedstock volatility escalates. For New Entrants and Emerging Players: Preventive back support segments in France represent the most penetrable entry point as health technology assessment bodies recalibrate coverage criteria. Direct-to-consumer telehealth partnerships bypass entrenched distributor relationships that incumbents control. Target sensor-equipped braces for sports rehabilitation centers in Australia and the Netherlands where clinical protocol specification remains fluid. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed orthopedic technology developers holding CE-marked back brace portfolios but lacking electrotherapy integration. Five-to-ten year viability hinges on convergence toward hybrid thermal-electrical modalities. Watch FDA 510(k) clearance timelines for powered muscle stimulators as an inflection indicator for competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation clinical evidence requirements extend timelines for posture-correcting braces claiming therapeutic efficacy. |
| Hospital System Partnership | Group purchasing organizations in the United States consolidate vendor relationships through outcome documentation and device utilization telemetry demands. |
| Software Companion Development | Bluetooth-enabled biofeedback loops in smart textile braces displace passive compression garments lacking real-time postural correction data. |
| Reimbursement Strategy | Germany's statutory health insurance funds create predictable procurement volumes for manufacturers with validated CE-marked devices. |
| Backward Integration | In-house production of medical-grade memory foam insulates against petroleum-derived feedstock price swings compressing mid-tier margins. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hospital procurement managers, physiotherapy clinic directors, biomedical engineers, GPO contracts managers, and sports rehabilitation specialists. Secondary validation drew from FDA 510(k) clearance databases, CE marking notifications under EU Medical Device Regulation, German statutory health insurance reimbursement schedules, and METI JIS standards documentation. Bottom-up volume estimates from manufacturer shipment data were triangulated against top-down expenditure flows from national health accounts.
Calibration against historical reimbursement policy shifts and regulatory pathway timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, application function, and material composition alongside regulatory classification tier. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory assumptions. Forecast inputs incorporated statutory insurance coverage recalibrations in France and Germany, plus FDA Class II device clearance velocity for powered electrotherapy entrants.
Stress conditions across petroleum feedstock price bands, Chinese manufacturing corridor disruption scenarios, and reimbursement eligibility contractions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and insurance coverage stability. Cross-checking against hospital procurement database benchmarks and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
UAE Horse Riding Equipment Market
Sports & Fitness
Global Commercial Fitness Equipment Market
Sports & Fitness
Tennis Racquet Market
Sports & Fitness
Trekking Poles Market
Sports & Fitness
Pickleball Paddle Market
Sports & Fitness
Europe Fitness Equipment Market
Sports & Fitness
Mexico Outdoor Fitness Equipment Market
Sports & Fitness
US Spectator Sports Market
Sports & Fitness
Smart Fitness Watches Market
Sports & Fitness
Gym Fitness Accessories Market
Sports & Fitness
Cycling Sunglasses Market
Sports & Fitness
Backboard Market
Sports & Fitness
Windsurfing Equipment Market
Sports & Fitness
Elliptical Trainers Market
Sports & Fitness
Climbing Harness Market
Sports & Fitness
Global Golf Accessories Market