
 Baby Personal Care Products Market | 2026-2036
Baby Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Personal Care Products Market Analysis
Specialty store distribution is narrowing as e-commerce platforms capture premium baby skincare transactions. Procter & Gamble leverages its manufacturing scale to dominate mass-market diaper and wipe categories across North American retail. The Himalaya Drug Company anchors its position through botanical ingredient specialization in emerging Asian markets. Johnson & Johnson Services, Inc. navigates regulatory scrutiny by reformulating legacy baby powder lines toward cornstarch-based alternatives.
Baby personal care products encompass cleansers, moisturizers, and hygiene items formulated with mild surfactants, pH-balanced compositions typically between 4.5 and 6.5, and hypoallergenic testing protocols designed for infant epidermal barrier protection. These products serve parents, caregivers, and healthcare providers seeking dermatologically safe daily hygiene solutions for neonates and toddlers. Wipes and lotions capture the deepest margin pools due to repeat purchase frequency and premium ingredient positioning, while shampoo formulations compete on tear-free surfactant technology. The customer type dimension reveals healthcare providers as a concentrated high-volume channel for hospital-branded newborn kits.
US FDA oversees cosmetic safety labeling for baby products under the Federal Food, Drug, and Cosmetic Act, while EU REACH restricts formaldehyde-releasing preservatives and allergenic fragrance compounds in infant formulations. China's NMPA and GB standards mandate microbiological testing and ingredient disclosure for imported baby cosmetics, raising compliance costs for foreign entrants. Stakeholders must monitor evolving preservative bans across multiple jurisdictions while deciding whether to develop region-specific formulations or pursue unified global SKU strategies.
Market Dynamics
Clean-label ingredient mandates and e-commerce channel capture are compressing traditional mass-market formulations while concentrating premium transactions in digital storefronts. Millennial parental preferences for botanical transparency now override legacy brand loyalty across major economies.
Growth Catalysts
- EU REACH allergen restrictions:Formaldehyde-releasing preservative bans force reformulation toward plant-derived alternatives, opening premium positioning for compliant entrants.
- Neonatal hospital kit procurement:Healthcare provider channel concentration sustains high-volume contracts for standardized newborn hygiene bundles.
- China tier-one urbanization:Shanghai and Beijing households demonstrate sustained willingness-to-pay for certified organic baby skincare lines.
Market Restraints
- Surfactant input volatility:Mild cleansing agent raw material costs fluctuate with palm oil and coconut derivative commodity cycles.
- Preservative efficacy limitations:Natural antimicrobial alternatives exhibit shorter shelf stability versus synthetic benchmarks, constraining distribution reach.
- China NMPA import compliance:Microbiological testing and ingredient disclosure mandates raise fixed costs for foreign brand market entry.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer platforms capture recurring revenue from wipes and lotion repeat purchases.
- India botanical heritage positioning:Ayurvedic ingredient narratives differentiate regional specialists in emerging Asian markets.
- Tear-free surfactant technology convergence:Amphoteric cleansing chemistry advances enable novel shampoo-ointment hybrid formats.
Industry Challenges
- Dermatological testing capacity constraints:Pediatric patch study bottlenecks delay hypoallergenic certification timelines.
- Legacy retail shelf space erosion:Specialty store footprint reduction complicates brand visibility for non-digital-native entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Personal Care Products Market |
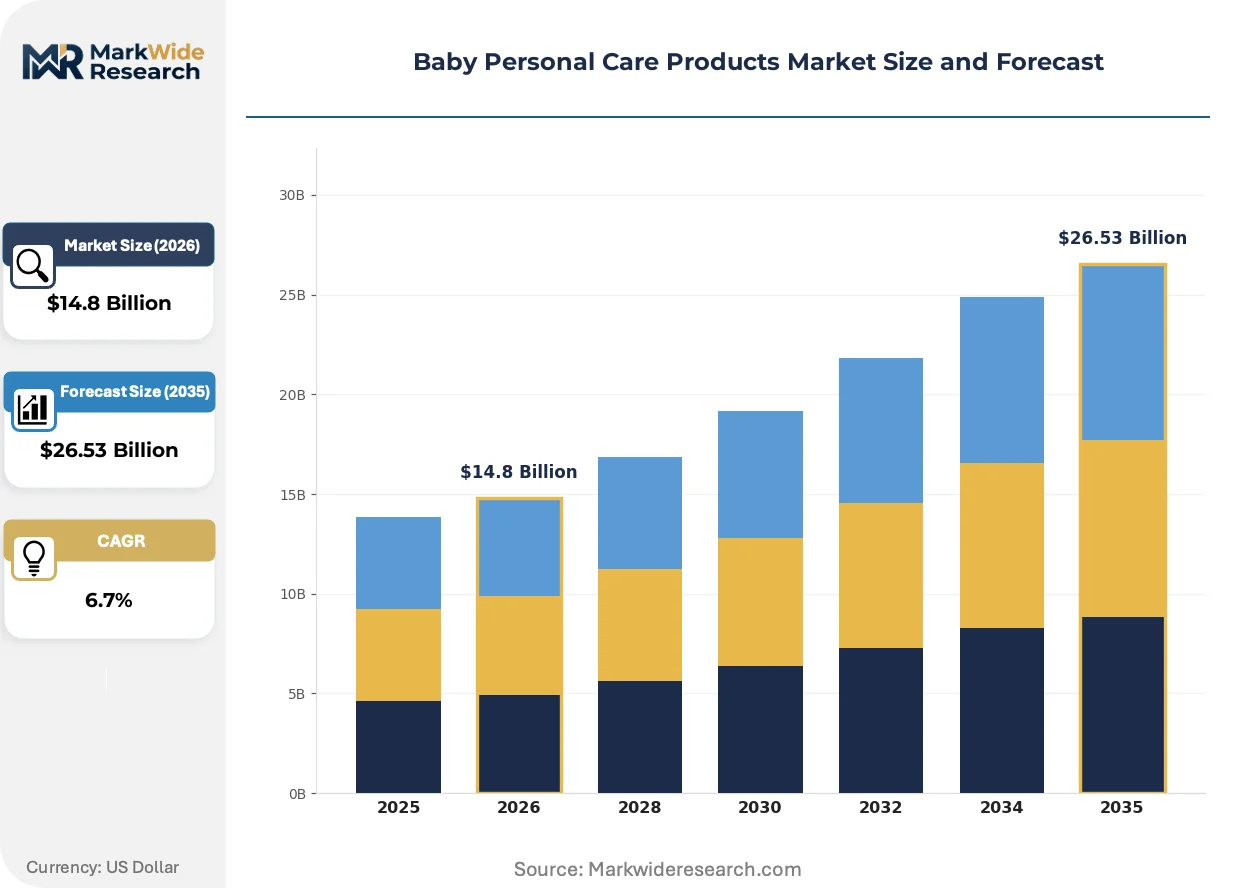
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Lotions, Wipes, Powders Customer Type: Parents, Caregivers, Healthcare Providers, Retailers Packaging Type: Bottles, Tubs, Tiolets, Sachets Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Unilever, The Himalaya Drug Company, Johnson & Johnson Services, Inc., Reckitt Benckiser, Burt's Bees, Procter & Gamble, Beiersdorf AG, KAO Corporation, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Personal Care Products Market Emerging Trajectories
Biotechnology-derived emollients and microbiome-conscious formulations are displacing conventional petrolatum bases. Regulatory fragmentation across FDA, REACH, and NMPA jurisdictions forces parallel development tracks.
Plant-based squalane and ceramide complexes from sugarcane fermentation are rendering obsolete mineral oil-derived moisturizers in premium baby skincare. Clean-label retailers in Germany and California accelerate adoption. This shift compresses margins for legacy petroleum-dependent suppliers while rewarding biotechnology partnerships.
EU REACH fragrance allergen disclosure mandates now require quantitative labeling of 26 specific compounds in leave-on baby products. Reformulation costs concentrate among mid-tier brands lacking in-house toxicology capacity. German and French markets exhibit fastest compliance adaptation through retailer-driven supplier audits.
Hospital discharge gift set procurement now bypasses traditional distributors for direct manufacturer contracting. Neonatal unit administrators negotiate consolidated newborn kit supply agreements. This pattern concentrates most visibly in US health system vertical integration and UK National Health Service tender consolidations.
Baby Personal Care Products Market Segmentation
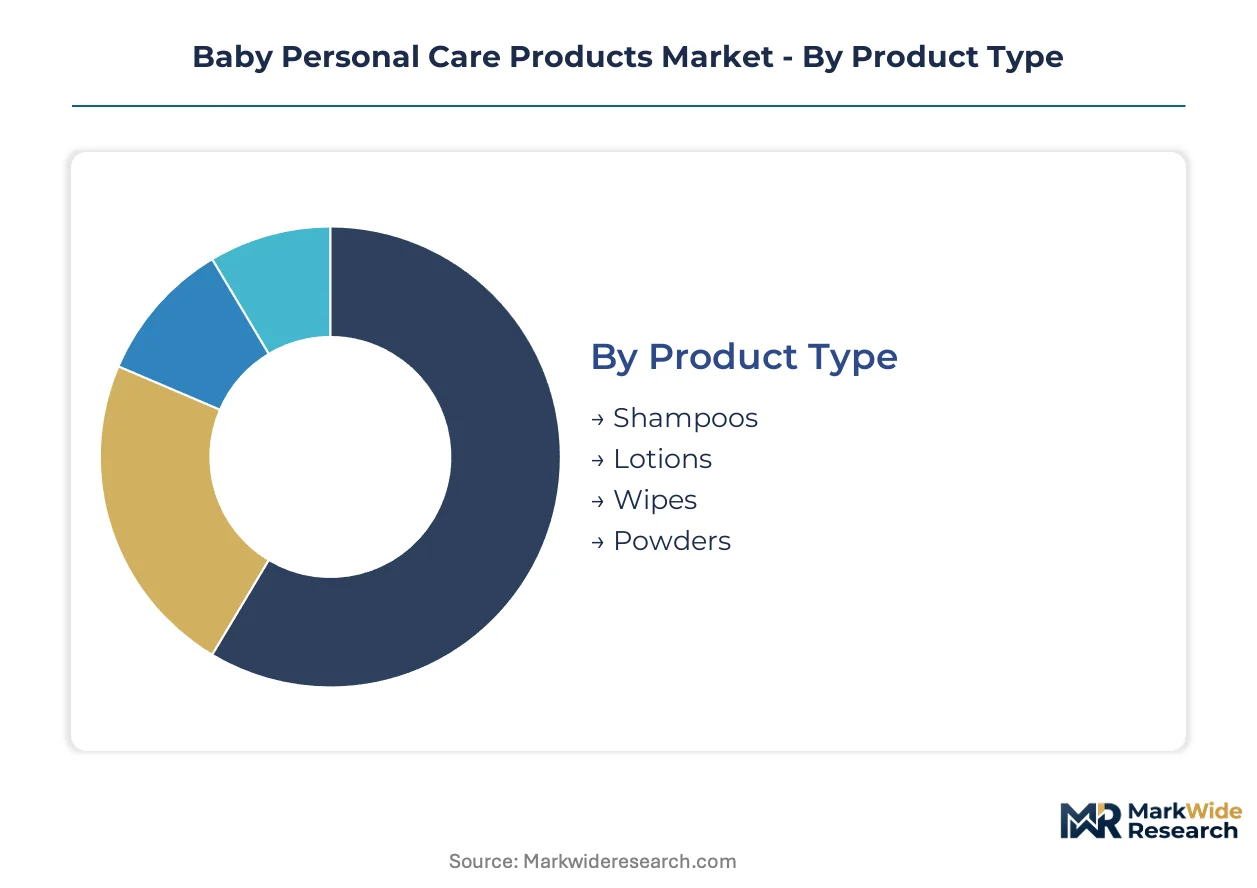
Segmentation in baby personal care reveals divergent margin structures and channel economics. Product formulation complexity varies sharply across categories, while customer procurement patterns dictate packaging and distribution investments.
Product Type:
Mature surfactant chemistry dominates mass-market categories while biotechnology-derived formats emerge in premium positioning.
- Wipes:Non-woven substrate formulations impregnated with mild cleansing solutions and pH-balanced moisturizers. Demand concentrates in US urban households and Chinese tier-one cities where subscription replenishment models sustain repeat purchase frequency and premium ingredient positioning.
- Lotions:Emulsion-based barrier products incorporating ceramide complexes and plant-derived squalane from sugarcane fermentation. German clean-label retailers and California specialty channels accelerate displacement of mineral oil-derived moisturizers through microbiome-conscious formulation positioning.
- Shampoos:Tear-free amphoteric surfactant systems with pH typically between 4.5 and 6.5 for neonatal epidermal compatibility.
- Powders:Cornstarch-based alternatives displacing legacy talc formulations under FDA cosmetic safety labeling scrutiny.
Wipes handle the majority of throughput; lotions are expanding most quickly on share.
Customer Type:
Procurement authority splits between institutional volume contracting and fragmented household decision-making.
- Healthcare Providers:Hospital-branded newborn kits procured through direct manufacturer contracting bypassing traditional distributors. US health system vertical integration and UK National Health Service tender consolidations concentrate most visibly in neonatal unit administrator negotiations for standardized hygiene bundles.
- Parents:Millennial demographic driving clean-label ingredient mandates and botanical transparency preferences that override legacy brand loyalty across major economies.
- Caregivers:Professional childcare facilities requiring bulk-format packaging and hypoallergenic certification documentation.
- Retailers:Pharmacy chains and specialty stores curating assortment based on EU REACH compliance status and preservative disclosure standards.
Healthcare providers anchor volume throughput; parents are gaining influence fastest on formulation requirements.
Packaging Type:
Unit economics and shelf stability requirements shape material selection across channel formats.
- Bottles:Pump-dispense and flip-top configurations for liquid cleansers and lotions, with PCR content mandates from major retailers.
- Tubs:Wide-mouth containers for thick cream formulations enabling single-hand access during diaper changes.
- Tiolets:Travel-sized formats targeting pharmacy convenience channels and hospital discharge gift set inclusion.
- Sachets:Single-use sachet packaging dominates sample distribution and emerging market affordability tiers.
Bottles carry the highest unit volumes; sachets are climbing the fastest in emerging market penetration.
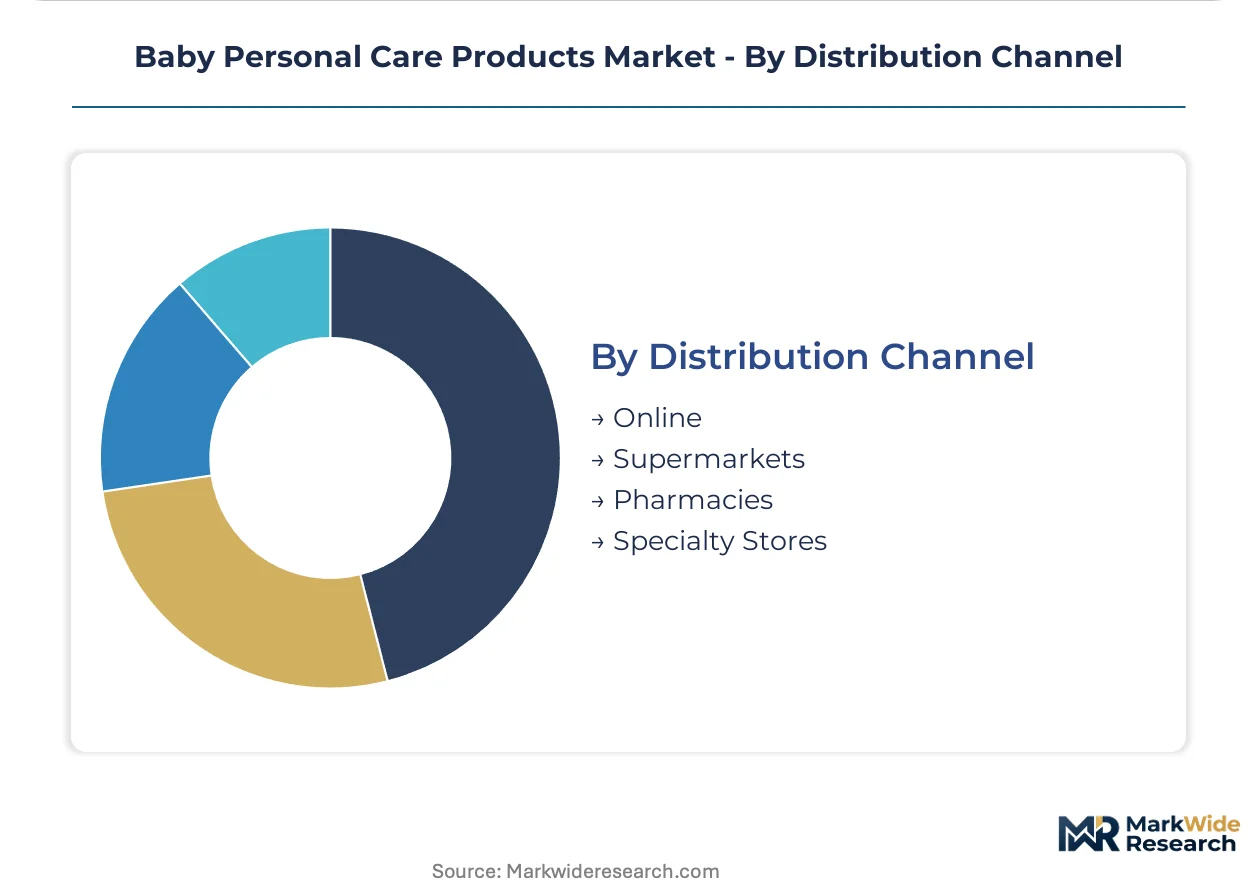
Distribution Channel:
Channel capture dynamics reflect premium transaction migration and regulatory compliance burden allocation.
- Online:Direct-to-consumer platforms capturing recurring revenue from wipes and lotion repeat purchases through subscription-based replenishment models. E-commerce storefronts concentrate premium baby skincare transactions as specialty store distribution narrows.
- Supermarkets:Mass-market diaper and wipe categories dominated by manufacturing scale advantages in North American retail.
- Pharmacies:Dermatological recommendation channels for hypoallergenic-certified formulations requiring pediatric patch study documentation.
- Specialty Stores:Clean-label retailers in Germany and California accelerating biotechnology-derived emollient adoption through supplier audit programs.
Online channels are seizing share fastest; supermarkets retain the deepest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic safety labeling governs the dominant United States market, while EU REACH allergen restrictions and China's NMPA import standards shape compliance trajectories across major consumption centers. Regulatory fragmentation concentrates formulation investments in jurisdictions with the most stringent disclosure mandates.
United States
Millennial parental preferences for clean-label transparency override legacy brand loyalty in urban coastal markets. FDA oversight under the Federal Food, Drug, and Cosmetic Act mandates cosmetic safety labeling without pre-market approval, creating compliance asymmetries versus EU benchmarks. Greater Boston and Pacific Northwest metropolitan clusters concentrate premium organic baby skincare adoption through specialty pharmacy and direct-to-consumer channels.
Germany
Clean-label retailers accelerate biotechnology-derived emollient adoption through supplier audit programs targeting preservative-free formulations. EU REACH fragrance allergen disclosure mandates require quantitative labeling of 26 specific compounds in leave-on infant products, concentrating reformulation costs among mid-tier brands. The Eindhoven-Randstadt corridor channels compliant formulations into Benelux distribution networks.
China
Shanghai and Beijing households demonstrate sustained willingness-to-pay for certified organic baby skincare lines in tier-one urban concentrations. NMPA and GB standards mandate microbiological testing and ingredient disclosure for imported baby cosmetics, raising fixed costs for foreign brand market entry. Yangtze River Delta manufacturing clusters supply domestic formulation capacity for regional brand development.
India
Ayurvedic ingredient narratives differentiate regional specialists in emerging Asian markets where botanical heritage positioning commands premium shelf placement. CDSCO and BIS frameworks govern cosmetic safety without harmonized infant-specific testing protocols, creating certification arbitrage opportunities. Maharashtra and Gujarat industrial corridors concentrate contract manufacturing capacity for export-oriented natural formulation brands.
Japan
PMDA pharmaceutical-grade standards for quasi-drug infant skincare create elevated entry barriers for foreign competitors seeking dermatological recommendation channels. METI industrial policy supports biotechnology fermentation capacity for plant-derived squalane and ceramide production. Kanto and Kansai metropolitan areas concentrate premium pharmacy distribution for hypoallergenic-certified newborn formulations.
Baby Personal Care Products Market Vendor Landscape
Scale-driven multinationals and botanical heritage specialists split the market into divergent margin structures. Mass-market categories consolidate around manufacturing scale advantages in diaper and wipe segments, while premium skincare fragments across clean-label positioning strategies. Three archetypes dominate: diversified consumer goods conglomerates with captive distribution, regional botanical specialists leveraging ingredient provenance narratives, and private-label contract manufacturers serving pharmacy and hospital channels. Competitive moves center on cornstarch-based powder reformulation to navigate regulatory scrutiny, and direct-to-consumer subscription platforms capturing recurring replenishment revenue.
Within the diversified conglomerate tier, Unilever and Procter & Gamble occupy positions defined by manufacturing scale and North American retail penetration. The Himalaya Drug Company exemplifies the botanical heritage archetype through its emerging Asia market specialization. Johnson & Johnson Services, Inc. represents the legacy brand navigating reformulation imperatives, while Beiersdorf AG and KAO Corporation sit within the premium skincare tier emphasizing dermatological credentials. Reckitt Benckiser and Kimberly-Clark Corporation anchor hygiene-focused portfolios across mass-market wipe and diaper categories.
| Leading Market Players |
|---|
| Unilever |
| The Himalaya Drug Company |
| Johnson & Johnson Services, Inc. |
| Reckitt Benckiser |
| Burt's Bees |
| Procter & Gamble |
| Beiersdorf AG |
| KAO Corporation |
| Kimberly-Clark Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor cost dynamics compress margins for imported formulations while amplifying price differentiation between domestic Chinese manufacturers and foreign brands navigating NMPA compliance overhead. Supply concentration in Southeast Asian surfactant production feeds directly into subscription pricing power for direct-to-consumer platforms, while palm oil commodity cycles force volatile input cost pass-through decisions across tiered product positioning.
Pricing Analysis
The customization-premium spread in baby personal care separates mass-market wipe subscriptions from configured-to-order hospital discharge kits with institutional procurement terms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale advantages. Cost compression in mass-market surfactant formulations is intensifying because palm oil derivative volatility squeezes fixed-margin contracts. Healthcare provider procurement demonstrates lowest price sensitivity due to bundled kit standardization, while emerging market sachet buyers exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock dependencies in palm oil derivatives and coconut-based mild surfactants draw from Indonesia, Malaysia, and Philippines plantation networks. Biotechnology fermentation capacity for plant-derived squalane rests on sugarcane supply from Brazilian and Indian agricultural corridors. Single-source vulnerability concentrates in Southeast Asian oleochemical processing clusters. Distribution runs through direct-to-consumer platforms for premium replenishment, with hospital procurement bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label biotechnology disruption and EU REACH preservative mandates are compressing legacy formulation margins while opening premium positioning for compliant entrants. This regulatory-technological inflection justifies aggressive repositioning across stakeholder archetypes.
For Market Incumbents: Entrench manufacturing scale advantages in wipe and diaper categories through backward integration into non-woven substrate production. Capture hospital procurement consolidation through direct contracting relationships with US health system administrators and UK NHS tender boards. Defend against botanical heritage specialists by accelerating cornstarch-based powder reformulation to neutralize talc-related regulatory exposure.
For New Entrants and Emerging Players: Establish a beachhead in India Ayurvedic positioning for emerging Asian market penetration. Target tier-one Chinese urban households through cross-border e-commerce platforms with certified organic SKU lines. Leverage subscription-based replenishment models for recurring revenue capture in US coastal millennial demographics.
For Investors and Strategic Acquirers: Regional botanical heritage specialists with captive ingredient sourcing and CDSCO compliance infrastructure represent optimal acquisition targets for portfolio diversification. Long-term viability across the projection horizon hinges on microbiome-conscious formulation pipelines and tear-free surfactant technology convergence. Monitor EU REACH fragrance allergen disclosure enforcement velocity as inflection indicator for reformulation cost concentration among mid-tier brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Direct-to-consumer replenishment captures recurring revenue from wipes and lotion repeat purchases. |
| Botanical Heritage Repositioning | Ayurvedic ingredient narratives differentiate regional specialists in emerging Asian markets. |
| Cornstarch Powder Reformulation | FDA cosmetic safety labeling scrutiny forces legacy talc displacement toward plant-derived alternatives. |
| Hospital Procurement Consolidation | Neonatal unit administrators negotiate direct manufacturer contracts bypassing traditional distributors. |
| EU REACH Compliance Investment | Fragrance allergen disclosure mandates concentrate reformulation costs among mid-tier brands lacking toxicology capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from brand managers, category buyers at pharmacy chains, neonatal unit procurement administrators, and supply planners, then refined through secondary validation. FDA cosmetic safety labeling databases, EU REACH substance restriction lists, NMPA import registration filings, and Nielsen retail audit data anchored quantitative baselines. Bottom-up demand modeling triangulated against top-down category spend estimates.
Demand-supply-balance framing across the analysis window integrated product type segmentation with customer procurement patterns, packaging format economics, and channel migration trajectories. CAGRs were derived from normalized growth rate convergence across modeled scenarios. Biotechnology fermentation capacity expansion and surfactant raw material commodity cycles served as industry-specific forecast inputs.
Sensitivities concentrate around EU REACH preservative ban enforcement timelines, NMPA import compliance cost escalation, and palm oil derivative price volatility. Forecasts reflect assumptions about clean-label adoption velocity and hospital procurement consolidation rates. Cross-checking against customs import data and health system tender award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Prams and Strollers Market
Baby Products
Baby Bouncers Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
North America Baby Bottle Market
Baby Products
Silicone Baby Product Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Canada Baby Care Products Market
Baby Products
Baby Bassinets Market
Baby Products
Baby Care Products Market
Baby Products
Kids Training Pant Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Bottle Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Baby Nose Suckers Market
Baby Products
Diaper Pails Market
Baby Products
Infant Care and Baby Care Equipment Market