
 Sippy Cups Market | 2026-2036
Sippy Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Sippy Cups Market Analytics
REACH compliance in Europe is hardening material requirements for baby feeding products. NUK leverages its German engineering heritage to sustain premium positioning across European pharmacies. Tommee Tippee anchors British market share through intensive nursery channel relationships. Philips AVENT competes on clinical credibility, extending its hospital-recommended brand into home-use sippy cups.
A sippy cup is a lidded drinking vessel with a controlled-flow mechanism, typically incorporating a spout, straw, or valve system to minimize spills during early childhood motor development. Most units employ food-grade polypropylene bodies with silicone or thermoplastic elastomer seals, manufactured through injection molding and assembled under cleanroom conditions to meet oral-contact safety thresholds. Plastic variants still dominate unit volume due to cost accessibility, though stainless steel is gaining fastest among environmentally conscious parents seeking durable alternatives. Silicone spout and straw designs command margin premiums for their orthodontic compatibility and temperature resistance. Distribution through specialty stores and online platforms captures higher-margin transactions compared to supermarket retail chains.
The FDA enforces stringent migration limits for plastics contacting infant foods under 21 CFR 177, while the EU's REACH and F-Gas Regulation constrain chemical inputs and manufacturing emissions respectively. China's GB standards for infant products and the NMPA's material registration requirements create divergent compliance pathways for exporters. Stakeholders must monitor evolving BPA-substitute scrutiny and polymer recycling mandates to anticipate which material platforms will retain market access.
Market Dynamics
The EU's REACH regulation on chemical safety in children's products is hardening material specifications across manufacturing, forcing producers to abandon legacy polymer formulations and requalify supply chains for silicone and stainless steel alternatives.
Growth Catalysts
- Early Childhood Hydration Focus:Pediatric dental associations now emphasize straw-based sipping for oral motor development, expanding addressable demand among parents of toddlers seeking orthodontic-compatible designs.
- REACH Compliance Mandate:The EU's chemical safety framework is eliminating BPA-substitute plasticizers from infant-contact materials, creating replacement demand for food-grade silicone and 316L stainless steel platforms.
- Stainless Steel Adoption:Environmentally conscious parents in premium retail channels are displacing disposable plastic units with vacuum-insulated metal variants that withstand multi-year use cycles.
Market Restraints
- Silicone Raw Material Volatility:Medical-grade silicone elastomer prices fluctuate with semiconductor and solar panel demand, compressing margins for spout and seal manufacturers.
- Asian Molding Concentration:Injection molding capacity for polypropylene bodies concentrates in Guangdong and Zhejiang provinces, exposing brands to freight cost spikes and tariff uncertainty.
- Valve Mechanism Durability:Thermoplastic elastomer valve components degrade after repeated dishwasher cycles, generating warranty claims and brand reputation risk.
Strategic Opportunities
- Subscription Refill Models:Direct-to-consumer channels enable recurring revenue through silicone straw and valve replacement kits, locking in brand loyalty beyond initial hardware purchase.
- Hospital Discharge Gifting:Clinical partnerships with maternity wards create captive introduction of premium sippy cups to new parents during the 0-6 month transition window.
- Extended Producer Responsibility:EU packaging waste directives are mandating take-back programs that favor durable stainless steel platforms with end-of-life material recovery value.
Industry Challenges
- Cleanroom Assembly Certification:FDA oral-contact safety thresholds require ISO 14644 Class 8 environments for final assembly, constraining contract manufacturer selection and extending facility qualification timelines.
- Multi-Regulatory File Management:Simultaneous compliance with FDA 21 CFR 177, EU REACH, and China's GB standards demands dedicated regulatory affairs headcount and divergent testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sippy Cups Market |
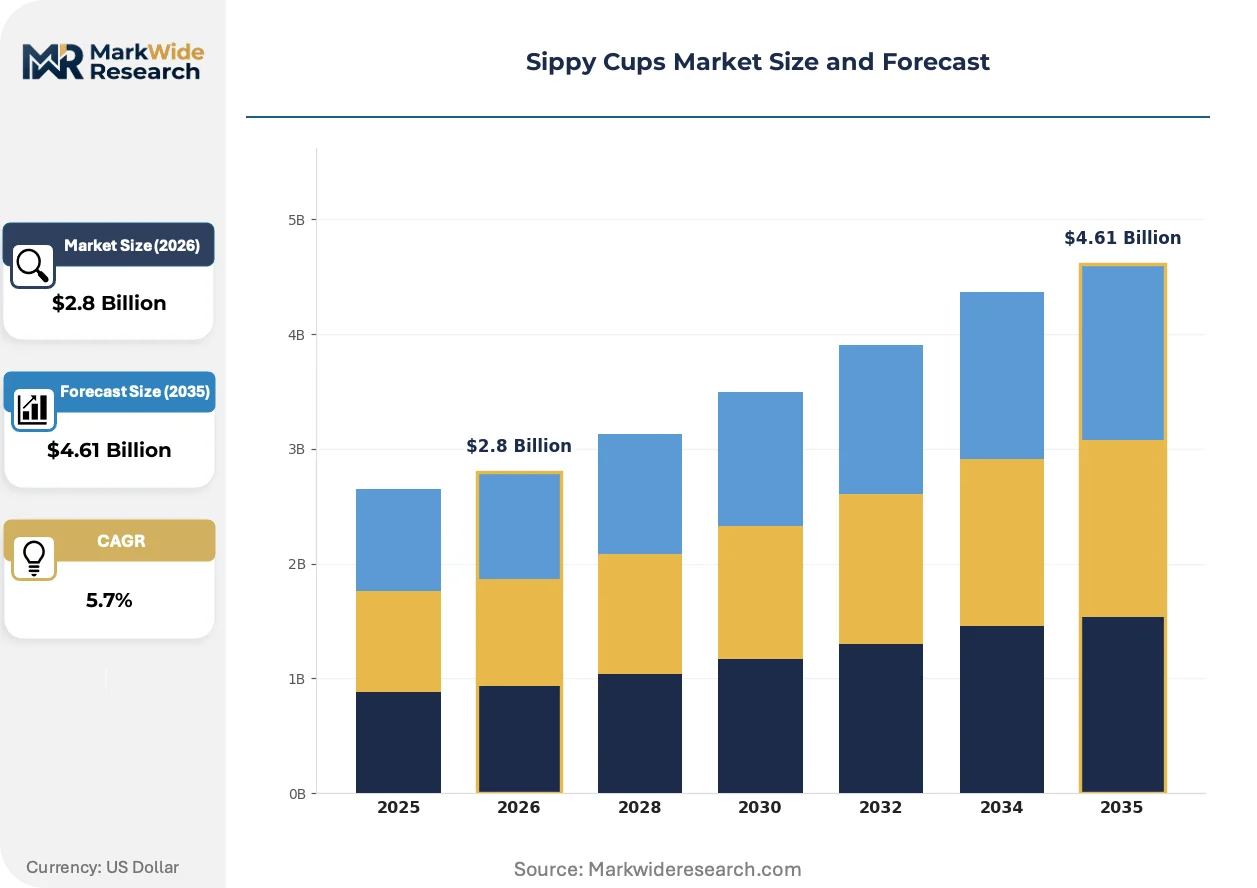
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Stainless Steel, Glass, Silicone Age Group: Toddlers, Infants, Children, Preschool Design Feature: Spout, Straw, Handle, Spill-proof Distribution Channel: Online, Supermarkets, Specialty Stores, Retail Chains |
| Companies Covered | NUK, Playtex, Munchkin, OXO Tot, b.box, Dr. Brown's, Tommee Tippee, Nuby, Philips AVENT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sippy Cups Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to reshape competitive positioning in toddler hydration hardware, with durability and safety certification displacing price as the primary purchase filter.
Smart temperature-sensing silicone is converging with Bluetooth-enabled parent notification systems to alert caregivers when liquid exceeds safe consumption thresholds. Early adopters in the premium parenting segment are integrating these connected cups into broader nursery monitoring ecosystems. This convergence is compressing the addressable market for basic uninstrumented plastic variants.
REACH Annex XVII restrictions on phthalates and bisphenol analogues are hardening migration limits for all infant-contact polymers. Manufacturers are reformulating polypropylene compounds with bio-based plasticizers or abandoning plastic entirely for metal and silicone architectures. The pharmacy and specialty retail channel in Germany and France is most affected, with shelf placement contingent on ECHA-compliant material declarations.
Parents are abandoning supermarket aisle browsing for algorithmic curation through social commerce platforms and pediatrician-endorsed subscription boxes. Instagram and TikTok discovery is displacing traditional retail search for first-time buyers. This behavioral shift concentrates demand in the United States and United Kingdom, where influencer-driven nursery product recommendations command disproportionate conversion rates.
Sippy Cups Market Segmentation
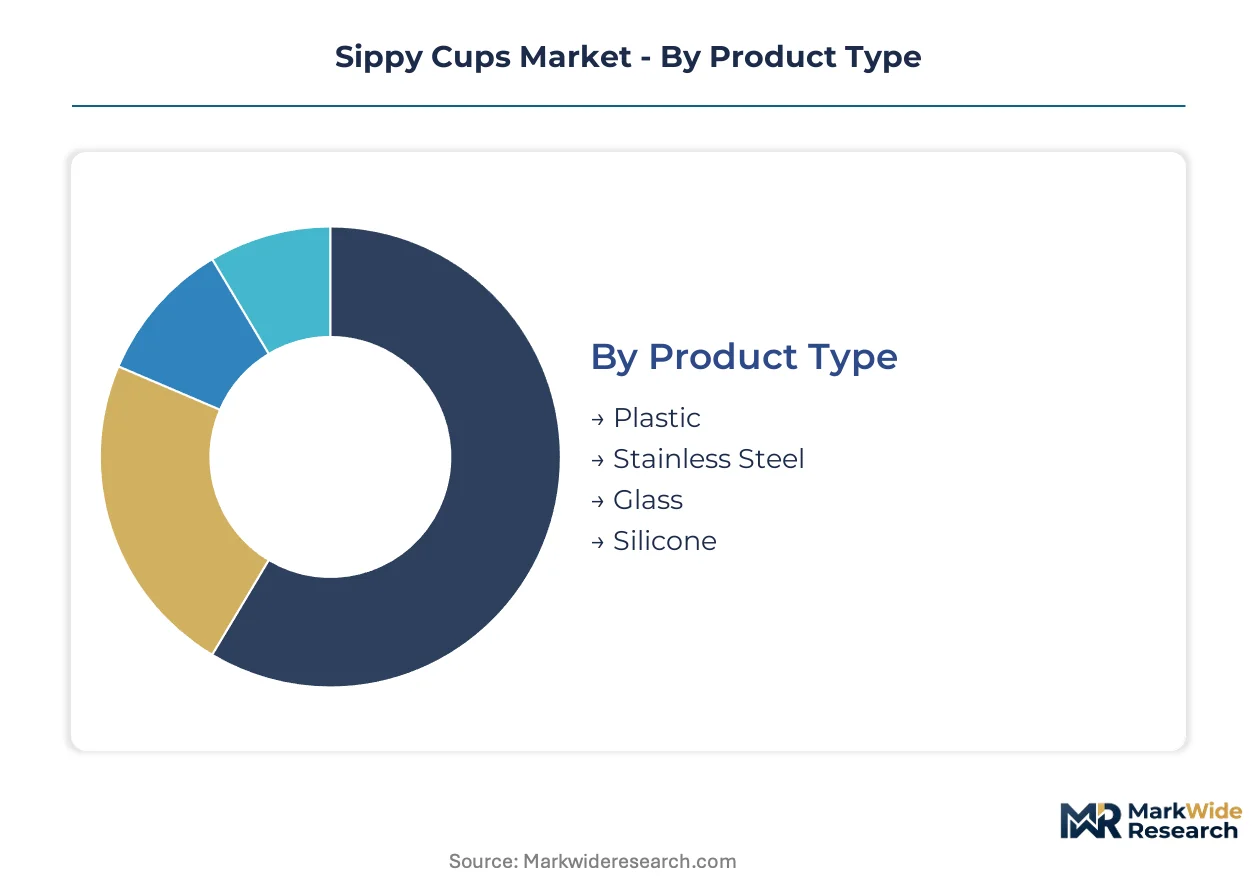
Segmentation in the sippy cups market reveals how material choices, developmental stages, and purchase contexts fragment demand across divergent price points and channel strategies. Understanding these divides helps manufacturers align R&D investment with where parents actually spend.
Product Type:
Material selection separates buyers by durability expectations, chemical safety concerns, and environmental values rather than price sensitivity alone.
- Plastic:Food-grade polypropylene bodies with thermoplastic elastomer seals dominate unit economics through injection-molded production in Guangdong province. Parents in mass retail channels prioritize accessibility, though REACH-mandated reformulation is eroding cost advantages against silicone alternatives.
- Stainless Steel:Vacuum-insulated 316L variants command premium placement in specialty channels across Germany and France, where ECHA-compliant material declarations and end-of-life recovery value align with extended producer responsibility mandates. Environmentally conscious households seeking multi-year use cycles drive steepest expansion trajectory here.
- Glass:Borosilicate constructions with silicone sleeves address parental anxiety about chemical migration, limited by weight and breakage risk to countertop use in higher-income households.
- Silicone:Food-grade elastomer cups collapse for travel and withstand temperature extremes, gaining traction among parents prioritizing orthodontic compatibility and dishwasher durability.
Volume sits with Plastic; growth tilts toward Stainless Steel.
Age Group:
Developmental milestones determine spout mechanics, flow rates, and ergonomic requirements that manufacturers must match precisely.
- Toddlers:Pediatric dental associations emphasize straw-based sipping for oral motor development, expanding demand among parents seeking orthodontic-compatible designs with controlled flow valves.
- Infants:Transition cups bridge bottle and cup feeding with soft silicone spouts mimicking nipple texture, capturing first-time parents during the 0-6 month window through hospital discharge partnerships.
- Children:Larger capacity vessels with sport-style lids serve school-age hydration needs, competing against disposable bottled water in lunchbox contexts.
- Preschool:Character-licensed designs and leak-proof guarantees dominate procurement decisions for daycare-compliant personal items.
Demand concentrates with Toddlers; margin expansion favors Infants.
Design Feature:
Functional mechanics determine spill containment effectiveness, cleaning complexity, and compatibility with developing oral structures.
- Spout:Hard or soft spout variants with bite-activated flow remain the default configuration for first-time cup users, though thermoplastic elastomer degradation after repeated dishwasher cycles generates warranty exposure.
- Straw:Silicone straw designs with weighted bases allow 360-degree drinking, preferred by pediatric dentists for proper tongue positioning and jaw development in the United States and United Kingdom.
- Handle:Removable ergonomic grips accommodate developing grip strength, with two-handle configurations standard for 6-12 month users transitioning from bottle feeding.
- Spill-proof:Valve mechanisms using silicone membranes or weighted balls minimize leakage but introduce cleaning complexity that parents report as a primary frustration in product reviews.
Spout configurations retain volume leadership; straw designs climb fastest on clinical endorsement.
Distribution Channel:
Channel selection reflects purchase urgency, information needs, and willingness to trade convenience for curation.
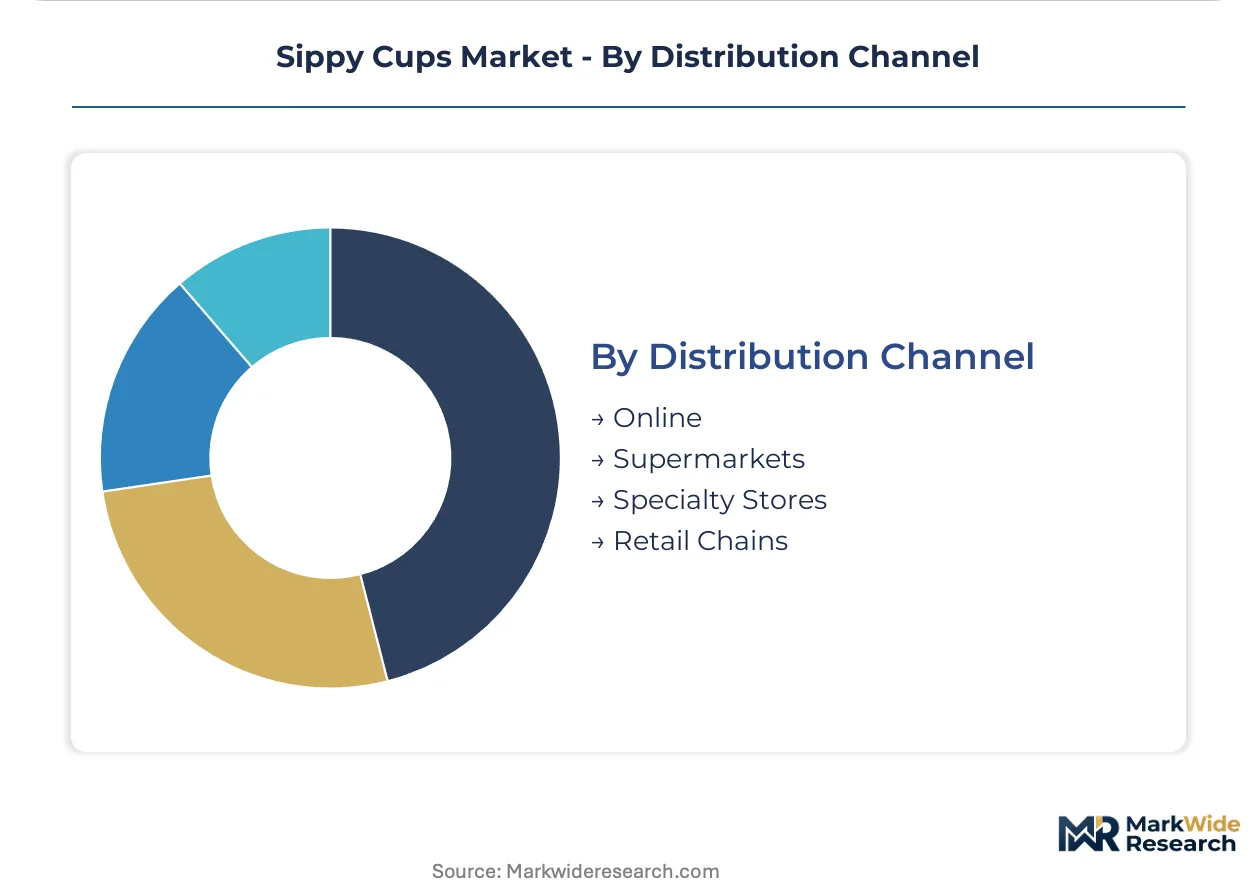
- Online:Algorithmic curation through social commerce platforms and subscription boxes concentrates first-time buyer discovery, with Instagram and TikTok driving disproportionate conversion in influencer-heavy markets.
- Supermarkets:Impulse placement and price promotions capture replacement purchases and emergency replacements, though shelf space for premium materials is contracting.
- Specialty Stores:Pharmacy and nursery channels in Germany and France require ECHA-compliant material declarations, filtering assortment toward silicone and stainless steel platforms with clinical credibility.
- Retail Chains:Mass merchandisers in the United States leverage private label programs to undercut branded plastic variants, compressing margin for mid-tier suppliers.
Supermarkets move the most units; specialty and online channels capture expanding margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors injection-molded polypropylene production for plastic sippy cup bodies, with Shenzhen and Dongguan hosting the densest concentration of contract manufacturers serving export markets.
United States
Pediatric dental endorsements of straw-based sipping drive demand for orthodontic-compatible designs among first-time parents. FDA enforces 21 CFR 177 migration limits for plastics contacting infant foods. Los Angeles and New York metro areas concentrate influencer-driven social commerce conversion for premium silicone and stainless steel variants.
Germany
Pharmacy channel relationships sustain premium positioning for engineered feeding products with clinical credibility. ECHA REACH Annex XVII restrictions on phthalates and bisphenol analogues harden material declarations for shelf placement. Bavaria's industrial corridor hosts specialized cleanroom assembly facilities meeting ISO 14644 Class 8 thresholds for oral-contact safety.
China
Domestic demand for food-grade silicone alternatives accelerates as middle-class parents prioritize chemical safety. NMPA material registration requirements and GB standards for infant products create divergent compliance pathways for exporters. Zhejiang province's molding clusters supply valve mechanisms and thermoplastic elastomer components to international brands.
United Kingdom
Intensive nursery channel relationships anchor market share for established feeding brands in the post-bottle transition segment. TikTok and Instagram discovery displaces traditional retail search for first-time buyers. Greater London and Manchester concentrate algorithmic curation through subscription boxes and pediatrician-endorsed parenting platforms.
France
ECHA-compliant material declarations filter pharmacy assortment toward silicone and stainless steel platforms with end-of-life recovery value. EU packaging waste directives mandate take-back programs favoring durable metal architectures. Île-de-France hosts headquarters of multinational infant care brands coordinating European regulatory affairs.
Sippy Cups Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and clinical endorsement dimensions, with the market fragmenting into three discernible tiers. German engineering heritage and British nursery channel dominance define the upper tier, while private-label programs at mass merchandisers compress mid-tier supplier economics. Strategic archetypes include clinically credentialed hospital-recommended brands, pharmacy-channel premium specialists, and direct-to-consumer subscription innovators. Competitive moves concentrate on hospital discharge gifting partnerships and silicone component replacement subscription models.
Within the clinically credentialed tier, Philips AVENT and Dr. Brown's occupy positions anchored by hospital-recommended heritage extending into home-use feeding products. Tommee Tippee exemplifies the nursery-channel specialist archetype through intensive British market presence. NUK represents the German engineering premium positioning sustained across European pharmacy networks.
| Leading Market Players |
|---|
| NUK |
| Playtex |
| Munchkin |
| OXO Tot |
| b.box |
| Dr. Brown's |
| Tommee Tippee |
| Nuby |
| Philips AVENT |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant silicone and stainless steel platforms versus legacy polypropylene variants manifests in both procurement premiums and supplier qualification timelines, with pharmacy-channel buyers absorbing higher landed costs for ECHA-validated material declarations while mass retail channels squeeze injection-molded commodity suppliers on volume terms.
Pricing Analysis
Orthodontic outcome value anchors premium tier positioning, with straw-based silicone designs commanding sustained margin premiums over spout configurations due to pediatric dental association endorsements. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel vacuum-insulated units from food-grade silicone intermediates and polypropylene mass-market variants. Cost compression in plastic tiers is intensifying because REACH-mandated reformulation erodes cost advantages against silicone alternatives. First-time parents through specialty channels exhibit lowest price sensitivity; mass retail replacement buyers demonstrate highest elasticity.
Supply Chain Analysis
Freight cost volatility from Guangdong and Zhejiang province molding clusters to North American and European distribution hubs compresses margins for brands without regional assembly footprints. Manufacturing gravity centers on China's injection molding capacity for polypropylene bodies, German cleanroom facilities for oral-contact assembly, and Vietnamese emerging capacity for valve component finishing. Raw material dependencies span medical-grade silicone elastomers, 316L stainless steel sheet, and thermoplastic elastomer seals. Single-source vulnerability concentrates in Guangdong province for polypropylene body production. Distribution runs through pharmacy and specialty retail channels for premium tiers, mass merchandisers for volume, and direct-to-consumer subscription models for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance mandates and raw material volatility are forcing sub-scale plastic-focused manufacturers toward exit or acquisition, creating consolidation headroom for certified players with diversified material platforms.
For Market Incumbents: Acquire cleanroom assembly certification assets to lock in FDA oral-contact production capacity before qualification timelines extend further. Secure backward integration into medical-grade silicone compounding to insulate margin from semiconductor and solar panel demand spikes. Defend against direct-to-consumer subscription entrants by preempting hospital discharge gifting partnerships with maternity ward networks. For New Entrants and Emerging Players: Social commerce algorithmic curation offers lowest customer acquisition cost entry for first-time parent segments in Los Angeles and New York metro areas. Target straw-based silicone designs for orthodontic positioning in United States and United Kingdom markets where pediatric dental endorsement drives conversion. White-space exists in stainless steel end-of-life recovery programs aligned with EU extended producer responsibility mandates. For Investors and Strategic Acquirers: Re-rating potential sits with clinically credentialed brands given hospital-recommended heritage extension into home-use categories. Long-term viability favors platforms with diversified silicone-metal architectures over pure-play plastic dependencies. Monitor ECHA substance restriction announcements as inflection signal for material platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital Discharge Gifting Partnership | Captive introduction to new parents during 0-6 month transition window locks in brand loyalty. |
| Silicone Component Subscription Model | Recurring revenue from straw and valve replacement kits extends customer lifetime value beyond hardware. |
| Cleanroom Assembly Certification Investment | ISO 14644 Class 8 qualification constrains contract manufacturer selection and extends facility timelines. |
| REACH-Compliant Material Platform Shift | ECHA-validated declarations filter pharmacy shelf placement toward silicone and stainless steel architectures. |
| Extended Producer Responsibility Program | EU packaging waste take-back mandates favor durable metal platforms with end-of-life recovery value. |
Research Methodology
Document review covered FDA 21 CFR 177 filings, ECHA REACH substance registrations, and customs trade records, complemented by interviews with brand managers at infant care manufacturers, category buyers at pharmacy and mass retail channels, supply planners at molding contractors, and regulatory affairs specialists at testing laboratories. Secondary validation drew from Nielsen retail audit data, hospital procurement databases, and SEC filings of publicly traded parent companies. Bottom-up unit volume modeling triangulated against top-down market sizing from trade association estimates.
Historical shipment patterns cross-referenced against expert panel input on REACH implementation timelines and silicone price trajectory assumptions. Segmentation dimensions modeled include material platform, age group developmental stage, design feature mechanics, and distribution channel type across the analysis window. CAGRs derived from regression against pediatric birth rate projections, premium channel penetration curves, and replacement purchase frequency by material durability tier. Industry-specific inputs incorporated dental association clinical guideline adoption rates and social commerce conversion benchmarks.
The model holds under stable regulatory enforcement intensity and freight rate normalization; deviation in ECHA substance restriction scope or Guangdong port congestion would shift volume and value outputs. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Nose Suckers Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Wet Wipes Market
Baby Products
Baby Shoes Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Diaper Pails Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
Baby High Chair Market
Baby Products
Baby Walker Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Baby Feeding Bottles Market
Baby Products
North America Baby Bottle Market
Baby Products
Postpartum Products Market
Baby Products
Automatic Baby Swing Market
Baby Products
Baby Bedding Market