
 Baby Bath Products Market | 2026-2036
Baby Bath Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Bath Products Market Outlook
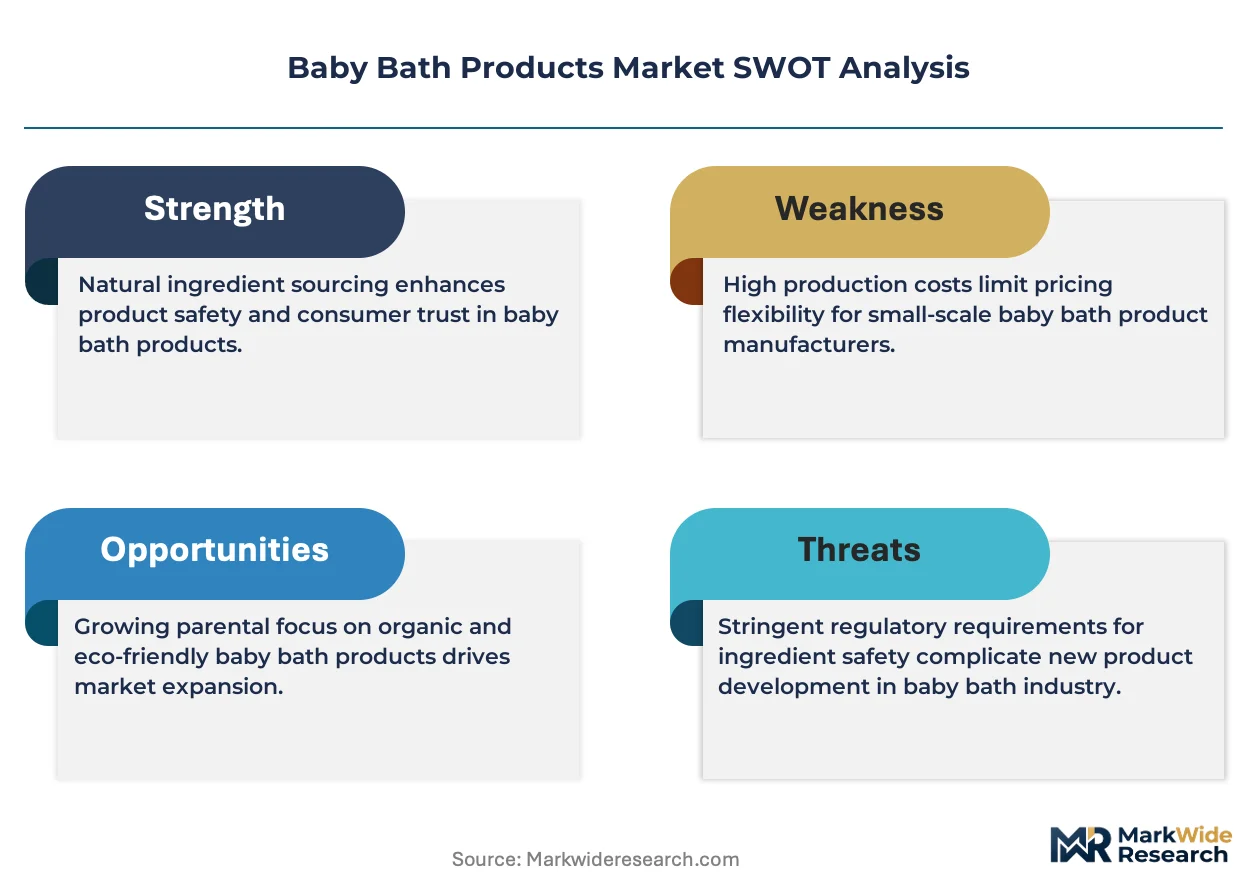
Premium organic certification is unwinding conventional commodity positioning across the baby bath category. Johnson & Johnson leverages its clinical heritage to sustain trust in hospital-delivery channels. Pigeon Corporation anchors its competitive position through deep specialization in Asian newborn care rituals. Beiersdorf differentiates via dermatological testing protocols that command shelf space in European pharmacy networks.
Baby bath products comprise cleansers, conditioners, and skin treatments formulated with pH-balanced surfactants typically below 5.5 acidity, designed to maintain infant epidermal barrier integrity during repeated washing cycles. Shampoos and washes dominate volume throughput, while organic and hypoallergenic formulations capture disproportionate margin pools as ingredient transparency becomes a non-negotiable purchase filter. Online retail channels are accelerating fastest, though pharmacies retain pricing power in markets where pediatric recommendation drives trial.
EU REACH and the FDA's cosmetic ingredient scrutiny shape permissible preservative systems and labeling claims across export markets. ECHA's evolving restrictions on sensitizing fragrances force continuous reformulation cycles that favor R&D-capable multinationals over regional assemblers. Stakeholders must monitor regulatory divergence between the EU Green Deal chemical phase-outs and state-level clean beauty legislation in the United States to anticipate compliance cost asymmetries that will reshape competitive fielding.
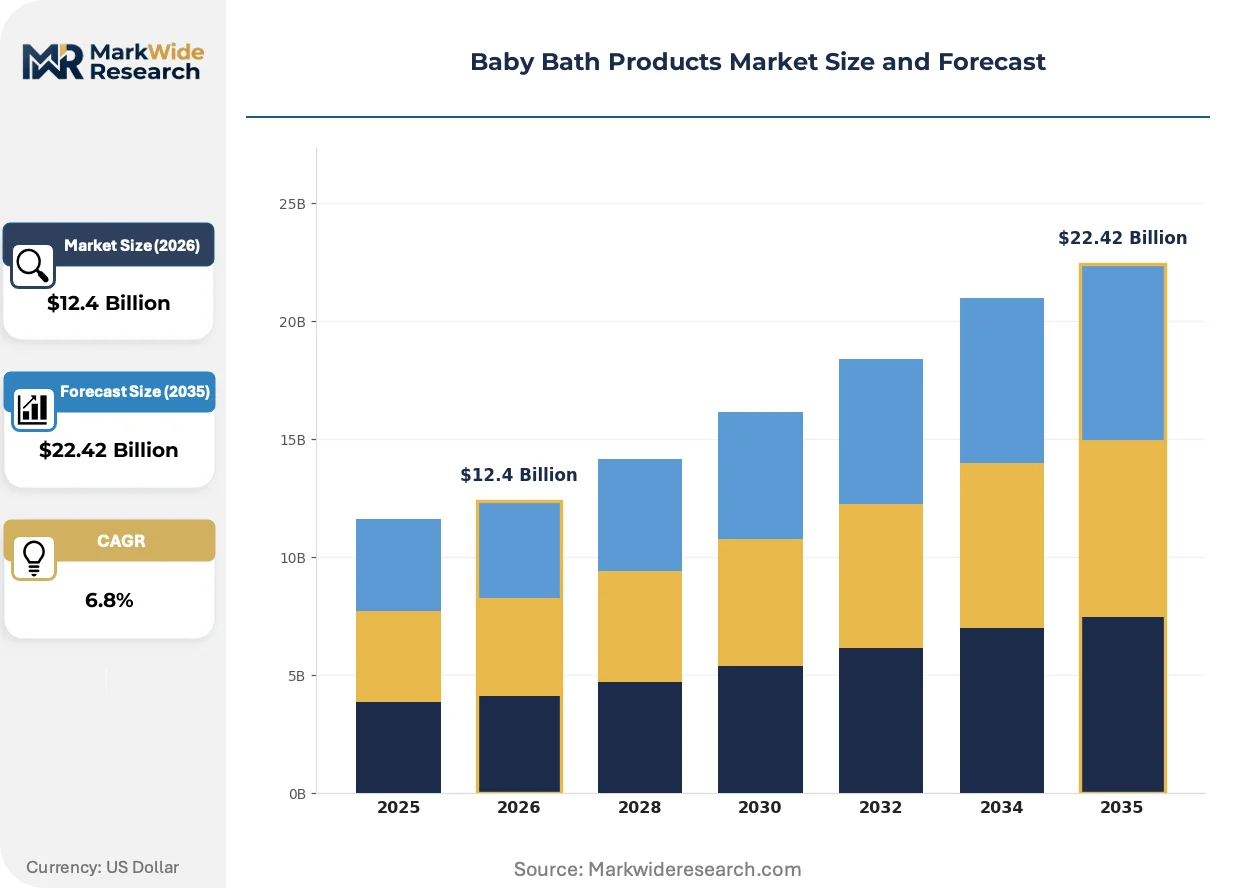
Market Dynamics
Clean-label ingredient mandates and pH-balanced surfactant chemistry are compressing legacy formulation cycles while rewarding R&D-capable manufacturers with pharmacy and hospital channel access.
Growth Catalysts
- EU REACH chemical phase-outs:ECHA restrictions on sensitizing fragrances force continuous reformulation that advantages established laboratories with dedicated toxicology teams.
- Hospital-delivery channel expansion:Clinical endorsement at birth creates lifetime brand attachment, with pediatric recommendation driving trial in maternity wards across Germany, China, and the United States.
- Plant-derived surfactant chemistry:Alkyl polyglucoside and amino acid-based cleansers replace sulfates in premium positioning, capturing disproportionate margin pools through organic certification premiums.
Market Restraints
- Raw material concentration:Coconut-derived feedstock supply concentrates in Southeast Asian processing clusters, exposing margin structures to weather volatility and shipping lane disruption.
- Preservative system limitations:ECHA's evolving restrictions on formaldehyde-releasers and isothiazolinones eliminate cost-effective preservation options, forcing expensive natural alternative sourcing.
- Substitution threat from multifunctional products:All-in-one hair-and-body washes compress unit volume potential in the shampoo segment as parents simplify routines.
Strategic Opportunities
- Clean beauty legislation tailwinds:State-level ingredient disclosure mandates in California and New York create first-mover advantage for brands with pre-built transparency infrastructure.
- Subscription replenishment models:Direct-to-consumer auto-ship programs capture predictable recurring revenue while bypassing retail slotting fee structures.
- Asian newborn care ritual specialization:Post-bath oil massage traditions in India and Southeast Asia open adjacent skin treatment categories beyond basic cleansing.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient stability and infant skin tolerance commands premium compensation, constraining mid-tier brand R&D scaling.
- Dual certification timeline compression:Simultaneous pursuit of COSMOS organic and National Eczema Association seals requires parallel toxicology studies, extending launch windows.
- Legacy ERP integration friction:Batch-level ingredient traceability systems for EU Digital Product Passport compliance clash with decades-old manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Bath Products Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Soaps, Washes, Moisturizers Formulation: Organic, Hypoallergenic, Fragrance-Free, Natural Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Target Age Group: Infants, Toddlers, Newborns, Children |
| Companies Covered | Beiersdorf, Pigeon Corporation, Johnson & Johnson, Kao Corporation, Kimberly-Clark, Procter & Gamble, Artsana, Colgate-Palmolive, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Bath Products Market Strategic Shifts
Biotechnology-derived emollients and waterless formulation formats are disrupting conventional liquid-dominant packaging while regulatory transparency mandates reshape competitive moats around disclosure infrastructure.
Biotechnology-derived squalane and fermented ceramides are fragmenting petroleum-based emollient supply chains. Premium organic brands adopt these ingredients fastest, compressing synthetic positioning to mass-market tiers. The technology is fragmenting supplier relationships as biotech fermentation capacity concentrates with specialty chemical houses.
ECHA's Digital Product Passport requirements under the EU Green Deal force granular ingredient disclosure down to parts-per-million contaminants. Manufacturers must rebuild labeling systems and supplier audit protocols. European pharmacy networks and export-oriented brands face the steepest compliance cost curves.
Parents now conduct ingredient database cross-checks via smartphone in retail aisles, bypassing traditional marketing claims. This verification behavior concentrates purchase decisions in channels with searchable digital transparency—specialty retailers and brand-direct sites—while eroding trust in opaque mass-market labeling. The shift is most pronounced among Millennial and Gen Z buyers in urban United States and German markets.
Baby Bath Products Market Segmentation
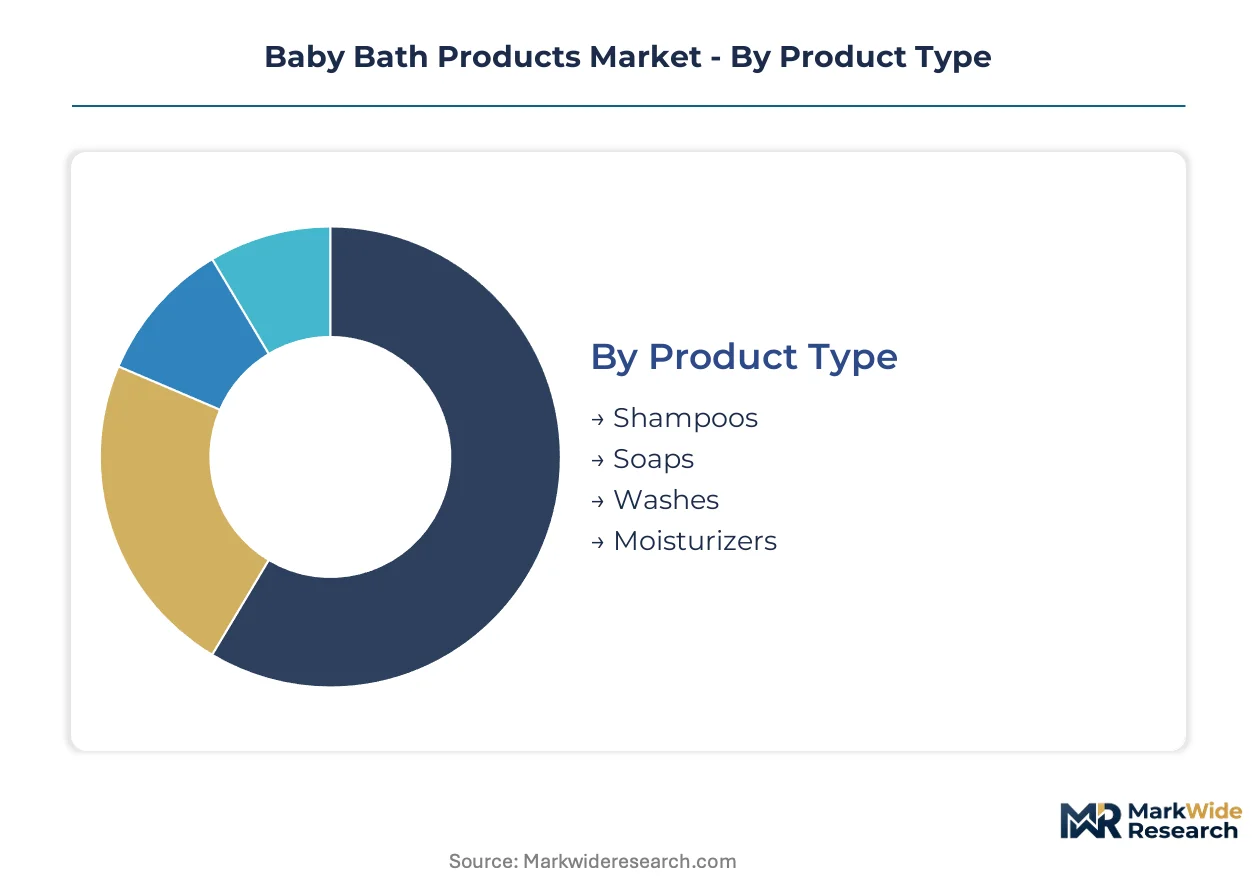
Segmentation in baby bath products reveals how formulation chemistry and channel access determine margin capture. Distinct age-specific needs and regulatory exposure across geographies reshape competitive positioning within each category.
Product Type:
Shampoos and washes concentrate manufacturing in domestic facilities serving hospital-delivery networks, while soaps and moisturizers increasingly source from export-oriented organic processors in Southeast Asia and Southern Europe.
- Shampoos:Mild surfactant systems with tear-free pH buffering below 5.5 acidity. Demand clusters in United States maternity wards and German pharmacy networks where pediatric endorsement drives trial. ECHA fragrance restrictions force continuous reformulation cycles.
- Washes:Multifunctional hair-and-body formulations simplify parent routines. Volume concentrates in Chinese e-commerce channels and Indian urban retail, though all-in-one positioning compresses unit pricing versus dedicated shampoos.
- Soaps:Bar formats retain traction in price-sensitive Indian and Southeast Asian markets. Cold-process artisan production concentrates in Kerala and Bali export clusters.
- Moisturizers:Post-bath emollients command premium positioning through biotech-derived ceramide and squalane content. Post-bath oil massage traditions in India and Indonesia expand addressable category scope.
Washes command the established base. The steepest expansion runs through moisturizers.
Formulation:
Cost tier stratification separates premium-certified organic from mass-market natural positioning, with hypoallergenic and fragrance-free occupying mid-tier pharmacy channels.
- Organic:COSMOS or USDA-certified formulations with alkyl polyglucoside surfactants and plant-derived preservatives. Millennial parents in United States coastal cities and German urban centers drive disproportionate margin capture through subscription channels.
- Hypoallergenic:Dermatologically tested protocols with National Eczema Association seals. Pharmacy networks in France, Germany, and Switzerland anchor distribution where pediatric recommendation influences purchase.
- Fragrance-Free:Elimination of all sensitizing aromatic compounds per ECHA guidance. Regulatory compliance costs favor R&D-capable multinationals over regional assemblers.
- Natural:Uncertified botanical positioning without synthetic surfactants. Price competition intensifies as clean-label claims proliferate without third-party verification.
Natural formulations command the established base. The steepest expansion runs through organic certification tiers.
Distribution Channel:
Volume throughput concentrates in high-frequency retail, while margin extraction shifts toward channels with searchable digital transparency infrastructure.
- Online Retail:Direct-to-consumer auto-ship models and marketplace storefronts with batch-level ingredient disclosure. Millennial and Gen Z parents in United States and German markets conduct smartphone cross-checks of EWG and ECHA databases before purchase.
- Supermarkets:Mass-market placement with slotting fee structures that disadvantage emerging brands. Shelf space concentrates in Walmart, Carrefour, and Tesco networks across United States, France, and United Kingdom.
- Pharmacies:European pharmacy networks in Germany, France, and Italy retain pricing power through pediatric recommendation and dermatological endorsement. EMA-aligned regulatory familiarity shapes permissible claims.
- Specialty Stores:Curated assortments with staff training on infant skin barrier science. Premium positioning in urban United States boutiques and Japanese department store baby floors.
Supermarkets command the established base. The steepest expansion runs through online retail.
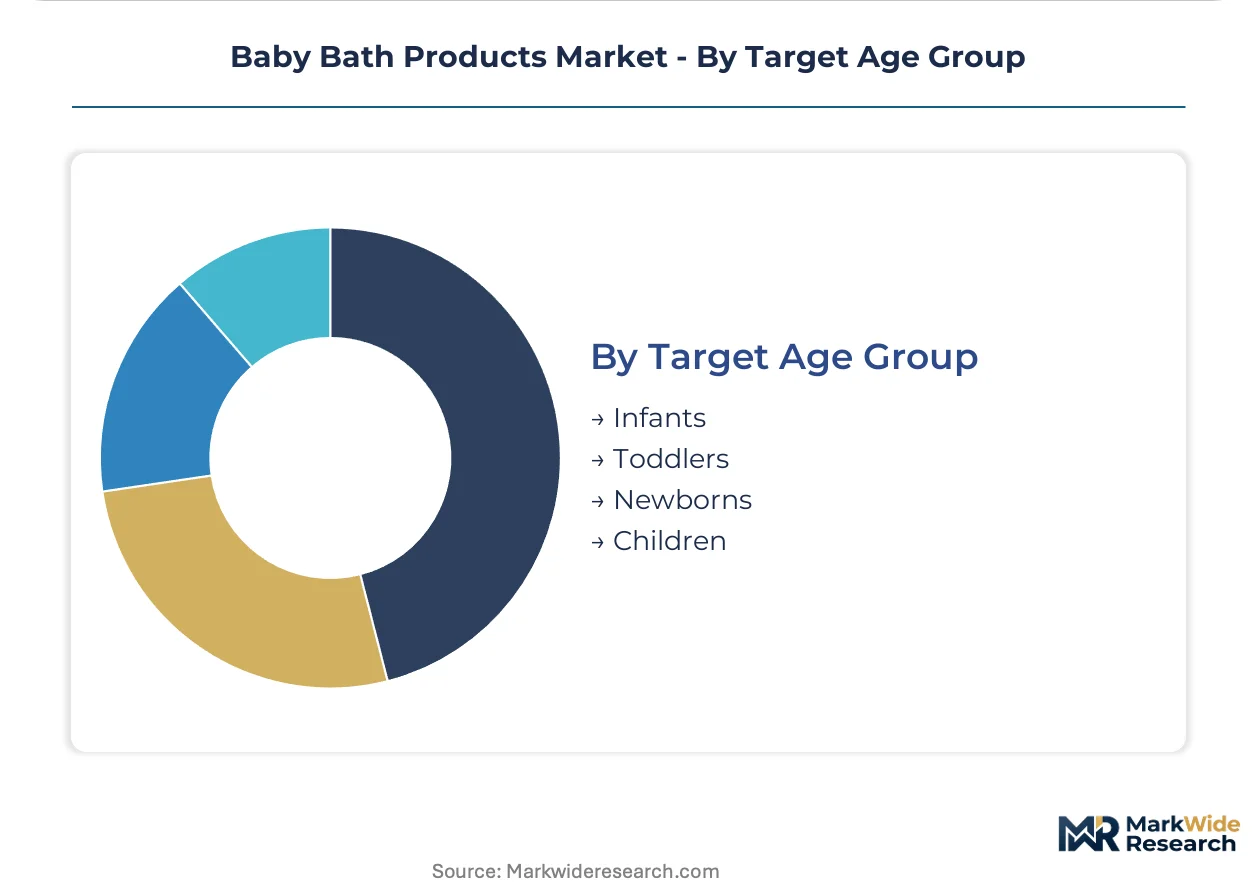
Target Age Group:
Application intensity varies by epidermal barrier maturity, with newborn-specific formulations commanding premium positioning through hospital-delivery channel access.
- Newborns:First-month formulations with extreme pH buffering and zero fragrance tolerance. Hospital-delivery sampling in United States, China, and Germany creates lifetime brand attachment.
- Infants:Zero-to-twelve-month cleansers balancing mildness with cleansing efficacy. Volume concentrates in first-time parent demographics with highest trial spending.
- Toddlers:Twelve-to-thirty-six-month transition products with playful packaging and mild conditioning. Repeat purchase frequency peaks as bathing routines stabilize.
- Children:Three-plus year formulations approaching adult surfactant chemistry with retained mildness claims. Price compression intensifies as parents substitute family products.
Infant formulations command the established base. The steepest expansion runs through newborn-specific positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut-derived surfactant feedstock concentrates in Southeast Asian processing clusters, exposing finished goods pricing to weather volatility and shipping lane disruption across export corridors. Hospital-delivery sampling networks and pharmacy endorsement systems concentrate demand generation in three distinct regulatory environments.
United States
Millennial parents in coastal cities drive organic formulation demand through subscription auto-ship models. FDA cosmetic ingredient scrutiny and state-level clean beauty legislation in California and New York reshape permissible preservative systems. New Jersey and Illinois manufacturing clusters supply hospital-delivery sampling programs that create lifetime brand attachment at birth.
China
Zero-to-twelve-month infant demographics concentrate volume in e-commerce channels with livestream commerce integration. NMPA cosmetic registration requirements and GB standards for infant products enforce pH and surfactant specifications. Guangdong and Zhejiang processing hubs dominate alkyl polyglucoside surfactant finishing for domestic brands and export markets.
Germany
Pharmacy network pricing power persists through pediatric recommendation and dermatological endorsement cultures. ECHA REACH restrictions on sensitizing fragrances force continuous reformulation cycles that favor R&D-capable laboratories. North Rhine-Westphalia chemical processing infrastructure supports COSMOS-certified organic production for European distribution.
India
Post-bath oil massage traditions expand addressable category scope beyond basic cleansing into adjacent skin treatment segments. FSSAI cosmetic safety standards and BIS labeling requirements govern infant product claims. Kerala cold-process artisan clusters and Mumbai formulation houses serve domestic price tiers and Gulf export markets.
Japan
Newborn care ritual specialization anchors premium positioning through department store baby floor channels. PMDA quasi-drug classification for medicated bath products creates regulatory moats around barrier-repair formulations. Osaka and Tokyo metropolitan areas concentrate specialty retail with staff training on infant epidermal science.
Baby Bath Products Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the baby bath category. Consolidated multinational presence in hospital-delivery and pharmacy channels coexists with fragmented artisan production in regional organic clusters. Three archetypes dominate: clinical heritage brands with toxicology infrastructure, Asian ritual specialists with newborn care expertise, and biotech-enabled clean beauty entrants with fermentation-derived emollient supply chains. M&A activity targets COSMOS-certified organic processors, while capacity expansion concentrates in Southeast Asian surfactant feedstock zones.
Within the clinical heritage tier, Johnson & Johnson and Beiersdorf occupy positions anchored by hospital-delivery channel access and dermatological testing protocols. Pigeon Corporation exemplifies the Asian ritual specialist archetype through deep specialization in newborn care practices. Kao Corporation represents scale-driven formulation capability spanning premium and mass-market positioning. These three anchors illustrate how channel access, regulatory compliance infrastructure, and cultural product-market fit separate sustainable competitive position from commodity substitution risk.
| Leading Market Players |
|---|
| Beiersdorf |
| Pigeon Corporation |
| Johnson & Johnson |
| Kao Corporation |
| Kimberly-Clark |
| Procter & Gamble |
| Artsana |
| Colgate-Palmolive |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Alkyl polyglucoside surfactants displacing sodium lauryl sulfate in premium formulations are rerouting procurement toward Southeast Asian coconut processing clusters while inflating raw material premiums against petroleum-based alternatives. This substitution dynamic concentrates cost leverage with plantation operators in Indonesia and the Philippines while forcing reformulation investments that compress margins at mid-tier brands.
Pricing Analysis
EU REACH dictates the pricing tier structure across export corridors, with fragrance-free and COSMOS-certified organic formulations commanding pharmacy premiums while mass-market natural positioning erodes under uncertified competition. Three-tier pricing separates dermatologically endorsed pharmacy products from supermarket natural claims from economy bar soaps. Price compression runs through the natural tier as clean-label claims proliferate without third-party verification. Millennial parents in subscription channels show lowest price sensitivity; Indian mass-market buyers exhibit highest.
Supply Chain Analysis
Port congestion at Singapore and Tanjung Pelepas is extending lead times for coconut-derived feedstock shipments to European and North American finishing facilities. Manufacturing concentrates in Indonesia, Malaysia, and Thailand for surfactant feedstock, with Germany and the United States hosting formulation and packaging. Supply chains rest on monsoon-dependent plantation yields and single-source alkyl polyglucoside processors. Distribution runs through hospital-delivery sampling networks for newborn trial, pharmacy networks for pediatric endorsement, and direct-to-consumer auto-ship for recurring replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Millennial and Gen Z parents who conduct smartphone ingredient verification before purchase, fragmenting traditional retail channel influence and elevating transparency infrastructure as the decisive competitive filter.
For Market Incumbents: Fortify hospital-delivery channel control through exclusive maternity ward sampling contracts that create lifetime brand attachment at birth. Deepen toxicology infrastructure investments to absorb ECHA reformulation cycles that regional assemblers cannot match. Capture pediatric recommendation networks in German and French pharmacy systems before biotech-enabled clean beauty entrants build comparable endorsement relationships. For New Entrants and Emerging Players: Lead with subscription auto-ship models targeting United States coastal cities where Millennial parents prioritize batch-level ingredient disclosure over mass-market availability. Penetrate the post-bath oil massage segment in Indian and Indonesian markets where incumbent coverage remains thin. Deploy direct-to-consumer transparency infrastructure with EWG and ECHA database integration to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors COSMOS-certified organic processors with established Southeast Asian surfactant supply relationships. Long-term viability hinges on regulatory compliance infrastructure capable of absorbing EU Digital Product Passport and state-level clean beauty disclosure mandates. Watch ECHA fragrance restriction expansion timelines as the signal for accelerated M&A activity targeting reformulation-capable laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| COSMOS Organic Certification Investment | Secures pharmacy shelf access in EMA-aligned European markets against uncertified competitors. |
| Hospital-Delivery Sampling Expansion | Creates lifetime brand attachment through pediatric endorsement at birth in United States and German maternity wards. |
| Biotech Emollient Supply Agreement | Locks in fermented ceramide and squalane capacity ahead of petroleum-based emollient displacement. |
| Direct-to-Consumer Transparency Platform | Captures Millennial verification behavior with batch-level ingredient disclosure bypassing opaque retail labeling. |
| Southeast Asian Surfactant Integration | Secures captive alkyl polyglucoside supply from Indonesian and Malaysian processing clusters. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at multinational consumer goods companies, category buyers at pharmacy and supermarket retailers, cosmetic chemists at formulation houses, and supply planners at surfactant processors, then refined against secondary validation from ECHA restriction databases, FDA cosmetic ingredient guidance, Nielsen retail audit data, and customs trade records. Bottom-up demand modeling across distribution channels triangulated with top-down market sizing from production capacity disclosures.
Variance decomposition across product type, formulation certification tier, distribution channel, and target age group enabled segment-level growth attribution throughout the forecast period. CAGRs were derived from regression analysis against demographic birth rate projections and channel shift elasticity parameters. Industry-specific inputs included ECHA regulatory timeline assumptions and coconut oil price volatility indices from plantation yield data.
Underlying assumptions cover stable EU REACH enforcement trajectory and continued Millennial preference for ingredient transparency, with deviation risk concentrated in regulatory acceleration or trade lane disruption affecting Southeast Asian surfactant feedstock. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Electric Nail Files Market
Consumer Goods
Pet Sitting Market
Consumer Goods
Baby Swaddle Wrap Market
Consumer Goods
White Sneakers Market
Consumer Goods
Asia-Pacific Mobile Phone Accessories Market
Consumer Goods
Kid Footwear Market
Consumer Goods
UV Nail Gel Market
Consumer Goods
Erotic Lingerie Market
Consumer Goods
Virgin Leather Market
Consumer Goods
Temperature Controlled Mug Market
Consumer Goods
United Kingdom Handheld Vacuum Cleaners Market
Consumer Goods
Beauty Oils Market
Consumer Goods
Aquarium Heaters and Chillers Market
Consumer Goods
Toilet Care Wipes Market
Consumer Goods
Book Light Market
Consumer Goods
Smart Connected Diaper Market