
 Mens Grooming Appliances Market | 2026-2036
Mens Grooming Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Mens Grooming Appliances Market Foresight
The R&D-to-manufacturing capability gap between established appliance conglomerates and emerging electronics specialists is redrawing competitive boundaries in mens grooming appliances. Koninklijke Philips N.V. leverages integrated blade-motor ecosystems to sustain premium positioning across cordless and wet-and-dry platforms. Panasonic Corporation anchors its position through ceramic blade metallurgy and precision motor control systems developed for professional barber channels. Xiaomi competes on aggressive cost engineering and direct-to-consumer distribution, extending its smartphone supply chain advantages into personal care electronics.
Mens grooming appliances encompass electrically powered devices engineered for hair reduction, facial hair sculpting, and scalp grooming, typically operating via rotary or linear drive motors at frequencies between 10,000 and 14,000 cycles per minute with stainless steel, titanium, or ceramic cutting surfaces. These devices serve both consumer bathroom routines and professional salon workflows where runtime reliability and hygiene sterilization compatibility determine commercial viability. Electric razors and beard trimmers command the largest revenue pools due to replacement blade cycles and battery degradation-driven repurchase patterns, while hair clippers targeted at barbers and salons generate superior per-unit margins through all-metal construction and extended warranty terms. The cordless technology segment is gaining structural momentum as lithium-ion energy density improvements enable 60-minute runtime thresholds that satisfy professional shift requirements.
FDA oversight governs laser-based hair removal devices marketed in the United States, requiring 510(k) clearance that elevates development costs and extends commercialization timelines for manufacturers incorporating intense pulsed light or diode laser technologies. The EU REACH regulation and F-Gas Directive constrain refrigerant-based cooling systems in high-end laser appliances, while CE marking mandates electromagnetic compatibility testing for all mains-connected and rechargeable grooming devices sold across European member states. Stakeholders must monitor evolving battery transportation regulations and right-to-repair legislative proposals that threaten sealed-unit designs and proprietary blade attachment systems.
Market Dynamics
The cordless lithium-ion transition is redrawing competitive boundaries in mens grooming appliances, as 60-minute runtime thresholds become the baseline for professional channel acceptance and consumer premium positioning.
Growth Catalysts
- EU Ecodesign Directive:Motor efficiency mandates are accelerating brushless DC motor adoption, forcing incumbents to redesign drive systems and creating upgrade cycles across European distribution channels.
- Ceramic blade metallurgy:Professional barber channels in Japan and South Korea are specifying zirconia-based cutting surfaces for sterilization compatibility, pulling manufacturers toward higher-margin precision engineering.
- Urban millennial grooming routines:Multi-step facial hair sculpting regimens in dense metropolitan clusters are expanding SKU breadth for specialized trimmer attachments and modular blade ecosystems.
Market Restraints
- Lithium cobalt oxide price volatility:Battery chemistry cost swings compress margin predictability for cordless platforms, particularly affecting mid-tier manufacturers without long-term cathode supply agreements.
- Guangdong-Shenzhen manufacturing concentration:Domestic Chinese supply chain dominance creates geopolitical exposure and tariff vulnerability for brands dependent on single-source assembly.
- FDA 510(k) clearance timelines:Laser-based hair removal devices face 18-24 month regulatory pathways that freeze R&D amortization and delay revenue recognition for photonics-integrated appliances.
Strategic Opportunities
- Right-to-repair legislative momentum:EU and select US state proposals threatening sealed-unit designs create openings for modular architecture specialists to capture sustainability-conscious professional buyers.
- Telemedicine-integrated dermatology:Connected grooming devices with skin-sensor feedback loops align with remote diagnostic reimbursement codes in Germany and the Netherlands.
- India tier-2 urbanization:Domestic manufacturing incentives under the PLI scheme and expanding modern trade penetration in cities like Pune and Ahmedabad enable localized cost structures for battery-operated entry segments.
Industry Challenges
- Electromagnetic compatibility certification:CE marking requirements for mains-connected and rechargeable devices demand specialized testing infrastructure that smaller electronics specialists struggle to access.
- Blade-motor ecosystem IP fragmentation:Proprietary attachment systems and drive frequency patents create licensing complexity for cross-platform compatibility initiatives.
- Professional channel technical support scaling:Barber and salon warranty service networks require trained technician density that direct-to-consumer brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mens Grooming Appliances Market |
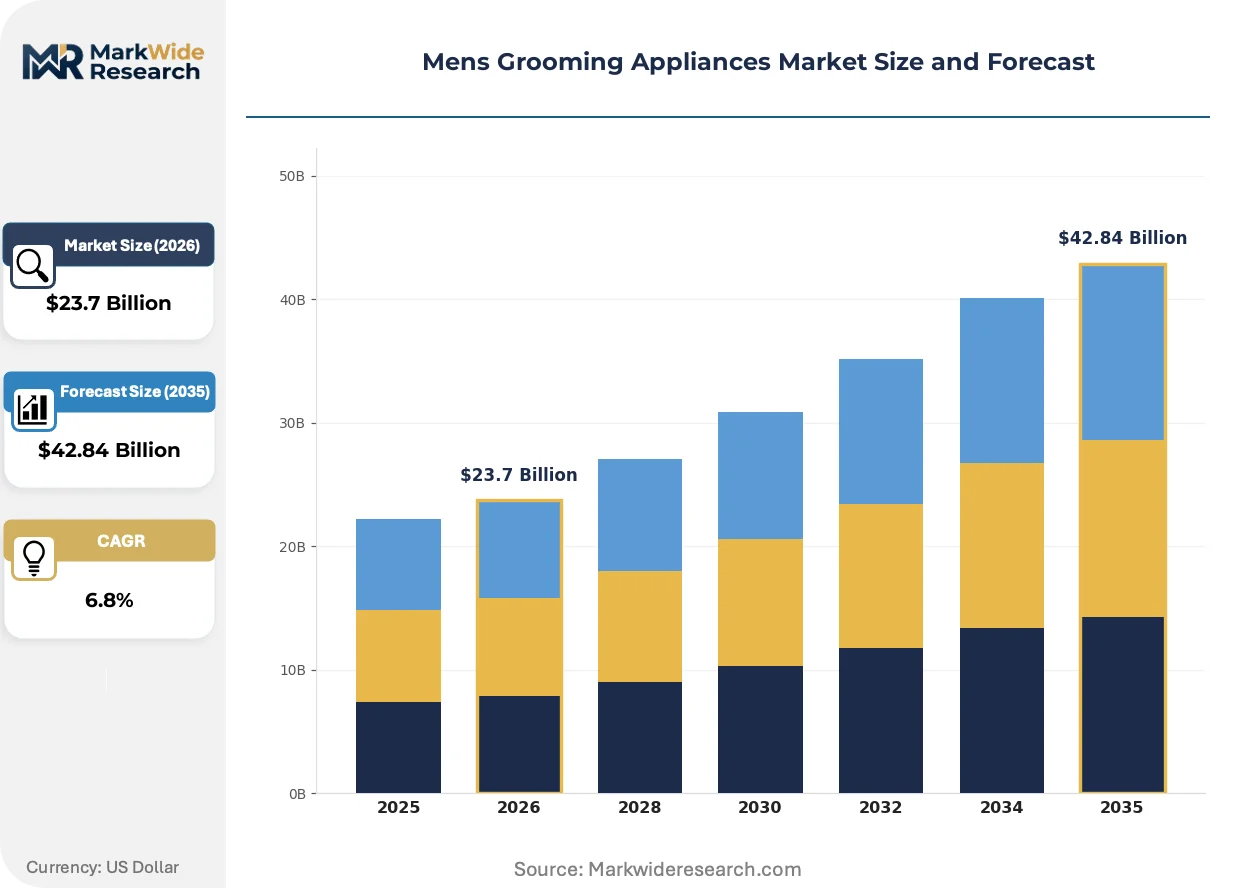
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Razors, Hair Clippers, Beard Trimmers, Shavers End User: Consumers, Salons, Barbers, Retailers Technology: Cordless, Rechargeable, Wet&Dry, Laser Feature: Waterproof, Ergonomic Design, Quick Charge, Self-Sharpening |
| Companies Covered | Koninklijke Philips N.V., Panasonic Corporation, Procter and Gamble Company, Wahl Clipper Corporation, Spectrum Brands Holdings, Inc., Xiaomi, Flyco, Midea, Braun GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mens Grooming Appliances Market Shifts & Advancements
Active materials science and regulatory chemistry constraints are converging to reshape product architecture, with sustainability mandates and professional durability requirements pulling development in parallel directions.
Linear drive motor systems operating at 14,000 cycles per minute are supplanting traditional rotary mechanisms in premium wet-and-dry platforms. Professional barber cooperatives in Spain and Italy are specifying these systems for reduced skin irritation during extended shift use. The shift is compressing aftermarket blade replacement revenue models while enabling higher upfront equipment pricing.
REACH regulation constraints on nickel and chromium release rates are forcing blade alloy reformulation across European-bound product lines. Manufacturers are substituting titanium-nitride coatings and solid ceramic inserts to maintain cutting performance under tightened material safety thresholds. Wet-shave compatible trimmers with full immersion ratings face the steepest compliance redesign costs.
Subscription-based blade replenishment programs are capturing recurring revenue from digitally native consumer segments. Direct-to-consumer channels in the United States and United Kingdom are displacing traditional retail attachment sales with automated replenishment algorithms tied to usage telemetry. Professional salon procurement remains resistant to this model due to bulk purchasing leverage and distributor credit terms.
Mens Grooming Appliances Market Segmentation
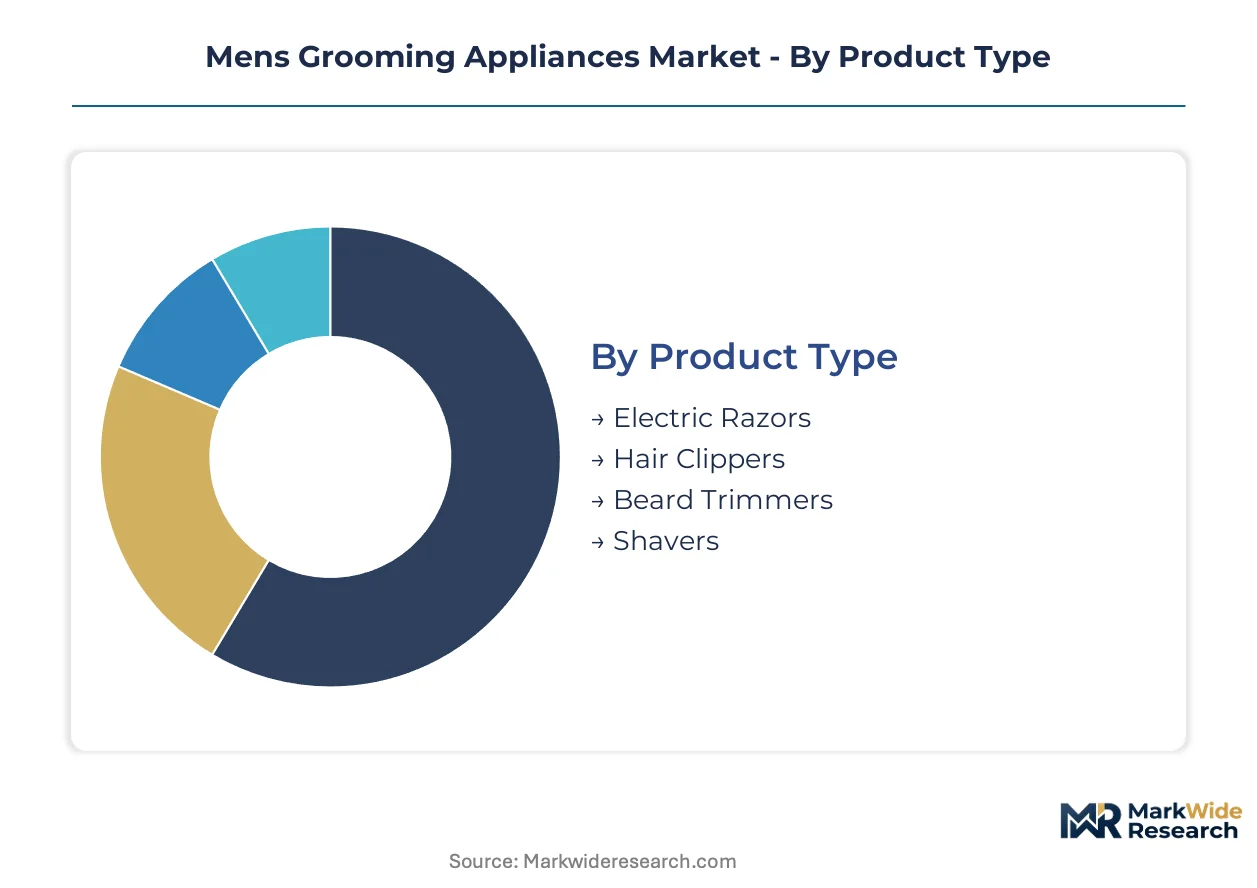
Segmentation in mens grooming appliances reveals how substitution pressures from manual grooming tools and professional services reshape demand across product categories. Understanding these fault lines exposes where electrification delivers irreplaceable value versus where price-sensitive consumers revert to traditional alternatives.
Product Type:
Substitution pressure from manual razors and salon services concentrates most intensely on entry-level electric devices, while professional-grade equipment demonstrates stronger retention against human barber alternatives.
- Electric Razors:Rotary and foil systems operating at 10,000-14,000 cycles per minute with stainless steel or titanium cutting surfaces. Demand clusters among urban commuters in China and Germany where water-free operation supports on-the-go grooming routines, though cartridge razor subscription models erode entry-tier electric adoption.
- Hair Clippers:Professional-grade units with brushless DC motors and all-metal construction designed for continuous salon shift operation. Barber cooperatives in Spain and Italy specify these for reduced wrist fatigue during extended use, with sterilization compatibility requirements under EU REACH regulation pulling alloy reformulation toward titanium-nitride coatings.
- Beard Trimmers:Modular attachment systems for facial hair sculpting with precision guards.
- Shavers:Wet-and-dry platforms with full immersion ratings for shower-compatible operation.
Electric razors anchor the volume base while hair clippers gain share at the steepest rate.
End User:
Cost tier differentiation separates mass-market bathroom routines from commercial procurement patterns where per-unit margins expand through warranty terms and technical support bundling.
- Consumers:Individual purchasers prioritizing cordless convenience and quick-charge capability for intermittent home use. Direct-to-consumer channels in the United States and United Kingdom displace retail attachment sales through subscription blade replenishment algorithms.
- Barbers:Independent professionals and cooperative networks requiring 60-minute runtime thresholds and sterilization-compatible construction. REACH regulation constraints on nickel release rates force blade alloy reformulation for European-bound equipment.
- Salons:Commercial establishments with bulk purchasing leverage and distributor credit terms resistant to automated replenishment models.
- Retailers:Inventory aggregators managing seasonal demand fluctuations and private-label sourcing from Guangdong-Shenzhen manufacturing clusters.
Consumer demand anchors the volume base while barber procurement gains share at the steepest rate.
Technology:
Volume concentration in cordless lithium-ion platforms reflects professional runtime requirements and consumer mobility expectations, with legacy corded designs retreating to price-sensitive fringe segments.
- Cordless:Lithium-ion powered platforms achieving 60-minute runtime thresholds through energy density improvements. Professional channel acceptance in Japan and South Korea specifies these for shift-length reliability, though cobalt price volatility compresses margin predictability for mid-tier manufacturers.
- Rechargeable:Nickel-metal hydride and early lithium-ion systems with shorter cycle life and reduced runtime performance.
- Wet&Dry:Sealed-unit designs with full immersion ratings for shower and sink operation, facing steepest compliance redesign costs under tightened material safety thresholds.
- Laser:Intense pulsed light and diode laser systems for hair removal requiring FDA 510(k) clearance in the United States, with 18-24 month regulatory pathways freezing R&D amortization.
Cordless platforms anchor the volume base while laser systems expand most quickly among dermatology-integrated applications.
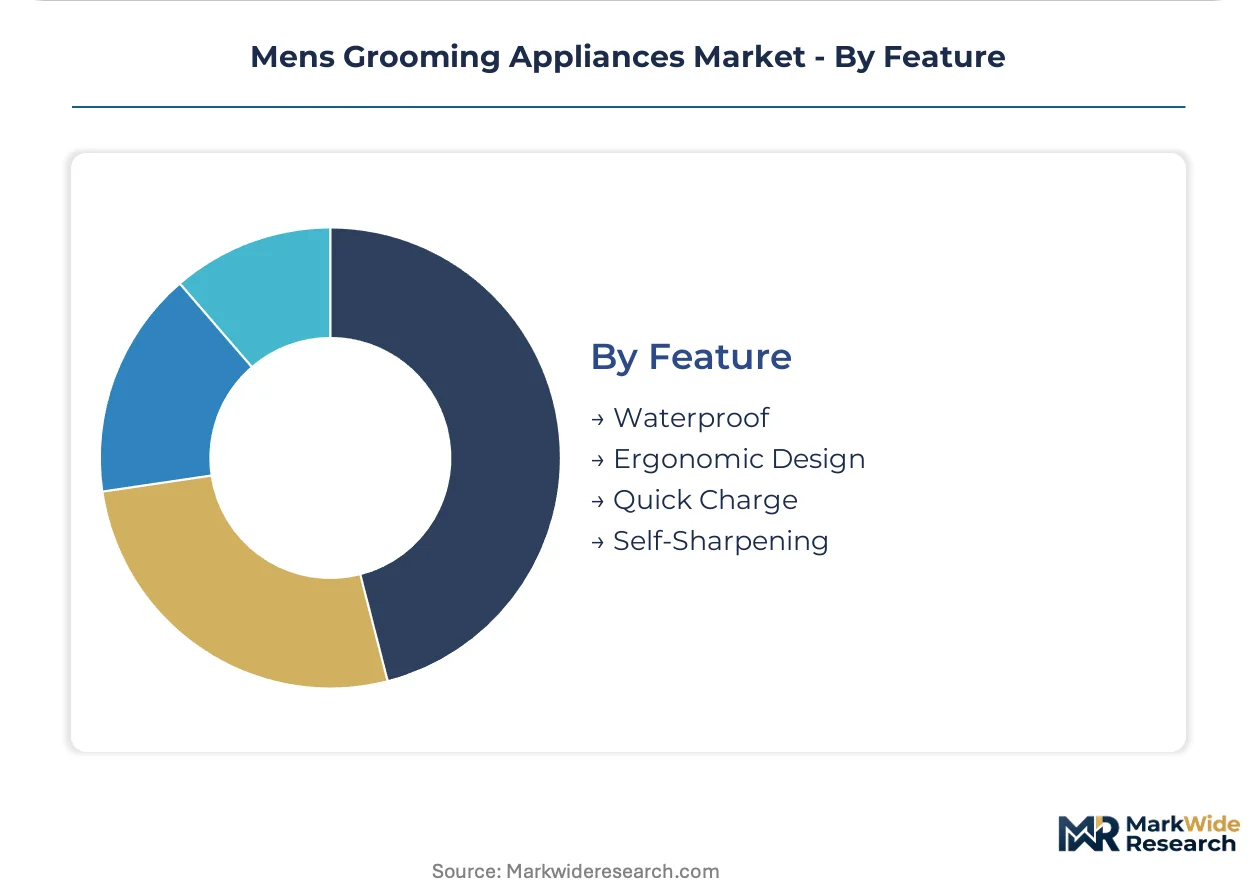
Feature:
Application context determines feature premiumization, with waterproofing commanding universal baseline status while ergonomic differentiation targets professional repetitive-use scenarios.
- Waterproof:IPX7-rated sealing for full immersion and rinse-clean maintenance, now standard across mid-tier and premium positioning rather than differentiating factor.
- Ergonomic Design:Weight distribution and grip geometry optimized for barber shift-length operation without repetitive strain. Professional cooperatives in Italy specify these configurations, with design IP creating licensing complexity for cross-platform compatibility.
- Quick Charge:Five-minute emergency charging for consumer convenience scenarios.
- Self-Sharpening:Blade systems with automated maintenance reducing replacement frequency and aftermarket revenue.
Waterproof capability anchors the volume base while ergonomic design gains share at the steepest rate among professional channel specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and Japan where professional channel specifications justify equipment premiums, while mass-market volume aggregates in China where domestic manufacturing clusters compress unit economics.
China
Guangdong-Shenzhen manufacturing corridors supply global OEM demand through vertically integrated electronics ecosystems. MIIT energy efficiency standards for small appliances are accelerating brushless DC motor adoption across export-bound production lines. Domestic e-commerce penetration in tier-1 cities like Shanghai and Beijing is displacing traditional retail distribution for cordless platforms.
Germany
Professional barber cooperatives in Munich and Hamburg specify 60-minute runtime thresholds and sterilization-compatible construction for shift-length reliability. EU REACH regulation constraints on nickel release rates are forcing blade alloy reformulation for European-bound equipment. The Mittelstand engineering base around Solingen maintains cutting-tool metallurgy expertise that feeds precision blade supply chains.
United States
FDA 510(k) clearance requirements for laser-based hair removal devices create 18-24 month regulatory pathways that freeze R&D amortization for photonics-integrated appliances. Direct-to-consumer subscription blade replenishment models in California and New York are displacing traditional retail attachment sales. The FCC governs electromagnetic compatibility testing for all rechargeable grooming devices sold through interstate commerce.
Japan
Professional barber channels in Tokyo and Osaka specify zirconia-based ceramic cutting surfaces for sterilization compatibility, pulling manufacturers toward higher-margin precision engineering. METI safety standards for lithium-ion powered appliances exceed baseline international requirements. Kansai region manufacturing maintains ceramic blade metallurgy capabilities developed for precision motor control systems.
India
Tier-2 urbanization in Pune and Ahmedabad is expanding modern trade penetration for battery-operated entry segments. PLI scheme domestic manufacturing incentives are enabling localized cost structures for cordless platforms. BIS certification requirements for small appliances are tightening quality thresholds for mass-market distribution.
Mens Grooming Appliances Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in mens grooming appliances, with integrated blade-motor ecosystems commanding premium positioning while direct-to-consumer specialists compress unit economics through supply chain leverage. The market structure consolidates around three tiers: conglomerate appliance divisions with professional channel relationships, electronics specialists exploiting smartphone supply chain adjacencies, and precision engineering houses serving barber cooperative specifications. Two dominant competitive moves are reshaping positioning: modular architecture development to exploit right-to-repair legislative momentum, and backward integration into brushless DC motor production to defend margin structures against cobalt price volatility.
Among conglomerate appliance divisions, Koninklijke Philips N.V. and Panasonic Corporation occupy positions defined by integrated manufacturing depth and professional channel entrenchment. Xiaomi represents the electronics specialist archetype, extending smartphone supply chain efficiencies into personal care electronics through aggressive cost engineering and direct-to-consumer distribution. These three exemplify how competitive boundaries are redrawing around R&D-to-manufacturing capability alignment rather than brand heritage alone.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Procter and Gamble Company |
| Wahl Clipper Corporation |
| Spectrum Brands Holdings, Inc. |
| Xiaomi |
| Flyco |
| Midea |
| Braun GmbH |
| Others |
Supply & Pricing Matrix
Guangdong-Shenzhen manufacturing clusters generate 40-50% unit cost advantages over dispersed regional production, compressing price floors for cordless platforms while elevating margin pressure on mid-tier competitors lacking captive assembly capacity. This scale concentration enables aggressive pricing in consumer segments but creates vulnerability to tariff exposure and logistics disruption.
Pricing Analysis
The customization-premium spread separates configured-to-order professional equipment from mass-market standard SKUs by 3-4x unit pricing. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by brushless DC motor certification grade and after-sales service bundling. Pricing pressure stems from lithium cobalt oxide cost volatility squeezing mid-tier cordless margins. Barber cooperatives exhibit lowest price sensitivity due to warranty-dependent procurement, while tier-2 urban consumers in India demonstrate highest sensitivity to entry-segment positioning.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen ports to European distribution centers have elevated working capital requirements for seasonal inventory builds. Manufacturing concentrates in China, Vietnam, and Mexico for final assembly, drawing precision motors from Japan and South Korea. The supply chain rests on lithium-ion cell supply from CATL and LG Chem facilities, ceramic blade substrates from Kansai-region specialists, and injection-molded housings from Guangdong toolmakers. Single-source vulnerability in brushless DC motor controllers threatens continuity. Distribution runs through professional salon distributors in Europe, direct-to-consumer platforms in North America, and e-commerce marketplaces in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among professional barber cooperatives and direct-to-consumer platforms, fragmenting traditional retail channel leverage and compressing distributor margins across mid-tier positioning.
For Market Incumbents: Shield premium positioning through backward integration into brushless DC motor production, defending margin structures against cobalt price volatility. Deepen professional channel entrenchment by expanding sterilization-compatible titanium-nitride coating capabilities for EU REACH compliance, creating switching costs against emerging electronics specialists. For New Entrants and Emerging Players: Lead with modular architecture development targeting right-to-repair legislative momentum in Germany and select US states, capturing sustainability-conscious professional buyers. The most penetrable white space sits in India tier-2 urbanization, where PLI scheme incentives and modern trade expansion enable localized cost structures for battery-operated entry segments. Deploy direct-to-consumer subscription blade replenishment algorithms to bypass entrenched retail distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer specialists with telemetry-integrated replenishment platforms, offering superior cash flow predictability against transactional hardware models. Long-term viability favors precision engineering houses with ceramic blade metallurgy capabilities and professional channel relationships. Watch FDA 510(k) clearance velocity for laser-integrated appliances as inflection indicator for photonics segment commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless DC Motors | Defends margin structures against cobalt price volatility affecting cordless platform economics. |
| Ceramic Blade Metallurgy Investment | Captures professional barber specifications in Japan and South Korea requiring zirconia-based sterilization compatibility. |
| Direct-to-Consumer Subscription Launch | Displaces traditional retail attachment sales through automated replenishment algorithms tied to usage telemetry. |
| Modular Architecture Development | Exploits EU right-to-repair legislative proposals threatening sealed-unit designs and proprietary attachment systems. |
| India Tier-2 Manufacturing Footprint | Enables localized cost structures under PLI scheme incentives for battery-operated entry segments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with product development executives at appliance conglomerates, procurement leads at professional barber cooperatives, channel sales heads at salon distributors, and regulatory affairs specialists; and secondary validation through MIIT energy efficiency filings, FDA 510(k) clearance databases, EU REACH substance restriction updates, and customs trade records for grooming appliance exports. Bottom-up unit economics modeling triangulated against top-down market sizing from retail audit data.
Across the analysis window, the forecast framework applied product type, end-user segment, technology platform, and geographic regulatory cluster dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating brushless DC motor adoption curves, lithium-ion energy density improvement rates, and professional channel specification evolution. Industry-specific inputs included cobalt price volatility scenarios and right-to-repair legislative passage probabilities.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cost reduction, stable trade policy environments, or unchanged EU chemical regulation thresholds would require recalibration. Forecasts assume documented regulatory compliance timelines and professional channel procurement patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Smart Bra Market
Consumer Goods
Brazil Vegan Cosmetics Market
Consumer Goods
Dog Biscuit Market
Consumer Goods
UAE Dog Food Market
Consumer Goods
Guitar Head Amplifiers Market
Consumer Goods
Europe Eyewear Market
Consumer Goods
Saudi Arabia Major Home Appliances Market
Consumer Goods
Ride-Ons Market
Consumer Goods
Trolley Bags Market
Consumer Goods
Hair Extension Market
Consumer Goods
Qatar Home Appliances Market
Consumer Goods
Nail Lamps Market
Consumer Goods
Computer Keyboard Market
Consumer Goods
South America Cosmetics Products Market
Consumer Goods
Commercial Lawnmower Market
Consumer Goods
Claw Machine Market